
 Mobile Handset Protection Market | 2026-2036
Mobile Handset Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Mobile Handset Protection Market Outlook
REACH compliance is consolidating the cost-of-entry calculus for any protection product sold across European retail channels. Asurion leverages its carrier-embedded distribution to sustain recurring revenue streams across North American markets. SquareTrade anchors its competitive stance through direct-to-consumer pricing transparency, while ZAGG specializes in premium material science for screen protection layers.
Mobile handset protection encompasses physical accessories and service plans engineered to prevent or remediate damage to portable cellular devices, with tempered glass screen protectors typically rated to 9H hardness on the Mohs scale and phone cases tested to military drop standards such as MIL-STD-810G. The category serves both individual consumers seeking asset preservation and enterprises managing device fleets under total-cost-of-ownership frameworks. Screen protectors and phone cases together capture the dominant share of product-type revenue, though skins represent the fastest-growing format as slim-profile aesthetics displace bulkier alternatives. Tempered glass leads material volumes while silicone commands premium positioning through enhanced shock absorption and tactile grip properties.
FDA oversight applies indirectly where antimicrobial coatings enter medical-adjacent claims, while FCC equipment authorization shapes the design constraints within which protection accessories must operate without signal interference. The EU's Ecodesign for Sustainable Products Regulation and REACH chemical restrictions jointly elevate compliance burdens for any supplier targeting European consumers. Stakeholders must monitor how right-to-repair legislation in multiple jurisdictions reshapes the economics of damage prevention versus replacement.
Market Dynamics
The EU's Ecodesign for Sustainable Products Regulation is compressing product lifecycles while simultaneously extending warranty obligations, forcing protection accessory suppliers to redesign for repairability and recyclability rather than planned obsolescence.
Growth Catalysts
- Enterprise fleet TCO frameworks:Distributed workforce managers now mandate damage prevention as a line-item cost control, expanding bulk procurement of screen protection and case bundles across logistics, field services, and healthcare verticals.
- REACH chemical compliance:European retailers are consolidating supplier bases to qualified vendors with pre-certified material documentation, accelerating market share capture by compliant manufacturers.
- India PLI scheme:Domestic smartphone assembly growth is creating parallel aftermarket demand for protection accessories through localized distribution networks and service plan bundling.
Market Restraints
- Petrochemical input volatility:Silicone and polycarbonate resin prices fluctuate with crude oil indices, compressing gross margins for case manufacturers without long-term supply contracts.
- Guangdong supply concentration:Tempered glass screen protector fabrication clusters in a single Chinese province, exposing buyers to logistics disruption and tariff exposure.
- Right-to-repair friction:Divergent national implementation timelines across France, Germany, and US states create compliance fragmentation for warranty-integrated protection plans.
Strategic Opportunities
- Antimicrobial coating medical adjacency:FDA-registered surface treatments for healthcare worker devices represent uncaptured premium pricing in hospital procurement channels.
- Enterprise insurance bundling:Device protection plans are converging with commercial property and casualty policies, creating new B2B distribution through brokers and risk managers.
- EU Green Deal circularity mandates:Take-back and recycling infrastructure requirements favor suppliers with closed-loop material recovery capabilities.
Industry Challenges
- Signal transparency engineering:FCC Part 15 compliance for mmWave 5G compatibility demands specialized RF testing capabilities that smaller case designers lack in-house.
- Modular design talent scarcity:Mechanical engineers with experience in disassembly-friendly fastening systems and repair-grade material selection command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mobile Handset Protection Market |
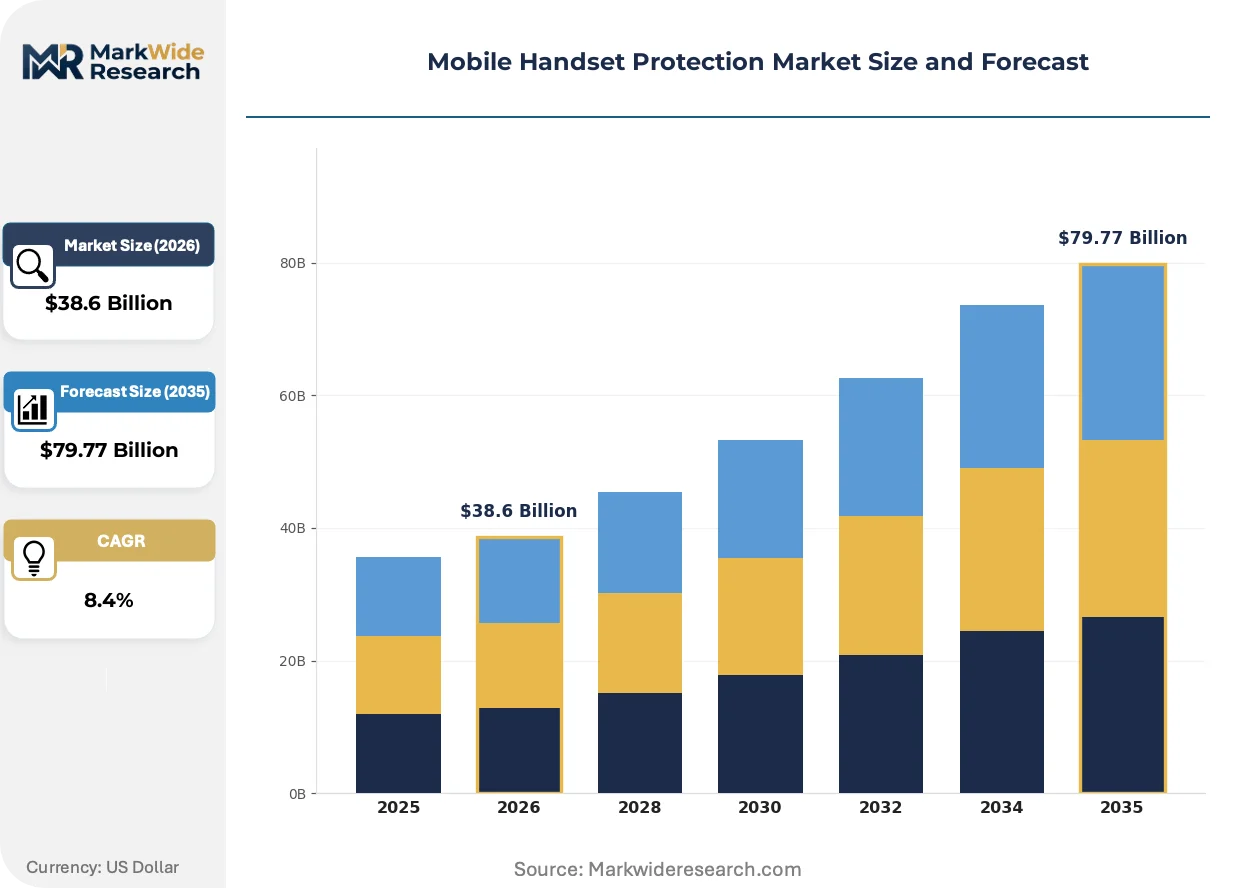
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $79.77 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Screen Protectors, Phone Cases, Skins, Pouches Material: Tempered Glass, Plastic, Silicone, Leather Distribution Channel: Online Retail, Specialty Stores, Electronic Retailers, Supermarkets End User: Consumers, Enterprises, Retailers, Service Providers |
| Companies Covered | Asurion, SquareTrade, AppleCare, Samsung Care+, Verizon Mobile Protect, AT&T Mobile Protection, ZAGG, ProtectCELL, Otter Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mobile Handset Protection Market Strategic Shifts
Material science breakthroughs are compressing the performance gap between slim-profile aesthetics and military-grade drop protection, while regulatory pressure on single-use plastics accelerates format experimentation.
Nano-ceramic composite films are converging with self-healing polymer substrates to create screen protectors that absorb impact energy while maintaining optical clarity. Enterprise procurement teams in logistics and construction verticals are piloting these hybrids for field worker devices. The technology is converging with traditional tempered glass manufacturing lines, enabling tier-one suppliers to upgrade capacity without greenfield investment.
The EU's Ecodesign for Sustainable Products Regulation mandates elimination of non-recyclable adhesives and improved disassembly scores for electronics accessories sold after compliance deadlines. Manufacturers must redesign case attachment mechanisms and document material flows through digital product passports. Protection accessory suppliers targeting German and French retail channels are accelerating bio-based polymer development to preempt enforcement actions.
Direct-to-enterprise procurement platforms are displacing carrier-bundled protection plans for fleet-managed device populations. Risk managers and IT procurement officers now negotiate standalone service contracts with defined SLA terms for damage remediation. This pattern is most visible in North American logistics and healthcare verticals where device refresh cycles have shortened to eighteen months.
Mobile Handset Protection Market Segmentation
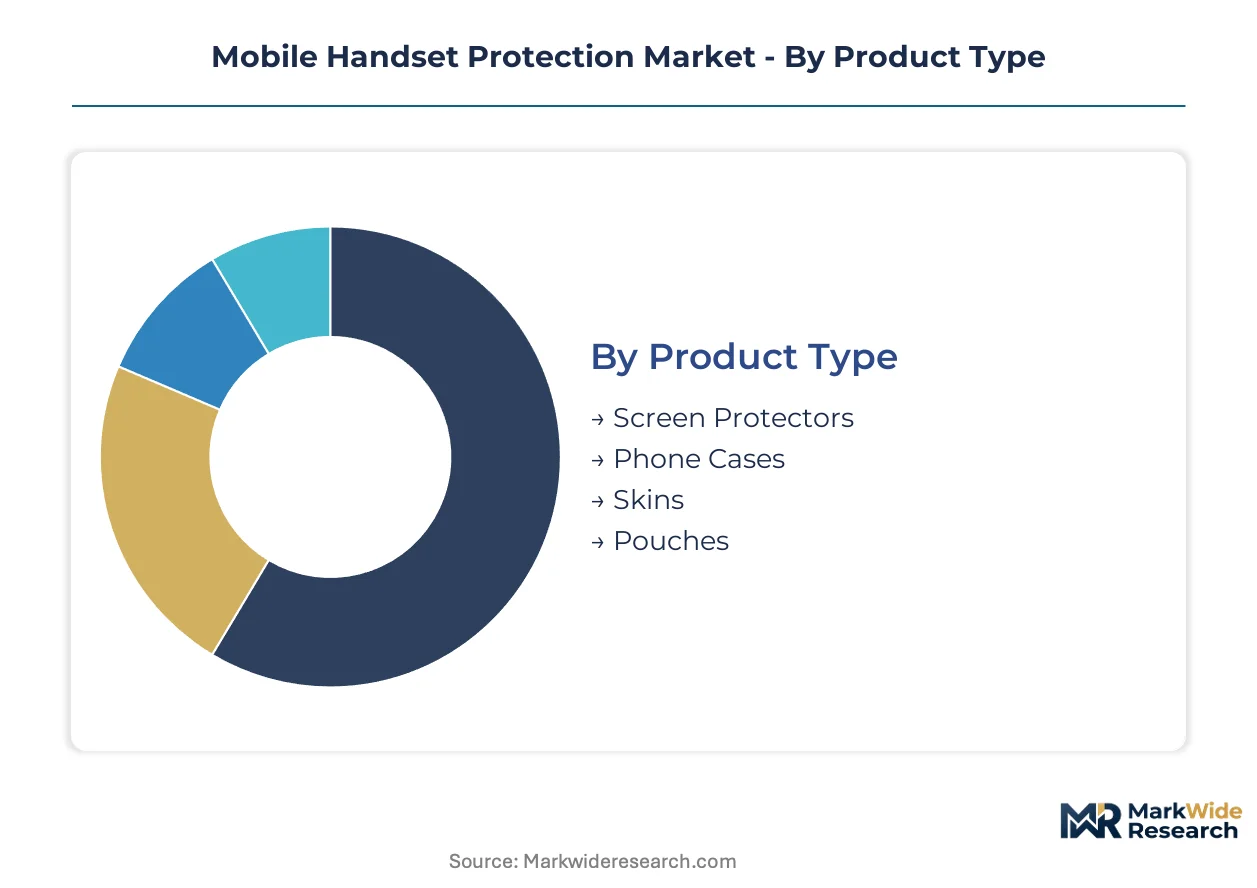
Device refresh cycles and damage frequency vary sharply across use environments, forcing suppliers to align protection specifications with replacement economics rather than uniform durability standards. Segmentation reveals where premium material investments recover their cost through extended device lifecycles versus commodity positioning for high-turnover fleets.
Product Type:
Upgrade intervals and residual value retention drive divergent protection strategies, with enterprise fleets prioritizing damage prevention over aesthetic refreshment.
- Screen Protectors:Tempered glass laminates rated to 9H Mohs hardness dominate volume, with nano-ceramic hybrids penetrating construction and logistics verticals where impact frequency exceeds consumer norms. Indian domestic assembly growth is amplifying aftermarket bundling through localized supply chains.
- Phone Cases:MIL-STD-810G drop certification anchors enterprise procurement specifications, while slim-profile designs capture consumer preference in premium smartphone segments. Silicone and polycarbonate resin price volatility compresses margins for manufacturers without long-term petrochemical contracts.
- Skins:Vinyl and thermoplastic polyurethane wraps address aesthetic customization demand with minimal bulk addition, climbing fastest among Gen Z device owners seeking seasonal refresh without case replacement.
- Pouches:Sleeve-style enclosures persist in emerging market feature phone segments and enterprise hot-swap environments where device sharing exceeds individual assignment frequency.
Screen Protectors sits at the top of the volume ranking, with Skins climbing the fastest.
Material:
Cost tier positioning separates medical-grade antimicrobial formulations from commodity petrochemical derivatives, with REACH compliance documentation becoming a gatekeeping credential for European channel access.
- Tempered Glass:Ion-exchange strengthened aluminosilicate dominates optical clarity specifications, with Guangdong Province fabrication clusters exposing buyers to logistics disruption and tariff exposure.
- Plastic:Polycarbonate and TPU formulations balance moldability with shock absorption, capturing mid-market volume where price elasticity constrains silicone adoption.
- Silicone:Liquid silicone rubber commands premium positioning through enhanced tactile grip and shock absorption properties, with bio-based alternatives accelerating under EU Green Deal circularity mandates.
- Leather:Genuine and synthetic hides address executive and luxury segments, with repair-grade material selection becoming critical as right-to-repair legislation extends warranty obligations.
Tempered Glass holds the volume lead, while Silicone captures the steepest expansion trajectory in premium tiers.
Distribution Channel:
Customer type fragmentation between individual purchasers and fleet procurement officers is reshaping channel investment priorities, with direct-to-enterprise platforms displacing traditional carrier bundling.
- Online Retail:Direct-to-consumer pricing transparency and review aggregation drive consumer discovery, with Amazon and specialized electronics marketplaces capturing protection accessory search traffic.
- Specialty Stores:ZAGG and dedicated accessory retailers emphasize premium material science demonstration and same-day installation services for tempered glass application.
- Electronic Retailers:Best Buy and comparable chains bundle protection with device purchase through point-of-sale attachment programs, sustaining volume despite enterprise procurement platform displacement.
- Supermarkets:Mass-market discounters address impulse replacement demand for commodity cases and basic screen protectors in high-frequency shopping environments.
Online Retail commands the highest transaction volume, with Electronic Retailers facing the sharpest share compression from enterprise platform migration.
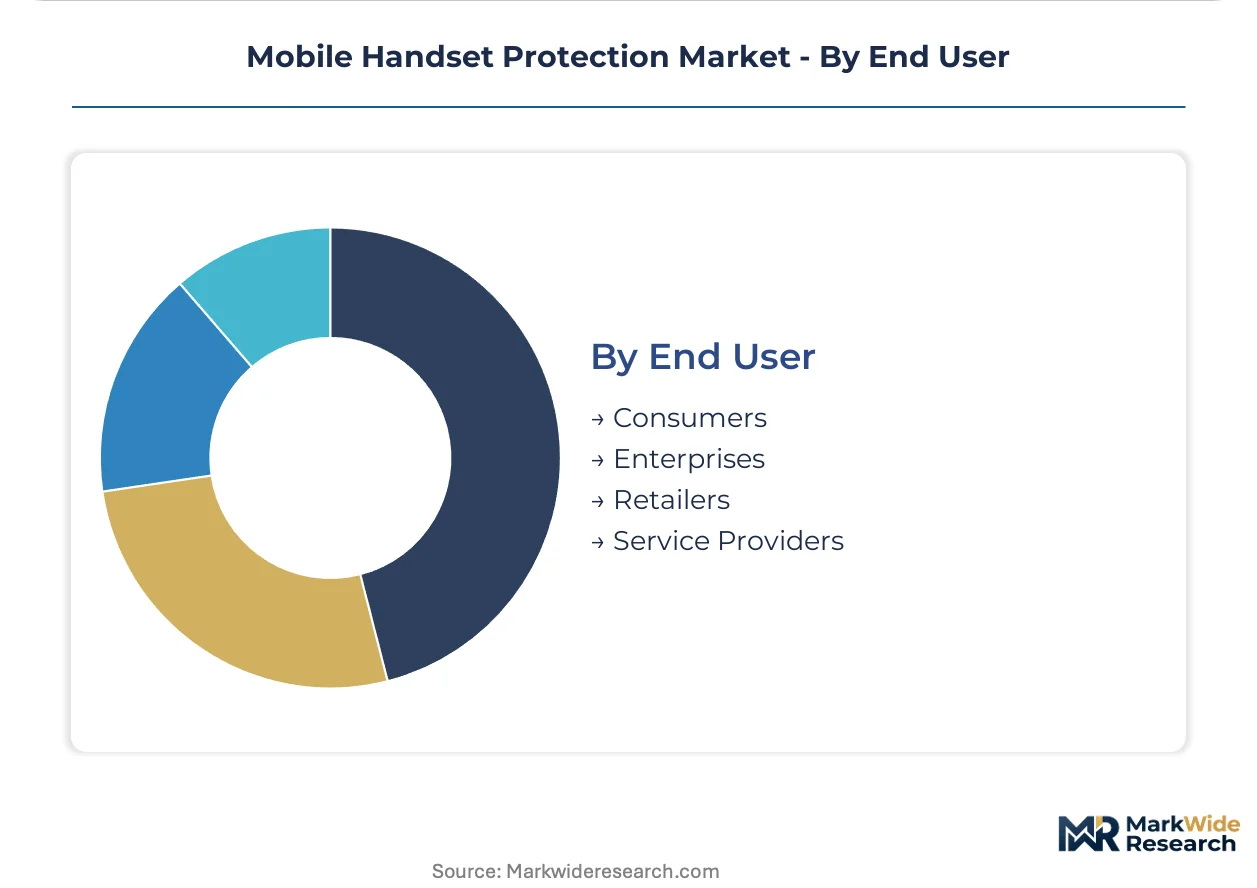
End User:
Application environment severity and total cost of ownership frameworks determine specification stringency, with healthcare and construction verticals driving antimicrobial and impact-resistance innovation respectively.
- Consumers:Individual purchasers prioritize aesthetic alignment and brand expression, with seasonal refresh patterns sustaining skin and case replacement cycles independent of functional degradation.
- Enterprises:Fleet managers in logistics, field services, and healthcare verticals mandate damage prevention as line-item cost control, expanding bulk procurement of bundled protection with defined SLA terms for damage remediation.
- Retailers:Channel partners seek margin-preserving private label and exclusive distribution arrangements, with pre-certified REACH documentation consolidating supplier bases to qualified vendors.
- Service Providers:Carrier-embedded protection plans and independent repair networks compete for recurring revenue streams, with insurance bundling creating new B2B distribution through commercial property and casualty brokers.
Consumers maintain absolute volume leadership, with Enterprises gaining share fastest as distributed workforce device populations expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mobile handset protection originated in the United States through carrier-embedded service plans before expanding through Asian manufacturing clusters. Distribution now follows smartphone assembly geography, with protection accessory supply chains co-locating near device production centers.
United States
Enterprise fleet managers in logistics and healthcare verticals drive bulk procurement of bundled protection with defined SLA terms. FCC Part 15 compliance for mmWave 5G compatibility shapes case design constraints. Dallas and Atlanta anchor carrier-embedded distribution networks for recurring revenue service plans.
China
Guangdong Province concentrates tempered glass screen protector fabrication, exposing global buyers to logistics disruption and tariff exposure. MIIT equipment authorization standards govern accessory RF performance. Shenzhen and Dongguan manufacturing clusters supply volume production for export markets and domestic smartphone assembly lines.
India
Domestic smartphone assembly growth under the PLI scheme creates parallel aftermarket demand for protection accessories. BIS certification requirements for electronic accessories consolidate qualified supplier bases. Noida and Chennai manufacturing corridors localize distribution networks for service plan bundling.
Germany
REACH chemical compliance and EU Ecodesign regulations elevate entry barriers for protection accessory suppliers. KBA and federal environmental agencies enforce circularity mandates on packaging and material recovery. Bavaria and North Rhine-Westphalia host retail distribution hubs serving pan-European channels.
Japan
Premium smartphone segments sustain demand for slim-profile aesthetic protection with minimal bulk addition. METI standards for material safety and recyclability shape product development requirements. Tokyo-Osaka metropolitan corridors concentrate specialty retail channels emphasizing material science demonstration.
Mobile Handset Protection Market Competitive Environment
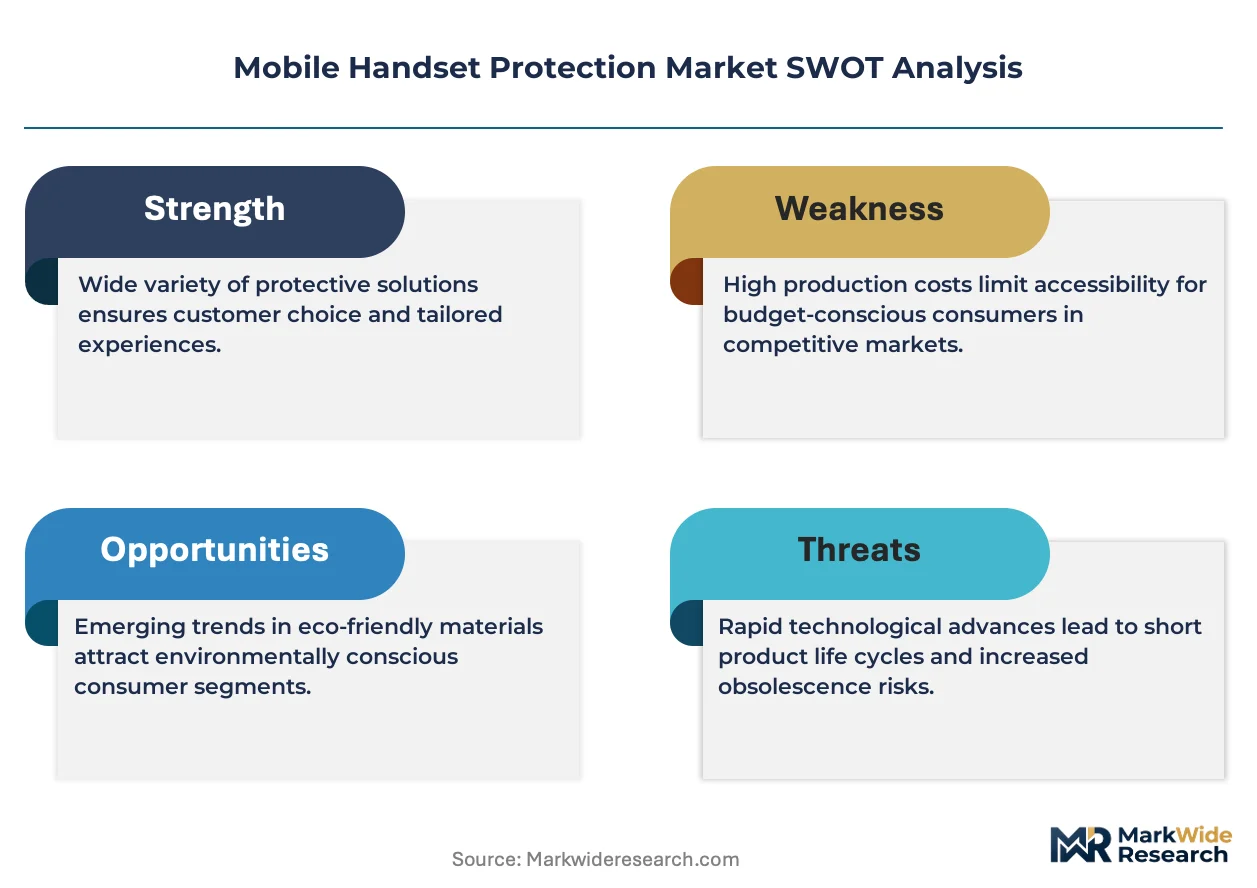
The competitive structure tilts toward carrier-embedded service providers with recurring revenue models. Tier-one suppliers with pre-certified REACH documentation capture European retail consolidation, while direct-to-consumer platforms displace traditional bundling in North American enterprise segments. Three archetypes dominate: insurance-backed service plan operators, premium material science specialists, and mass-market accessory fabricators. M&A activity concentrates among service plan providers seeking geographic expansion, while technology licensing agreements proliferate around nano-ceramic composite formulations.
Among carrier-embedded operators, Asurion and SquareTrade exemplify the insurance-backed service plan archetype with recurring revenue structures. ZAGG occupies a position within the premium material science tier, representing specialization in screen protection layers. These three anchors illustrate the divergence between risk-transfer service models and physical protection manufacturing across the competitive landscape.
| Leading Market Players |
|---|
| Asurion |
| SquareTrade |
| AppleCare |
| Samsung Care+ |
| Verizon Mobile Protect |
| AT&T Mobile Protection |
| ZAGG |
| ProtectCELL |
| Otter Products |
| Others |
Value Chain & Pricing Dynamics
Captive integration into Guangdong fabrication clusters anchors both supply positioning and pricing power for tempered glass screen protectors, with ion-exchange strengthened aluminosilicate production concentrated in a single Chinese province that feeds global aftermarket demand through long-term offtake contracts.
Pricing Analysis
The bundled-vs-unbundled service split separates carrier-embedded protection plans from direct-to-consumer accessory sales. Subscription-based service plans command premium positioning through risk-transfer value, while transactional screen protector pricing stratifies across 9H hardness certification tiers and brand equity. Cost compression in commodity polycarbonate cases is intensifying because petrochemical input volatility erodes manufacturer margins. Enterprise fleet buyers exhibit the lowest price sensitivity due to total cost of ownership frameworks, whereas mass-market consumers drive volume through promotional discounting.
Supply Chain Analysis
Freight cost escalation from Guangdong Province to North American and European distribution hubs is reshaping procurement geography for global brands. Tempered glass fabrication draws from Chinese ion-exchange facilities, Indian domestic assembly corridors under the PLI scheme, and Vietnamese emerging capacity. Raw material dependencies center on petrochemical resins, rare-earth strengthened glass substrates, and bio-based silicone alternatives. Single-province concentration in Guangdong exposes buyers to logistics disruption and tariff exposure. Distribution runs through carrier-embedded service networks, direct-to-enterprise procurement platforms, and electronics retail chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage economics favor suppliers with dual-hemisphere manufacturing footprints, as REACH compliance costs in Germany diverge sharply from India's PLI-incentivized production economics.
For Market Incumbents: Deploy REACH pre-certification as a channel-locking lever. Consolidate supplier relationships with German and French retailers by maintaining compliant material documentation that emerging entrants cannot replicate. Vertical integration into ion-exchange glass strengthening insulates against Guangdong logistics disruption. Defend enterprise accounts through service-level agreement bundling that substitutes pure-play accessory vendors. For New Entrants and Emerging Players: Capture antimicrobial coating adjacency in healthcare procurement channels where FDA-registered surface treatments command uncaptured premium pricing. Target Indian domestic assembly growth through localized distribution networks and service plan bundling with PLI-beneficiary smartphone manufacturers. Build brand recognition through direct-to-consumer platforms emphasizing material science transparency before attempting carrier-embedded placement. For Investors and Strategic Acquirers: Roll-up economics work for service plan operators because recurring revenue structures attract valuation multiples above transactional accessory manufacturers. The fragmented landscape of regional repair networks and independent protection plan providers offers consolidation targets with complementary geographic footprints. Monitor right-to-repair legislative implementation timelines as the inflection signal for warranty-integrated plan restructuring.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Pre-Certification Investment | European retailer consolidation favors suppliers with compliant material documentation. |
| Enterprise Platform Integration | Direct-to-fleet procurement displaces carrier bundling in North American logistics verticals. |
| Nano-Ceramic Composite Licensing | Technology agreements proliferate around impact-absorbing screen protection formulations. |
| Indian PLI Corridor Localization | Domestic assembly growth creates parallel aftermarket demand through co-located supply chains. |
| Antimicrobial Coating FDA Registration | Healthcare worker device protection represents uncaptured premium pricing in hospital procurement. |
Study Parameters
Bottom-up enterprise fleet modeling reconciled against top-down tempered glass production tracking forms the analytical core of this study. Primary interviews with carrier partnership directors, electronics retailer category managers, enterprise IT procurement officers, and protection plan actuaries combined with secondary validation from BIS certification databases, MIIT equipment authorization filings, customs trade records, and SEC 10-K disclosures from publicly traded service plan operators. Triangulation between demand-side fleet TCO frameworks and supply-side Guangdong fabrication capacity estimates anchors volume projections.
Historical trendline analysis of device refresh cycles and damage frequency patterns informed the projection framework across product type, material, distribution channel, and end-user segmentation. Modeled dimensions include protection format specifications, REACH compliance tiers, procurement platform migration patterns, and vertical application severity. CAGRs were derived from elasticity-adjusted replacement rates and enterprise fleet expansion trajectories. Forecast inputs incorporated petrochemical price volatility indices and right-to-repair legislative implementation timelines.
EU Ecodesign enforcement acceleration, India PLI scheme expansion, and mmWave 5G case redesign cycles are the dominant revision risks to modeled assumptions. A model refresh is warranted upon material change in carrier-embedded service plan pricing structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Protective Gear
Flavored Condoms Market
Protective Gear
Tactical Boots Market
Protective Gear
Waterproof Cases Market
Protective Gear
Battery Heated Gloves Market
Protective Gear
Europe Protective Footwear Market
Protective Gear
Safety Shoes Market
Protective Gear
Home Outdoor Pest Control Devices Market
Protective Gear
Body Worn Insect Repellent Market
Protective Gear
Goalkeeper Gloves Market
Protective Gear
Cooking Gloves Market
Protective Gear
Waterproof Boots Market
Protective Gear
Europe Lanyards Market
Protective Gear
Hand Gloves Market
Protective Gear
Personal Floatation Devices (Pfds) Market
Protective Gear
Advanced Protective Gear and Armor Market
Protective Gear
Helmet Lining Market