
 Ultrapure Water Market | 2026-2036
Ultrapure Water Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrapure Water Market Intelligence
Capital-intensity divergence between membrane-system specialists and full-service water utilities is reorganizing competitive tiers in ultrapure water supply. DuPont leverages its polymer science heritage to dominate high-performance reverse osmosis membrane supply for semiconductor-grade systems. Veolia sustains integrated service contracts spanning design, build, and long-term operation of ultrapure water plants at major manufacturing sites. Organo Corporation anchors its position through specialized ion-exchange resin technology tailored to sub-ppb contaminant removal.
Ultrapure water is water purified to resistivity levels of 18.2 MΩ·cm and total organic carbon below 5 ppb, achieved through sequential reverse osmosis, electrodeionization, and ultraviolet oxidation to remove ions, particles, and microorganisms for critical industrial processes. Electrodeionization systems are capturing margin pools in new fab construction as semiconductor manufacturers demand continuous operation without chemical regeneration downtime. Pharmaceutical applications of distillation technology remain mature with steady replacement cycles, while UV radiation modules are growing fastest in point-of-use polishing skids for research laboratories requiring pyrogen-free water.
The EPA regulates ultrapure water discharge under the Clean Water Act while the FDA enforces purity standards for pharmaceutical and medical applications, creating dual compliance burdens for multi-sector suppliers. EMEA jurisdictions apply REACH substance restrictions to ion-exchange resin chemistries and MEE in China enforces wastewater discharge standards that push manufacturers toward closed-loop ultrapure water recycling. Stakeholders must monitor how evolving semiconductor node transitions and tightening pharmacopeial standards will reshape capital allocation between membrane replacement and full-system upgrades.
Market Dynamics
Semiconductor node transitions below 3nm are compressing ultrapure water purity tolerances from parts-per-billion to parts-per-trillion, forcing simultaneous upgrades across membrane, ion-exchange, and UV oxidation stages in existing fabrication facilities.
Growth Catalysts
- EPA effluent rule tightening:The Clean Water Act's evolving discharge standards in the United States are compelling fabs to invest in closed-loop recycling systems that regenerate ultrapure water on-site rather than treating once-through flows.
- Advanced packaging expansion:Heterogeneous integration and chiplet architectures in Taiwan and South Korea are multiplying the number of cleaning cycles per wafer, directly scaling volumetric demand for 18.2 MΩ·cm water.
- Electrodeionization maturation:Continuous electrodeionization systems are eliminating chemical regeneration downtime, allowing semiconductor manufacturers to match the 99.999% uptime requirements of EUV lithography clusters.
Market Restraints
- Fluoropolymer membrane supply concentration:High-performance reverse osmosis membrane production clusters in Japan and the United States, creating vulnerability to export control disruptions or raw material allocation constraints.
- Energy intensity escalation:Multi-stage purification trains for sub-ppb water require 10-15 kWh per cubic meter, exposing operational costs to electricity price volatility in manufacturing-heavy jurisdictions.
- REACH substance restrictions:ECHA's evolving limitations on ion-exchange resin chemistries are forcing reformulation cycles that extend qualification timelines for European semiconductor and pharmaceutical facilities.
Strategic Opportunities
- India semiconductor corridor emergence:The country's PLI scheme and Gujarat-Telangana fab investments are creating greenfield demand for integrated ultrapure water design-build-operate contracts without legacy infrastructure constraints.
- Pharmaceutical single-use systems:Bioprocessing facilities are adopting disposable water-for-injection loops that bypass stainless steel validation cycles, opening point-of-use polishing skid demand.
- AI-driven predictive maintenance:Machine learning models trained on resistivity and TOC sensor arrays are enabling condition-based membrane replacement, converting capex into service revenue streams for equipment suppliers.
Industry Challenges
- Metrology talent scarcity:Sub-ppt contaminant detection requires specialized mass spectrometry and inductively coupled plasma expertise that outpaces university pipeline output in East Asian manufacturing hubs.
- Legacy system integration friction:Brownfield semiconductor facilities face piping material incompatibility when retrofitting 193nm lithography-era ultrapure water distribution into EUV-compatible loops.
- Pharmacopeial certification timelines:USP and EP water grade requalification cycles extend 18-24 months, delaying revenue recognition for pharmaceutical contract manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrapure Water Market |
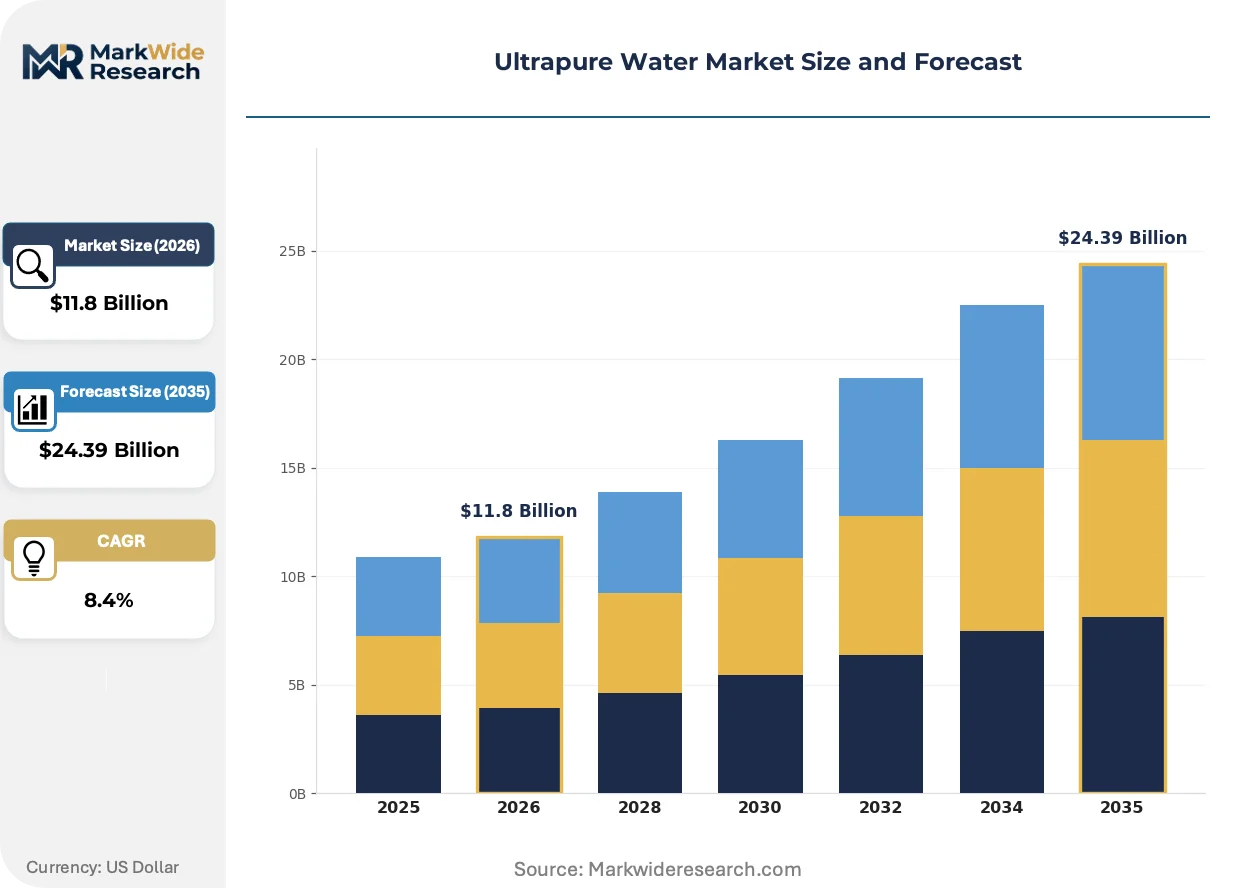
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $24.39 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reverse Osmosis, Distillation, Electrodeionization, UV Radiation Application: Semi-Conductors, Pharmaceuticals, Power Generation, Food & Beverage End User: Healthcare Facilities, Manufacturing Plants, Research Laboratories, Educational Institutions Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Organo Corporation, DuPont, Veolia, Aquatech, Asahi Kasei, Kurita Water Industries, Ecolab, Hitachi, Xylem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrapure Water Market Strategic Shifts & Innovations
Process intensification through module miniaturization and real-time analytics is compressing footprint requirements while elevating reliability expectations across semiconductor and life science applications.
Membrane-based boron and silica selective removal is bifurcating the pretreatment landscape for coastal semiconductor facilities drawing seawater-impacted feedstock. Taiwan Semiconductor Manufacturing and Samsung Foundry are deploying these systems at new Arizona and Texas sites where municipal water chemistry varies seasonally. The technology is bifurcating capex allocation between conventional reverse osmosis trains and specialized nanofiltration stages that protect downstream electrodeionization modules from scalant fouling.
REACH substance restrictions on per- and polyfluoroalkyl substances are accelerating ion-exchange resin chemistry transitions across European pharmaceutical and electronics manufacturing. ECHA's 2023-2027 restriction roadmap is forcing resin manufacturers to eliminate long-chain fluorinated polymer backbones from anion exchange media. German and French water treatment integrators are qualifying alternative acrylic-based matrices that trade chemical stability for regulatory compliance, compressing resin replacement cycles from five years to three.
After-sales service unbundling is fragmenting long-term ultrapure water plant contracts into discrete membrane supply, resin regeneration, and remote monitoring subscriptions. Semiconductor fabs in South Korea are disaggregating single-source operation agreements to benchmark component-level performance and accelerate supplier switching. This pattern concentrates in high-volume memory manufacturing where yield sensitivity to water quality excursions justifies redundant qualification of secondary membrane and resin suppliers.
Ultrapure Water Market Segmentation
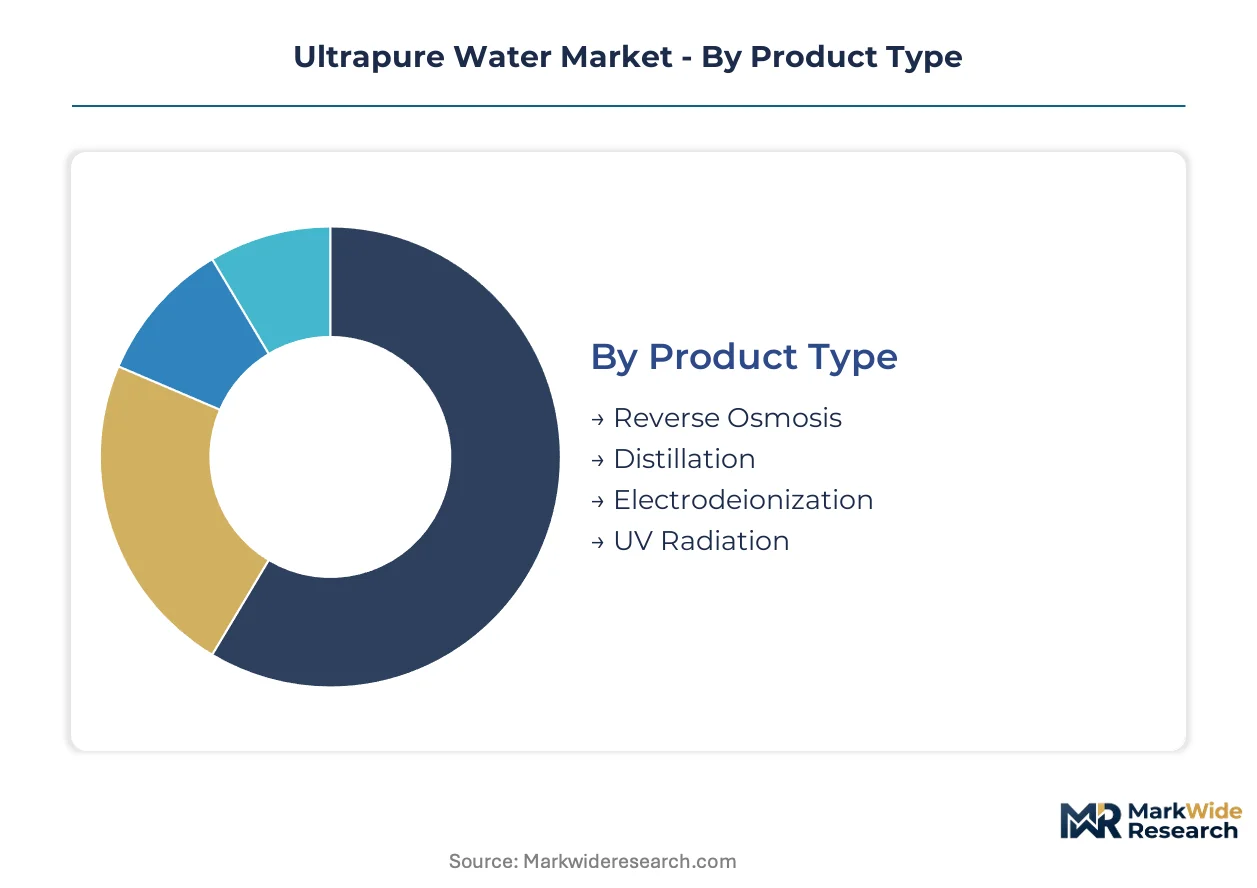
Ultrapure water procurement patterns diverge sharply across purification technologies and end-use applications. Regulatory frameworks in the United States, European Union, and East Asia impose distinct purity specifications that reshape equipment selection and supplier relationships.
Product Type:
EPA discharge rules under the Clean Water Act and FDA pharmaceutical standards create divergent equipment qualification pathways across purification technologies.
- Reverse Osmosis:Membrane-based pressure-driven separation removes dissolved ions, organic compounds, and particulates through semi-permeable fluoropolymer barriers. Taiwan Semiconductor Manufacturing and Samsung Foundry deploy multi-stage RO trains at new Arizona and Texas facilities where seasonal municipal water chemistry variations demand robust pretreatment. The technology dominates capital allocation in greenfield semiconductor construction.
- Electrodeionization:Continuous electrochemical deionization eliminates chemical regeneration downtime by combining ion-exchange resins with direct current fields. Semiconductor manufacturers in South Korea specify electrodeionization for EUV lithography clusters requiring 99.999% operational uptime. The technology is displacing mixed-bed ion exchange in advanced node fabs.
- Distillation:Thermal vaporization and condensation achieves pyrogen-free water for pharmaceutical compounding and parenteral manufacturing. USP and EP compliance cycles extend 18-24 months for new still installations.
- UV Radiation:Ultraviolet oxidation destroys microorganisms and degrades trace organics through 185nm and 254nm wavelength exposure. Research laboratories specify point-of-use UV polishing skids for TOC reduction below 5 ppb.
Reverse Osmosis handles the majority of throughput; Electrodeionization is expanding most quickly on share.
Application:
Purity tolerance compression from parts-per-billion to parts-per-trillion across critical manufacturing processes elevates capital intensity unevenly across end-use sectors.
- Semi-Conductors:Sub-3nm node transitions demand 18.2 MΩ·cm resistivity and sub-ppt metallic contamination control for wafer cleaning and EUV lithography. Taiwan and South Korea fabs are scaling ultrapure water treatment capacity fastest.
- Pharmaceuticals:Water-for-injection and compendial-grade specifications govern parenteral drug manufacturing and active pharmaceutical ingredient synthesis. EMA and FDA dual compliance burdens extend equipment validation timelines.
- Power Generation:Boiler feedwater and steam cycle chemistry control requires silica and conductivity management for turbine protection. Combined-cycle gas turbine installations drive replacement demand.
- Food & Beverage:Ingredient water and CIP applications require microbial control without pharmaceutical-grade capital overhead. Bottling facilities prioritize operational cost minimization.
Semi-Conductors command the steepest capital allocation; Pharmaceuticals maintains the longest replacement cycles.
End User:
Facility scale and validation burden separate capital-intensive manufacturing installations from lower-volume institutional demand.
- Manufacturing Plants:Integrated design-build-operate contracts span 15-20 year terms for semiconductor and pharmaceutical production sites. Veolia and Suez compete for multi-billion dollar fab water infrastructure.
- Healthcare Facilities:Dialysis centers and hospital pharmacies require continuous pyrogen-free water supply with redundant treatment trains. Joint Commission accreditation mandates documented purity monitoring.
- Research Laboratories:Point-of-use polishing systems serve analytical instrumentation and cell culture applications. Academic procurement favors modular capital expenditure over centralized plants.
- Educational Institutions:Teaching laboratories and general research support operate at lower purity tiers with standard reverse osmosis systems.
Manufacturing Plants absorb the dominant share of industry revenue; Research Laboratories are climbing the fastest on volume.
Distribution Channel:
Equipment complexity and service integration requirements fragment procurement pathways across direct and indirect channels.
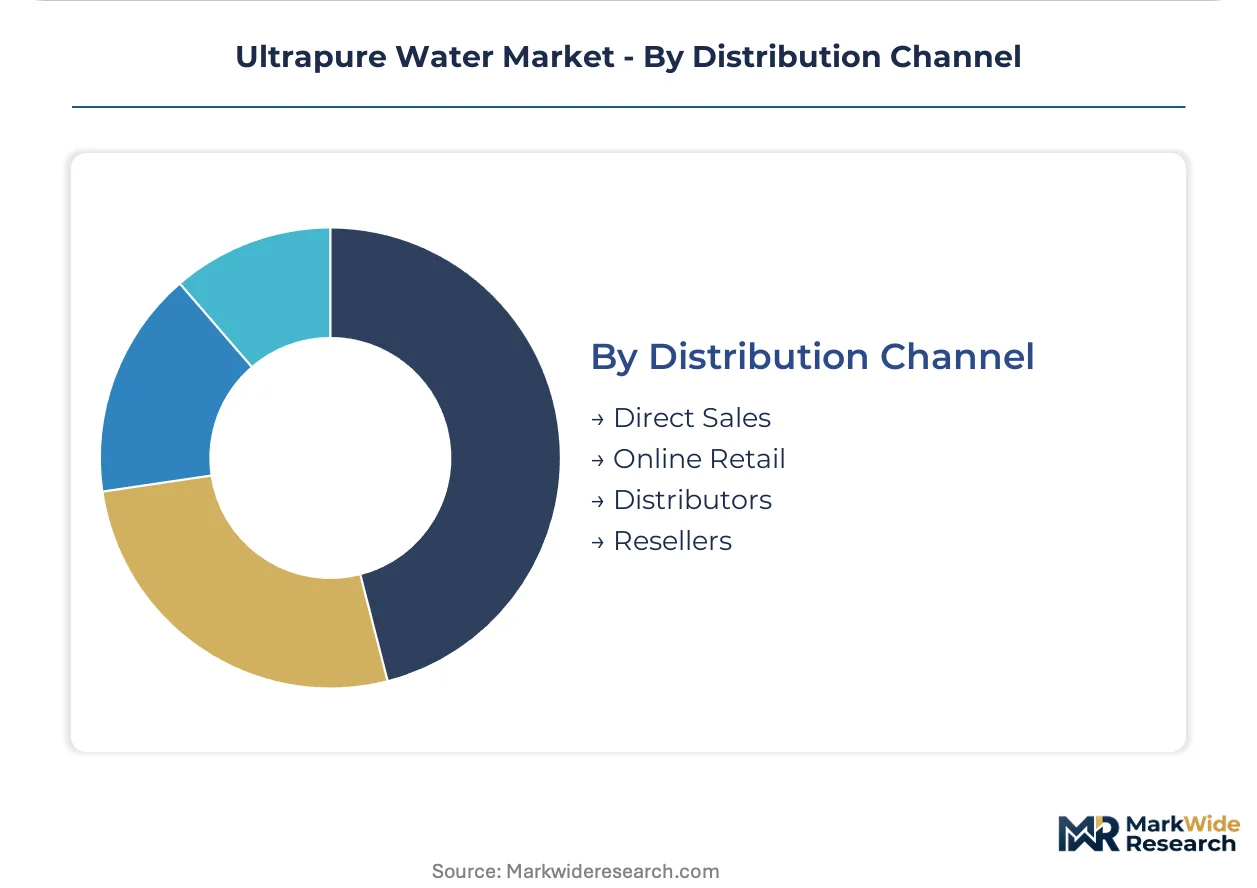
- Direct Sales:Original equipment manufacturers engage semiconductor fabs and pharmaceutical sponsors through dedicated account teams. DuPont Water Solutions and Organo Corporation maintain field engineering presence at major manufacturing corridors.
- Distributors:Regional water treatment integrators aggregate membrane, resin, and instrumentation components for mid-scale industrial clients. German and French distributors navigate REACH substance restriction compliance.
- Resellers:Secondary market channels serve replacement parts and aftermarket service for legacy installed base.
- Online Retail:Standardized laboratory water systems and consumables move through e-commerce for research and educational procurement.
Direct Sales captures the bulk of project value; Distributors are gaining share fastest in mid-market manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in East Asian manufacturing corridors where semiconductor fabs negotiate volume contracts, while European pharmaceutical water utilities absorb compliance premiums from REACH substance restrictions without equivalent volume leverage.
United States
Advanced packaging fabs in Arizona and Texas are scaling ultrapure water treatment capacity to match EUV lithography cluster deployment. EPA effluent rule tightening under the Clean Water Act is compelling closed-loop recycling investments rather than once-through discharge systems. The Phoenix-Tucson corridor hosts Taiwan Semiconductor Manufacturing and Intel facilities where seasonal municipal water chemistry variations demand robust membrane pretreatment.
Taiwan
Sub-3nm node transitions at TSMC fabs are compressing purity tolerances from parts-per-billion to parts-per-trillion, forcing simultaneous upgrades across membrane and electrodeionization stages. The Hsinchu Science Park anchors concentrated demand for 18.2 MΩ·cm water with 99.999% uptime requirements. Local ion-exchange resin regeneration infrastructure supports continuous operation without chemical downtime.
South Korea
Samsung Foundry and SK Hynix are expanding Pyeongtaek and Yongin facilities with heterogeneous integration architectures multiplying cleaning cycles per wafer. The Ministry of Environment enforces wastewater discharge standards that push manufacturers toward closed-loop ultrapure water recycling. Busan-Ulsan industrial complexes concentrate membrane system deployment for memory manufacturing.
China
Domestic semiconductor self-sufficiency targets are accelerating fab construction in Shanghai and Beijing where MEE enforces stringent wastewater discharge standards. Yangtze Memory Technologies and SMIC are scaling ultrapure water treatment capacity for 14nm and 7nm node production. The Yangtze River Delta hosts the densest concentration of electrodeionization system deployment outside Taiwan.
Germany
Pharmaceutical water-for-injection demand from Merck KGaA and Boehringer Ingelheim facilities sustains steady replacement cycles for distillation technology. ECHA REACH restrictions on per- and polyfluoroalkyl substances are forcing ion-exchange resin chemistry transitions that compress replacement cycles from five years to three. The Rhine-Main and Upper Bavaria regions concentrate compendial-grade water system validation expertise.
Ultrapure Water Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes, with membrane-system specialists commanding premium positioning while full-service water utilities compete on integrated contract scope. The market structures around three tiers: polymer science heritage players dominating high-performance reverse osmosis supply, integrated service providers capturing long-term operation contracts, and regional system integrators serving mid-scale industrial replacement demand. Consolidation pressure concentrates in electrodeionization module supply where semiconductor fabs demand redundant supplier qualification. Strategic moves center on geographic expansion into India semiconductor corridors and service unbundling to capture recurring membrane and resin revenue streams.
Among Japanese water treatment specialists, Organo Corporation and Kurita Water Industries exemplify the ion-exchange resin technology archetype, while Veolia represents the integrated service contract model spanning design, build, and long-term operation. DuPont occupies a position within the polymer science heritage tier leveraging fluoropolymer membrane supply for semiconductor-grade systems. These three anchors illustrate how competitive positioning diverges between component technology leadership and full-plant operational control.
| Leading Market Players |
|---|
| Organo Corporation |
| DuPont |
| Veolia |
| Aquatech |
| Asahi Kasei |
| Kurita Water Industries |
| Ecolab |
| Hitachi |
| Xylem |
| Others |
Cost & Logistics Intelligence
Acrylic-based ion-exchange resin substitution for fluorinated backbones under ECHA REACH restrictions is redrawing raw material sourcing maps while compressing replacement cycle economics for European pharmaceutical and electronics manufacturers. This chemistry transition simultaneously elevates procurement costs from shortened resin lifespans and concentrates supplier qualification burdens on German and French water treatment integrators.
Pricing Analysis
Configured-to-order electrodeionization systems for EUV lithography clusters command 40-60% premiums over standard reverse osmosis trains due to continuous-operation uptime guarantees and sub-ppt contamination specifications. Price differentiation separates membrane-system specialists from full-service utilities, with DuPont and Organo Corporation capturing technology premiums while Veolia competes on integrated contract scope. Cost compression in standard RO membrane supply is intensifying because South Korean fabs are disaggregating single-source agreements to benchmark component-level performance. Research laboratories exhibit highest price sensitivity, prioritizing modular capital expenditure over centralized plant investments.
Supply Chain Analysis
Japan and the United States anchor high-performance fluoropolymer reverse osmosis membrane production, with DuPont's polymer science heritage sustaining captive supply of semiconductor-grade barriers. Raw material dependencies center on perfluorinated polymer feedstocks, specialty ion-exchange monomers, and high-purity quartz for UV oxidation chambers. Single-source vulnerability concentrates in Japanese membrane manufacturing clusters exposed to export control disruptions. Distribution runs through direct OEM engagement for fab-scale projects and regional integrators for mid-market pharmaceutical installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent water treatment specialists face substitution defense against membrane-less electrochemical purification technologies that threaten to bypass traditional ion-exchange resin architectures in next-generation fabs.
For Market Incumbents: Consolidate backward integration into fluoropolymer membrane manufacturing to secure raw material allocation against Japanese supply concentration risks. Deepen captive resin regeneration infrastructure in Taiwan and South Korea to match TSMC and Samsung Foundry demands for 99.999% uptime without chemical downtime. Lock in 15-20 year design-build-operate contract renewals before Indian semiconductor corridor greenfield projects mature competitive bidding environments. For New Entrants and Emerging Players: Lead with AI-driven predictive maintenance platforms that convert membrane replacement capex into recurring service revenue streams, targeting South Korean memory manufacturers disaggregating single-source supplier agreements. Capture white-space demand in India's Gujarat-Telangana fab investments where legacy infrastructure constraints are absent and integrated water utility contracts remain unawarded. Pursue point-of-use polishing skid qualification for pharmaceutical single-use systems bypassing stainless steel validation cycles. For Investors and Strategic Acquirers: The market sits at a technology transition phase that favors electrodeionization module specialists with redundant semiconductor fab qualifications. Long-term viability over the next decade rests on suppliers capable of navigating sub-ppt purity tolerances and REACH-compliant resin chemistry transitions. Acquisition targets should demonstrate installed base density in Hsinchu Science Park or Pyeongtaek manufacturing corridors. Monitor ECHA restriction roadmap acceleration as the primary inflection signal for resin replacement cycle compression and chemistry reformulation timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Electrodeionization Module Capacity Expansion | Samsung Foundry and SK Hynix EUV cluster deployment demands continuous deionization without regeneration downtime. |
| Backward Integration into Fluoropolymer Membrane Manufacturing | DuPont polymer science heritage secures semiconductor-grade barrier supply against Japanese export control exposure. |
| REACH-Compliant Resin Chemistry Transition | ECHA restrictions on perfluorinated backbones force German and French integrators toward acrylic-based alternatives. |
| India Semiconductor Corridor Market Entry | Gujarat-Telangana fab investments under PLI scheme create greenfield demand without legacy infrastructure constraints. |
| AI-Driven Predictive Maintenance Platform Launch | Machine learning on resistivity sensor arrays enables condition-based membrane replacement converting capex to service revenue. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with ultrapure water system procurement managers at Taiwan Semiconductor Manufacturing and Samsung Foundry, electrodeionization module engineering leads, pharmaceutical water-for-injection validation specialists, and EMEA regulatory affairs directors; alongside secondary validation through EPA Clean Water Act discharge filings, ECHA REACH restriction roadmaps, FDA pharmaceutical water guidance documents, and semiconductor fab construction permit databases. Bottom-up triangulation across membrane replacement cycle data and top-down reconciliation against electrodeionization system deployment records anchored volume estimates.
Across the analysis window, the forecasting framework modeled purification technology segmentation by resistivity tier and contamination specification, application splits across semiconductor node transitions and pharmaceutical compendial grades, and end-user distinctions between integrated manufacturing plants and point-of-use research installations. CAGRs derived from capacity expansion announcements at Arizona and Texas advanced packaging fabs, Hsinchu Science Park infrastructure scaling, and Indian PLI scheme water utility contract awards.
The analysis sits within stated boundaries; outcomes outside sustained sub-3nm node progression, stable ECHA restriction implementation timelines, or uninterrupted fluoropolymer membrane supply from Japan and the United States would require recalibration. Forecasts reflect assumptions on semiconductor manufacturing capital intensity and pharmaceutical validation cycle duration. Recalibration cycles align with material shifts in EUV lithography cluster deployment schedules and REACH substance restriction enforcement phases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Industrial Water Treatment Chemicals Market
Water & Sludge Treatment
Water Softening Systems Market
Water & Sludge Treatment
South America Water Treatment Chemicals Market
Water & Sludge Treatment
North America Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
Global Sludge Treatment Chemicals Market
Water & Sludge Treatment
Middle-East and Africa Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Feedwater Treatment Chemicals Market
Water & Sludge Treatment
Membrane Filtration Systems Market
Water & Sludge Treatment
Water Purification Systems Market
Water & Sludge Treatment
South America Membrane Water and Wastewater (WWT) Treatment Market
Water & Sludge Treatment
Global Flocculant and Coagulant Market
Water & Sludge Treatment
Asia-Pacific Water Free/ Waterless Urinals Market
Water & Sludge Treatment
Global Liquid Waste Management Market
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Produced Water Treatment Market