
 Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market | 2026-2036
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market Outlook
ISO 9001 certification for membrane module manufacturing is rotating supplier eligibility across the Asia-Pacific procurement landscape. Asahi Kasei Corporation leverages its hollow-fiber ultrafiltration expertise to dominate municipal retrofit programs in Japan and Australia. Veolia sustains competitive positioning through integrated operations and maintenance contracts spanning desalination plants in the Middle East corridor of the region. TORAY INDUSTRIES, INC. anchors high-flux reverse osmosis supply to semiconductor fabs requiring ultrapure water generation.
Membrane water and wastewater treatment employs semipermeable barriers—typically polyamide thin-film composites, polysulfone, or polyvinylidene fluoride substrates—operating at transmembrane pressures from 0.1 to 6.0 MPa to selectively separate dissolved solids, pathogens, and organic contaminants from feed streams. Reverse osmosis commands the largest installed base for seawater desalination and industrial process water, while membrane bioreactor technology captures the fastest growth trajectory as urban utilities confront land scarcity and effluent quality mandates. Ultrafiltration pre-treatment modules represent a mature margin pool where replacement cycles and aftermarket services concentrate vendor profitability.
China's MEE enforces progressively stringent discharge limits for industrial effluent, compelling facilities to upgrade from conventional activated sludge to membrane-based systems. Australia's TGA-aligned water quality frameworks and India's CPCB zero-liquid-discharge directives for textile and tannery clusters collectively expand addressable demand across divergent regulatory intensities. Stakeholders must monitor how Japan's METI circular-economy roadmaps and emerging ASEAN harmonization talks reshape cross-border equipment certification requirements.
Market Dynamics
Zero-liquid-discharge mandates across India's textile corridors and China's dual carbon enforcement are compressing membrane replacement cycles and forcing technology upgrades ahead of scheduled capital refresh timelines.
Growth Catalysts
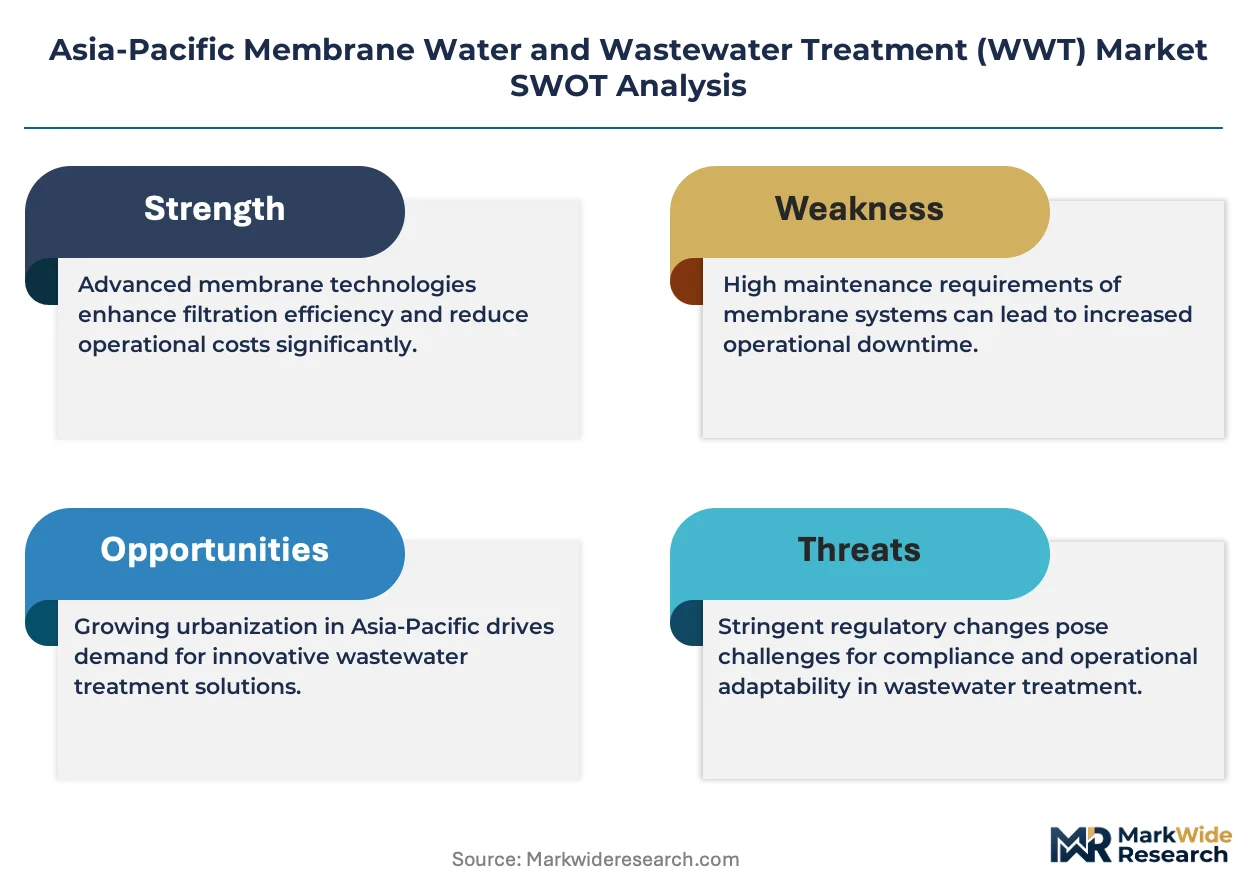
- MEE discharge limits:China's Ministry of Ecology and Environment enforces progressively tighter industrial effluent standards, compelling facilities to retrofit conventional activated sludge systems with membrane bioreactor technology.
- Semiconductor fabs:Ultrapure water requirements for chip manufacturing in Taiwan and South Korea are anchoring demand for high-flux reverse osmosis modules with polyamide thin-film composite membranes.
- Land scarcity:Urban utilities across Southeast Asia are adopting membrane bioreactors to achieve tertiary treatment within constrained footprints, eliminating secondary clarifier requirements.
Market Restraints
- Polymer feedstock volatility:Polysulfone and polyvinylidene fluoride resin prices fluctuate with crude oil derivatives, compressing module manufacturing margins and destabilizing project economics.
- Spare parts concentration:Hollow-fiber membrane replacement inventory concentrates with Japanese and Korean suppliers, exposing Australian and Southeast Asian operators to extended lead times.
- Energy intensity:Reverse osmosis operations at 4.0-6.0 MPa transmembrane pressure impose electricity costs that disadvantage membrane adoption against thermal desalination in markets with subsidized natural gas.
Strategic Opportunities
- Vietnam industrial zones:Textile and electronics manufacturing clusters around Ho Chi Minh City and Hanoi remain underpenetrated by membrane systems, presenting first-mover positioning ahead of anticipated discharge rule tightening.
- Integrated O&M contracts:Performance-based service agreements bundling membrane replacement, chemical cleaning, and remote monitoring are displacing transactional equipment sales in Australian municipal procurement.
- ISO 14001 alignment:Australia's environmental management certification requirements and Japan's METI circular-economy roadmaps are creating preference premiums for membrane vendors with verified lifecycle assessments.
Industry Challenges
- Membrane fouling expertise:Specialized operators capable of diagnosing biofouling versus inorganic scaling in mixed industrial effluents remain scarce across Southeast Asian service markets.
- Legacy infrastructure integration:Retrofitting membrane modules into existing concrete basins and pumping stations requires custom civil engineering that extends project timelines and inflates capital costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market |
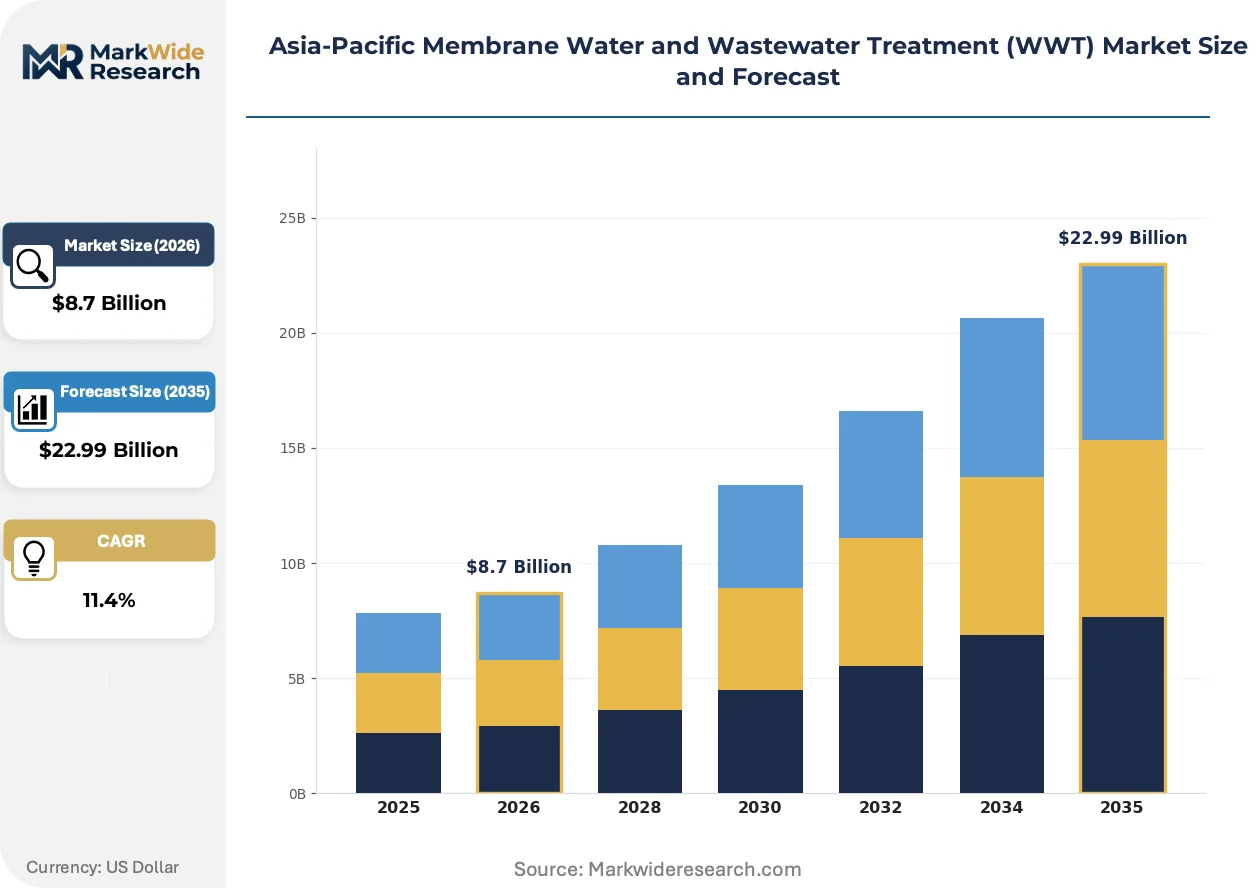
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reverse Osmosis, Ultrafiltration, Microfiltration, Nanofiltration End User: Municipal, Industrial, Residential, Agricultural Technology: Membrane Bioreactor, Filtration Systems, Desalination, Activated Sludge Application: Drinking Water Treatment, Wastewater Recycling, Desalination Process, Effluent Treatment |
| Companies Covered | Asahi Kasei Corporation, Aquatech International LLC., Veolia, Koch Membrane Systems, Inc., Suez, Kurita Water Industries Ltd., Evoqua Water Technologies LLC, Alfa Laval, TORAY INDUSTRIES, INC., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market Strategic Shifts
Membrane technology advancement is bifurcating between high-performance specialty materials for semiconductor and pharmaceutical applications and cost-optimized configurations for municipal scale-out.
Ceramic membrane modules with aluminum oxide or titanium dioxide substrates are displacing polymeric ultrafiltration in high-temperature industrial process streams and aggressive chemical cleaning regimes. Food and beverage processors across Australia and Japan are adopting ceramic systems for protein concentration and dairy whey recovery. The shift is compressing addressable demand for polysulfone hollow-fiber replacements in thermal and pH-stressed applications.
Australia's TGA-aligned water quality frameworks and India's CPCB zero-liquid-discharge directives are mandating tertiary treatment capabilities that conventional biological processes cannot achieve. Industrial facilities in Gujarat and Tamil Nadu are responding by procuring integrated membrane bioreactor-reverse osmosis trains rather than sequential upgrades. The regulatory convergence is accelerating technology refresh cycles and consolidating vendor relationships around full-system suppliers.
Performance guarantees and chemical optimization subscriptions are displacing capital equipment transactions in municipal and industrial procurement. Australian water utilities and Indian special economic zone operators are negotiating availability-based contracts where membrane suppliers retain module ownership and absorb fouling-related replacement risk. The model is most visible in desalination and high-purity industrial water segments where operational expertise differentiates vendor selection beyond initial capex comparison.
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market Segmentation
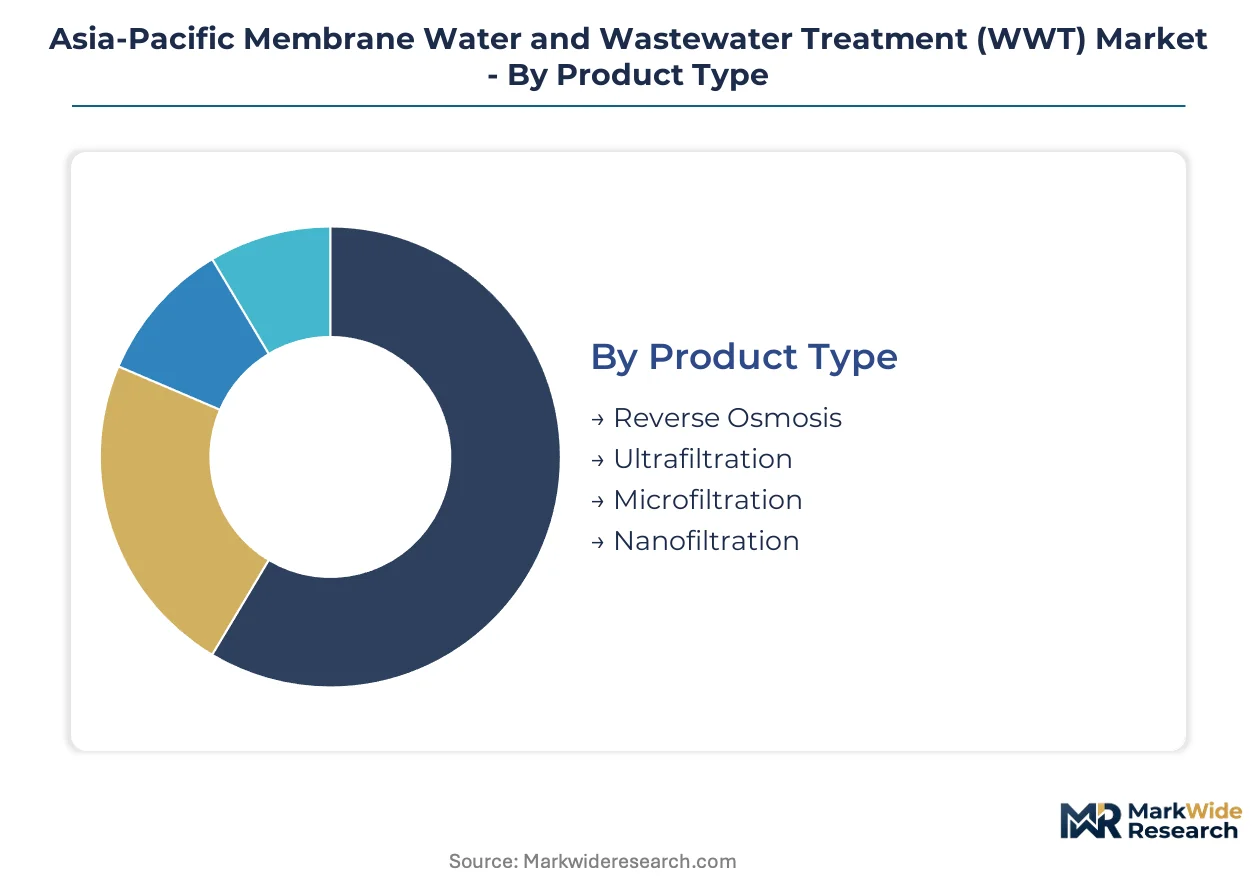
Membrane technology selection in Asia-Pacific hinges on effluent chemistry, energy economics, and regulatory stringency. Procurement patterns diverge sharply between municipal utilities prioritizing lifecycle cost and industrial operators responding to discharge mandates.
Product Type:
China's MEE and India's CPCB enforce divergent contaminant limits that reshape module specification across jurisdictions.
- Reverse Osmosis:Polyamide thin-film composite membranes operating at 4.0-6.0 MPa transmembrane pressure achieve dissolved solids rejection exceeding 99 percent. Semiconductor fabs in Taiwan and South Korea anchor demand for high-flux configurations producing ultrapure water for chip fabrication.
- Ultrafiltration:Hollow-fiber polysulfone or polyvinylidene fluoride modules with 0.01-0.1 micron pore ratings serve as pre-treatment barriers. Australia's municipal retrofit programs and Japan's aging water infrastructure drive replacement cycles in established utility networks.
- Microfiltration:Larger 0.1-10 micron pore structures target suspended solids and bacterial removal in food and beverage processing across Thailand and Vietnam.
- Nanofiltration:Selective divalent ion rejection suits softening applications and selective contaminant removal in industrial process water loops.
Established volume favors Reverse Osmosis; emerging adoption favors Ultrafiltration.
End User:
Customer procurement sophistication spans from centralized government tenders to fragmented industrial site specifications.
- Municipal:Urban utilities across Southeast Asia deploy membrane bioreactors to eliminate secondary clarifiers and compress plant footprints. Land scarcity in Jakarta, Manila, and Ho Chi Minh City accelerates technology substitution ahead of conventional activated sludge depreciation cycles.
- Industrial:Textile clusters in Gujarat and Tamil Nadu face zero-liquid-discharge directives from India's CPCB that mandate membrane-based tertiary treatment. Electronics manufacturers in Vietnam's industrial zones are pre-positioning for anticipated discharge rule tightening.
- Residential:Point-of-use reverse osmosis units penetrate affluent urban households in Australia and Japan seeking TGA-aligned drinking water quality.
- Agricultural:Drought-prone regions in Australia's Murray-Darling basin deploy membrane filtration for irrigation water recycling and salinity management.
Industrial procurement exhibits steepest expansion trajectory; Municipal contracts concentrate vendor relationships around long-term service agreements.
Technology:
Process intensification demands are compressing technology refresh timelines across the region's industrial corridors.
- Membrane Bioreactor:Integrated suspended growth biological treatment with membrane solids separation achieves tertiary effluent quality within 40-60 percent of conventional activated sludge footprint. Urban utilities in China and Southeast Asia adopt MBR configurations where land constraints override energy cost premiums.
- Filtration Systems:Pressure-driven and vacuum-driven membrane configurations span ultrafiltration through microfiltration ratings for solids-liquid separation.
- Desalination:Seawater reverse osmosis trains with energy recovery devices supply municipal water to coastal cities across Australia and the Middle East corridor of the region.
- Activated Sludge:Conventional biological treatment retains share in cost-sensitive markets where discharge standards permit secondary effluent quality without membrane polishing.
Membrane Bioreactor technology is gaining share fastest; Activated Sludge retains residual position in price-sensitive procurement.
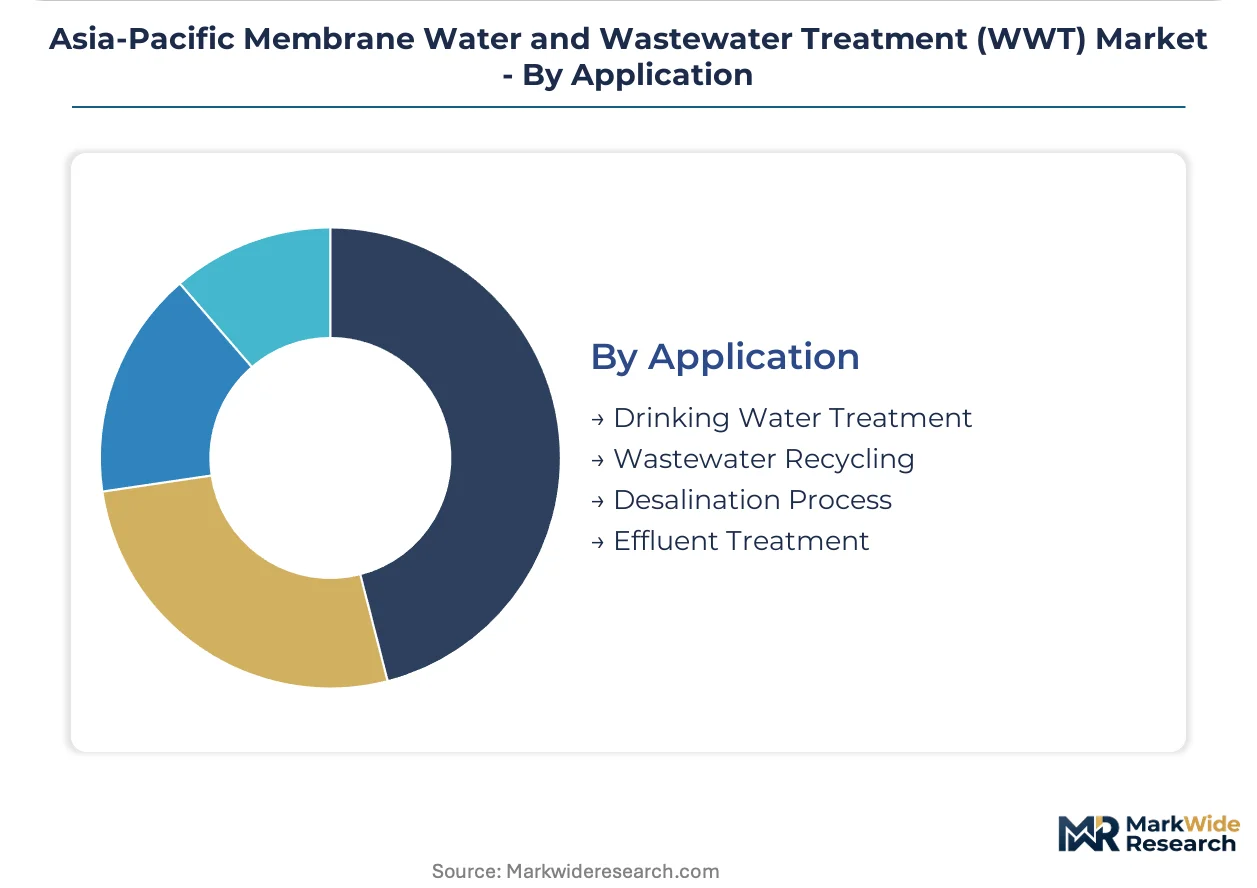
Application:
End-use specification intensity ranges from pharmaceutical-grade ultrapure water to agricultural irrigation standards.
- Drinking Water Treatment:Surface water and groundwater membrane filtration for pathogen removal and aesthetic quality improvement serves municipal distribution networks across Japan and Australia.
- Wastewater Recycling:Industrial process water recovery and municipal non-potable reuse applications expand in water-stressed regions of India and Australia.
- Desalination Process:Seawater and brackish water reverse osmosis for potable supply concentrates in Australian coastal cities and island nations throughout Southeast Asia.
- Effluent Treatment:Pre-discharge polishing for industrial facilities responding to China's MEE limits and India's sector-specific zero-liquid-discharge mandates.
Desalination Process commands premium pricing; Wastewater Recycling climbs fastest on regulatory tightening and water scarcity convergence.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's dual carbon goals and India's zero-liquid-discharge mandates are compressing membrane replacement cycles across industrial corridors. Municipal utilities from Australia to Vietnam are retrofitting aging infrastructure to meet tightening effluent standards. The regional landscape fragments across divergent regulatory intensities and procurement sophistication levels.
China
Semiconductor fabs in the Yangtze River Delta and Pearl River Delta anchor demand for high-flux reverse osmosis modules. The Ministry of Ecology and Environment enforces progressively tighter industrial discharge limits that compel facilities to upgrade from conventional activated sludge systems. Textile and electronics manufacturers in Zhejiang and Guangdong provinces are pre-positioning membrane bioreactor technology ahead of scheduled capital refresh timelines.
India
Textile clusters in Gujarat and Tamil Nadu face zero-liquid-discharge directives from the Central Pollution Control Board that mandate membrane-based tertiary treatment. The country's special economic zone operators are negotiating availability-based contracts where membrane suppliers retain module ownership. Industrial facilities around Ahmedabad and Coimbatore are procuring integrated membrane bioreactor-reverse osmosis trains rather than sequential upgrades.
Japan
Aging water infrastructure in the Kanto and Kansai regions drives replacement cycles for hollow-fiber ultrafiltration modules. The Ministry of Economy, Trade and Industry circular-economy roadmaps create preference premiums for vendors with verified lifecycle assessments. Municipal retrofit programs in Tokyo and Osaka concentrate procurement around established utility networks with long-term service agreements.
Australia
Coastal cities deploy seawater reverse osmosis trains with energy recovery devices for municipal water supply. The Therapeutic Goods Administration-aligned water quality frameworks and ISO 14001 environmental management certification requirements reshape vendor selection criteria. Desalination plants in Perth and Sydney sustain competitive positioning through integrated operations and maintenance contracts.
Vietnam
Textile and electronics manufacturing clusters around Ho Chi Minh City and Hanoi remain underpenetrated by membrane systems. Anticipated discharge rule tightening from the national environmental regulator is accelerating first-mover positioning among industrial zone developers. Food and beverage processors are adopting ceramic membrane systems for protein concentration in thermal and pH-stressed applications.
Asia-Pacific Membrane Water and Wastewater Treatment (WWT) Market Competitive Environment
Listed leaders compete with private specialists across technology licensing and service contract dimensions in a moderately consolidated vendor base. Japanese and Korean suppliers dominate hollow-fiber membrane manufacturing, while European operators anchor integrated O&M capabilities. Three archetypes define competitive positioning: materials-focused module fabricators, full-system integrators with captive service arms, and regional EPC contractors sourcing third-party membranes. Dominant competitive moves include backward integration into polymer resin production and geographic expansion through performance-based service agreements.
Within the premium-tier materials segment, Asahi Kasei Corporation and TORAY INDUSTRIES, INC. represent Japanese-listed leaders with hollow-fiber and reverse osmosis expertise respectively. Veolia occupies a position exemplifying the integrated service archetype through bundled operations and maintenance contracts. These three anchors demonstrate how competitive differentiation concentrates around either proprietary membrane substrate technology or long-term operational risk absorption rather than equipment transactions alone.
| Leading Market Players |
|---|
| Asahi Kasei Corporation |
| Aquatech International LLC. |
| Veolia |
| Koch Membrane Systems, Inc. |
| Suez |
| Kurita Water Industries Ltd. |
| Evoqua Water Technologies LLC |
| Alfa Laval |
| TORAY INDUSTRIES, INC. |
| Others |
Value Chain & Pricing Dynamics
Capacity utilization at Japanese and Korean hollow-fiber membrane plants sits above 85 percent, compressing available supply for Australian and Southeast Asian operators and establishing price floors that resist downward pressure despite polymer feedstock volatility. This scale concentration simultaneously amplifies procurement leverage for volume buyers and extends lead times for fragmented municipal utilities without consolidated purchasing power.
Pricing Analysis
Certification level creates the primary spread between membrane module tiers, with ISO 9001-verified manufacturing commanding 15-25 percent premiums over uncertified alternatives in Australian municipal tenders. Three-tier pricing structure across premium, standard, and economy levels reflects performance durability guarantees and chemical cleaning cycle tolerances. Cost compression in the economy tier is intensifying because Chinese module fabricators are expanding polysulfone hollow-fiber capacity. Industrial zero-liquid-discharge operators exhibit lowest price sensitivity due to regulatory compliance deadlines, while Vietnamese textile processors remain most cost-constrained.
Supply Chain Analysis
Inventory concentration for polyamide thin-film composite membranes extends replacement lead times to 12-16 weeks for Australian desalination operators, forcing advance procurement commitments that strain working capital. Manufacturing gravity centers on Japan, South Korea, and China for hollow-fiber and spiral-wound configurations. Raw material sourcing draws from Saudi Arabian and Qatari petrochemical complexes for polysulfone resin, Belgian and German specialty chemical producers for polyamide intermediates, and Chinese titanium dioxide suppliers for ceramic membrane substrates. Single-source vulnerability concentrates with Japanese suppliers for high-flux reverse osmosis elements specified in semiconductor ultrapure water systems. Distribution runs through regional EPC contractors and integrated service providers rather than direct module sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane water treatment is experiencing technology substitution acceleration as China's MEE discharge limits and India's CPCB zero-liquid-discharge mandates compress replacement cycles ahead of conventional depreciation schedules.
For Market Incumbents: Compound defensive positioning through backward integration into polyvinylidene fluoride resin production and captive hollow-fiber spinning capacity to offset polymer feedstock volatility. Secure long-term operations and maintenance contracts with Australian municipal utilities to lock out emerging competitors. The threat of ceramic membrane displacement in high-temperature food processing applications demands accelerated polysulfone performance upgrades. For New Entrants and Emerging Players: Anchor in Vietnam's underpenetrated textile and electronics manufacturing corridors around Ho Chi Minh City and Hanoi, where discharge rule tightening remains anticipated rather than enforced. Target integrated membrane bioreactor-reverse osmosis train procurement in India's Gujarat and Tamil Nadu special economic zones, where availability-based contracting models reduce upfront capital barriers. Pursue partnership structures with established Japanese or Korean membrane fabricators for technology licensing rather than independent substrate development. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among full-system integrators with captive service arms absorbing operational risk through performance-based contracts. The 5-10 year viability window favors vendors with verified lifecycle assessments aligned to Japan's METI circular-economy roadmaps and Australia's ISO 14001 environmental certification requirements. Acquisition targets should demonstrate ceramic membrane manufacturing expertise or integrated O&M capabilities in water-stressed industrial corridors. Monitor ASEAN harmonization talks on cross-border equipment certification as a signal for regional consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Production | Captive polysulfone supply insulates margin compression from crude oil derivative volatility. |
| Integrated O&M Contract Expansion | Performance-based service agreements with Australian utilities displace transactional equipment sales. |
| Ceramic Membrane Manufacturing Scale-Up | Aluminum oxide substrate production captures food and beverage processing demand in Japan and Australia. |
| Vietnam Industrial Zone First-Mover Positioning | Early membrane system deployment ahead of anticipated CPCB-aligned discharge rules secures anchor customers. |
| Lifecycle Assessment Certification Investment | Verified environmental credentials unlock preference premiums in Japan's METI circular-economy procurement. |
Study Parameters
A spread of perspectives from membrane module manufacturing executives, municipal utility procurement directors, industrial plant engineers, EPC project managers, and aftermarket service operators converged on the working assumptions underlying demand forecasts. Primary field engagement combined structured interviews with secondary validation through MEE discharge limit notifications, CPCB zero-liquid-discharge directives, TGA water quality frameworks, and METI circular-economy policy documents. Customs data on polysulfone and polyvinylidene fluoride resin trade flows, alongside desalination plant capacity registers, provided volume anchors. Bottom-up module shipment analysis triangulated against top-down water infrastructure investment tracking.
Segmentation dimensions modeled span product type (reverse osmosis, ultrafiltration, microfiltration, nanofiltration), end user (municipal, industrial, residential, agricultural), technology (membrane bioreactor, filtration systems, desalination, activated sludge), and application (drinking water treatment, wastewater recycling, desalination process, effluent treatment) across the projection horizon. CAGRs derived from installed base replacement cycles, regulatory compliance deadlines, and technology substitution elasticities. Forecast inputs incorporated semiconductor fab capacity expansion in Taiwan and South Korea, textile cluster zero-liquid-discharge enforcement trajectories in India, and urban land scarcity constraints in Southeast Asian megacities.
Material uncertainties — polymer feedstock price spikes, ASEAN regulatory harmonization delays, ceramic membrane substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about MEE enforcement consistency, CPCB sectoral coverage expansion, and METI procurement guideline adoption rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Australia & New Zealand Water Treatment Chemicals Market
Water & Sludge Treatment
Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Anionic Flocculants Market
Water & Sludge Treatment
Process Water Treatment Market
Water & Sludge Treatment
Drinking Water Adsorbents Market
Water & Sludge Treatment
Hazardous Waste Treatment System Market
Water & Sludge Treatment
Europe Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Global Sludge Treatment Chemicals Market
Water & Sludge Treatment
Polish Water Treatment Chemicals Market
Water & Sludge Treatment
North America Industrial Water Treatment Market
Water & Sludge Treatment
Water Dispersible Granules Market
Water & Sludge Treatment
Salt Water Softeners Market
Water & Sludge Treatment
Global Valves in Water and Wastewater Market
Water & Sludge Treatment
Water Treatment Market
Water & Sludge Treatment
Feedwater Treatment Chemicals Market
Water & Sludge Treatment
North America Membrane Water Treatment Chemicals Market