
 Ballast Water Treatment Market | 2026-2036
Ballast Water Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Ballast Water Treatment Market Analysis
Market Context with Strategic Players
The IMO Ballast Water Management Convention is decoupling compliance costs from vessel age, forcing owners to treat retrofit deadlines as fleet-wide capital events rather than staggered obligations. PANASIA CO. LTD leverages its Korean shipyard partnerships to dominate retrofit installations across Panamax and Capesize classes. Alfa Laval AB sustains technology leadership through continuous R&D in UV reactor efficiency and filtration integration. Wärtsilä Corporation anchors its position with full-service contracts spanning engineering, commissioning, and lifecycle parts supply.
Technical Definition and Structural Segments
Ballast water treatment encompasses physical, chemical, and biological processes designed to remove, neutralize, or render harmless aquatic organisms and pathogens carried in ships' ballast tanks, with systems typically achieving organism reduction targets measured per cubic meter of discharged water. UV treatment systems occupy the fastest-expanding technology tier as ship operators favor chemical-free compliance paths that avoid residual toxicity concerns and port-state detention risks. Shore-based solutions concentrate margin pools where port authorities monetize centralized treatment for vessels lacking onboard capacity, while onboard filtration systems retain volume leadership due to mandatory newbuild specifications.
Regulatory Frame and Forward-Looking Close
The USCG enforces type-approval standards that exceed IMO baseline requirements, creating a dual-certification burden for manufacturers serving trans-Pacific routes, while the EU Marine Strategy Framework Directive extends ballast discharge monitoring into European port waters. National regulators in China and South Korea are aligning domestic type-approval processes with IMO guidelines, compressing certification timelines for regional suppliers. Stakeholders must monitor divergence between USCG and IMO testing protocols, as any harmonization gap will dictate which technology platforms capture retrofit contracts across the major flag states.
Market Dynamics
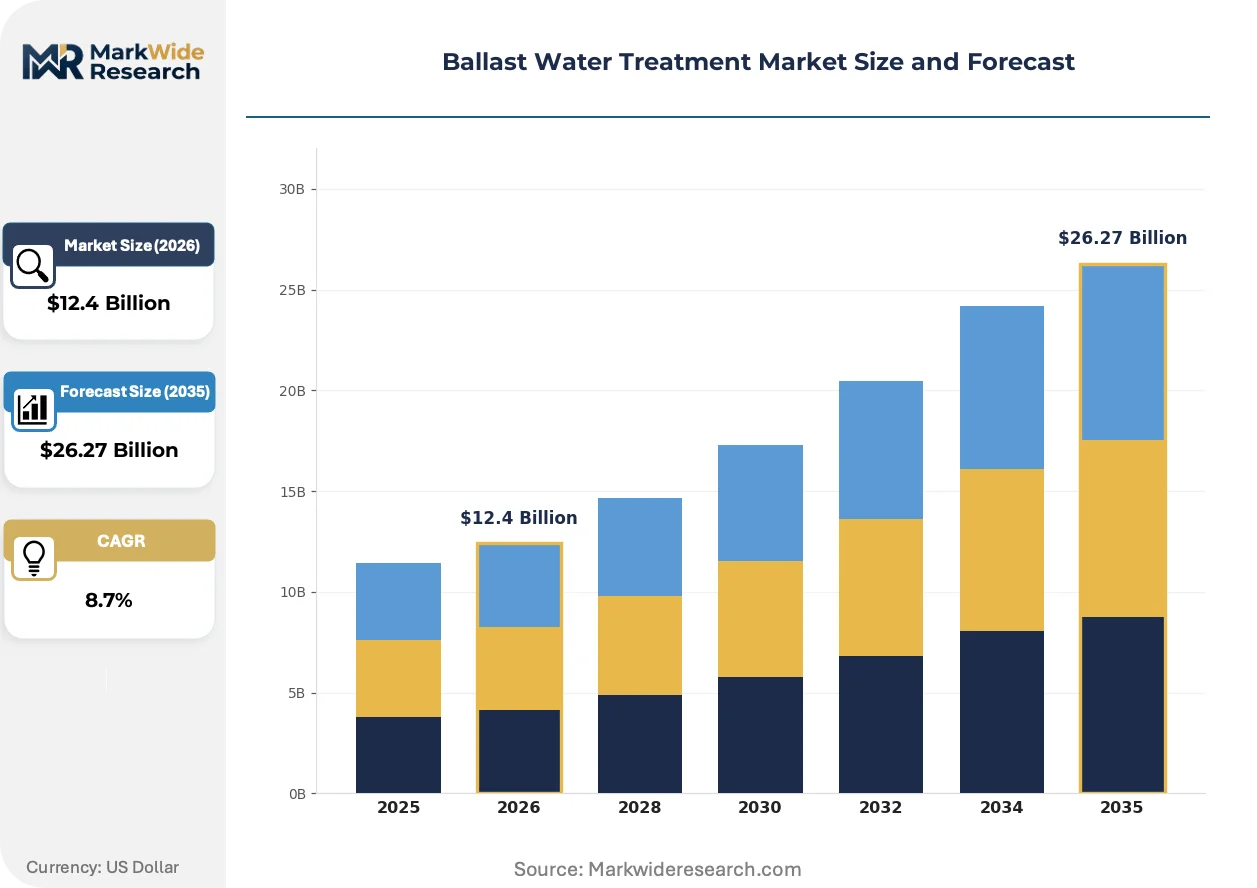
The retrofit deadline compression from IMO's Ballast Water Management Convention is forcing shipowners to synchronize fleet-wide compliance spending, collapsing what was a staggered replacement cycle into concentrated capital deployment between 2026 and 2030.
Growth Catalysts
- IMO Convention Enforcement:The International Maritime Organization's discharge standards now apply to all international voyages, compelling owners of older tonnage to install treatment systems before renewal surveys.
- UV Technology Maturation:Ultraviolet reactor systems have achieved power-density thresholds that allow retrofit installation without engine-room reconfiguration, accelerating uptake on Panamax bulk carriers.
- East Asian Shipbuilding:South Korean and Chinese yards are bundling treatment systems into newbuild contracts, creating captive demand that locks in supplier relationships for 15-25 year vessel lifecycles.
Market Restraints
- Titanium Electrode Supply:UV system manufacturers depend on Japanese and Russian titanium suppliers for reactor components, exposing production schedules to geopolitical supply interruptions.
- Dual Certification Burden:The USCG type-approval process requires separate testing protocols from IMO guidelines, forcing manufacturers to maintain parallel validation programs for trans-Pacific routes.
- Filtration System Saturation:Physical separation technologies face displacement pressure as chemical-free UV alternatives capture retrofit preference, limiting expansion headroom for established filtration suppliers.
Strategic Opportunities
- Shore-Based Treatment Hubs:Port authorities in Singapore and Rotterdam are developing centralized ballast processing facilities for vessels lacking onboard capacity, creating recurring revenue streams from per-cubic-meter discharge fees.
- Digital Monitoring Integration:Real-time organism detection sensors are converging with automated logging systems to satisfy port-state documentation requirements without manual sampling.
- EU Marine Strategy Extension:The European Commission's discharge monitoring mandates are expanding ballast water surveillance into coastal waters, generating aftermarket demand for sensor upgrades on EU-flagged fleets.
Industry Challenges
- Commissioning Engineer Shortage:The specialized workforce required for system validation and crew training cannot scale with retrofit demand, extending installation timelines at major conversion yards.
- Legacy Tank Compatibility:Pre-2000 vessels with uncoated ballast tanks face corrosion complications during UV piping installation, requiring unanticipated structural remediation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ballast Water Treatment Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $26.27 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Filtration, Chemical Treatment, UV Treatment, Ozone Treatment End User: Shipping Lines, Port Authorities, Environmental Agencies, Research Institutions Deployment: Onboard Systems, Shore-based Solutions, Modular Units, Centralized Treatment Facilities Regulatory Compliance: IMO Standards, USCG Regulations, EU Directives, National Guidelines |
| Companies Covered | PANASIA CO. LTD, Evoqua Water Technologies LLC, Wärtsilä Corporation, Veolia Water Technologies, Mitsubishi Heavy Industries Ltd., Alfa Laval AB, ERMA FIRST ESK Engineering Solutions S.A., Headway Technology Group Co. Ltd., Xylem Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ballast Water Treatment Market Emerging Trajectories
Technology convergence between filtration, UV irradiation, and automated monitoring is compressing system footprints and enabling installation on vessels previously excluded by space constraints.
Advanced oxidation processes using ozone and hydrogen peroxide are integrating electrochemical cell technology to reduce energy consumption below 50 kWh per 100 cubic meters treated. Container line operators are piloting these hybrid systems on neo-Panamax vessels where power allocation is constrained by reefer cargo loads. The technology is integrating shore-power compatibility that allows pre-treatment during port stays, reducing at-sea power draw.
The EPA's Vessel General Permit renewal is tightening organism discharge limits in US waters beyond IMO baseline standards, creating a regulatory premium for systems achieving sub-10 viable organisms per cubic meter. Manufacturers serving trans-Pacific routes must maintain dual validation protocols, with USCG type-approval timelines extending 18-24 months. Chemical treatment suppliers are responding with enhanced dosing automation to satisfy port-state inspection protocols.
Charterers are inserting ballast compliance clauses into time-charter agreements, transferring system performance risk from owners to operators. This contractual shift is displacing traditional owner-operated maintenance models with third-party service contracts covering sensor calibration and filter replacement. The pattern is most visible in Singapore and London maritime clusters where commodity traders control vessel deployment.
Ballast Water Treatment Market Segmentation
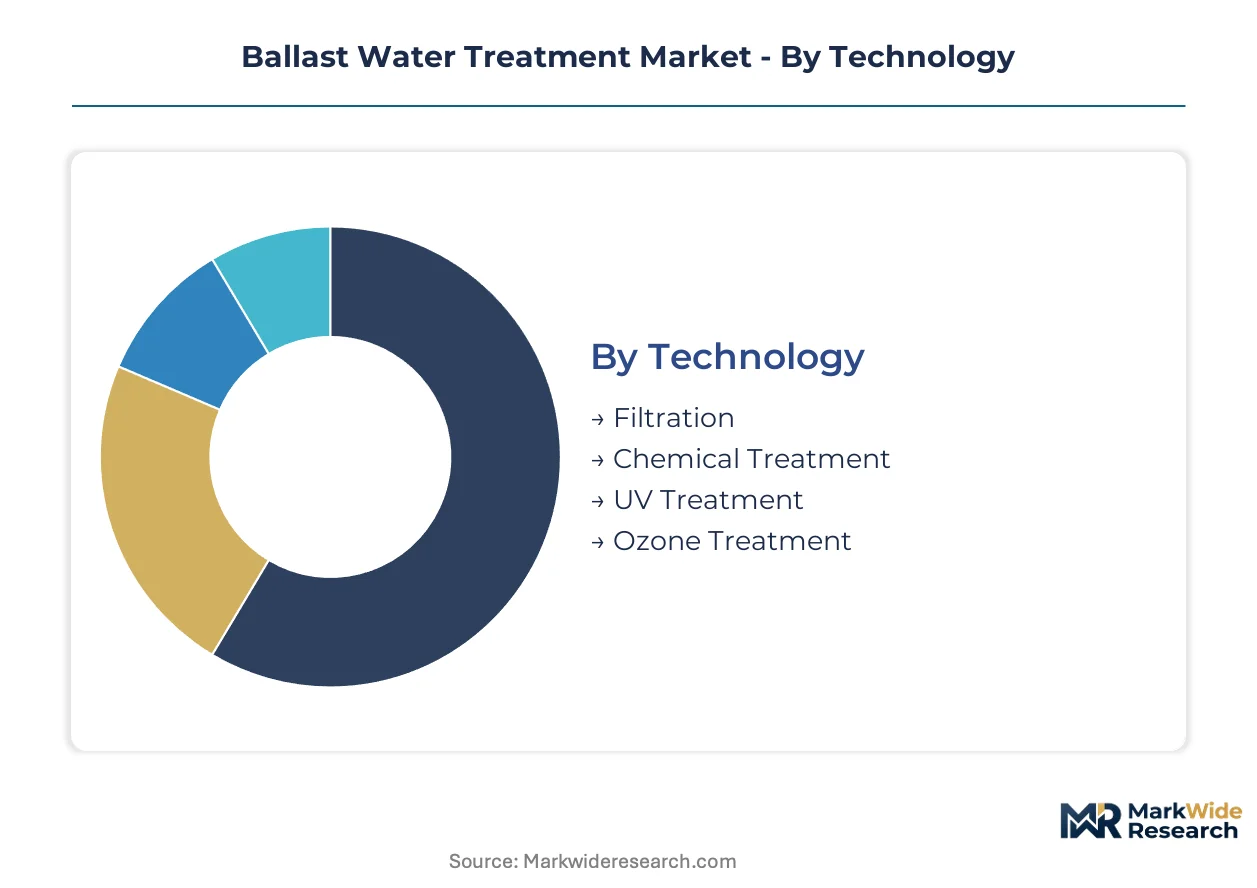
Technology choice in ballast water treatment locks shipowners into fifteen-year maintenance commitments and determines port-state detention risk. Deployment mode separates newbuild specifications from retrofit economics, while regulatory compliance tier dictates which routes a vessel can legally serve.
Technology:
Cost tier separates chemical-dependent systems from capital-intensive physical alternatives, with power availability and crew training levels driving selection.
- Filtration:Physical separation systems remove organisms above 50 microns through automatic back-flush screens and hydrocyclone assemblies. Demand concentrates in newbuild contracts at South Korean yards where shipowners specify proven mechanical reliability over unproven chemical alternatives. Volume sits with Filtration; growth tilts toward UV Treatment.
- Chemical Treatment:Active substance dosing uses chlorine-based oxidants or biocides to neutralize remaining organisms post-filtration. Port authorities in Rotterdam and Singapore favor these systems for shore-based installations where residual neutralization can be controlled.
- UV Treatment:Ultraviolet irradiation destroys organism DNA without chemical residuals, satisfying USCG and EPA discharge limits for trans-Pacific routes. Norwegian and Finnish suppliers dominate reactor manufacturing.
- Ozone Treatment:Advanced oxidation generates ozone in-situ through corona discharge or electrolytic cells, achieving high log-reduction rates for resistant pathogens. Energy consumption limits adoption to vessels with surplus generating capacity.
Shipowners with Panamax bulk carriers favor UV systems; chemical treatment climbs fastest in port infrastructure projects.
End User:
Application separates vessel-operating entities from regulatory enforcement bodies, with procurement authority and risk ownership dividing the customer base.
- Shipping Lines:Container operators and bulk carriers bear capital costs for onboard installation and lifecycle maintenance. CMA CGM and Maersk retrofits concentrate demand in East Asian conversion yards during statutory survey windows.
- Port Authorities:Singapore PSA and Rotterdam Port Authority deploy centralized reception facilities for vessels lacking compliant onboard systems. Revenue models charge per-cubic-meter processing fees with guaranteed throughput contracts.
- Environmental Agencies:EPA and EEA fund demonstration projects and monitor enforcement compliance through discharge sampling programs. Grants support technology validation in emerging supplier markets.
- Research Institutions:DHI Denmark and SINTEF Norway conduct organism efficacy testing and develop alternative compliance metrics for polar route exceptions.
Procurement volume concentrates with Shipping Lines; Port Authorities expand most quickly as retrofit deadlines compress.
Deployment:
Customer type separates permanent installations from temporary or shared infrastructure, with asset ownership and operational control defining contract structures.
- Onboard Systems:Fixed installation within engine rooms or pump rooms treats ballast during voyage. Newbuild specifications at Chinese yards lock in supplier relationships for vessel lifecycles.
- Shore-based Solutions:Land-based reception facilities at Antwerp and Hamburg process ballast for coastal traders and legacy tonnage. Port operators monetize through mandatory use regulations.
- Modular Units:Containerized skids enable rapid deployment for spot charter vessels and temporary fleet coverage. Leasing models transfer technology obsolescence risk from owners to equipment providers.
- Centralized Treatment Facilities:Regional hubs at Strait of Malacca chokepoints serve multiple ports through pipeline networks. Scale economies reduce per-unit treatment costs below onboard alternatives.
Onboard Systems capture current installation volume; Shore-based Solutions gain share fastest as port states mandate reception facilities.
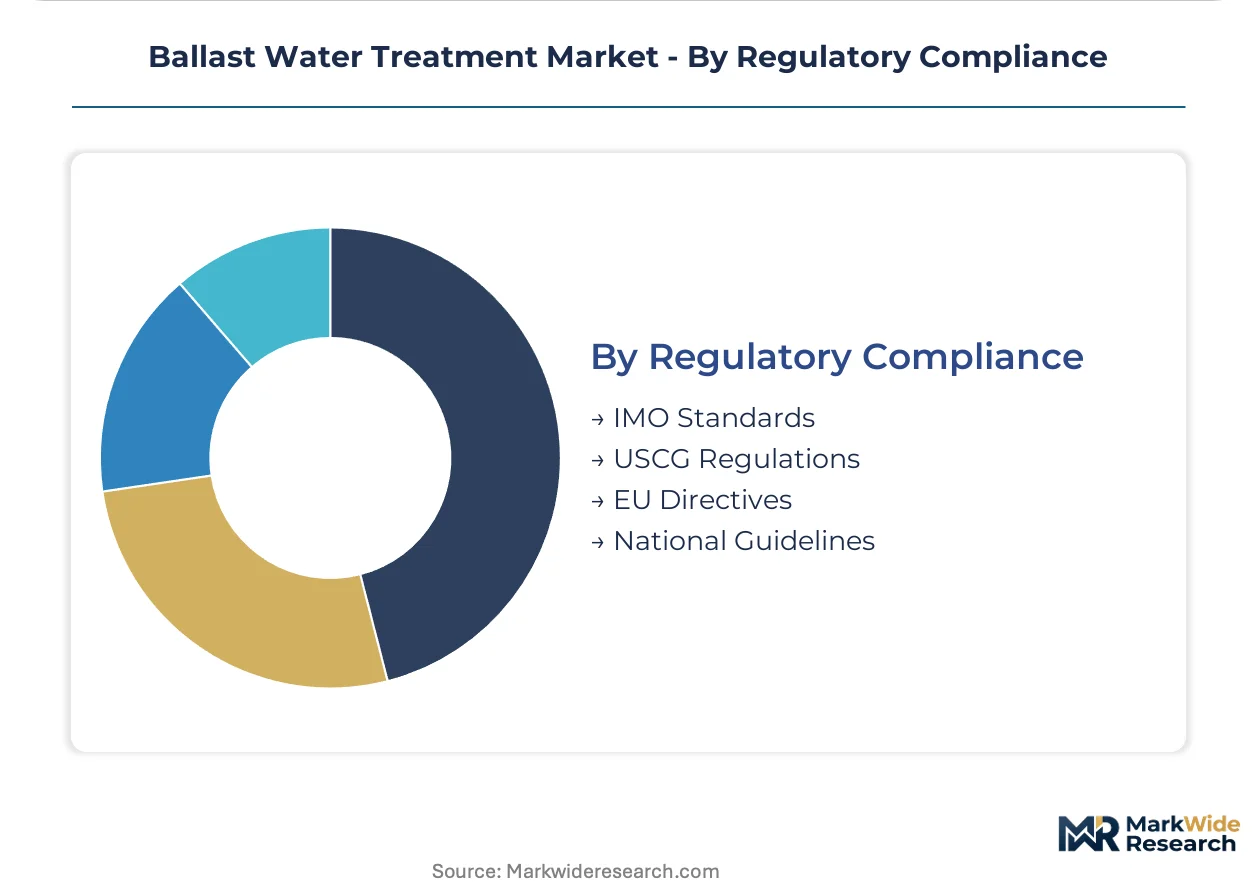
Regulatory Compliance:
Maturity separates established international conventions from evolving national standards, with certification burden and testing protocol divergence shaping supplier strategy.
- IMO Standards:The Ballast Water Management Convention sets baseline organism reduction targets and type-approval procedures. Compliance certificates from classification societies enable global trading.
- USCG Regulations:United States Coast Guard type-approval exceeds IMO organism limits, requiring separate validation for trans-Pacific routes. Testing protocols extend certification timelines.
- EU Directives:The Marine Strategy Framework Directive extends monitoring into European coastal waters and territorial seas. Port state control inspections verify discharge documentation.
- National Guidelines:China's MEE and South Korea's MFDS operate domestic approval processes aligned with but distinct from IMO procedures. Regional suppliers benefit from compressed certification timelines.
Certification volume concentrates with IMO Standards; USCG Regulations drive the steepest expansion trajectory as manufacturers pursue dual validation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for ballast water treatment systems concentrates in maritime economies with dense port infrastructure and active shipbuilding bases. South Korean and Chinese yards currently dominate newbuild specifications, while European and North American operators drive retrofit urgency through stringent enforcement timelines.
China
Domestic shipbuilding orders at Dalian and Shanghai yards are bundling treatment systems into newbuild contracts at unprecedented scale. The Ministry of Ecology and Environment operates domestic type-approval processes that compress certification timelines for regional suppliers. Yangtze River Delta shipyards are retrofitting legacy bulk carriers ahead of IMO renewal survey windows.
South Korea
Hanjin and DSME facilities are accelerating Panamax and Capesize retrofits through partnerships with domestic equipment suppliers. The Ministry of Food and Drug Safety aligns national approval protocols with IMO guidelines, streamlining validation for regional manufacturers. Busan-Ulsan shipbuilding clusters are capturing conversion demand from Japanese and Greek shipowners.
United States
Trans-Pacific container operators face USCG type-approval requirements that exceed IMO baseline standards, forcing dual-certification investments. The EPA's Vessel General Permit renewal tightens organism discharge limits in coastal waters. Gulf Coast conversion yards in Texas and Louisiana are extending installation timelines due to commissioning engineer shortages.
Germany
Port authorities at Hamburg and Bremerhaven are developing shore-based reception facilities for coastal traders lacking onboard capacity. The EU Marine Strategy Framework Directive extends discharge monitoring into German territorial waters. North Rhine-Westphalia engineering clusters are supplying filtration components to Scandinavian system integrators.
Singapore
PSA Corporation is monetizing centralized ballast processing through per-cubic-meter discharge fees with guaranteed throughput contracts. The Maritime and Port Authority mandates reception facility usage for specific vessel classes. The Strait of Malacca chokepoint is attracting regional hub investments from European port operators.
Ballast Water Treatment Market Vendor Landscape
Nordic and Korean producers anchor one tier; North American and Japanese specialists hold differentiated positions in chemical treatment and advanced oxidation. Market structure tilts toward consolidation among full-service providers capable of engineering, commissioning, and lifecycle parts supply. Three archetypes dominate: shipyard-integrated suppliers, standalone technology licensors, and port infrastructure operators. Capacity expansion and strategic partnerships represent the dominant competitive moves as retrofit deadlines compress installation windows.
Within the shipyard-integrated tier, PANASIA CO. LTD and Wärtsilä Corporation exemplify full-service positioning across engineering and lifecycle support. Alfa Laval AB occupies a specialist position in UV reactor efficiency. Evoqua Water Technologies LLC and Xylem Inc. represent North American exposure to shore-based treatment infrastructure. Mitsubishi Heavy Industries Ltd. anchors Japanese industrial conglomerate participation in advanced oxidation development.
| Leading Market Players |
|---|
| PANASIA CO. LTD |
| Evoqua Water Technologies LLC |
| Wärtsilä Corporation |
| Veolia Water Technologies |
| Mitsubishi Heavy Industries Ltd. |
| Alfa Laval AB |
| ERMA FIRST ESK Engineering Solutions S.A. |
| Headway Technology Group Co. Ltd. |
| Xylem Inc. |
| Others |
Supply Flow & Price Mechanics
The USCG type-approval mandate gates both qualified supply and premium-tier pricing access, compressing certification timelines for manufacturers while erecting entry barriers that protect validated incumbents from price erosion in trans-Pacific routes.
Pricing Analysis
Lead-time-driven pricing angles dominate procurement negotiations, with shipowners paying premiums for systems deliverable within compressed retrofit windows while spot inventory from non-validated suppliers trades at steep discounts. Three-tier pricing structure across IMO-only, dual-certified, and USCG-premium tiers separates compliance grades, with certification level and after-sales service bundling as primary differentiation drivers. Pricing pressure stems from titanium electrode supply constraints and commissioning engineer shortages. Coastal traders and legacy tonnage operators exhibit highest price sensitivity; container lines on trans-Pacific routes demonstrate lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from South Korean and Chinese shipyards, while aftermarket parts distribution runs through authorized service networks concentrated in Rotterdam, Singapore, and Houston. Manufacturing draws from Japanese and Russian titanium suppliers for UV reactor components, with Norwegian and Finnish engineering clusters supplying core reactor technology. Single-source vulnerability in electrode supply and logistics chokepoint exposure through the Strait of Malacca constitute primary structural risks. Distribution runs through shipyard-integrated procurement for newbuilds and third-party service contracts for retrofits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Commissioning engineer scarcity props pricing power for full-service providers capable of rapid installation turnaround, creating supply-constrained conditions that favor incumbents with validated training pipelines.
For Market Incumbents: Deepen shipyard partnership exclusivity in Busan-Ulsan and Yangtze River Delta clusters to lock out emerging UV reactor specialists from newbuild specifications. Expand captive titanium electrode inventory positions to insulate production schedules from Russian supply disruption. Certification investment in USCG dual-validation protocols remains the critical defensive lever against IMO-only competitors. For New Entrants and Emerging Players: Coastal traders operating legacy tonnage without onboard treatment capacity represent the most penetrable buyer archetype, particularly in Mediterranean and Southeast Asian short-sea routes. Shore-based modular units for port reception facilities offer faster path to revenue than onboard system development. Leasing models with technology refresh clauses provide differentiated go-to-market positioning against capital-sale incumbents. For Investors and Strategic Acquirers: USCG harmonization announcements with IMO testing protocols are the leading indicator that dual-certification burden will ease, compressing margins for specialists and favoring scaled full-service platforms. Long-term viability centers on providers with shipyard-integrated positioning and lifecycle parts revenue streams. Acquisition targets should combine validated reactor technology with established commissioning engineer networks. Monitor port authority mandatory reception facility regulations as demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Shipyard Partnership Exclusivity | Locks in newbuild specifications at DSME and Dalian yards for vessel lifecycle durations. |
| Dual-Certification Investment | Enables trans-Pacific route access beyond IMO-only competitors constrained to regional trades. |
| Commissioning Engineer Pipeline | Resolves installation bottleneck at Gulf Coast and Mediterranean conversion facilities. |
| Shore-Based Infrastructure Development | Captures recurring revenue from PSA Corporation and Rotterdam Port Authority throughput contracts. |
| Titanium Supply Diversification | Reduces dependency on Japanese and Russian electrode suppliers amid geopolitical volatility. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with shipyard procurement directors, port authority technical officers, and classification society surveyors with validation against IMO type-approval registries and USCG certification databases. Bottom-up installation volume estimates from South Korean and Chinese yard reports triangulated against top-down fleet compliance modeling.
Data-stream reconciliation across technology deployment records, newbuild order books, and retrofit yard capacity schedules informed analytical framework construction across the projection horizon. Segmentation dimensions modeled include treatment technology tier, deployment mode, regulatory compliance tier, and vessel size class. CAGRs derived from vessel fleet age profiles, statutory survey windows, and regional enforcement intensity trajectories. Forecast inputs incorporated titanium supply availability curves and commissioning workforce expansion assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to USCG-IMO protocol harmonization, alternative compliance pathway approvals, and shipowner scrapping decisions versus retrofit commitments. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and shipyard capacity expansion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Global Sodium Hypochlorite Market
Water & Sludge Treatment
Europe Membrane Bioreactor (MBR) Market
Water & Sludge Treatment
CMP Slurry Blend and Delivery Systems Market
Water & Sludge Treatment
North America Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
United States Water Treatment Chemicals Market
Water & Sludge Treatment
Drinking Water Adsorbents Market
Water & Sludge Treatment
Global Mobile Water Treatment Market
Water & Sludge Treatment
Semiconductor Wastewater Treatment Market
Water & Sludge Treatment
Electrodeionization (EDI) Technology Market
Water & Sludge Treatment
Europe Water Treatment Chemicals Market
Water & Sludge Treatment
Global Turbidity Meters Market
Water & Sludge Treatment
Hypochlorous Acid Water Generator Market
Water & Sludge Treatment
Swimming Pool Treatment Chemicals Market
Water & Sludge Treatment
Asia-Pacific Drilling Waste Management Services Market
Water & Sludge Treatment
Global Wet Waste Management Market
Water & Sludge Treatment
South America Membrane Water Treatment Chemicals Market