
 Single-Use Packaging Market | 2026-2036
Single-Use Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Single-Use Packaging Market Outlook
Asset-light leasing models for converting equipment are reshaping how mid-sized converters enter the single-use packaging arena. Tetra Pak leverages its integrated aseptic systems to dominate liquid food formats. Amcor sustains global film and flexible packaging capacity through continuous capital deployment across multiple continents. Huhtamaki Oyj specializes in fiber-based molded products, occupying a defensible niche as plastic restrictions tighten.
Single-use packaging encompasses containers, wraps, pouches, and trays engineered for one-time product protection, typically constructed from polymers, paperboard, aluminum foil, or biodegradable substrates with barrier coatings measured in oxygen transmission rates below 1 cc/m²/day. Its primary commercial purpose centers on preserving shelf stability, ensuring sanitary delivery, and enabling portion-controlled distribution across retail and foodservice channels. Plastics retain volume leadership due to cost efficiency and seal integrity, though biodegradable materials represent the fastest-expanding category as compostability certifications become procurement prerequisites. The Food & Beverage end-user segment anchors overall demand, while Healthcare applications command premium margin pools through sterilization-grade validation requirements.
The EU Packaging and Packaging Waste Regulation and FDA food-contact substance notifications jointly determine material approval pathways and recycling infrastructure investments across the Atlantic. ECHA REACH restrictions on per- and polyfluoroalkyl substances are forcing reformulation of grease-resistant paper coatings, redirecting R&D spending toward mineral and plant-derived alternatives. China's GB standards and SAMR food-contact material rules add a third compliance layer for suppliers serving export manufacturing clusters. Stakeholders must monitor how extended producer responsibility fee structures evolve, as these mechanisms will determine which material platforms achieve cost-competitive scale without cross-subsidy.
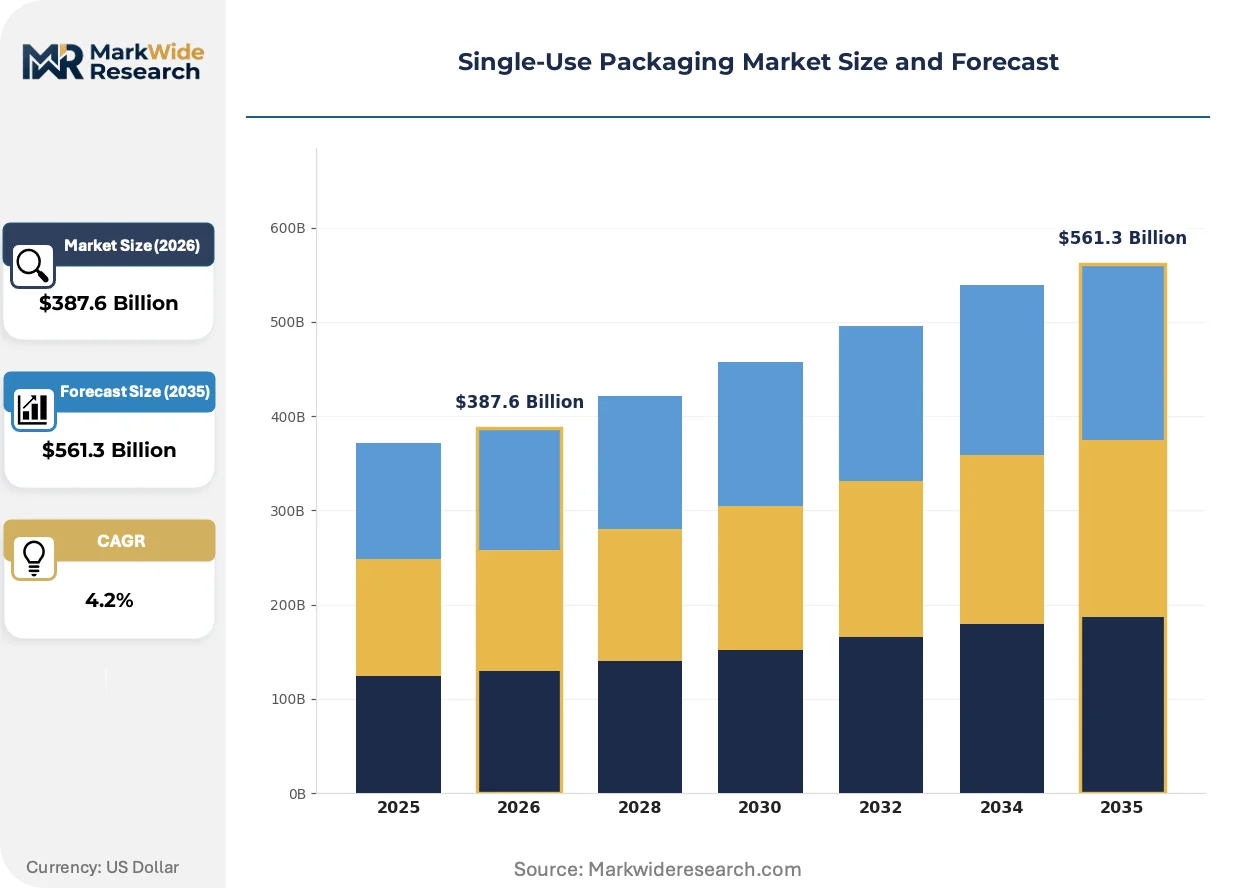
Market Dynamics
Extended producer responsibility frameworks across the EU, China, and US states are forcing converters to internalize end-of-life costs, compressing margins for virgin plastic formats while redirecting capital toward fiber and biopolymer lines.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recyclability targets and recycled content floors are pulling investment into compatible material platforms and sorting infrastructure.
- Foodservice channel expansion:QSR chains and cloud kitchen operators are standardizing single-use formats for delivery-optimized portion control and tamper-evidence.
- Barrier coating advances:Mineral and bio-derived grease-resistant layers are achieving oxygen transmission rates below legacy fluorinated chemistries, unlocking fiber tray adoption in prepared foods.
Market Restraints
- Resin price volatility:Ethylene and propylene feedstock swings compress converter margins, particularly for commodity polypropylene thermoforming operations.
- Collection infrastructure gaps:Inconsistent municipal sorting streams limit the effective supply of food-grade recycled polyethylene terephthalate, constraining rPET tray expansion.
- Composting certification bottlenecks:Industrial composting facility scarcity in the US and uneven home composting standards delay biodegradable format scale.
Strategic Opportunities
- India foodservice penetration:Organized retail and delivery platform growth in tier-2 cities creates first-mover positioning for portion-controlled fiber formats.
- Healthcare sterilization-grade expansion:Ambulatory surgical center networks are demanding validated barrier systems for instrument kits and pharmaceutical unit-dose delivery.
- Digital watermarks and AI sorting:Convergence of invisible marker technologies and machine-vision separation is enabling higher-purity recycling streams for flexible films.
Industry Challenges
- Barrier chemist talent scarcity:Formulation expertise in mineral and plant-derived coatings remains concentrated among a narrow pool of specialists, elongating R&D timelines.
- Legacy equipment retrofit costs:Converting lines engineered for petroleum-based resins require substantial capital outlay to process biodegradable alternatives at commercial speeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single-Use Packaging Market |
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $561.3 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plastics, Paper, Biodegradable Materials, Aluminum End User: Food & Beverage, Healthcare, Personal Care, Consumer Electronics Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales Geographical Focus: Domestic, International, Export, Local |
| Companies Covered | Tetra Pak, Stora Enso, Amcor, WestRock, Constantia Flexibles, Sealed Air, Huhtamaki Oyj, Crown Holdings, Smurfit Westrock, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single-Use Packaging Market Strategic Shifts
Material science breakthroughs and compliance-driven specification changes are compressing development cycles, forcing converters to integrate real-time regulatory monitoring into product roadmaps.
Digital twin platforms for packaging design and lifecycle assessment are virtualizing how converters model barrier performance, end-of-life pathways, and carbon footprint before physical prototyping. Food and beverage brand technical teams are adopting these tools for supplier qualification, compressing traditional sample-and-test cycles from months to weeks. The technology is virtualizing competitive advantage toward firms with integrated data architectures rather than standalone manufacturing scale.
China's GB standards for food-contact materials and SAMR notification requirements are tightening documentation burdens for imported substrates, particularly for novel biopolymers lacking multi-year migration study histories. Domestic converters with established testing relationships and local regulatory affairs capabilities are capturing specification share from foreign suppliers. The healthcare and infant nutrition segments are most affected, with multinationals accelerating in-country compounding partnerships to bypass notification delays.
Consolidated procurement by quick-service restaurant chains and meal-kit platforms is displacing fragmented distributor relationships with direct converter contracts tied to sustainability scorecards. Technical buyers now mandate third-party compostability certification and recycled content verification as baseline qualification criteria, not premium differentiators. This pattern is most visible in North American and Western European foodservice channels, where top-ten operators command sufficient volume to dictate format standardization across their supply bases.
Single-Use Packaging Market Segmentation
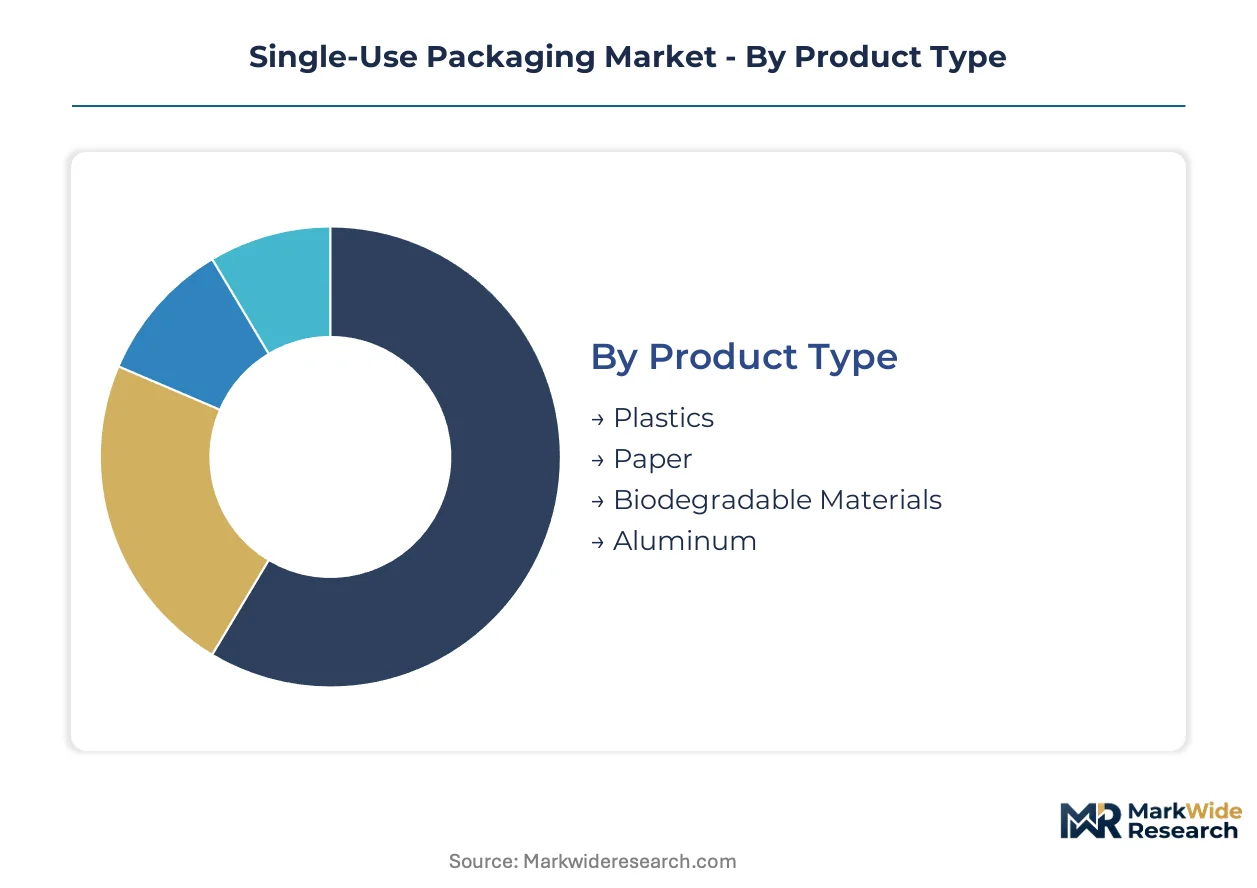
Single-use packaging segmentation reveals how material specifications, end-use hygiene requirements, and channel logistics create distinct margin architectures across the value chain. Each dimension carries regulatory and capital implications that reshape supplier positioning.
Product Type:
Use-case spectrum spans sterile barrier films to compostable foodservice ware, with each substrate commanding different compliance burdens and equipment footprints.
- Plastics:Polyethylene, polypropylene, and PET films dominate through oxygen transmission rates below 1 cc/m²/day and heat-seal reliability. Food & Beverage processors in China and Germany specify these for extended shelf-life dairy and prepared meals. Virgin resin price volatility compresses converter margins, particularly for commodity thermoforming operations serving QSR chains.
- Paper:Molded fiber trays and paperboard cartons carry grease-resistant mineral coatings replacing legacy fluorinated chemistries under ECHA REACH restrictions. EU quick-service restaurants are standardizing these formats for prepared foods. Barrier coating R&D timelines elongate due to concentrated formulation expertise among narrow specialist pools.
- Biodegradable Materials:PLA, PHA, and starch-based polymers achieve compostability certifications that procurement teams now mandate as baseline qualification. Industrial composting facility scarcity in the US and uneven home composting standards delay format scale despite brand sustainability commitments.
- Aluminum:Foil laminates and trays provide absolute moisture and light barriers for pharmaceutical blister packs and premium ready-to-eat meals. Healthcare sterilization-grade validation requirements command premium margin pools.
Established volume favors Plastics; emerging adoption favors Biodegradable Materials.
End User:
Margin concentration tracks validation intensity and contamination liability exposure across sectors.
- Food & Beverage:Anchors absolute demand through portion-controlled distribution, tamper-evidence requirements, and delivery-optimized formats. Cloud kitchen operators and meal-kit platforms standardize specifications across North America and Western Europe. Direct converter contracts displace fragmented distributor relationships.
- Healthcare:Ambulatory surgical center networks demand validated barrier systems for instrument kits and pharmaceutical unit-dose delivery. FDA food-contact substance notifications and sterilization-grade validation create approval moats. This segment commands the steepest expansion trajectory in premium margin capture.
- Personal Care:Single-dose sachets and sample formats serve travel retail and subscription box channels. Asia-Pacific beauty brands drive specification innovation in film-laminate structures.
- Consumer Electronics:Anti-static trays and moisture-barrier pouches protect components through global supply chains. E-commerce fulfillment centers mandate standardized void-fill and cushioning formats.
Food & Beverage sustains volume leadership; Healthcare captures margin expansion.
Distribution Channel:
Channel control determines specification authority and sustainability data transparency.
- Retail:Supermarket and hypermarket private-label programs consolidate procurement around recyclability-compliant formats. Shelf-ready packaging requirements drive standardization in tray and wrap dimensions.
- E-commerce:Direct-to-consumer fulfillment demands right-sized packaging to minimize dimensional weight shipping penalties. Amazon and Alibaba marketplace sellers face sustainability scorecard mandates.
- Wholesale:Foodservice distributors aggregate fragmented restaurant demand into volume commitments for converters. Limited specification influence compared to direct chain contracts.
- Direct Sales:Quick-service restaurant chains and meal-kit platforms bypass intermediaries to dictate format standardization. Third-party compostability certification and recycled content verification function as baseline entry criteria.
Direct Sales concentrates specification authority; E-commerce gains share fastest.
Geographical Focus:
Regulatory geography shapes material approval pathways and recycling infrastructure investment.
- Domestic:Local converters leverage established testing relationships and regulatory affairs capabilities to capture specification share. China's SAMR notification requirements particularly advantage domestic suppliers for novel biopolymers.
- International:Multinational brand technical teams adopt digital twin platforms for supplier qualification, compressing sample-and-test cycles. Integrated data architectures virtualize competitive advantage.
- Export:Manufacturing clusters in China serve foreign brand owners under EU Packaging and Packaging Waste Regulation and FDA compliance layers. GB standards tightening documentation burdens for imported substrates.
- Local:Municipal collection infrastructure gaps constrain food-grade rPET tray expansion despite brand commitments. Industrial composting facility scarcity limits biodegradable format effective scale.
Export manufacturing concentrates volume; Domestic regulatory proximity gains strategic weight.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and China where regulatory stringency and manufacturing scale create divergent margin architectures. Converters in Düsseldorf and Shanghai command specification authority through compliance proximity and cluster density. Peripheral markets absorb cost pass-through with limited negotiation leverage.
United States
QSR chains and meal-kit platforms in Chicago and Dallas-Fort Worth standardize fiber tray specifications for delivery-optimized formats. FDA food-contact substance notifications govern material approval pathways for grease-resistant coatings. California's SB 54 mandates plastic pollution reduction, redirecting procurement toward compostable alternatives in Los Angeles basin foodservice operations.
Germany
Extended producer responsibility frameworks force converters in North Rhine-Westphalia to internalize end-of-life costs for virgin plastic formats. ECHA REACH restrictions on per- and polyfluoroalkyl substances compel reformulation of paper coatings toward mineral alternatives. Düsseldorf-based technical teams leverage digital twin platforms to compress supplier qualification cycles for EU Packaging and Packaging Waste Regulation compliance.
China
Domestic consumption scaling in Shanghai and export manufacturing clusters in Guangdong pull investment into single-use format capacity. SAMR food-contact material rules and GB standards tighten documentation burdens for imported substrates. Shenzhen converters with established testing relationships capture specification share from foreign suppliers in healthcare and infant nutrition segments.
India
Organized retail penetration and delivery platform growth in Mumbai and Bengaluru create positioning opportunities for portion-controlled fiber formats. FSSAI food safety standards govern material migration limits for food-contact applications. Tamil Nadu's converting corridor attracts capital for biodegradable tray production serving quick-service restaurant chain procurement consolidation.
Japan
Ambulatory surgical center networks in Tokyo and Osaka demand validated barrier systems for pharmaceutical unit-dose delivery. PMDA sterilization-grade requirements create approval moats for healthcare-focused converters. Nagoya industrial packaging specialists supply anti-static formats for precision electronics fulfillment through regional distribution hubs.
Single-Use Packaging Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying substrates and barrier coatings to converters lacking in-house formulation capabilities. The market structures around three tiers: multinational integrated systems providers, regional flexible packaging converters, and niche material science specialists. Strategic moves concentrate on M&A for geographic footprint expansion and partnerships for biopolymer feedstock security.
Among Nordic- and Swiss-based material platform providers, Tetra Pak and Amcor occupy positions as system integrators with captive aseptic and barrier technologies. Huhtamaki Oyj represents the fiber-based specialist archetype, anchoring molded product capabilities as plastic restrictions tighten across EU member states. These three entities exemplify how regulatory proximity and integrated manufacturing architectures virtualize competitive advantage beyond standalone scale.
| Leading Market Players |
|---|
| Tetra Pak |
| Stora Enso |
| Amcor |
| WestRock |
| Constantia Flexibles |
| Sealed Air |
| Huhtamaki Oyj |
| Crown Holdings |
| Smurfit Westrock |
| Others |
Value Chain & Pricing Dynamics
Ethylene and propylene feedstock concentration in Gulf Coast petrochemical clusters and Middle Eastern integrated complexes funnels pricing power toward resin producers, squeezing converter margins while premium pools accumulate downstream at healthcare sterilization-grade validators and fiber-based molded product specialists.
Pricing Analysis
Configured-to-order barrier coating formulations command 40-60% premiums over standard polyethylene terephthalate tray specifications. Three-tier pricing structure across premium sterilization-grade, standard food-contact, and economy commodity thermoforming levels tracks FDA notification tier and oxygen transmission rate performance. Cost compression in commodity polypropylene operations intensifies because QSR procurement consolidation extracts volume discounts. Cloud kitchen operators and meal-kit platforms exhibit highest price sensitivity; ambulatory surgical center networks show least sensitivity due to contamination liability exposure.
Supply Chain Analysis
Upstream feedstock supply draws from Saudi Arabian ethane crackers, US Gulf Coast shale gas derivatives, and naphtha-fed complexes in South Korea and Japan. Virgin resin, mineral barrier coatings, and food-grade recycled polyethylene terephthalate constitute critical input dependencies. Single-source vulnerability concentrates in fluorinated chemistry alternatives where formulation expertise pools narrowly. Distribution runs through direct converter contracts with QSR chains and meal-kit platforms, displacing fragmented wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidated procurement by quick-service restaurant chains and meal-kit platforms has shifted buyer power toward volume aggregators, fragmenting converter pricing leverage and mandating sustainability scorecards as baseline entry criteria.
For Market Incumbents: Harden barrier coating R&D capabilities through captive mineral formulation expertise to offset ECHA REACH-driven fluorinated chemistry obsolescence. Expand fiber tray capacity in Tamil Nadu and North Rhine-Westphalia to capture EU Packaging and Packaging Waste Regulation-compliant demand. Prioritize sterilization-grade validation investment for healthcare segment margin defense. For New Entrants and Emerging Players: India's tier-2 city foodservice penetration offers first-mover positioning for portion-controlled molded fiber formats. Target cloud kitchen operator procurement consolidation with direct sales models bypassing wholesale distributors. Lead with third-party compostability certification and recycled content verification as qualification differentiators against legacy plastic converters. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed flexible packaging converters lacking integrated barrier formulation capabilities. Five-to-ten year viability favors specialists with captive mineral coating R&D and established SAMR testing relationships in China. Monitor industrial composting facility buildout rates in the US as inflection indicator for biodegradable material scale viability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Mineral Coating Formulation | Captures ECHA REACH-compliant barrier technology as fluorinated alternatives face restriction. |
| Healthcare Sterilization-Grade Capacity Expansion | Positions converters for ambulatory surgical center network procurement with FDA-validated barriers. |
| Direct QSR Chain Contract Acquisition | Bypasses wholesale intermediaries to capture specification authority and sustainability scorecard compliance. |
| Industrial Composting Facility Partnership | Unlocks biodegradable PLA and PHA format scale by addressing certification-to-disposal infrastructure gaps. |
| Digital Twin Platform Deployment | Compresses supplier qualification cycles from months to weeks for EU regulatory compliance modeling. |
Study Parameters
Cross-validation between converter procurement director interviews and regulatory filing analysis anchors the qualitative findings. Primary discussions with food & beverage technical buyers, healthcare sterilization-grade validators, barrier coating formulators, and extended producer responsibility framework administrators combined with secondary validation through FDA food-contact substance notifications, ECHA REACH restriction updates, SAMR GB standard releases, and EU Packaging and Packaging Waste Regulation implementation guidance. Bottom-up capacity modeling and top-down demand aggregation triangulate market sizing.
Calibration against historical resin price volatility patterns and regulatory implementation timelines shapes the projection framework. Segmentation dimensions include material substrate, end-use hygiene requirement tier, distribution channel control level, and regional regulatory cluster across the analysis window. CAGRs derive from installed capacity expansion announcements, brand sustainability commitment tracking, and substitution elasticity estimates for biodegradable alternatives.
The forecast holds incumbent behavior within observed patterns; aggressive backward integration moves by resin producers or rapid industrial composting facility buildout would shift outcomes. Cross-checking against customs trade data for food-contact material substrate imports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaging Materials
Single Dose Detergent Packaging Market
Packaging Materials
Global Packaging Foams Market
Packaging Materials
Bakeable Trays Market
Packaging Materials
Skin Packaging Market
Packaging Materials
Greaseproof Sheets Market
Packaging Materials
Thermoformed Skin Packaging Market
Packaging Materials
Food Grade Sealant Market
Packaging Materials
PCR Thermoforms Market
Packaging Materials
PCR Packaging Market
Packaging Materials
EPE Liner Market
Packaging Materials
Urn Liners Market
Packaging Materials
Chemical Packaging Market
Packaging Materials
Foam Bottle Technology Market
Packaging Materials
Carded Packaging Market
Packaging Materials
Sealed Wax Packaging Market
Packaging Materials
PET Material Packaging Market