
 Nordic Countries Architectural Coatings Market | 2026-2036
Nordic Countries Architectural Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Nordic Countries Architectural Coatings Market Analytics
Multi-source procurement for resin and pigment supply is hardening among Nordic formulators seeking supply security after recent raw-material disruptions. Teknos leverages its Finnish manufacturing base to sustain consistent delivery across the Baltic-Nordic corridor. Beckers Group anchors its position through specialized coil and industrial coatings that extend into select architectural lines. Jotun competes on marine-derived technology leadership, translating anti-corrosion expertise into premium exterior paint systems for harsh coastal climates.
Nordic Countries Architectural Coatings comprise water-borne, solvent-borne, and powder-based formulations designed to protect and finish building substrates across residential, commercial, and infrastructure applications, typically incorporating acrylic, alkyd, or polyurethane binders at film thicknesses of 40–150 microns. These coatings must withstand freeze-thaw cycles, high humidity, and intense UV exposure during long summer days while meeting strict volatile organic compound limits. Interior Paints and Exterior Paints dominate volume, with water-based formulations capturing the bulk of residential demand due to tightening environmental standards and contractor preference for low-odor application. Specialty Coatings for wood facades and heritage restoration command disproportionate margin pools, as architects and developers specify certified systems for moisture-breathable protection in historic Nordic timber construction.
REACH restricts hazardous substance content across all coatings sold in EU member states including Denmark, Sweden, and Finland, while the EU Green Deal pushes embodied-carbon disclosure that reshapes procurement criteria for public housing projects. Norway's national building codes and Iceland's adaptation of EEA environmental standards further tighten performance benchmarks for thermal-bridge mitigation and indoor air quality. Stakeholders must monitor evolving ECHA substance evaluations and national green-public-procurement criteria to anticipate which binder chemistries and bio-based raw materials will retain formulation approval.
Market Dynamics
The EU Green Deal is compressing formulation windows for Nordic coating producers as embodied-carbon disclosure rules reshape public procurement criteria and binder chemistry approvals across Denmark, Sweden, Norway, Finland, and Iceland.
Growth Catalysts
- Energy-efficiency retrofits:Sweden's Million Homes Programme and Denmark's building stock renewal mandates are accelerating exterior paint cycles for thermal-bridge mitigation in multi-family housing.
- REACH substance restrictions:ECHA evaluations of titanium dioxide and biocides are pulling demand toward water-borne alkyd and bio-based acrylic systems certified for low-VOC interior application.
- Heritage timber restoration:Norway's stave church conservation protocols and Finnish wood-facade preservation standards are expanding specification pools for moisture-breathable specialty coatings.
Market Restraints
- Titanium dioxide price volatility:Pigment supply concentration in Chinese sulfate-process production is squeezing margin stability for Nordic formulators dependent on imported raw materials.
- Freeze-thaw performance thresholds:Technical limitations in pure bio-based binders are blocking full substitution of petrochemical acrylics in exterior facade systems rated for sub-zero cycling.
- Icelandic import dependency:EEA-aligned environmental standards adoption without domestic manufacturing base creates structural cost premiums versus mainland Nordic supply.
Strategic Opportunities
- Green public procurement expansion:Finland's KEINO competence center and Sweden's Klimatklivet investment support are creating specification pathways for carbon-declared coating systems in social housing.
- Powder coating convergence:Industrial electrostatic application technology is migrating into architectural metal cladding segments, displacing liquid solvent-borne systems in Copenhagen and Oslo commercial developments.
- Digital color matching platforms:Contractor-direct specification tools are compressing distributor intermediation in Danish renovation markets, opening margin recapture for integrated manufacturers.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in bio-based binder stabilization and VOC compliance testing is concentrating in Stockholm and Copenhagen, creating recruitment bottlenecks for Norwegian and Finnish operations.
- CE marking timeline compression:Extended ECHA substance evaluation periods are delaying new product launches by 18-24 months, forcing maintenance of legacy formulation inventories.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nordic Countries Architectural Coatings Market |
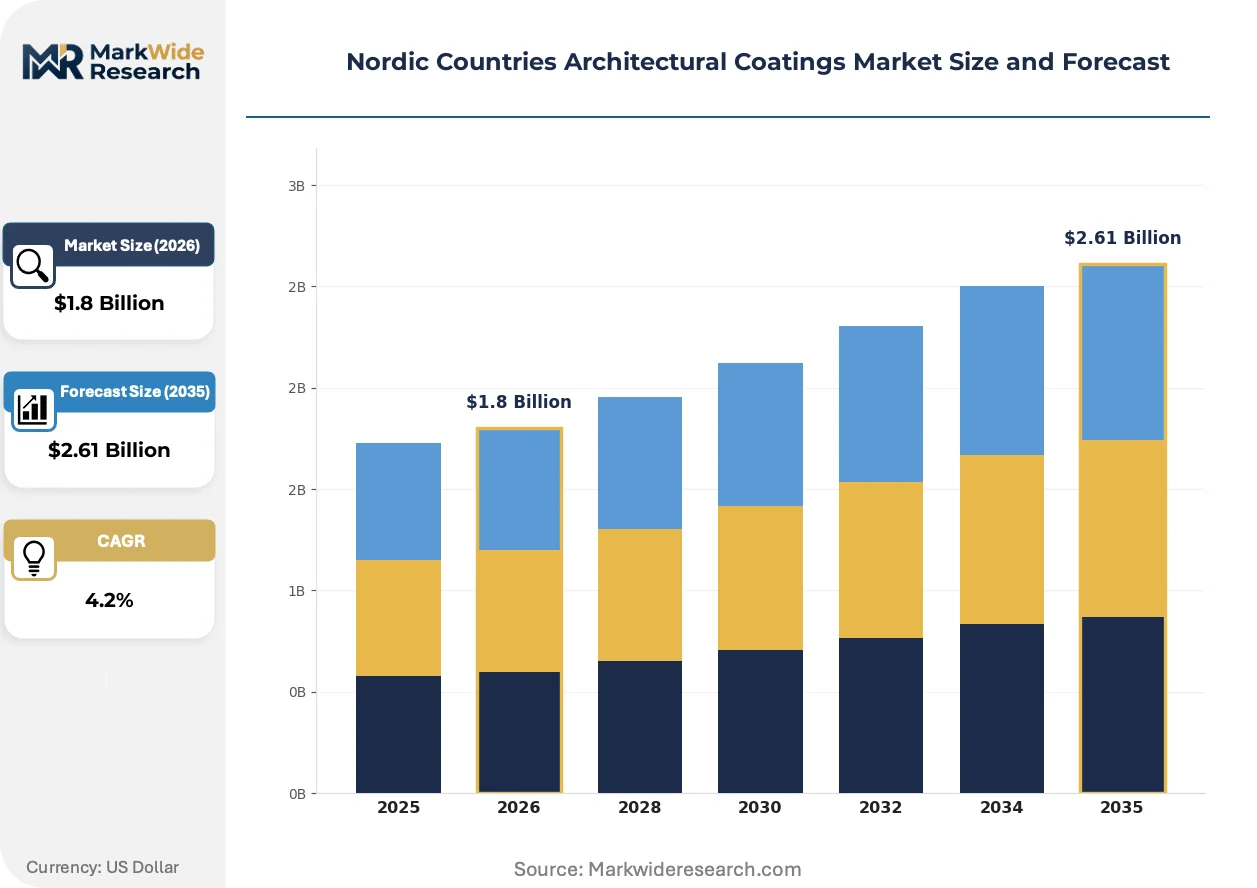
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.61 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interior Paints, Exterior Paints, Primers, Varnishes Application: Residential Buildings, Commercial Structures, Industrial Facilities, Infrastructure Projects Formulation: Water-Based, Solvent-Based, Powder Coatings, Specialty Coatings End User: Contractors, DIY Consumers, Architects, Developers |
| Companies Covered | Teknos, Tikkurila Oyj, AkzoNobel, Beckers Group, Hempel A/S, Jotun, Flügger, Scanox AS, PPG Industries, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nordic Countries Architectural Coatings Market Evolving Landscape
Formulation science is pivoting toward carbon-accounted raw material sourcing as digital specification tools compress traditional distribution hierarchies across Nordic construction procurement.
Self-healing microcapsule technology is modularizing maintenance economics for coastal exterior systems in Norway and western Denmark. Municipal housing authorities in Bergen and Aarhus are piloting silicone-alkyd hybrids with autonomous crack-sealing capability. The technology is modularizing service-contract structures by decoupling warranty terms from annual inspection cycles.
REACH Annex XVII restrictions on intentionally added microplastics are forcing pigment dispersion reformulation across all EU member Nordic states. Industrial consequence includes accelerated phase-out of certain effect pigments in decorative interior lines. Swedish formulators are responding fastest, with Denmark and Finland trailing by 12-18 months in compliance certification.
Architects are consolidating specification authority through centralized sustainability scoring platforms that weight embodied-carbon disclosure above unit price. Copenhagen and Stockholm commercial developers now mandate third-party verified Environmental Product Declarations for all coating categories. Norway's state housing bank is embedding equivalent criteria into loan conditionality for 2024-2025 project pipelines.
Nordic Countries Architectural Coatings Market Segmentation
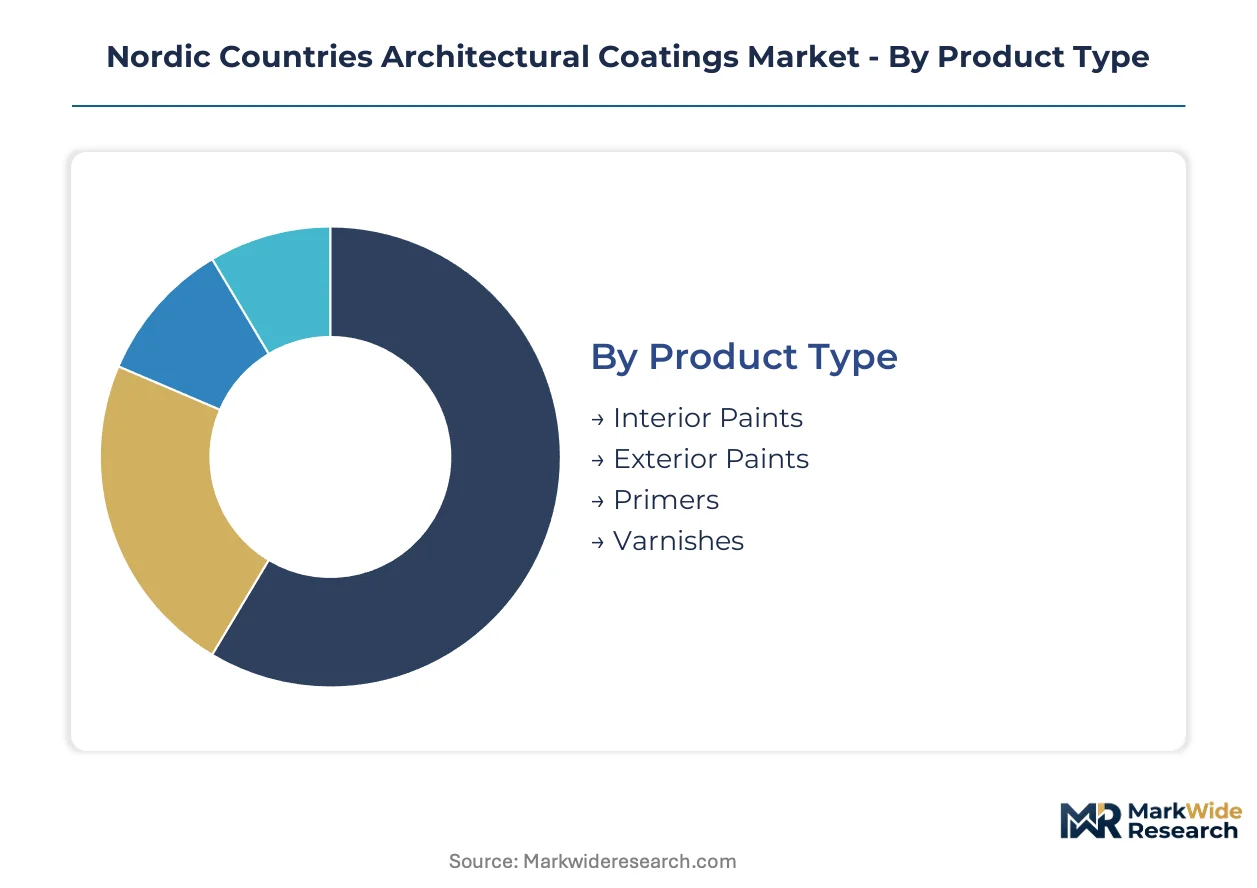
Architectural coatings in the Nordic region fragment across formulation chemistry, application substrate, and procurement channel, each dimension carrying distinct REACH compliance burdens and carbon-disclosure thresholds. Specification authority varies sharply between segments, with public housing procurement driving standardization in some categories while heritage restoration preserves artisanal complexity in others.
Product Type:
CE marking requirements and VOC certification intensity diverge sharply across this category, with interior systems facing stricter indoor air quality protocols under REACH Annex XVII while exterior products must demonstrate freeze-thaw resilience.
- Interior Paints:Water-borne acrylic and alkyd formulations dominate, formulated below 30 g/L VOC content to satisfy Danish and Swedish building codes for occupied-space application. Demand concentrates in Stockholm and Copenhagen metropolitan renovation markets, where Million Homes Programme retrofits specify low-odor systems for tenant-in-place redecoration.
- Exterior Paints:Silicone-modified acrylics and polyurethane hybrids withstand sub-zero cycling and intense UV exposure during Nordic summer daylight extension. Norway's coastal housing stock and Denmark's brick facade renewal programs anchor volume, though bio-based binder substitution remains technically constrained for full weathering performance.
- Primers:Penetrating alkyd and acrylic blocking sealers for substrate preparation on historic timber and moisture-damaged masonry.
- Varnishes:Polyurethane and oil-modified urethane systems for interior wood protection, concentrated in Finnish residential joinery and Norwegian stave church conservation.
Leading the category by volume: Interior Paints. Growing fastest: Exterior Paints.
Application:
Cost tier stratification separates premium specification-driven segments from price-sensitive maintenance cycles, with thermal-bridge mitigation mandates reshaping procurement criteria in multi-family housing.
- Residential Buildings:Single-family and multi-family housing account for the majority of Nordic coating consumption, spanning new construction and renovation. Sweden's energy-efficiency retrofit mandates and Denmark's building stock renewal programs accelerate exterior repaint cycles for thermal performance certification.
- Commercial Structures:Office, retail, and hospitality developments in Oslo and Copenhagen drive demand for durable, color-stable facade systems. Third-party verified Environmental Product Declarations are becoming mandatory in green-lease negotiations.
- Industrial Facilities:Manufacturing plants and logistics centers require chemical-resistant floor coatings and corrosion-protection systems, with powder coating penetration rising for metal cladding applications.
- Infrastructure Projects:Bridges, tunnels, and transportation facilities specify heavy-duty protective coatings with extended maintenance intervals, subject to public procurement carbon-accounting rules.
Residential Buildings command the largest volume share. Commercial Structures are climbing the fastest as green-building certification expands.
Formulation:
Supply concentration in imported titanium dioxide and specialty resin chemistries creates margin pressure that favors water-based and powder alternatives with more localized raw material sourcing.
- Water-Based:Acrylic and alkyd emulsions capture the majority of architectural volume, driven by contractor preference for low-odor application and tightening VOC limits across all five Nordic markets.
- Solvent-Based:High-solids alkyds and urethanes persist in exterior wood protection and industrial maintenance where water-borne alternatives fail on durability metrics.
- Powder Coatings:Thermoset polyester and epoxy systems are displacing liquid solvent-borne alternatives in architectural metal cladding for Copenhagen and Oslo commercial developments.
- Specialty Coatings:Moisture-breathable silicate and hybrid systems for historic timber conservation command premium positioning in Norwegian and Finnish heritage restoration.
Water-Based formulations lead by volume. Powder Coatings are gaining share fastest through metal cladding substitution.
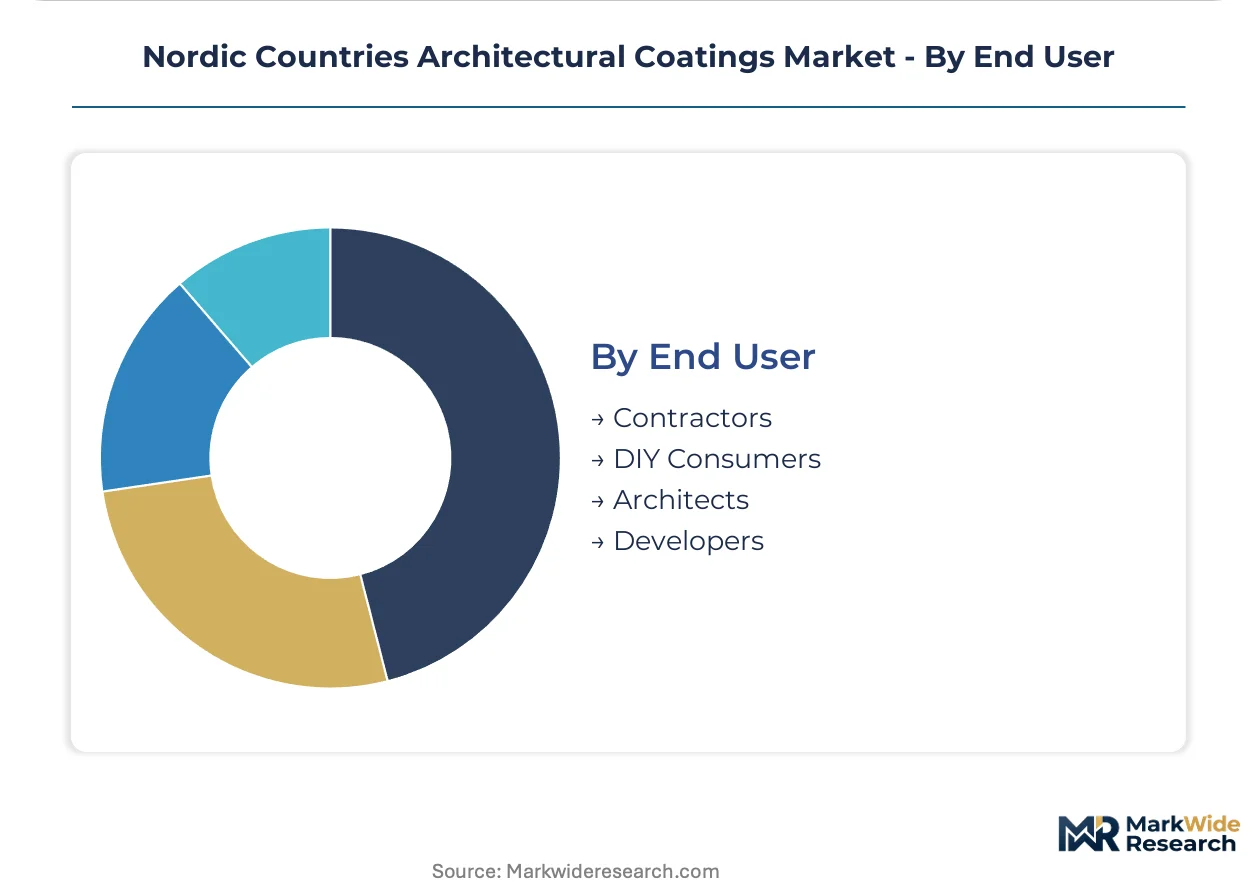
End User:
Customer type determines specification authority depth, with architects and developers wielding platform-level sustainability scoring tools that override contractor preferences on public and commercial projects.
- Contractors:Professional applicators dominate volume procurement in renovation markets, with Danish and Swedish painting contractors consolidating around preferred manufacturer-direct digital color matching platforms.
- DIY Consumers:Retail channel purchases concentrate in single-family home maintenance and interior redecoration, with seasonal demand peaking during Nordic summer daylight hours.
- Architects:Specification authority is centralizing through sustainability scoring platforms that weight embodied-carbon disclosure above unit price in Copenhagen and Stockholm commercial developments.
- Developers:Large-scale residential and commercial project sponsors mandate Environmental Product Declarations and green procurement compliance as loan conditionality tightens.
Contractors represent the largest volume channel. Architects are expanding influence fastest through specification platform consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium dioxide import corridors through Rotterdam and Hamburg supply Nordic formulators, creating raw-material dependency patterns that shape national market structures across Denmark, Sweden, Norway, Finland, and Iceland.
Sweden
Stockholm's Million Homes Programme and Gothenburg's harbor district renewal accelerate exterior repaint cycles for thermal-bridge certification. The Swedish Chemicals Agency enforces REACH Annex XVII biocide restrictions that favor water-borne alkyd systems. Malmö's Øresund corridor concentrates contractor procurement platforms that compress distributor intermediation.
Denmark
Copenhagen's building stock renewal mandates and Aarhus municipal housing retrofits expand specification pools for low-VOC interior systems. The Danish EPA implements EU Green Deal carbon-disclosure rules for public procurement. The Zealand-Funen corridor anchors coil coating demand for commercial metal cladding developments.
Norway
Bergen's coastal housing stock and Oslo's waterfront commercial projects require silicone-modified acrylics rated for sub-zero cycling. The Norwegian Environment Agency adapts EEA standards for heritage timber conservation protocols. Stavanger's industrial base sustains demand for corrosion-resistant exterior systems.
Finland
Helsinki's wooden suburb preservation and Tampere's multi-family retrofits specify moisture-breathable specialty coatings. ECHA substance evaluations drive Finnish formulators toward bio-based acrylic certification. Teknos leverages its domestic manufacturing base for Baltic-Nordic corridor delivery consistency.
Iceland
Reykjavik's compact construction market imports finished coatings under EEA-aligned environmental standards without domestic manufacturing. The Housing and Construction Authority mandates thermal performance benchmarks that accelerate exterior system replacement cycles. Import dependency creates structural cost premiums versus mainland Nordic supply.
Nordic Countries Architectural Coatings Market Competitive Landscape
Global majors compete with regional champions across formulation chemistry and specification authority dimensions, producing a tiered structure where multinational resin technology meets localized color-matching infrastructure. The vendor base clusters around three strategic archetypes: integrated Nordic manufacturers with captive distribution, marine-technology translators repurposing anti-corrosion expertise, and industrial-coating anchors extending into architectural lines. Capacity expansion and portfolio diversification dominate competitive moves as players respond to REACH compliance windows and green procurement criteria.
Within the integrated Nordic tier, Teknos and Tikkurila Oyj exemplify regional champions leveraging domestic manufacturing for supply security across the Baltic-Nordic corridor. Jotun occupies a position translating marine-derived technology leadership into premium exterior systems for harsh coastal climates. Among diversified industrial specialists, Beckers Group anchors its market presence through coil coating expertise that extends into select architectural applications. These three represent distinct competitive vectors: geographic integration, technology translation, and industrial-to-architectural extension.
| Leading Market Players |
|---|
| Teknos |
| Tikkurila Oyj |
| AkzoNobel |
| Beckers Group |
| Hempel A/S |
| Jotun |
| Flügger |
| Scanox AS |
| PPG Industries |
| Others |
Value Network & Pricing Analysis
Certification-grade divergence between REACH-compliant low-VOC systems and legacy formulations manifests in both margin structures and raw material sourcing strategies across Nordic coating procurement. Premium tiers command pricing power through ECHA-certified bio-based binders and third-party verified Environmental Product Declarations, while commodity segments face cost compression from titanium dioxide import volatility and distributor margin stacking.
Pricing Analysis
Warranty bundling separates premium exterior silicone-acrylic systems from unbundled interior renovation paints across Nordic contractor procurement. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with carbon-declared systems commanding 15-25% premiums in Swedish and Danish public housing tenders. Price differentiation hinges on REACH Annex XVII compliance status and freeze-thaw performance certification. Pricing pressure stems from Chinese sulfate-process titanium dioxide supply concentration squeezing formulator margins. DIY consumers in single-family renovation channels exhibit highest price sensitivity, while architects specifying green-lease commercial projects demonstrate lowest sensitivity to unit cost.
Supply Chain Analysis
Dual-sourcing mandates from Nordic formulators now cover both titanium dioxide pigment and specialty acrylic resin streams after recent raw-material disruptions. Supply concentrates in China for pigment, Germany and the Netherlands for resin intermediates, and the Baltic states for regional distribution hubs. Raw material dependencies span titanium dioxide, bio-based alkyd precursors, and silicone-modified acrylic polymers. Single-source vulnerability in Chinese sulfate-process pigment creates exposure to Rotterdam-Hamburg logistics chokepoints. Distribution runs through integrated manufacturer-direct platforms and specialized coating distributors serving contractor networks across the Øresund corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Nordic architectural coatings function as a cost-of-compliance market where REACH substance evaluations and EU Green Deal carbon-disclosure rules erect barrier-to-entry moats favoring incumbents with certified formulation libraries and established ECHA relationships.
For Market Incumbents: Lock in specification authority by embedding carbon-accounted raw material sourcing into long-term municipal housing contracts before green procurement criteria harden. Threat from powder coating convergence in commercial metal cladding demands accelerated water-borne technology R&D. Prioritize backward integration into bio-based alkyd precursor supply to defend margin position against titanium dioxide volatility. For New Entrants and Emerging Players: Enter via heritage timber restoration segments in Norway and Finland where moisture-breathable specialty coatings face limited certified competition. White-space targets include stave church conservation protocols and wooden suburb preservation mandates in Helsinki. Most penetrable entry point lies in digital color matching platforms serving Danish renovation contractors. Go-to-market angle should leverage direct contractor relationships bypassing traditional distributor intermediation. For Investors and Strategic Acquirers: Re-rating potential sits with regional champions possessing captive Baltic-Nordic manufacturing and established ECHA certification pipelines given accelerating green public procurement expansion. Long-term viability over the next decade favors integrated formulators with multi-country REACH compliance infrastructure and heritage restoration specialization. Signal to watch is Finland's KEINO competence center specification pathway adoption rates as inflection indicator for carbon-declared system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Resins | Captive supply of alkyd precursors reduces REACH compliance cost exposure for Nordic formulators. |
| Carbon-Declared Product Line Launch | Environmental Product Declaration certification unlocks Swedish Klimatklivet investment support eligibility. |
| Digital Color Matching Platform Deployment | Contractor-direct specification tools recapture distributor margins in Danish renovation markets. |
| Heritage Conservation Specialty Acquisition | Moisture-breathable timber expertise commands premium positioning in Norwegian stave church protocols. |
| Powder Coating Capacity Expansion | Thermoset polyester systems displace liquid solvent-borne alternatives in Copenhagen commercial metal cladding. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this Nordic architectural coatings assessment. Primary interviews with formulation chemists, procurement managers at municipal housing authorities, distributor channel heads, and sustainability officers at commercial developers cross-validated demand patterns. Secondary sources included ECHA substance evaluation databases, EU Green Deal implementation directives, national building code repositories, and Nordic coatings trade association statistics. Bottom-up volume modeling by formulation type and application substrate triangulated against top-down market value estimates.
Granularity-level modeling deployed country-specific formulation splits across Denmark, Sweden, Norway, Finland, and Iceland, with chemistry-level disaggregation for water-borne, solvent-borne, and powder systems. End-use segmentation captured residential renovation, new construction, commercial development, and infrastructure maintenance cycles. CAGRs were derived from fitted growth curves incorporating energy-efficiency retrofit mandates, REACH compliance timelines, and green procurement adoption rates. Industry-specific forecast inputs included Million Homes Programme expenditure trajectories and heritage restoration protocol expansion schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ECHA substance evaluation acceleration or titanium dioxide supply disruption scenarios. Projections reflect assumptions on REACH Annex XVII implementation consistency and EU Green Deal procurement criteria harmonization across EEA member states. Deviation in bio-based binder performance certification timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paints & Coatings
GCC Paints and Coatings Market
Paints & Coatings
India Automotive Paints and Coatings Market
Paints & Coatings
Core Plate Varnishes Market
Paints & Coatings
Sri Lanka Paints and Coatings Market
Paints & Coatings
Solar Paint Market
Paints & Coatings
Polyurethane Resins Paints and Coatings Market
Paints & Coatings
Global Antifouling Paints and Coatings Market
Paints & Coatings
Industrial Paint Booth Market
Paints & Coatings
Fire Resistant Paints Market
Paints & Coatings
Europe Paints and Coatings Additives Market
Paints & Coatings
Global Anti-Formaldehyde Paint Market
Paints & Coatings
Asia-Pacific Paints and Coatings Additives Market
Paints & Coatings
Low VOC Paints and Coatings Market
Paints & Coatings
Europe Paints and Coatings Market
Paints & Coatings
Wall Putty Powder Market
Paints & Coatings
Automotive OEM Coatings Market