
 Water-Borne Inks and Paints Market | 2026-2036
Water-Borne Inks and Paints Market Size, Share, and Industry Trends Forecast 2026-2036
Water-Borne Inks and Paints Market Analytics
The capital-intensity divergence between integrated resin producers and regional blenders is unwinding competitive stability in water-borne formulations. BASF SE leverages captive acrylic emulsion capacity to secure feedstock cost advantages across European coating lines. PPG Industries anchors North American automotive refinish demand through proprietary low-VOC clearcoat technology. Asian Paints Limited dominates decorative coatings in South Asia via dense contractor networks and localized tinting systems.
Water-borne inks and paints are aqueous dispersion systems where polymer resins, pigments, and additives remain suspended in water rather than organic solvents, with volatile organic compound content typically below regulatory thresholds. Their primary industrial purpose centers on delivering durable, color-fast surface protection and print fidelity while satisfying workplace exposure limits and air-quality mandates. Coatings within the product-type dimension carry the largest revenue pool due to infrastructure and automotive volume, though digital printing technology in the application stack is capturing share from analog methods in packaging. Spray application technology leads in automotive and wood finishing segments where film-build uniformity commands premium pricing, while roller application remains entrenched in construction for its throughput economics on large surface areas.
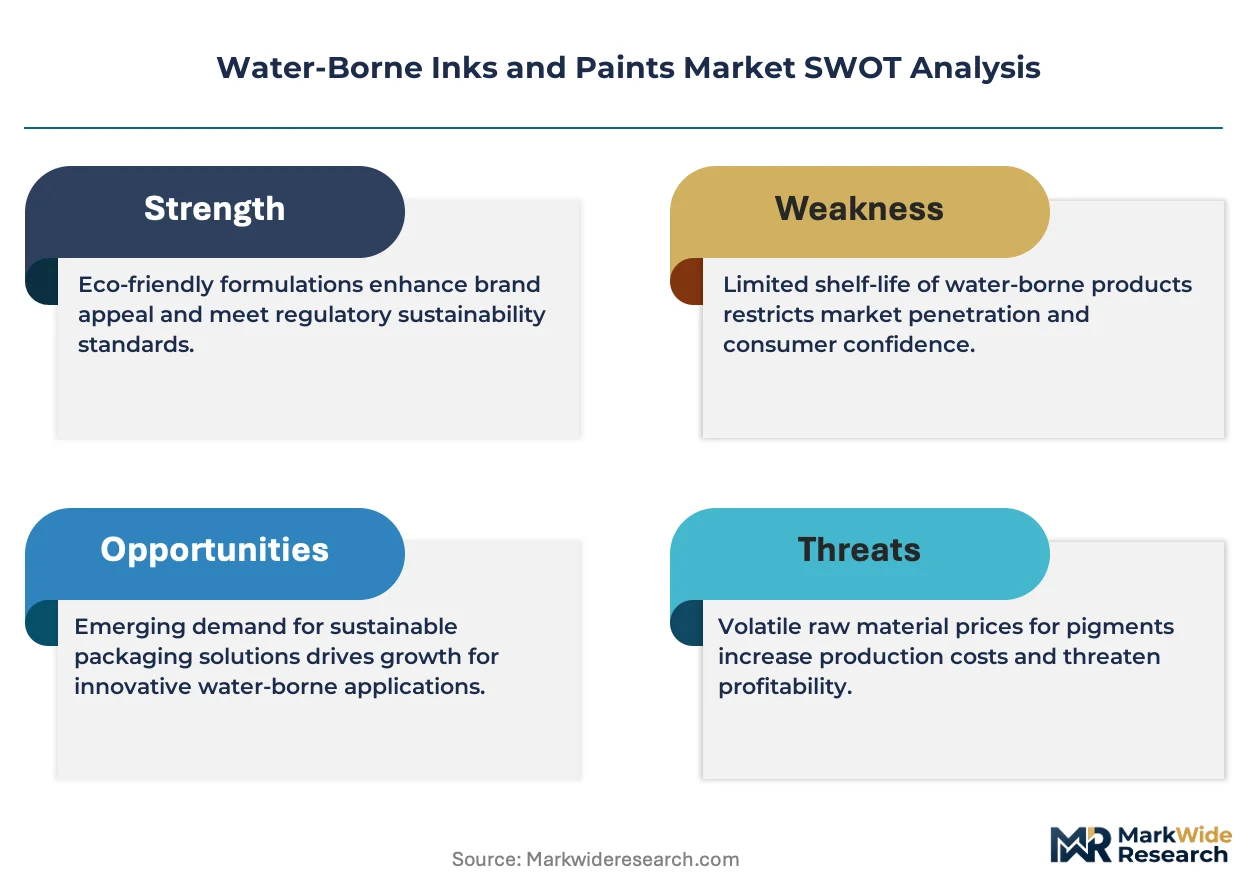
EPA rules under the National Emission Standards for Hazardous Air Pollutants constrain solvent-borne alternatives in US manufacturing facilities, while REACH registration requirements in Europe elevate compliance costs for imported formulations. China's MEE enforces dual carbon goals that tighten VOC discharge permits for coating operations in the Yangtze and Pearl River deltas. Stakeholders must monitor how divergent regional enforcement timelines reshape capital allocation between water-borne retrofit investments and next-generation bio-based resin platforms.
Market Dynamics
Water-borne formulation chemistry is miniaturizing batch sizes and accelerating line changeovers as automotive OEMs retool coating operations to meet tightening VOC discharge limits across multiple jurisdictions.
Growth Catalysts
- EU REACH registration thresholds:Chemical compliance costs for solvent-borne imports are redirecting specification decisions toward water-borne alternatives in European industrial coatings procurement.
- Electronics packaging clusters:Flexible printed circuit manufacturing in South Korea and Taiwan is absorbing high-performance water-borne inks for roll-to-roll processing of display components.
- UV-curable water-borne hybrids:Wood furniture manufacturers are adopting dual-cure systems that combine aqueous dispersion with ultraviolet crosslinking to accelerate drying without sacrificing film hardness.
Market Restraints
- Acrylic monomer supply concentration:Bulk emulsion polymer feedstock is concentrating among integrated petrochemical complexes in the US Gulf Coast and Middle Eastern export hubs, exposing regional blenders to price volatility.
- Freeze-thaw stability limitations:Water-borne coatings require controlled storage and transport infrastructure that solvent-borne alternatives do not, elevating logistics costs in cold-climate distribution.
- Performance gaps in corrosion protection:Heavy-equipment and marine segments continue specifying solvent-borne epoxies for immersion service where water-borne films have not achieved equivalent salt-spray resistance.
Strategic Opportunities
- Brazilian industrial expansion:ANVISA-aligned environmental licensing for manufacturing facilities is creating first-mover advantage for water-borne coating suppliers establishing local emulsion production.
- Digital textile printing:Reactive water-borne ink sets are displacing rotary screen methods in apparel manufacturing, with adoption concentrated in Bangladesh and Vietnam garment export zones.
- China MEE dual carbon enforcement:Provincial discharge permit trading systems in Jiangsu and Zhejiang are monetizing VOC reductions, rewarding early water-borne adopters with compliance credit reserves.
Industry Challenges
- Formulation chemist scarcity:Expertise in colloidal stability and film-formation kinetics is concentrating among senior technologists at established resin producers, constraining independent blender R&D capacity.
- Application equipment retrofit costs:Converting solvent-borne spray lines to water-borne operation requires stainless steel fluid delivery systems and humidity-controlled drying zones that compress capital deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water-Borne Inks and Paints Market |
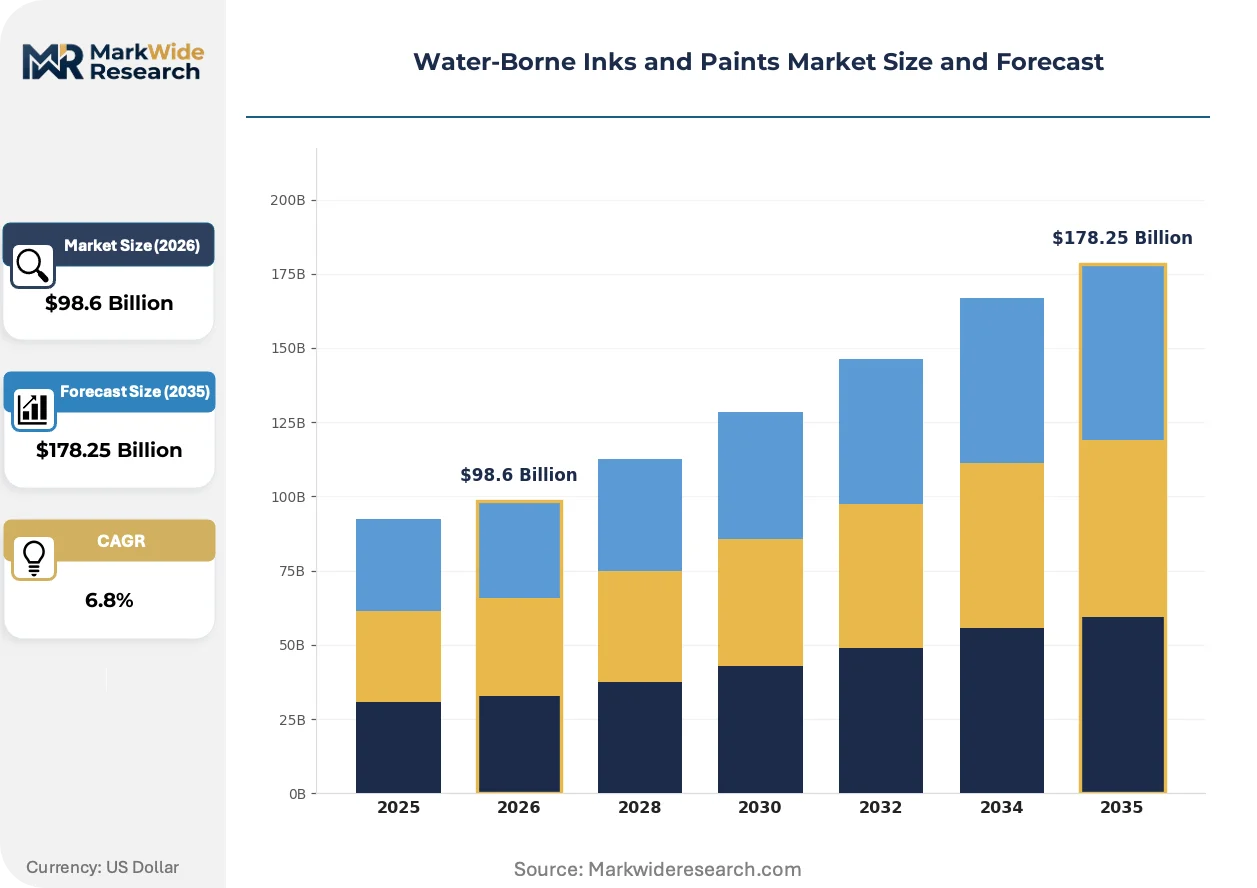
| Market Size in 2026 | $98.6 Billion |
| Market Size in 2035 | $178.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inks, Coatings, Stains, Varnishes Application: Packaging, Automotive, Wood Finishing, Construction End User: Manufacturers, Printers, Contractors, Retailers Technology: Direct to Film, Digital Printing, Spray Application, Roller Application |
| Companies Covered | BASF SE, Flint Group, AkzoNobel N.V., Sakata Inx Corporation, Siegwerk Druckfarben AG & Co. KGaA, PPG Industries Inc., DIC Corporation, Asian Paints Limited, The Sherwin-Williams Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water-Borne Inks and Paints Market Evolving Landscape
Polymer architecture and curing chemistry are converging to compress drying cycles and expand water-borne performance envelopes into industrial segments previously reserved for solvent systems.
Self-crosslinking acrylic emulsions are miniaturizing the performance gap between water-borne and solvent-borne automotive clearcoats. Tier 1 suppliers in Germany and Japan are qualifying these materials for exterior body panels where gloss retention and chip resistance must match two-component polyurethane benchmarks. The technology is miniaturizing the traditional trade-off between environmental compliance and coating durability that has constrained water-borne penetration in premium automotive segments.
EPA National Emission Standards for Hazardous Air Pollutants are tightening coating operation limits at US manufacturing facilities. Metal fabrication and wood furniture plants in the Midwest and Southeast are facing accelerated compliance timelines that favor water-borne system conversions over add-on control equipment. Automotive assembly operations in Michigan and Tennessee are responding by consolidating water-borne specification authority at corporate engineering centers rather than delegating to plant-level procurement.
Specification authority is migrating from plant maintenance managers to corporate sustainability officers with carbon accounting mandates. Industrial coatings procurement in European manufacturing multinationals now requires lifecycle assessment documentation that water-borne suppliers are better positioned to provide than solvent-borne competitors. This shift is most visible in German and Dutch capital equipment manufacturing where supplier scorecards now weight Scope 3 emissions from coating operations alongside unit price and delivery performance.
Water-Borne Inks and Paints Market Segmentation
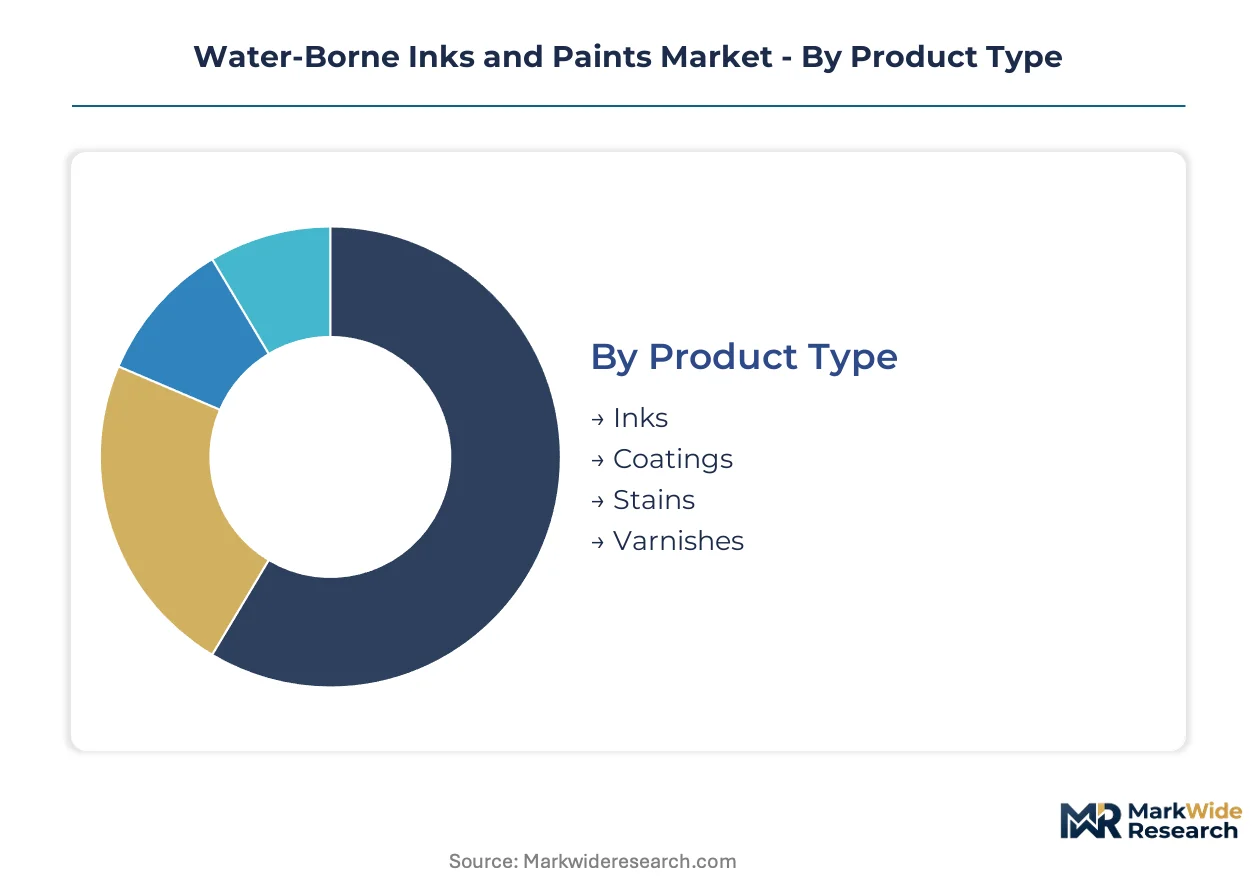
Water-borne formulation economics vary sharply across end-use specifications, with automotive clearcoats commanding premium pricing against commodity construction stains. Segment boundaries are blurring as UV-curable hybrids and digital printing technologies create hybrid demand profiles that resist traditional categorization.
Product Type:
Margin pools concentrate in coatings and specialized inks where formulation complexity and regulatory documentation create pricing power, while stains and varnishes compete on volume throughput in saturated distribution channels.
- Coatings:These aqueous dispersions incorporate acrylic, polyurethane, or epoxy resins for protective film formation on metal, plastic, and composite substrates. Automotive OEM coating lines in Germany and China absorb the highest-specification grades where VOC compliance under EU REACH and China's MEE standards is non-negotiable. The segment captures the largest revenue pool due to infrastructure and automotive volume.
- Inks:Pigmented or dye-based aqueous formulations designed for absorption or film-forming substrates in printing applications. Electronics packaging clusters in South Korea and Taiwan drive offtake for high-performance grades used in roll-to-roll processing of flexible printed circuits. Water-borne inks are displacing solvent alternatives in food-contact packaging where migration limits are tightening.
- Stains:Low-viscosity water-borne penetrants for wood coloration without film buildup. Residential construction and furniture restoration in North American markets absorb volume grades where application simplicity outweighs durability requirements.
- Varnishes:Clear water-borne topcoats providing gloss and abrasion resistance over stained or printed surfaces. Architectural wood finishing and specialty paper coating represent primary demand channels with price sensitivity to solvent-borne alternatives.
The dominant share belongs to Coatings, while Inks is closing the gap fastest through electronics packaging and digital printing adoption.
Application:
Application-driven demand splits between specification-heavy industrial segments where compliance documentation is mandatory, and price-sensitive trades where contractor economics dominate procurement decisions.
- Automotive:Exterior body panel clearcoats and interior trim coatings requiring chip resistance, gloss retention, and weathering stability. German and Japanese Tier 1 suppliers are qualifying self-crosslinking acrylic emulsions that match two-component polyurethane benchmarks. The segment commands the steepest expansion trajectory as OEMs retool coating lines to meet tightening VOC discharge limits.
- Packaging:Food-contact and consumer goods printing where migration limits and odor specifications constrain formulation options. Flexible packaging converters in Bangladesh and Vietnam garment export zones are absorbing reactive water-borne ink sets for digital textile printing applications.
- Wood Finishing:Furniture, cabinetry, and flooring coatings where UV-curable water-borne hybrids combine aqueous dispersion with ultraviolet crosslinking. The technology accelerates drying without sacrificing film hardness in high-throughput manufacturing environments.
- Construction:Architectural coatings and decorative finishes applied to interior and exterior building surfaces. Roller application dominates for throughput economics on large surface areas, with dense contractor networks in South Asia driving volume through localized tinting systems.
Automotive captures the premium pricing tier, while Packaging is gaining share fastest through digital printing displacement of analog methods.
End User:
Procurement authority is migrating from plant-level maintenance managers to corporate sustainability officers with carbon accounting mandates, reshaping vendor selection criteria across end-user categories.
- Manufacturers:Industrial coating operations in automotive assembly, metal fabrication, and wood furniture plants. Midwest and Southeast US facilities face accelerated EPA National Emission Standards compliance timelines that favor water-borne system conversions.
- Printers:Commercial, packaging, and specialty printing operations specifying ink systems for substrate compatibility and regulatory compliance. European multinationals now require lifecycle assessment documentation that water-borne suppliers are better positioned to provide.
- Contractors:Professional applicators in construction and refinishing trades purchasing through distribution networks. Asian Paints Limited dominates South Asian decorative coatings via dense contractor networks and localized tinting systems.
- Retailers:Home improvement and specialty paint stores serving DIY consumers and small professional accounts. The channel absorbs commodity stains and architectural coatings with price positioning against private-label alternatives.
Manufacturers hold the specification authority, while Printers are shifting procurement fastest toward compliance-documented supply relationships.
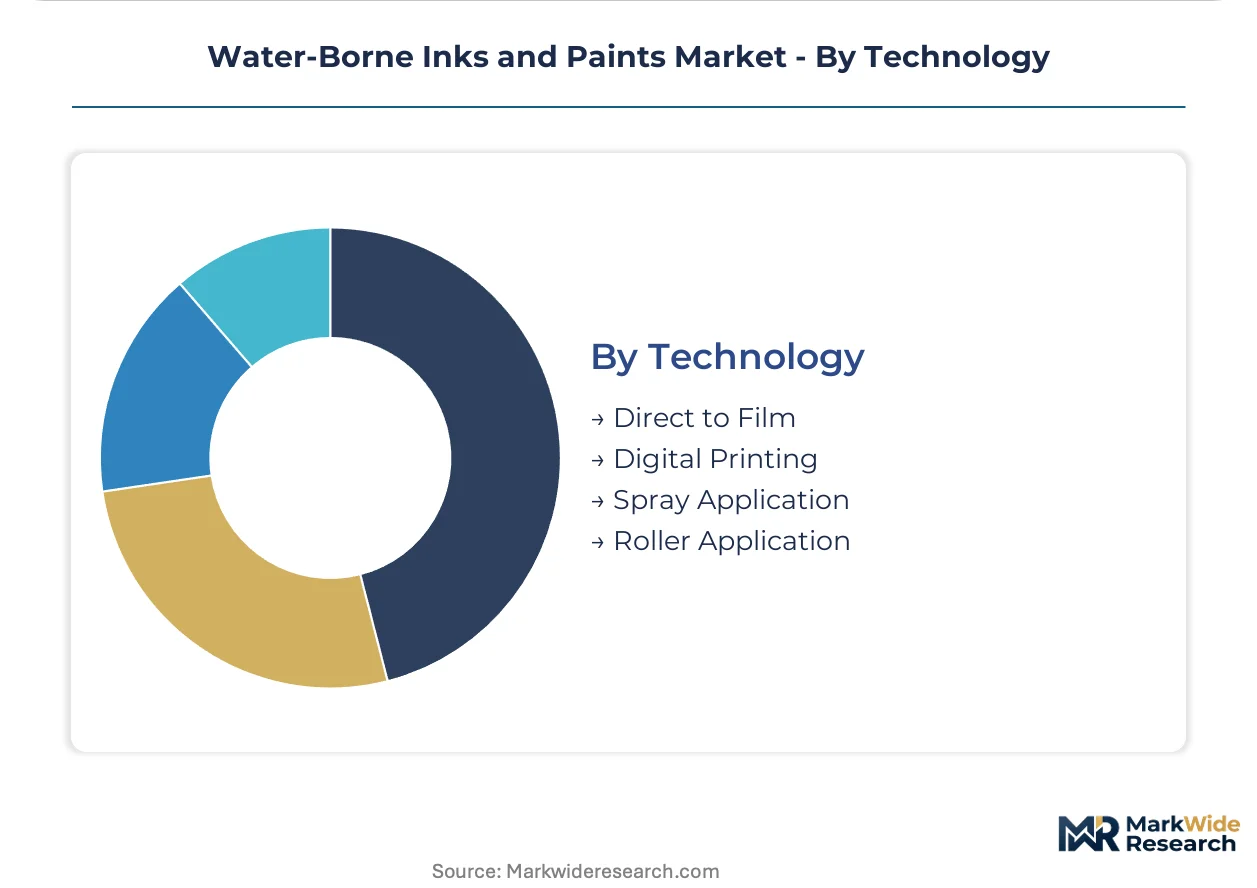
Technology:
Technology selection is compressing drying cycles and expanding water-borne performance envelopes into industrial segments previously reserved for solvent systems.
- Spray Application:Atomized fluid delivery for automotive, wood finishing, and industrial coating where film-build uniformity commands premium pricing. Conversion from solvent-borne operation requires stainless steel fluid delivery systems and humidity-controlled drying zones.
- Digital Printing:Piezoelectric or thermal inkjet deposition of water-borne inks without plate or screen preparation. The technology is capturing share from analog methods in packaging and displacing rotary screen methods in apparel manufacturing.
- Roller Application:Direct transfer coating for construction and large-surface industrial finishing where throughput economics outweigh precision requirements. The method remains entrenched in architectural coatings for wall and ceiling applications.
- Direct to Film:Water-borne ink printing onto transfer films for subsequent heat-press application onto textiles and hard substrates. The technology enables complex multicolor designs without direct garment printing infrastructure.
Spray Application retains the largest installed base, while Digital Printing is climbing the fastest through packaging and textile adoption curves.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Construction contractors in India and Brazil face acute price sensitivity on commodity coatings, while German automotive OEMs absorb premium clearcoat pricing without volume elasticity. This demand-elasticity contrast shapes regional formulation strategies and distribution economics.
Germany
Automotive OEM coating lines in Stuttgart and Munich drive specification-grade water-borne clearcoat offtake. EU REACH registration thresholds elevate compliance costs for solvent-borne imports, redirecting procurement toward domestic emulsion suppliers. The Rhine-Ruhr industrial corridor hosts integrated resin production serving Tier 1 automotive suppliers.
China
Electronics packaging clusters in Suzhou and Shenzhen absorb high-performance water-borne inks for flexible circuit manufacturing. MEE dual carbon enforcement tightens VOC discharge permits in Jiangsu and Zhejiang provinces, monetizing compliance through provincial permit trading systems. Yangtze River Delta coating operations are retrofitting spray lines to capture regulatory credits.
United States
Automotive assembly plants in Michigan and Tennessee consolidate water-borne specification authority at corporate engineering centers. EPA National Emission Standards for Hazardous Air Pollutants constrain solvent-borne alternatives in Midwest metal fabrication facilities. Southeast wood furniture manufacturers face accelerated compliance timelines favoring system conversions over add-on controls.
India
Dense contractor networks in Maharashtra and Gujarat drive decorative coatings volume through localized tinting systems. BIS certification requirements for architectural coatings create compliance differentiation between organized and unorganized suppliers. Western India manufacturing clusters absorb industrial maintenance coatings for textile and pharmaceutical processing equipment.
Brazil
Industrial expansion in São Paulo and Minas Gerais creates first-mover positioning for emulsion producers establishing local manufacturing. ANVISA-aligned environmental licensing for manufacturing facilities elevates compliance barriers for imported formulations. Southeastern coating applicators serve capital equipment and agricultural machinery OEMs with maintenance-grade water-borne systems.
Water-Borne Inks and Paints Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with resin producers commanding feedstock cost advantages over regional blenders. The upper tier leverages captive acrylic emulsion capacity to secure formulation economics across coating lines. Mid-scale specialists concentrate on application-specific performance gaps in automotive clearcoats and digital printing inks. Competitive moves center on backward integration into resin production and geographic licensing of proprietary curing chemistries.
Within the integrated leader tier, BASF SE anchors European coating supply through captive emulsion capacity, while PPG Industries exemplifies North American automotive refinish positioning. Asian Paints Limited occupies a dominant contractor-channel position in South Asian decorative coatings. These three entities represent distinct archetypes: feedstock-integrated multinational, technology-licensing refinish specialist, and distribution-anchored regional leader.
| Leading Market Players |
|---|
| BASF SE |
| Flint Group |
| AkzoNobel N.V. |
| Sakata Inx Corporation |
| Siegwerk Druckfarben AG & Co. KGaA |
| PPG Industries Inc. |
| DIC Corporation |
| Asian Paints Limited |
| The Sherwin-Williams Company |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts between integrated resin producers and automotive OEMs lock in acrylic emulsion supply access while anchoring price visibility across coating formulation tiers. These arrangements concentrate procurement leverage among German and Chinese manufacturers facing EU REACH and MEE compliance deadlines, compressing margin flexibility for regional blenders lacking backward integration.
Pricing Analysis
After-sales technical service and tinting system support drive lifetime value capture in decorative coatings, separating premium suppliers from commodity competitors. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under EPA National Emission Standards and ISO environmental management tiers. Cost compression in economy-grade architectural coatings is intensifying as unorganized suppliers in India undercut BIS-certified competitors. Contractors in South Asian construction markets exhibit acute price sensitivity, while German automotive OEMs absorb premium clearcoat pricing without volume elasticity.
Supply Chain Analysis
Inventory buffers and extended lead times for acrylic monomer feedstock expose regional blenders to Gulf Coast and Middle Eastern export hub volatility. Supply concentrates in integrated petrochemical complexes across the United States, Saudi Arabia, and South Korea, with specialty additives sourcing from Japanese and German chemical producers. Raw material dependencies center on acrylic monomers, polyurethane dispersions, and UV photoinitiators for hybrid curing systems. Single-source vulnerability runs through concentrated emulsion polymer production, with tariff exposure on imported specialty resins elevating formulation costs. Distribution runs through authorized dealer networks for decorative coatings and direct technical sales for automotive specification grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Water-borne formulation chemistry fragmentation creates opportunity as procurement authority migrates from plant managers to corporate sustainability officers, opening niches for compliance-documented suppliers. Digital printing displacement and UV-curable hybrid adoption are splintering demand across application-specific performance tiers.
For Market Incumbents: Consolidate captive emulsion capacity through selective acquisition of distressed regional blenders facing feedstock cost pressure. Deepen technical service bundling for automotive OEMs to defend specification authority against emerging self-crosslinking acrylic suppliers. Channel control through localized tinting systems in South Asia anchors volume retention against price-aggressive competitors.
For New Entrants and Emerging Players: Digital textile printing service gaps in Bangladesh and Vietnam garment export zones offer white-space positioning for reactive water-borne ink sets with rapid color-matching capabilities. Brazilian industrial licensing alignment under ANVISA creates penetrable geography for emulsion production investments serving São Paulo capital equipment manufacturers. Go-to-market through direct mill relationships bypasses entrenched distributor networks.
For Investors and Strategic Acquirers: Regional resin producers with captive acrylic emulsion capacity and established automotive qualifications represent acquisition targets with durable cash flow visibility. Long-term viability hinges on feedstock integration depth and geographic exposure to tightening VOC regulatory clusters. Monitor provincial discharge permit trading system liquidity in Jiangsu and Zhejiang as inflection indicator for compliance credit monetization potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Emulsion Production | Captive feedstock supply secures cost position against Gulf Coast price volatility for European coating lines. |
| UV-Curable Water-Borne Hybrid Platform Launch | Dual-cure chemistry accelerates wood furniture drying cycles without sacrificing film hardness benchmarks. |
| Provincial Compliance Credit Accumulation | Early MEE-aligned water-borne adoption in Jiangsu generates tradable VOC reduction reserves for carbon accounting. |
| Digital Printing Ink Formulation Partnership | Piezoelectric inkjet compatibility with flexible circuit substrates captures electronics packaging cluster demand. |
| Localized Tinting System Network Expansion | Dense contractor-channel presence in Maharashtra and Gujarat defends decorative coatings volume against unorganized competitors. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with formulation chemists, automotive coating procurement leads, and distribution channel partners, combined with secondary validation against customs trade data, Cefic chemical industry reports, and SEC filings from integrated resin producers. Plant managers at Midwest metal fabrication facilities and Southeast wood furniture manufacturers provided operational perspective on EPA compliance timelines. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Across the modeling period, analytical frameworks projected demand trajectories by product type, application technology, and regional regulatory cluster intensity. CAGRs were derived from segment-level volume elasticities and price trajectory assumptions. Forecast inputs incorporated automotive OEM coating line retooling schedules, electronics packaging capacity expansion in East Asian manufacturing clusters, and provincial discharge permit trading system development in China.
Forecasts assume regulatory continuity in EU REACH, EPA National Emission Standards, and China MEE dual carbon enforcement; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Printing Inks
Squid Ink Market
Printing Inks
Eco-Friendly Inks Market
Printing Inks
Waterborne Ink Market
Printing Inks
Screen Printing Inks Market
Printing Inks
Lithography Inks Market
Printing Inks
Lithographic Printing Chemicals Market
Printing Inks
Water-Based Metal-Deco Beverage Can Inks Market
Printing Inks
Printing Inks Market
Printing Inks
Global UV (Ultraviolet) Curable Inks Market
Printing Inks
North America Ink Market
Printing Inks
North America Printing Inks Market
Printing Inks
United States Flexographic Printing Market
Printing Inks
Global Flexographic Inks Market
Printing Inks
Rapid Liquid Printing Market
Printing Inks
Inkjet Colorants Market
Printing Inks
UV Fluorescing Ink Market