
 Water Recycle and Reuse Technologies Market | 2026-2036
Water Recycle and Reuse Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Water Recycle and Reuse Technologies Market Insights
Australia's mining belt is fragmenting technology procurement patterns as remote sites confront escalating freshwater logistics costs and tightening discharge permits. Veolia leverages its integrated service model across consulting, implementation, and maintenance to capture recurring revenue streams in these dispersed operations. Xylem sustains technology leadership in membrane filtration and reverse osmosis systems through sustained R&D intensity in energy-efficient pumping and advanced oxidation processes. Fluence Corporation Limited specializes in decentralized, containerized treatment units that navigate infrastructure gaps across Western Australia's Pilbara region and Queensland's Bowen Basin.
Water recycle and reuse technologies encompass engineered systems that recover, treat, and reintroduce process or wastewater into industrial, agricultural, or municipal supply loops, typically achieving total dissolved solids reduction below 10 mg/L for ultrapure applications and pathogen elimination to 4-log standards for potable reuse. These systems serve primarily to reduce freshwater withdrawal volumes, minimize effluent discharge liabilities, and secure operational continuity against hydrological volatility and regulatory constraint. Membrane filtration occupies the dominant technology position due to its modular scalability and declining specific energy consumption per cubic meter treated. Reverse osmosis represents the fastest-expanding segment as semiconductor and pharmaceutical end users demand ever-tighter contaminant rejection for process water recycling. Chemical treatment retains mature, margin-compressed status in bulk municipal applications where commodity coagulant and disinfectant costs limit differentiation.
The EPA's effluent limitation guidelines and the EU's Water Framework Directive, alongside Australia's National Water Initiative, collectively shape product standards, certification requirements, and market access conditions for technology suppliers across their respective jurisdictions. These frameworks mandate progressively lower discharge limits, impose water accounting and reporting obligations, and create compliance-driven procurement that favors validated, third-party-certified treatment packages over unproven alternatives. Stakeholders must monitor regulatory harmonization pressures between jurisdictions and assess whether their technology portfolios can adapt to emerging contaminants of concern including per- and polyfluoroalkyl substances and antimicrobial resistance genes.
Market Dynamics
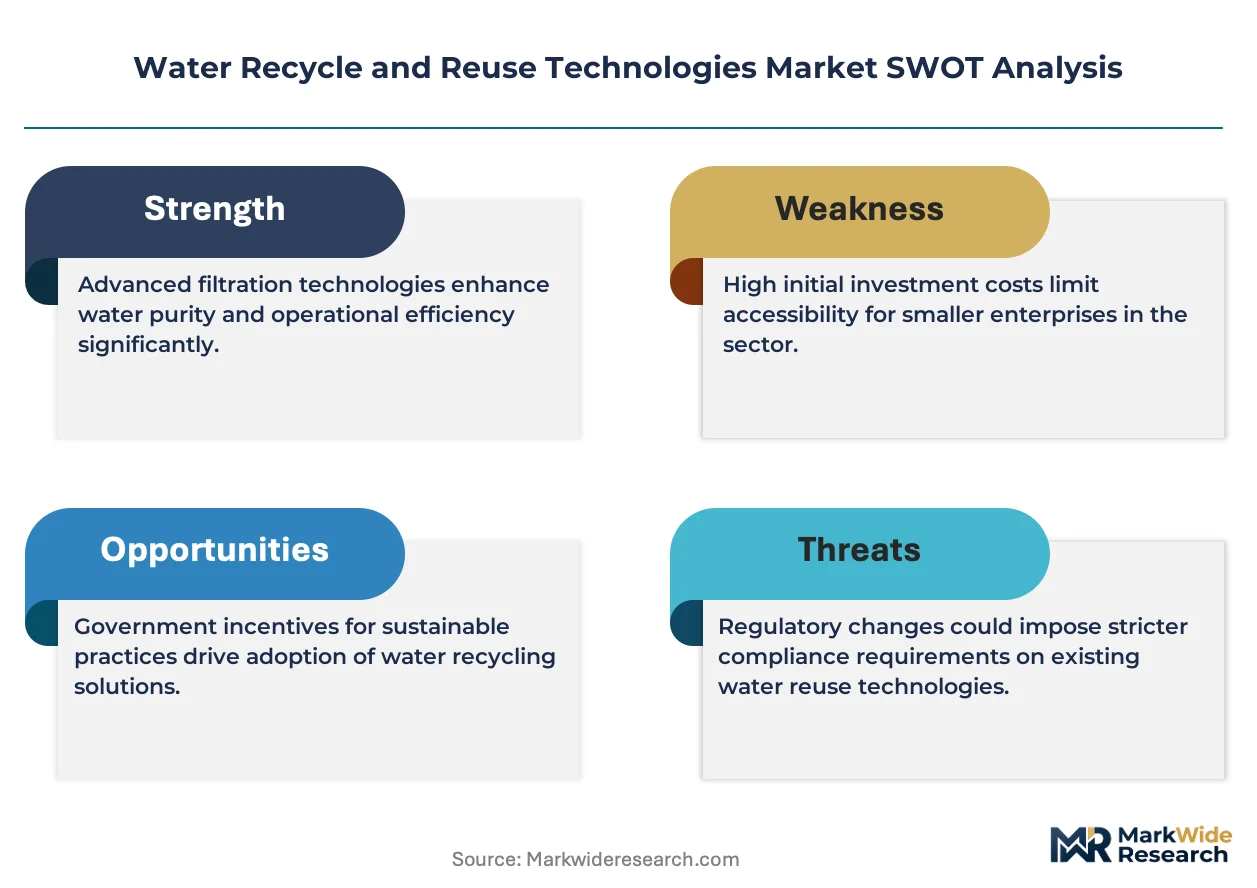
Membrane filtration economics are compressing capital recovery timelines for ultrapure water systems, forcing incumbent chemical treatment suppliers to restructure their equipment-plus-chemicals bundling models or exit semiconductor and pharmaceutical verticals entirely.
Growth Catalysts
- EPA Effluent Limitation Guidelines:Industrial dischargers across Arizona, Texas, and California face mandated transition from once-through cooling to closed-loop configurations, directly stimulating membrane bioreactor procurement.
- Semiconductor fabrication expansion:Taiwan Semiconductor Manufacturing and Intel are scaling Arizona operations, each facility requiring 10-15 million gallons of ultrapure water daily that must be recycled to secure operating permits.
- Containerized treatment units:Western Australia's Pilbara iron ore corridors are adopting plug-and-deploy reverse osmosis skids to eliminate 400-kilometer freshwater trucking circuits.
Market Restraints
- Specialized membrane polymer supply:Polyamide thin-film composite production concentrates in Japan and Germany, exposing system integrators to 14-18 month order backlogs during feedstock disruptions.
- Energy cost volatility:High-pressure reverse osmosis pumping consumes 3-4 kWh per cubic meter treated, making operations in Queensland and Nevada vulnerable to grid price spikes.
- PFAS destruction limitations:Current advanced oxidation processes achieve only partial mineralization of per- and polyfluoroalkyl substances, leaving semiconductor fabs exposed to emerging discharge limits.
Strategic Opportunities
- Saudi Arabia's NEOM gigaproject:The kingdom's zero-liquid-discharge mandate for Red Sea coastal developments creates demand for 100% water recycling at scale unprecedented outside Singapore's Tuas Nexus.
- Electrochemical oxidation convergence:Boron-doped diamond electrodes paired with UV-LED arrays are opening direct potable reuse pathways that bypass multi-barrier configurations.
- India's semiconductor incentive scheme:Gujarat and Karnataka fabs must meet 40% recycling thresholds to qualify for PLI scheme subsidies, accelerating localized membrane manufacturing partnerships.
Industry Challenges
- Cross-connection control certification:California's Title 22 and Texas Commission on Environmental Quality require separate licensed operators for potable and non-potable reuse systems, fragmenting workforce deployment.
- Legacy SCADA integration:Mining and power generation facilities operating 1990s-era distributed control systems face protocol incompatibility with modern membrane performance monitoring platforms.
- Antimicrobial resistance gene validation:No standardized qPCR protocols exist for 4-log removal verification, forcing utilities to negotiate case-by-case approval with state health departments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Recycle and Reuse Technologies Market |
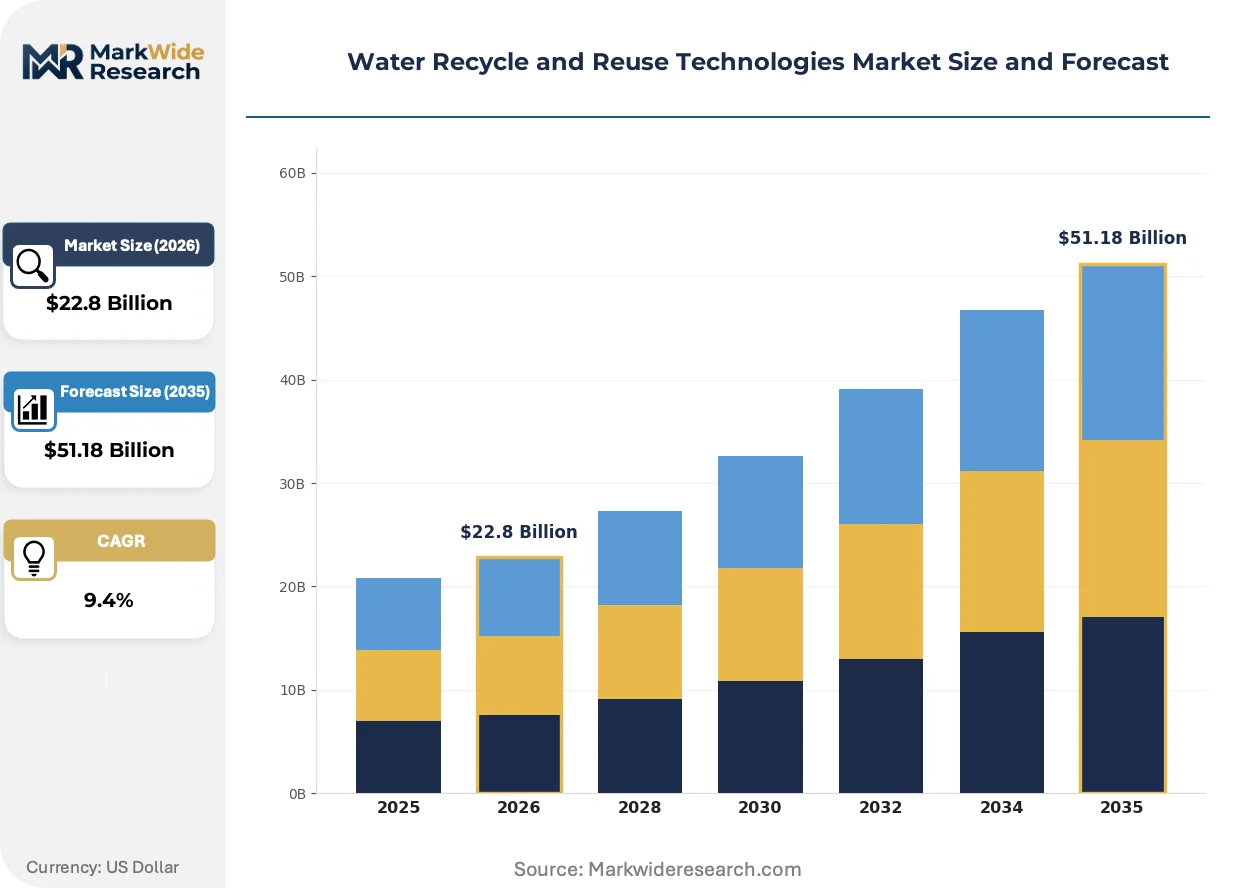
| Market Size in 2026 | $22.8 Billion |
| Market Size in 2035 | $51.18 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Membrane Filtration, Reverse Osmosis, Distillation, Chemical Treatment Application: Agricultural Irrigation, Industrial Processes, Potable Reuse, Aquifer Recharge End User: Municipalities, Manufacturing Plants, Power Generation, Hospitality Sector Service Type: Consulting Services, Implementation, Maintenance, System Design |
| Companies Covered | Veolia, Xylem, SUEZ, Ecolab Inc., DuPont, Aquatech, Pentair, Fluence Corporation Limited, Hitachi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Recycle and Reuse Technologies Market Trends and Innovations
Digital twins and real-time membrane fouling prediction are displacing scheduled maintenance cycles, while regulatory pressure on emerging contaminants forces technology suppliers to validate performance against evolving analytical methods rather than static discharge limits.
Artificial neural networks trained on transmembrane pressure, conductivity, and particle count signals are digitizing predictive maintenance for reverse osmosis trains. Semiconductor fabs in Arizona and Texas deploy these systems to compress unplanned downtime from 48-hour catastrophic membrane failures to 4-hour planned module replacements. The shift is digitizing service contract structures from fixed-fee maintenance toward performance-guaranteed availability pricing.
The EU's revised Drinking Water Directive now mandates monitoring of 20 additional micro-pollutants including pharmaceutical residues and endocrine disruptors, compelling municipal reuse projects to upgrade from conventional ozonation to ozone-plus-biofiltration sequences. German utilities in Bavaria and North Rhine-Westphalia are piloting these configurations ahead of 2027 compliance deadlines. The regulation is accelerating technology substitution in European municipal procurement, where chemical treatment incumbents face displacement unless they acquire advanced oxidation capabilities.
Consolidated purchasing by hyperscale data center operators is compressing vendor margins and unbundling after-sales service from equipment supply. Microsoft and Amazon Web Services now contract membrane replacement and chemical optimization separately through third-party facility managers, stripping original equipment manufacturers of recurring revenue streams. This disintermediation is most advanced in Northern Virginia's Data Center Alley and Amsterdam's Schiphol-Rijk corridor, where single buyers represent 30-40% of quarterly ultrapure water system orders.
Water Recycle and Reuse Technologies Market Segmentation
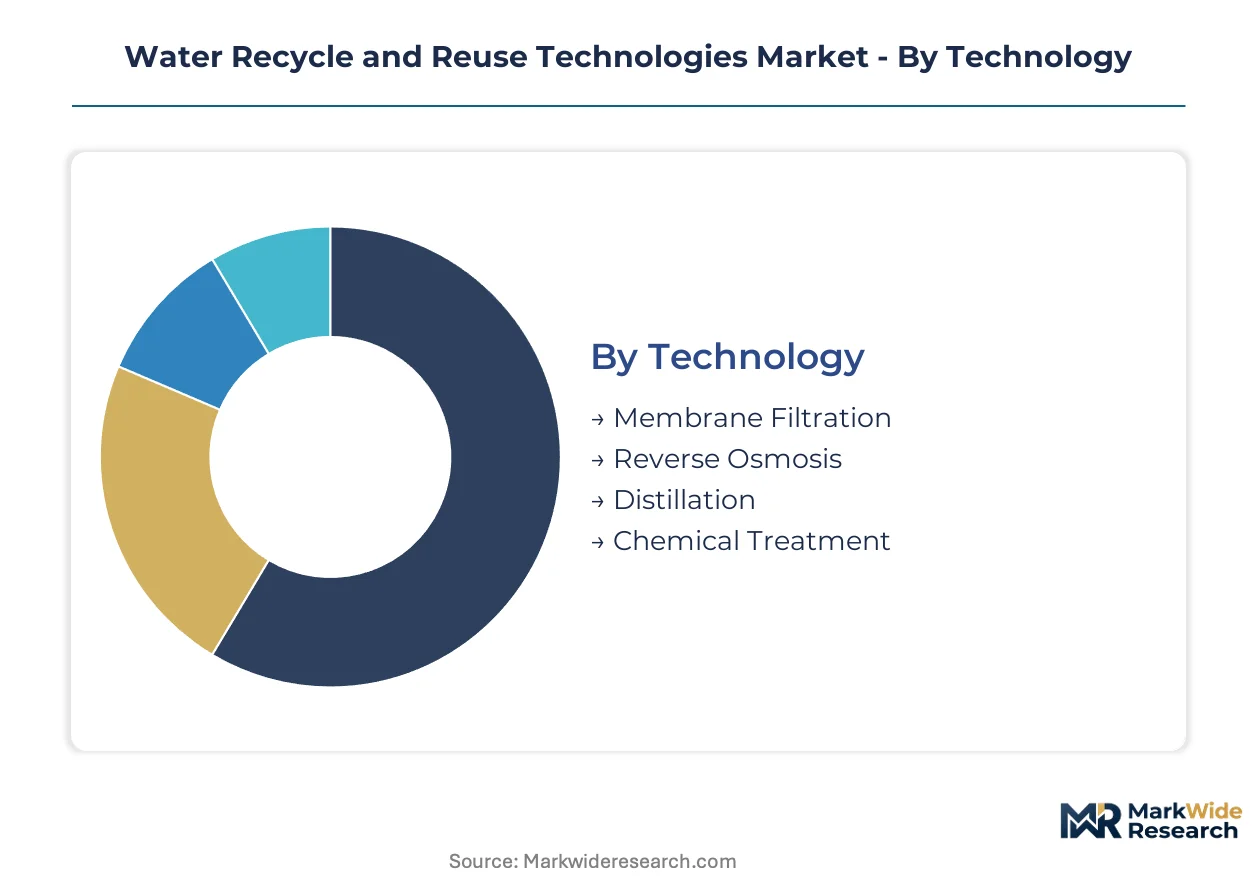
Technology choices in water recycling determine capital intensity, energy footprint, and service contract structures. Procurement patterns fragment sharply across end-use verticals, with semiconductor fabs demanding 24/7 availability guarantees while mining operations prioritize modular deployability.
Technology:
After-sales service intensity varies dramatically across technology categories, with membrane systems requiring quarterly module replacement and chemical treatment demanding continuous reagent logistics.
- Membrane Filtration:Polymeric or ceramic barriers operating at 0.1-10 micron precision remove suspended solids and microorganisms without phase change. Arizona semiconductor fabs deploy these systems for particle control in ultrapure water loops, with service contracts typically covering 15-20% of initial capital annually in consumables and membrane replacement.
- Reverse Osmosis:High-pressure semipermeable membranes achieving dissolved solids rejection above 99% through size exclusion and solution-diffusion mechanisms. Western Australia's Pilbara mining corridors specify containerized RO skids to eliminate 400-kilometer freshwater trucking circuits, with energy costs representing 35-45% of operating expenditure.
- Distillation:Thermal separation leveraging vapor-liquid equilibrium for near-total contaminant rejection, deployed where energy costs are subsidized or waste heat is available.
- Chemical Treatment:Coagulation, flocculation, and disinfection sequences using commodity aluminum or iron salts plus chlorine derivatives, common in bulk municipal applications with thin margins.
Membrane filtration holds the largest share; momentum sits with reverse osmosis as semiconductor and pharmaceutical end users tighten contaminant rejection specifications.
Application:
Cost tier stratification separates premium ultrapure systems from economy-grade irrigation configurations, with price differentials exceeding 10x per cubic meter treated.
- Industrial Processes:Closed-loop treatment for cooling towers, boilers, and manufacturing rinses requiring conductivity below 100 μS/cm. Texas and Arizona fabrication facilities drive specification intensity here, with EPA effluent guidelines mandating zero liquid discharge at new semiconductor campuses.
- Potable Reuse:Multi-barrier treatment trains achieving 4-log pathogen reduction and advanced oxidation for trace organic destruction, qualifying for direct or indirect drinking water augmentation. Queensland and California utilities lead deployment, navigating state-specific health department validation protocols.
- Agricultural Irrigation:Tertiary-treated municipal effluent or farm-scale runoff recovery, common in water-stressed growing regions of Spain and Australia's Murray-Darling Basin.
- Aquifer Recharge:Soil-aquifer treatment or direct injection of reclaimed water for groundwater replenishment, requiring extended detention times for natural attenuation.
Industrial processes command the largest installed base; potable reuse is climbing the fastest as regulatory frameworks mature in multiple jurisdictions.
End User:
Customer type determines procurement sophistication, with municipalities favoring design-build-operate concessions while manufacturing plants prefer equipment purchase with separate service contracts.
- Municipalities:Public water utilities managing centralized wastewater reclamation facilities serving 100,000+ connections. Australia's National Water Initiative drives investment here, with discharge permits tightening total nitrogen and phosphorus limits.
- Manufacturing Plants:Discrete industrial facilities with process-specific water quality requirements. Intel and Taiwan Semiconductor Manufacturing operations in Arizona exemplify this segment, each demanding 10-15 million gallons of ultrapure water daily with 85-95% recycling ratios.
- Power Generation:Thermal and combined-cycle plants requiring cooling tower blowdown recovery and boiler feedwater pretreatment.
- Hospitality Sector:Hotels and resorts pursuing green certification through greywater recycling for irrigation and toilet flushing.
Manufacturing plants represent the fastest-expanding customer type; municipalities retain the largest cumulative capacity under management.
Service Type:
Margin profiles diverge across the service lifecycle, with consulting and system design capturing premium pricing while maintenance contracts generate predictable recurring revenue.
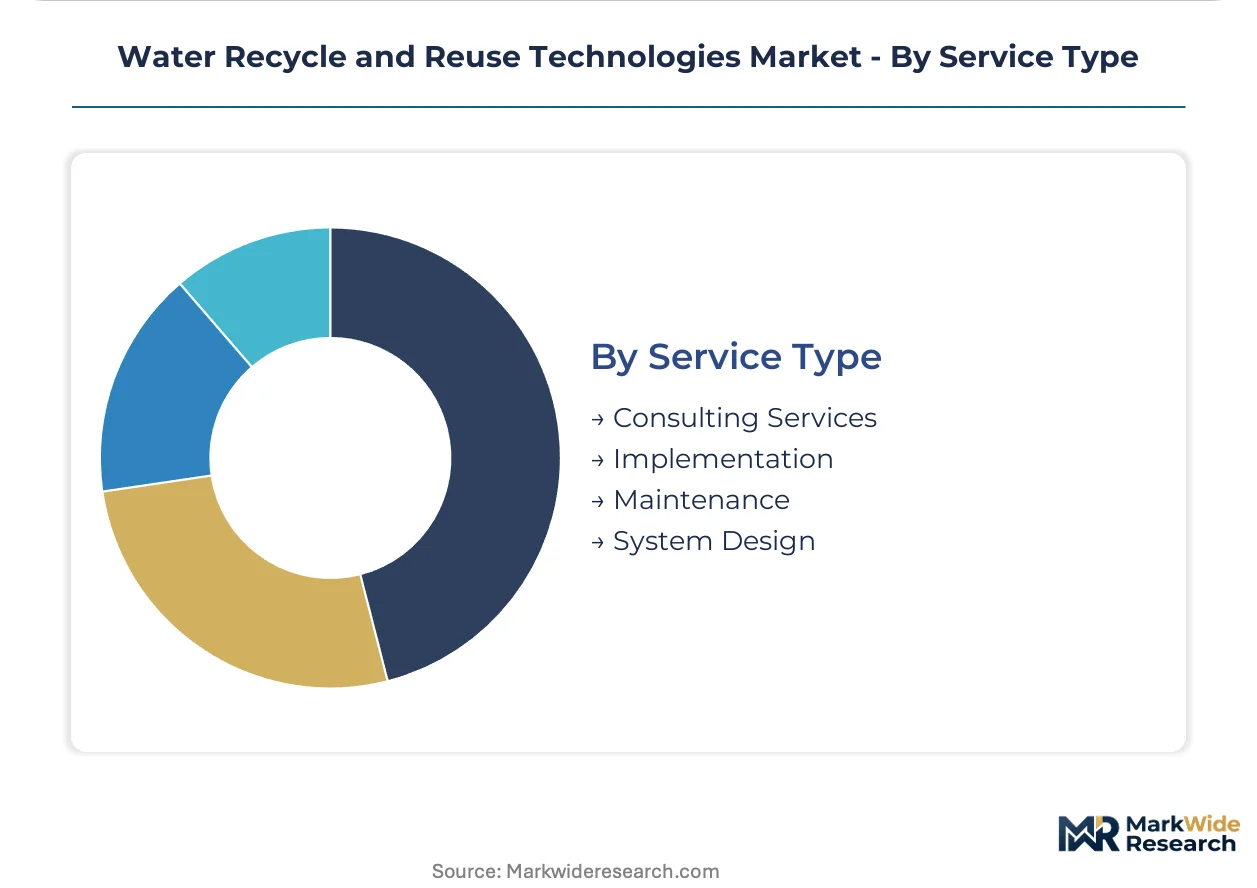
- Implementation:Turnkey engineering, procurement, and construction delivery of integrated treatment trains. Veolia and Suez dominate this segment in Australia's mining corridors, bundling civil works with process equipment.
- Maintenance:Scheduled membrane replacement, chemical optimization, and emergency response services. Semiconductor fabs in Arizona contract these separately through third-party facility managers, compressing OEM margins.
- Consulting Services:Feasibility studies, regulatory permitting support, and water balance optimization for new developments.
- System Design:Process flow development, equipment specification, and integration engineering for custom applications.
Implementation generates the largest project values; maintenance commands the steepest expansion trajectory as installed base ages and outsourcing accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Colorado River Aqueduct underpins southwestern US industrial water security, while Australia's 3,000-kilometer Goldfields Water Supply Scheme enables mining operations across the Pilbara and Kalgoorlie corridors.
United States
Semiconductor fabrication expansion in Arizona and Texas drives membrane bioreactor procurement as each new campus requires 10-15 million gallons of ultrapure water daily. EPA effluent limitation guidelines mandate closed-loop cooling configurations at industrial discharge points. Intel and Taiwan Semiconductor Manufacturing operations in Phoenix and Chandler exemplify this demand concentration.
Australia
Western Australia's iron ore corridors face 400-kilometer freshwater trucking circuits that containerized reverse osmosis skids now eliminate. The National Water Initiative tightens discharge permits across mining leases in the Pilbara and Queensland's Bowen Basin. Fluence Corporation Limited specializes in decentralized treatment units navigating these infrastructure gaps.
Saudi Arabia
NEOM's zero-liquid-discharge mandate for Red Sea coastal developments creates demand for complete water recycling at unprecedented scale. The kingdom's regulatory framework for gigaproject developments exceeds Singapore's Tuas Nexus standards. Desalination brine management and industrial process loops concentrate technology deployment in the northwestern province.
Germany
Bavarian and North Rhine-Westphalian utilities pilot ozone-plus-biofiltration sequences ahead of 2027 EU Drinking Water Directive compliance deadlines for 20 additional micro-pollutants. The revised directive mandates pharmaceutical residue and endocrine disruptor monitoring. German chemical treatment incumbents face displacement unless they acquire advanced oxidation capabilities.
India
Gujarat and Karnataka semiconductor fabrication facilities must meet 40% recycling thresholds to qualify for PLI scheme subsidies. India's semiconductor incentive scheme accelerates localized membrane manufacturing partnerships. The country's national water regulator validates treatment packages through third-party certification protocols.
Water Recycle and Reuse Technologies Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying membranes, pumps, and sensors. The vendor base stratifies into three tiers: multinational conglomerates bundling engineering, procurement, and construction; mid-cap technology houses with concentrated membrane or oxidation expertise; and regional fabricators of containerized skids for remote deployment. Strategic moves concentrate on acquiring advanced oxidation capabilities and forming localized manufacturing partnerships to bypass polyamide thin-film composite supply bottlenecks.
Within the integrated service tier, Veolia and SUEZ exemplify platform players capturing recurring revenue across consulting, implementation, and maintenance. Xylem anchors the component specialist category through sustained positioning in membrane filtration and energy-efficient pumping. Fluence Corporation Limited occupies the decentralized deployment archetype, representing regional fabricators that navigate infrastructure gaps through containerized treatment configurations.
| Leading Market Players |
|---|
| Veolia |
| Xylem |
| SUEZ |
| Ecolab Inc. |
| DuPont |
| Aquatech |
| Pentair |
| Fluence Corporation Limited |
| Hitachi |
| Others |
Pricing and Supply Chain Analysis
Polyamide thin-film composite supply bottlenecks from Japan and Germany determine both the 14-18 month order backlog spreads between premium and economy tiers and the geographic clustering of membrane system integrators near coastal logistics hubs.
Pricing Analysis
Volume-discount tiering structures separate semiconductor fabs purchasing 10-15 million gallon daily ultrapure systems from mining operators procuring single containerized skids. Price differentiation hinges on ISO 9001 certification grade and after-sales service bundling intensity. Cost compression in the economy tier is intensifying as hyperscale data center operators unbundle maintenance from equipment supply. Municipal utilities exhibit highest price sensitivity due to bond-financing constraints, while pharmaceutical manufacturers prioritize availability guarantees over unit economics.
Supply Chain Analysis
Contract manufacturing capacity for membrane modules concentrates with Toray Industries and LG Chem facilities in Japan and South Korea. Polymeric membrane production draws from petrochemical feedstocks anchored in the US Gulf Coast and Northeast Asian refining complexes. Single-source vulnerability pervades the polyamide thin-film composite segment, where two suppliers control 80% of global capacity. Distribution runs through system integrators who bundle engineering, procurement, and construction services for end-to-end project delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates sticky customer relationships. Validation protocols and discharge permits embed incumbents deeply into operational continuity planning.
For Market Incumbents: Harden service contract structures against disintermediation by third-party facility managers through predictive maintenance platform lock-in. Deepen backward integration into membrane polymer production to neutralize Japanese and German supply chokepoints. The threat of hyperscale buyer consolidation demands captive chemical optimization capabilities to preserve recurring revenue streams. For New Entrants and Emerging Players: Establish a beachhead in Western Australia's Pilbara iron ore corridors where 400-kilometer freshwater trucking circuits create urgent substitution demand. Containerized reverse osmosis skids for remote mining operations represent the most penetrable white-space segment. A go-to-market angle anchored on modular deployability and rapid commissioning timelines bypasses incumbent engineering advantages. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors advanced oxidation capability acquirers over pure-play membrane suppliers. Long-term viability rests on emerging contaminant treatment validation, particularly PFAS destruction and antimicrobial resistance gene removal. Acquisition targets should demonstrate third-party certification depth and regulatory relationships across multiple jurisdictions. The signal to watch is EPA effluent guideline expansion to semiconductor process streams beyond cooling applications.| Strategic Initiative | Industry Significance |
|---|---|
| Advanced Oxidation Capability Acquisition | PFAS destruction mandates from EPA and EU Water Framework Directive displace chemical treatment incumbents lacking mineralization technology. |
| Localized Membrane Manufacturing Partnership | India's PLI scheme subsidies require 40% recycling thresholds, creating captive supply opportunities for Gujarat and Karnataka fabs. |
| Predictive Maintenance Platform Development | Artificial neural networks trained on transmembrane pressure signals compress Arizona semiconductor fab downtime from 48 hours to 4 hours. |
| Containerized Treatment Unit Expansion | Plug-and-deploy reverse osmosis skids eliminate 400-kilometer freshwater trucking circuits across Western Australia's Pilbara region. |
| Zero-Liquid-Discharge System Integration | Saudi Arabia's NEOM gigaproject mandates 100% water recycling, exceeding Singapore's Tuas Nexus standards for coastal developments. |
Research Methodology
The analysis maps membrane filtration, reverse osmosis, chemical treatment, and distillation sub-sectors, each validated through interviews with plant engineers at semiconductor fabs and mining operations, membrane system procurement leads, EPA regulatory affairs specialists, and aftermarket service directors. Secondary sources include EPA effluent limitation guideline filings, EU Water Framework Directive implementation reports, Australia's National Water Initiative compliance databases, and SEC 10-K disclosures from publicly traded water technology suppliers. Bottom-up project pipeline tracking triangulates against top-down regulatory mandate sizing.
Analytical frameworks held energy cost volatility and polyamide supply continuity as fixed baseline conditions while varying semiconductor fab expansion timelines and mining corridor freshwater logistics costs across the projection horizon. Segmentation dimensions modeled include technology category, application tier, end-user type, and service lifecycle phase. CAGRs derive from installed base aging curves and replacement demand elasticity calibrated to regulatory compliance deadlines. Forecast inputs incorporate membrane replacement frequency data and containerized unit deployment velocity in remote resource extraction zones.
Stress conditions across polyamide supply disruption duration, grid electricity price spikes in Queensland and Nevada, and PFAS discharge limit stringency were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions regarding regulatory harmonization pace and emerging contaminant analytical method standardization. Quarterly review of EPA effluent guideline expansion scope and EU Drinking Water Directive micro-pollutant list updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Water Treatment Market
Water & Sludge Treatment
Water Purification Systems Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
Global Sludge Treatment Chemicals Market
Water & Sludge Treatment
Global Industrial Sludge Treatment Chemicals Market
Water & Sludge Treatment
North America Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
United States Water Treatment Chemicals Market
Water & Sludge Treatment
US Water and Wastewater Treatment Market
Water & Sludge Treatment
Global Electrodeionization Market
Water & Sludge Treatment
Water Dispersible Granules Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
India Water Treatment Chemicals Market
Water & Sludge Treatment
Global Liquid Waste Management Market
Water & Sludge Treatment
US Liquid Waste Management Market
Water & Sludge Treatment
Salt Water Softeners Market
Water & Sludge Treatment
Ballast Water Treatment Market