
 Salt Water Softeners Market | 2026-2036
Salt Water Softeners Market Size, Share, and Industry Trends Forecast 2026-2036
Salt Water Softeners Market Insights
EPA effluent guidelines for water treatment residuals is repositioning the cost-of-entry calculus for new salt water softener manufacturers. Culligan International Company leverages its captive dealer network to sustain installation-service revenue across fragmented local markets. Pentair PLC anchors its position through backward integration into control valve assembly, while Kinetico Incorporated differentiates via non-electric, demand-initiated regeneration systems that reduce salt consumption per cycle.
Salt water softeners are ion-exchange systems that remove calcium and magnesium ions from hard water by substituting sodium ions through a resin bed, typically regenerating with sodium chloride brine at programmable intervals. The primary purpose is preventing scale accumulation in plumbing, appliances, and industrial heat-exchange equipment. Traditional softeners dominate unit shipments across residential channels, though digital softeners with Wi-Fi-enabled monitoring represent the fastest-expanding margin pool as homeowners prioritize predictive maintenance alerts. Ion exchange technology leads commercial and industrial installations for its proven capacity at high flow rates, while reverse osmosis systems capture premium segments requiring simultaneous contaminant reduction.
The EPA oversees brine discharge permitting under the Clean Water Act, while NSF/ANSI Standard 44 governs performance certification for residential cation exchange systems, and the DOE regulates standby energy consumption for electrically powered units. These frameworks collectively elevate compliance costs for uncertified imports and redirect procurement toward validated equipment. Stakeholders must monitor evolving salt-efficiency thresholds and emerging municipal brine-restriction ordinances that could abruptly reshape product specifications and replacement cycles.
Market Dynamics
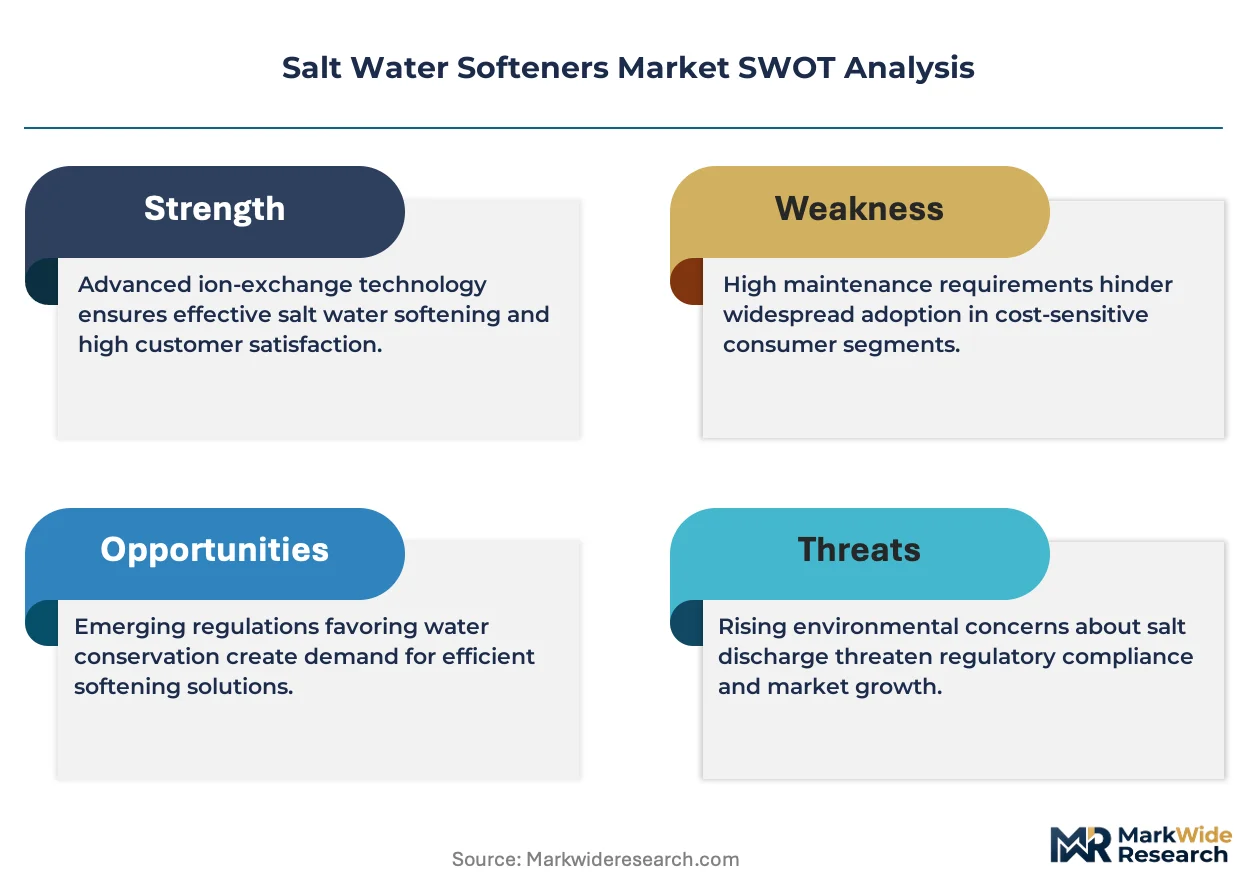
EPA brine discharge scrutiny under the Clean Water Act is forcing manufacturers to redesign regeneration cycles around salt-efficiency metrics, compressing margins for uncertified equipment while elevating demand-validated systems.
Growth Catalysts
- Suburban Housing Construction:Sun Belt states including Texas and Florida are experiencing rapid residential development where calcium-heavy municipal supplies necessitate whole-home softening infrastructure.
- NSF/ANSI Standard 44 Certification:Performance validation requirements for residential cation exchange systems are filtering uncertified imports and consolidating procurement toward tested equipment.
- Industrial Heat-Exchange Protection:Manufacturing facilities with high-volume boiler operations require ion-exchange softening to prevent scale-induced thermal efficiency losses and unplanned downtime.
Market Restraints
- Sodium Chloride Price Volatility:Bulk salt costs fluctuate with winter road treatment demand and agricultural runoff regulations, compressing operating margins for high-frequency regeneration systems.
- Municipal Brine Restriction Ordinances:Local wastewater authorities in California and Arizona are imposing discharge concentration limits that render conventional softeners non-compliant without costly pretreatment.
- Template-Assisted Crystallization:Salt-free conditioning alternatives are capturing price-sensitive residential segments despite inferior scale prevention performance at high flow rates.
Strategic Opportunities
- Wi-Fi-Enabled Predictive Maintenance:Digital softeners with remote monitoring capabilities are creating recurring revenue streams through subscription-based salt delivery and filter replacement services.
- Non-Electric Demand-Initiated Regeneration:Kinetic-powered systems eliminate standby energy consumption, aligning with DOE efficiency mandates while reducing salt waste per cycle.
- Commercial Laundry Operations:Hospitality and healthcare facilities with continuous hot water demand represent underpenetrated verticals requiring high-capacity twin-tank configurations.
Industry Challenges
- Control Valve Assembly Expertise:Precision machining of multi-port valve bodies requires specialized hydraulic engineering talent concentrated among legacy Midwest manufacturers.
- Dual Certification Timelines:Simultaneous NSF/ANSI 44 and DOE energy compliance testing extends product launch cycles by 8-14 months for new market entrants.
- Legacy Plumbing Integration:Retrofit installations in pre-1980s housing stock encounter incompatible pipe sizing and electrical routing that inflate labor costs and cancellation rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salt Water Softeners Market |
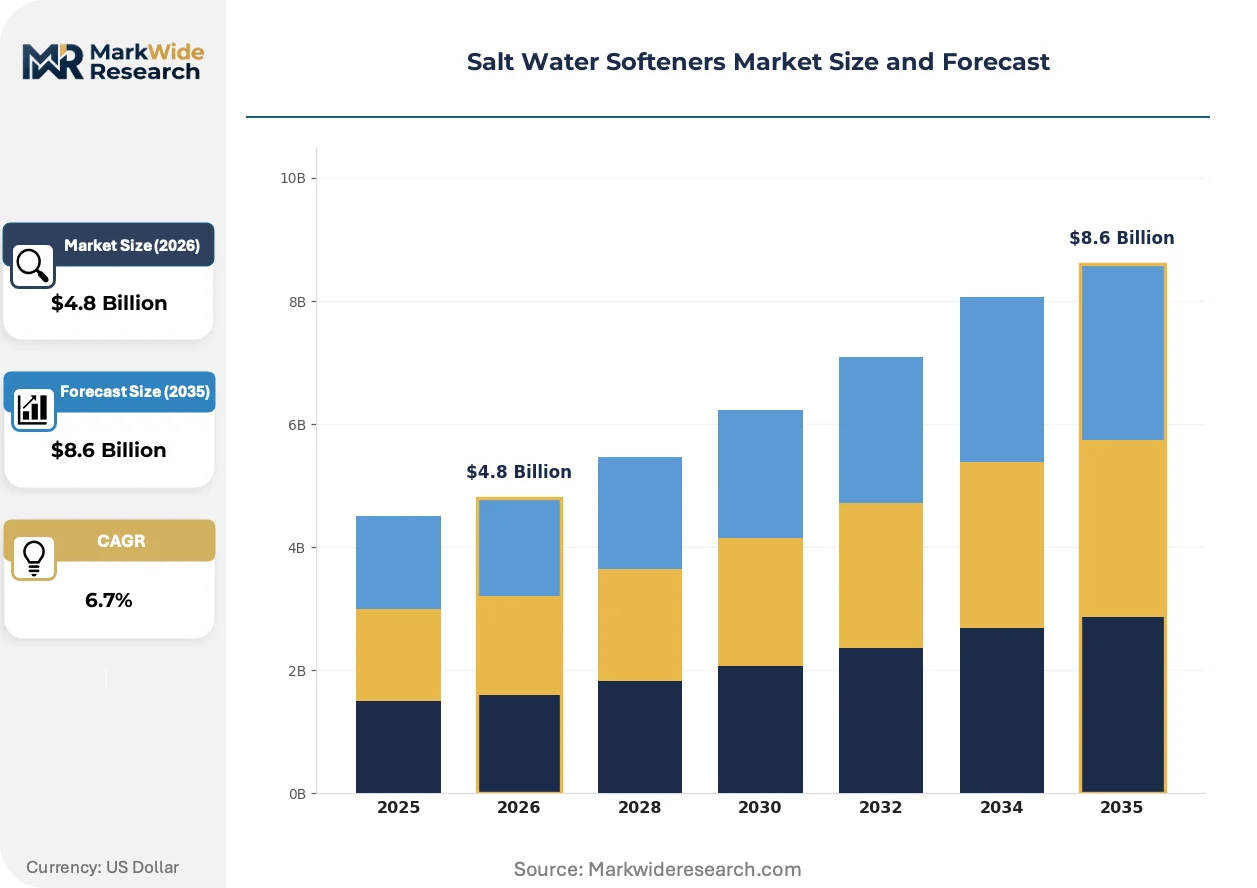
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Softeners, Magnetic Softeners, Digital Softeners, Portable Softeners Technology: Ion Exchange, Reverse Osmosis, Electrodialysis, Carbon Filtration End User: Residential, Commercial, Industrial, Agricultural Distribution Channel: Online Retail, Direct Sales, Wholesalers, Supermarkets |
| Companies Covered | Culligan International Company, EcoWater Systems LLC, Kinetico Incorporated, Pentair PLC, A.O. Smith Corporation, NuvoH2O, LLC, Watts Water Technologies, Inc., Hague Quality Water International, Fleck Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salt Water Softeners Market Trends and Innovations
Digital connectivity and salt-efficiency mandates are converging to redefine equipment specifications, shifting competitive advantage from hardware durability toward data-driven service ecosystems and regulatory pre-certification.
Smart softener systems with embedded flow sensors and cloud-connected control boards are absorbing market share from electromechanical timer-based units. Residential buyers in suburban developments are specifying Wi-Fi monitoring during new construction at accelerating rates. This technology is absorbing service revenue from traditional dealer networks by enabling direct-to-consumer salt replenishment and remote diagnostic troubleshooting.
The EPA's evolving effluent guidelines for water treatment residuals are tightening brine discharge concentration thresholds in coastal watersheds. Manufacturers are responding with variable-brining algorithms that adjust salt dosage based on actual water usage rather than fixed intervals. California and Florida municipalities are most affected, with local authorities accelerating permit reviews for salt-efficient equipment while restricting conventional system installations.
Homeowners are unbundling installation from equipment purchase, sourcing softeners through online marketplaces and engaging independent plumbers for retrofit work. Big-box retail and direct-to-consumer channels are displacing captive dealer networks in residential replacement cycles. This pattern is most visible in Texas and Arizona metropolitan areas where housing turnover rates exceed national averages and consumer price transparency tools are widely adopted.
Salt Water Softeners Market Segmentation
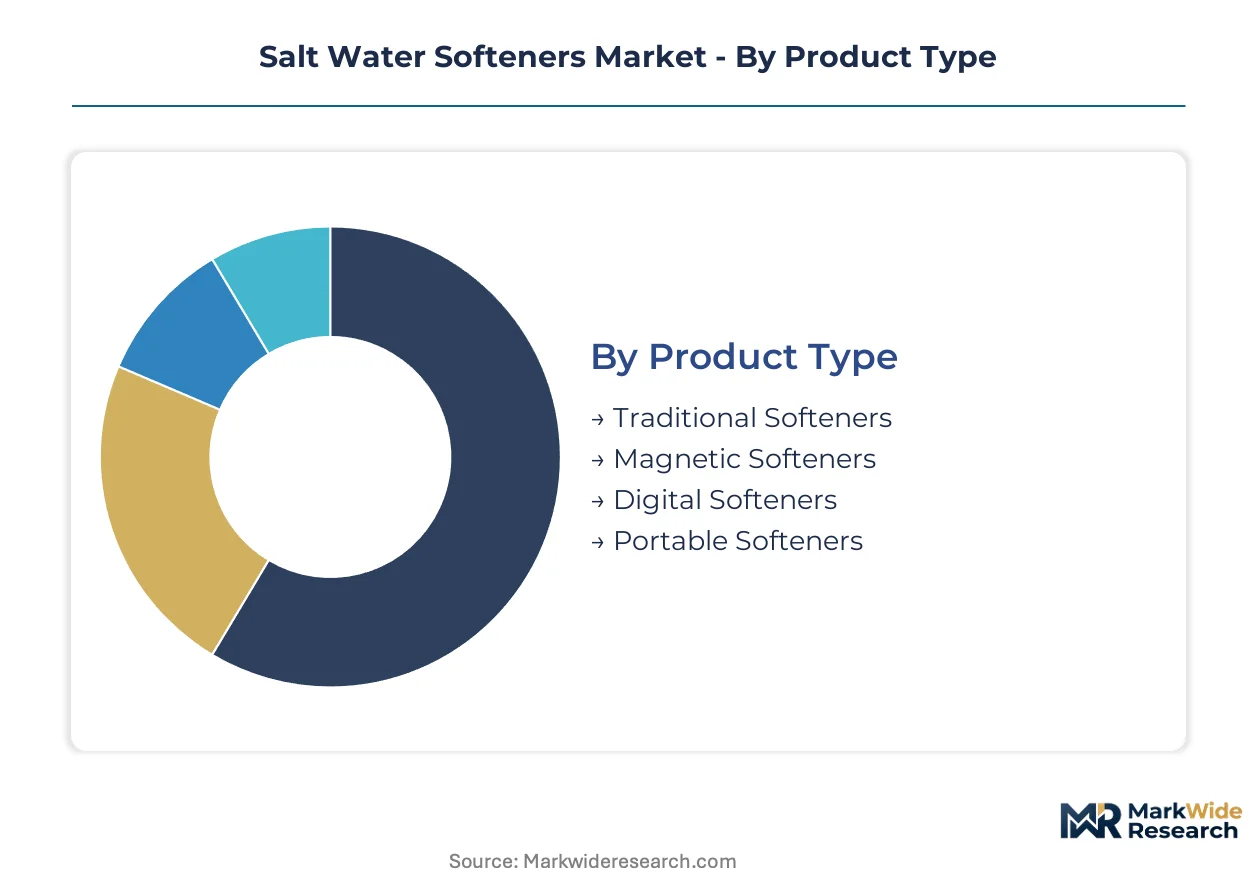
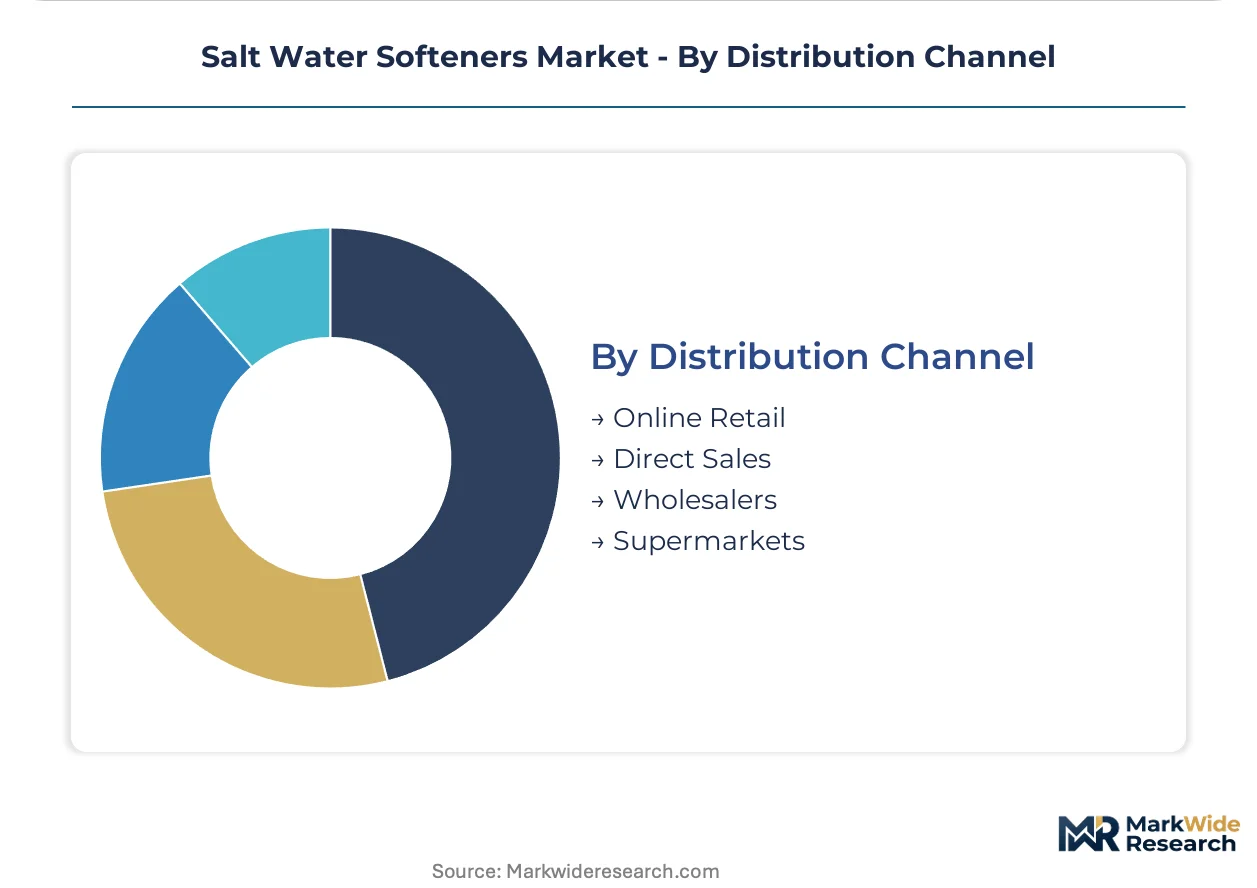
Segmentation in salt water softeners reveals how technology maturity, regulatory pressure, and channel economics partition value capture. Product design priorities diverge sharply between incumbent ion-exchange systems and emerging connectivity-enabled alternatives, while distribution restructuring redraws competitive boundaries.
Product Type:
Supply concentration for finished softener assemblies clusters among Midwest valve manufacturers and Sun Belt distribution hubs, creating geographic moats around service-intensive product categories.
- Traditional Softeners:Electromechanical timer-based units with fixed-interval regeneration dominate replacement cycles in pre-2000s housing stock. Demand concentrates in Texas and Florida suburban developments where calcium-heavy municipal supplies necessitate whole-home infrastructure and dealer installation networks retain pricing power.
- Digital Softeners:Wi-Fi-enabled systems with embedded flow sensors and cloud-connected control boards absorb share from timer-based units. Demand concentrates in Arizona and Nevada metropolitan areas where housing turnover exceeds national averages and consumers unbundle installation from equipment purchase through online marketplaces.
- Magnetic Softeners:Descaling devices using electromagnetic fields alter mineral crystallization without ion removal. Consumer adoption clusters among price-sensitive buyers in states without municipal brine restrictions.
- Portable Softeners:Compact regeneration units target RV owners and rental property managers requiring temporary hard water treatment. Seasonal demand peaks align with Sun Belt migration patterns.
Today's leader: Traditional Softeners. Tomorrow's challenger: Digital Softeners.
Technology:
Cost tier stratification separates proven ion-exchange systems from premium alternatives competing on contaminant reduction capabilities rather than scale prevention alone.
- Ion Exchange:Sodium-substitution resin beds regenerated with sodium chloride brine deliver proven capacity at high flow rates. Commercial and industrial installations in manufacturing facilities with boiler operations require this technology to prevent thermal efficiency losses, while residential adoption climbs across Sun Belt states with calcium-heavy supplies.
- Reverse Osmosis:Membrane-based separation removes dissolved solids alongside hardness minerals. Premium residential segments in coastal California municipalities with brine discharge restrictions specify these systems despite higher capital costs and wastewater volumes.
- Electrodialysis:Electric-field-driven ion transport through selective membranes suits specialized industrial applications with moderate hardness loads. Niche adoption in food processing facilities with sodium-sensitive operations.
- Carbon Filtration:Activated carbon removes chlorine and organic compounds but provides minimal scale prevention. Frequently paired with ion-exchange softeners in municipal supply areas with taste and odor complaints.
Volume concentrates with Ion Exchange. Margin expansion centers on Reverse Osmosis.
End User:
Application-specific performance requirements segment procurement patterns across residential convenience priorities, commercial uptime imperatives, and industrial thermal efficiency mandates.
- Residential:Whole-home systems protecting plumbing and appliances from scale accumulation. Suburban housing construction in Texas and Florida drives specification rates during new development.
- Commercial:Hospitality and healthcare facilities with continuous hot water demand require high-capacity twin-tank configurations. Underpenetrated verticals represent expansion opportunities for service-enabled suppliers.
- Industrial:Manufacturing facilities with high-volume boiler and heat-exchange operations specify ion-exchange systems to prevent unplanned downtime from scale-induced thermal losses.
- Agricultural:Irrigation systems in calcium-heavy groundwater regions employ softening to prevent emitter clogging. Seasonal demand patterns align with planting cycles in Central Valley operations.
Replacement revenue anchors Residential. Service contract potential distinguishes Commercial.
Distribution Channel:
Customer type and purchase occasion reshape channel economics, with digital-native buyers bypassing traditional dealer networks while retrofit installations sustain plumber-dependent intermediaries.
- Online Retail:Direct-to-consumer platforms enable equipment purchase unbundled from installation. Big-box and marketplace channels displace captive dealer networks in Texas and Arizona replacement cycles where price transparency tools are widely adopted.
- Direct Sales:Manufacturer-owned dealer networks sustain installation-service revenue across fragmented local markets. Culligan International Company leverages this structure to defend recurring maintenance relationships.
- Wholesalers:Plumbing supply houses serve independent contractors performing retrofit installations in pre-1980s housing stock with incompatible pipe sizing.
- Supermarkets:Big-box retail locations capture emergency replacement purchases and salt replenishment traffic. Limited to portable units and consumables rather than whole-home systems.
Transaction volume shifts to Online Retail. Relationship value persists with Direct Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The salt water softener industry traces its modern origins to Midwestern United States manufacturing clusters established during the post-war suburban expansion, where ion-exchange resin technology first achieved residential scale. Today, demand geography follows hard water prevalence and housing construction patterns across distinct national markets.
United States
Sun Belt suburban developments in Texas and Florida drive residential specification rates where calcium-heavy municipal supplies necessitate whole-home infrastructure. The EPA's Clean Water Act brine discharge scrutiny under evolving effluent guidelines is tightening salt-efficiency requirements for coastal watershed installations. Phoenix and Las Vegas metropolitan areas exhibit accelerating consumer adoption of Wi-Fi-enabled digital systems unbundled from traditional dealer networks.
Germany
Industrial boiler operations in the Ruhr manufacturing corridor sustain commercial ion-exchange demand for scale prevention and thermal efficiency protection. The country's national environmental regulator enforces wastewater discharge standards that elevate certification requirements for brine-intensive equipment. Bavarian precision engineering clusters around Munich supply control valve assemblies to European OEMs.
China
Rapid urban residential construction in Yangtze River Delta cities including Shanghai and Hangzhou is expanding addressable market for compact softening systems. The Ministry of Ecology and Environment implements dual carbon goals that redirect procurement toward energy-efficient regeneration technologies. Shandong Peninsula chemical manufacturing bases represent emerging industrial demand for high-capacity twin-tank configurations.
India
Groundwater-dependent housing developments in Gujarat and Maharashtra face severe hardness levels that accelerate residential penetration. The Bureau of Indian Standards governs equipment safety certification, though salt-efficiency standards remain less stringent than Western benchmarks. Bangalore's technology corridor exhibits early adoption of subscription-based salt delivery models enabled by IoT-connected units.
Australia
Calcium-rich bore water in Western Australian mining towns sustains portable and industrial softener demand for worker housing and processing facilities. The national environmental regulator oversees brine disposal permits that constrain conventional system deployment in sensitive coastal catchments. Queensland agricultural irrigation operations employ softening to prevent emitter clogging in high-value horticulture zones.
Salt Water Softeners Market Competitive Landscape
The competitive structure tilts toward integrated manufacturers with captive distribution networks defending recurring service revenue. Market concentration is moderate, with legacy Midwest valve fabricators and diversified water treatment conglomerates commanding distinct tier positions. Two strategic archetypes dominate: vertically integrated assemblers controlling critical component supply, and service-intensive dealers monetizing installation and maintenance relationships. Primary competitive moves encompass backward integration into resin and valve production, plus geographic expansion through authorized dealer territory acquisition.
Among North American diversified water technology conglomerates, Pentair PLC and A.O. Smith Corporation exemplify scale-driven positions anchored by multi-product portfolio breadth. Culligan International Company represents the service-intensive archetype, with its captive dealer structure sustaining localized installation and salt replenishment relationships. Kinetico Incorporated occupies a differentiated niche through non-electric system architecture. Specialists in salt-free conditioning alternatives include NuvoH2O, LLC, while component suppliers such as Fleck Systems provide valve assemblies to downstream assemblers.
| Leading Market Players |
|---|
| Culligan International Company |
| EcoWater Systems LLC |
| Kinetico Incorporated |
| Pentair PLC |
| A.O. Smith Corporation |
| NuvoH2O, LLC |
| Watts Water Technologies, Inc. |
| Hague Quality Water International |
| Fleck Systems |
| Others |
Pricing and Supply Chain Analysis
Sodium chloride brine costs cascade from agricultural and road-treatment demand cycles through to residential softener operating expenses, compressing margins for high-frequency regeneration systems while rewarding salt-efficient equipment with pricing power in brine-restricted municipalities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates NSF/ANSI 44-certified digital systems from uncertified timer-based units and entry-level magnetic conditioners. Price differentiation hinges on certification grade and after-sales service bundling, with installation-inclusive packages commanding substantial premiums over direct-to-consumer equipment sales. Pricing pressure stems from bulk salt volatility and municipal discharge compliance costs, with price-sensitive buyers in unrestricted states gravitating toward salt-free alternatives while certified-system purchasers show lower elasticity.
Supply Chain Analysis
Control valve assembly expertise rests on Midwest United States precision machining clusters and Bavarian engineering hubs around Munich, with resin bed production concentrated among specialty chemical manufacturers in China and Germany. Raw material dependencies span ion-exchange resins, multi-port valve bodies, and electronic control boards, creating exposure to semiconductor availability for digital system production. Supply chain risk centers on single-source vulnerability for specialized hydraulic engineering talent, while distribution runs through captive dealer networks, online retail platforms, and plumbing supply wholesalers serving retrofit contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The salt water softener market functions as a regulatory compounder where EPA brine discharge scrutiny under evolving Clean Water Act effluent guidelines continuously elevates compliance costs and redirects procurement toward pre-certified, salt-efficient equipment.
For Market Incumbents: Acquire control valve assembly capabilities to secure upstream margin capture and reduce dependency on Midwest specialty fabricators. Consolidate authorized dealer territories in Texas and Florida suburban corridors to defend recurring salt replenishment revenue against direct-to-consumer disintermediation. Template-assisted crystallization alternatives and Wi-Fi-enabled predictive maintenance platforms represent the most credible substitution threats requiring monitoring. For New Entrants and Emerging Players: California municipal brine restriction ordinances open a window for salt-efficient system specialists to capture replacement cycles where conventional equipment faces permit denials. Target Arizona and Nevada metropolitan areas exhibiting accelerating housing turnover and online marketplace adoption for unbundled equipment-installation transactions. A subscription-based salt delivery model enabled by IoT-connected flow sensors offers the most penetrable go-to-market angle against entrenched dealer networks. For Investors and Strategic Acquirers: Consolidation pressure builds where fragmented local dealer operations lack capital to fund dual NSF/ANSI 44 and DOE certification investments required for product launch viability. Mid-scale assemblers with captive resin supply or proprietary non-electric regeneration technology present the most attractive acquisition archetypes over the coming decade. Watch for municipal brine-restriction ordinance adoption rates in coastal watersheds as the primary inflection indicator for salt-efficient equipment demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Control Valve Production | Pentair PLC's captive valve assembly secures margin capture and supply continuity against Midwest fabricator bottlenecks. |
| Wi-Fi-Enabled Predictive Maintenance Platform Launch | Remote monitoring capabilities create recurring revenue streams through subscription salt delivery and filter replacement services. |
| Non-Electric Demand-Initiated Regeneration Investment | Kinetico Incorporated's kinetic-powered systems align with DOE efficiency mandates while reducing salt waste per cycle. |
| Authorized Dealer Territory Acquisition | Culligan International Company's captive network sustains installation-service revenue across fragmented local Sun Belt markets. |
| Dual Certification Compliance Program | Simultaneous NSF/ANSI 44 and DOE testing extends product launch cycles but filters uncertified import competition. |
Research Methodology
Bottom-up residential and commercial installation modeling reconciled against top-down manufacturer shipment tracking forms the analytical core of this study. Primary interviews with water treatment equipment dealers, municipal wastewater authority permitting officers, plumbing contractor procurement leads, and residential construction specification managers combined with secondary validation from EPA effluent guideline dockets, NSF/ANSI certification registries, DOE appliance standards databases, and customs import records. Triangulation across these sources ensures demand-side consumption patterns align with supply-side production and distribution flows.
Input-output matrices map ion-exchange resin consumption, control valve assembly volumes, and finished system shipments across product type, technology, end user, and distribution channel dimensions over the projection horizon. CAGRs derive from regression analysis of housing construction permits, municipal water hardness data, and regulatory adoption timelines, with segment-specific growth rates calibrated against replacement cycle frequencies and new installation penetration rates in calcium-heavy supply regions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt municipal brine-restriction ordinance adoption or sodium chloride price spikes from agricultural runoff regulation changes. Forecasts reflect documented assumptions regarding EPA effluent guideline evolution timelines, Sun Belt housing construction sustainability, and consumer unbundling of installation from equipment purchase. A small set of named triggers—municipal discharge permit denial rates, Wi-Fi-enabled system adoption curves, and template-assisted crystallization performance improvements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water & Sludge Treatment
Global Municipal Water Treatment Chemicals Market
Water & Sludge Treatment
Sludge Heater Market
Water & Sludge Treatment
Water Treatment Polymers Market
Water & Sludge Treatment
North America Boiler Water Treatment Chemicals Market
Water & Sludge Treatment
India Water Treatment Chemicals Market
Water & Sludge Treatment
Hypochlorous Acid Water Generator Market
Water & Sludge Treatment
North America Membrane Water and Wastewater Treatment (WWT) Market
Water & Sludge Treatment
Global Water Clarifiers Market
Water & Sludge Treatment
Water Treatment Market
Water & Sludge Treatment
Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Europe Water Treatment Chemicals Market
Water & Sludge Treatment
Global Naphthalene Water Reducers Market
Water & Sludge Treatment
Germany Water Treatment Chemicals Market
Water & Sludge Treatment
North America Membrane Water Treatment Chemicals Market
Water & Sludge Treatment
Oil and Gas Water Treatment Chemicals Market
Water & Sludge Treatment
Produced Water Treatment Market