
 Water Cut Monitor Market | 2026-2036
Water Cut Monitor Market Size, Share, and Industry Trends Forecast 2026-2036
Water Cut Monitor Market Analysis
API-compliant precision-tier measurement is unwinding legacy tolerance bands across upstream separation systems. Emerson Electric Co. leverages its automation platform to anchor permanent-deployment contracts in deepwater basins. Schlumberger Limited sustains technology leadership in nuclear magnetic resonance sensing for high-salinity reservoirs. Weatherford competes through integrated flow-measurement bundles that reduce wellsite instrumentation count.
A water cut monitor measures the volumetric ratio of water to hydrocarbon in multiphase flow streams, typically operating across 0-100% water-cut range with ±2% accuracy using microwave, capacitance, or optical sensing principles; its core industrial purpose is to optimize separator performance, allocate production, and ensure pipeline quality specifications. Capacitance technology dominates onshore installations where cost sensitivity and moderate salinity levels predominate, while nuclear magnetic resonance systems command premium positioning in heavy-oil and high-salinity offshore environments where dielectric methods degrade. Ultrasonic segments are gaining share in mobile deployment configurations for well-testing and workover applications where rapid rig-up outweighs absolute precision requirements.
EPA effluent limitation guidelines for produced water discharge shape product certification requirements in US onshore and offshore operations, while OSPAR regulations in the North Sea mandate continuous monitoring for zero-harmful-discharge platforms. The EU Industrial Emissions Directive extends comparable obligations to European offshore assets, creating harmonized demand for calibration-traceable instruments. Stakeholders must weigh sensor longevity against total cost of ownership as operators extend field life in mature basins and redeploy capital toward emissions-reduction technologies.
Market Dynamics
Offshore operators in the North Sea and Gulf of Mexico are accelerating permanent-installation deployments to meet tightening produced-water discharge standards while optimizing separation efficiency. Real-time water-cut measurement is becoming non-negotiable for compliance verification and operational cost control.
Growth Catalysts
- EPA Effluent Limitation Guidelines:US onshore and offshore producers must install continuous monitoring systems to verify discharge compliance, driving certified instrument procurement.
- OSPAR Convention mandates:North Sea platforms face zero-harmful-discharge obligations requiring real-time water-cut validation for produced-water reinjection or overboard release.
- Microwave sensing miniaturization:Packaged sensor electronics reduce footprint and installation costs for brownfield retrofit applications.
Market Restraints
- High-salinity sensor degradation:Dielectric methods fail in heavy-brine reservoirs, forcing costly nuclear magnetic resonance upgrades or dual-technology redundancy.
- Calibration service concentration:Third-party calibration providers cluster in Houston, Aberdeen, and Stavanger, creating logistics bottlenecks for remote field locations.
- Capital intensity of permanent installations:Subsea-rated housings and explosion-proof certifications multiply upfront costs versus portable alternatives.
Strategic Opportunities
- Brazil pre-salt expansion:Deepwater developments off Rio de Janeiro and Espírito Santo lack mature water-cut infrastructure, creating first-mover positioning for integrated flow-measurement vendors.
- Digital twin integration:Combining real-time water-cut data with predictive separation models enables automated setpoint adjustment and reduced chemical injection.
- EU Industrial Emissions Directive extension:Offshore assets in Norwegian, UK, and Dutch waters face harmonized continuous-monitoring obligations, standardizing procurement specifications.
Industry Challenges
- Multiphase flow expertise scarcity:Field engineers capable of interpreting water-cut anomalies in high-GOR or slug-flow conditions command premium compensation and extended deployment timelines.
- Legacy SCADA integration friction:Proprietary communication protocols in existing separator control systems require custom gateway development for new sensor feeds.
- Traceability documentation burden:API and ISO calibration certificates must chain through national metrology institutes, extending commissioning schedules by weeks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Cut Monitor Market |
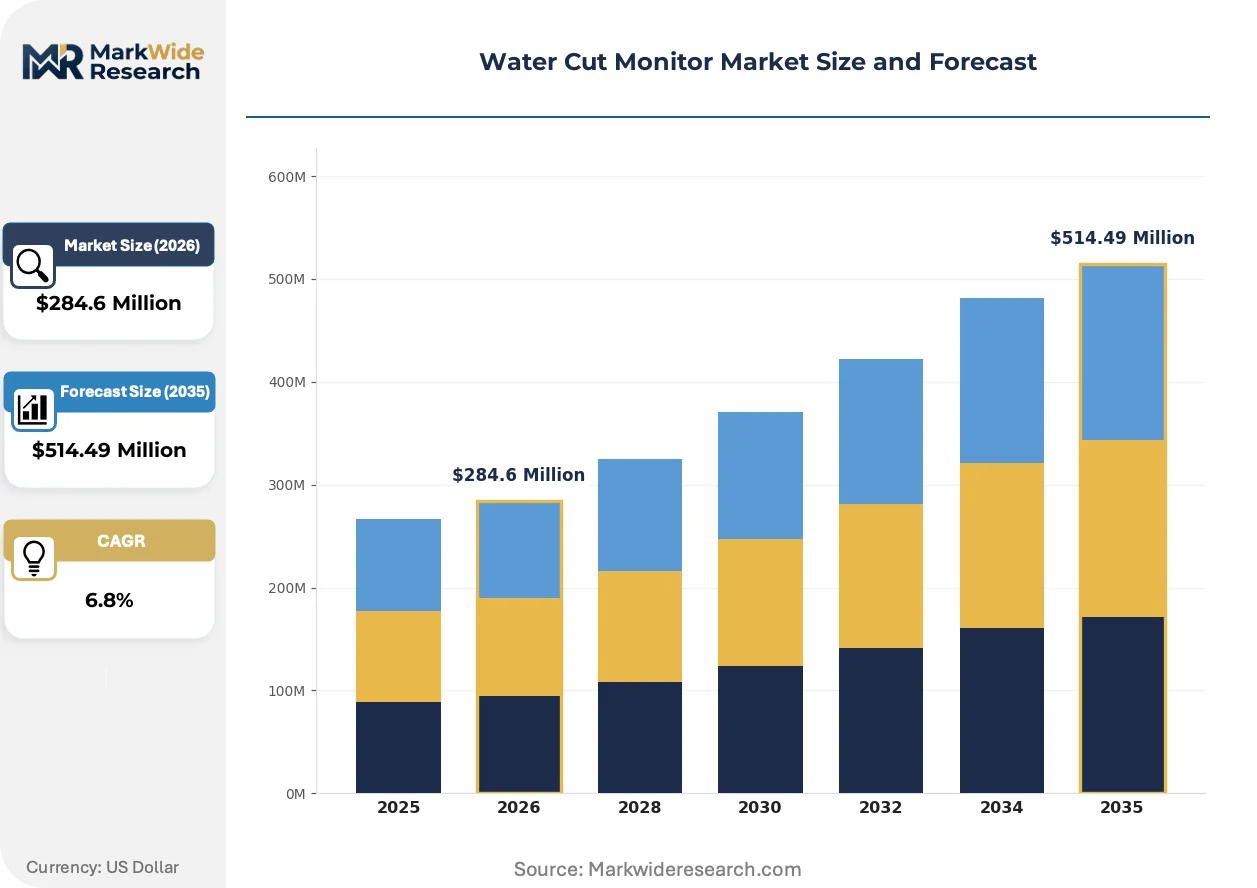
| Market Size in 2026 | $284.6 Million |
| Market Size in 2035 | $514.49 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Capacitance, Nuclear Magnetic Resonance, Ultrasonic, Optical End User: Oil & Gas Producers, Refineries, Water Treatment Facilities, Environmental Agencies Deployment: Onshore, Offshore, Mobile, Permanent Application: Chemical Injection, Flow Measurement, Leak Detection, Quality Control |
| Companies Covered | Emerson Electric Co., Schlumberger Limited, Weatherford, AMETEK Inc., TechnipFMC, Phase Dynamics, Agar Corporation, Sentech AS, ZelenTech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Cut Monitor Market Emerging Trajectories
Sensor fusion architectures are replacing single-technology dependence as operators demand measurement redundancy across wider salinity and temperature ranges. Vendors are bundling diagnostic software to transform raw water-cut data into actionable separation optimization guidance.
Microwave resonance sensing is supplanting traditional capacitance methods in offshore installations where high-salinity formation water degrades dielectric accuracy. Major operators in the Gulf of Mexico and North Sea are specifying dual-frequency microwave systems for new permanent deployments. This technology shift is compressing the addressable market for pure capacitance vendors while elevating RF engineering capabilities as a competitive differentiator.
OSPAR's 2025 zero-discharge framework revision tightens continuous-monitoring requirements for platforms with produced-water reinjection capacity. Operators must demonstrate real-time water-cut verification at injection headers, not merely separator outlets. Subsea-rated NMR systems are capturing premium positioning in Norwegian and UK sectors where reinjection dominates disposal economics.
Integrated service contracts are displacing equipment-only procurement as national oil companies consolidate vendor relationships. Saudi Aramco and Petrobras now specify performance-based water-cut assurance spanning hardware, calibration, and data interpretation. This bundling compresses pure-play sensor margins while rewarding vendors with adjacent automation portfolios.
Water Cut Monitor Market Segmentation
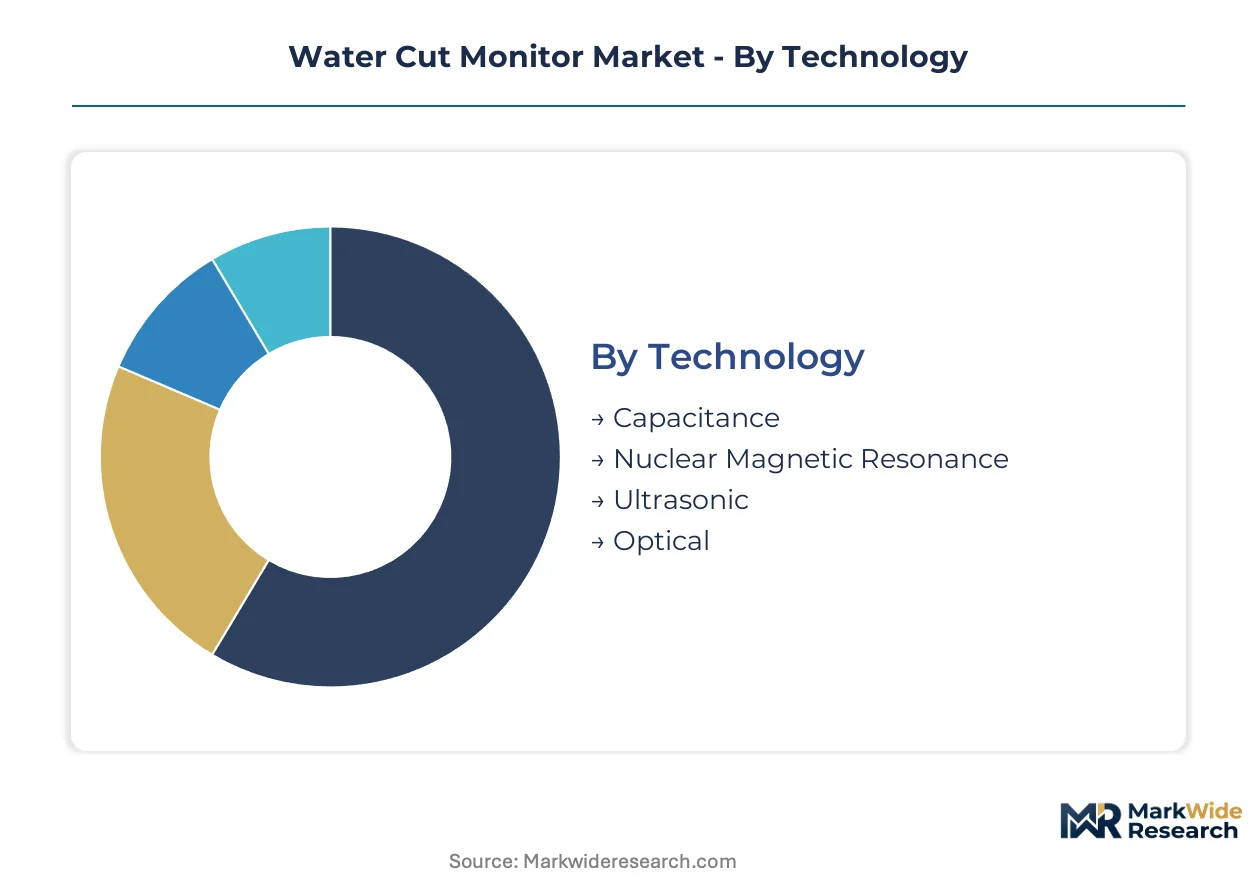
Technology selection in water cut monitoring directly determines total cost of ownership and calibration frequency across upstream installations. Deployment mode and end-user requirements further stratify procurement specifications, with offshore operators demanding subsea-rated housings and environmental agencies mandating traceable certification chains.
Technology:
Margin pools concentrate in premium sensing platforms that tolerate high-salinity formation water without dual-technology redundancy.
- Capacitance:Dielectric measurement systems detect water content through permittivity differentials between hydrocarbon and aqueous phases. Onshore Permian and Bakken producers favor this technology for moderate-salinity crude streams where unit economics prioritize capital efficiency over absolute precision.
- Nuclear Magnetic Resonance:NMR platforms exploit hydrogen spin relaxation properties to distinguish water from oil independent of salinity or density variations. Deepwater Gulf of Mexico and North Sea operators specify these systems for heavy-oil reservoirs where dielectric methods degrade, accepting premium pricing for measurement stability.
- Ultrasonic:Acoustic attenuation sensors measure phase distribution through sound wave propagation characteristics. Mobile well-testing units across Texas and Alberta deploy these for rapid rig-up scenarios where portability outweighs laboratory-grade accuracy.
- Optical:Near-infrared absorption systems identify water-cut through spectral signature analysis. These occupy niche positions in light-oil pipelines where clarity permits optical path transmission.
Capacitance holds installed capacity across North American onshore basins. Nuclear Magnetic Resonance is rotating up the share rankings in high-salinity offshore developments.
End User:
Procurement authority shifts between operational and regulatory stakeholders depending on discharge permit structure.
- Oil & Gas Producers:Upstream operators integrate water-cut monitors into separator control loops to optimize chemical injection rates and reduce wastewater handling costs. Supermajors in the North Sea and Gulf of Mexico specify permanent-installation contracts with embedded calibration services.
- Refineries:Downstream facilities deploy monitors at crude receipt points to verify pipeline quality specifications and trigger desalting unit adjustments. Complex refineries along the US Gulf Coast prioritize real-time data integration with distributed control systems.
- Water Treatment Facilities:Produced-water processing plants use water-cut validation to confirm reinjection fluid quality or verify overboard discharge compliance. These installations cluster around mature basins where water production volumes exceed oil output.
- Environmental Agencies:Regulatory bodies mandate third-party certified instruments for permit verification and enforcement sampling. EPA regional offices and OSPAR competent authorities specify API-traceable calibration protocols.
Oil & Gas Producers dominate current procurement volumes. Environmental Agencies are expanding fastest as discharge rules tighten across multiple jurisdictions.
Deployment:
Capital intensity varies by an order of magnitude between portable rental units and subsea permanent installations.
- Onshore:Fixed installations at wellhead separators and gathering stations characterize mature basins with established infrastructure. Brownfield retrofit applications in the Permian Basin favor compact microwave sensors with minimal piping modifications.
- Offshore:Platform-mounted and subsea-rated housings must satisfy explosion-proof certifications and marine corrosion standards. Norwegian sector developments specify redundant measurement chains for zero-discharge compliance verification.
- Mobile:Trailer-mounted or skid-based systems support well-testing, workover, and exploration appraisal activities. Rental fleets in Houston and Aberdeen serve spot demand without permanent capital commitment.
- Permanent:Hardwired installations with integrated SCADA connectivity enable automated separator control and continuous data logging. Deepwater pre-salt developments off Brazil increasingly specify this deployment mode from first oil.
Onshore holds installed capacity across conventional and unconventional basins. Permanent installations are climbing the fastest as digital integration priorities reshape procurement specifications.
Application:
Functional requirements determine sensor specification, with safety-critical applications demanding higher redundancy than allocation metering.
- Chemical Injection:Real-time water-cut data triggers automatic demulsifier and corrosion inhibitor dosing to optimize separation efficiency and reduce chemical spend. North Sea platforms integrate these control loops to minimize opex in high-water-cut mature fields.
- Flow Measurement:Multiphase metering applications combine water-cut with total flow rate to allocate production across commingled well streams. Permian Basin operators deploy these for reservoir management and royalty distribution.
- Leak Detection:Anomalous water-cut signatures indicate pipeline breaches or separator failures requiring immediate shutdown. Subsea gathering systems in the Gulf of Mexico specify these for environmental protection and asset integrity.
- Quality Control:Crude custody transfer and export specifications require verified water content below contractual thresholds. Nigerian and Angolan export terminals mandate redundant measurement for liftings to European refineries.
Flow Measurement holds installed capacity across production allocation networks. Leak Detection is expanding most quickly as environmental liability frameworks intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented sensor manufacturers in Germany and the United States supply calibration-traceable instruments to offshore operators in Brazil and Norway, while import dependency shapes procurement patterns in emerging deepwater markets lacking domestic metrology infrastructure.
United States
Gulf of Mexico producers deploy permanent-installation monitors to satisfy EPA effluent limitation guidelines for produced-water discharge verification. The Bureau of Safety and Environmental Enforcement mandates continuous monitoring for subsea tiebacks in federal waters. Houston anchors the largest calibration service cluster, with third-party providers supporting Permian Basin brownfield retrofits and offshore platform upgrades.
Norway
North Sea operators specify subsea-rated nuclear magnetic resonance systems to meet OSPAR zero-harmful-discharge obligations for produced-water reinjection. The Norwegian Environment Agency enforces real-time verification at injection headers under revised 2025 frameworks. Stavanger concentrates vendor engineering support and metrology traceability services for UK and Dutch sector clients.
Brazil
Pre-salt developments off Rio de Janeiro and Espírito Santo lack mature water-cut infrastructure, creating first-mover opportunities for integrated flow-measurement vendors. The National Petroleum Agency requires continuous monitoring for deepwater production allocation and environmental compliance. Local content regulations are accelerating partnerships between international sensor suppliers and domestic fabrication facilities.
United Kingdom
North Sea decommissioning timelines are extending field life in mature basins, driving replacement demand for corrosion-resistant monitor housings. The Environment Agency implements OSPAR-aligned discharge permits with mandatory API-traceable calibration chains. Aberdeen maintains specialized service capacity for platform-mounted installations and mobile well-testing units.
China
Offshore expansion in the South China Sea and Bohai Bay generates procurement for explosion-proof monitors compliant with GB standards and MEE environmental guidelines. State-owned producers prioritize digital integration with existing SCADA infrastructure. Shenzhen and Shanghai sensor manufacturers are developing microwave resonance capabilities to reduce import dependency for high-salinity applications.
Water Cut Monitor Market Vendor Landscape
Concentration sits with diversified industrial automation conglomerates and specialized oilfield service providers. The vendor base stratifies across three tiers: integrated automation platforms commanding permanent-installation contracts, pure-play sensor specialists competing on measurement precision, and regional fabricators serving mobile deployment markets. Strategic moves center on technology licensing for microwave miniaturization and performance-based service bundling that compresses equipment-only margins.
Among diversified automation conglomerates, Emerson Electric Co. and Schlumberger Limited occupy positions spanning hardware, software, and calibration services. Weatherford exemplifies the integrated oilfield service archetype, competing through bundled flow-measurement offerings that reduce wellsite instrumentation complexity. These three anchors represent distinct competitive vectors: automation platform depth, reservoir characterization expertise, and integrated service scalability.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Schlumberger Limited |
| Weatherford |
| AMETEK Inc. |
| TechnipFMC |
| Phase Dynamics |
| Agar Corporation |
| Sentech AS |
| ZelenTech |
| Others |
Supply Flow & Price Mechanics
Performance-based service contracts spanning hardware, calibration, and data interpretation lock in multi-year supply access and price visibility for North Sea and Gulf of Mexico operators facing OSPAR and EPA compliance deadlines. These bundled arrangements compress pure-play sensor margins while rewarding vendors with adjacent automation portfolios and recurring revenue streams.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate permanent-installation procurement. Three-tier pricing structure across premium, standard, and economy levels separates API-certified nuclear magnetic resonance systems from capacitance alternatives and portable ultrasonic rentals. Pricing pressure stems from national oil companies consolidating vendor relationships and demanding integrated service bundles. Mid-tier capacitance vendors serving Permian Basin brownfield retrofits exhibit highest price sensitivity, while deepwater operators prioritize measurement stability over unit cost.
Supply Chain Analysis
Port congestion at Houston and Rotterdam delays subsea-rated housing deliveries from German and US fabrication centers to North Sea and Brazilian offshore yards. Component supply concentrates in Germany, the United States, and China, with microwave resonance electronics and explosion-proof enclosures drawing from specialized industrial automation clusters. Single-source vulnerability sits with nuclear magnetic resonance magnet suppliers in Germany and the United States. Distribution runs through OEM-direct channels for permanent installations and rental fleet operators for mobile deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent sensor vendors face substitution pressure from integrated automation platforms bundling water-cut measurement into broader separator control systems, requiring defensive positioning around calibration service density and digital twin integration capabilities.
For Market Incumbents: Secure calibration service concentration in Houston, Aberdeen, and Stavanger to defend against third-party metrology entrants. Anchor permanent-installation contracts through embedded digital twin integration that raises switching costs for operators.
For New Entrants and Emerging Players: Anchor in Brazil pre-salt developments where mature water-cut infrastructure remains underbuilt and local content regulations favor partnership structures. Target mobile deployment markets in Texas and Alberta through rental fleet partnerships rather than direct OEM competition.
For Investors and Strategic Acquirers: Pure-play sensor specialists with NMR technology portfolios and established API calibration chains represent priority acquisition targets for automation conglomerates seeking offshore positioning. Watch microwave miniaturization patent filings as inflection indicator for technology substitution risk.
| Strategic Initiative | Industry Significance |
|---|---|
| Technology Licensing for Microwave Miniaturization | Enables brownfield retrofit penetration in Permian Basin without piping modifications. |
| Performance-Based Service Bundling | Aligns vendor incentives with Saudi Aramco and Petrobras cost-reduction targets. |
| Calibration Service Network Expansion | Reduces logistics bottlenecks for remote North Sea and Gulf of Mexico platforms. |
| Digital Twin Platform Integration | Combines real-time water-cut data with predictive separation models for automated control. |
| Subsea-Rated NMR System Development | Captures premium positioning in Norwegian sector zero-discharge reinjection applications. |
Methodological Framework
A standing panel of separator control engineers, calibration service technicians, offshore platform operations managers, and environmental compliance officers provided ongoing calibration against secondary data from EPA effluent limitation guidelines, OSPAR discharge reports, API calibration protocols, and Bureau of Safety and Environmental Enforcement monitoring mandates. Primary field interviews with procurement leads at supermajors and national oil companies combined with bottom-up equipment shipment tracking and top-down automation platform revenue analysis.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window. Segmentation dimensions modeled include technology type, deployment mode, end-user category, and application function. CAGRs were derived from equipment procurement trajectories and service contract renewal patterns, incorporating offshore field development timelines and regulatory compliance deadlines as industry-specific forecast inputs.
Material uncertainties — regulatory framework revisions, commodity price volatility affecting offshore capital allocation, and technology substitution rates for microwave versus capacitance sensing — sit outside the modeled envelope. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Smart Temporal Thermometer Market
Sensors and Controls
Asia-Pacific Nano Radiation Sensors Market
Sensors and Controls
Antenna Transducer and Radome Market
Sensors and Controls
Wind Speed Sensor Market
Sensors and Controls
Body Worn Temperature Sensors Market
Sensors and Controls
Global Level Sensors Market
Sensors and Controls
Voltage Sensor Market
Sensors and Controls
Asia-Pacific Water Detection Sensors Market
Sensors and Controls
Global Signal Conditioning Modules Market
Sensors and Controls
Asia-Pacific Digital Thermometer Market
Sensors and Controls
Biomedical Pressure Sensors Market
Sensors and Controls
Europe Smart Air Purifier Market
Sensors and Controls
High-Precision Confocal Sensor Market
Sensors and Controls
Safety Laser Scanner Market
Sensors and Controls
Thin Film Sensor Market
Sensors and Controls
Japan Sensor Market