
 Rigid Spray Polyurethane Foam Market | 2026-2036
Rigid Spray Polyurethane Foam Market Size, Share, and Industry Trends Forecast 2026-2036
Rigid Spray Polyurethane Foam Market Analysis
Asset-light leasing models for spray foam application rigs is fragmenting the contractor base, allowing smaller regional operators to challenge established incumbents without capital-intensive fleet ownership. BASF SE leverages its polyol chemistry expertise to sustain formulation leadership across North American construction markets. Huntsman Corporation anchors its position through backward integration into MDI production, controlling raw material cost volatility. Carlisle Companies Inc. competes by dominating the roofing application channel with specialized distribution partnerships.
Rigid spray polyurethane foam comprises a thermoset cellular plastic formed by reacting polymeric isocyanate with polyol blends, typically achieving closed-cell densities between 1.5 and 3.0 pounds per cubic foot and thermal resistance values of R-6 to R-7 per inch. The material creates monolithic, seamless insulation barriers that seal building envelopes against air infiltration and moisture intrusion. Closed-cell foam commands the largest share of product type revenue due to its superior structural rigidity and moisture resistance in below-grade and exterior applications. The automotive end user category represents the fastest-growing demand pool as electric vehicle manufacturers adopt spray foam for battery pack thermal management and lightweight cabin insulation.
The EPA enforces hydrofluorocarbon phase-down schedules under the AIM Act, compelling reformulation toward hydrofluoroolefin and hydrocarbon blowing agents that alter foam expansion ratios and installation protocols. OSHA maintains permissible exposure limits for methylene diphenyl diisocyanate and toluene diisocyanate vapors, shaping contractor training requirements and personal protective equipment standards across application sites. State-level energy codes in California and Massachusetts exceed federal baseline efficiency mandates, creating premium demand segments for high-performance spray foam systems. Stakeholders must monitor evolving blowing agent regulations and assess whether captive formulation capabilities or supplier partnerships offer superior compliance economics.
Market Dynamics
The EPA's phasedown of hydrofluorocarbon blowing agents under the AIM Act is forcing reformulation across the entire supply chain, redirecting R&D investment toward hydrofluoroolefin and hydrocarbon alternatives while altering installation protocols and contractor certification requirements.
Growth Catalysts
- California Title 24 Building Standards:Mandatory higher thermal performance standards in residential and commercial construction are accelerating specification of high-R-value spray foam systems in the United States.
- Cold chain logistics expansion:Temperature-controlled warehousing operators are adopting spray foam insulation for superior thermal envelope sealing and reduced energy consumption in refrigerated facilities.
- Electric vehicle thermal management:Automotive manufacturers are integrating spray foam for battery pack insulation and lightweight cabin applications, creating new demand pools outside traditional construction.
Market Restraints
- MDI price volatility:Methylene diphenyl diisocyanate feedstock costs fluctuate with crude oil and benzene derivatives, compressing formulation margins and destabilizing contractor pricing.
- Application equipment concentration:Specialized spray rig manufacturing concentrates in limited industrial clusters, creating supply bottlenecks during demand surges.
- Substitution by mineral wool:Fire-rated assemblies in commercial high-rises increasingly specify non-combustible insulation alternatives where code restricts foam plastic use.
Strategic Opportunities
- Retrofit residential envelope sealing:Existing housing stock in the United States presents substantial underpenetrated demand for attic and crawl space insulation upgrades driven by utility rebate programs.
- Low-GWP blowing agent convergence:Hydrofluoroolefin chemistry paired with advanced catalyst systems enables compliance with AIM Act schedules while maintaining foam performance.
- Asset-light rig leasing:Equipment rental platforms allow regional contractors to enter markets without capital-intensive fleet ownership, fragmenting incumbent dominance.
Industry Challenges
- Certified applicator shortage:OSHA-mandated training for methylene diphenyl diisocyanate and toluene diisocyanate exposure limits constrains workforce expansion and project throughput.
- Reformulation timeline compression:Blowing agent transition deadlines require simultaneous chemistry validation, equipment recalibration, and installer retraining across distributed contractor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rigid Spray Polyurethane Foam Market |
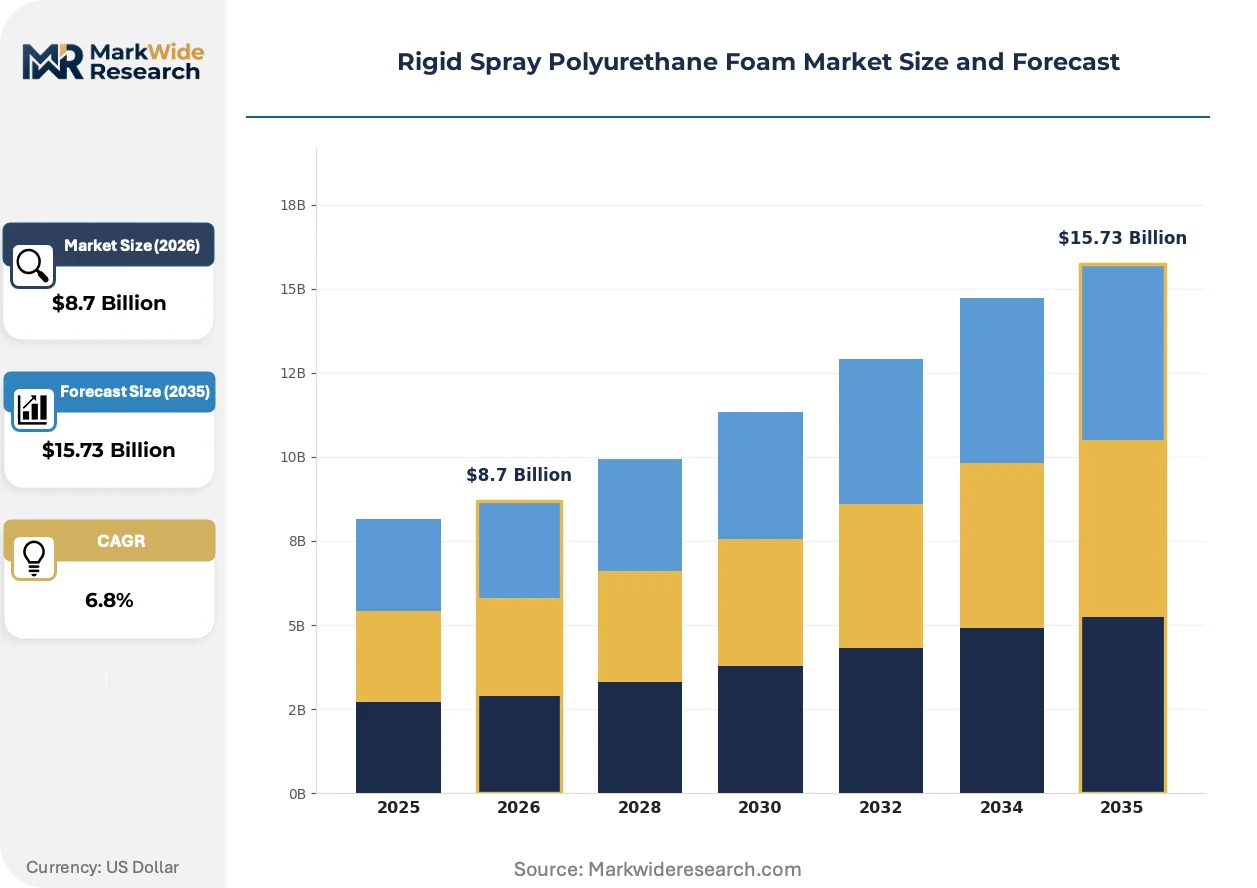
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Closed-Cell Foam, Open-Cell Foam, Hybrid Foam, High-Density Foam Application: Roofing, Insulation, Refrigeration, Construction End User: Residential, Commercial, Industrial, Automotive Distribution Channel: Online, Retail, Direct Sales, Wholesale |
| Companies Covered | Covestro AG, Armacell International S.A., BASF SE, Rogers Corporation, Sekisui Chemical Co., Ltd., Dow Inc., Recticel NV/SA, Carlisle Companies Inc., Huntsman Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rigid Spray Polyurethane Foam Market Emerging Trajectories
Formulation chemistry, regulatory compliance architecture, and contractor service models are undergoing simultaneous transformation as the industry navigates material phase-down mandates and end-use diversification.
Hydrofluoroolefin blowing agent technology is collapsing the performance gap between legacy hydrofluorocarbon systems and next-generation low-GWP alternatives. Electric vehicle manufacturers and cold chain operators are accelerating adoption of HFO-blown foam for thermal management applications. The transition is collapsing incumbent formulation advantages and redistributing competitive position toward suppliers with captive catalyst development capabilities.
The EPA's AIM Act enforcement schedule mandates staged reductions in hydrofluorocarbon consumption across aerosols, foams, and refrigeration sectors. Formulators must recalibrate expansion ratios, cell structure, and adhesion properties when substituting hydrofluoroolefin or hydrocarbon alternatives. Closed-cell roofing and below-grade applications in the United States face the most compressed compliance timelines, driving premium pricing for validated low-GWP systems.
Performance-based contractor selection is displacing relationship-driven procurement in commercial construction. General contractors and developers now specify third-party-certified installation quality metrics rather than brand loyalty. This shift concentrates volume with applicators carrying ISO 9001 quality management and manufacturer-authorized certification, most visible in California and New York commercial envelope projects where energy code enforcement is strictest.
Rigid Spray Polyurethane Foam Market Segmentation
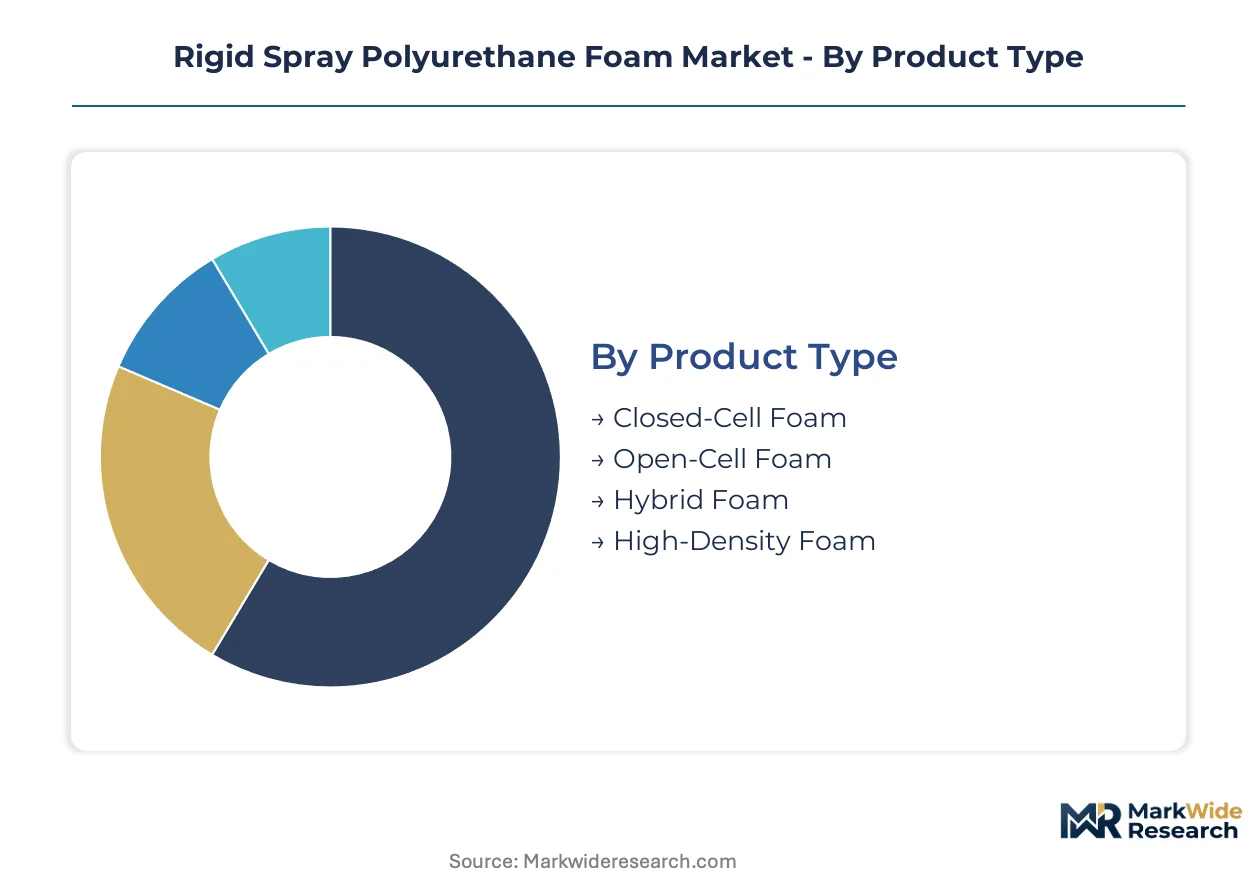
Spray polyurethane foam exhibits divergent performance profiles across density grades and cellular structures, driving specification patterns that vary sharply by building code requirements and end-use thermal demands. Segmentation clarity enables stakeholders to align formulation investments with the application channels where compliance economics and contractor certification requirements create the steepest barriers to entry.
Product Type:
The use-case spectrum spans structural load-bearing applications requiring compression resistance to flexible cavity-fill systems prioritizing acoustic dampening and cost efficiency.
- Closed-Cell Foam:Thermoset cellular plastic with densities between 1.5 and 3.0 pounds per cubic foot achieves R-6 to R-7 thermal resistance per inch while providing structural rigidity and moisture impermeability. Demand concentrates in below-grade and exterior envelope applications across California and New York commercial construction where energy codes mandate highest thermal performance standards.
- Open-Cell Foam:Lower-density cellular structure with permeable vapor transmission properties delivers superior acoustic absorption and reduced material cost per board foot. Residential attic and wall cavity applications in the United States favor this grade where moisture management relies on assembly design rather than material impermeability.
- Hybrid Foam:Combines layered closed-cell and open-cell chemistries to balance cost and performance in complex envelope assemblies.
- High-Density Foam:Exceeds 3.0 pounds per cubic foot for structural reinforcement and roofing traffic-bearing surfaces.
Established volume favors Closed-Cell Foam; emerging adoption favors Hybrid Foam as contractors seek installation efficiency across mixed-requirement projects.
Application:
Cost tier differentiation separates premium roofing systems with extended warranty requirements from commodity insulation fills competing on installed price per thermal unit.
- Roofing:Monolithic membrane systems achieve seamless waterproofing with integrated thermal resistance, specified for commercial flat roof retrofits where tear-off costs drive spray foam economics. Carlisle Companies dominates this channel through specialized distribution partnerships in the United States.
- Insulation:Envelope sealing for walls, attics, and crawl spaces represents the highest-volume application category driven by utility rebate programs and federal tax incentives for residential energy efficiency upgrades.
- Refrigeration:Cold chain logistics operators specify spray foam for temperature-controlled warehousing thermal envelopes.
- Construction:General building envelope applications span new commercial and residential ground-up development.
Margin concentration sits with Roofing; volume scale concentrates in Insulation as retrofit demand accelerates.
End User:
Customer type fragmentation separates specification authority between architect-driven commercial projects and contractor-influenced residential retrofits.
- Automotive:Electric vehicle manufacturers integrate spray foam for battery pack thermal management and lightweight cabin insulation. This segment is expanding most quickly as OEMs seek thermal runaway protection and acoustic refinement without weight penalties.
- Residential:Single-family and multifamily housing stock retrofits present substantial underpenetrated demand for attic and crawl space envelope sealing.
- Commercial:Office, retail, and institutional construction specifies spray foam for continuous insulation and air barrier compliance.
- Industrial:Manufacturing facilities and process equipment insulation requirements favor high-density and hybrid formulations.
Procurement sophistication separates Commercial from Residential; technology integration intensity distinguishes Automotive as the steepest expansion trajectory.
Distribution Channel:
Supply concentration varies from manufacturer-direct relationships with national applicator networks to fragmented retail availability serving DIY and small contractor segments.
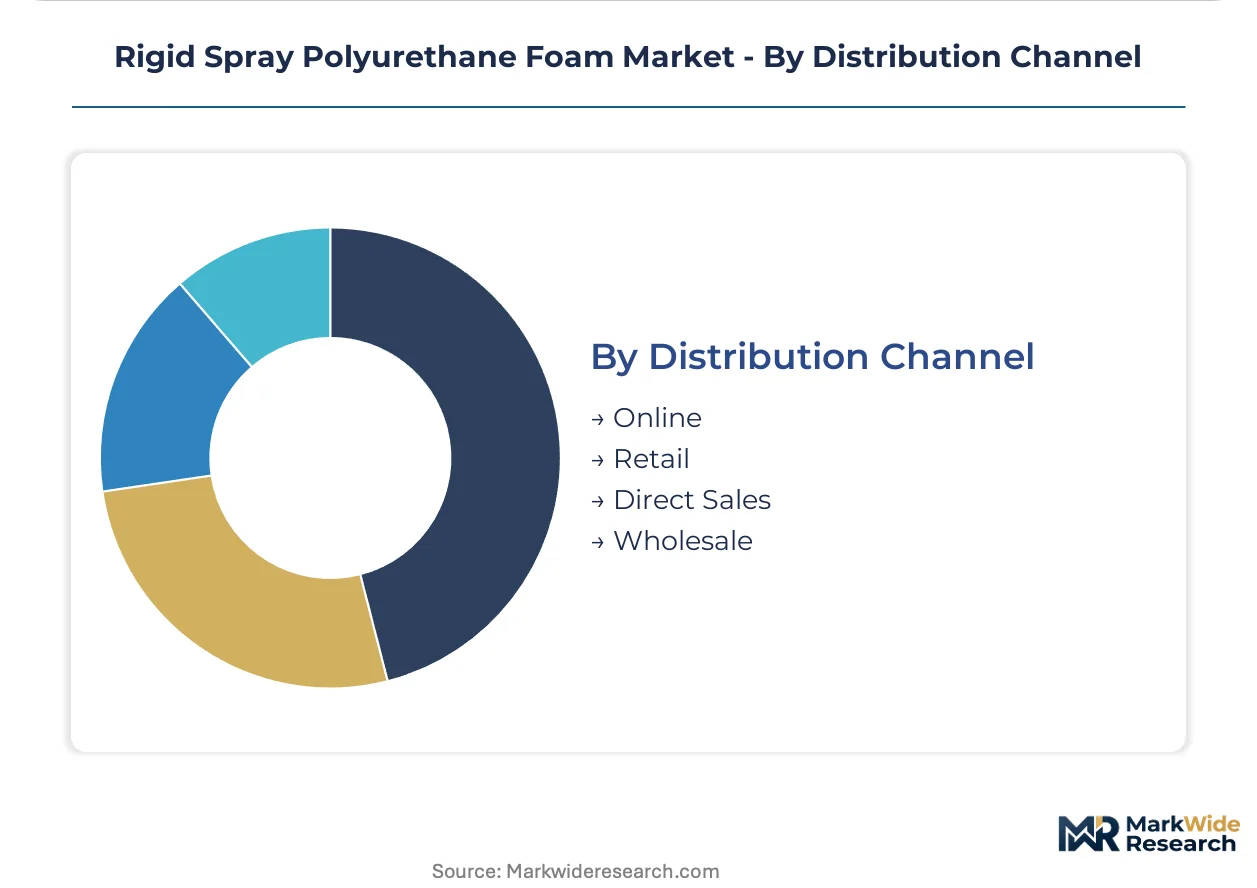
- Direct Sales:Formulators like BASF SE and Huntsman Corporation maintain direct contractor relationships for large commercial projects requiring technical service support and certified installation oversight.
- Wholesale:Regional distributors stock multiple manufacturer lines to serve contractor bases with equipment, chemicals, and training certification.
- Online:E-commerce platforms serve small residential contractors and advanced DIY segments with kit-based foam systems.
- Retail:Big-box home improvement channels carry limited portable foam systems for weatherization and repair applications.
Project scale and certification requirements concentrate volume with Direct Sales and Wholesale; Online and Retail serve price-sensitive segments with lower service intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cold chain logistics operators and electric vehicle manufacturers concentrate demand in markets with stringent energy efficiency mandates and advanced chemical manufacturing infrastructure. Regulatory phase-down schedules for high-global-warming-potential blowing agents are compressing reformulation timelines across major economies.
United States
California Title 24 Building Standards and New York State energy codes mandate R-6 to R-7 thermal resistance per inch in commercial envelope assemblies. The EPA enforces AIM Act hydrofluorocarbon phasedown schedules that redirect formulation strategies toward hydrofluoroolefin alternatives. Houston and the Gulf Coast chemical corridor host concentrated polyol and isocyanate production capacity serving North American construction markets.
Germany
Industrial refrigeration and passive house construction standards drive specification of high-performance spray foam systems in commercial building retrofits. The EU F-Gas Regulation mandates progressive hydrofluorocarbon quota reductions that accelerate transition to low-GWP blowing agent chemistries. The Rhine-Ruhr industrial region maintains integrated polyurethane precursor manufacturing clusters supplying formulation houses across Europe.
China
Electric vehicle battery pack thermal management and cold storage warehouse construction are expanding addressable demand beyond traditional building insulation. The Ministry of Ecology and Environment implements dual carbon goals that constrain high-carbon-footprint blowing agent utilization in domestic foam production. The Yangtze River Delta chemical manufacturing zone concentrates polyol and MDI capacity serving Asia-Pacific automotive and construction markets.
Japan
Automotive lightweighting requirements and precision electronics thermal management create specialized demand for high-density spray foam formulations. METI energy efficiency standards for commercial buildings exceed baseline international thermal performance requirements. The Chubu region around Nagoya anchors automotive supplier networks integrating spray foam into electric vehicle battery enclosures.
Canada
Arctic climate zone construction and indigenous community housing programs specify spray foam for extreme-temperature envelope performance. Natural Resources Canada administers energy efficiency incentive programs that subsidize residential retrofit insulation upgrades. Alberta's petrochemical processing corridor supplies blowing agent and polyol feedstocks to North American formulation operations.
Rigid Spray Polyurethane Foam Market Vendor Landscape
Channel-controlling players compete with product-specialist players across differentiated application segments. The market structure consolidates around integrated chemical conglomerates with captive polyol and isocyanate supply, mid-scale formulation specialists serving regional contractor networks, and roofing-system integrators dominating membrane-application channels. Strategic archetypes include backward-integrated raw material producers, certified-installation ecosystem orchestrators, and asset-light equipment-leasing platform operators. Dominant competitive moves center on blowing agent reformulation partnerships with catalyst developers and geographic expansion through distributor acquisition.
Within the integrated chemical tier, BASF SE and Huntsman Corporation exemplify archetypes defined by upstream control over polyurethane precursor supply chains. BASF SE represents the polyol chemistry leadership model sustaining formulation development across North American construction channels. Huntsman Corporation anchors the MDI production integration archetype that mitigates raw material cost volatility exposure. Carlisle Companies Inc. occupies the application-channel specialization position through roofing-system distribution partnerships in the United States. Covestro AG and Dow Inc. sit within the diversified materials science tier with cross-regional polyurethane system house operations.
| Leading Market Players |
|---|
| Covestro AG |
| Armacell International S.A. |
| BASF SE |
| Rogers Corporation |
| Sekisui Chemical Co., Ltd. |
| Dow Inc. |
| Recticel NV/SA |
| Carlisle Companies Inc. |
| Huntsman Corporation |
| Others |
Supply Flow & Price Mechanics
Gulf Coast polyol and isocyanate manufacturing clusters in the United States concentrate upstream supply, anchoring margin capture with formulators possessing captive precursor production while squeezing pure-play contractors exposed to MDI price volatility.
Pricing Analysis
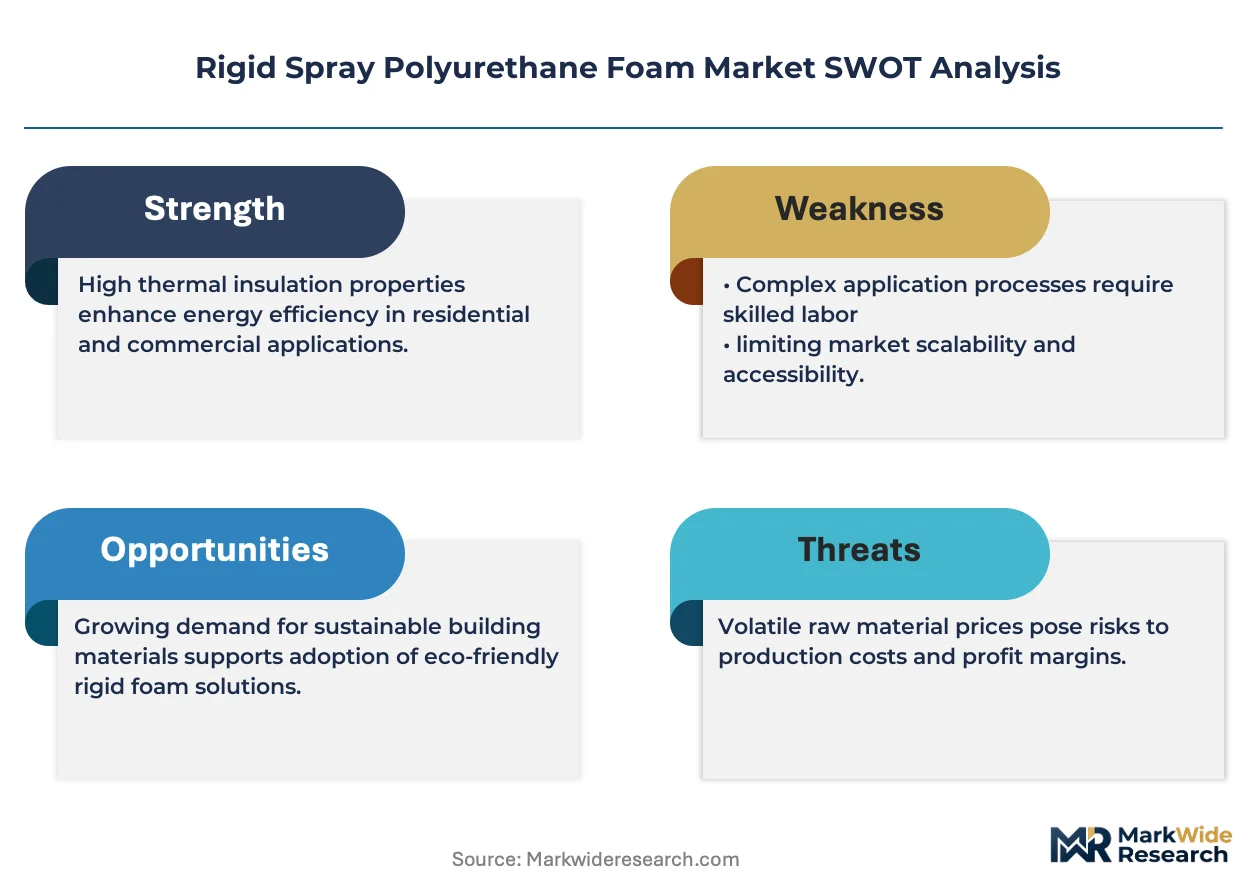
Certification level creates the primary spread between premium manufacturer-authorized applicators and economy-tier regional operators. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 9001 quality management credentials, OSHA-mandated installer certification status, and bundled technical service intensity. Pricing pressure stems from asset-light rig leasing platforms fragmenting contractor bases and compressing installation margins. Residential retrofit segments exhibit highest price sensitivity due to utility rebate program dependency, while cold chain logistics operators prioritize thermal performance over unit cost.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for catalyst and specialty additive sourcing. Raw material procurement draws from benzene derivative feedstocks concentrated in the Gulf Coast chemical corridor, polyol production anchored in Germany's Rhine-Ruhr industrial region, and MDI manufacturing clustered in China and the United States. Single-source vulnerability persists for hydrofluoroolefin blowing agent catalyst systems controlled by limited specialty chemical suppliers. Distribution runs through manufacturer-direct relationships with certified applicator networks for commercial projects, supplemented by wholesale distributors serving regional contractor bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Rigid Spray Polyurethane Foam Market represents a high-growth disruption as electric vehicle thermal management and cold chain logistics create demand pools outside traditional construction, compounded by EPA AIM Act reformulation mandates that collapse incumbent formulation advantages.
For Market Incumbents: Entrench position through backward integration into MDI production or captive polyol supply chains to mitigate benzene derivative cost volatility. Accelerate hydrofluoroolefin catalyst development partnerships to secure reformulation leadership before AIM Act compliance deadlines compress. Defend certified applicator network exclusivity against asset-light leasing platforms fragmenting contractor relationships. For New Entrants and Emerging Players: Establish a beachhead in electric vehicle battery pack thermal management applications where specification authority sits with automotive OEMs rather than incumbent construction channels. Target cold chain logistics operators expanding temperature-controlled warehousing capacity with HFO-blown foam systems validated for low-GWP compliance. Pursue equipment-leasing platform models to bypass capital-intensive fleet ownership barriers. For Investors and Strategic Acquirers: Capital is best deployed toward formulation specialists with captive catalyst development capabilities and validated AIM Act compliance trajectories over the medium-term horizon. Acquisition targets should demonstrate established manufacturer-authorized certification networks and direct contractor relationships insulated from wholesale distributor disintermediation. Monitor EPA enforcement schedule acceleration and state-level energy code adoption rates as inflection indicators for premium system demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into MDI Production | Huntsman Corporation's captive isocyanate supply mitigates raw material cost volatility exposure. |
| HFO Catalyst Development Partnership | BASF SE's polyol chemistry expertise accelerates low-GWP blowing agent validation timelines. |
| Certified Applicator Network Expansion | Carlisle Companies dominates roofing channels through specialized distribution partnerships. |
| Asset-Light Rig Leasing Platform | Equipment rental fragmentation enables regional contractors to challenge established incumbents. |
| Electric Vehicle Thermal Management Entry | Automotive OEM battery pack specifications create new demand pools outside construction. |
Methodological Framework
Cross-validation between primary interviews with spray foam contractors, chemical plant managers, and cold chain logistics operators anchors the qualitative findings, supplemented by secondary validation through EPA AIM Act regulatory filings, OSHA exposure limit documentation, and customs trade data for polyurethane precursor imports. Bottom-up triangulation across contractor installation volume estimates and top-down reconciliation with chemical producer capacity disclosures ensures segmentation accuracy.
Calibration against historical price elasticity patterns and regulatory compliance cost curves informs the analytical framework across the analysis window. Segmentation dimensions modeled include closed-cell versus open-cell density grades, roofing versus insulation application channels, and automotive versus residential end-user categories. CAGRs derive from installation volume trajectories, chemical feedstock cost projections, and energy code adoption diffusion curves.
Stress conditions across MDI price volatility bands, EPA enforcement acceleration scenarios, and electric vehicle adoption rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about reformulation timeline compliance and certified applicator workforce expansion that could shift with regulatory enforcement intensity or training program scaling. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Middle East and Africa Hydroxyl-Terminated Polybutadiene (HTPB) Market
Polymers & Resins
Soil Release Polymer Market
Polymers & Resins
Middle East and Africa Poly Vinyl Chloride (PVC) Market
Polymers & Resins
MDI, TDI, and Polyurethane Market
Polymers & Resins
Polymer Colloids Market
Polymers & Resins
Methyl Silicone Resins Market
Polymers & Resins
Global Anti-Vibration Polymer Market
Polymers & Resins
Europe Polycarbonate (PC) Market
Polymers & Resins
Global Polyalkylene Glycol (PAG) and Esters Market
Polymers & Resins
Asia-Pacific Polyamide Market
Polymers & Resins
Synthetic Polymer Waxes Market
Polymers & Resins
Polymer Binders Market
Polymers & Resins
Glycolide Polymers Market
Polymers & Resins
Global Polybutene Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Asia-Pacific Polyethylene Terephthalate (PET) Resin Market