
 Middle East Feed Additives Market | 2026-2036
Middle East Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Feed Additives Market Outlook
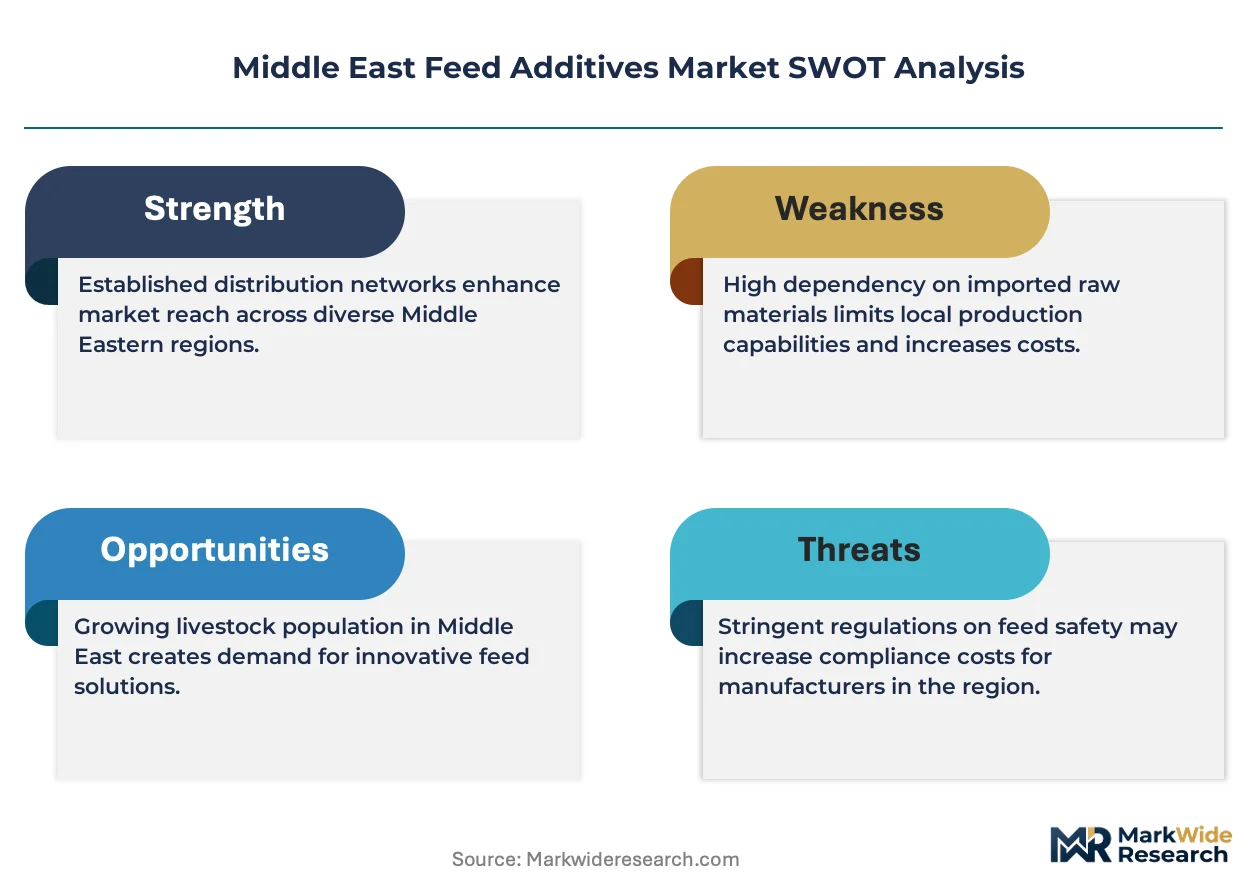
Saudi Arabia's industrial poultry capacity build-out is reshaping procurement patterns across the Middle East feed additives supply chain. Cargill leverages its Red Sea logistics network to dominate bulk vitamin and mineral distribution into the Kingdom. Alltech anchors its regional position through yeast-based additive formulations tailored to heat-stressed broiler flocks. BASF SE competes on synthetic antioxidant and carotenoid premixes for layer operations in the Gulf Cooperation Council states.
Feed additives comprise biologically active compounds, trace nutrients, and processing aids incorporated into compound feeds at inclusion rates typically ranging from 0.01% to 1.0% by weight to enhance animal performance, health, or feed efficiency. Their primary commercial purpose centers on optimizing nutrient utilization, mitigating metabolic stress, and extending feed shelf life in arid climates where heat degradation accelerates vitamin loss. Enzyme additives, particularly phytase and non-starch polysaccharide complexes, represent the fastest-growing product category as Saudi and Emirati integrators seek to reduce soybean meal import dependence. Poultry end users command the dominant share of additive value given the region's near-total reliance on imported genetic stock with exacting nutritional requirements.
Saudi Food and Drug Authority (SFDA) and Emirates Authority for Standardization and Metrology (ESMA) enforce divergent maximum residue limits and import certification requirements that fragment compliance costs across Gulf markets. The UAE's Ministry of Climate Change and Environment has tightened aquaculture feed additive registrations, creating new documentation burdens for enzyme and probiotic suppliers. Stakeholders must monitor harmonization negotiations between Gulf standardization bodies, as regulatory misalignment continues to dictate formulation strategies and country-specific product portfolios.
Market Dynamics
Saudi Arabia's industrial poultry build-out is compressing procurement cycles across the Middle East feed additives supply chain, forcing distributors to hold larger buffer stocks of heat-sensitive vitamins near Red Sea ports.
Growth Catalysts
- SFDA residue protocol harmonization:Saudi Food and Drug Authority alignment with Gulf Cooperation Council standards is reducing duplicate testing costs for premix importers serving the Kingdom's central Qassim dairy clusters.
- Phytase enzyme adoption:Saudi and Emirati integrators are deploying phytase complexes to cut soybean meal import volumes, creating additive pull-through in compound feed formulations.
- UAE aquaculture registration expansion:Emirates Authority for Standardization and Metrology streamlined enzyme and probiotic approvals for marine feed producers, opening new demand verticals beyond terrestrial livestock.
Market Restraints
- Vitamin E acetate price volatility:Synthetic antioxidant feedstock costs fluctuate with palm oil derivative markets, squeezing premix margin structures for layer operations.
- Red Sea logistics concentration:Cargill's dominance of Jeddah bulk vitamin terminals creates single-point vulnerability for Saudi integrators sourcing time-sensitive carotenoids.
- Heat degradation technical ceiling:Vitamin A and D3 stability losses exceed 15% during Jeddah-Riyadh inland transit in summer months, limiting formulation potency guarantees.
Strategic Opportunities
- Oman aquaculture underpenetration:Sultanate's nascent marine shrimp and finfish sectors lack established additive supply relationships, creating first-mover positioning for enzyme suppliers.
- SFDA digital traceability mandate:Saudi barcode serialization requirements for imported premixes favor suppliers with integrated ERP-to-customs data pipelines.
- Yeast-beta-glucan and probiotic convergence:Heat-stable immunomodulator combinations address broiler stress management in Saudi summer production cycles.
Industry Challenges
- Formulation chemist scarcity:Saudi universities produce insufficient feed science graduates to staff quality control labs at expanding Qassim poultry complexes.
- ESMA-SFDA certification timeline divergence:UAE and Saudi maximum residue limit misalignment forces dual registration costs for suppliers serving both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Feed Additives Market |
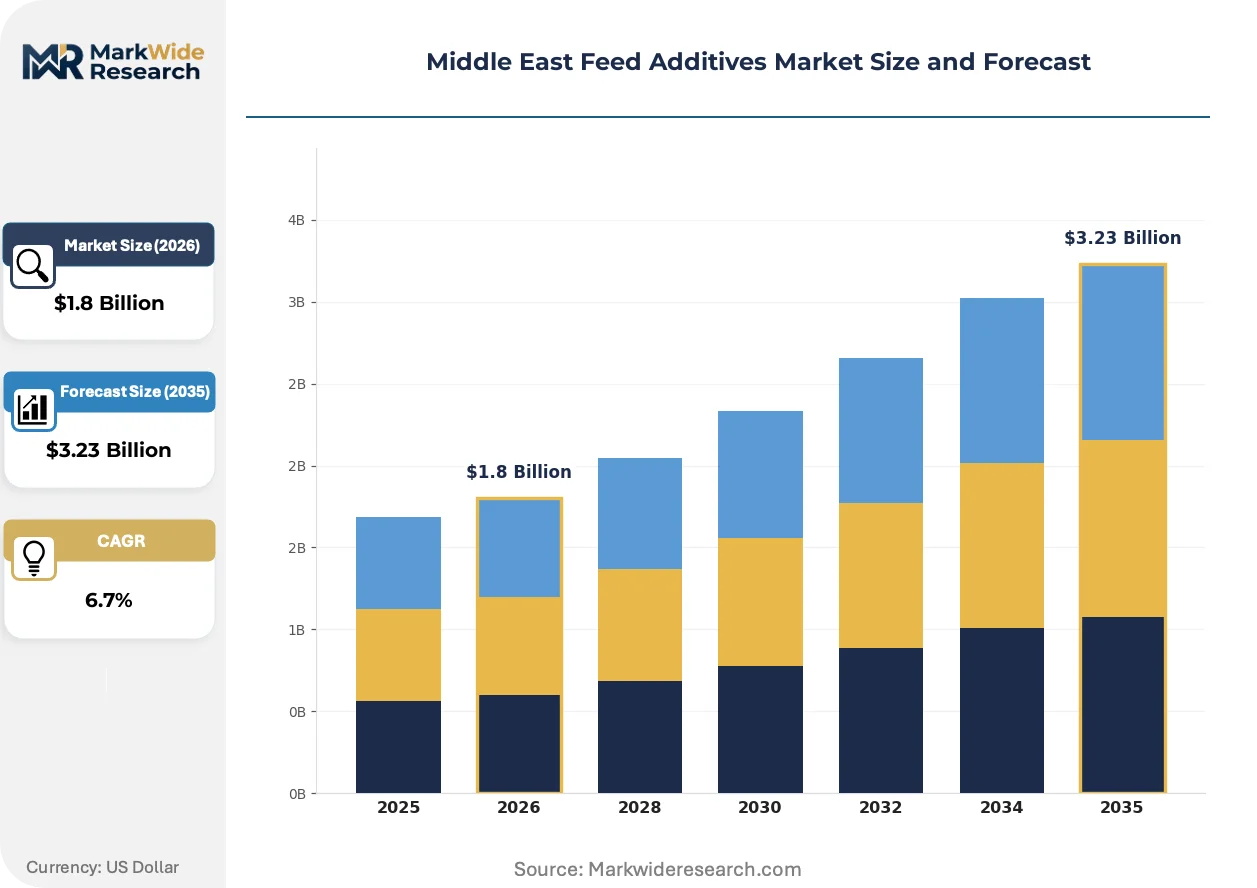
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antioxidants, Vitamins, Minerals, Enzymes End User: Poultry, Ruminants, Swine, Aquaculture Form: Liquid, Powder, Granular, Pelleted Technology: Fermentation, Extraction, Chemical Synthesis, Others |
| Companies Covered | Archer Daniels Midland, Alltech, Kemin Industries, Adisseo, Cargill, DSM Nutritional Products, BASF SE, Evonik Industries, Elanco Animal Health, Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Feed Additives Market Strategic Shifts
Heat-stability engineering and digital supply chain integration are displacing conventional additive handling protocols across Middle East feed operations, with regulatory data requirements accelerating faster than vendor adaptation.
Encapsulated fat-soluble vitamin technologies using lipid-matrix shielding are extending potency retention through Jeddah-Riyadh summer transit corridors. Saudi layer operations with exacting yolk color specifications are adopting these formats despite 12-18% unit cost premiums. Synthetic antioxidant premixes without encapsulation protection are rendering obsolete for high-value genetic stock operations.
UAE Ministry of Climate Change and Environment tightened aquaculture feed additive documentation requirements, extending registration timelines for enzyme and probiotic categories. Marine feed producers now face 8-14 month approval cycles versus 4-6 months for terrestrial livestock products. Probiotic suppliers are responding with dedicated aquaculture formulation subsidiaries to isolate regulatory risk.
Direct mill procurement from Jeddah port terminals is displacing traditional distributor intermediaries for Saudi integrators above 50,000 ton annual compound feed volumes. Large Qassim poultry operations now contract vitamin premixes on quarterly price formulas indexed to Red Sea freight benchmarks. This compression is most visible in Saudi Arabia's central region where feed mill consolidation has reduced active additive buyers by one-third since 2022.
Middle East Feed Additives Market Segmentation
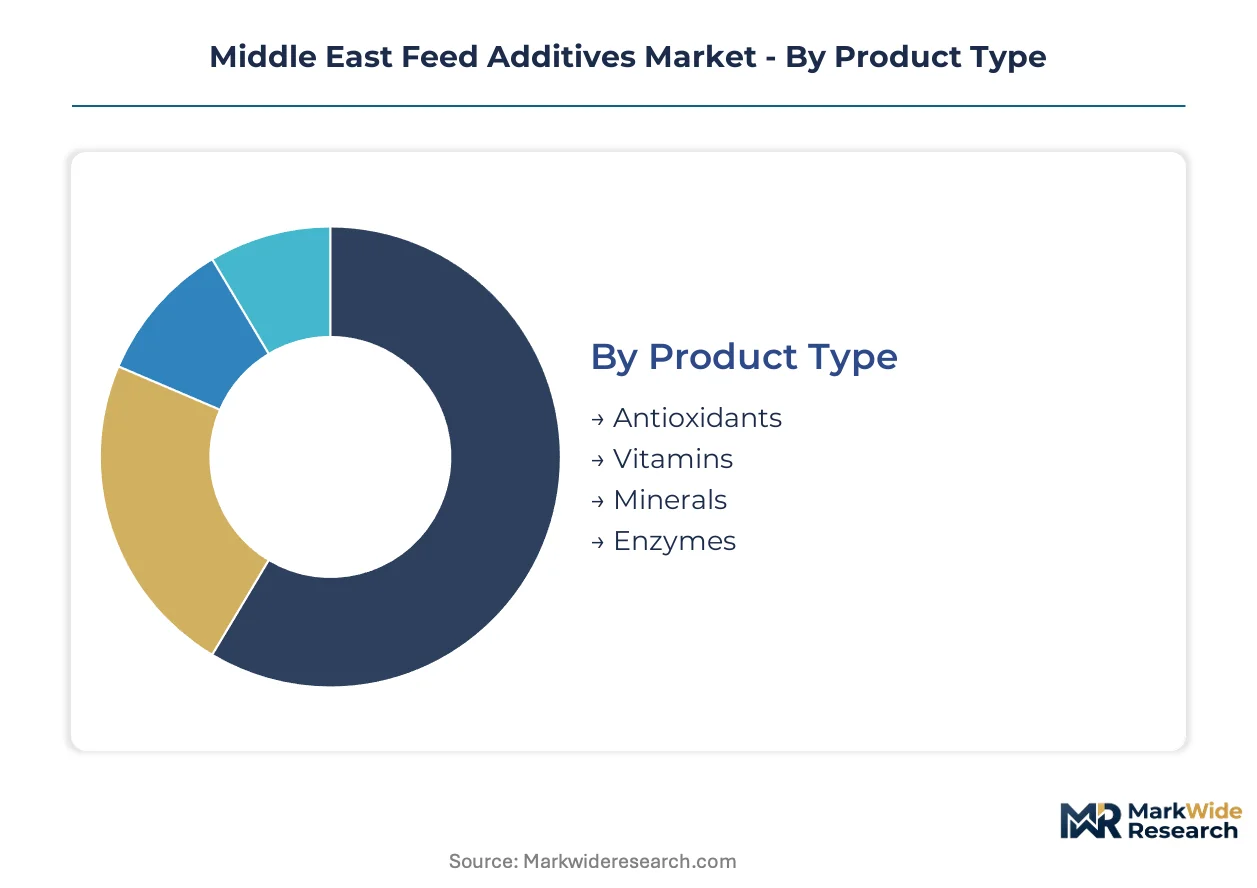
Feed additive procurement cycles vary dramatically across product categories, with enzymes and vitamins turning over monthly while mineral premixes stabilize on quarterly contracts. Understanding these velocity differentials helps suppliers align inventory positioning with Saudi integrator cash-flow patterns.
Product Type:
Enzyme formulations rotate through feed mills fastest due to batch-specific potency calibration, whereas mineral premixes maintain longer shelf stability in Jeddah port storage.
- Enzymes:Phytase and non-starch polysaccharide complexes accelerate nutrient release from regional grain sorghum and barley diets. Saudi Qassim poultry clusters consume the majority of phytase volumes as integrators seek soybean meal import reduction. Heat-stable liquid formulations are displacing powder variants in summer production cycles.
- Vitamins:Fat-soluble A, D, E, and K premixes require climate-controlled logistics through Red Sea corridors. Layer operations in Saudi Arabia's central region drive carotenoid demand for yolk color standardization. Encapsulated lipid-matrix formats command premium positioning despite higher unit costs.
- Antioxidants:Synthetic ethoxyquin and BHT variants preserve feed integrity in arid storage conditions.
- Minerals:Trace element premixes of copper, zinc, and selenium support metabolic function in heat-stressed flocks.
Mineral premixes dominate installed base tonnage. Enzyme formulations are where expansion concentrates.
End User:
Poultry integrators generate the highest additive consumption velocity per animal unit, while aquaculture operations stretch procurement across longer grow-out cycles.
- Poultry:Broiler and layer operations across Saudi Arabia and the UAE account for the majority of phytase and vitamin premix demand. Genetic stock imported from European and North American suppliers imposes exacting nutritional specifications. Feed conversion ratio optimization drives continuous formulation refinement.
- Aquaculture:Marine shrimp and finfish producers in the UAE and Oman are accelerating enzyme and probiotic adoption. Emirates Authority for Standardization and Metrology registration timelines extend 8-14 months for aquatic versus 4-6 months for terrestrial applications. Dedicated aquaculture formulation subsidiaries are emerging to isolate regulatory risk.
- Ruminants:Saudi dairy clusters in Qassim region utilize buffer additives and yeast cultures for rumen pH management.
- Swine:Limited regional production confines demand to niche research and breeding operations.
Poultry commands current volume leadership. Aquaculture is climbing the fastest as marine protein production scales.
Form:
Liquid additives integrate directly into feed mill slurry systems with minimal handling, while pelleted formats require dedicated pelleting lines that constrain adoption to larger facilities.
- Liquid:Heat-stable enzyme suspensions and vitamin emulsions flow directly into Saudi feed mill mixing systems. Qassim poultry complexes favor liquid phytase for dosing precision and reduced dust exposure. Red Sea port terminals maintain dedicated liquid storage to preserve potency through summer transit.
- Powder:Traditional vitamin and mineral premixes remain prevalent in smaller Emirati feed operations with limited liquid infrastructure. Powder formats face 15% stability loss during Jeddah-Riyadh inland transport in peak heat months.
- Granular:Intermediate particle size reduces segregation in mixed feed rations.
- Pelleted:Coated additive formats protect active ingredients through pelleting thermal stress.
Powder maintains broadest installed base penetration. Liquid formats are gaining share fastest as mill automation advances.
Technology:
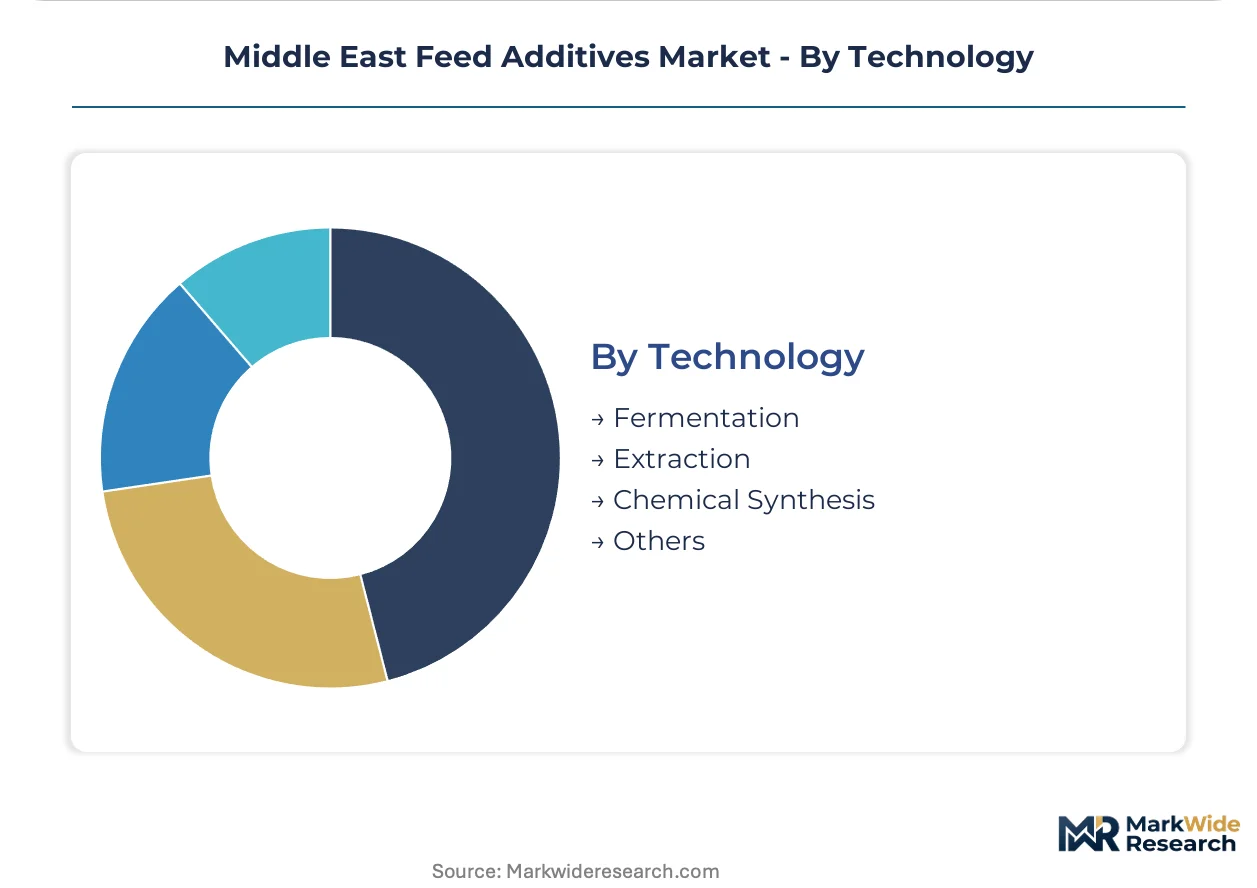
Fermentation-derived additives command extended production lead times, while chemical synthesis enables rapid scale-up for commodity antioxidant demand.
- Fermentation:Yeast-derived beta-glucans and bacterial probiotics require 3-6 week production cycles with strict temperature control. Alltech anchors regional supply through dedicated fermentation capacity serving heat-stressed broiler operations. Immunomodulator combinations are expanding in Saudi summer production protocols.
- Chemical Synthesis:Synthetic antioxidants and fat-soluble vitamins scale rapidly to meet layer operation demand spikes. BASF SE leverages European synthesis capacity for carotenoid premix supply into Gulf Cooperation Council states. Price volatility in palm oil derivatives squeezes margin structures for ethoxyquin producers.
- Extraction:Plant-derived tocopherols and botanical additives serve niche organic feed certifications.
- Others:Encapsulation and micro-encapsulation technologies extend shelf stability for premium genetic stock operations.
Chemical synthesis dominates current production volume. Fermentation platforms are expanding most quickly as functional feed additives displace antibiotic growth promoters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Red Sea port infrastructure concentrates additive import flows through Jeddah and Dubai terminals. Saudi Arabia and the UAE absorb the majority of regional vitamin and enzyme volumes. Regulatory divergence between Gulf standardization bodies fragments supplier compliance strategies.
Saudi Arabia
Industrial poultry complexes in Qassim region drive phytase and vitamin premix consumption. SFDA residue protocol harmonization with GCC standards reduces duplicate testing costs for importers. Jeddah-Riyadh inland corridors experience 15% vitamin stability loss during summer transit.
United Arab Emirates
Aquaculture operations in Abu Dhabi and Dubai accelerate enzyme and probiotic adoption for marine feed. ESMA streamlined aquatic additive registrations but extended timelines to 8-14 months versus terrestrial categories. Dubai's logistics free zones attract premix distributors serving re-export markets.
Oman
Nascent shrimp and finfish sectors lack established additive supply relationships, creating positioning opportunities. The country's national food security initiatives prioritize marine protein production scaling. Salalah port infrastructure supports direct enzyme import for coastal aquaculture facilities.
Qatar
Dairy self-sufficiency targets under the national food security strategy expand buffer additive demand. The country's central veterinary laboratory enforces import certification parallel to SFDA protocols. Al Khor agricultural zone concentrates ruminant feed operations requiring yeast culture supplements.
Kuwait
Poultry import substitution policies stimulate domestic broiler capacity expansion. The Public Authority for Food and Nutrition monitors premix residue limits aligned with GCC harmonization efforts. Wafra agricultural area hosts integrated operations sourcing heat-stable vitamin formulations.
Middle East Feed Additives Market Competitive Environment
Multinational nutrition conglomerates and specialized fermentation houses split the market between bulk commodity supply and functional additive innovation. Cargill's Jeddah terminal dominance creates scale advantages in vitamin distribution. Three archetypes define competitive positioning: Red Sea logistics-integrated distributors, heat-stability technology specialists, and aquaculture-dedicated formulation subsidiaries. Capacity expansion and regulatory compliance automation constitute the dominant competitive moves.
Within the logistics-integrated tier, Cargill and BASF SE occupy positions shaped by port infrastructure control and synthesis capacity respectively. Alltech exemplifies the fermentation-specialist archetype through yeast-derived platform positioning. These three anchors illustrate how geographic concentration and production technology divergence create defensible market positions.
| Leading Market Players |
|---|
| Archer Daniels Midland |
| Alltech |
| Kemin Industries |
| Adisseo |
| Cargill |
| DSM Nutritional Products |
| BASF SE |
| Evonik Industries |
| Elanco Animal Health |
| Others |
Value Chain & Pricing Dynamics
Jeddah-Riyadh inland freight corridors transmit Red Sea port cost volatility directly into Saudi integrator procurement budgets, concentrating pricing power among terminal-controlling distributors while fragmenting downstream negotiation leverage for smaller Qassim feed mills.
Pricing Analysis
SFDA barcode serialization mandates dictate the pricing tier structure across imported premix categories. Three-tier pricing structure across premium encapsulated vitamins, standard powder formats, and economy synthetic antioxidants separates heat-stable formulations from commodity alternatives. Cost compression in standard vitamin tiers is intensifying because Jeddah-Riyadh summer transit degradation forces potency overage purchases. Large Qassim poultry integrators above 50,000 ton annual volumes exhibit lowest price sensitivity due to direct port contracting, while smaller Emirati feed operations face acute margin pressure from liquid infrastructure deficits.
Supply Chain Analysis
Cargill's Jeddah bulk vitamin terminal dominance anchors European and North American synthesis capacity serving Gulf markets. Manufacturing concentrates in Germany, Netherlands, and Belgium for carotenoid and antioxidant premixes, with fermentation-derived enzymes sourcing from dedicated Irish and Brazilian facilities. Raw material flows draw from Malaysian palm oil derivatives, Chinese vitamin intermediates, and Indian trace mineral ores. Single-source vulnerability runs through Cargill's Red Sea logistics control for time-sensitive carotenoid distribution. Distribution runs through quarterly price-indexed contracts for large integrators and traditional distributor intermediaries for sub-scale buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feed mill consolidation across Saudi Arabia's Qassim region has reduced active additive buyers by one-third since 2022, shifting procurement leverage toward volume-committed integrators and compressing margin capture for undifferentiated suppliers.
For Market Incumbents: Insulate terminal-controlled distribution networks by securing dedicated liquid storage capacity at Jeddah and Dubai free zones before competitor port access expansion. Lock in multi-year synthesis supply agreements with European carotenoid producers to preempt raw material cost pass-through volatility. Prioritize ERP-to-customs data pipeline certification to capture SFDA digital traceability mandate premiums. For New Entrants and Emerging Players: Oman's nascent aquaculture sectors and Kuwait's poultry import substitution zones represent the most penetrable entry points for enzyme and probiotic specialists lacking established Gulf relationships. Target marine feed producers in Salalah coastal facilities with dedicated aquaculture formulation subsidiaries that isolate ESMA-SFDA regulatory divergence risks. Lead with heat-stable liquid enzyme demonstrations during Saudi summer production cycles to bypass powder format incumbency. For Investors and Strategic Acquirers: Fermentation-platform specialists with captive yeast-derived beta-glucan capacity and integrated heat-stability engineering capabilities command the strongest long-term positioning as antibiotic growth promoter displacement accelerates. Monitor harmonization negotiations between Gulf standardization bodies as the critical inflection signal—regulatory convergence would collapse dual-registration cost barriers and trigger consolidation among country-specific formulation subsidiaries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Synthesis Capacity | Captive antioxidant production insulates BASF and DSM from palm oil derivative volatility. |
| Heat-Stability Engineering Investment | Encapsulated lipid-matrix formats command 12-18% premiums from Saudi layer operations. |
| Aquaculture Formulation Subsidiary Launch | Dedicated marine units isolate ESMA's 8-14 month registration timeline risks. |
| ERP-to-Customs Pipeline Certification | SFDA digital traceability mandates favor suppliers with integrated data infrastructure. |
| Direct Port Terminal Procurement Contracting | Quarterly price formulas indexed to Red Sea freight benchmarks displace distributor markups. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with feed mill procurement directors, SFDA regulatory compliance officers, and aquaculture facility managers across Saudi Arabia, UAE, and Oman; and secondary validation through customs import records, Gulf Cooperation Council standardization body filings, and European synthesis capacity disclosures. Bottom-up triangulation against top-down regional feed production estimates anchored volume projections.
Forecast inputs span enzyme, vitamin, antioxidant, and mineral premix categories across poultry, aquaculture, and ruminant end uses, with form factors and production technology dimensions layered throughout the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macro feed production trajectories. Heat degradation loss coefficients and regulatory timeline differentials between terrestrial and aquatic applications shaped scenario boundaries.
Stress conditions across Red Sea freight rate volatility, vitamin E acetate feedstock price swings, and SFDA-ESMA harmonization failure were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about Qassim poultry capacity expansion and UAE marine protein scaling. Quarterly review of GCC standardization body negotiation progress and Jeddah port infrastructure investment announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Chelated Trace Minerals Market
Additives
Global Isosorbide Market
Additives
Chemical Silage Additives Market
Additives
North America Citric Acid Market
Additives
Grinding Aids Market
Additives
Asia Pacific Plastic Additives Market
Additives
Drilling Fluid Additives Market
Additives
Micronized Powder Market
Additives
Carboxymethyl Cellulose Market
Additives
Tragacanth Market
Additives
Hydrogen Peroxide Chemical Indicator Market
Additives
Organic Dispersants Market
Additives
Mycotoxin Binders Market
Additives
Anti Crystallizing Agents Market
Additives
Metallic Stearate Market
Additives
Global Matting Agents Market