
 Saudi Arabia Feed Additives Market | 2026-2036
Saudi Arabia Feed Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Feed Additives Market Analytics
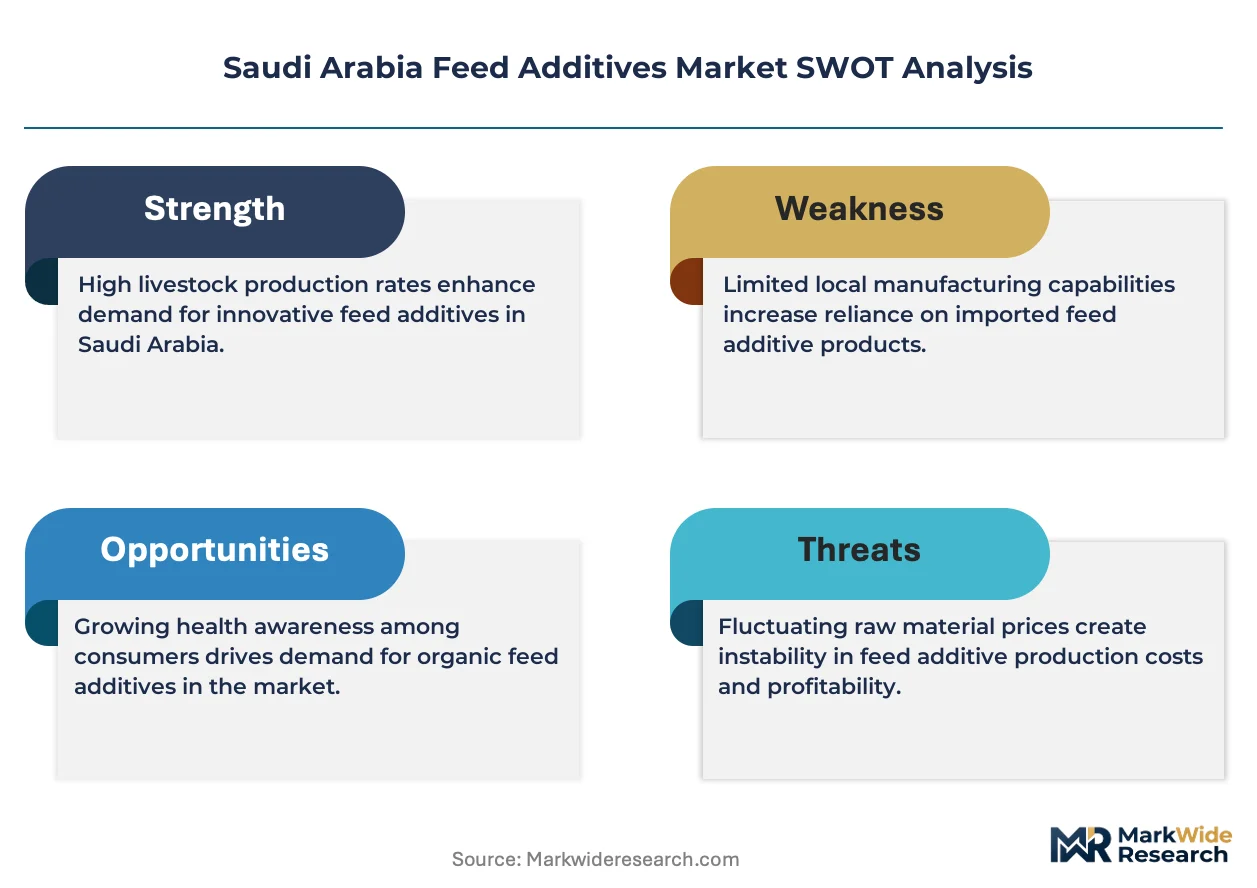
Phytase-enhanced additive tiers is unwinding legacy commodity positioning across Saudi Arabia's feed sector. Alltech Inc leverages its yeast fermentation platform to dominate enzyme additive supply to independent mills. Arasco Feed and Food Company Ltd anchors domestic production through backward integration into premix manufacturing at its Al-Kharj complex. Cargill Incorporated competes via direct technical service teams embedded with large dairy cooperatives in the central region.
Feed additives comprise biologically active compounds including enzymes, organic acids, amino acids, and probiotic cultures formulated at precise inclusion rates, typically between 0.01% and 1.0% of total ration weight, to enhance nutrient digestibility, preserve feed quality, or support animal metabolic function. Nutritional feed additives, particularly lysine and methionine formulations, command the deepest margin pools due to volume scale and technical formulation complexity. Acidifiers represent the fastest-growing product category as Saudi poultry producers phase out antibiotic growth promoters under tightening residue monitoring protocols. Poultry applications absorb the largest share of value, though aquaculture additives are gaining traction among Red Sea coastal operations targeting export certification standards.
SFDA implements feed ingredient registration and import inspection regimes that determine market access timelines for foreign suppliers. The Saudi Standards, Metrology and Quality Organization (SASO) governs labeling and contaminant thresholds for domestically blended products. Stakeholders must monitor evolving halal certification requirements for microbial fermentation-derived additives, as religious compliance increasingly intersects with technical product registration pathways.
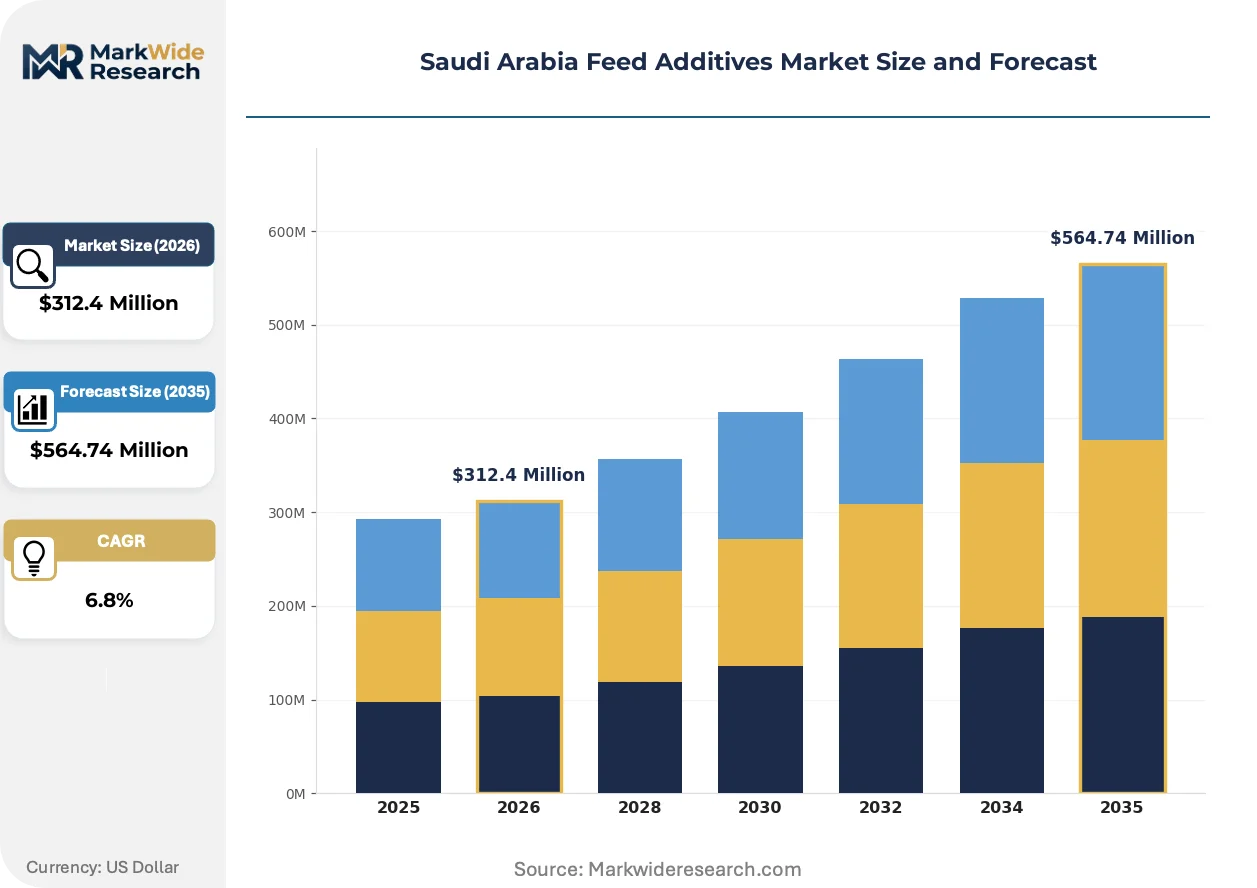
Market Dynamics
SFDA's phased tightening of mycotoxin binding specifications for imported premixes is compressing supplier qualification timelines and forcing reformulation investments across Saudi Arabia's feed additive supply base.
Growth Catalysts
- Antibiotic growth promoter phase-out:Poultry integrators in the Eastern Province are accelerating acidifier adoption to maintain feed conversion ratios under SFDA residue surveillance protocols.
- Amino acid premix localization:Riyadh-based captive feed mills are expanding lysine and methionine blending capacity to reduce import dependency and customs clearance delays.
- Red Sea aquaculture export certification:Coastal shrimp and finfish operations are procuring enzyme-enhanced additives to meet EU and Gulf state veterinary residue standards.
Market Restraints
- Import concentration risk:Over 70 percent of vitamin and trace mineral premixes originate from Chinese and European suppliers, exposing mills to shipping rate volatility and port congestion at Jeddah Islamic Port.
- Halal certification friction:Microbial fermentation-derived additives face extended review timelines by Saudi religious authorities, delaying product registration by 8-14 months versus chemically synthesized alternatives.
- Water-energy cost structure:Desert climate feed production requires intensive cooling and groundwater desalination, elevating operational expenditures for domestic additive compounders versus regional competitors.
Strategic Opportunities
- Al-Kharj corridor expansion:Arasco's backward integration model offers template for independent mills to establish captive premix facilities within 100 kilometers of Riyadh's dairy cooperative clusters.
- Phytase-enzyme convergence:Next-generation thermostable phytase variants combined with organic acid coatings enable pelleting temperature tolerance above 85 degrees Celsius, opening contract manufacturing relationships with extruded feed specialists.
- E-commerce technical service channels:Direct-to-mill digital platforms with embedded formulation calculators are penetrating smaller independent poultry operations previously served by distributor networks.
Industry Challenges
- Specialized nutritionist talent scarcity:Formulation expertise combining rumen microbiology and precision premix dosing remains concentrated among Saudi nationals with international veterinary training, constraining mill technical service expansion.
- SFDA-SASO dual registration complexity:Additive suppliers must navigate parallel approval pathways for ingredient safety validation and finished product labeling compliance, extending time-to-revenue by four to six quarters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Feed Additives Market |
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein Supplements, Acidifiers, Antioxidants, Nutritional Feed Additives Application: Poultry, Ruminants, Swine, Aquaculture End User: Farmers, Feed Manufacturers, Veterinary Clinics, Livestock Producers Distribution Channel: Online Sales, Retail Outlets, Wholesalers, Distributors |
| Companies Covered | Saudi Mix Feed Additives Company, Alltech Inc, United Feed Company, Cargill Incorporated, Arasco Feed and Food Company Ltd, Brenntag SE, Al-Watania Poultry, Evonik Industries AG, Al-Akhawai, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Feed Additives Market Evolving Landscape
Precision dosing technologies and regulatory compliance automation are compressing the gap between commodity additive supply and differentiated nutritional service models across Saudi feed operations.
Encapsulated organic acid blends with targeted release profiles are miniaturizing the effective inclusion window for gut health management in broiler rations. Eastern Province integrators are deploying these micro-encapsulated formulations at 0.3-0.5 percent inclusion rates versus legacy acidifier levels above 1.0 percent. This compression is enabling cost-neutral substitution of antibiotic growth promoters while maintaining intestinal pH modulation.
SFDA's 2024 implementation of blockchain-tracked import certificates for mycotoxin binders is tightening traceability requirements across the supply chain. Foreign suppliers must now submit batch-level chromatography data prior to port clearance, extending documentation lead times but reducing post-import rejection rates. Independent mills in the central region are prioritizing suppliers with pre-registered SFDA dossiers to avoid feed formulation delays.
Consolidated procurement committees at Riyadh-based dairy cooperatives are displacing individual mill purchasing autonomy with centralized amino acid tendering. These cooperative buying pools aggregate annual lysine and methionine volumes exceeding 15,000 metric tons, extracting volume-tier pricing previously available only to vertically integrated poultry operators. Smaller independent feed manufacturers in Asir and Jazan provinces face margin compression as they remain excluded from these purchasing collectives.
Saudi Arabia Feed Additives Market Segmentation
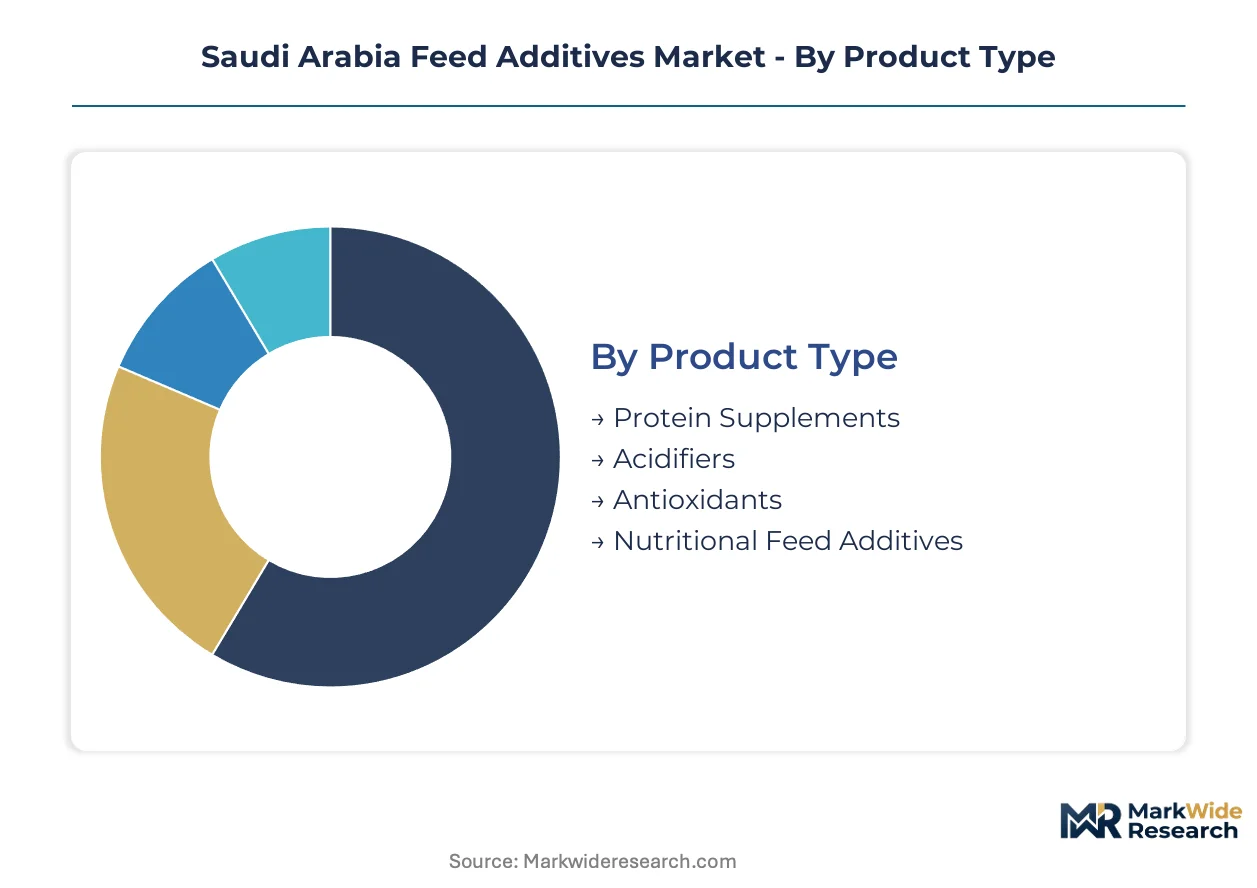
Feed additive purchasing patterns in Saudi Arabia diverge sharply across customer types and distribution pathways, with regulatory compliance requirements and captive milling capacity creating distinct demand clusters that reshape competitive positioning.
Product Type:
Acidifiers face the most intense substitution pressure as encapsulated organic acid blends displace legacy mineral acid formulations under SFDA residue monitoring protocols.
- Acidifiers:Encapsulated organic acid blends with targeted release profiles enable pelleting temperature tolerance above 85 degrees Celsius. Eastern Province poultry integrators deploy these formulations at 0.3-0.5 percent inclusion rates versus legacy levels above 1.0 percent, maintaining intestinal pH modulation while eliminating antibiotic growth promoters.
- Nutritional Feed Additives:Lysine and methionine formulations command premium positioning due to technical formulation complexity and volume scale. Riyadh-based captive feed mills are expanding blending capacity to reduce import dependency and customs clearance delays at Jeddah Islamic Port.
- Protein Supplements:Soy-based and alternative protein concentrates support amino acid balancing in ruminant rations across central region dairy cooperatives.
- Antioxidants:Ethoxyquin and BHT variants preserve fat-soluble vitamin stability in premixes subjected to desert climate storage conditions.
Nutritional feed additives anchor the volume base while acidifiers gain share at the steepest rate.
Application:
Margin structures across livestock categories correlate directly with export certification requirements and integration depth of end-users.
- Poultry:Broiler and layer operations absorb the largest value share, with commercial integrators in the Eastern Province driving demand for phytase-enhanced enzyme tiers and acidifier substitution protocols.
- Aquaculture:Red Sea coastal shrimp and finfish operations procure enzyme-enhanced additives to meet EU and Gulf state veterinary residue standards, representing the most rapidly expanding application trajectory.
- Ruminants:Dairy cooperatives in the Riyadh corridor concentrate demand for rumen-protected amino acids and mycotoxin binding agents under stricter SFDA feed safety protocols.
- Swine:Limited domestic production restricts segment scale, with specialty additives serving niche research and limited commercial operations.
Poultry anchors the volume base while aquaculture climbs the fastest on export certification tailwinds.
End User:
Procurement autonomy concentrates among integrated operators with captive formulation capabilities, fragmenting across independent purchasers.
- Feed Manufacturers:Independent mills in Asir and Jazan provinces face margin compression as consolidated procurement committees at Riyadh-based dairy cooperatives displace individual purchasing autonomy with centralized amino acid tendering.
- Livestock Producers:Vertically integrated poultry operators in the Eastern Province maintain direct supplier relationships with enzyme and acidifier specialists, bypassing distributor markups.
- Farmers:Smaller independent poultry operations increasingly access technical service through direct-to-mill digital platforms with embedded formulation calculators.
- Veterinary Clinics:Specialty probiotic and therapeutic additive recommendations flow through clinical channels serving high-value dairy and breeding stock operations.
Feed manufacturers anchor the volume base while livestock producers expand most quickly through backward integration.
Distribution Channel:
Channel selection tracks directly with customer scale and technical service requirements, compressing traditional intermediary roles.
- Distributors:Technical service teams embedded with large dairy cooperatives in the central region maintain dominant positioning for amino acid and premix supply.
- Online Sales:E-commerce technical service channels penetrate smaller independent poultry operations previously served exclusively by distributor networks.
- Wholesalers:Bulk vitamin and trace mineral premixes flow through wholesale channels serving compound feed mills with established SFDA registration dossiers.
- Retail Outlets:Specialty additives for smaller livestock operations and hobby farming segments reach end-users through agricultural supply retailers.
Distributors anchor the volume base while online sales expand most quickly on digital platform penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Saudi Arabia's feed additive landscape. Riyadh-based integrated livestock producers with captive milling capacity show minimal price sensitivity for amino acid premixes. Smaller independent mills in Asir and Jazan provinces face acute margin compression from centralized cooperative procurement.
Riyadh
Dairy cooperatives in the Riyadh corridor concentrate demand for rumen-protected amino acids and mycotoxin binding agents. SFDA feed safety protocols mandate stricter standards for imported premixes entering this central hub. Captive feed mills at Al-Kharj complex anchor domestic lysine and methionine blending capacity expansion.
Eastern Province
Commercial poultry operations drive acidifier substitution protocols as antibiotic growth promoters phase out under residue surveillance. Dammam-based integrators deploy phytase-enhanced enzyme tiers at commercial scale. SFDA's blockchain-tracked import certificates for mycotoxin binders tighten traceability requirements across port entries.
Western Region
Jeddah Islamic Port handles over 70 percent of vitamin and trace mineral premix imports, exposing mills to shipping volatility and congestion delays. Red Sea coastal aquaculture operations procure enzyme-enhanced additives for EU export certification. Makkah and Madinah livestock clusters rely on distributor networks for smaller-volume specialty additive procurement.
NEOM Northwest
Emerging agricultural zones in the northwest corridor attract greenfield feed milling investment aligned with food security mandates. Water-energy cost structures challenge domestic compounders versus regional competitors due to intensive cooling and desalination requirements. Regulatory sandbox frameworks for halal-certified microbial fermentation additives face extended review timelines.
Saudi Arabia Feed Additives Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Saudi Arabia's feed additive sector. Consolidated supply relationships dominate amino acid and enzyme categories, while fragmented procurement persists among independent mills. Three archetypes define competitive positioning: multinational fermentation technology specialists, regionally integrated feed-to-farm operators, and chemical distribution intermediaries. Dominant competitive moves include backward integration into premix manufacturing and direct technical service team deployment with large dairy cooperatives.
Within the domestic integrated tier, Arasco Feed and Food Company Ltd anchors backward integration models through captive premix production. Among multinational technology providers, Alltech Inc and Cargill Incorporated occupy positions representing fermentation platform specialists and direct service embedment strategies respectively. These three entities exemplify the divergence between technology-driven and relationship-driven competitive approaches in a market where SFDA registration dossiers and halal certification timelines create distinct qualification barriers.
| Leading Market Players |
|---|
| Saudi Mix Feed Additives Company |
| Alltech Inc |
| United Feed Company |
| Cargill Incorporated |
| Arasco Feed and Food Company Ltd |
| Brenntag SE |
| Al-Watania Poultry |
| Evonik Industries AG |
| Al-Akhawai |
| Others |
Value Network & Pricing Analysis
SFDA feed ingredient registration and halal certification protocols gate both supplier qualification timelines and price differentiation across acidifier and enzyme categories simultaneously. Buyers face extended review periods for microbial fermentation-derived additives that compress margin windows for foreign entrants while rewarding pre-registered dossier holders with pricing power.
Pricing Analysis
Technical service contracts and formulation consulting drive lifetime value beyond commodity premix transactions. Three-tier pricing structure across premium, standard, and economy levels separates enzyme specialists with embedded dairy cooperative teams from wholesale vitamin distributors serving independent mills. Cost compression in standard-grade amino acid blends is intensifying because Riyadh-based cooperative procurement committees aggregate volumes exceeding fifteen thousand metric tons annually. Smaller independent feed manufacturers in Asir and Jazan provinces exhibit acute price sensitivity, while integrated poultry operators in the Eastern Province prioritize performance metrics over unit cost.
Supply Chain Analysis
China and Europe anchor vitamin and trace mineral premix manufacturing for Saudi import dependency. Domestic production draws from imported lysine and methionine intermediates, microbial fermentation cultures, and organic acid raw materials. Single-source vulnerability concentrates at Jeddah Islamic Port, where shipping rate volatility and congestion delays expose mills to feed formulation interruptions. Distribution runs through technical service teams embedded with large dairy cooperatives, supplemented by direct-to-mill digital platforms penetrating smaller independent poultry operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story. SFDA registration dossiers and halal certification timelines create switching costs that protect incumbent positioning against commodity substitution.
For Market Incumbents: Consolidate backward integration into premix manufacturing at captive facilities within one hundred kilometers of Riyadh dairy cooperative clusters. Deepen technical service embedment with Eastern Province poultry integrators facing acidifier substitution protocols under residue surveillance. Threat of Chinese supplier volume-tier pricing demands capacity addition in domestic lysine and methionine blending. For New Entrants and Emerging Players: SFDA pre-registration fast-track for chemically synthesized additives offers entry pathway with eight to fourteen month timeline advantage over microbial fermentation alternatives. White-space targets concentrate in Red Sea aquaculture enzyme supply for EU export certification and e-commerce technical service channels for Asir and Jazan independent mills. Go-to-market angle should prioritize direct-to-mill digital platforms with embedded formulation calculators. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across thermostable phytase manufacturing and encapsulated organic acid coating technologies. Long-term viability favors acquisition targets with captive premix production and established SFDA dossiers rather than pure distribution plays. Signal to watch is blockchain-tracked import certificate adoption rates for mycotoxin binders as proxy for regulatory compliance automation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Premix Manufacturing | Arasco's Al-Kharj complex demonstrates margin capture from captive lysine and methionine blending capacity. |
| Technical Service Team Embedment | Cargill's direct deployment with central region dairy cooperatives locks in amino acid supply relationships. |
| Halal Certification Fast-Track Investment | Pre-cleared microbial fermentation dossiers reduce registration delays versus chemically synthesized alternatives. |
| E-Commerce Platform Development | Direct-to-mill digital channels penetrate smaller independent poultry operations previously served by distributors. |
| Thermostable Phytase R&D Partnership | Next-generation variants with organic acid coatings enable pelleting temperature tolerance above eighty-five degrees Celsius. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across feed mill procurement managers, poultry integration nutritionists, dairy cooperative technical directors, and SFDA regulatory affairs specialists. Secondary validation incorporated customs import records, SFDA registration dossiers, Saudi Standards Metrology and Quality Organization labeling databases, and cooperative procurement committee tender documentation. Bottom-up volume estimates from individual mill capacity and top-down value triangulation from import value declarations were cross-referenced for convergence.
Across the analysis window, projections modeled product type segmentation by acidifier, nutritional additive, protein supplement, and antioxidant categories alongside application splits across poultry, aquaculture, ruminant, and swine end-uses. CAGRs were derived from regression analysis against livestock headcount growth, feed conversion ratio improvement trajectories, and regulatory phase-out timelines for antibiotic growth promoters. Industry-specific inputs included SFDA mycotoxin binding specification tightening schedules and Red Sea aquaculture export certification adoption curves.
Decision-makers should treat outputs as directional under assumptions of continued SFDA enforcement intensity and cooperative procurement consolidation; material deviation in halal certification timelines or port logistics would warrant model refresh. Recalibration cycles align with material shifts in regulatory specification implementation and blockchain-tracked import certificate penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Calcium Acetate Market
Additives
Trioctyldodecyl Citrate Market
Additives
Drilling Fluid Additives Market
Additives
Hydrogen Peroxide Chemical Indicator Market
Additives
Binding Agents Market
Additives
Plastic Fillers Market
Additives
Global Ester Gum Market
Additives
Green Polymer Additive Market
Additives
Powder Induction and Dispersion Systems Market
Additives
Ammonium Phosphatide Market
Additives
Dispersing Agents Market
Additives
Europe UV Stabilizers Market
Additives
Calcium Tartrate Market
Additives
Lactic Acid Ester Market
Additives
Global PVC Stabilizer Market
Additives
Magnesium Stearate Market