
 Sludge Dewatering Equipment Market | 2026-2036
Sludge Dewatering Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Sludge Dewatering Equipment Market Analysis
Consolidation among municipal wastewater utilities is restructuring procurement patterns across the sludge dewatering equipment value chain. Evoqua Water Technologies leverages its integrated service platform to capture recurring revenue from utility operators. ANDRITZ anchors its position through deep specialization in high-capacity centrifuge systems for industrial effluent. Alfa Laval competes on thermal efficiency metrics that reduce downstream disposal costs for concentrated buyers.
Sludge dewatering equipment encompasses mechanical, thermal, chemical, and electro-dewatering systems engineered to reduce water content in residual solids from 95% to 10-40% dry matter, enabling volume reduction and downstream handling. Belt press and centrifuge configurations dominate the product landscape, with centrifuge systems commanding premium positioning due to higher throughput rates and lower footprint requirements. Mechanical technology leads in installed base across municipal wastewater applications, while electro-dewatering represents the fastest-expanding technology segment as energy efficiency benchmarks tighten in European and East Asian jurisdictions.
EPA effluent guidelines under the Clean Water Act, the EU Urban Wastewater Treatment Directive, and China's MEE discharge standards collectively mandate escalating solids recovery rates and landfill diversion targets. These frameworks compel end users to replace legacy gravity-thickening infrastructure with automated dewatering platforms that deliver certifiable mass-balance documentation. Stakeholders must evaluate equipment selection against evolving per-tonne disposal cost structures and emerging carbon-accounting requirements for sludge transport.
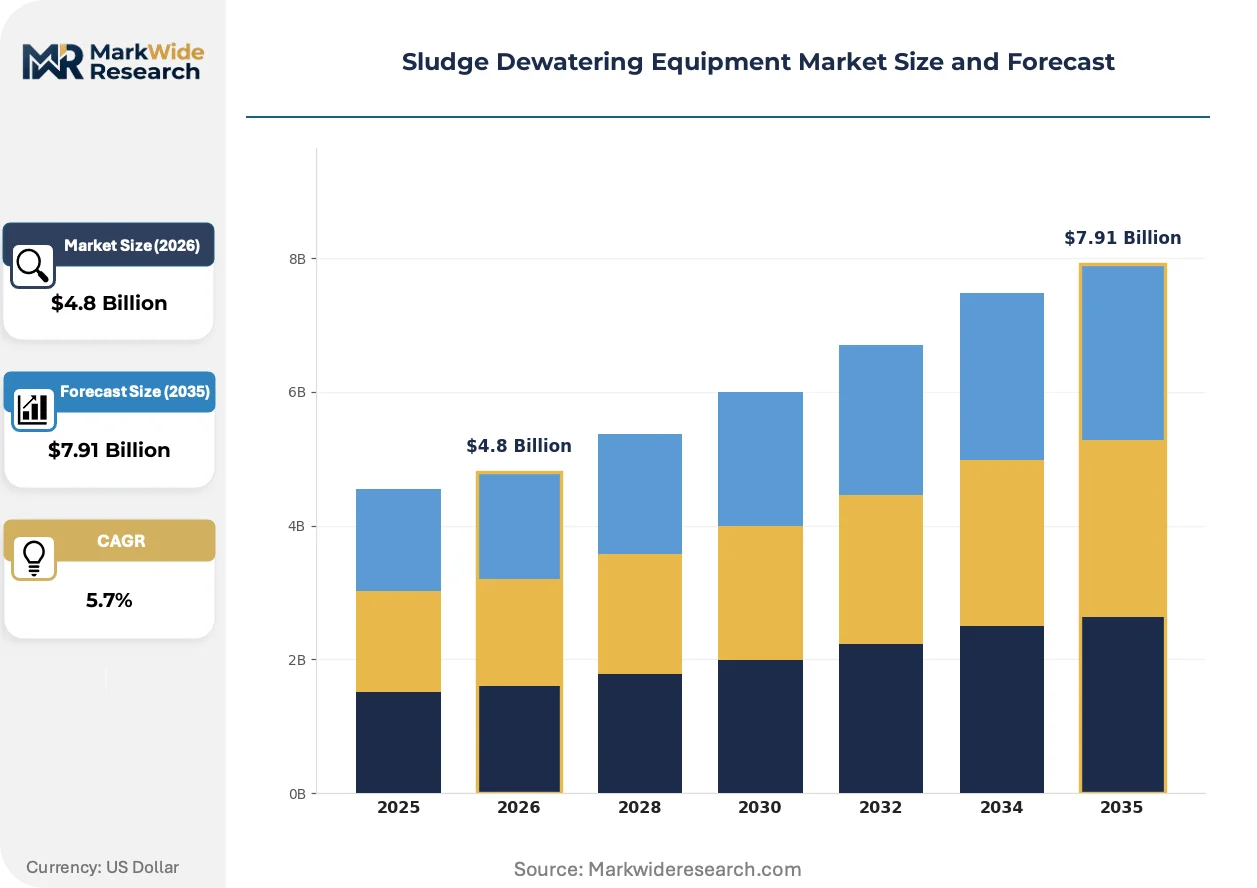
Market Dynamics
Electro-dewatering technology is compressing payback periods for high-volume municipal operators while EU and Chinese discharge mandates force wholesale replacement of gravity-thickening infrastructure.
Growth Catalysts
- EU Urban Wastewater Treatment Directive:Germany and France are retrofitting legacy plants with automated centrifuge systems to meet landfill diversion targets. Procurement volumes from municipal utilities in these countries are accelerating replacement cycles.
- China's MEE discharge standards:Industrial zones in the Yangtze River Delta face mandatory solids recovery rate upgrades. Belt press and centrifuge deployments are expanding across chemical and food processing clusters.
- Electro-dewatering systems:Energy efficiency benchmarks in Japanese and South Korean jurisdictions are pulling adoption of low-temperature electro-osmotic dewatering for pharmaceutical and electronics effluent.
Market Restraints
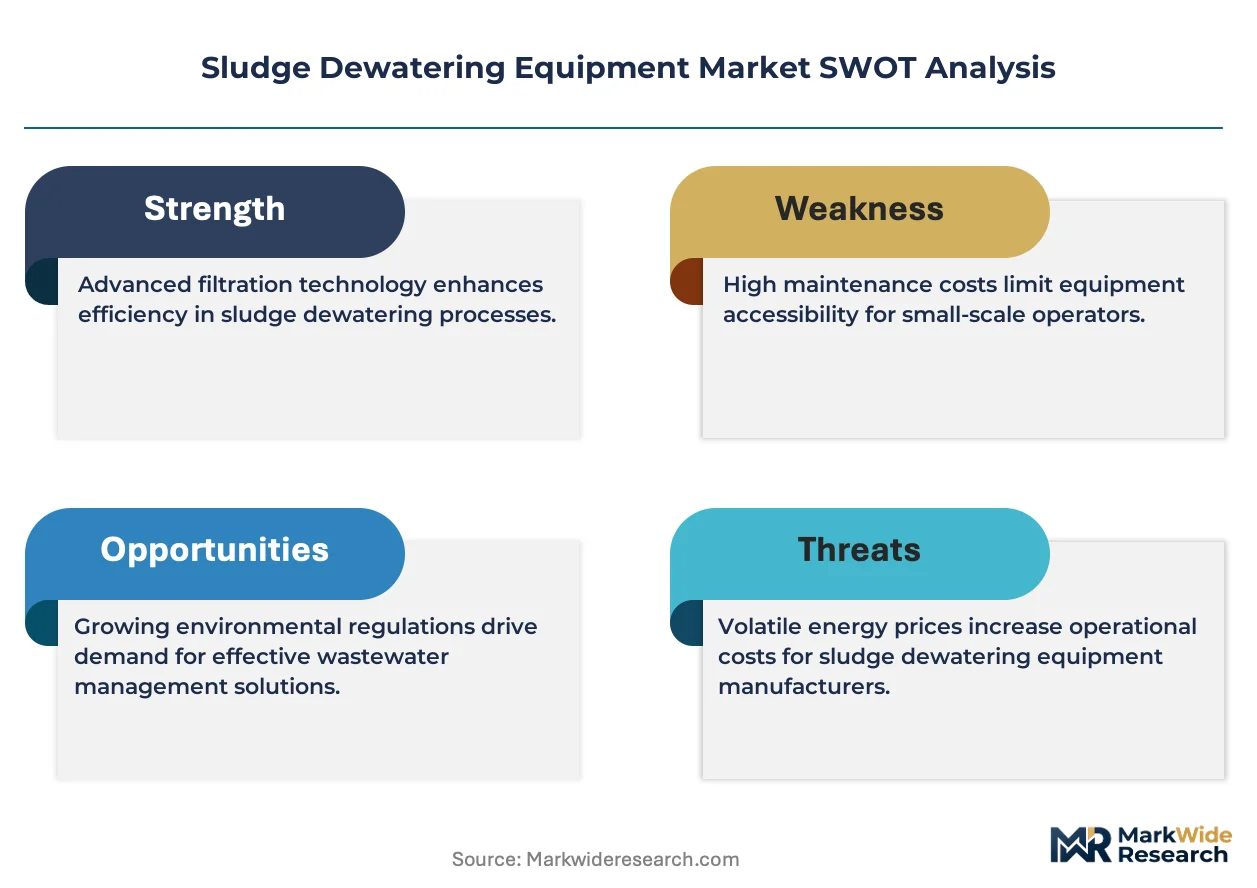
- Stainless steel input volatility:Centrifuge bowl and screw conveyor fabrication depends on specialty alloys. Price swings in nickel and chromium feedstocks compress equipment margins during contract bidding.
- Concentrated component supply:High-torque gearbox and bearing assemblies for decanter centrifuges source primarily from German and Japanese industrial suppliers, creating single-source vulnerability.
- Technical limitation in high-fiber sludge:Belt press throughput degrades significantly with pulp and paper effluent, forcing these end users toward higher-cost centrifuge alternatives.
Strategic Opportunities
- Underpenetrated Indian municipal sector:The country's National Mission for Clean Ganga is unlocking centralized procurement for sewage treatment infrastructure in tier-2 and tier-3 urban clusters.
- Carbon-accounting convergence:Integration of dewatering equipment with biogas capture and thermal drying systems creates bundled energy-credit offerings for European utilities facing CSRD disclosure requirements.
- Mobile dewatering rental channels:Industrial processors in Texas and Alberta are shifting from capital purchase to on-site rental of containerized centrifuge units for seasonal turnaround maintenance.
Industry Challenges
- Automation engineering talent scarcity:PLC programming and remote monitoring integration for smart dewatering platforms outpaces vocational training output in Midwest US manufacturing hubs.
- Legacy SCADA integration friction:Brownfield municipal plants require custom protocol bridges to connect new dewatering controllers with decades-old distributed control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sludge Dewatering Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Drum, Belt Press, Filter Press, Centrifuge Technology: Mechanical, Thermal, Chemical, Electro-dewatering Application: Municipal Wastewater, Industrial Sludge, Agricultural Waste, Mining Effluent End User: Municipalities, Oil & Gas, Manufacturing, Food Processing |
| Companies Covered | Veolia Water Technologies, Evoqua Water Technologies, Alfa Laval, GEA Group, Komline-Sanderson, ANDRITZ, Flottweg SE, Aqseptence Group, HUBER SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sludge Dewatering Equipment Market Emerging Trajectories
Equipment intelligence and energy recovery architectures are redefining competitive differentiation as operators prioritize total cost of ownership over upfront capital expenditure.
Electro-dewatering technology is rewriting the economics of high-moisture industrial sludge handling. Pharmaceutical and electronics manufacturers in Japan and South Korea are deploying low-temperature electro-osmotic systems at pilot scale. The technology is rewriting disposal cost structures by eliminating thermal drying stages and reducing downstream transport volumes by half.
REACH chemical restrictions and the EU F-Gas Regulation are accelerating refrigerant transition in thermal drying ancillaries. Equipment suppliers must certify heat pump and vacuum belt dryer configurations for low-GWP working fluids. German and Dutch engineering firms are most exposed, retooling product lines ahead of 2027 compliance deadlines.
Performance-based service contracts are displacing traditional equipment sale arrangements. Municipal utilities in Denmark and Sweden now contract for guaranteed dry solids output rather than machine availability. Channel intermediaries in Nordic markets are restructuring as outcome guarantors, absorbing operational risk in exchange for per-tonne processing fees.
Sludge Dewatering Equipment Market Segmentation
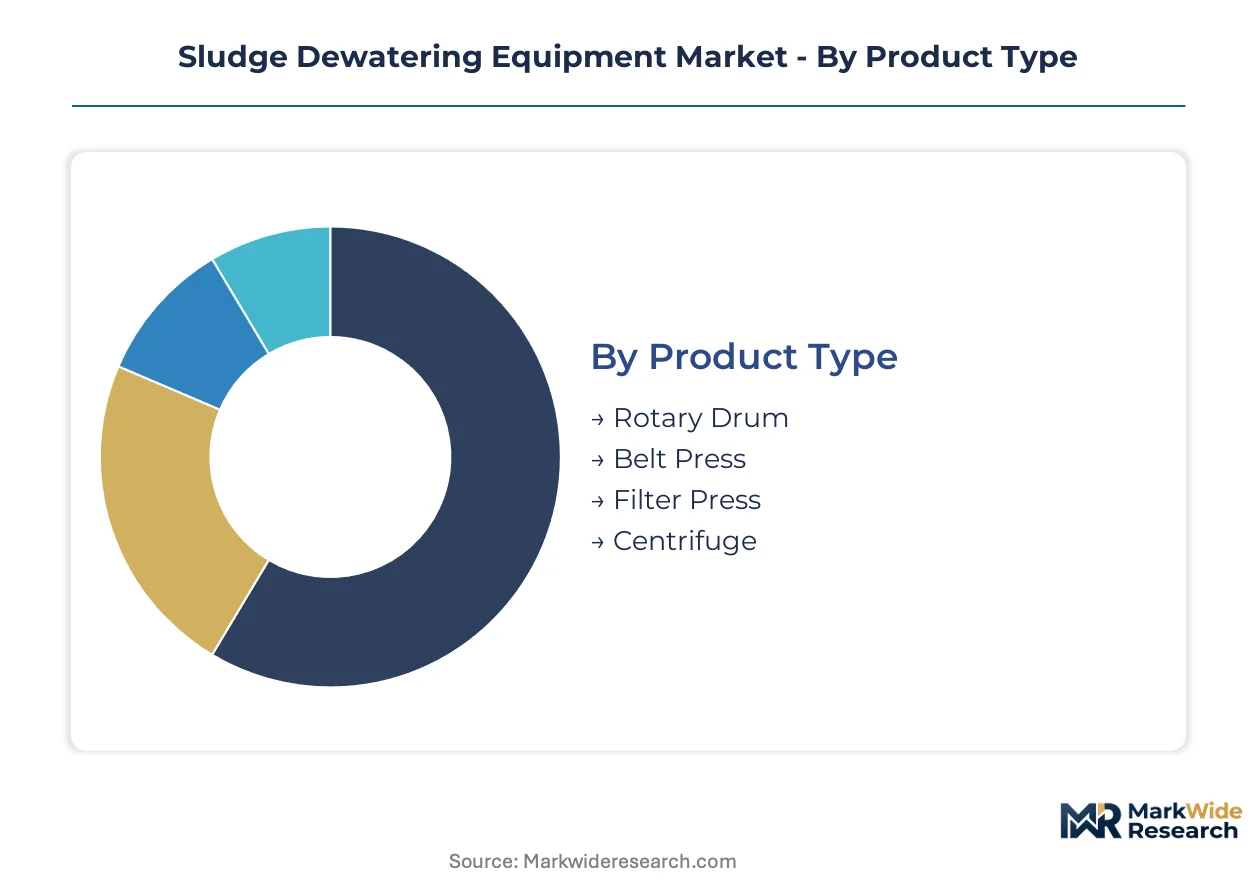
Equipment segmentation in sludge dewatering tracks divergent upgrade cycles across municipal and industrial infrastructure. Procurement patterns split between footprint-constrained retrofits and greenfield capacity expansions, with technology selection driven by discharge compliance deadlines and per-tonne disposal economics.
Product Type:
Replacement cycles accelerate where legacy gravity systems fail to meet landfill diversion mandates or energy efficiency benchmarks.
- Centrifuge:Decanter configurations achieve 20-35% dry solids throughput using high-G force separation in enclosed footprints. German and Chinese municipal utilities specify these for dense urban retrofits where space constraints block belt press installations.
- Belt Press:Gravity-assisted mechanical dewatering operates at lower capital intensity with open-channel maintenance access. Demand clusters in North American municipal markets with lower labor costs and established technician training pipelines.
- Filter Press:Chamber and membrane plate designs deliver highest cake dryness for hazardous industrial sludge requiring landfill minimization.
- Rotary Drum:Pre-thickening configurations integrate upstream of downstream dewatering stages in combined mechanical systems.
Centrifuge sits at the top of the volume ranking, with belt press climbing the fastest in cost-sensitive procurement environments.
Technology:
Cost tier stratification separates proven mechanical platforms from emerging thermal and electro-chemical alternatives with extended payback horizons.
- Mechanical:Centrifuge, belt press, and screw press configurations dominate installed base with mature supply chains and standardized spare parts logistics. Municipal operators in France and Japan prioritize these for predictable operational expenditure profiles.
- Electro-dewatering:Low-temperature electro-osmotic systems apply direct current fields to mobilize bound water without thermal phase change. South Korean pharmaceutical manufacturers pilot these for electronics effluent with strict moisture content specifications.
- Thermal:Direct and indirect drying systems achieve 90%+ dry solids for incineration feedstock or agricultural reuse pathways.
- Chemical:Conditioning polymer and flocculant integration optimizes upstream dewatering performance across all mechanical configurations.
Mechanical technology retains the dominant revenue share, while electro-dewatering gains share fastest in high-disposal-cost jurisdictions.
Application:
Application focus determines equipment specification through sludge rheology, contaminant loading, and downstream fate requirements.
- Municipal Wastewater:Mixed primary and secondary sludge with high organic fraction demands robust odor control and pathogen reduction. China's MEE discharge standards force Yangtze River Delta utilities toward automated centrifuge platforms with certifiable mass-balance documentation.
- Industrial Sludge:Metal hydroxide, chemical precipitate, and oily waste streams require corrosion-resistant materials and hazardous area electrical classification. Chemical processing clusters in Germany's Ruhr region drive specification for duplex stainless steel wetted components.
- Mining Effluent:High-density mineral tailings and acid rock drainage sludge demand abrasion-resistant bowl and conveyor geometries.
- Agricultural Waste:Manure and digestate applications favor lower-cost belt press configurations with biogas integration potential.
Municipal wastewater commands the largest equipment volume, with industrial sludge expanding most quickly on regulatory tightening.
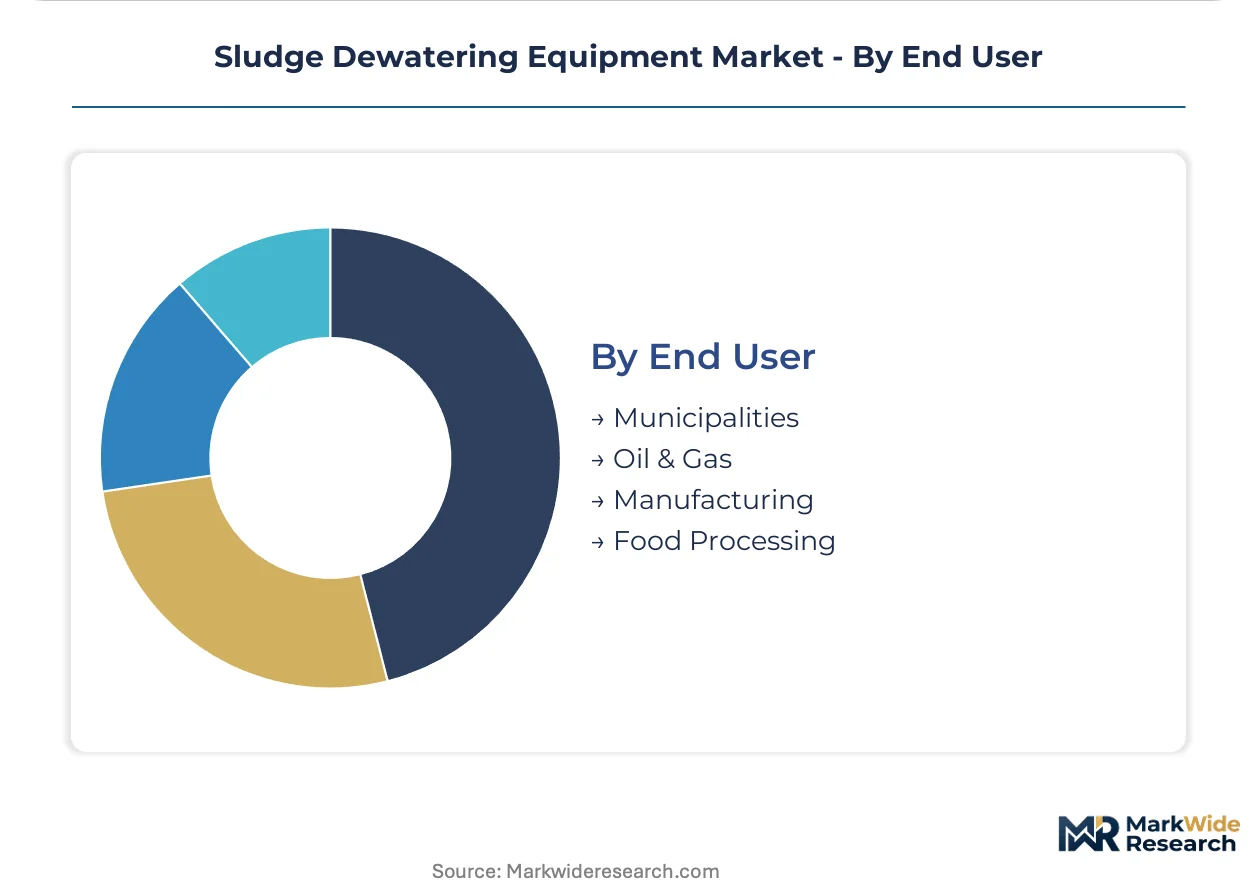
End User:
Customer type shapes procurement modality between capital purchase, performance contracting, and rental fleet deployment.
- Municipalities:Consolidated water utilities in Denmark and Sweden contract for guaranteed dry solids output rather than machine availability, transferring operational risk to equipment suppliers. EU Urban Wastewater Treatment Directive compliance deadlines compress decision timelines.
- Food Processing:Seasonal production cycles and high-organic sludge volumes favor mobile centrifuge rental in Texas and Alberta over fixed capital deployment.
- Oil & Gas:Drill cuttings and produced water sludge require explosion-proof configurations and offshore platform footprint optimization.
- Manufacturing:General industrial effluent spans metal finishing, textile, and automotive coatings with diverse polymer conditioning requirements.
Municipalities represent the largest customer category, with food processing climbing fastest on rental channel expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's municipal retrofit cycles run ahead of China's industrial procurement surge, though both markets face converging landfill diversion mandates from their respective environmental regulators.
Germany
Municipal utilities in North Rhine-Westphalia and Bavaria are replacing gravity-thickening infrastructure with automated centrifuge platforms. The EU Urban Wastewater Treatment Directive compels certifiable mass-balance documentation for all new installations. Engineering clusters around Munich and Düsseldorf concentrate specification activity for duplex stainless steel equipment.
China
Chemical and food processing facilities in the Yangtze River Delta face mandatory solids recovery rate upgrades under tightened MEE discharge standards. Belt press and centrifuge deployments are accelerating across Jiangsu and Zhejiang industrial zones. Procurement volumes from Shanghai municipal utilities are compressing decision timelines for automated dewatering systems.
United States
EPA effluent guidelines under the Clean Water Act are forcing legacy plant upgrades in the Great Lakes and Gulf Coast regions. Food processors in Texas are shifting toward mobile centrifuge rental channels for seasonal turnaround maintenance. Municipal consolidations in the Midwest are restructuring procurement patterns toward performance-based service contracts.
Japan
Pharmaceutical and electronics manufacturers in the Kanto and Kansai regions are piloting low-temperature electro-osmotic dewatering systems. METI energy efficiency benchmarks are pulling adoption of electro-dewatering for high-moisture industrial effluent. Tokyo Bay industrial corridors are deploying pilot installations to eliminate thermal drying stages.
India
The National Mission for Clean Ganga is unlocking centralized procurement for sewage treatment infrastructure in tier-2 and tier-3 urban clusters. State pollution control boards are mandating dry solids output specifications for new municipal contracts. Industrial zones in Gujarat and Maharashtra are importing centrifuge technology for textile and chemical effluent processing.
Sludge Dewatering Equipment Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across equipment fabrication and aftermarket service layers. The vendor base stratifies into three tiers: integrated water technology platforms, centrifuge engineering specialists, and regional fabrication houses serving cost-sensitive procurement environments. Two dominant competitive moves are reshaping positioning: M&A activity consolidating municipal service capabilities, and technology licensing partnerships accelerating electro-dewatering commercialization.
Among European-integrated water technology platforms, Veolia Water Technologies and GEA Group occupy positions spanning equipment fabrication through long-term service contracting. Evoqua Water Technologies exemplifies the North American integrated service archetype, capturing recurring revenue streams through outcome-based municipal contracts. ANDRITZ anchors the industrial centrifuge specialist tier, with Flottweg SE representing German engineering depth in high-capacity decanter systems.
| Leading Market Players |
|---|
| Veolia Water Technologies |
| Evoqua Water Technologies |
| Alfa Laval |
| GEA Group |
| Komline-Sanderson |
| ANDRITZ |
| Flottweg SE |
| Aqseptence Group |
| HUBER SE |
| Others |
Supply Flow & Price Mechanics
Family-owned German engineering houses and private-equity-rolled-up centrifuge specialists anchor supply-side discipline, translating captive fabrication capabilities into pricing power over municipal utilities facing landfill diversion deadlines. Their ownership structures favor long-dated contract bidding with embedded alloy price escalators rather than spot-market competition.
Pricing Analysis
Capacity additions in China's Jiangsu and Zhejiang provinces are reshaping price floors for standard belt press configurations, compressing margins for European fabricators serving cost-sensitive Asian industrial clusters. Three-tier pricing structure across premium decanter systems, standard belt presses, and economy screw presses differentiates on throughput certification and polymer consumption rates. Pricing pressure stems from nickel and chromium volatility in specialty stainless steel feedstocks. Municipal utilities in Denmark and Sweden exhibit lowest price sensitivity due to outcome-based contracting models, while tier-2 Indian cities drive hardest bargain on upfront capital expenditure.
Supply Chain Analysis
Single-source vulnerability sits with German and Japanese suppliers of high-torque gearbox and bearing assemblies for decanter centrifuge drive trains. Component fabrication concentrates in Germany, China, and Japan, with final assembly tethered to engineering clusters around Munich, Shanghai, and Osaka. Raw material dependencies span duplex stainless steel alloys, specialty polymers for conditioning systems, and precision-machined ceramic wear parts. Tariff exposure on Chinese steel semifinished products threatens margin stability for European OEMs. Distribution runs through authorized service networks and municipal procurement consortia rather than open distribution channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between European landfill taxes driving premium equipment specification and Asian discharge mandates forcing volume procurement of mid-tier systems at compressed price points.
For Market Incumbents: Extend service contracting capabilities into outcome-guarantor roles that absorb dry solids output risk from municipal utilities, insulating against centrifuge commoditization by emerging Chinese fabricators. Deepen backward integration into specialty alloy foundries to neutralize nickel price volatility. Prioritize certification investment for EU F-Gas Regulation compliance on thermal drying ancillaries ahead of Dutch and German engineering competitors. For New Entrants and Emerging Players: Digital rental platform routes into Texas and Alberta food processing clusters bypass capital-intensive manufacturing scale requirements while capturing seasonal turnaround demand. Target India's tier-2 municipal markets under National Mission for Clean Ganga procurement windows where incumbent service networks remain thin. Pursue technology licensing partnerships with Japanese electro-dewatering pilot developers to accelerate commercialization without captive R&D infrastructure. For Investors and Strategic Acquirers: Integrated water technology platforms are the most active acquirer in this space, consolidating municipal service capabilities to capture recurring revenue streams. Five-to-ten year viability hinges on electro-dewatering technology maturation beyond pilot scale. Watch for MEE discharge standard tightening in China's Yangtze River Delta as inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Service Contracting | Danish and Swedish utilities now contract for guaranteed dry solids output rather than machine availability. |
| Backward Integration into Specialty Alloys | German centrifuge fabricators are securing captive duplex stainless steel supply against nickel volatility. |
| Electro-Dewatering Technology Licensing | South Korean pharmaceutical manufacturers pilot low-temperature electro-osmotic systems for electronics effluent. |
| Mobile Rental Channel Expansion | Texas food processors shift from capital purchase to containerized centrifuge rental for seasonal maintenance. |
| EU F-Gas Regulation Compliance Retooling | Dutch and German engineering firms are certifying heat pump dryers for low-GWP refrigerants ahead of deadlines. |
Methodological Framework
Coverage spans Germany, China, the United States, Japan, and India, with primary inputs from each market triangulated against secondary validation. Interviews with municipal wastewater utility procurement directors, industrial plant engineers, centrifuge OEM technical sales leads, and aftermarket service heads informed demand-side assumptions. Secondary sources include EPA effluent guideline filings, EU Urban Wastewater Treatment Directive implementation reports, China's MEE discharge standard enforcement data, and customs records for sludge dewatering equipment trade flows. Bottom-up equipment deployment tracking and top-down regulatory mandate sizing were cross-referenced for triangulation.
Rate-of-change decomposition separates replacement cycle timing from greenfield capacity additions across the projection horizon. Segmentation dimensions modeled include product type, technology tier, application sector, and end-user procurement modality. CAGRs were derived from equipment shipment volumes mapped against regulatory compliance deadlines and disposal cost trajectories. Forecast inputs incorporate stainless steel price elasticity coefficients and municipal budget cycle phasing.
The model assumes a particular technology adoption path; alternative pathways for electro-dewatering commercialization would alter the outlook if energy efficiency benchmarks accelerate faster than projected. Forecasts reflect documented assumptions on regulatory enforcement intensity and alloy price stabilization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
US Wastewater Secondary Treatment Equipment Market
Water and Wastewater Treatment
Global Biological Wastewater Treatment Market
Water and Wastewater Treatment
Global Wastewater Diffused Aerator Market
Water and Wastewater Treatment
Global Vertical Sewage Pumps Market
Water and Wastewater Treatment
Bio Filter Market
Water and Wastewater Treatment
Water Testing Meter Market
Water and Wastewater Treatment
Sewage Pump Market
Water and Wastewater Treatment
United States Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Latin America Membrane Bioreactor (MBR) Market
Water and Wastewater Treatment
Zero Liquid Discharge (ZLD) Systems Market
Water and Wastewater Treatment
Global Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Global SCADA in Water and Wastewater Management Market
Water and Wastewater Treatment
Global Microbiological Testing of Water Market
Water and Wastewater Treatment
Aeration Pads Market
Water and Wastewater Treatment
Primary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Tertiary Water and Wastewater Treatment Equipment Market