
 Asia-Pacific Consumer Battery Market | 2026-2036
Asia-Pacific Consumer Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Consumer Battery Market Outlook
Solid-state electrolyte development is narrowing the performance gap between laboratory prototypes and mass-manufactured cells across the region. Samsung SDI Co. Ltd leverages its Korean R&D base to anchor next-generation format development. Panasonic Corporation dominates cylindrical cell supply for premium tool brands. BYD Company Ltd extends vertical control from cathode powders to finished packs.
Asia-Pacific consumer batteries encompass electrochemical energy storage devices rated below industrial scale, typically employing lithium cobalt oxide or nickel manganese cobalt cathodes paired with graphite anodes in pouch or cylindrical formats, designed to power portable equipment through reversible ion intercalation. Lithium-ion chemistry leads value generation due to energy density requirements in smartphones and laptops, while alkaline cells sustain volume across retail consumer channels through price accessibility in remotes and toys. Nickel-metal hydride retains niche positioning in power tools where thermal stability outweighs specific energy demands.
China's SAMR enforces GB standards for cell safety and transport classification, while Japan's METI administers JIS certification for household battery interchangeability. India's BIS mandates IS mark compliance for imported cells sold through online retailers and supermarkets. Stakeholders must track how South Korea's KATS aligns recyclability rules with EU Battery Directive precedents to anticipate compliance cost shifts.
Market Dynamics
Solid-state electrolyte commercialization is compressing development cycles across the Asia-Pacific consumer battery sector, forcing incumbent manufacturers to accelerate pilot-to-production transitions or cede positioning to chemistry-agnostic entrants.
Growth Catalysts
- China's dual carbon goals:Binding emissions targets under the 14th Five-Year Plan are accelerating lithium-ion substitution for alkaline cells in consumer electronics, tightening cell chemistry standards across domestic supply chains.
- India's tier-two city electrification:Power tool and personal mobility device penetration beyond Mumbai, Delhi, and Bangalore is creating first-time battery replacement demand through organized retail channels.
- Silicon-anode adoption:Korean and Japanese cell makers are scaling silicon-composite anode production for premium smartphone formats, extending cycle life thresholds that justify unit price premiums.
Market Restraints
- Cobalt price volatility:Democratic Republic of Congo concentrate supply disruptions transmit directly to NCM cathode cost structures, compressing margin buffers for mid-tier pack assemblers.
- Single-source electrolyte dependence:Fluoroethylene carbonate purification capacity concentrates in Chinese chemical parks, exposing non-Chinese cell manufacturers to input rationing during environmental compliance inspections.
- Energy density ceiling:Conventional graphite anode intercalation limits are approaching theoretical maximums, constraining form factor innovation for ultra-thin wearable applications.
Strategic Opportunities
- Vietnam's manufacturing relocation:Samsung and Apple supplier audits are qualifying Ho Chi Minh City corridor pack assembly facilities for tariff-advantaged export to North American consumer markets.
- Japan's METI efficiency mandates:Revised JIS C 8712 standards for household battery interchangeability are creating certification-premium tiers that reward standardized cell formats.
- Direct-to-consumer online channels:India's BIS-marked cell sales through Flipkart and Amazon are compressing distributor margins while capturing end-user replacement cycle data.
Industry Challenges
- Solid-state manufacturing yield gaps:Dry electrode coating and sulfide electrolyte handling require cleanroom investments that strain balance sheets of sub-scale Korean and Japanese specialists.
- Cross-border transport classification:China's SAMR GB 31241 and UN 38.3 testing synchronization delays are extending inventory holding periods for cells shipped through Shenzhen and Hong Kong logistics hubs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Consumer Battery Market |
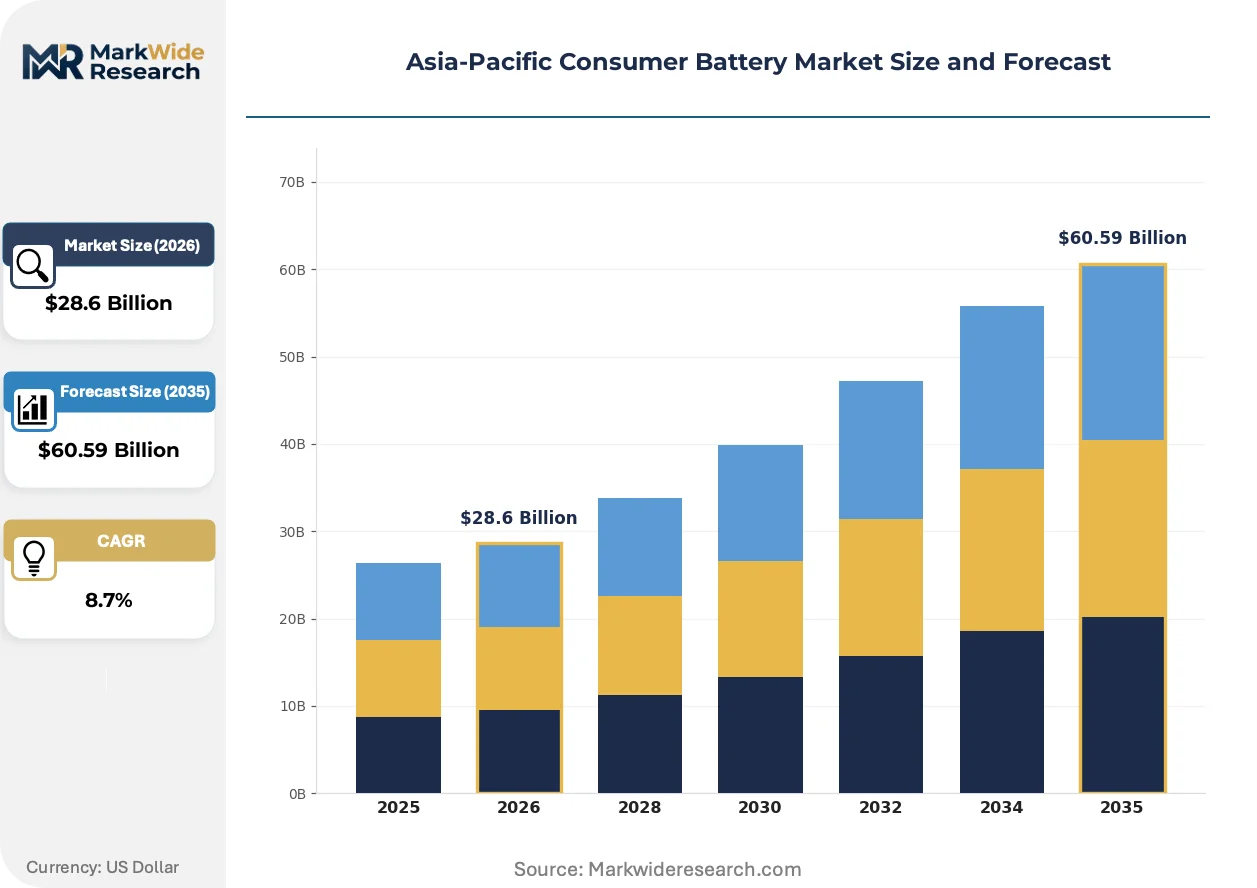
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Nickel-metal Hydride, Lead-acid, Alkaline Application: Consumer Electronics, Electric Vehicles, Power Tools, Renewable Energy Storage End User: Retail Consumers, Small Businesses, Industrial Sectors, Educational Institutions Distribution Channel: Online Retailers, Supermarkets, Specialty Stores, Wholesale Distributors |
| Companies Covered | Samsung SDI Co. Ltd, LG Chem Ltd, Panasonic Corporation, BYD Company Ltd, CATL, GS Yuasa Corporation, Toshiba Corporation, FDK Corporation, EVE Energy Co., Ltd., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Consumer Battery Market Strategic Shifts
Electrode architecture virtualization and regulatory chemistry mandates are converging to compress product lifecycles across the Asia-Pacific consumer battery sector, rewarding manufacturers with captive materials science capabilities.
Solid-state battery technology is virtualizing the traditional liquid electrolyte manufacturing footprint. Samsung SDI and Toyota-affiliated suppliers are piloting sulfide-based ceramic electrolyte deposition for cylindrical formats, with smartphone OEMs qualifying samples for 2026 platform integration. This virtualization is collapsing the distinction between laboratory cell performance and mass-manufactured consistency, enabling tier-one brands to source from non-traditional chemistry houses.
METI's revised JIS standards for household battery interchangeability are mandating dimensional and terminal configurations that override proprietary format advantages. Japanese power tool and home appliance manufacturers must redesign battery compartments to accept standardized cells, eroding lock-in strategies that previously tethered consumables to original equipment. Premium cordless tool brands are responding by shifting differentiation toward thermal management firmware rather than physical pack incompatibility.
Replacement cycle compression is fragmenting procurement authority across Asia-Pacific consumer segments. Indian smartphone users in tier-two cities are purchasing cells through quick-commerce platforms with sub-30-minute delivery guarantees, displacing traditional electronics retail for emergency replacements. This channel shift is most visible in Bengaluru and Hyderabad, where Blinkit and Zepto dark stores stock BIS-certified lithium-ion inventories matched to device model databases.
Asia-Pacific Consumer Battery Market Segmentation
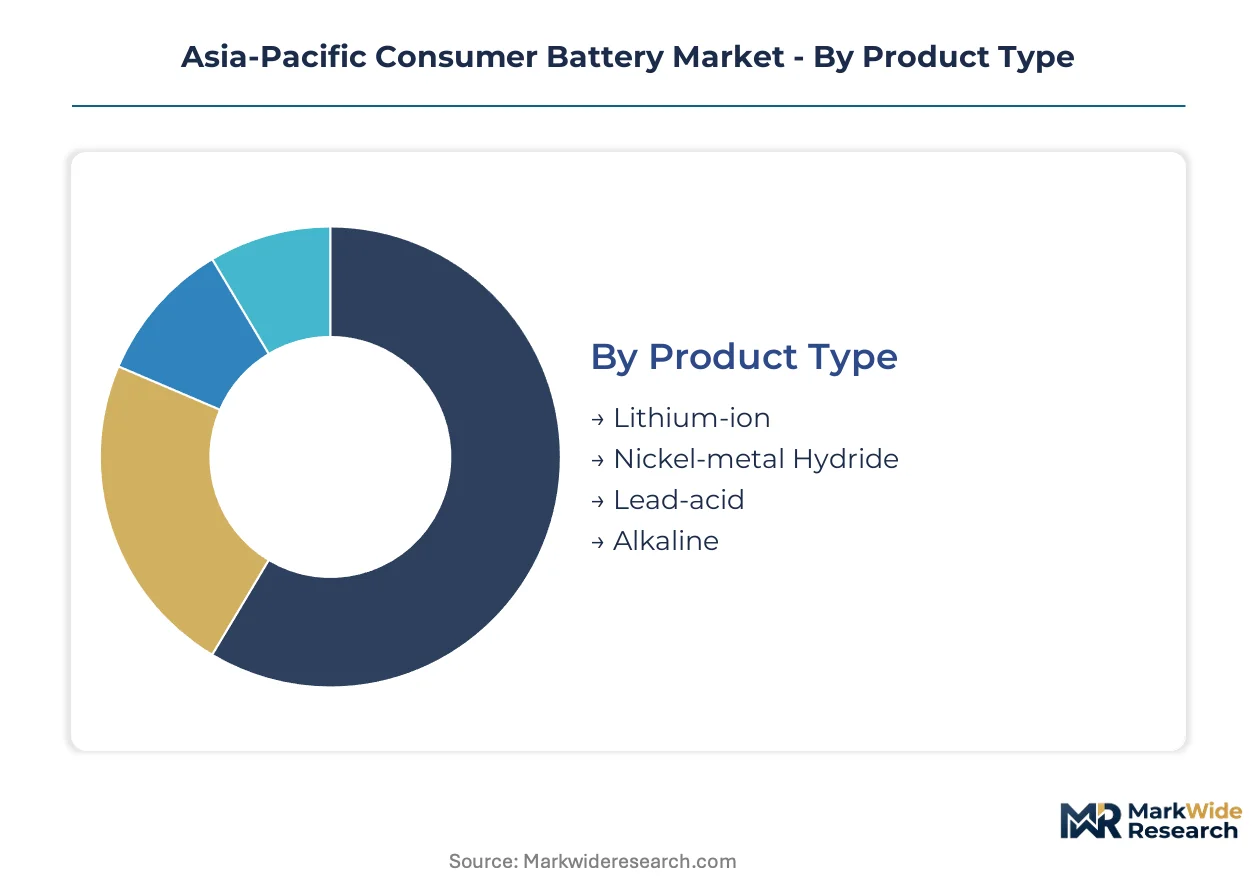
Segmentation in the Asia-Pacific consumer battery market reveals how chemistry selection, procurement channel, and end-use thermal requirements create divergent margin structures. Manufacturers must align format development with India's quick-commerce logistics or Japan's METI interchangeability mandates to capture replacement cycle value.
Product Type:
Mature alkaline formats coexist with emerging solid-state lithium-ion architectures across regional supply chains.
- Lithium-ion:Reversible ion intercalation chemistry employing lithium cobalt oxide or nickel manganese cobalt cathodes paired with graphite anodes. Demand concentrates in Korean and Japanese smartphone OEM supply chains where Samsung SDI and Panasonic qualify high-voltage pouch cells for flagship device platforms. China's dual carbon goals are accelerating lithium-ion substitution for alkaline cells in consumer electronics.
- Nickel-metal Hydride:Metal hydride anode paired with nickel oxyhydroxide cathode delivering superior thermal stability over lithium-ion at moderate energy density. Demand concentrates in Japanese power tool brands where METI efficiency mandates reward standardized cell formats and thermal stability outweighs specific energy demands for contractor-grade cordless equipment.
- Lead-acid:Mature flooded or valve-regulated lead-acid chemistry for cost-sensitive backup power applications in Indian tier-two cities.
- Alkaline:Zinc-manganese dioxide primary cells sustaining volume across Southeast Asian retail consumer channels through price accessibility in remotes and toys.
Alkaline retains volume leadership; lithium-ion holds the steepest expansion curve.
Application:
Cost tier stratification separates premium interchangeability mandates from price-driven replacement cycles.
- Consumer Electronics:Ultra-thin pouch and cylindrical formats for smartphones, laptops, and wearables requiring maximum volumetric energy density. Samsung and Apple supplier audits in Vietnam's Ho Chi Minh City corridor are qualifying pack assembly facilities for tariff-advantaged export.
- Electric Vehicles:High-capacity cell modules for personal mobility devices and micro-mobility platforms. India's tier-two city electrification beyond Mumbai and Delhi is creating first-time battery replacement demand through organized retail channels.
- Power Tools:Cylindrical cell configurations for cordless contractor equipment where Japanese manufacturers are shifting differentiation toward thermal management firmware rather than physical pack incompatibility under revised JIS C 8712 standards.
- Renewable Energy Storage:Residential and small commercial battery systems for solar integration in Australian and Southeast Asian markets.
Consumer electronics commands premium pricing; electric vehicles is gaining share fastest.
End User:
Customer type determines whether procurement runs through B2B distributor networks or direct-to-consumer platforms.
- Retail Consumers:Individual purchasers of replacement cells for personal electronics and household devices. Quick-commerce platforms with sub-30-minute delivery guarantees in Bengaluru and Hyderabad are displacing traditional electronics retail for emergency replacements.
- Small Businesses:Contractor fleets and service operations procuring power tool batteries through wholesale distributors.
- Industrial Sectors:Manufacturing and logistics operations requiring standardized cell formats for material handling equipment.
- Educational Institutions:Bulk procurement of primary cells for laboratory and administrative applications.
Retail consumers drive replacement frequency; small businesses generate the most stable contract volumes.
Distribution Channel:
Supply concentration in Chinese chemical parks shapes channel reliability for non-domestic manufacturers.
- Online Retailers:Flipkart and Amazon India sales of BIS-marked cells compressing distributor margins while capturing end-user replacement cycle data matched to device model databases.
- Supermarkets:Mass-market alkaline and primary cell volume through organized retail chains in Southeast Asian urban centers.
- Specialty Stores:Electronics retailers and mobile phone service centers stocking lithium-ion replacements for specific device models.
- Wholesale Distributors:B2B procurement channels for industrial and commercial battery requirements across the region.
Online retailers are expanding most quickly; wholesale distributors retain the largest transaction sizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese cell exports flow through Shenzhen and Hong Kong logistics hubs to Southeast Asian assembly plants, while Korean manufacturers anchor premium supply chains serving Japanese and Australian consumer electronics brands.
China
Domestic lithium-ion demand accelerates as SAMR enforces GB 31241 safety standards for cells sold through online retailers. The dual carbon goals under the 14th Five-Year Plan tighten cathode chemistry requirements across Pearl River Delta manufacturing zones. Shenzhen pack assemblers are scaling automated production lines to meet certification deadlines for export-bound consumer electronics.
Japan
METI's revised JIS C 8712 interchangeability mandates are forcing power tool manufacturers to redesign battery compartments for standardized cell formats. Kansai-region OEMs are shifting differentiation toward thermal management firmware rather than proprietary pack designs. Osaka-based suppliers are qualifying cylindrical cells for contractor-grade cordless equipment under the new efficiency thresholds.
South Korea
Silicon-anode adoption is accelerating across Seoul Capital Area R&D facilities as Samsung SDI pilots next-generation formats for 2026 smartphone platforms. KATS is aligning domestic recyclability rules with EU Battery Directive precedents, raising compliance costs for mid-tier pack assemblers. Busan-Ulsan chemical parks are expanding fluoroethylene carbonate purification capacity to reduce single-source dependence.
India
Tier-two city electrification beyond Mumbai and Delhi is creating first-time replacement demand for power tools and personal mobility devices. BIS mandates IS mark compliance for cells sold through Flipkart and Amazon, compressing distributor margins while capturing end-user data. Bengaluru and Hyderabad quick-commerce platforms stock BIS-certified inventories matched to device model databases for sub-30-minute delivery.
Vietnam
Ho Chi Minh City corridor pack assembly facilities are qualifying for tariff-advantaged export to North American consumer markets under Samsung and Apple supplier audits. Domestic demand for alkaline cells sustains volume through Southeast Asian retail channels serving remotes and toys. Regulatory alignment with China's SAMR transport classification standards is reducing cross-border shipping delays through regional logistics hubs.
Asia-Pacific Consumer Battery Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered procurement networks. The vendor base clusters around three strategic archetypes: diversified conglomerates with captive materials science capabilities, chemistry-agnostic contract manufacturers, and regional pack assemblers serving price-driven replacement cycles. Consolidation pressure is accelerating as solid-state yield gaps force balance sheet investments in cleanroom infrastructure. Dominant competitive moves include backward integration into cathode powder production and strategic partnerships with quick-commerce platforms for last-mile distribution.
Within the diversified conglomerate tier, Samsung SDI Co. Ltd and Panasonic Corporation anchor premium-format development through Korean and Japanese R&D bases respectively. BYD Company Ltd exemplifies vertical control extending from raw materials through finished pack assembly. These three entities represent distinct geographic concentrations of electrochemical expertise while occupying positions across cylindrical, pouch, and prismatic format specializations.
| Leading Market Players |
|---|
| Samsung SDI Co. Ltd |
| LG Chem Ltd |
| Panasonic Corporation |
| BYD Company Ltd |
| CATL |
| GS Yuasa Corporation |
| Toshiba Corporation |
| FDK Corporation |
| EVE Energy Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Shenzhen-Hong Kong logistics corridor freight cost dynamics amplify pricing power for Chinese cathode powder suppliers while forcing Korean and Japanese cell manufacturers into premium tier positioning against mid-tier pack assemblers.
Pricing Analysis
Next-generation silicon-anode cell pricing commands triple-digit premiums over conventional graphite-anode formats, while alkaline cells sustain economy-tier positioning through zinc-manganese dioxide commodity sourcing. Pricing stratifies across premium, standard, and economy tiers based on certification grade and volume scale, with BIS-marked lithium-ion cells in India compressing distributor margins through direct-to-consumer channels. Cost compression in mid-tier cylindrical formats is intensifying because cobalt concentrate supply disruptions transmit directly to NCM cathode cost structures. Retail consumers in Indian tier-two cities exhibit highest price sensitivity, while Japanese power tool OEMs demonstrate lowest sensitivity due to METI efficiency mandate compliance requirements.
Supply Chain Analysis
Cobalt concentrate from the Democratic Republic of Congo, lithium carbonate from Australian spodumene operations, and fluoroethylene carbonate from Chinese chemical parks constitute the upstream feedstock foundation. Cell manufacturing concentrates in China, South Korea, and Japan, with cathode powder production anchored in Pearl River Delta industrial zones. Single-source electrolyte dependence creates vulnerability when environmental compliance inspections trigger input rationing. Distribution runs through wholesale distributor networks for industrial procurement and quick-commerce platforms for retail replacement cycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific consumer battery market is entering a cyclical recovery phase as solid-state electrolyte commercialization compresses development cycles and replacement demand accelerates across India's electrifying tier-two cities.
For Market Incumbents: Entrench positioning through backward integration into cathode powder production and captive fluoroethylene carbonate purification capacity in Busan-Ulsan chemical parks. Chemistry-agnostic entrants threaten premium format margins; defend through accelerated pilot-to-production transitions for sulfide-based ceramic electrolyte deposition. Samsung SDI and Panasonic should expand cleanroom infrastructure investments to close solid-state manufacturing yield gaps before sub-scale specialists achieve scale. For New Entrants and Emerging Players: Pursue white-space opportunities in Vietnam's Ho Chi Minh City corridor pack assembly for tariff-advantaged North American export, and quick-commerce platform partnerships for last-mile distribution in Bengaluru and Hyderabad. India's BIS-certified online retail channel remains the most penetrable entry point. Target direct-to-consumer replacement cycle data capture through device model database integration. For Investors and Strategic Acquirers: Chemistry-agnostic contract manufacturers with pilot-scale solid-state capabilities represent the priority acquisition archetype for portfolio exposure to next-generation format transitions. Long-term viability hinges on 5-10 year technology licensing revenue streams from sulfide electrolyte intellectual property. Watch for KATS alignment with EU Battery Directive recyclability rules as inflection indicator for compliance cost shifts affecting mid-tier pack assembler valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cathode Powder Production | BYD's vertical control from raw materials through finished packs insulates margin buffers from cobalt price volatility. |
| Solid-State Electrolyte Pilot-to-Production Scale-Up | Samsung SDI's Korean R&D base accelerates sulfide-based ceramic electrolyte qualification for smartphone OEM platforms. |
| Quick-Commerce Platform Partnership | Flipkart and Amazon India BIS-marked cell sales compress distributor margins while capturing end-user replacement cycle data. |
| Vietnam Manufacturing Relocation | Ho Chi Minh City corridor facilities qualify for tariff-advantaged export under Samsung and Apple supplier audits. |
| METI JIS C 8712 Certification Investment | Osaka-based suppliers qualifying cylindrical cells under revised efficiency thresholds capture premium interchangeability tiers. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with cell manufacturing executives, cathode powder procurement leads, power tool OEM platform engineers, and quick-commerce supply chain managers; and secondary validation through SAMR GB standard filings, METI JIS certification databases, BIS IS mark registries, and customs trade records. Bottom-up and top-down triangulation reconciled facility-level production capacity with regional consumption estimates.
Forecast inputs considered chemistry-type segmentation, application thermal requirements, procurement channel evolution, and end-user replacement cycle compression across the projection horizon. CAGRs were derived from modeled adoption curves for silicon-anode and solid-state formats, with India's tier-two city electrification and Vietnam's export qualification timeline as battery-specific demand drivers.
Macroeconomic conditions sit as an overlay; deviation in cobalt concentrate pricing, yuan-dollar exchange rates, or environmental inspection intensity in Chinese chemical parks would shift the trajectory. Cross-checking against UN 38.3 transport classification testing volumes and regional logistics hub throughput data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Drone Power Sources Market
Batteries
Global Electric Scooter Batteries Market
Batteries
Battery Simulator Market
Batteries
Vanadium Redox Batteries Market
Batteries
Middle East and Africa Solar and Motorcycle Battery Market
Batteries
Primary Lithium Battery Market
Batteries
Electric Battery Market
Batteries
Battery Plate Market
Batteries
Iron-Chromium Flow Battery Market
Batteries
Submarine Lead-Acid Battery Market
Batteries
Global Cylindrical Lithium Battery Pack Market
Batteries
Battery Maintainer Market
Batteries
South America Primary Battery Market
Batteries
Rear Rack Battery Market
Batteries
Heavy-Duty Truck Megapack Battery Systems Market
Batteries
Global Industrial Battery Market