
 Waste Paper Management Market | 2026-2036
Waste Paper Management Market Size, Share, and Industry Trends Forecast 2026-2036
Waste Paper Management Market Outlook
Municipal collection channels is narrowing as private haulers and producer-funded schemes consolidate last-mile access. DS Smith Plc leverages its integrated recycling and packaging model to control fiber flows across multiple European markets. Smurfit Kappa Group anchors its competitive position through mill-scale pulping operations that reduce third-party dependency. International Paper Company competes via geographic breadth in North American recovered fiber networks.
Waste paper management encompasses the collection, sorting, grading, and reprocessing of post-consumer and post-industrial paper streams into reusable pulp, typically requiring deinking to below 100 ppm ink residue for premium grades. The practice diverts cellulose fiber from landfills and returns it to packaging and tissue manufacturing loops. Cardboard recovery leads volume due to e-commerce box generation, while office paper commands margin premiums through superior fiber length and lower contamination. Pulping dominates processing economics at scale, though composting gains traction for soiled mixed paper streams that fail cleanliness thresholds.
EPA landfill diversion targets and EU Green Deal circular economy requirements shape collection infrastructure investment across the United States and Europe. BIS recycling standards in India and ECHA REACH compliance for deinking chemicals further constrain operational protocols. Stakeholders must monitor how extended producer responsibility rollouts alter cost allocation between brands, municipalities, and waste collectors.
Market Dynamics
The EU Green Deal's circular economy mandates are compressing virgin fiber demand while forcing packaging manufacturers to reconfigure sourcing networks around certified recovered paper streams. This regulatory pressure is redrawing competitive boundaries between integrated recyclers and independent collectors.
Growth Catalysts
- EU Green Deal Packaging Mandates:Brussels' recycled content thresholds for corrugated boxes are pulling industrial-scale deinking investment into Germany and the Netherlands.
- E-commerce Box Generation:Parcel volume growth is concentrating cardboard recovery in urban logistics hubs, creating captive feedstock for nearby pulping operations.
- Deinking Chemistry Advances:Enzyme-based ink removal is cutting water consumption below 50 liters per ton in Nordic mill trials, expanding capacity for high-grade output.
Market Restraints
- Recovered Paper Price Volatility:OCC bale costs swing with Chinese import quota fluctuations, compressing margin predictability for independent processors.
- German Infrastructure Concentration:Three-quarters of EU deinking capacity sits within 500 kilometers of Düsseldorf, creating geographic supply risk.
- Contamination Rate Ceilings:Food residue and plastic film adherence above 2% renders mixed paper unmillable, shrinking addressable feedstock pools.
Strategic Opportunities
- Eastern European Collection Gaps:Poland and Romania lack industrial-scale sorting infrastructure, opening first-mover positions for automated optical separation deployment.
- Chemical Pulp Substitution:Tissue manufacturers are qualifying recovered fiber for premium hygiene grades previously reserved for virgin cellulose.
- Producer Responsibility Schemes:France's Citeo-funded collection networks are demonstrating brand-financed last-mile models replicable across Southern Europe.
Industry Challenges
- Optical Sorting Technician Scarcity:Near-infrared calibration and AI-driven contamination detection require skill sets absent from traditional waste management labor pools.
- Mill Retrofit Timelines:Converting graphic paper machines to packaging-grade recycled output demands 18-24 month shutdown windows that strain customer contract continuity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Waste Paper Management Market |
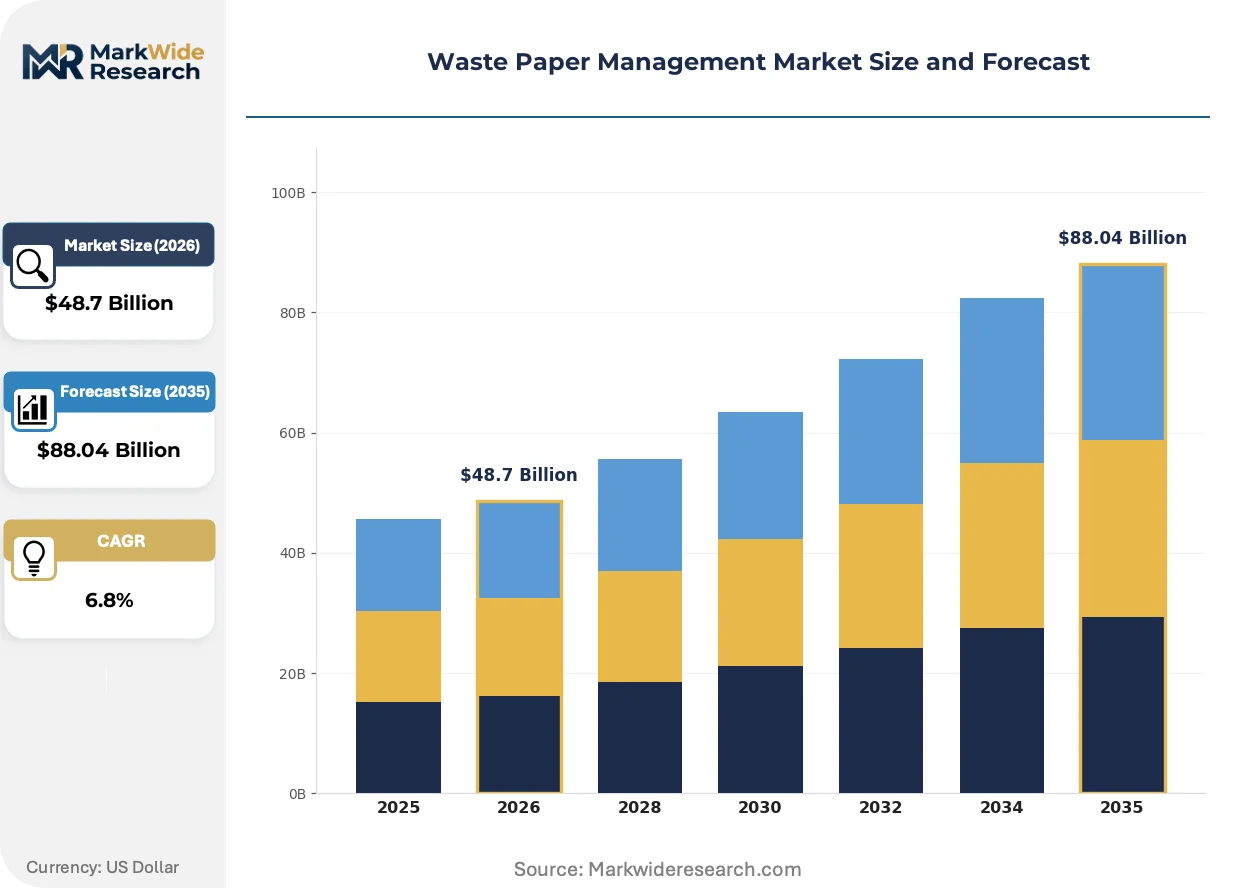
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardboard, Newsprint, Office Paper, Mixed Paper Processing Method: Pulping, Recycling, Composting, Landfilling End User: Manufacturers, Retailers, Waste Collectors, Government Agencies Application: Packaging, Paper Products, Construction Materials, Industrial Use |
| Companies Covered | Mondi Group, Nine Dragons Paper Holdings Limited, International Paper Company, UPM-Kymmene Corporation, Stora Enso Oyj, Smurfit Kappa Group, DS Smith Plc, Oji Holdings Corporation, WestRock Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Waste Paper Management Market Strategic Shifts
Processing technology is pivoting toward water-minimal systems as energy costs and discharge regulations tighten simultaneously. This shift is compressing the advantage of legacy integrated mills while elevating modular, distributed recycling units.
Enzymatic deinking is migrating from pilot-scale Nordic installations to commercial contracts with major tissue producers. Metsä Group's Kemi facility has operationalized cellulase-based fiber liberation for magazine-grade feedstock. The technology is migrating from batch-tank processing to continuous-flow reactor designs, enabling 40% throughput gains without expanding physical footprint.
ECHA REACH compliance deadlines for deinking surfactants are forcing reformulation of fatty acid-based collectors by mid-decade. German chemical suppliers are accelerating biodegradable alternatives through toxicity screening protocols. Small and mid-scale Italian recyclers face the steepest adaptation costs, driving consolidation around compliant chemical sourcing networks.
Retailer compliance programs are displacing spot-market purchasing for recovered paper. Amazon's European packaging standards now require chain-of-custody documentation from baler to mill gate. French supermarket chains are extending this traceability requirement to private-label tissue products, privileging vertically integrated recyclers with in-house audit capabilities.
Waste Paper Management Market Segmentation
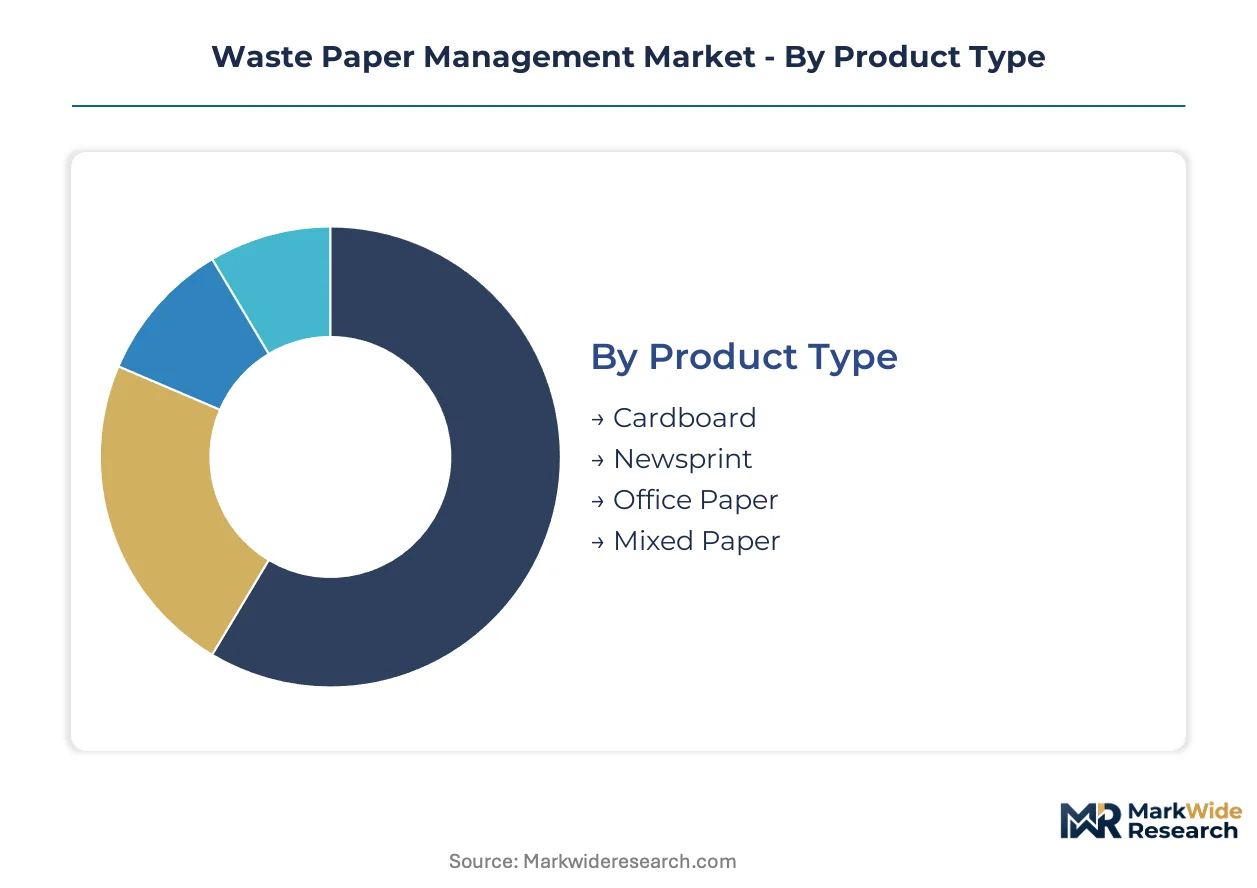
Waste paper management markets fragment across fiber grade, processing intensity, and customer procurement power. Understanding these divisions reveals where margin concentrates and which infrastructure investments align with demand trajectories.
Product Type:
Volume concentration across fiber grades maps directly to e-commerce logistics density and commercial printing decline.
- Cardboard:Corrugated containers and boxboard dominate tonnage flows. E-commerce fulfillment centers in Germany and the Netherlands generate captive feedstock for nearby deinking mills, with Amazon's packaging standards now requiring chain-of-custody documentation from baler to mill gate.
- Office Paper:Long cellulose fibers and low contamination rates command premium pricing in tissue manufacturing. French supermarket chains extend traceability requirements to private-label hygiene products, privileging recyclers with in-house audit capabilities.
- Newsprint:Declining print circulation compresses availability but sustains niche demand for insulation fiber.
- Mixed Paper:Contamination ceilings above 2% render substantial volumes unmillable, diverting streams toward composting or energy recovery.
Cardboard commands the established base. The steepest expansion runs through Office Paper as tissue manufacturers qualify recovered fiber for premium hygiene grades.
Processing Method:
Technology intensity separates capital-intensive mill operations from distributed collection and disposal alternatives.
- Pulping:Hydrapulper systems liberate fibers through mechanical and chemical action, with enzyme-based deinking cutting water consumption below 50 liters per ton in Nordic trials. Metsä Group's Kemi facility has operationalized cellulase-based processing for magazine-grade feedstock.
- Recycling:Sorting, baling, and direct re-manufacturing without full fiber separation serves lower-grade applications. Smurfit Kappa's mill-scale pulping operations reduce third-party dependency through captive fiber preparation.
- Composting:Soiled mixed paper streams failing cleanliness thresholds divert to aerobic digestion for soil amendment production.
- Landfilling:Residual fractions with excessive contamination or composite construction face final disposal under EPA landfill diversion targets and EU circular economy mandates.
Pulping anchors revenue concentration. The technology frontier advances fastest through Recycling as optical sorting and AI-driven contamination detection reshape preparation economics.
End User:
Procurement scale and contract duration differentiate stakeholders across the value chain.
- Manufacturers:Packaging and tissue producers with multi-year fiber supply agreements. DS Smith's integrated recycling and packaging model controls flows across multiple European markets.
- Retailers:Brand-owners facing extended producer responsibility obligations. France's Citeo-funded collection networks demonstrate brand-financed last-mile models replicable across Southern Europe.
- Waste Collectors:Municipal and private haulers consolidating last-mile access as producer-funded schemes displace traditional collection.
- Government Agencies:Regulators setting contamination thresholds and diversion targets under EU Green Deal circular economy requirements.
Manufacturers retain procurement volume leadership. Regulatory pressure is accelerating fastest through Retailers as compliance programs displace spot-market purchasing.
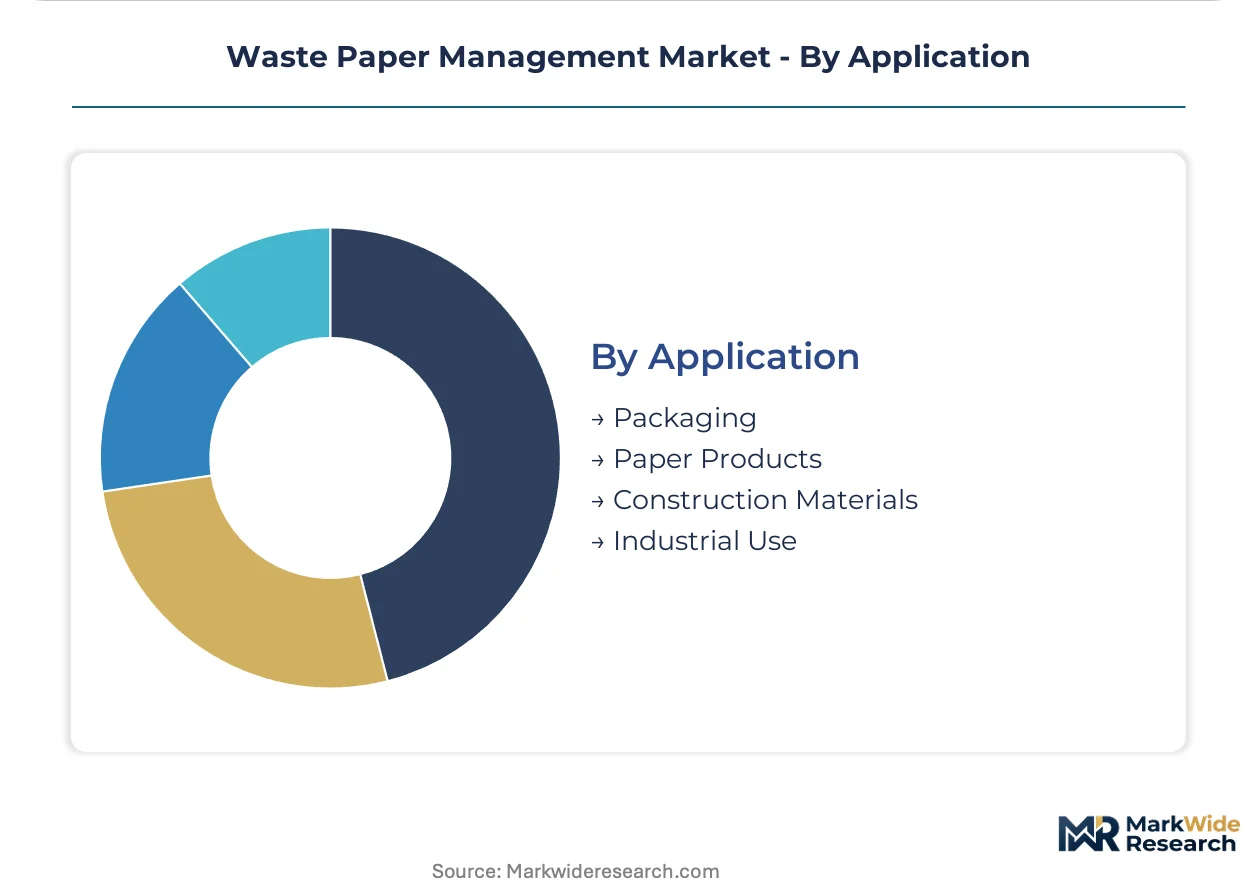
Application:
End-use specifications determine fiber quality requirements and pricing stratification.
- Packaging:Corrugated boxes and molded pulp containers absorb the majority of recovered OCC streams. Brussels' recycled content thresholds pull industrial-scale deinking investment into Germany.
- Paper Products:Tissue, printing, and writing grades demand sub-100 ppm ink residue through advanced deinking chemistry.
- Construction Materials:Lower-grade fibers enter insulation, gypsum board facing, and composite panel applications with relaxed cleanliness standards.
- Industrial Use:Absorbent media, filtration, and specialty cellulose derivatives consume niche high-purity fractions.
Packaging dominates tonnage absorption. The specification ladder climbs fastest through Paper Products as chemical pulp substitution accelerates in premium hygiene segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput underwrites Europe's recovered fiber import capacity, connecting Nordic pulp mills to Atlantic bale flows. German rail corridors distribute processed material to packaging clusters along the Rhine-Ruhr industrial belt. This infrastructure geometry concentrates deinking investment within 500 kilometers of Düsseldorf.
Germany
Amazon's European fulfillment network generates captive OCC streams for industrial-scale pulping operations. The EU Green Deal's recycled content thresholds mandate certified chain-of-custody documentation from baler to mill gate. The Rhine-Ruhr corridor hosts three-quarters of continental deinking capacity, with Smurfit Kappa's mill-scale operations reducing third-party fiber dependency.
France
Citeo-funded collection networks demonstrate brand-financed last-mile models replicable across Southern Europe. Extended producer responsibility obligations require retailers to finance municipal sorting infrastructure. The Paris Basin concentrates tissue manufacturing demand for premium-grade recovered office paper with sub-100 ppm ink residue specifications.
Netherlands
Enzyme-based deinking trials in Nordic mill installations cut water consumption below 50 liters per ton for high-grade output. ECHA REACH compliance deadlines for surfactant reformulation accelerate biodegradable alternative development. The Port of Rotterdam's bale import capacity connects Dutch processors to Atlantic recovered fiber flows.
Poland
Automated optical separation deployment gaps create first-mover positions for infrastructure investors. BIS recycling standards constrain operational protocols for cross-border material shipments. The Silesian industrial zone lacks industrial-scale sorting infrastructure, diverting mixed paper streams toward composting or energy recovery.
United States
EPA landfill diversion targets shape collection infrastructure investment across municipal and private hauler networks. WestRock's geographic breadth in North American recovered fiber networks competes against integrated recycling models. The Southeast's corrugated manufacturing expansion pulls OCC bales from urban logistics hubs in Atlanta and Charlotte.
Waste Paper Management Market Competitive Environment
On the supply side, the industry is consolidating around integrated recyclers with captive pulping capacity and mill-scale fiber preparation operations. Independent collectors face margin compression from recovered paper price volatility linked to Chinese import quota fluctuations. Two strategic archetypes dominate: vertically integrated packaging manufacturers controlling fiber flows from collection to finished product, and geographic network specialists optimizing last-mile access across dispersed municipal contracts. Competitive moves center on M&A for sorting infrastructure and strategic partnerships for deinking chemical supply security.
Within the integrated packaging tier, DS Smith Plc and Smurfit Kappa Group exemplify mill-scale operators reducing third-party dependency through captive fiber preparation. International Paper Company anchors the geographic breadth archetype across North American recovered fiber networks. Mondi Group and Stora Enso Oyj occupy positions bridging European collection density with Nordic pulp mill integration. Nine Dragons Paper Holdings Limited represents Asia-Pacific scale dynamics, while Oji Holdings Corporation and WestRock Company complete the competitive set across Pacific Rim and North American markets respectively.
| Leading Market Players |
|---|
| Mondi Group |
| Nine Dragons Paper Holdings Limited |
| International Paper Company |
| UPM-Kymmene Corporation |
| Stora Enso Oyj |
| Smurfit Kappa Group |
| DS Smith Plc |
| Oji Holdings Corporation |
| WestRock Company |
| Others |
Value Chain & Pricing Dynamics
German deinking capacity concentration within 500 kilometers of Düsseldorf funnels margin capture toward integrated mill operators with captive fiber preparation, while independent collectors absorb OCC bale cost volatility from Chinese import quota fluctuations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies recovered paper markets by fiber grade certification and contamination thresholds. Premium office paper with sub-100 ppm ink residue commands tissue manufacturer premiums, while standard-grade OCC serves corrugated packaging under EU Green Deal recycled content mandates, and economy mixed paper faces composting diversion when food residue exceeds 2%. Cost compression in the standard tier is intensifying as retailer compliance programs displace spot-market purchasing. Municipal collectors exhibit highest price sensitivity due to fixed-rate contracts, whereas integrated packaging manufacturers with backward integration into pulping operations demonstrate lowest sensitivity through captive supply absorption.
Supply Chain Analysis
DS Smith Plc and Smurfit Kappa Group control contract-manufacturing concentration through mill-scale pulping operations across Germany, France, and the Netherlands. Raw material dependencies center on post-consumer OCC streams from Amazon's European fulfillment network, post-industrial boxboard from packaging converters, and enzyme-based deinking chemicals subject to ECHA REACH reformulation deadlines. Single-source vulnerability concentrates in German rail corridors distributing processed material to Rhine-Ruhr packaging clusters. Distribution runs through producer-funded collection schemes like France's Citeo network, displacing traditional municipal hauler channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where EU Green Deal circular economy mandates create switching costs for packaging manufacturers requalifying fiber supply relationships.
For Market Incumbents: Entrench position through backward integration into automated optical sorting infrastructure in Poland and Romania, closing collection gaps before first-movers capture Eastern European feedstock pools. Accelerate cellulase-based deinking chemistry investment to meet ECHA REACH surfactant deadlines ahead of Italian recycler consolidation waves. Capacity addition in the Silesian industrial zone addresses geographic supply risk concentration near Düsseldorf. For New Entrants and Emerging Players: Establish a beachhead in composting-adjacent mixed paper processing for soiled streams failing 2% contamination ceilings, leveraging lower capital intensity than mill-scale pulping. Target Romanian and Polish sorting infrastructure deployment with AI-driven contamination detection systems, where optical sorting technician scarcity constrains incumbent expansion. Go-to-market angle emphasizes brand-financed last-mile collection partnerships replicating France's Citeo model across Southern Europe. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed independent collectors facing margin compression from recovered paper price volatility and lacking captive mill capacity. Long-term viability favors integrated operators with in-house audit capabilities for retailer chain-of-custody documentation requirements. Watch Nordic enzyme-based deinking commercialization rates as inflection indicator for water-minimal processing technology displacement of legacy hydrapulper systems.| Strategic Initiative | Industry Significance |
|---|---|
| Automated Optical Sorting Deployment | AI-driven contamination detection in Poland and Romania closes Eastern European infrastructure gaps. |
| Enzymatic Deinking Scale-Up | Cellulase-based fiber liberation at Metsä Group's Kemi facility cuts water consumption below 50 liters per ton. |
| Producer Responsibility Scheme Replication | France's Citeo-funded collection networks demonstrate brand-financed last-mile models across Southern Europe. |
| Backward Integration into Pulping | Smurfit Kappa's mill-scale operations reduce third-party fiber dependency through captive preparation. |
| Retailer Compliance Program Certification | Amazon's chain-of-custody documentation requirements privilege vertically integrated recyclers with in-house audit capabilities. |
Study Parameters
Cross-validation between mill operator production data and customs trade records anchors the qualitative findings in this study. Primary interviews with deinking facility managers, municipal collection contract officers, tissue manufacturer procurement leads, and ECHA regulatory compliance specialists were combined with secondary validation from EU Green Deal implementation reports, EPA landfill diversion databases, and BIS recycling standard filings. Bottom-up fiber flow modeling and top-down packaging demand estimation provided triangulation across the analysis window.
Calibration against historical OCC price volatility and deinking capacity utilization rates shaped the analytical framework. Segmentation dimensions modeled include fiber grade tier, processing intensity level, end-use application specifications, and regional regulatory cluster variations. CAGRs were derived through trend extrapolation of e-commerce box generation rates and EU recycled content threshold compliance timelines, with enzyme-based processing adoption curves and extended producer responsibility rollout schedules serving as industry-specific forecast inputs.
Stress conditions across Chinese import quota fluctuations, ECHA surfactant reformulation compliance costs, and optical sorting technician availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Quarterly review of Nordic enzymatic deinking commercialization rates and Eastern European infrastructure investment announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Waste Management & Pollution Control
United States Trash Bags Market
Waste Management & Pollution Control
Trash Pump Market
Waste Management & Pollution Control
North America Solid Waste Management Market
Waste Management & Pollution Control
Vietnam Waste Management Market
Waste Management & Pollution Control
India Waste Management Market
Waste Management & Pollution Control
Waste Management Market
Waste Management & Pollution Control
Qatar Solid Waste Management Market
Waste Management & Pollution Control
Food Waste Management Market
Waste Management & Pollution Control
Global Smart Trash Bin Market
Waste Management & Pollution Control
Africa Waste Management Market
Waste Management & Pollution Control
North America Waste Management Market
Waste Management & Pollution Control
Medical Waste Management System Market
Waste Management & Pollution Control
Europe Municipal Solid Waste Management Market
Waste Management & Pollution Control
Landfill Compactor Market
Waste Management & Pollution Control
Global Automated Marine Debris Collection Equipment Market
Waste Management & Pollution Control
Global Pharmaceutical Waste Management Market