
 Ethyl Cellulose Market | 2026-2036
Ethyl Cellulose Market Size, Share, and Industry Trends Forecast 2026-2036
Ethyl Cellulose Market Analysis
The EU Green Deal is broadening the addressable market for bio-based film formers and barrier coatings derived from cellulose ethers. Ashland Global Specialty Chemicals Inc. leverages its integrated supply chain for pharmaceutical-grade ethyl cellulose to sustain premium positioning in controlled-release formulations. Shandong Head Co. Ltd. anchors regional supply for Asian coating manufacturers, while Eastman Chemical Company competes through specialized grades targeting hot-melt adhesive applications.
Ethyl cellulose is a cellulose ether produced by ethoxylation of alkali cellulose, typically containing 44–50% ethoxyl content by weight, and functions primarily as a water-insoluble film former, binder, and controlled-release agent across pharmaceutical, food, and industrial systems. The pharmaceutical segment dominates value capture due to stringent excipient certification requirements and long qualification cycles for tablet coating and taste-masking films. Powder and granule forms lead volume shipments, though solution grades command higher margins in precision coating operations for microencapsulation and enteric barrier systems.
FDA excipient guidelines, EMA quality standards for pharmaceutical starting materials, and China's NMPA registration requirements for imported drug additives collectively shape product specifications, testing protocols, and market access conditions for ethyl cellulose suppliers. REACH registration obligations in Europe further constrain entry for unqualified producers by mandating full toxicological dossiers. Stakeholders must monitor evolving pharmacopeial harmonization between USP-NF, EP, and ChP standards, as divergence in ethoxyl content acceptance ranges could fragment formulation strategies and force redundant qualification investments across manufacturing footprints.
Market Dynamics
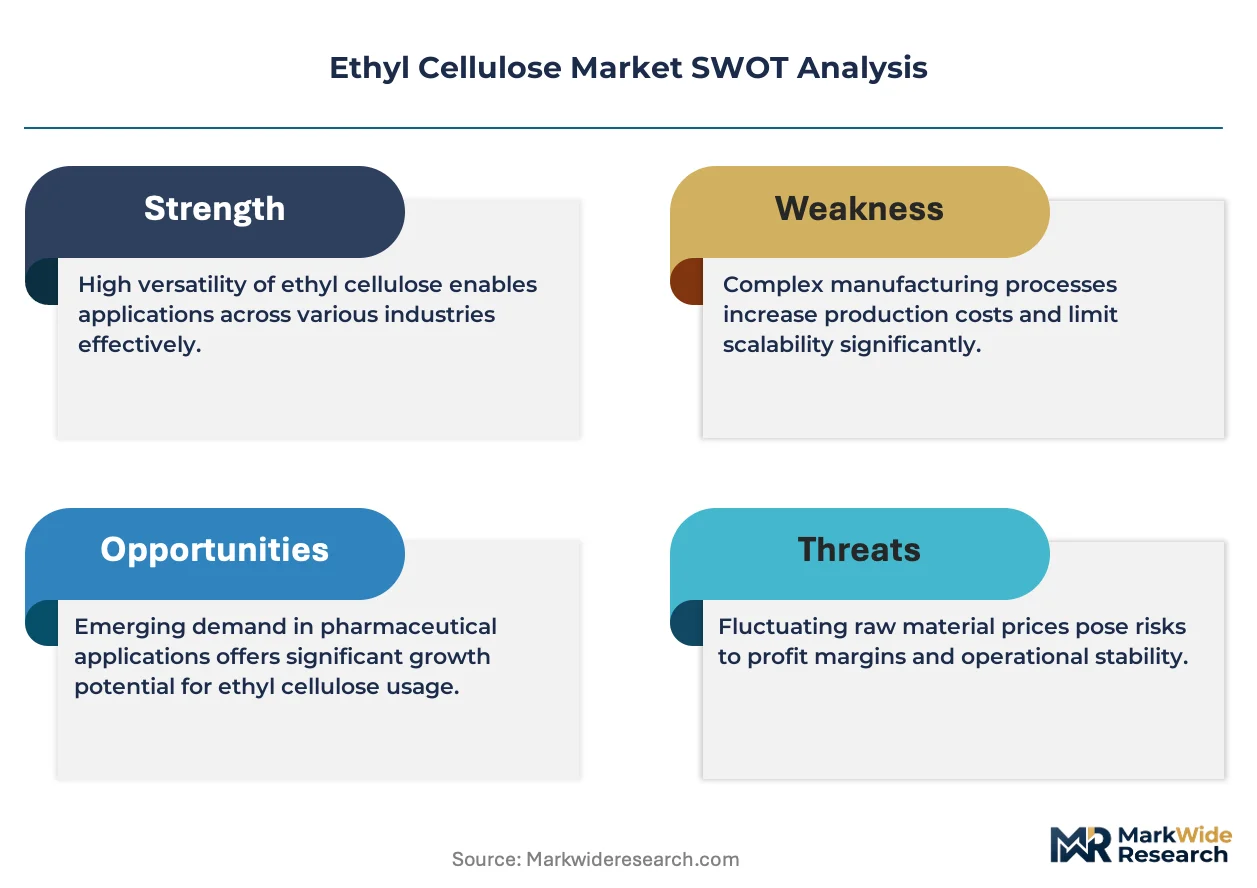
Pharmaceutical-grade certification requirements are compressing supplier margins while concentrating volume among excipient specialists capable of sustaining multi-jurisdictional pharmacopeial compliance across USP-NF, EP, and ChP standards.
Growth Catalysts
- Controlled-release tablet demand:Chronic disease management protocols in North America and Western Europe are expanding prescriptions for extended-release oral dosages requiring ethyl cellulose barrier films.
- REACH registration completion:Full toxicological dossier acceptance under ECHA requirements has cleared market access for qualified European cellulose ether producers serving food-contact and medical-device segments.
- Hot-melt adhesive specification:Automotive interior assembly lines in Germany and Japan are qualifying ethyl cellulose-based formulations for low-VOC bonding applications.
Market Restraints
- Wood pulp supply volatility:Dissolving-grade pulp prices fluctuate with Brazilian and South African forestry harvest cycles, compressing margin predictability for cellulose ether producers.
- Ethoxylation capacity concentration:Contract manufacturing for pharmaceutical-grade ethoxylation clusters in the Rhine-Ruhr industrial corridor, creating single-point vulnerability for European supply security.
- HPMC substitution in coatings:Hydroxypropyl methylcellulose offers aqueous processing advantages that displace ethyl cellulose in immediate-release tablet formulations where moisture barriers are unnecessary.
Strategic Opportunities
- Indian pharmaceutical excipient localization:CDSCO registration pathways for imported drug additives are incentivizing domestic ethyl cellulose production to serve formulation houses in Hyderabad and Ahmedabad.
- Biodegradable mulch film applications:EU Green Deal agricultural sustainability mandates are opening specification trials for cellulose-derived soil barrier coatings in Mediterranean horticulture zones.
- 3D-printed pharmaceutical dosing:Precision deposition technologies are integrating ethyl cellulose as a tunable-release matrix polymer for personalized medicine fabrication.
Industry Challenges
- Multi-pharmacopeial harmonization gaps:Divergent ethoxyl content acceptance ranges between USP-NF and ChP standards force redundant batch testing and qualification investments for suppliers serving both markets.
- Specialized chemical engineering talent scarcity:Cellulose ether process optimization requires expertise in heterogeneous reaction kinetics that outpaces university training pipeline output in Western Europe and North America.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethyl Cellulose Market |
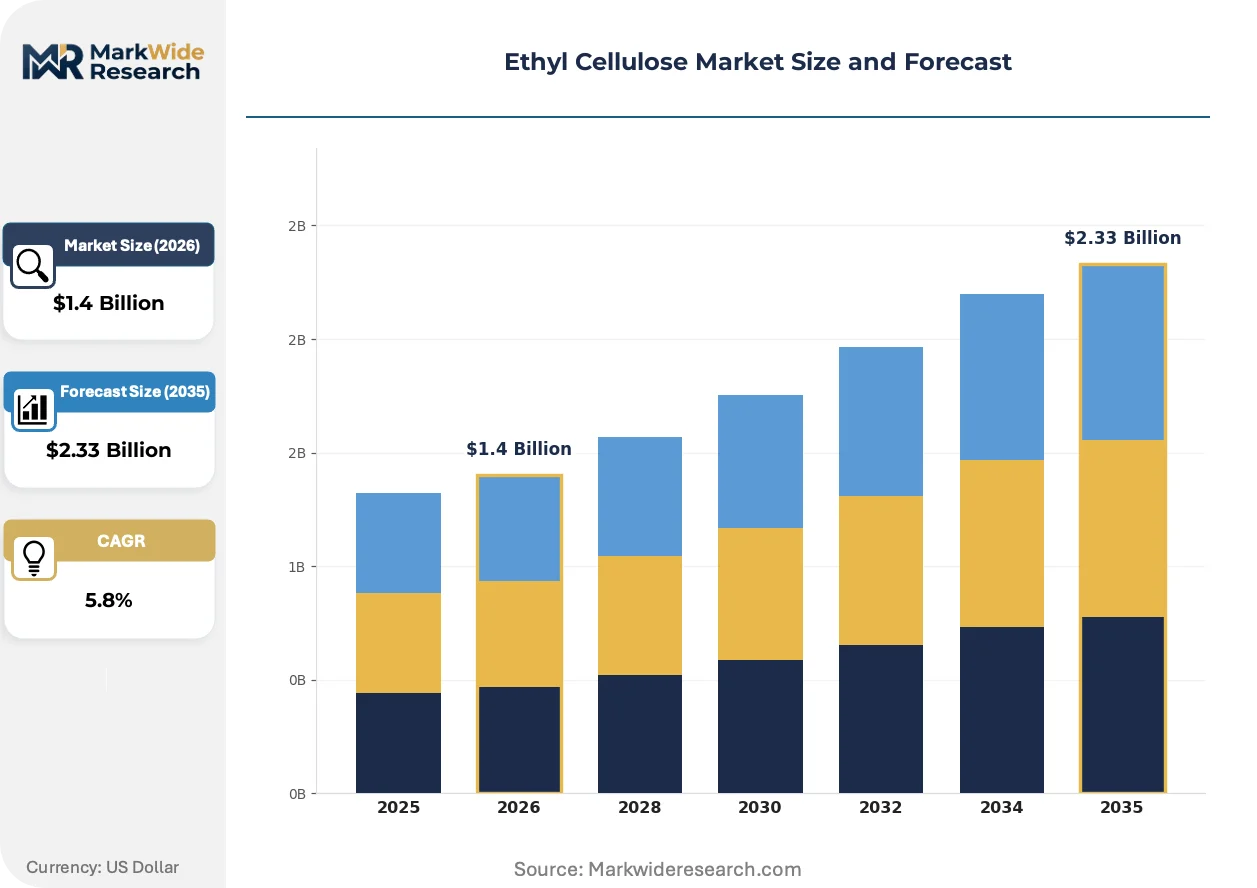
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pharmaceuticals, Coatings, Adhesives, Food Additives Application: Films, Tablets, Beverages, Cosmetics End User: Food Industry, Healthcare, Cosmetics Industry, Packaging Form: Granules, Powder, Solution, Emulsion |
| Companies Covered | Ashland Global Specialty Chemicals Inc., Shandong Head Co. Ltd., Dow Inc., African Chemicals S.A.E., SIDLEY CHEMICAL CO., LTD., Eastman Chemical Company, Lotte Fine Chemicals, JRS PHARMA GmbH & Co. KG, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethyl Cellulose Market Emerging Trajectories
Active pharmaceutical ingredient manufacturers are reconfiguring their excipient qualification workflows around real-time release testing protocols, compressing traditional batch-release timelines and favoring suppliers with integrated analytical capabilities.
Precision coating equipment for microencapsulation is integrating ethyl cellulose solution grades with electrostatic spray deposition systems, enabling sub-10-micron film thickness control for taste-masking applications. Pediatric and geriatric formulation houses in Switzerland and the Netherlands are adopting these systems at replacement cycle intervals of 18-24 months. The technology is integrating quality-by-design principles that reduce coating variability and API loss during processing.
EMA quality standards for pharmaceutical starting materials are tightening residual solvent specifications for ethyl cellulose used in implantable device coatings. Manufacturers must now demonstrate sub-50-ppm limits for chlorinated hydrocarbons that were previously tolerated at higher thresholds. Medical-device coating specialists in Ireland and Denmark are restructuring their supplier audit protocols to capture these evolving requirements before MDR conformity assessment deadlines.
Formulation scientists are consolidating their excipient vendor lists from an average of 12 suppliers to 3-4 strategic partners capable of dual-sourcing security and regulatory documentation packages. This concentration is compressing commercial negotiation leverage for mid-tier ethyl cellulose distributors. The shift is most visible among generic pharmaceutical manufacturers in India and China seeking to streamline their USFDA and EMA inspection readiness.
Ethyl Cellulose Market Segmentation
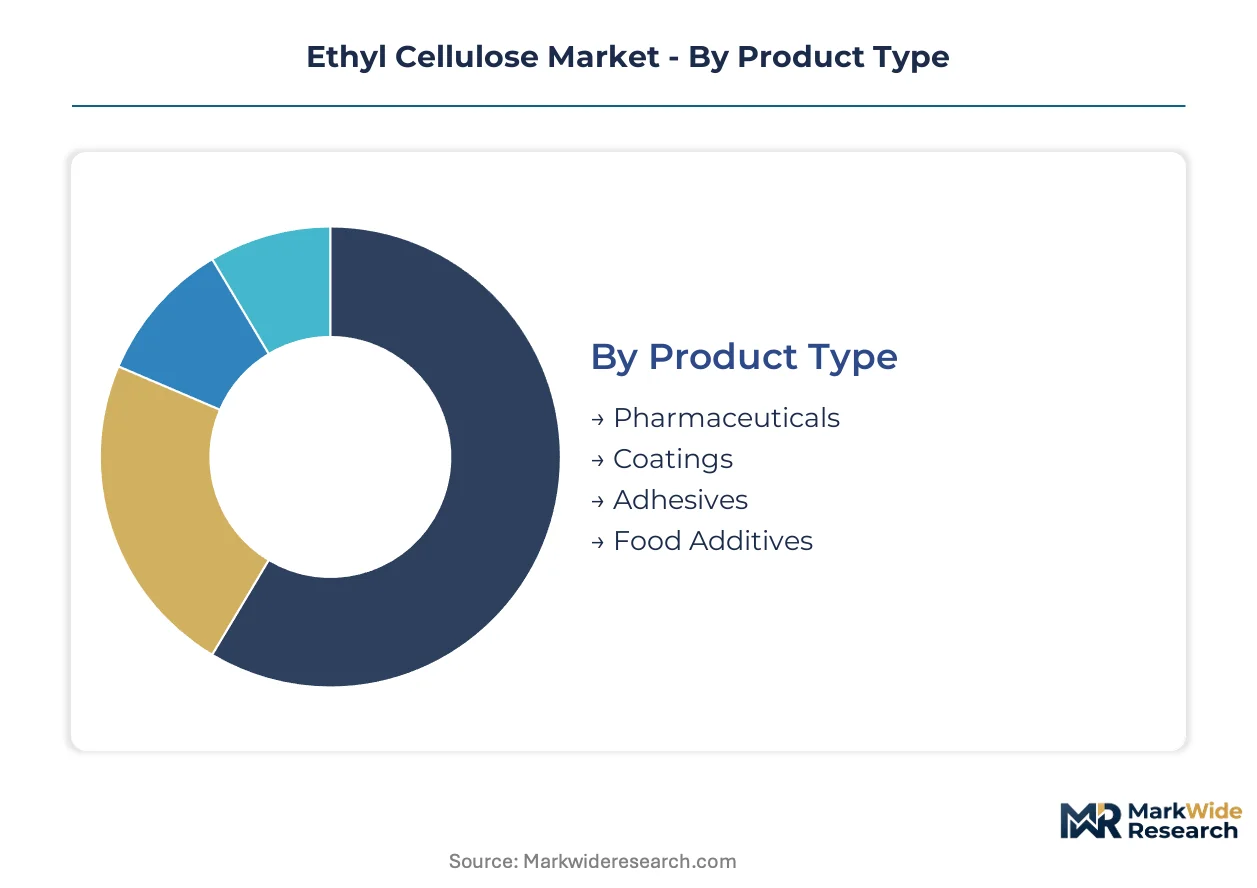
Ethyl cellulose specifications diverge sharply across end-use contexts, with pharmaceutical-grade purity requirements commanding tenfold testing intensity versus industrial coating grades. Formulators select product types and physical forms based on solubility parameters, film-forming kinetics, and regulatory pathway constraints rather than commodity pricing alone.
Product Type:
Standardization dominates pharmaceutical and food additive grades where pharmacopeial certification locks specifications, while coatings and adhesives permit broader formulation latitude and regional customization.
- Pharmaceuticals:USP-NF and EP compliance mandates residual solvent limits below 50 ppm for implantable device coatings, with ethoxyl content strictly controlled between 44-50 percent. EMA quality standards for pharmaceutical starting materials are tightening chlorinated hydrocarbon thresholds, forcing suppliers to revalidate batch release protocols for European market access.
- Coatings:Hot-melt adhesive specifications in German and Japanese automotive assembly lines favor low-VOC ethyl cellulose formulations for interior bonding applications. Demand concentrates in solvent-based barrier systems where moisture resistance and thermal stability outweigh aqueous processing convenience.
- Adhesives:Specialized grades target pressure-sensitive tape backings and textile laminates in East Asian manufacturing clusters.
- Food Additives:EFSA and FDA food contact approvals govern film-forming applications in confectionery glazes and protective coatings.
Most installed capacity flows through Pharmaceuticals. Expansion is steepest in Coatings.
Application:
Volume scale concentrates in tablet coating operations, while precision applications in microencapsulation and beverage stabilization command disproportionate margin capture.
- Films:Controlled-release barrier layers in extended-release oral dosages require sub-10-micron thickness control achievable only with solution-grade ethyl cellulose. Swiss and Dutch formulation houses are replacing equipment at 18-24 month cycles to integrate electrostatic spray deposition systems for pediatric taste-masking applications.
- Tablets:Immediate-release formulations face substitution pressure from hydroxypropyl methylcellulose where moisture barriers are unnecessary, compressing ethyl cellulose share in generic manufacturing.
- Beverages:Clouding agents and stabilization matrices in citrus and juice applications depend on food-grade emulsion compatibility.
- Cosmetics:Hair fixative films and nail coating systems leverage ethyl cellulose's alcohol solubility and flexible film formation.
Tablet coating absorbs the largest production volumes. Films are climbing the fastest as precision deposition technology penetrates formulation R&D.
End User:
Healthcare procurement operates through qualified supplier lists with 3-4 strategic partners, while food and cosmetics buyers maintain broader vendor bases and spot-market flexibility.
- Food Industry:Confectionery manufacturers in Mediterranean zones specify cellulose-derived barrier coatings under EU Green Deal agricultural sustainability mandates for biodegradable mulch film trials.
- Healthcare:CDSCO registration pathways in India are incentivizing domestic excipient production to serve Hyderabad and Ahmedabad formulation houses, reducing import dependency for USFDA-inspected facilities.
- Cosmetics Industry:Fragrance encapsulation and color cosmetic binders drive demand for cosmetic-grade powder forms with controlled particle size distribution.
- Packaging:Heat-sealable coatings for flexible packaging structures require thermal adhesion properties distinct from pharmaceutical film specifications.
Healthcare commands premium pricing tiers. Food Industry volumes are gaining share fastest through sustainability-driven specification shifts.
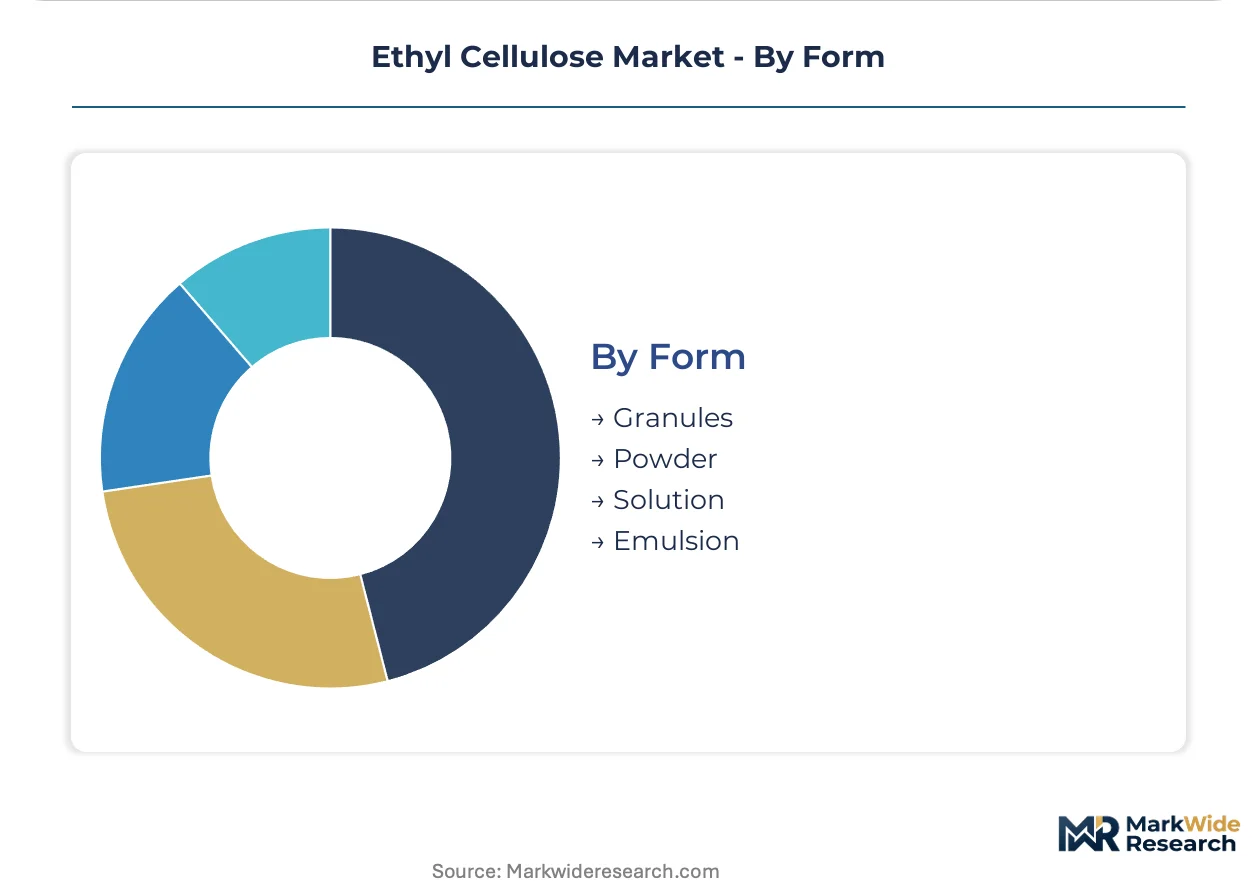
Form:
Physical form selection determines processing economics, with powder and granule shipments leading volume while solution grades capture margin in precision coating operations.
- Granules:Free-flowing agglomerates suit high-shear mixing in tablet compression and direct compression formulations where dust control and flowability are critical. German and Japanese automotive adhesive compounders prefer granule forms for controlled melt rheology in hot-melt extrusion.
- Powder:Standard-grade milled powders dominate commodity coating applications and food additive blending where dissolution kinetics are less stringent.
- Solution:Pre-dissolved grades eliminate solvent handling for microencapsulation and enteric barrier systems in pharmaceutical manufacturing.
- Emulsion:Aqueous dispersion forms serve niche applications where organic solvent elimination is mandated by workplace safety protocols.
Powder and granule forms absorb baseline manufacturing capacity. Solution grades are expanding most quickly through microencapsulation technology adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial cellulose ether production first scaled in Germany and the United States during the interwar period, establishing quality benchmarks that still govern pharmaceutical-grade specifications today. Demand now fragments across manufacturing clusters in Asia, Europe, and North America, each shaped by distinct regulatory pathways and end-use concentrations.
China
Domestic excipient production is scaling rapidly to serve local drug manufacturers and export markets under NMPA registration requirements for imported drug additives. The country's national pharmaceutical regulator is tightening documentation standards for cellulose derivatives used in controlled-release formulations. Shandong Province anchors regional supply for Asian coating manufacturers, with capacity expansion concentrated in chemical parks near Qingdao and Yantai.
Germany
Automotive interior assembly lines are qualifying ethyl cellulose-based hot-melt adhesive formulations for low-VOC bonding applications. REACH registration obligations under ECHA requirements constrain market access to qualified producers with full toxicological dossiers. The Rhine-Ruhr industrial corridor hosts concentrated ethoxylation capacity for pharmaceutical-grade production, creating single-point vulnerability for European supply security.
United States
Chronic disease management protocols are expanding prescriptions for extended-release oral dosages requiring ethyl cellulose barrier films. FDA excipient guidelines shape product specifications and testing protocols for tablet coating applications. New Jersey and Pennsylvania formulation houses are consolidating vendor lists from twelve suppliers to three or four strategic partners capable of dual-sourcing security.
India
CDSCO registration pathways for imported drug additives are incentivizing domestic ethyl cellulose production to serve formulation houses in Hyderabad and Ahmedabad. The country's national pharmaceutical regulator is streamlining inspection readiness protocols for USFDA-inspected facilities. Domestic manufacturers are capturing share from imports as generic pharmaceutical producers seek to reduce supply chain complexity.
Switzerland
Pediatric and geriatric formulation houses are adopting precision coating equipment with 18-24 month replacement cycles to integrate electrostatic spray deposition systems. Swissmedic standards for pharmaceutical starting materials govern residual solvent specifications in implantable device coatings. Basel-area R&D clusters are pioneering microencapsulation applications with sub-10-micron film thickness control for taste-masking.
Ethyl Cellulose Market Vendor Landscape
Premium-margin players sit above commodity-margin players across certification intensity, with pharmaceutical-grade specialists commanding tenfold testing premiums over industrial coating suppliers. The vendor base clusters into three tiers: integrated chemical conglomerates with captive cellulose ether units, dedicated excipient specialists with multi-jurisdictional pharmacopeial compliance, and regional toll manufacturers serving spot coating markets. Dominant competitive moves include backward integration into dissolving-grade pulp supply and technology licensing partnerships for precision coating equipment integration.
Among integrated chemical conglomerates, Ashland Global Specialty Chemicals Inc. and Eastman Chemical Company occupy positions spanning pharmaceutical and industrial grades. Shandong Head Co. Ltd. anchors regional supply for Asian markets. These three exemplify distinct strategic archetypes: the first represents North American premium-tier positioning, the second illustrates diversified specialty chemical portfolios, and the third embodies China-based scale manufacturing serving both domestic and export demand.
| Leading Market Players |
|---|
| Ashland Global Specialty Chemicals Inc. |
| Shandong Head Co. Ltd. |
| Dow Inc. |
| African Chemicals S.A.E. |
| SIDLEY CHEMICAL CO., LTD. |
| Eastman Chemical Company |
| Lotte Fine Chemicals |
| JRS PHARMA GmbH & Co. KG |
| Celanese Corporation |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade certification requirements from FDA and EMA are compressing supplier margins while concentrating procurement among excipient specialists, forcing mid-tier distributors to absorb testing cost inflation or exit multi-jurisdictional markets entirely.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial coating levels dominates the market, with certification intensity and ethoxyl content precision as primary price differentiation drivers. Cost compression in standard-grade powder forms is intensifying because HPMC substitution erodes volume share in immediate-release tablet applications. Generic pharmaceutical manufacturers in India exhibit highest price sensitivity, while implantable device coating specialists in Ireland and Denmark tolerate premium solution-grade pricing for sub-50-ppm residual solvent compliance.
Supply Chain Analysis
Regional distribution centers in the Rhine-Ruhr corridor, Qingdao-Yantai chemical parks, and New Jersey-Pennsylvania formulation clusters anchor hub-and-spoke patterns for pharmaceutical-grade ethyl cellulose. Manufacturing concentrates in Germany, China, and the United States, with dissolving-grade pulp feedstock drawn from Brazilian and South African forestry operations. Single-source vulnerability in European ethoxylation capacity creates structural risk, as the Rhine-Ruhr corridor hosts concentrated pharmaceutical-grade production. Distribution runs through qualified supplier lists with 3-4 strategic partners per healthcare procurement operation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ethyl cellulose market reads as a late-cycle quality story, with EMA tightening residual solvent specifications and formulation houses consolidating vendor lists toward dual-sourcing-capable partners.
For Market Incumbents: Deepen backward integration into dissolving-grade pulp supply to offset Brazilian harvest cycle volatility, while expanding analytical capabilities for real-time release testing to match compressed batch-release timelines from API manufacturers. HPMC substitution in immediate-release coatings and CDSCO localization incentives in India represent dual threats requiring preemptive capacity positioning in Hyderabad-Ahmedabad corridors. For New Entrants and Emerging Players: Launch via toll manufacturing partnerships with established ethoxylation facilities in Shandong Province to bypass REACH registration barriers, targeting food-grade coating applications under EU Green Deal agricultural sustainability mandates as the most penetrable white space. Precision coating equipment integration for microencapsulation offers a differentiated go-to-market angle against commodity powder suppliers. For Investors and Strategic Acquirers: Asymmetric upside sits with dedicated excipient specialists possessing multi-jurisdictional pharmacopeial compliance across USP-NF, EP, and ChP standards. Long-term viability hinges on qualification cycle capture in controlled-release formulations, with CDSCO registration completion rates in India serving as the critical inflection signal for import substitution momentum.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pulp Supply | Captive dissolving-grade pulp sourcing insulates margin from Brazilian harvest volatility. |
| Real-Time Release Testing Capability | Integrated analytical infrastructure matches API manufacturers' compressed batch-release timelines. |
| CDSCO Registration Completion | Domestic excipient certification in India captures share from import-dependent formulation houses. |
| Precision Coating Equipment Partnership | Technology licensing for electrostatic spray deposition secures solution-grade volume in microencapsulation. |
| Multi-Pharmacopeial Compliance Investment | Simultaneous USP-NF, EP, and ChP qualification prevents redundant testing costs across manufacturing footprints. |
Methodological Framework
Bottom-up pharmaceutical formulation modeling reconciled against top-down cellulose ether production tracking forms the analytical core of this study. Primary interviews with excipient procurement managers, regulatory affairs directors at API manufacturers, plant managers at ethoxylation facilities, and formulation scientists at generic pharmaceutical houses combined with secondary validation from FDA 483 inspection observations, EMA quality guideline updates, NMPA registration databases, and customs trade flows. Triangulation across these sources calibrated volume estimates against dissolving-grade pulp consumption patterns and pharmaceutical-grade capacity utilization rates.
Input-output matrices mapped ethoxyl content specifications, residual solvent thresholds, and regional regulatory clusters across the projection horizon. Segmentation dimensions included grade tier, end-use application, physical form, and regional production hub. CAGRs derived from elasticity modeling of controlled-release tablet prescription growth, HPMC substitution rates, and REACH registration completion timelines. Forecast inputs incorporated EMA solvent specification tightening trajectories and CDSCO localization incentive intensity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under pharmacopeial harmonization failure between USP-NF and ChP standards. Decision-makers should treat outputs as directional within the stated assumption set, recognizing that wood pulp supply disruptions or abrupt HPMC aqueous processing breakthroughs could materially revise trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Explosives and Pyrotechnics Market
Specialty Chemicals
Isoeicosane Market
Specialty Chemicals
Squalene Market
Specialty Chemicals
Dehazer Market
Specialty Chemicals
Stearyl Alcohol Market
Specialty Chemicals
Carnauba Wax Market
Specialty Chemicals
CMIT/MIT Market
Specialty Chemicals
Polyether Modified Silicone Market
Specialty Chemicals
Global Optical Brighteners Market
Specialty Chemicals
13X Molecular Sieve Activated Powder Market
Specialty Chemicals
Global Specialty Resins Market
Specialty Chemicals
Octofluoropropane Market
Specialty Chemicals
Australia and New Zealand Aerosol Market
Specialty Chemicals
4-Benzoylbutyric Acid Market
Specialty Chemicals
Eitelite Market
Specialty Chemicals
North America Perms and Relaxants Market