
 Global Lab Supplies Market | 2026-2036
Global Lab Supplies Market Size, Share, and Industry Trends Forecast 2026-2036
Global Lab Supplies Market Foresight
Aftermarket service revenue is narrowing as a distinct margin pool as manufacturers bundle preventive maintenance with instrument leases. Thermo Fisher Scientific leverages its global service infrastructure to capture recurring revenue across installed bases. Agilent Technologies anchors its competitive stance through chromatography consumables that lock in replacement cycles. Beckman Coulter specializes in centrifugation workflows where consumable pull-through sustains instrument placement economics.
Lab supplies encompass the instruments, consumables, and containment systems used to execute controlled experimental, analytical, and quality-assurance procedures, typically manufactured from borosilicate glass, medical-grade polymers, or corrosion-resistant alloys to withstand thermal cycling and chemical exposure. Their primary purpose is to enable reproducible measurement, sample preparation, and biological containment across research and regulated testing environments. Consumables and glassware represent the highest-velocity revenue streams where volume scale offsets thinner per-unit margins, while spectroscopy and chromatography instruments command capital-intensive procurement cycles with attached service contracts. PCR technology is displacing legacy detection methods in food safety and diagnostic applications, creating concentrated demand for thermal cycler-compatible plastics and reagent kits.
The FDA enforces quality system regulation and device labeling requirements that shape how lab instrument manufacturers validate software and calibrate optical subsystems for US market access. REACH and RoHS frameworks in Europe restrict hazardous substances in electronic lab equipment and mandate material disclosure across supply chains, compelling reformulation of coatings and solder compositions. ISO 17025 accreditation requirements from national bodies in Japan and South Korea further filter vendor eligibility for government-funded research tenders. Stakeholders must monitor how dual carbon goals in China and the EU Green Deal's embodied-carbon tracking will reshape polymer sourcing and instrument end-of-life protocols for cross-border tenders.
Market Dynamics
PCR workflows are compressing detection timelines in food safety and diagnostic labs, forcing consumable suppliers to reconfigure polymer formulations for thermal cycling compatibility while regulatory bodies tighten validation protocols.
Growth Catalysts
- High-throughput screening expansion:Pharmaceutical companies are scaling automated liquid handling workflows, pulling demand for certified low-retention pipette tips and microplates.
- EU Green Deal carbon tracking:Embodied-carbon disclosure mandates are accelerating instrument refurbishment programs and polymer recycling infrastructure investments.
- Germany CRO clustering:Contract research organizations in Munich and Heidelberg are consolidating vendor relationships around ISO 17025-certified distributors, concentrating procurement volume.
Market Restraints
- Medical-grade polymer supply concentration:Specialty resin production clusters in the US Gulf Coast and Rotterdam, exposing consumable manufacturers to feedstock volatility and force majeure risk.
- ISO 13485 compliance friction:FDA's updated quality system regulation for medical devices extends validation timelines for new instrument introductions, delaying revenue recognition.
- Legacy glassware substitution:Borosilicate demand erodes as single-use plastics capture routine analytical workflows, compressing replacement cycles for durable goods.
Strategic Opportunities
- India research infrastructure buildout:Government-funded laboratory expansion under national biotechnology missions creates tender opportunities for ISO 17025-accredited suppliers.
- Reagent kit bundling:PCR-compatible plastics paired with proprietary chemistries lock in replacement revenue and raise switching costs for diagnostic labs.
- Preventive maintenance integration:Service contracts bundled with instrument leases capture recurring revenue streams and extend customer lifetime value.
Industry Challenges
- Optical calibration expertise gap:Spectroscopy instrument deployment requires specialized field engineers capable of validating software-aligned subsystems under FDA labeling requirements.
- Cross-border polymer certification:REACH substance restrictions, RoHS hazardous material bans, and dual carbon goals in China create conflicting compliance matrices for multinational tenders.
- Chromatography consumable standardization:Proprietary column formats from dominant suppliers fragment procurement, forcing labs to maintain redundant inventory across instrument platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Lab Supplies Market |
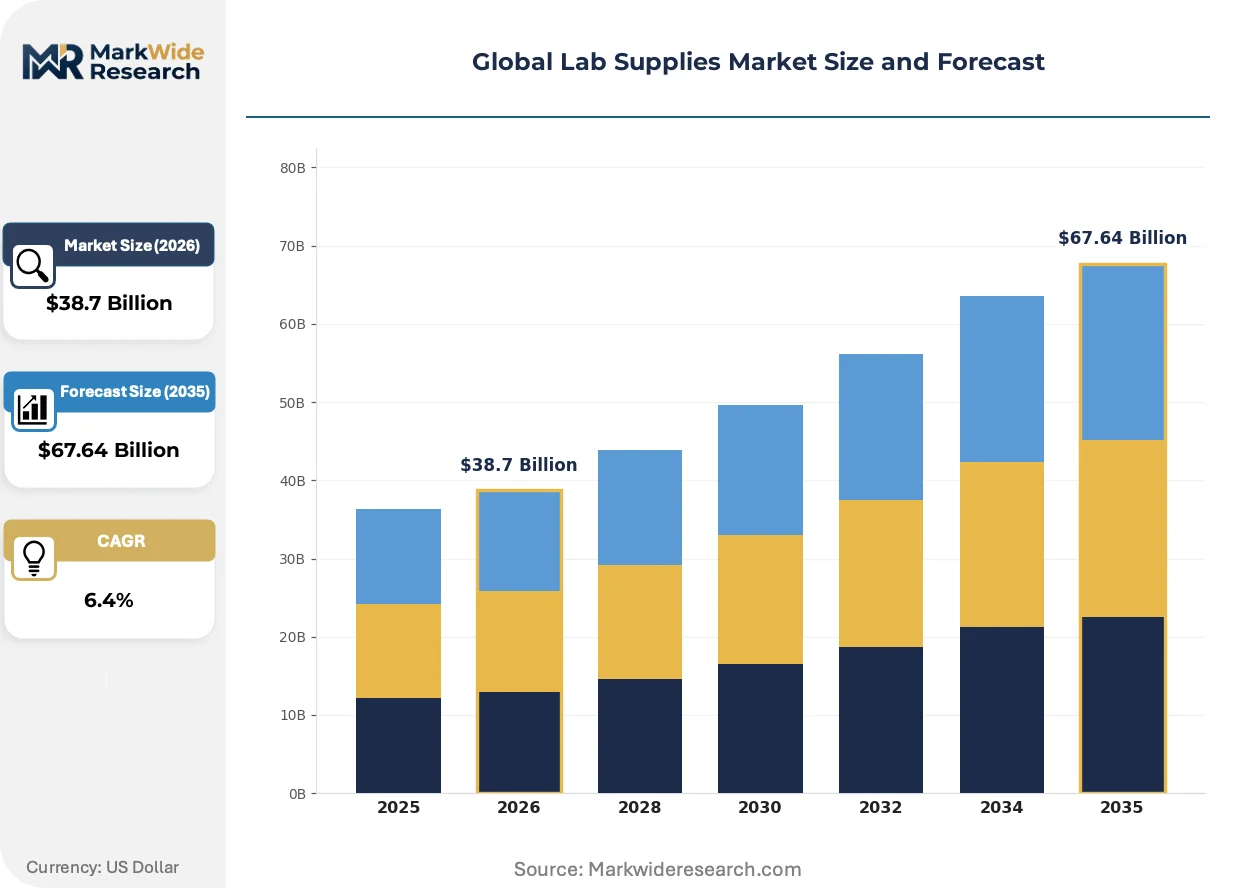
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glassware, Plasticware, Lab Instruments, Consumables, Storage Containers Technology: Centrifugation, Spectroscopy, Chromatography, Microscopy, PCR End User: Research Institutes, Pharmaceutical Companies, Biotechnology Firms, Food Testing Labs, Forensic Labs Distribution Channel: Direct Sales, Online Retailers, Distributors, Specialty Stores, Wholesalers |
| Companies Covered | Beckman Coulter, PerkinElmer, Thermo Fisher Scientific, VWR International, Bruker Corporation, Agilent Technologies, Waters Corporation, Bio-Rad Laboratories, Mettler Toledo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Lab Supplies Market Shifts & Advancements
Workflow automation and regulatory disclosure requirements are converging to reshape how consumables are specified, validated, and replaced across research and regulated testing environments.
Digital PCR platforms are migrating from research-only installations into clinical diagnostic workflows, enabling absolute quantification without standard curves. Hospital laboratories in the US and EU are adopting these systems for liquid biopsy monitoring, compressing the validation timelines that manufacturers must maintain under FDA and EMA guidance. The technology is migrating from high-complexity reference labs toward decentralized testing sites, forcing consumable suppliers to develop shelf-stable reagent formats.
REACH authorization requirements for persistent organic pollutants are restricting fluoropolymer use in lab equipment seals and coatings. ECHA's sunset date enforcement is compelling manufacturers to reformulate with perfluoroalkyl-free alternatives, particularly affecting chromatography instrument wetted components. European analytical labs are responding by demanding material disclosure certificates that trace polymer provenance through tier-three suppliers.
Consolidated procurement through group purchasing organizations is displacing direct vendor relationships in academic and government research segments. Large university systems in the US and national research councils in the UK are centralizing consumable buying, extracting volume discounts while reducing supplier counts. This concentration is most visible in Germany, where Max Planck Institute networks have standardized centrifugation consumables across distributed facilities.
Global Lab Supplies Market Segmentation
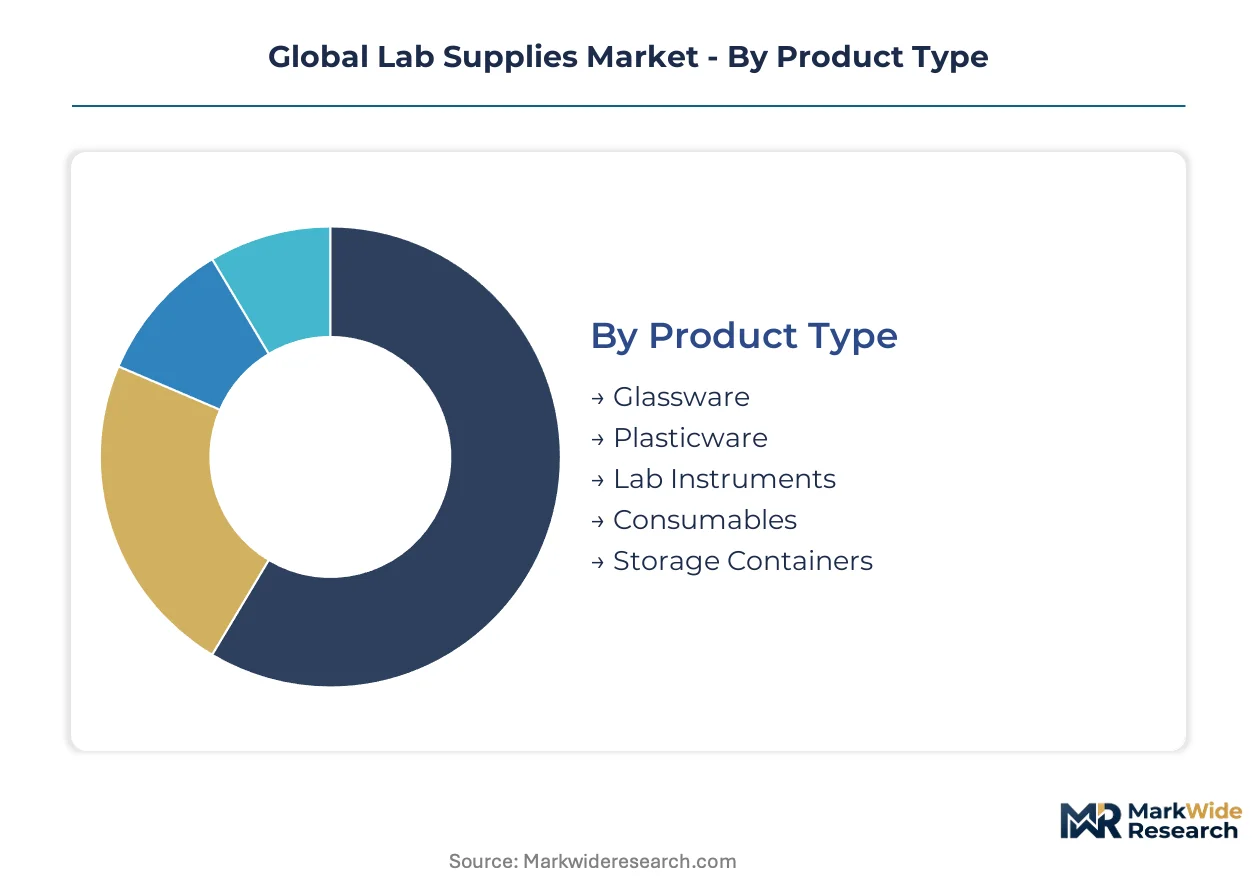
Segmentation in lab supplies reveals how procurement priorities diverge across experimental workflows, regulatory environments, and capital deployment strategies. Each dimension exposes distinct margin structures and vendor lock-in mechanisms that shape competitive positioning.
Product Type:
Material selection traces directly to thermal cycling demands, chemical exposure profiles, and single-use versus durability trade-offs across analytical and biological applications.
- Consumables:Certified low-retention pipette tips, microplates, and reagent kits dominate high-throughput pharmaceutical workflows. Demand concentrates in automated liquid handling installations where validation protocols from the FDA and ISO 17025 bodies filter vendor eligibility.
- Lab Instruments:Spectrometers, thermal cyclers, and centrifuges command capital-intensive procurement cycles with attached preventive maintenance contracts. Germany's CRO clusters in Munich and Heidelberg are consolidating vendor relationships around ISO-certified distributors for these placements.
- Plasticware:PCR-compatible polymers and thermal cycling-resistant formulations displace glass in routine diagnostics. REACH restrictions on fluoropolymers are forcing reformulation of seals and coatings.
- Glassware:Borosilicate beakers and flasks retain share in thermal shock applications but face erosion from single-use alternatives. Academic labs in India under national biotechnology missions sustain tender demand.
- Storage Containers:Medical-grade polymer vials and cryogenic preservation systems serve biobanking and clinical sample workflows. Cold chain logistics requirements shape specification criteria.
The dominant share belongs to consumables, while lab instruments capture the steepest expansion trajectory through bundled service contracts.
Technology:
Detection and separation modalities stratify by capital intensity, consumable pull-through economics, and the regulatory validation burden for clinical deployment.
- PCR:Digital platforms are migrating from research-only installations into clinical diagnostics for liquid biopsy monitoring, compressing FDA and EMA validation timelines. Consumable suppliers must develop shelf-stable reagent formats for decentralized testing sites.
- Chromatography:Proprietary column formats from dominant suppliers fragment procurement and force redundant inventory maintenance. Agilent Technologies anchors competitive stance through consumables that lock in replacement cycles.
- Spectroscopy:Optical calibration expertise gaps constrain field deployment, with FDA labeling requirements demanding software-aligned subsystem validation.
- Centrifugation:Beckman Coulter specializes in workflows where consumable pull-through sustains instrument placement economics. Max Planck Institute networks in Germany have standardized consumables across distributed facilities.
- Microscopy:Advanced imaging systems serve materials science and pathology applications with attached service revenue streams narrowing as distinct margin pools.
PCR commands the fastest volume growth, though chromatography retains the deepest consumable lock-in per installed base.
End User:
Procurement authority and specification rigor vary sharply across funded research, regulated manufacturing, and statutory testing environments.
- Pharmaceutical Companies:Automated high-throughput screening workflows pull demand for certified consumables and integrated liquid handling systems. Procurement teams prioritize ISO 13485-aligned suppliers under FDA quality system regulation pressure.
- Research Institutes:Consolidated buying through group purchasing organizations displaces direct vendor relationships in US university systems and UK national research councils. Volume discounts reduce supplier counts.
- Biotechnology Firms:Cell culture and bioprocessing applications demand medical-grade polymer containment with material disclosure certificates tracing provenance through tier-three suppliers.
- Food Testing Labs:PCR workflows are compressing detection timelines, forcing consumable reconfiguration for thermal cycling compatibility while regulatory bodies tighten validation protocols.
- Forensic Labs:Chain-of-custody requirements and contamination controls drive specification for certified low-retention consumables and validated instrument platforms.
Pharmaceutical companies anchor revenue concentration, while food testing labs are expanding procurement most aggressively.
Distribution Channel:
Channel selection reflects order fragmentation, technical support requirements, and the geographic concentration of end-user clusters.
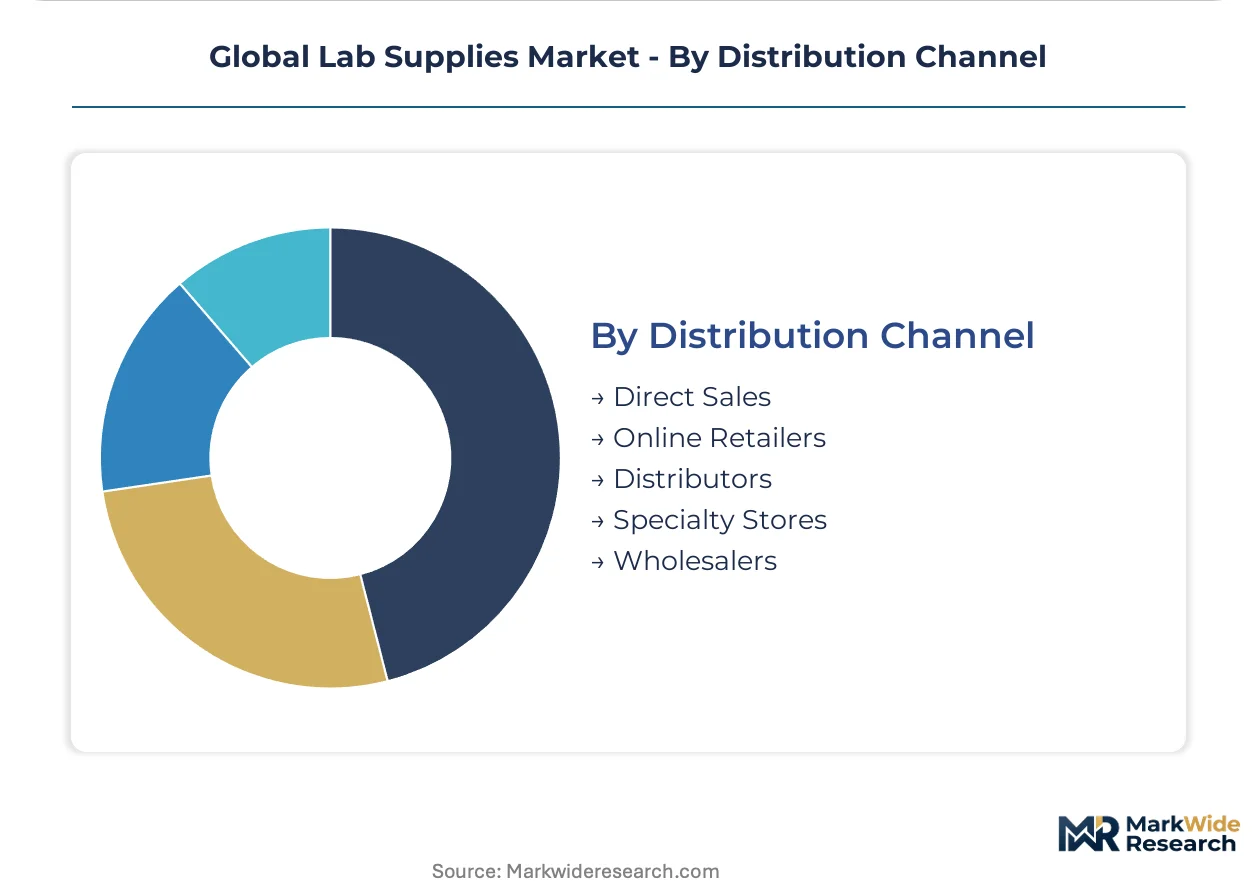
- Distributors:ISO 17025-certified distributors in Germany concentrate procurement volume from CRO clusters, capturing value-add through technical specification support and inventory consolidation.
- Direct Sales:Instrument manufacturers deploy global service infrastructure to capture recurring revenue across installed bases, bundling preventive maintenance with capital placements.
- Online Retailers:Routine consumable replenishment shifts to digital channels in academic and smaller commercial labs, compressing margin capture for traditional field sales.
- Specialty Stores:Regional suppliers serve localized research clusters with rapid-turn fulfillment for urgent experimental requirements.
- Wholesalers:Volume aggregation for standard plasticware and glassware serves price-sensitive segments with thinner technical support overlays.
Distributors hold the deepest penetration in regulated European markets, while direct sales are gaining share fastest through instrument-service bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany deploys lab supplies predominantly within contract research workflows, while the United States concentrates procurement in pharmaceutical high-throughput screening and India channels investment toward government-funded biotechnology infrastructure expansion.
United States
Pharmaceutical companies in Massachusetts and New Jersey drive automated liquid handling demand for certified low-retention consumables. FDA quality system regulation updates extend validation timelines for new instrument introductions. The Research Triangle Park cluster in North Carolina consolidates vendor relationships around ISO 13485-aligned suppliers.
Germany
Contract research organizations in Munich and Heidelberg concentrate procurement volume for chromatography and centrifugation workflows. EU Green Deal embodied-carbon tracking mandates accelerate instrument refurbishment programs. The Rhine-Main biotech corridor standardizes consumable specifications across distributed Max Planck Institute facilities.
China
Dual carbon goals reshape polymer sourcing protocols for cross-border tenders in analytical instrument manufacturing. NMPA medical device regulations align with international quality system standards. The Yangtze River Delta biopharma cluster drives demand for medical-grade polymer containment systems.
India
Government-funded laboratory expansion under national biotechnology missions creates tender opportunities for ISO 17025-accredited suppliers. CDSCO medical device rules tighten quality system requirements for diagnostic instrument imports. The Genome Valley cluster in Telangana anchors bioprocessing consumable demand.
Japan
PMDA validation requirements for clinical diagnostic platforms compress timelines for PCR-compatible consumable introductions. METI research infrastructure programs fund advanced microscopy and spectroscopy installations. The Kansai pharmaceutical corridor in Osaka sustains chromatography consumable procurement.
Global Lab Supplies Market Competitive Landscape
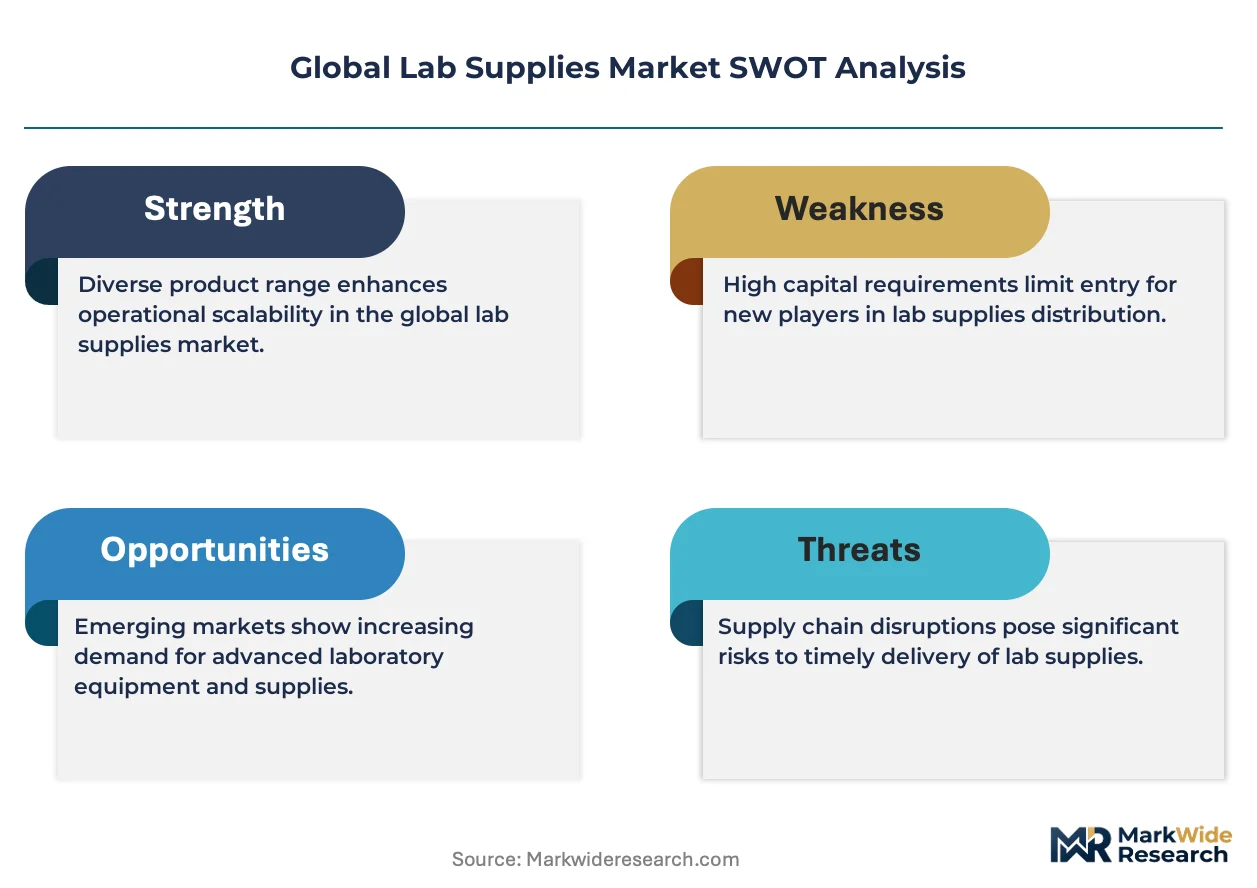
Capability concentration sits with specialized instrument manufacturers; scale advantage sits with diversified life science conglomerates. The market structures around three tiers: integrated conglomerates bundling service contracts with capital placements, focused instrument specialists anchoring consumable lock-in strategies, and regional distributors capturing value through ISO certification overlays. Dominant competitive moves include preventive maintenance bundling with instrument leases and reagent kit pairing with proprietary plastics.
Among integrated life science conglomerates, Thermo Fisher Scientific and Agilent Technologies exemplify archetypes that leverage global service infrastructure and chromatography consumable ecosystems respectively. Beckman Coulter occupies a position within the centrifugation specialist tier where consumable pull-through sustains instrument economics. These three represent distinct strategic postures: scale-driven service integration, technology-specific consumable lock-in, and workflow-anchored placement models.
| Leading Market Players |
|---|
| Beckman Coulter |
| PerkinElmer |
| Thermo Fisher Scientific |
| VWR International |
| Bruker Corporation |
| Agilent Technologies |
| Waters Corporation |
| Bio-Rad Laboratories |
| Mettler Toledo |
| Others |
Supply & Pricing Matrix
Rotterdam's medical-grade polymer production clusters anchor European consumable supply, with capacity utilization swings directly transmitted to downstream pricing power for pipette tips and microplate manufacturers serving pharmaceutical workflows.
Pricing Analysis
Long-term offtake contracts dominate instrument procurement, while spot purchasing prevails for routine consumable replenishment. Three-tier pricing structure across premium, standard, and economy levels separates ISO 17025-certified distributors from uncertified wholesalers. Cost compression in standard-grade plasticware is intensifying because academic labs consolidate buying through group purchasing organizations. Biotechnology firms show lowest price sensitivity due to validation protocol lock-in, whereas smaller commercial testing labs prioritize economy tiers.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for electronic lab equipment manufacturers. Specialty resin production concentrates in the US Gulf Coast, Rotterdam, and Singapore, with consumable manufacturing drawing from these hubs. Borosilicate glass feedstocks, medical-grade polypropylene, and fluoropolymer alternatives constitute critical input dependencies. Single-source vulnerability persists for thermal cycler-compatible polymer formulations. Distribution runs through ISO-certified distributors in Germany, direct sales for capital instruments, and online channels for routine replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Lab Supplies Market sits at a platform-economics inflection where consumable-instrument bundling creates ecosystem lock-in comparable to printer-ink models, with PCR reagent-plastic pairing exemplifying the interoperability shift.
For Market Incumbents: Build switching-cost moats through preventive maintenance integration with instrument leases. Thermo Fisher Scientific's global service infrastructure demonstrates how captive maintenance contracts extend customer lifetime value. Agilent Technologies anchors positioning through proprietary chromatography column formats that fragment procurement and force redundant inventory. ISO 13485 certification investment filters competitor access to FDA-regulated medical device tenders.
For New Entrants and Emerging Players: Build out shelf-stable reagent formats for decentralized digital PCR testing sites migrating from reference labs. India's government-funded biotechnology missions under national infrastructure expansion present the most penetrable tender environment. Food safety testing labs in Asia-Pacific offer white-space opportunity as PCR workflows compress detection timelines. Partner with ISO 17025-accredited distributors to bypass direct sales infrastructure requirements.
For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue play because consumable pull-through economics sustain instrument placement returns across decade-long installed base lifecycles. Target acquisition candidates include centrifugation workflow specialists with consumable lock-in models comparable to Beckman Coulter's positioning. Monitor FDA quality system regulation enforcement intensity as inflection signal for compliance-cost barriers.
| Strategic Initiative | Industry Significance |
|---|---|
| Preventive Maintenance Bundling | Captures recurring revenue streams across thermal cycler and centrifuge installed bases under FDA quality system oversight. |
| Reagent Kit Pairing | Locks diagnostic labs into proprietary PCR-compatible plastics with shelf-stable chemistries that raise switching costs. |
| ISO 17025 Accreditation Investment | Filters vendor eligibility for Germany CRO clusters and India government-funded biotechnology mission tenders. |
| Fluoropolymer Reformulation | Addresses REACH sunset date enforcement for persistent organic pollutants in chromatography instrument wetted components. |
| Instrument Refurbishment Programs | Aligns with EU Green Deal embodied-carbon tracking mandates for analytical equipment cross-border procurement. |
Research Methodology
A standing panel of laboratory procurement managers, biomedical engineers, GPO contracts directors, and regulatory affairs specialists provided ongoing calibration against operating reality. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) filings, EMA medical device registrations, ISO certification databases, and customs trade records. Bottom-up segment sizing triangulated against top-down market aggregation across product type, technology modality, end-user category, and distribution channel dimensions.
Scenario-bracketing framed volume and value outputs across the projection horizon, with base, optimistic, and conservative cases reflecting differential assumptions for pharmaceutical R&D expenditure trajectories and diagnostic testing demand elasticity. Segmentation modeling captured consumable velocity, instrument capital cycles, service contract attach rates, and geographic regulatory cluster variations. CAGRs derived from fitted growth curves applied to validated baseline estimates, with cross-checks against disclosed instrument placement data and reagent kit revenue disclosures.
Stress conditions across medical-grade polymer feedstock volatility, FDA validation timeline extensions, and EU carbon border adjustment implementation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about CRO procurement consolidation rates and academic lab funding trajectories. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Equipment
Global Laboratory Analytical Instruments and Consumables Market
Testing Equipment
Paint Tester Market
Testing Equipment
Paper Tester Market
Testing Equipment
Global Silica Analyzer Market
Testing Equipment
Laboratory Balances and Scales Market
Testing Equipment
Global Asbestos Testing Market
Testing Equipment
Material Tester Market
Testing Equipment
Clean-Up Gel Permeation Chromatography Market
Testing Equipment
Ambient Temperature Gel Permeation Chromatography Market
Testing Equipment
US Eddy-Current Testing Market
Testing Equipment
Global Film Thickness Measurement Market
Testing Equipment
Combustion Testing Equipment Market
Testing Equipment
Laboratory Ware Market
Testing Equipment
Cone Calorimeter Market
Testing Equipment
Fibrin Degradation Product (Fndp) Assays Market
Testing Equipment
In-Line UV-Vis Spectroscopy Market