
 US Pharmaceutical Glycerin Based Products Market | 2026-2036
US Pharmaceutical Glycerin Based Products Market Size, Share, and Industry Trends Forecast 2026-2036
US Pharmaceutical Glycerin Based Products Market Insights
Midwest bio-refinery expansion is reshaping domestic glycerin availability for pharmaceutical applications. Cargill Inc. leverages its integrated agricultural processing network to secure consistent feedstock supply. BASF SE anchors its position through specialized high-purity glycerin derivatives for sensitive formulations. Stepan Company differentiates via controlled manufacturing protocols that meet stringent injectable-grade specifications.
Pharmaceutical glycerin based products encompass refined glycerol formulations exceeding 99.5% purity, functioning as humectants, solvents, and stabilizers in drug delivery systems manufactured through multi-stage distillation and activated carbon filtration processes. Oral medications and topical applications command the largest addressable bases within the use case dimension, while home healthcare channels are expanding fastest among end user categories as patient-administered therapies gain preference. Syrups retain mature volume dominance though emulsions present concentrated margin pools due to complex formulation requirements.
FDA Current Good Manufacturing Practice regulations and USP-NF monograph standards govern pharmaceutical glycerin identity, strength, and purity, with EPA wastewater discharge rules affecting refinery siting decisions. The Drug Supply Chain Security Act traceability mandates are reshaping how glycerin lots move through pharmaceutical packaging and distribution networks. Stakeholders must monitor evolving USP compendial updates and state-level pharmacy compounding rules to anticipate specification shifts before they disrupt formulation approvals.
Market Dynamics
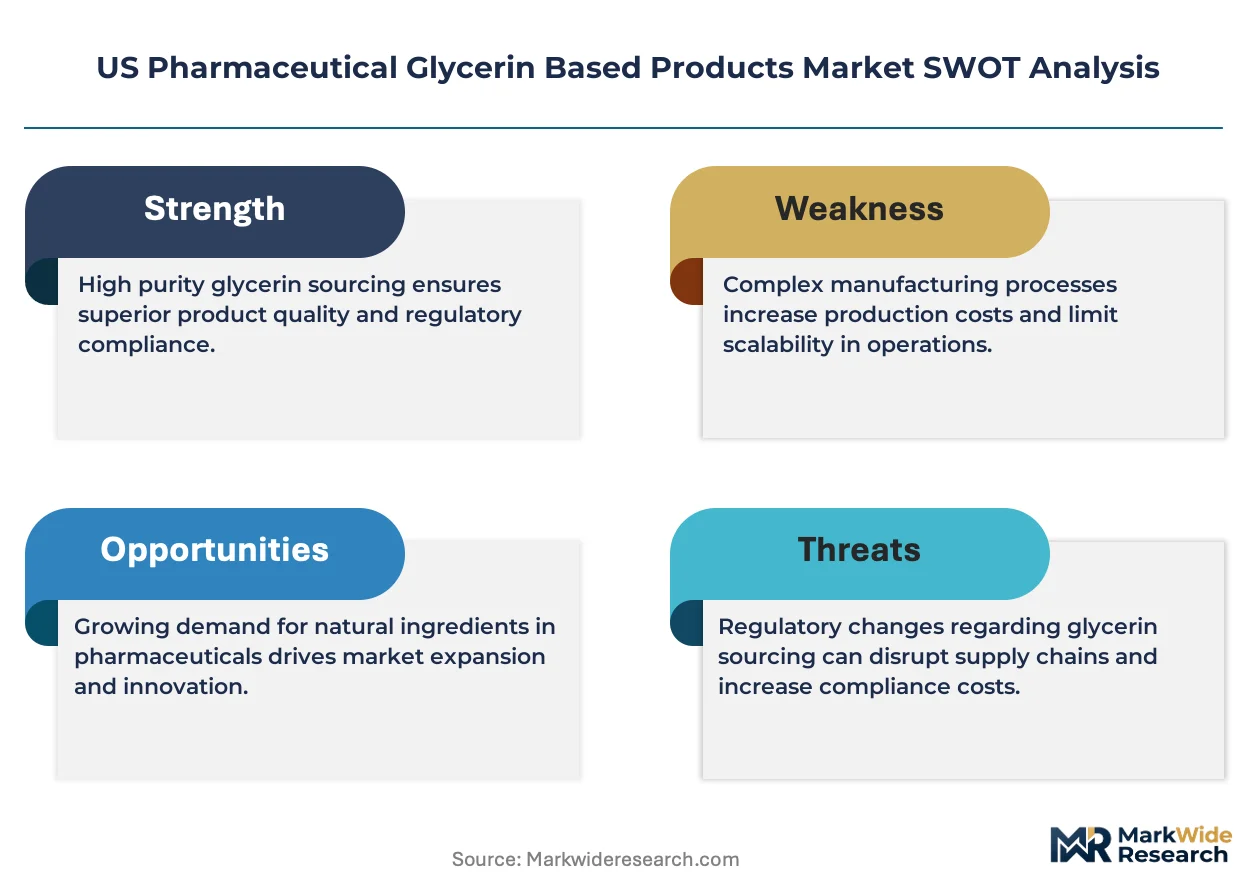
FDA purity standard escalations are compressing supplier margins while simultaneously consolidating the qualified vendor base, as multi-stage distillation and activated carbon filtration investments separate capable refiners from marginal operators.
Growth Catalysts
- Oral medication formulation demand:Liquid drug manufacturers favor glycerin as a humectant and solvent in syrups and suspensions, with hospital and pharmacy channels absorbing rising volumes across the Northeast and California.
- Drug Supply Chain Security Act traceability:Lot-level tracking mandates are reshaping pharmaceutical packaging and distribution networks, creating specification-compliant glycerin demand from serialization-ready suppliers.
- Home healthcare channel expansion:Patient-administered therapies are accelerating glycerin-based topical and oral product consumption outside institutional settings.
Market Restraints
- Crude glycerin feedstock volatility:Biodiesel production fluctuations create price instability for refined glycerol inputs, pressuring contract margin predictability for pharmaceutical-grade suppliers.
- Midwest supply concentration:Bio-refinery capacity clusters in agricultural processing corridors, exposing formulation manufacturers to regional logistics disruptions and single-source dependencies.
- Substitution by propylene glycol:Synthetic alternatives compete in select topical and parenteral applications where hygroscopic performance requirements permit formulation flexibility.
Strategic Opportunities
- Injectable-grade specification premium:Controlled manufacturing protocols meeting stringent parenteral standards command concentrated margin pools beyond standard pharmaceutical grades.
- Emulsion formulation complexity:Multi-phase drug delivery systems require specialized glycerin derivatives, creating technical differentiation avenues for high-purity refiners.
- USP-NF monograph anticipation services:Stakeholders monitoring compendial updates ahead of specification shifts can secure first-mover positioning in reformulation partnerships.
Industry Challenges
- Activated carbon filtration capex cycles:Upgrading refining capabilities to meet tightening quality benchmarks demands substantial capital deployment with extended payback horizons.
- EPA wastewater discharge compliance:Refinery siting decisions face environmental permitting complexity that delays capacity expansion timelines.
- State pharmacy compounding rule fragmentation:Multi-jurisdictional regulatory tracking burdens quality assurance functions with non-harmonized specification monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Pharmaceutical Glycerin Based Products Market |
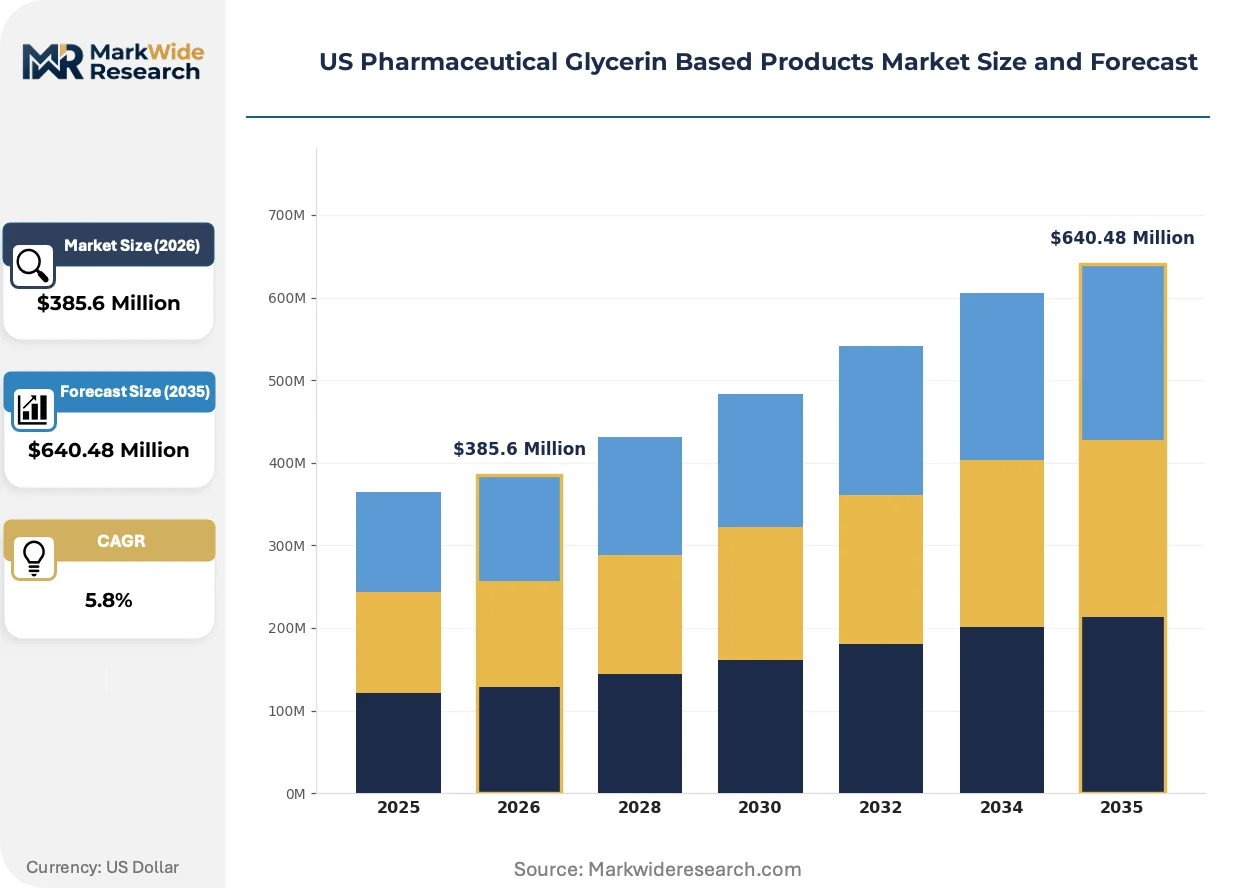
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $640.48 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Syrups, Ointments, Solutions, Emulsions Use Case: Topical Applications, Oral Medications, Rectal Formulations, Inhalation Therapies End User: Hospitals, Pharmacies, Clinics, Home Healthcare Packaging Type: Glass Bottles, Plastic Containers, Blister Packs, Bulk Packaging |
| Companies Covered | Cargill Inc., Dow Inc., BASF SE, Wilmar International, Emery Oleochemicals, Kao Corporation, Stepan Company, Archer Daniels Midland Company, Glycerin Products LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Pharmaceutical Glycerin Based Products Market Trends and Innovations
Multi-stage molecular distillation systems are replacing conventional refining architectures, compressing impurity profiles while reducing solvent consumption. These process intensification approaches are redrawing technical barriers to entry.
Membrane separation technology is rendering obsolete energy-intensive evaporative concentration steps in glycerin purification workflows. Specialized high-purity derivative manufacturers are adopting ceramic and polymeric membrane systems at pilot scale. This transition is compressing per-unit production costs while tightening specification consistency for sensitive parenteral formulations.
FDA Current Good Manufacturing Practice regulations are mandating enhanced process analytical technology integration across pharmaceutical excipient supply chains. Real-time release testing protocols are displacing offline quality verification, accelerating batch release timelines. Injectable-grade glycerin suppliers face the steepest compliance investment requirements as aseptic processing standards extend upstream to excipient characterization.
Hospital procurement consolidation is compressing supplier rosters through centralized contracting mechanisms, with integrated delivery networks demanding volume commitments and technical service bundling. Regional group purchasing organizations are displacing direct manufacturer relationships for standard-grade glycerin formulations. This concentration is most visible in the Northeast corridor, where health system mergers have reduced active vendor panels by half.
US Pharmaceutical Glycerin Based Products Market Segmentation
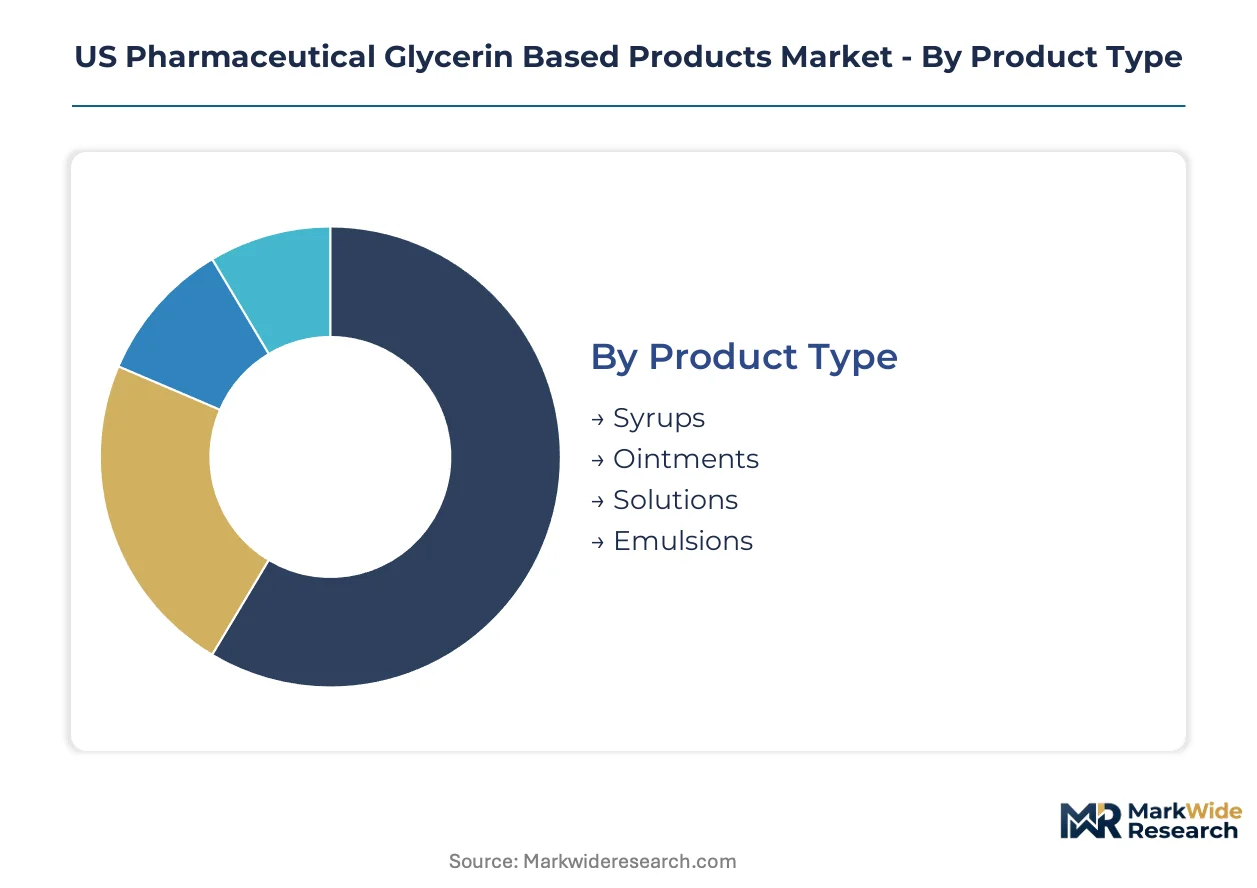
Segmentation reveals how glycerin purity grades and formulation complexity create divergent margin structures across the US pharmaceutical supply chain. Each dimension carries distinct regulatory burdens and customer procurement behaviors that reshape competitive positioning.
Product Type:
Formulation complexity determines margin stratification, with multi-phase systems commanding specification premiums over single-phase alternatives.
- Syrups:Liquid oral formulations incorporating glycerin as a humectant and viscosity modifier dominate hospital and pharmacy procurement volumes. Northeast health system consolidation has compressed supplier rosters for standard-grade syrup excipients, favoring refiners with serialization-ready lot tracking.
- Emulsions:Multi-phase drug delivery systems require specialized high-purity glycerin derivatives with controlled impurity profiles. California formulation manufacturers absorb concentrated volumes for dermatological and parenteral applications where hygroscopic stability is critical.
- Ointments:Semi-solid topical bases leverage glycerin's occlusive properties for wound care and dermatology segments.
- Solutions:Aqueous formulations for oral and topical administration represent mature volume demand with standardized USP-NF specifications.
Syrups hold installed capacity. Emulsions are rotating up the share rankings.
Use Case:
Application route dictates purity thresholds, with mucosal and parenteral exposures demanding stricter specification compliance than external applications.
- Oral Medications:Liquid drug manufacturers across the Northeast and California favor glycerin as a solvent and stabilizer in suspensions and elixirs. FDA Current Good Manufacturing Practice regulations for excipient characterization are extending upstream compliance burdens to syrup-grade suppliers.
- Topical Applications:Dermatological and wound care formulations utilize glycerin's humectant properties for moisture retention. Home healthcare channel expansion is accelerating patient-administered topical consumption outside institutional settings.
- Rectal Formulations:Suppository and enema applications require pharmaceutical-grade glycerin with specific melting point characteristics.
- Inhalation Therapies:Nebulized and respiratory formulations impose the most stringent particulate and endotoxin specifications on glycerin inputs.
Oral medications anchor volume demand. Inhalation therapies are climbing the fastest as biologic aerosol formulations proliferate.
End User:
Procurement concentration varies sharply by care setting, with consolidated health systems exerting pricing leverage that fragmented retail channels cannot replicate.
- Hospitals:Integrated delivery networks in the Northeast corridor have reduced active glycerin vendor panels by half through centralized contracting mechanisms. These institutions demand volume commitments bundled with technical service and regulatory documentation support.
- Home Healthcare:Patient-administered therapies are expanding fastest among end user categories as chronic disease management shifts outside institutional boundaries. This rotation pressures packaging formats toward unit-dose and patient-friendly designs.
- Pharmacies:Retail and specialty pharmacy channels absorb standard-grade glycerin-based products with established USP-NF monograph compliance.
- Clinics:Outpatient settings procure smaller lot sizes with flexible delivery schedules for compounded preparations.
Hospitals concentrate purchasing power. Home healthcare is gaining share fastest as site-of-care economics reshape prescribing patterns.
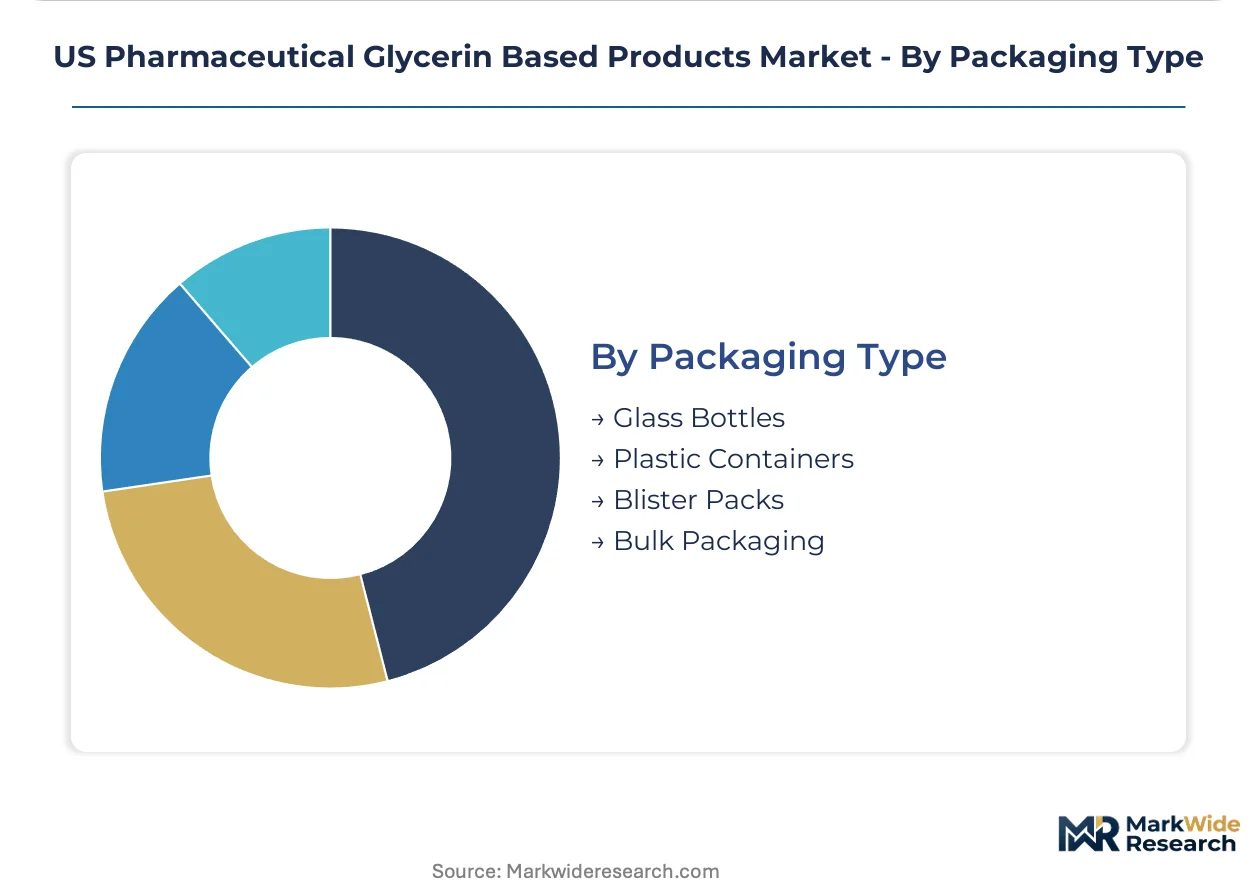
Packaging Type:
Material selection reflects stability requirements and regulatory serialization mandates that vary by distribution channel and product risk classification.
- Glass Bottles:Amber and clear glass containers dominate light-sensitive and high-value formulations requiring inert contact surfaces. Parenteral and ophthalmic applications in California manufacturing clusters specify borosilicate glass for glycerin-based solutions.
- Plastic Containers:HDPE and PET formats serve cost-sensitive oral and topical products with shorter shelf-life requirements. Drug Supply Chain Security Act traceability mandates are reshaping how plastic-containered glycerin lots move through distribution networks.
- Blister Packs:Unit-dose configurations support compliance packaging for institutional and retail pharmacy dispensing.
- Bulk Packaging:Intermediate bulk containers and drums supply compounding pharmacies and manufacturing facilities with multi-batch glycerin requirements.
Glass bottles maintain premium positioning. Plastic containers are expanding most quickly as serialization infrastructure commoditizes traceability compliance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA Current Good Manufacturing Practice regulations anchor pharmaceutical glycerin demand concentration across US sub-regions, with integrated delivery networks and bio-refinery corridors dictating procurement patterns and supplier qualification requirements.
Northeast Corridor
Hospital system consolidation in Massachusetts, New York, and Pennsylvania compresses glycerin vendor rosters through centralized contracting mechanisms. FDA Drug Supply Chain Security Act traceability mandates reshape lot-level tracking for serialization-ready suppliers serving institutional pharmacies. Boston and Philadelphia manufacturing clusters absorb concentrated volumes of high-purity glycerin for parenteral formulations.
California
Biopharmaceutical formulation manufacturers in San Diego and San Francisco Bay Area drive demand for specialized glycerin derivatives in dermatological and inhalation therapies. EPA wastewater discharge rules delay refinery expansion timelines in Central Valley agricultural processing zones. Los Angeles and Orange County compounding pharmacies source USP-NF grade glycerin for patient-customized preparations.
Midwest
Bio-refinery capacity clusters in Illinois, Iowa, and Minnesota expose formulation manufacturers to regional logistics dependencies and single-source feedstock vulnerabilities. USDA biofuel program incentives influence biodiesel production fluctuations that cascade into crude glycerin price volatility. Chicago and Minneapolis pharmaceutical packaging facilities process rising volumes of glycerin-based syrups for national distribution.
Southeast
Home healthcare channel expansion in Florida and Georgia accelerates patient-administered topical and oral glycerin product consumption outside institutional settings. State pharmacy compounding rule fragmentation burdens quality assurance with non-harmonized specification monitoring across jurisdictions. Atlanta and Research Triangle Park formulation development centers test multi-phase emulsion systems requiring controlled impurity profiles.
Pacific Northwest
Membrane separation technology pilot programs in Washington and Oregon compress per-unit glycerin production costs while tightening specification consistency. Environmental permitting complexity for refinery siting delays capacity expansion in Columbia River industrial corridors. Seattle and Portland pharmaceutical contract manufacturers source injectable-grade glycerin for aseptic processing applications.
US Pharmaceutical Glycerin Based Products Market Competitive Landscape
Integrated agricultural processors and specialized chemical refiners split the market between feedstock security and purity-grade specialization. Supplier consolidation accelerates as multi-stage distillation investments separate capable refiners from marginal operators. Three archetypes dominate: crop-based integrated processors, petrochemical-derived specialists, and toll-refining service providers. Competitive moves center on backward integration into biodiesel feedstock streams and technology licensing for membrane purification systems.
Within the integrated-processor tier, Cargill Inc. and Archer Daniels Midland Company represent agricultural network leverage strategies that secure consistent feedstock supply across Midwest corridors. BASF SE anchors the specialty-chemical archetype through high-purity derivative positioning. Stepan Company exemplifies controlled-manufacturing protocol differentiation for stringent parenteral-grade specifications. These three occupy positions that reflect divergent capital deployment priorities: upstream agricultural asset control versus downstream purification technology specialization versus formulation partnership depth.
| Leading Market Players |
|---|
| Cargill Inc. |
| Dow Inc. |
| BASF SE |
| Wilmar International |
| Emery Oleochemicals |
| Kao Corporation |
| Stepan Company |
| Archer Daniels Midland Company |
| Glycerin Products LLC |
| Others |
Pricing and Supply Chain Analysis
Midwest bio-refinery undercapacity relative to Northeast and California formulation demand compresses supplier pricing power while simultaneously rewarding serialization-ready vendors with volume commitments. This utilization asymmetry forces refiners to prioritize contract structures that lock in offtake before committing distillation capex.
Pricing Analysis
Geographic price spreads between Illinois bio-refinery corridors and California formulation clusters reflect logistics premiums and purity-grade stratification. Three-tier pricing structure across injectable-grade, pharmaceutical-grade, and technical-grade levels separates Cargill and BASF SE positioning from toll refiners. Cost compression in standard pharmaceutical grades is intensifying because crude glycerin feedstock volatility cascades from biodiesel production fluctuations. Hospital procurement consolidation renders integrated delivery networks least price-sensitive while compounding pharmacies absorb margin pressure most acutely.
Supply Chain Analysis
Export-control regimes limiting specialized membrane separation technology flows constrain domestic adoption timelines for energy-intensive purification alternatives. Supply concentrates in the US Midwest bio-refinery corridor, with secondary sourcing from European specialty chemical producers and Southeast Asian oleochemical operations. Refined glycerin production rests on crude glycerin from biodiesel transesterification, activated carbon filtration media, and multi-stage distillation equipment. Single-source vulnerability pervades the Midwest feedstock cluster where agricultural processing networks dominate. Distribution runs through pharmaceutical packaging facilities in Chicago and Minneapolis for national hospital and pharmacy channel fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Injectable-grade purification capability represents the scarcest technical asset in this market, with multi-stage molecular distillation expertise concentrated among Stepan Company and a handful of specialized refiners. This skill gap separates margin-capture leaders from commodity-positioned competitors.
For Market Incumbents: Entrench serialization-ready lot tracking infrastructure ahead of FDA Drug Supply Chain Security Act enforcement waves. Deepen backward integration into Midwest biodiesel feedstock streams to secure crude glycerin supply predictability against USDA biofuel program volatility. Capacity addition in Pacific Northwest membrane technology corridors offers geographic diversification from Illinois-Iowa concentration risk.
For New Entrants and Emerging Players: Injectable-grade specification gaps in California biopharmaceutical clusters represent the most penetrable entry point for qualified refiners seeking premium positioning. Home healthcare channel packaging format innovation—unit-dose and patient-friendly designs—offers white-space acceleration as site-of-care economics reshape prescribing patterns. Partner with regional group purchasing organizations in the Northeast corridor to bypass entrenched hospital vendor panels.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among refiners with injectable-grade certification and long-term offtake agreements with integrated delivery networks. Long-term viability over the next decade hinges on membrane separation technology adoption timelines and EPA wastewater discharge permitting agility. Watch for FDA USP-NF monograph specification shifts as inflection indicators forcing reformulation partnerships and supplier requalification cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Biodiesel Feedstock | Cargill and ADM secure crude glycerin supply predictability against USDA program volatility. |
| Membrane Separation Technology Licensing | Pacific Northwest pilot programs compress per-unit production costs for parenteral-grade specifications. |
| Injectable-Grade Certification Investment | Stepan Company commands concentrated margin pools beyond standard pharmaceutical grades. |
| Serialization-Ready Lot Tracking Infrastructure | FDA Drug Supply Chain Security Act mandates reshape pharmaceutical packaging network requirements. |
| Long-Term Supply Agreement with IDNs | Northeast health system consolidation favors refiners with volume commitment and technical service bundling. |
Research Methodology
A spread of perspectives from pharmaceutical formulation executives, bio-refinery operations managers, hospital procurement directors, and FDA regulatory affairs specialists converged on the working assumptions driving this analysis. Primary interviews with these stakeholders combined with secondary validation against FDA Current Good Manufacturing Practice guidance documents, USP-NF monograph standards, EPA wastewater discharge filings, and SEC 10-K disclosures from publicly traded agricultural processors. Bottom-up demand modeling across oral medication, topical application, and parenteral formulation use cases triangulated with top-down supply assessment of Midwest bio-refinery capacity.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeled by product type, use case, end user, and packaging format dimensions. CAGRs were derived from volume trajectory analysis calibrated against purity-grade pricing differentials and channel absorption patterns. Industry-specific forecast inputs incorporated biodiesel production fluctuation scenarios and FDA traceability mandate implementation timelines.
Stress conditions across crude glycerin feedstock price volatility, EPA permitting delays, and USP-NF specification revision cycles were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding Midwest bio-refinery utilization rates and hospital procurement consolidation trajectories. Material shifts in FDA injectable-grade aseptic processing standards would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
India Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Amphetamine Drug Market
Pharmaceutical Ingredients
Pharmaceutical Chemicals Market
Pharmaceutical Ingredients
Medicinal Chemistry for Drug Discovery Market
Pharmaceutical Ingredients
Global Barbiturate Drugs Market
Pharmaceutical Ingredients
Pharmaceutical Glycerin Based Products Market
Pharmaceutical Ingredients
Pharmaceutical Glycerine Market
Pharmaceutical Ingredients
Ferrous Succinate Market
Pharmaceutical Ingredients
Furosemide Market
Pharmaceutical Ingredients
Encapsulated Salicylic Acid Market
Pharmaceutical Ingredients
Immunosuppressants Market
Pharmaceutical Ingredients
Mitotic Inhibitors Market
Pharmaceutical Ingredients
Cyclooxygenase 2 Inhibitor Market
Pharmaceutical Ingredients
Folinic Acid Market
Pharmaceutical Ingredients
Diosmin API Market
Pharmaceutical Ingredients
Oxycodone Drugs Market