
 Digital Menu Boards Market | 2026-2036
Digital Menu Boards Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Menu Boards Market Outlook
Buyer concentration across the restaurant sector is broadening beyond top-tier chains to encompass regional quick-service operators and independent coffee shops. McDonald's sustains one of the largest deployed fleets of networked menu displays, setting operational benchmarks for content synchronization across thousands of locations. Starbucks differentiates through mobile-integrated digital menu experiences that tie loyalty program data to real-time pricing and promotion. Raydiant competes on software-hardware bundling, offering cloud-native content management that reduces IT overhead for mid-size restaurant groups.
Digital menu boards comprise networked electronic display systems engineered for commercial foodservice environments, typically employing LED or LCD panels with brightness ratings exceeding 700 nits for visibility under direct interior lighting. These systems integrate content management software, media players, and display hardware to enable remote scheduling, daypart pricing, and nutritional disclosure compliance across multi-location operations. Indoor displays anchor current revenue volumes due to their ubiquity in quick-service restaurant drive-thrus and counter-service formats, while kiosks represent the fastest-expanding product category as self-order interfaces reduce labor touchpoints and lift average ticket values through automated upsell prompts. LED technology leads the technology dimension on energy efficiency and longevity metrics, though LCD retains cost advantages for smaller operators with limited capital replacement cycles.
The U.S. FDA enforces calorie disclosure mandates that effectively require chain restaurants to present standardized nutritional information, a compliance burden that digital formats resolve through automated database-driven content updates rather than static board reprints. The FCC governs wireless connectivity protocols embedded in modern menu board networks, shaping hardware certification requirements for Wi-Fi and cellular-enabled media players. OSHA workplace safety standards influence display mounting specifications and electrical installation practices in commercial kitchens. Stakeholders must monitor evolving state-level privacy regulations that could restrict customer-facing camera analytics used for demographic targeting and dwell-time measurement on smart menu systems.
Market Dynamics
The FDA's menu labeling mandate for chain restaurants has compressed replacement cycles for static signage, forcing operators toward networked digital displays that automate nutritional disclosure updates across multi-location fleets.
Growth Catalysts
- Calorie Disclosure Mandates:The U.S. FDA requires chain restaurants to display standardized nutritional information, driving compliance-focused upgrades from printed boards to database-driven digital systems that update automatically.
- LED Panel Efficiency:Energy consumption reductions exceeding 40% versus legacy fluorescent backlit displays accelerate payback periods for quick-service operators managing 24-hour drive-thru operations.
- Cloud Content Management:Remote scheduling and daypart pricing capabilities reduce IT headcount requirements for regional restaurant groups expanding across multiple states.
Market Restraints
- Display Panel Supply Concentration:Korean and Taiwanese semiconductor foundries dominate high-brightness LED driver IC production, creating vulnerability to fab allocation disruptions.
- Cellular Connectivity Hardware Costs:FCC-certified LTE and 5G media players carry 60-80% premiums over Wi-Fi-only equivalents, constraining deployment in rural locations lacking reliable broadband.
- LCD Technology Persistence:Mature liquid-crystal display supply chains and refurbishment ecosystems extend replacement timelines for budget-constrained independent operators.
Strategic Opportunities
- Self-Service Kiosk Integration:Combined digital menu and ordering terminals reduce labor touchpoints while lifting average ticket values through automated upsell prompts at quick-service counters.
- State Privacy Regulation Gaps:Absence of uniform biometric consent frameworks creates first-mover advantage for operators deploying camera-enabled demographic analytics before compliance obligations crystallize.
- Mobile-Loyalty Convergence:Integration of point-of-sale systems with customer relationship management platforms enables real-time personalized pricing tied to purchase history and geolocation.
Industry Challenges
- Legacy POS Integration Complexity:Proprietary protocols from established restaurant technology vendors obstruct seamless data exchange with third-party digital menu platforms, extending deployment timelines.
- Electrical Infrastructure Retrofitting:Older quick-service locations lack dedicated circuits and mounting structures rated for commercial display loads, requiring costly contractor interventions.
- Content Synchronization Failures:Network latency and media player firmware inconsistencies create pricing mismatches between drive-thru and counter displays, exposing operators to consumer protection complaints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Menu Boards Market |
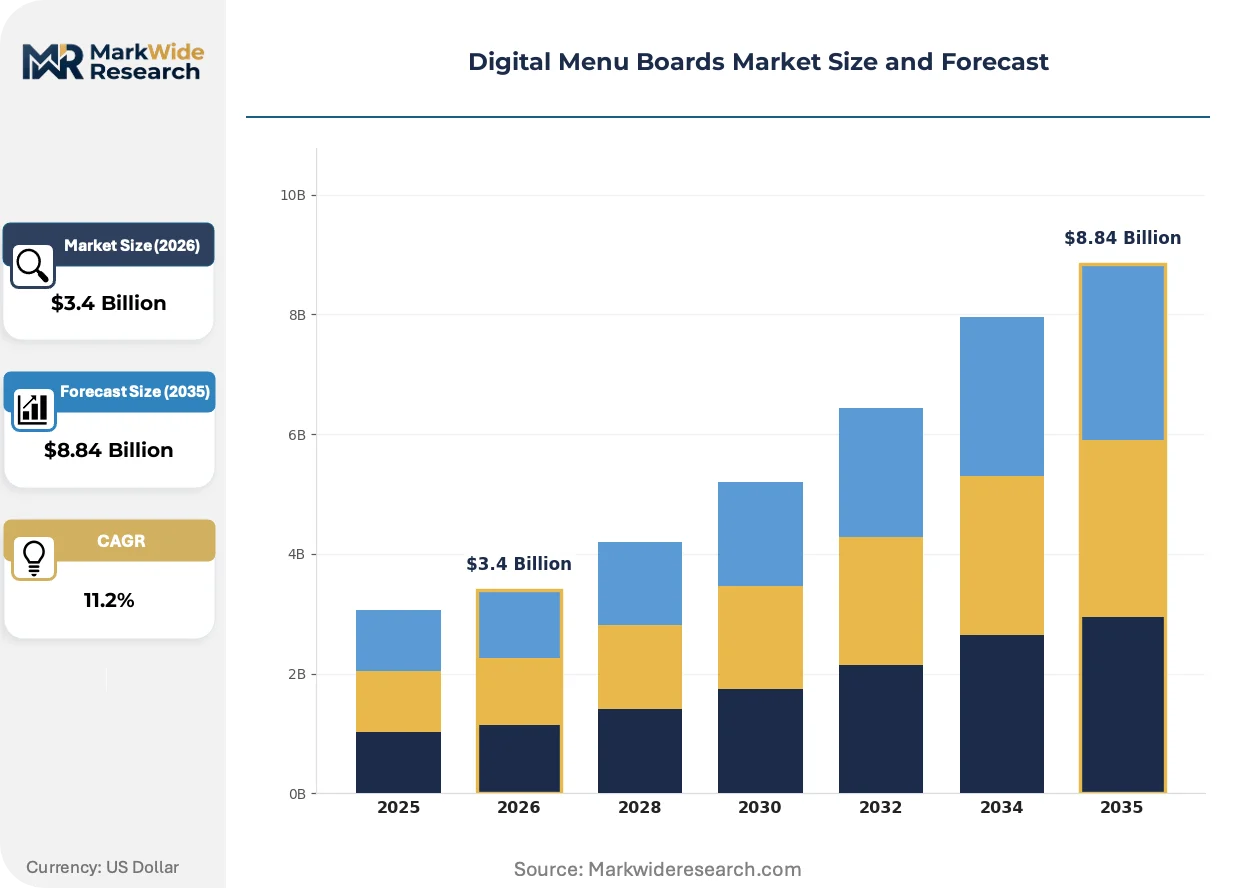
| Market Size in 2026 | $3.4 Billion |
| Market Size in 2035 | $8.84 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Displays, Outdoor Displays, Kiosks, Monitors Technology: LED, LCD, Projection, E-Paper Application: Quick Service Restaurants, Coffee Shops, Retail Stores, Hospitality End User: Food Service, Retail, Entertainment, Transportation |
| Companies Covered | Raydiant, NowSignage, McDonald's, Mandoe Media, Spectrio, Starbucks, Coates, Xibo Signage, SmarterSign, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Menu Boards Market Strategic Shifts
Networked display architectures are converging with customer data platforms and kitchen automation systems, transforming menu boards from passive signage into dynamic revenue optimization infrastructure.
LED direct-view display technology is consolidating market share in high-ambient-light environments such as drive-thru lanes and storefront windows. Quick-service chains with 500-plus locations are standardizing on 1,000-nit minimum brightness ratings to ensure readability under direct sunlight. This technology shift is consolidating supplier relationships around vertically integrated panel manufacturers capable of delivering color-calibrated batches across national rollouts.
The U.S. FDA's enforcement discretion timeline for menu labeling compliance has hardened into binding requirements for chains with 20 or more locations. Operators now face civil monetary penalties for non-compliant nutritional disclosures, accelerating replacement of static boards with software-updatable formats. Drive-thru menu systems represent the most affected category given their exposure to regulatory inspection and consumer litigation risk.
Franchisee procurement autonomy is eroding as corporate parent companies mandate approved vendor lists for digital menu deployments. Regional operators previously selecting hardware independently now source through centralized national agreements that bundle content management subscriptions with display hardware. This pattern is most visible in the United States, where franchisor-controlled supply programs dominate the top 50 quick-service chains by location count.
Digital Menu Boards Market Segmentation
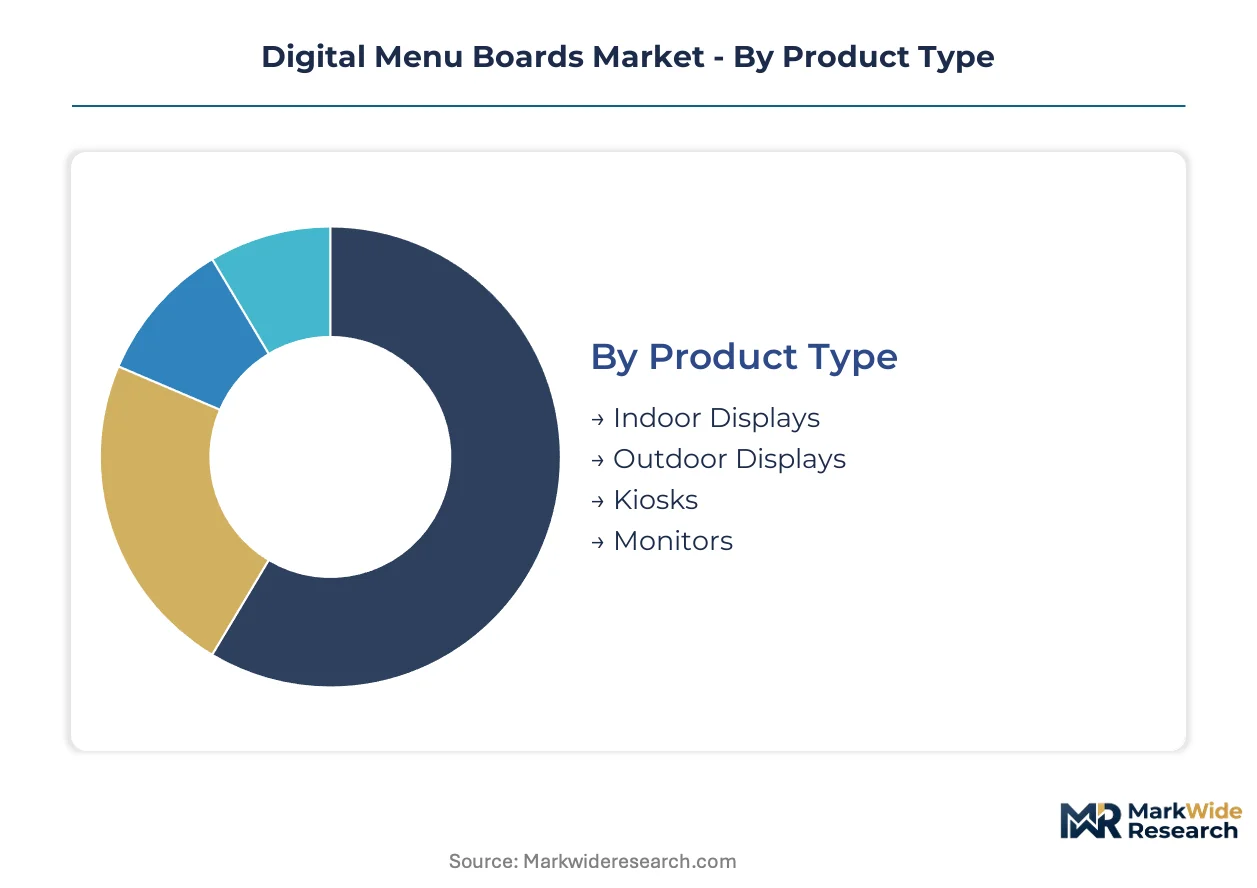
Segmentation in the digital menu boards market reveals distinct capital requirements and operational constraints across display technologies and deployment environments. Operators must match hardware specifications to ambient lighting conditions, traffic patterns, and integration complexity.
Product Type:
Capital intensity varies sharply across form factors, with outdoor-rated systems demanding weatherproofing, thermal management, and vandal-resistant enclosures that multiply upfront costs versus indoor equivalents.
- Indoor Displays:LED-backlit panels rated at 700-1,000 nits brightness dominate counter-service and dining room installations. Quick-service chains with 24-hour operations prioritize these for energy efficiency and remote content synchronization across multi-location fleets.
- Kiosks:Self-order terminals integrate touchscreen interfaces, payment readers, and receipt printers into unified enclosures. McDonald's and Starbucks deploy these at scale to reduce labor touchpoints and drive automated upsell prompts, lifting average ticket values.
- Outdoor Displays:High-brightness panels exceeding 1,500 nits with IP65 ingress protection serve drive-thru lanes and storefront windows. These systems require dedicated HVAC modules and surge-resistant power supplies.
- Monitors:Standard commercial-grade screens without integrated media players suit budget-constrained independent operators retrofitting existing mounting infrastructure.
Indoor displays absorb the bulk of installed capacity; kiosks are expanding most quickly as labor costs pressure operators toward self-service automation.
Technology:
Technology selection hinges on replacement cycle economics and ambient light tolerance, with LED consolidating share in high-visibility applications despite higher unit costs.
- LED:Direct-view LED tiles deliver 100,000-hour lifespans and 40% energy savings versus legacy fluorescent backlit systems. Major quick-service chains standardize on 1,000-nit minimum brightness for drive-thru readability under direct sunlight.
- LCD:Mature liquid-crystal supply chains and refurbishment ecosystems extend replacement timelines for regional operators with limited capital budgets. These panels retain cost advantages for smaller location counts.
- Projection:Short-throw laser projectors enable oversized menu presentations in food courts and stadium concessions where wall space exceeds standard display dimensions.
- E-Paper:Bistable display technology consumes power only during image updates, suiting static menu boards in coffee shops with infrequent price changes and extended battery-operated deployments.
LED technology commands the dominant revenue share; kiosk-integrated touch displays are climbing the fastest as operators consolidate hardware footprints.
Application:
Application segmentation tracks regulatory exposure and transaction velocity, with FDA-mandated nutritional disclosure requirements driving replacement urgency in chain environments.
- Quick Service Restaurants:Drive-thru and counter-service formats require synchronized content networks that automate daypart pricing and calorie disclosure compliance. The FDA's menu labeling mandate accelerates upgrades from static boards to database-driven systems.
- Coffee Shops:Smaller footprint locations prioritize compact displays with mobile loyalty integration, enabling real-time personalized pricing tied to purchase history and geolocation data.
- Retail Stores:Grocery deli counters and convenience store foodservice departments adopt commercial-grade screens for prepared food merchandising and promotional scheduling.
- Hospitality:Hotel breakfast buffets and convention center food courts deploy large-format displays for multilingual menu presentation and event-specific catering announcements.
Quick service restaurants anchor current demand volumes; coffee shops are gaining share fastest as independent operators digitize to match chain-level customer experience.
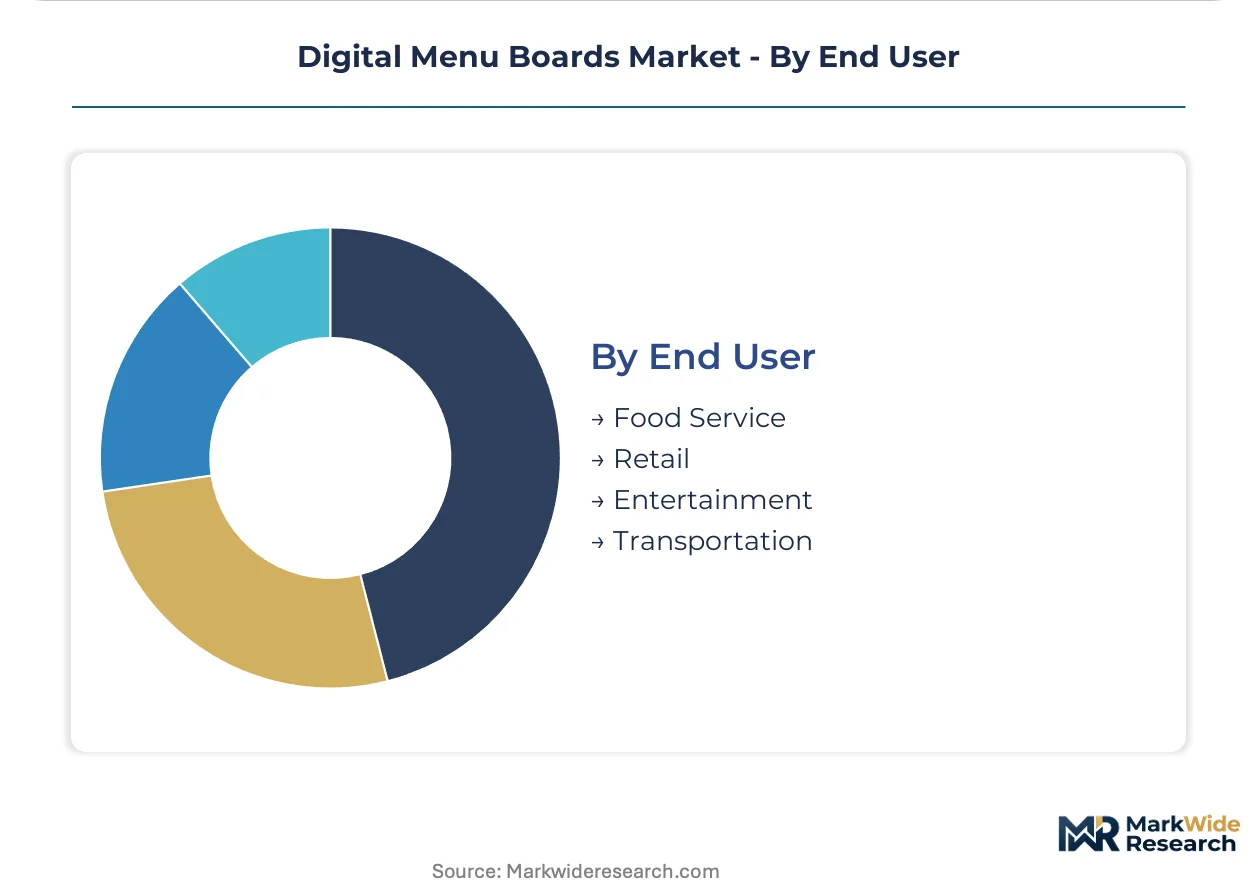
End User:
End-user segmentation reflects diverging procurement sophistication, with corporate-controlled chains deploying centralized vendor programs while independent operators retain hardware selection autonomy.
- Food Service:Chain restaurants with 20-plus locations face binding FDA calorie disclosure enforcement, forcing compliance-focused upgrades. Franchisee procurement autonomy is eroding as parent companies mandate approved vendor lists bundling hardware with content management subscriptions.
- Retail:Big-box retailers and convenience store operators integrate menu boards with inventory systems to automate out-of-stock item suppression and dynamic pricing based on spoilage risk.
- Entertainment:Movie theaters and sports venues prioritize high-refresh-rate displays for video content integration alongside static menu pricing, requiring specialized media players with HDMI 2.1 connectivity.
- Transportation:Airport terminals and highway rest stops deploy ruggedized displays with 24/7 operation ratings and remote diagnostic capabilities for minimal on-site maintenance.
Food service captures the dominant installed base; retail applications are expanding most quickly as non-traditional foodservice operators adopt digital merchandising infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in the United States, where quick-service chains deploy cloud-managed screen networks at scale. The FDA's menu labeling mandate forces compliance-driven upgrades from static boards to database-driven digital systems. Secondary growth clusters are emerging in Western Europe and East Asia as regulatory frameworks mature.
United States
McDonald's and Starbucks anchor fleet-wide deployments across tens of thousands of locations, establishing operational benchmarks for content synchronization. The FDA enforces calorie disclosure mandates that effectively require chain restaurants to present standardized nutritional information. Dallas-Fort Worth and Atlanta host concentrated vendor ecosystems serving regional quick-service franchisees retrofitting legacy locations.
Canada
Health Canada aligns with FDA disclosure frameworks, driving parallel compliance upgrades among cross-border operators. Provincial energy efficiency programs subsidize LED panel retrofits in Ontario and British Columbia. Toronto's foodservice technology cluster supplies mid-size restaurant groups with bundled hardware-software solutions.
Germany
The EU Green Deal and national energy efficiency standards accelerate LED adoption over fluorescent backlit alternatives. REACH compliance shapes material specifications for display housings and electronic components. Munich and Stuttgart host systems integrators serving quick-service chains expanding across Central Europe.
United Kingdom
The FSA's nutritional disclosure guidance pushes chains toward automated content management systems. GDPR constraints limit camera-enabled demographic analytics on customer-facing displays. London's digital signage sector concentrates vendor relationships for nationwide franchise rollouts.
Japan
METI's energy conservation standards favor LED technology in 24-hour convenience store and fast-food operations. JIS certification requirements govern display mounting safety in high-traffic retail environments. Tokyo and Osaka anchor demand from major domestic convenience store chains digitizing menu presentations.
Digital Menu Boards Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue software-native content management and kiosk integration. The vendor base stratifies across three tiers: vertically integrated display manufacturers, cloud-native software platforms, and systems integrators bundling hardware with managed services. Strategic archetypes include franchise program specialists, mid-market SaaS providers, and enterprise-scale managed service operators. Competitive moves center on franchisor-approved vendor list placement and national account consolidation.
Within the cloud-native tier, Raydiant and NowSignage exemplify software-hardware bundling strategies that reduce IT overhead for regional restaurant groups. McDonald's and Starbucks occupy distinctive positions as operator-integrators whose internal technology deployments set industry standards for fleet-scale synchronization and mobile-loyalty convergence.
| Leading Market Players |
|---|
| Raydiant |
| NowSignage |
| McDonald's |
| Mandoe Media |
| Spectrio |
| Starbucks |
| Coates |
| Xibo Signage |
| SmarterSign |
| Others |
Value Chain & Pricing Dynamics
Certification-tier divergence between FCC-compliant cellular-enabled systems and Wi-Fi-only alternatives manifests in both hardware premiums and sourcing complexity, with the former commanding substantial markups that reshape procurement patterns among regional quick-service operators and rural franchisees lacking reliable broadband infrastructure.
Pricing Analysis
Volume concentration in indoor LED-backlit panels sustains thinner margins than outdoor-rated systems, where weatherproofing and thermal management specifications protect premium positioning. Three-tier pricing structure across enterprise-managed fleets, mid-market SaaS bundles, and independent operator hardware separates buyers by IT sophistication and location count. Pricing pressure stems from Korean and Taiwanese semiconductor foundry allocation constraints affecting LED driver IC availability. Independent operators exhibit highest price sensitivity, deferring replacement cycles through LCD refurbishment ecosystems.
Supply Chain Analysis
Refurbishment and redeployment flows for commercial-grade LCD panels extend effective supply availability, buffering new production constraints for budget-constrained buyers. Panel assembly concentrates in China, South Korea, and Taiwan, with LED tile manufacturing anchored in Shenzhen and Seoul metropolitan clusters. High-brightness LED driver ICs, aluminum thermal management housings, and FCC-certified wireless modules constitute critical input dependencies. Single-source vulnerability in semiconductor foundry allocation for driver ICs threatens fulfillment timelines. Distribution runs through franchisor-approved vendor programs for top-tier chains, while regional integrators serve independent operators via direct hardware-software bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FDA's menu labeling mandate transforms compliance infrastructure into a structural barrier, elevating capital requirements for database-driven content systems and consolidating procurement around vendors capable of automated nutritional disclosure updates across multi-location fleets.
For Market Incumbents: To counter cloud-native software platforms eroding mid-market share, established display manufacturers should deepen backward integration into LED driver IC sourcing and secure franchisor-approved vendor list placement through bundled content management subscriptions. Capacity expansion in Mexico and Southeast Asia mitigates tariff exposure on Chinese-assembled panels.
For New Entrants and Emerging Players: Regional quick-service franchisees with 10-50 locations represent the most penetrable buyer archetype, underserved by enterprise vendor programs yet requiring compliance-grade systems. White-space targets include independent coffee shops lacking mobile-loyalty integration and rural operators constrained by cellular connectivity hardware costs. A hardware-as-a-service model with embedded IT support reduces upfront capital barriers.
For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated software-hardware platforms given FDA enforcement hardening and franchisee procurement autonomy erosion. Long-term viability favors vendors with national account consolidation momentum and cloud-native architecture. The signal to watch is state-level privacy regulation crystallization affecting camera-enabled demographic analytics deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Franchisor-Approved Vendor Program Placement | McDonald's and Starbucks procurement centralization mandates bundled hardware-software sourcing for franchisees. |
| Cloud-Native Content Management Platform Launch | Remote daypart pricing and nutritional disclosure automation reduce IT headcount for regional restaurant groups. |
| Self-Service Kiosk Hardware Integration | Touchscreen ordering terminals with payment readers lift average ticket values through automated upsell prompts. |
| LED Panel Supply Agreement with Korean Foundries | Direct driver IC sourcing secures allocation priority amid semiconductor fab capacity constraints. |
| Mobile-Loyalty System Partnership | Starbucks-style real-time personalized pricing tied to purchase history and geolocation drives customer retention. |
Study Parameters
Multi-period observation of FDA enforcement timelines, franchisor procurement centralization patterns, and LED panel technology substitution rates anchored the trend analysis, supplemented by interviews with quick-service restaurant technology officers, regional franchise operations directors, digital signage systems integrators, and content management platform product managers. Secondary validation drew from FDA Federal Register filings, FCC equipment authorization databases, SEC 10-K disclosures from publicly traded restaurant operators, and LED industry association shipment statistics. Bottom-up location-count modeling and top-down market sizing triangulated volume estimates.
Segment-weighting across product type, display technology, application environment, and end-user procurement sophistication structured the analytical framework. Modeled dimensions included indoor versus outdoor deployment requirements, LED versus LCD technology substitution curves, quick-service versus coffee shop application intensity, and corporate-controlled versus independent operator buying behavior. CAGRs were derived from installed base replacement cycle analysis and technology penetration curve fitting. Forecast inputs incorporated FDA compliance deadline enforcement patterns and cloud content management adoption velocity.
Revisions become necessary when semiconductor foundry allocation disruptions intensify, state-level privacy regulations restrict camera analytics deployment, or franchisor procurement autonomy erosion accelerates beyond modeled timelines. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and technology cost reduction curves. Practitioners should monitor FCC equipment authorization backlogs, Korean foundry capacity announcements, and state biometric consent legislation for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market
Food Service Equipment
Catering Equipment Market
Food Service Equipment
Gas Smoker Market
Food Service Equipment
North America and Europe Vending Machine Market
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
Commercial Refrigerated Display Cabinet Market
Food Service Equipment
Combi Cooler Market
Food Service Equipment
Europe Walk-In Refrigerators and Freezers Market
Food Service Equipment
Food Service Equipment Market
Food Service Equipment
Mobile Food Warmer Market
Food Service Equipment
Multi-Deck Refrigerated Display Cases Market
Food Service Equipment
Food Warmer Machines Market
Food Service Equipment
Commercial Hot Dog Cooker Market
Food Service Equipment
Smart Cooker Market
Food Service Equipment
Commercial Convection Ovens Market
Food Service Equipment
Global QSR Food Service Equipment Market