
 Gas Commercial Deep Fryers Market | 2026-2036
Gas Commercial Deep Fryers Market Size, Share, and Industry Trends Forecast 2026-2036
Gas Commercial Deep Fryers Market Foresight
Market Context
Modular fryer-battery configurations is consolidating buyer preference as kitchen operators seek flexible layouts that scale with menu complexity. Middleby Corporation leverages its broad portfolio to anchor positions across both independent restaurants and hospitality chains. Henny Penny specializes in precision temperature control systems that differentiate its offerings in high-volume frying environments.
Technical Definition and Segment Structure
Gas commercial deep fryers are pressurized-vessel cooking appliances utilizing natural gas or propane combustion to heat cooking oil between 300°F and 400°F for batch or continuous food preparation in professional foodservice operations. Floor fryers dominate installed base across full-service restaurants where volume throughput dictates equipment scale, while countertop fryers capture fastest growth in food trucks and compact kitchen footprints where space constraints override capacity needs. Quick service restaurants represent the deepest end-user margin pool given standardized menus and rapid equipment replacement cycles.
Regulatory Environment
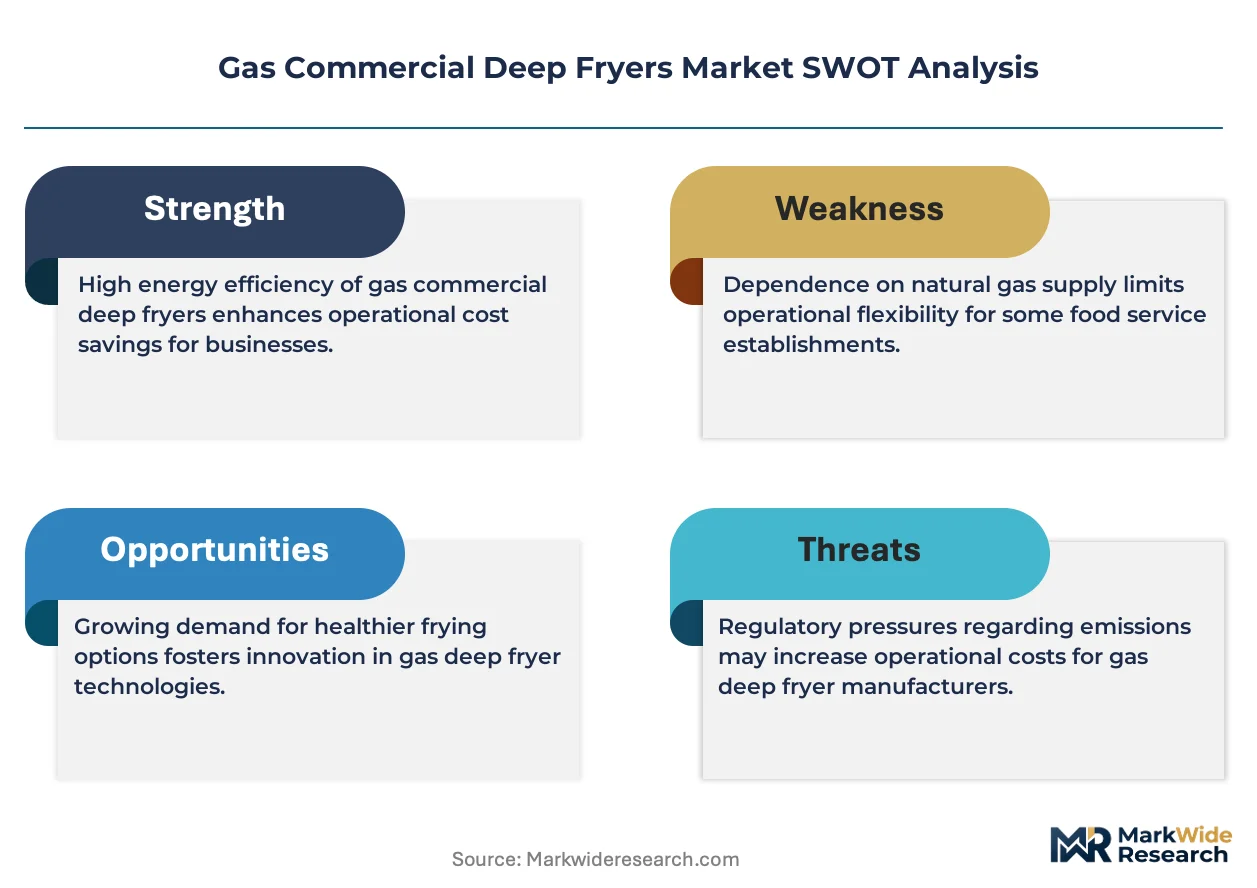
NFPA 96 ventilation standards and DOE commercial kitchen equipment efficiency regulations shape product design and market access for gas fryer manufacturers operating in the United States. EPA emissions guidelines for commercial cooking appliances additionally constrain burner technology choices and influence R&D allocation. Stakeholders must monitor evolving efficiency benchmarks and ventilation compliance costs as these factors increasingly determine competitive viability in replacement-driven markets.
Market Dynamics
The U.S. Department of Energy's commercial kitchen equipment efficiency standards are compressing replacement cycles and forcing burner redesign commitments across the installed base. Manufacturers must now engineer higher-efficiency combustion systems while maintaining throughput performance for high-volume operators.
Growth Catalysts
- NFPA 96 ventilation mandates:Stricter fire safety codes in professional kitchens are accelerating fryer replacement timelines as older units fail compliance audits. Operators in Texas and California are prioritizing compliant equipment to avoid shutdown risk.
- Quick service restaurant expansion:Chain operators are standardizing gas fryer footprints across new locations to simplify training and maintenance protocols. This creates predictable equipment demand from national accounts.
- Propane infrastructure in mobile foodservice:Food truck operators are adopting propane-powered countertop units where natural gas hookups remain unavailable. This extends addressable market beyond fixed-location restaurants.
Market Restraints
- Stainless steel input volatility:Fryer vessel fabrication depends on nickel-alloy steel grades subject to commodity price swings. Foundry capacity concentration in China amplifies cost uncertainty for U.S. manufacturers.
- EPA emissions compliance layering:Burner technology investments required for NOx reduction add engineering cost without direct revenue recovery. Smaller fabricators lack R&D budgets to absorb successive regulatory waves.
- Electric fryer substitution in urban cores:Grid-connected kitchens in dense municipalities are evaluating induction alternatives where gas infrastructure is restricted. California's building decarbonization policies accelerate this calculus.
Strategic Opportunities
- Modular battery configurations:Flexible fryer banks that scale from two to six vessels are capturing independent restaurant interest. This configuration adapts to menu expansion without full kitchen redesign.
- Used equipment refurbishment channels:Certified pre-owned programs are opening secondary markets for budget-constrained operators. Third-party servicers in Florida and Ohio are building regional refurbishment hubs.
- DOE efficiency incentive alignment:Utility rebate programs for high-efficiency gas equipment are shortening payback periods for premium burner designs. Manufacturers bundling rebate navigation into sales processes capture preference.
Industry Challenges
- Combustion technician scarcity:Gas burner calibration and safety certification require specialized skills that vocational programs have deprioritized. Service backlogs in metropolitan markets are extending equipment downtime.
- Legacy control system integration:IoT-enabled fryer management platforms must interface with existing kitchen display systems and enterprise resource planning software. Middleware development consumes engineering resources without direct product differentiation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gas Commercial Deep Fryers Market |
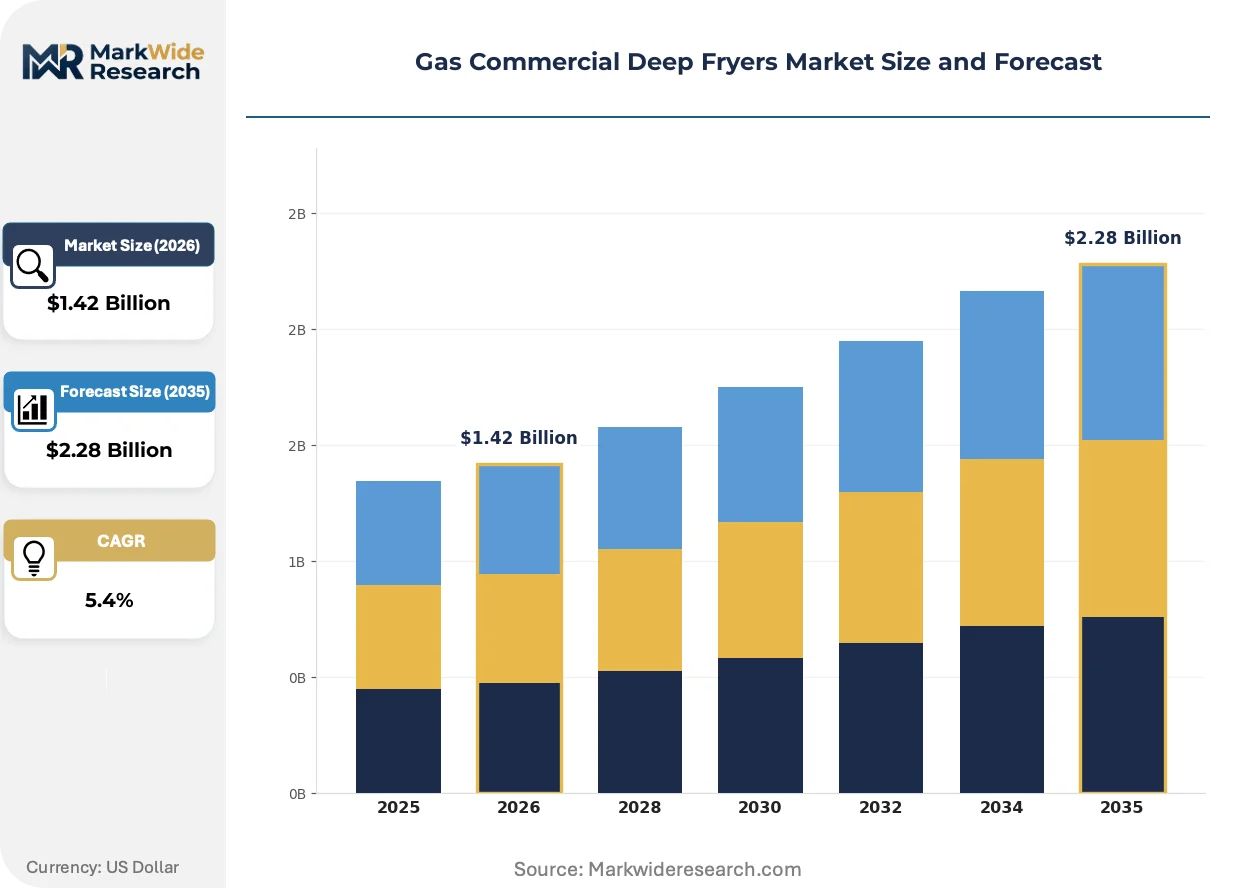
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.28 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop Fryers, Floor Fryers, High Capacity Fryers, Compact Fryers Technology: Direct Gas Fired, Infrared Heating, Radiant Burner, Electronic Ignition Application: Restaurants, Catering Services, Food Trucks, Hotels, Cafeterias End User: Quick Service Restaurants, Casual Dining, Institutional Kitchens, Hospitality Chains |
| Companies Covered | Middleby Corporation, Ali Group, Illinois Tool Works (ITW), Electrolux Professional, Henny Penny, Welbilt, Standex International, Frymaster, Avantco Equipment, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gas Commercial Deep Fryers Market Shifts & Advancements
Intelligent oil management and connected kitchen ecosystems are redefining how operators monitor fryer performance and schedule maintenance. These capabilities are shifting competitive advantage from hardware durability to data-enabled operational efficiency.
Infrared burner technology is absorbing market share from traditional atmospheric burners by delivering faster temperature recovery and reduced heat loss to the kitchen environment. High-volume quick service chains in Texas are specifying infrared systems for 24-hour operations where recovery speed directly impacts throughput. The technology is absorbing capital allocation that previously funded conventional burner R&D, compressing development timelines for legacy architectures.
EPA commercial cooking emissions guidelines are forcing burner redesigns that reduce particulate matter and nitrogen oxide output without sacrificing thermal efficiency. Fabricators must recertify existing product lines under tightened test protocols, adding six to twelve months to product launch schedules. Floor fryer categories face the steepest compliance burden due to higher BTU ratings and continuous-duty cycles.
Equipment-as-a-service contracting is displacing traditional capital purchase models among multi-unit operators seeking to outsource maintenance liability. National hospitality groups are negotiating fleet-management agreements that bundle fryer provisioning, oil filtration, and predictive maintenance. This restructuring is most visible in California where labor cost pressures amplify the value of outsourced kitchen equipment management.
Gas Commercial Deep Fryers Market Segmentation
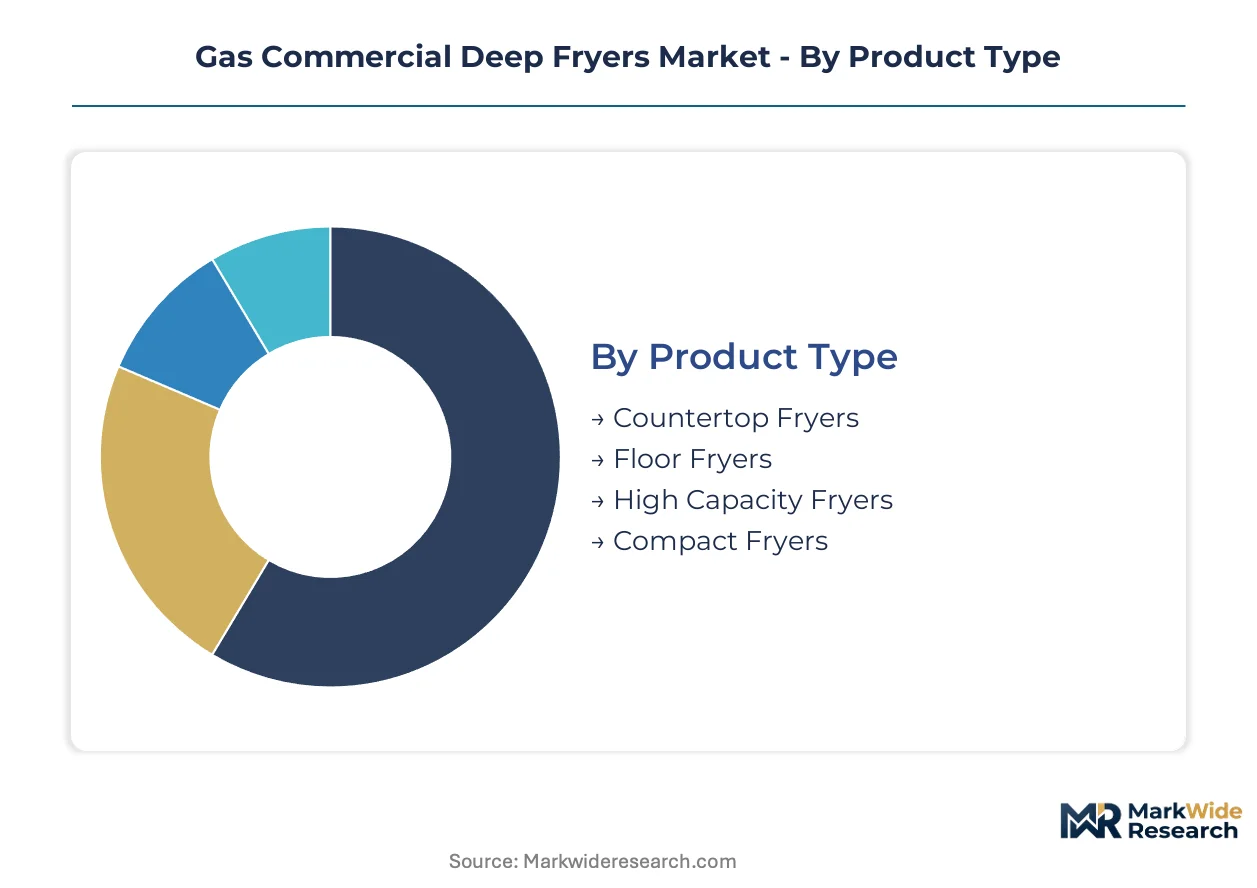
Gas commercial deep fryer purchasing decisions hinge on kitchen footprint constraints, throughput requirements, and fuel infrastructure availability. Operators weigh capital expenditure against operational flexibility when selecting across product configurations and burner technologies. Understanding segment boundaries clarifies where manufacturers must align engineering investment with buyer procurement priorities.
Product Type:
Capacity requirements and floor space availability drive equipment selection across commercial kitchen environments.
- Floor Fryers:These freestanding units incorporate multiple vessels with BTU ratings exceeding 80,000 per tank, enabling continuous high-volume production. Full-service restaurants in Texas deploy floor configurations for peak dinner service where batch size and recovery speed determine throughput capacity.
- Countertop Fryers:Compact single or dual-vessel designs mount on existing work surfaces, utilizing 20,000-40,000 BTU burners. Food truck operators across California favor these units where propane tank exchange replaces fixed natural gas infrastructure.
- High Capacity Fryers:Industrial-scale systems with 100+ pound oil capacity serve central commissary operations.
- Compact Fryers:Reduced-footprint floor models target ghost kitchens and delivery-only facilities with constrained mechanical space.
Volume sits with Floor Fryers; growth tilts toward Countertop Fryers.
Technology:
Energy efficiency mandates and thermal performance benchmarks shape burner technology adoption curves.
- Infrared Heating:Ceramic radiant panels convert gas combustion to infrared radiation, achieving 85%+ thermal efficiency versus 50-60% for atmospheric designs. Quick service chains specify infrared for 24-hour operations where temperature recovery directly impacts hourly throughput metrics.
- Direct Gas Fired:Traditional atmospheric burners mix gas and air below the fryer vessel, offering lower capital cost and simpler maintenance protocols. Independent restaurants with limited technical staff favor this proven architecture despite higher operating costs.
- Radiant Burner:Forced-air combustion systems optimize flame geometry for uniform heat distribution across large oil volumes.
- Electronic Ignition:Automated spark or hot-surface ignition eliminates standing pilot lights, reducing gas consumption during idle periods.
Direct Gas Fired retains installed base dominance; Infrared Heating captures specification momentum in new construction.
Application:
Menu complexity and service format dictate fryer count, vessel configuration, and oil management requirements.
- Restaurants:Full-service and limited-service establishments operate the deepest fryer penetration, with multi-vessel batteries dedicated to protein, seafood, and vegetable separation. California's chain restaurant density sustains replacement cycle velocity as operators refresh equipment to meet ventilation compliance deadlines.
- Food Trucks:Mobile foodservice operators prioritize propane compatibility and compact dimensions over production scale. Texas metropolitan markets host the densest food truck clusters, driving countertop unit demand where municipal permitting restricts fixed infrastructure.
- Catering Services:Event-based operators require portable or rapidly deployable frying capacity for off-premise execution.
- Hotels:On-property food and beverage operations balance room service, banquet, and restaurant frying needs within unified kitchen footprints.
- Cafeterias:Institutional feeding operations emphasize durability and simplified operation for high-turnover kitchen staff.
Restaurants command equipment volume; Food Trucks are expanding most quickly as mobile foodservice proliferates.
End User:
Procurement centralization and equipment standardization intensity vary dramatically across operator categories.
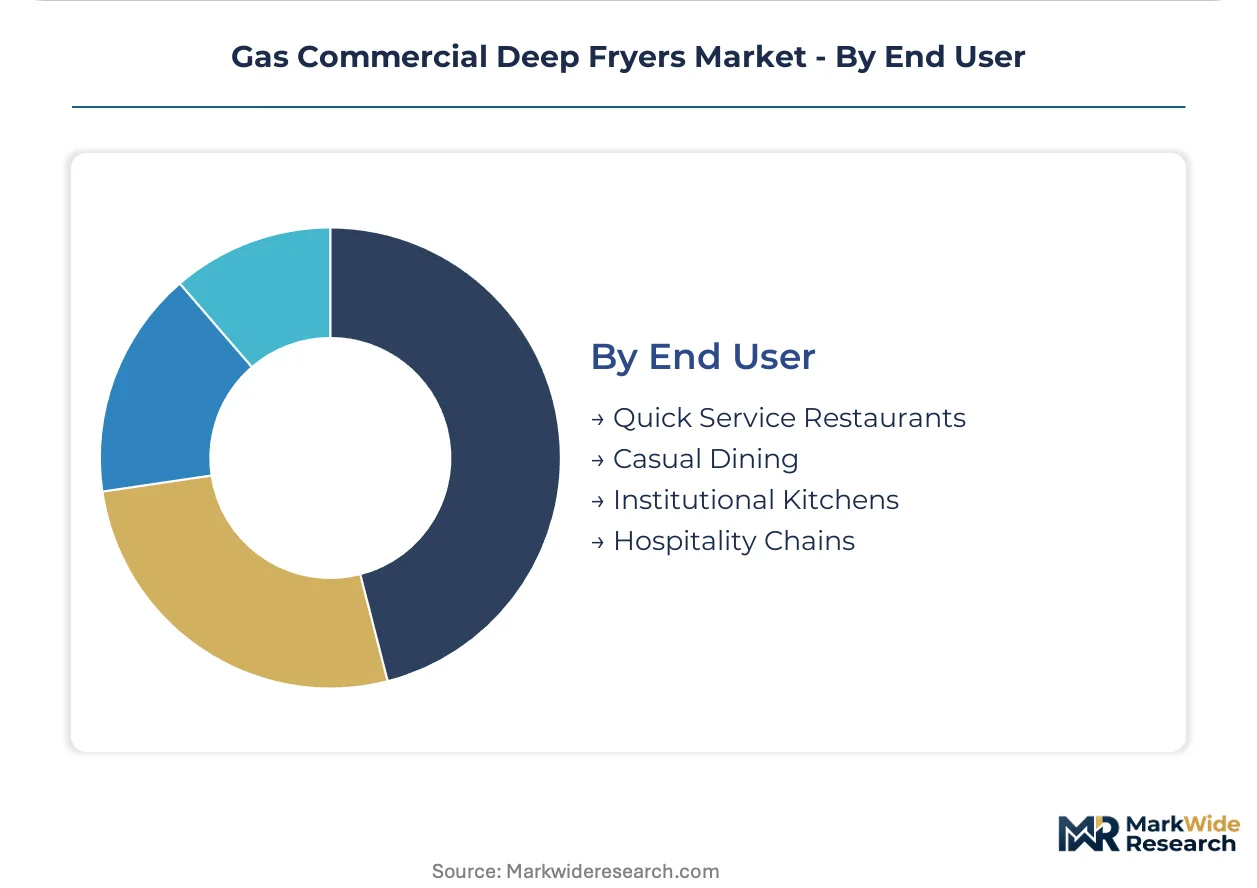
- Quick Service Restaurants:National and regional chains specify standardized fryer footprints across franchise and company-owned locations, creating predictable volume demand. These operators negotiate fleet pricing and bundled service agreements that compress manufacturer margins in exchange for multi-unit commitment.
- Hospitality Chains:Hotel and resort groups pursue equipment-as-a-service contracting to outsource maintenance liability and capital planning complexity. California-based national hospitality groups lead this shift where labor cost pressures amplify outsourced kitchen equipment management value.
- Casual Dining:Independent and small-chain full-service restaurants balance equipment cost against menu differentiation requirements.
- Institutional Kitchens:School, hospital, and correctional feeding operations prioritize durability and regulatory compliance over performance optimization.
Quick Service Restaurants anchor manufacturer revenue; Hospitality Chains are driving contract structure innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity for gas commercial deep fryers clusters in the United States and Germany, while consumption concentrates in North American and Western European foodservice markets. Supply chains bridge this divide through specialized component sourcing and regional assembly configurations. Regulatory divergence across jurisdictions shapes product specifications and market access requirements.
United States
Chain restaurant density in Texas and California sustains replacement cycle velocity as operators modernize kitchen footprints. The Department of Energy's commercial kitchen equipment standards mandate higher-efficiency burner designs that compress product development timelines. Dallas-Fort Worth and Los Angeles metropolitan clusters anchor specification activity for quick service restaurant chains.
Germany
Precision engineering capabilities support premium burner technology development for export-oriented manufacturers. REACH chemical safety regulations and CE marking requirements constrain material selection for vessel fabrication and combustion system components. The Baden-Württemberg industrial corridor hosts specialized fabricators serving Central European hospitality markets.
China
Stainless steel foundry capacity concentrates in Jiangsu and Zhejiang provinces, supplying raw vessel components to global assembly operations. GB standards for commercial cooking equipment establish baseline safety and performance benchmarks for domestic market access. The Yangtze River Delta region exports finished countertop units to Southeast Asian foodservice markets.
United Kingdom
Independent restaurant operators in London and Manchester drive demand for modular fryer configurations that adapt to constrained kitchen footprints. Gas Safe Register certification requirements govern installation and maintenance protocols across commercial foodservice establishments. The Southeast England logistics corridor facilitates equipment distribution to Irish and Nordic secondary markets.
Japan
Compact kitchen designs in Tokyo and Osaka metropolitan areas favor high-efficiency countertop units with precision temperature control. METI energy conservation standards incentivize infrared burner adoption over conventional atmospheric designs. The Kansai region hosts testing facilities for commercial cooking equipment export certification.
Gas Commercial Deep Fryers Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with broad foodservice equipment portfolios. Market positions stratify across three tiers: multinational platform companies with integrated R&D and distribution, regional specialists concentrating on burner technology or temperature control systems, and value-oriented fabricators serving replacement parts and refurbishment channels. Dominant competitive moves include portfolio diversification through adjacent cooking equipment categories and strategic partnerships with oil filtration and kitchen management system providers.
Among diversified platform operators, Middleby Corporation and Ali Group occupy positions spanning independent restaurants and hospitality chains through extensive brand portfolios. Henny Penny exemplifies the technology-specialist archetype, with its corporate identity signaling precision engineering heritage. Illinois Tool Works represents the industrial conglomerate model, leveraging cross-divisional manufacturing capabilities to serve commercial foodservice equipment demand.
| Leading Market Players |
|---|
| Middleby Corporation |
| Ali Group |
| Illinois Tool Works (ITW) |
| Electrolux Professional |
| Henny Penny |
| Welbilt |
| Standex International |
| Frymaster |
| Avantco Equipment |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap fabricators across Ohio and Pennsylvania anchor the supply base for gas fryer vessel production, concentrating procurement leverage among a handful of domestic foundries while enforcing disciplined contract pricing on stainless steel inputs. Their ownership structure resists vertical consolidation, fragmenting bargaining power against nickel-alloy suppliers and perpetuating cost pass-through volatility to end-users.
Pricing Analysis
Margin tightening in standard-grade floor fryers traces to EPA compliance engineering costs that smaller fabricators cannot absorb without price adjustments. Three-tier pricing structure across premium infrared systems, standard atmospheric burners, and economy refurbished units segments buyer budgets. Certification tier differentiation—UL-listed versus uncertified imports—widens spreads by fifteen to twenty percent. Quick service restaurant chains exhibit lowest price sensitivity through fleet standardization, while independent restaurants in Texas negotiate aggressively on single-unit replacement cycles.
Supply Chain Analysis
Stainless steel vessel fabrication rests on foundry capacity concentrated in Jiangsu province, China, with secondary forging operations in Germany and domestic U.S. mills. Nickel-alloy grades, ceramic radiant panels for infrared systems, and electronic ignition modules constitute critical component dependencies. Tariff exposure on Chinese steel inputs amplifies cost uncertainty for U.S. assembly operations. Distribution runs through regional equipment dealers serving metropolitan foodservice clusters, with national accounts contracting directly through manufacturer sales organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Infrared burner technology is displacing legacy atmospheric combustion architectures across quick service restaurant specifications, compressing R&D timelines for conventional product lines and forcing portfolio repositioning among incumbent fabricators.
For Market Incumbents: Deepen captive supply relationships with Jiangsu foundries to secure stainless steel allocation ahead of tariff escalation, while accelerating infrared burner certification under EPA test protocols. Electric fryer substitution in California building decarbonization zones threatens gas equipment replacement velocity, demanding defensive specification engineering for high-efficiency combustion systems that extend gas relevance. For New Entrants and Emerging Players: Direct-to-food-truck digital channels bypass established dealer networks, opening white-space penetration in California and Texas mobile foodservice markets where propane countertop units face supply gaps. Refurbishment-as-a-service platforms target budget-constrained independent restaurants in Florida and Ohio, leveraging third-party technician networks for installation support without capital-intensive manufacturing footprints. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional burner technology specialists in the Baden-Württemberg corridor where REACH compliance costs strain mid-tier engineering margins. Five-to-ten year viability hinges on infrared patent portfolios and utility rebate program alignment. The signal to watch is DOE efficiency standard advancement pace, which would accelerate replacement demand or strand legacy inventory.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Stainless Steel Forging | Captive supply from Jiangsu or domestic mills insulates margin against nickel price volatility and tariff exposure. |
| Infrared Burner Patent Portfolio Expansion | Ceramic radiant technology differentiation captures quick service chain specifications ahead of EPA compliance deadlines. |
| Equipment-as-a-Service Contracting | Fleet management agreements with California hospitality groups outsource maintenance liability while securing recurring revenue. |
| Refurbishment Hub Regionalization | Certified pre-owned programs in Florida and Ohio extend equipment life cycles for price-sensitive independent operators. |
| Utility Rebate Program Alignment | DOE efficiency incentive bundling shortens payback periods for premium burner designs in Texas and California markets. |
Research Methodology
Independent corroboration across foodservice equipment distributor interviews, stainless steel foundry procurement leads, and quick service restaurant facility managers underwrites the qualitative findings on replacement cycle dynamics. Secondary validation drew from DOE efficiency standard filings, EPA emissions test protocols, NFPA 96 ventilation code revisions, and commercial kitchen equipment trade association shipment data. Bottom-up unit economics from individual operator interviews triangulate against top-down manufacturer revenue segmentation.
Rate-of-change decomposition across the projection horizon isolates volume drivers by product type, burner technology, end-user procurement centralization, and metropolitan market regulatory intensity. CAGRs derive from segmented growth rate reconciliation against aggregate market expansion. Modeled inputs include chain restaurant unit development pipelines, food truck permitting velocity in Texas and California, and DOE compliance timeline assumptions.
The model holds under steady regulatory enforcement and commodity price bands; deviation in nickel alloy cost spikes or accelerated electric equipment substitution would shift replacement timing. Forecasts reflect documented assumptions without contingency for trade policy disruption or building electrification mandate acceleration. A small set of named triggers—EPA test protocol revision, DOE standard advancement, and stainless steel tariff adjustment—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Refrigerated Counter Market
Food Service Equipment
Food Display Cabinet Market
Food Service Equipment
Commercial Steamer Market
Food Service Equipment
Beverage Refrigeration Market
Food Service Equipment
Asia-Pacific Commercial Dishwashers Market
Food Service Equipment
Instant Pot Market
Food Service Equipment
Commercial Bar Equipment Market
Food Service Equipment
North America and Europe Vending Machine Market
Food Service Equipment
Warewashing Professional Equipment Market
Food Service Equipment
Rapid Cook-High Speed Ovens Market
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
Used Restaurant Equipment Market
Food Service Equipment
Hospital Foodservice Equipment Market
Food Service Equipment
Commercial Catering Equipment Market
Food Service Equipment
Commercial Microwaves Market