
 Combi Cooler Market | 2026-2036
Combi Cooler Market Size, Share, and Industry Trends Forecast 2026-2036
Combi Cooler Market Outlook
Multi-source procurement for heat exchanger assemblies is restructuring supply relationships across the European combi cooler value chain. GEA Group leverages captive manufacturing of plate heat exchangers to sustain margin control in process cooling segments. Vaillant Group anchors its position through R&D intensity in condensing technology for residential applications. Panasonic competes aggressively in inverter-driven systems for the Asian commercial sector.
A combi cooler integrates refrigeration and heating circuits within a single thermal management unit, typically employing brazed plate heat exchangers with working pressures between 25 and 40 bar to enable simultaneous or sequential cooling and heating duty. Its primary industrial purpose centers on recovering waste heat from cooling cycles to service space heating or domestic hot water loads, thereby reducing aggregate energy consumption in buildings and production facilities. Air-cooled configurations dominate residential installations due to simpler plumbing requirements and lower upfront capital outlay, while water-cooled variants command premium positioning in industrial process cooling where higher thermal transfer coefficients improve coefficient of performance. Smart technology segments are attracting disproportionate engineering investment as building management system integration becomes a baseline procurement specification rather than an upsell feature.
EU F-Gas Regulation and REACH compliance frameworks are tightening refrigerant eligibility criteria and material substance restrictions, forcing redesign cycles across European manufacturers. The EPA Significant New Alternatives Policy program in the United States is creating parallel pressure for low-GWP transition in imported equipment. Japan's METI Top Runner program drives efficiency benchmarking that shapes export competitiveness for inverter-based systems. Stakeholders must monitor divergence between regional refrigerant approval timelines to avoid stranded inventory or non-compliant product configurations.
Market Dynamics
EU F-Gas Regulation phase-down schedules are compressing refrigerant choice sets and forcing simultaneous redesign of heat exchanger materials and compressor architectures across European manufacturing footprints.
Growth Catalysts
- Pharmaceutical cold chain expansion:Germany, Italy, and Japan are deploying combi coolers in vaccine storage and biologics processing facilities, driving specification upgrades toward redundant cooling circuits and validated temperature logging.
- EU F-Gas Regulation:The mandated transition to refrigerants with GWP below 150 for new stationary equipment is pulling demand toward systems engineered for R-290, R-1234ze, and CO2 transcritical cycles.
- Heat recovery integration:Dairy processing clusters in the Netherlands and Denmark are specifying combi coolers to capture waste heat from chilling operations for CIP water preheating, cutting thermal energy draw by measurable increments.
Market Restraints
- Copper and aluminum price volatility:Brazed plate heat exchanger fabrication depends on thin-gauge copper foil and extruded aluminum profiles, exposing margin structures to London Metal Exchange swings without pass-through elasticity in contract terms.
- Compressor supply concentration:Scroll and semi-hermetic compressor sourcing concentrates among German and Japanese suppliers, creating single-source vulnerability for mid-tier system integrators lacking dual qualification.
- Refrigerant thermodynamic limits:Lower-GWP alternatives exhibit reduced volumetric capacity versus legacy HFCs, forcing larger displacement compressors and heat exchanger surface area penalties that erode footprint advantages.
Strategic Opportunities
- Data center liquid cooling convergence:Hyperscale facilities in Virginia and Singapore are piloting combi-derived thermal loops that reject heat to district heating networks, opening a specification channel outside traditional HVAC procurement.
- Japan METI Top Runner efficiency benchmarking:The program's escalating COP thresholds for commercial refrigeration equipment create export certification pathways for inverter-driven combi systems that exceed baseline performance.
- Aftermarket refrigerant retrofit services:The installed base of R-404A and R-410A systems in Italy and Spain faces obsolescence, generating recurring revenue potential for drop-in replacement engineering and control system upgrades.
Industry Challenges
- Refrigerant handling certification gaps:The shift to flammable A3 and mildly flammable A2L refrigerants requires technician retraining under EU F-Gas certification modules, constraining field service capacity during peak installation seasons.
- Building management system protocol fragmentation:Integration with BACnet, Modbus, and proprietary cloud platforms demands custom gateway development, extending commissioning timelines and escalating software validation costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Combi Cooler Market |
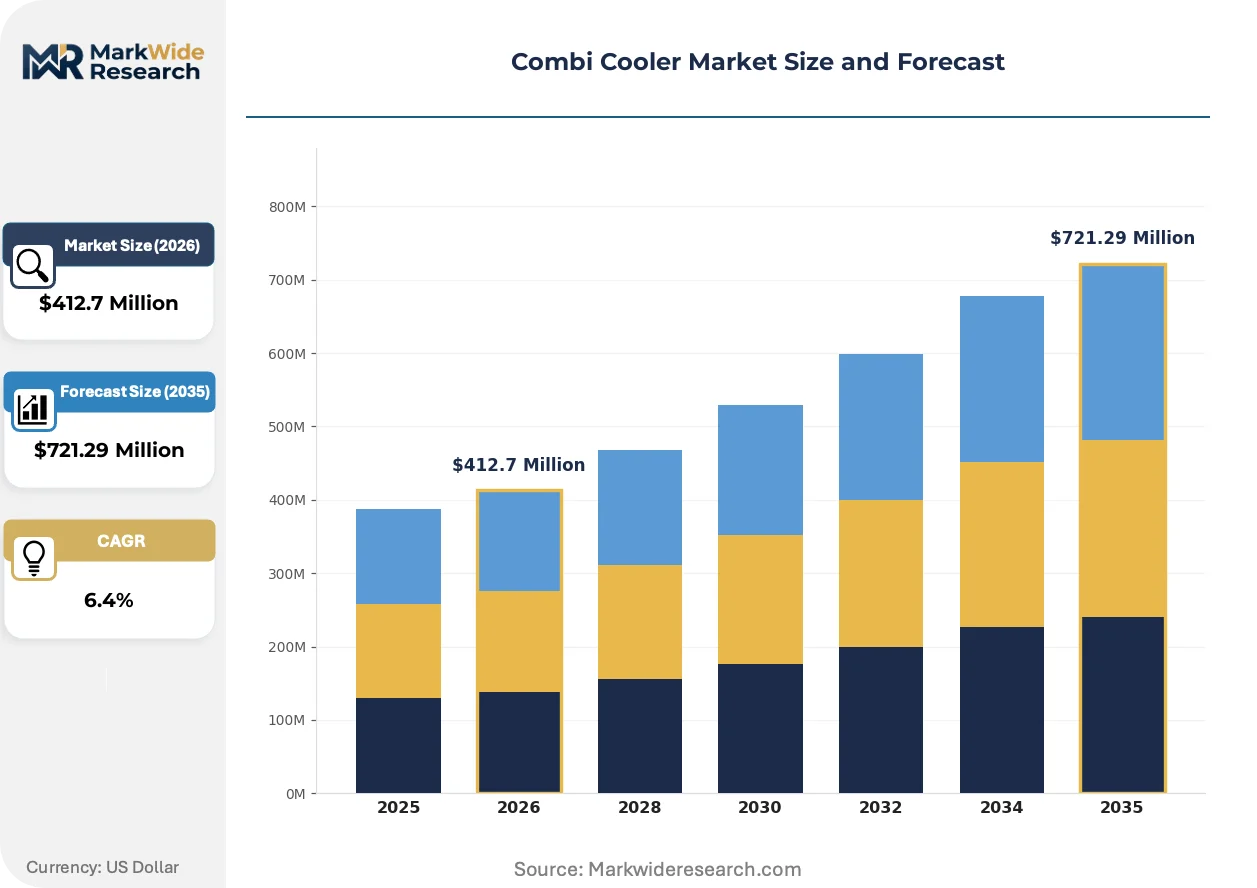
| Market Size in 2026 | $412.7 Million |
| Market Size in 2035 | $721.29 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air-Cooled, Water-Cooled, Hybrid, Modular End User: Residential, Commercial, Industrial, Hospitality Technology: Inverter, Non-Inverter, Smart, Conventional Application: Indoor Cooling, Process Cooling, Food Preservation, Climate Control |
| Companies Covered | Ariston Group, Ferroli S.p.A., Vaillant Group, GEA Group, Carrier, Viessmann Werke GmbH & Co. KG, Baxi Heating UK Limited, Panasonic, Worcester Bosch Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Combi Cooler Market Strategic Shifts
Refrigerant chemistry constraints are compressing equipment design freedom and accelerating convergence between HVAC and industrial process cooling engineering cultures.
CO2 transcritical booster systems are consolidating market position in commercial refrigeration applications where heat recovery to space heating or domestic hot water offsets the efficiency penalty of transcritical operation. Supermarket chains in Germany and Denmark are specifying these architectures as baseline for new-build and retrofit programs. The technology is consolidating vendor relationships around suppliers with in-house gas cooler and ejector engineering capabilities.
The EPA Significant New Alternatives Policy program is narrowing approved refrigerant lists for imported equipment, compelling non-US manufacturers to maintain parallel product configurations. This regulatory friction is segmenting the North American market from European refrigerant approval timelines. Process cooling applications serving pharmaceutical manufacturing face the steepest compliance burden due to FDA validation requirements that resist rapid refrigerant substitution.
Buyers in the dairy and beverage processing verticals are unbundling after-sales service from initial equipment purchase, soliciting multi-year performance contracts from third-party service providers rather than OEM service divisions. This procurement pattern is compressing captive service revenue for traditional manufacturers. The shift is most visible in the Netherlands, where energy-as-a-service providers now contract directly for thermal output rather than equipment ownership.
Combi Cooler Market Segmentation
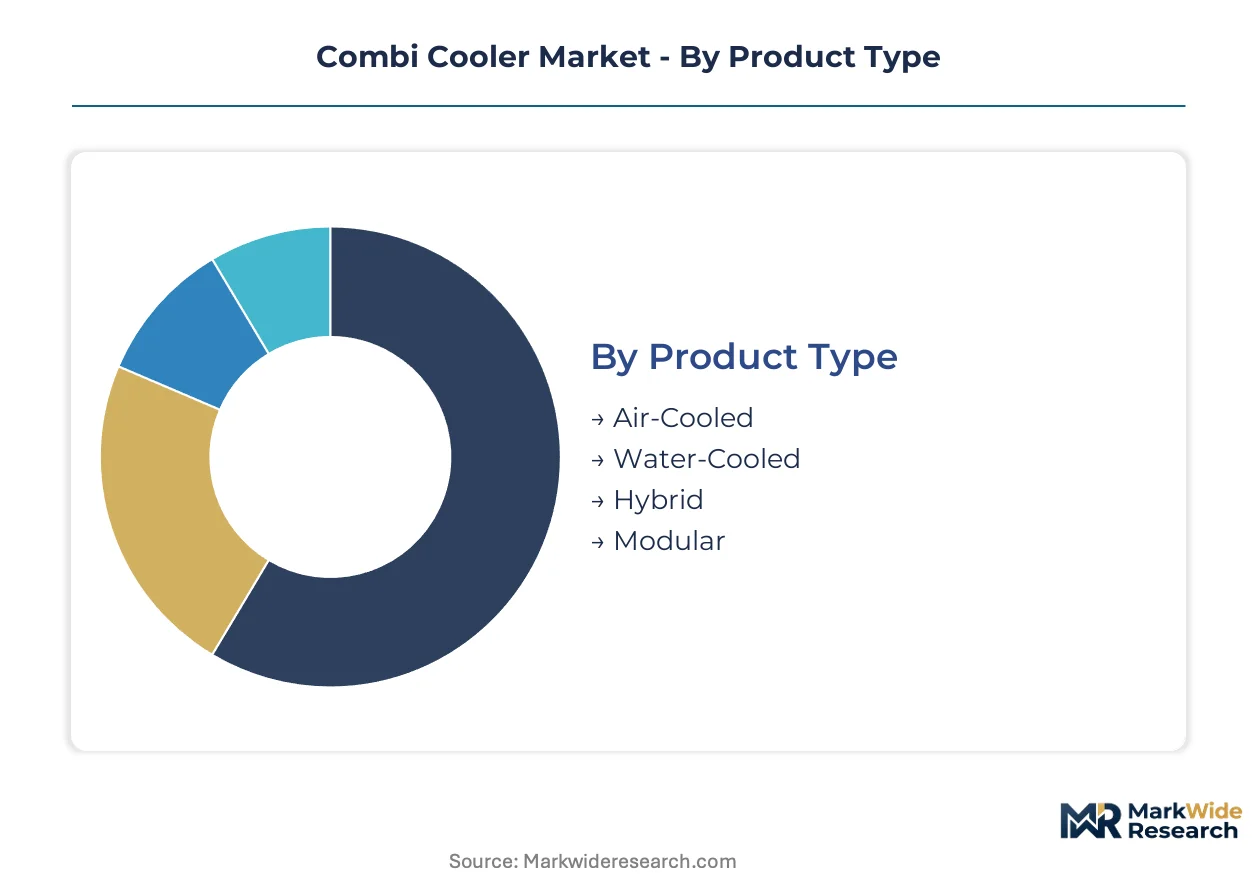
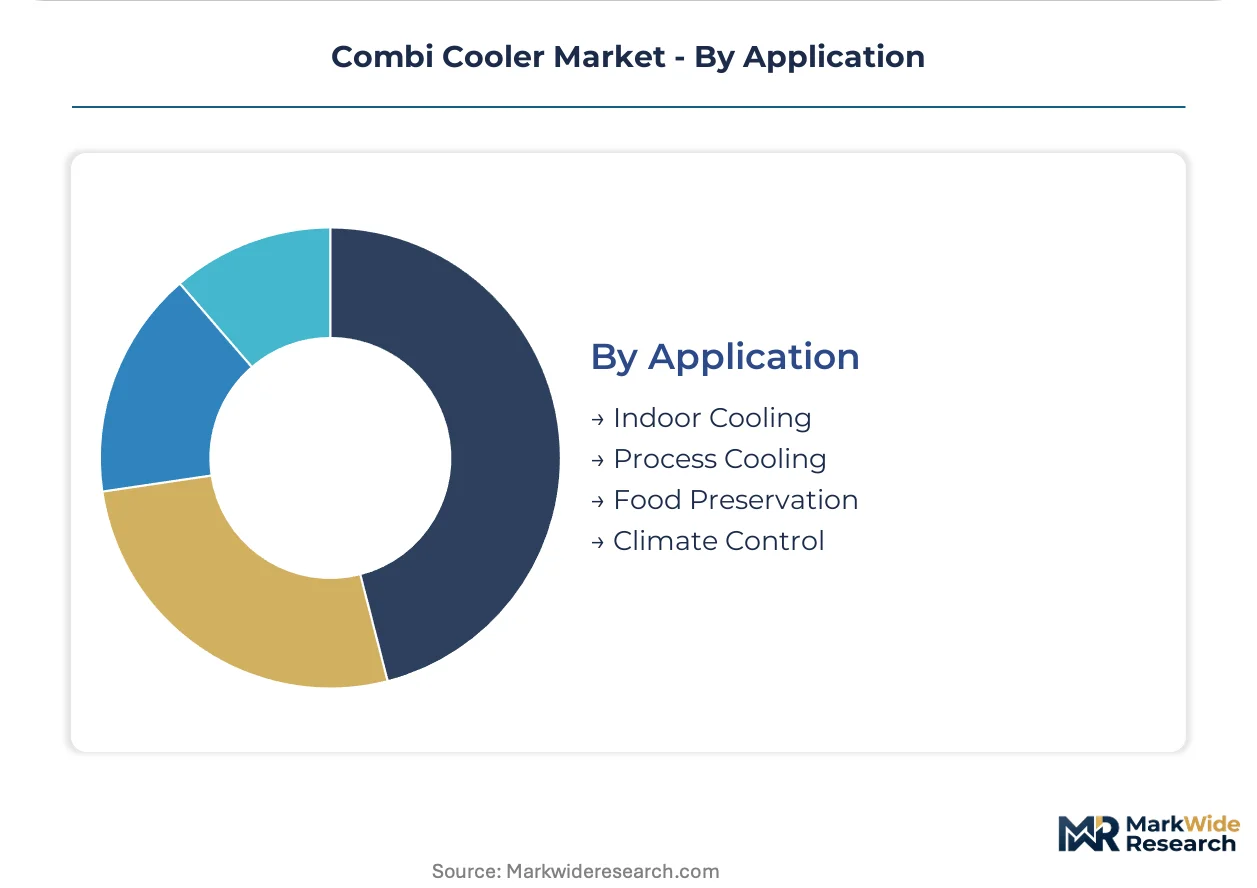
Combi cooler procurement patterns diverge sharply across thermal duty requirements, refrigerant handling constraints, and building integration complexity. Segmentation reveals where engineering investment concentrates and which specification tiers command pricing premiums.
Product Type:
Buyers in this category separate by available infrastructure and thermal load density, with capital constraints and operating cost tolerance driving the selection logic.
- Air-Cooled:Fin-and-tube or microchannel condensers eliminate cooling tower infrastructure, cutting installed cost for distributed residential and light commercial sites. Demand clusters in German single-family retrofits where space constraints prohibit water loop installation and F-Gas service access is limited. The segment trades efficiency for simplicity, with COP penalties accepted where electricity tariffs remain moderate.
- Water-Cooled:Shell-and-tube or plate heat exchanger configurations exploit higher heat transfer coefficients for industrial process loads above 100kW. Dutch dairy processing clusters specify these systems to recover waste heat into CIP preheating loops, capturing thermal value that air-cooled units forfeit. Cooling water quality and treatment chemistry become critical procurement variables.
- Hybrid:Switchable air/water rejection modes adapt to seasonal ambient conditions or utility pricing signals. Japanese commercial buildings deploy hybrid architectures to optimize against METI Top Runner efficiency benchmarks across variable load profiles.
- Modular:Stacked compressor and heat exchanger skids enable capacity scaling without full system replacement. Data center operators in Singapore pilot modular thermal blocks for phased deployment alongside compute rack additions.
Volume sits with Air-Cooled; growth tilts toward Water-Cooled as process cooling specifications tighten.
End User:
Specification authority and lifecycle cost accountability shape procurement behavior across these buyer types.
- Residential:Condensing combi units with integrated domestic hot water cylinders dominate replacement cycles in Italian apartment stock. Homeowners prioritize compact footprint and whisper-quiet operation over peak efficiency, accepting higher running costs for lower upfront outlay. Installation channel fragmentation—plumbers versus HVAC specialists—creates specification inconsistency.
- Commercial:Office and retail landlords specify inverter-driven systems with BACnet integration to meet ESG reporting requirements under CSRD. German commercial property funds now mandate 15-year efficiency warranties as loan covenant conditions.
- Industrial:Pharmaceutical manufacturers in Japan demand redundant cooling circuits with validated temperature logging for biologics storage. FDA and PMDA qualification protocols resist rapid refrigerant transitions, extending legacy system depreciation schedules.
- Hospitality:Hotels balance guest comfort against kitchen refrigeration loads, specifying combi architectures that recover kitchen waste heat for pool water and space conditioning. Mediterranean resorts prioritize summer peak capacity over annualized efficiency metrics.
Industrial buyers capture the steepest expansion trajectory as cold chain validation requirements proliferate.
Technology:
Control sophistication and compressor modulation capability separate price tiers and service contract structures.
- Inverter:Variable-speed scroll and rotary compressors modulate capacity against partial loads, cutting cycling losses in variable climate zones. Japanese manufacturers leverage METI Top Runner certification to export inverter platforms into Southeast Asian commercial markets.
- Non-Inverter:Fixed-speed compressors with hot gas bypass maintain relevance in price-sensitive residential segments and stable-load process applications where capital recovery periods dominate operating cost calculus.
- Smart:Cloud-connected controllers with predictive maintenance algorithms and demand-response interfaces command 20-30% price premiums. Building management system integration shifts from upsell feature to baseline procurement specification in German commercial new-build.
- Conventional:Electromechanical thermostats and standalone operation persist in replacement markets where technician familiarity and spare parts availability outweigh efficiency gains.
Smart systems are climbing the fastest as ESG disclosure mandates harden.
Application:
Thermal duty specificity determines refrigerant selection, heat exchanger materials, and regulatory compliance burden.
- Indoor Cooling:Comfort conditioning applications prioritize low noise and rapid pull-down capability over precision control. Residential and light commercial specifications converge on R-32 and R-454B as EU F-Gas phase-down accelerates.
- Process Cooling:Pharmaceutical and dairy applications demand ±0.5K temperature stability and redundant compressor circuits. CO2 transcritical systems with parallel compression and ejector expansion are consolidating position in German and Danish food processing.
- Food Preservation:Supermarket display case and cold room applications drive heat recovery integration to space heating and domestic hot water loads. German REWE and EDEKA chains specify transcritical CO2 as baseline for new-build programs.
- Climate Control:Precision humidity and temperature management for data centers and cleanrooms requires glycol-based secondary loops and N+1 redundancy. Hyperscale facilities in Virginia pilot heat export to district heating networks.
Process Cooling anchors current revenue; Food Preservation is expanding most quickly as supermarket retrofit cycles accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Copper foil mills in northern Germany and aluminum extrusion plants in northern Italy anchor European heat exchanger supply chains for combi cooler manufacturing. These material localities shape regional production footprints and procurement radii across the continent.
Germany
Pharmaceutical cold chain expansion in Bavaria and Baden-Württemberg drives specification upgrades for redundant cooling circuits. EU F-Gas Regulation phase-down schedules compress refrigerant choice sets for stationary equipment. The Ruhr industrial cluster concentrates heat exchanger fabrication for process cooling applications serving dairy processing facilities.
Italy
Residential replacement cycles in Lombardy and Veneto prioritize compact condensing combi units with integrated domestic hot water cylinders. The national transposition of EU F-Gas Regulation mandates technician retraining for flammable refrigerant handling. Emilia-Romagna hosts engineering centers specializing in inverter-driven compressor modulation for Mediterranean climate zones.
Japan
METI Top Runner efficiency benchmarking shapes export competitiveness for inverter-based systems targeting Southeast Asian commercial markets. Osaka-Kansai manufacturers optimize variable-speed scroll platforms against escalating COP thresholds. Pharmaceutical manufacturing clusters around Tokyo specify redundant cooling architectures for biologics storage with PMDA-validated temperature logging.
Netherlands
Dairy processing clusters in Friesland and Gelderland deploy water-cooled combi architectures to capture waste heat into CIP preheating loops. REACH compliance frameworks tighten material substance restrictions on brazing alloys and gasket compounds. The Randstad logistics corridor concentrates cold storage retrofit demand from supermarket chains transitioning to transcritical CO2 systems.
United States
Hyperscale data center operators in Virginia pilot combi-derived thermal loops rejecting heat to district heating networks. EPA Significant New Alternatives Policy narrows approved refrigerant lists for imported equipment, creating compliance friction with European approval timelines. The Pacific Northwest software corridor generates specification pull for cloud-connected controllers with predictive maintenance algorithms.
Combi Cooler Market Competitive Environment
Global majors compete with regional champions across refrigerant transition timelines and heat exchanger integration depth. The vendor base separates into three tiers: full-system integrators with captive component manufacturing, specialized heat exchanger fabricators supplying downstream assemblers, and regional boiler manufacturers extending into thermal management. Strategic moves concentrate on backward integration into plate heat exchanger production and geographic expansion through distribution partnerships in Southeast Asian commercial markets.
Among European heating equipment specialists, Vaillant Group and Viessmann Werke GmbH & Co. KG exemplify the premium-tier archetype through R&D intensity in condensing technology and residential system integration. GEA Group occupies a distinct position as a process cooling incumbent with captive manufacturing capabilities. Japanese manufacturers represented by Panasonic anchor the inverter-driven commercial segment, while Italian specialists Ferroli S.p.A. and Ariston Group sit within the Mediterranean residential replacement market structure.
| Leading Market Players |
|---|
| Ariston Group |
| Ferroli S.p.A. |
| Vaillant Group |
| GEA Group |
| Carrier |
| Viessmann Werke GmbH & Co. KG |
| Baxi Heating UK Limited |
| Panasonic |
| Worcester Bosch Group |
| Others |
Value Chain & Pricing Dynamics
Certification-grade bifurcation between EU F-Gas-compliant systems and legacy refrigerant architectures manifests in both pricing premiums and supply chain reconfiguration. Premium-tier manufacturers capture margin through captive heat exchanger production in Germany and Italy, while commodity assemblers face margin compression from London Metal Exchange volatility in copper foil and aluminum extrusions.
Pricing Analysis
Warranty bundling separates premium from commodity tiers, with German manufacturers offering 15-year efficiency guarantees against 5-year standard coverage. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth, with PED-certified pressure vessels and METI Top Runner-rated inverter platforms commanding 20-30% uplifts. Pricing pressure stems from technician retraining costs for A2L/A3 refrigerant handling, which compresses field service margins. Residential replacement buyers in Italy exhibit highest price sensitivity, while Japanese pharmaceutical manufacturers absorb premiums for redundant cooling validation.
Supply Chain Analysis
Single-source vulnerability sits with Japanese and German scroll compressor suppliers, where dual qualification remains rare among mid-tier integrators. Heat exchanger fabrication draws from northern German copper foil mills and northern Italian aluminum extrusion plants, with REACH compliance tightening on brazing alloys. Commodity price volatility in London Metal Exchange-traded inputs creates margin instability without contractual pass-through elasticity. Distribution runs through HVAC wholesalers in Europe and specialized refrigeration contractors in Japan, with direct OEM-to-integrator relationships gaining share in Dutch dairy processing clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents a vertical-integration race where captive plate heat exchanger manufacturing and refrigerant handling certification infrastructure determine margin sustainability. Players pursuing upstream control over thermal transfer components or downstream lock-in through performance contracting will capture structural advantage.
For Market Incumbents: Deepen backward integration into brazed plate heat exchanger production to defend margin against commodity metal volatility. Secure dual-source compressor qualification with Japanese and German suppliers to mitigate single-source vulnerability. Expand captive service networks for A2L/A3 refrigerant handling before technician capacity constraints peak. For New Entrants and Emerging Players: Cloud-connected controller platforms offer the most penetrable entry vector, with German commercial property funds mandating BMS integration as baseline specification. Target data center liquid cooling pilots in Virginia and Singapore where traditional HVAC incumbents lack established relationships. Pursue energy-as-a-service contracting models in Dutch dairy processing to bypass capital equipment procurement cycles. For Investors and Strategic Acquirers: Re-rating potential sits with heat exchanger fabricators possessing in-house gas cooler engineering for CO2 transcritical systems, given supermarket retrofit acceleration across Germany and Denmark. Long-term viability hinges on refrigerant transition execution over the next decade. Monitor EU F-Gas phase-down enforcement velocity as the critical inflection signal for stranded legacy inventory risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Heat Exchanger Manufacturing | Captive production of brazed plate assemblies insulates GEA Group and Vaillant Group from copper price volatility. |
| Refrigerant Handling Certification Infrastructure | Technician training networks for A2L/A3 refrigerants create defensive moats as EU F-Gas enforcement tightens. |
| Cloud-Connected Controller Development | Predictive maintenance algorithms command 20-30% price premiums in German commercial new-build specifications. |
| Energy-as-a-Service Contracting Models | Dutch thermal output contracting bypasses equipment ownership, compressing traditional OEM service revenue. |
| CO2 Transcritical System Engineering | In-house gas cooler and ejector capabilities consolidate vendor relationships with German REWE and EDEKA chains. |
Study Parameters
Independent corroboration across OEM engineering directors, refrigeration contractor networks, and pharmaceutical facility managers underwrites the qualitative findings. Primary fieldwork encompassed plant engineers at Dutch dairy processing clusters, procurement leads at German supermarket chains, and aftermarket service heads in Italian residential replacement channels. Secondary validation drew from EU F-Gas Regulation implementation reports, METI Top Runner certification databases, and SEC filings of listed thermal equipment manufacturers. Bottom-up demand modeling triangulated against top-down industry association estimates.
Comparable-period anchoring established baseline growth rates from historical deployment trajectories across the projection horizon. Segmentation modeling incorporated product type, end user archetype, technology tier, and application-specific thermal duty requirements. CAGRs derived from unit shipment trajectories weighted by average selling price evolution, with refrigerant transition timelines and efficiency benchmark escalation as key forecast inputs.
The model holds under steady EU F-Gas phase-down enforcement and stable London Metal Exchange pricing; deviation in refrigerant approval timeline divergence or copper supply disruption would shift volume and value trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Service Equipment
Commercial Bar Equipment Market
Food Service Equipment
Restaurant Equipment Market
Food Service Equipment
Dispensing Tap Market
Food Service Equipment
Digital Menu Boards Market
Food Service Equipment
Commercial Griddles and Flat Top Grills Market
Food Service Equipment
Food and Beverage Vending Machine Market
Food Service Equipment
Sheet Pan Racks Market
Food Service Equipment
Rapid Cook-High Speed Ovens Market
Food Service Equipment
Germany Countertop Ice Makers Market
Food Service Equipment
Hospital Foodservice Equipment Market
Food Service Equipment
Warewashing Equipment Market
Food Service Equipment
Commercial Refrigerator Market
Food Service Equipment
Global Refrigerated Display Cases and Chilled Rooms Market
Food Service Equipment
Hot Food Display Cabinet Market
Food Service Equipment
Back Bar Coolers Market
Food Service Equipment
Meal Delivery Carts and Racks Market