
 Multiservice Provisioning Platform Market | 2026-2036
Multiservice Provisioning Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Multiservice Provisioning Platform Market Intelligence
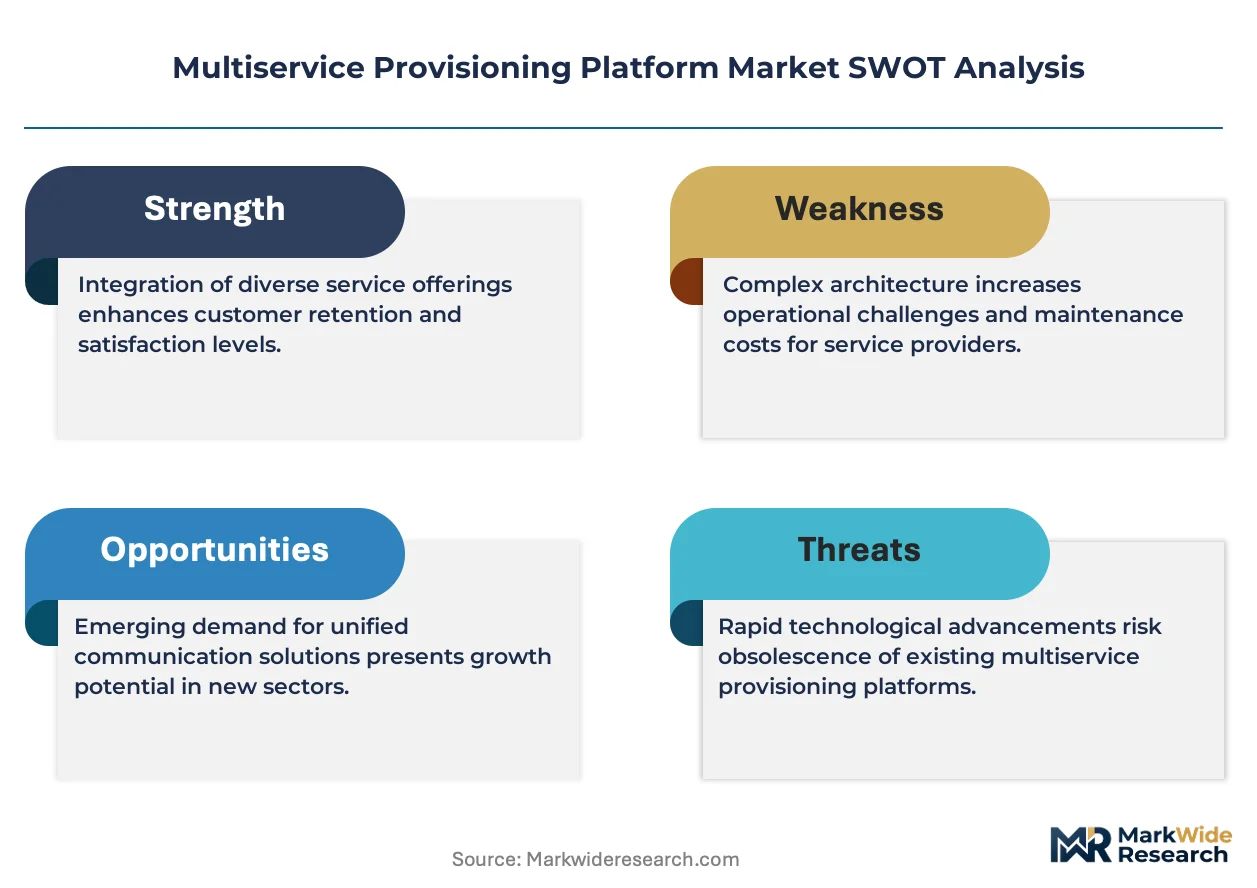
A divergence between advanced service assurance capabilities and basic network orchestration is repositioning the market, splitting it between high-end and commodity tiers. Cisco Systems Inc. leverages its broad networking portfolio to offer integrated security and orchestration solutions. Ciena Corp. differentiates through its specialization in optical networking and coherent optics, targeting high-capacity metro and long-haul networks. Ericsson sustains its position by focusing on mobile backhaul solutions for its expansive 5G infrastructure customer base.
A Multiservice Provisioning Platform is a network device that aggregates diverse traffic types like voice, data, and video onto a single optical transport network. These platforms historically supported legacy protocols such as TDM and SONET/SDH but now primarily manage packet-based traffic. Cloud-Based deployment models offer greater scalability for Managed Service Providers compared to traditional On-Premises systems. Among solution types, Network Orchestration and Service Assurance are critical for operators managing complex, multi-vendor environments.
Regulatory bodies like the US FCC and China's MIIT mandate specific network performance and security standards. European Union cybersecurity directives influence the security management features required in these platforms, shaping product development. Vendors must now decide whether to prioritize backward compatibility for legacy systems or focus exclusively on next-generation virtualized network services.
Market Dynamics
The market's primary dynamic is the architectural shift from hardware-centric legacy systems to software-defined networking and network function virtualization. This transition forces telecommunication operators to overhaul capital expenditure models and operational skill sets, creating a clear division between next-generation and legacy-focused platform providers.
Growth Catalysts
- 5G Network Rollouts:The global deployment of 5G infrastructure necessitates extensive upgrades to mobile backhaul networks, demanding MSPPs that can handle increased traffic density and diverse service requirements.
- Data Center Interconnect Expansion:Rapid growth of cloud services fuels demand for high-capacity optical links between data centers, particularly in markets like India, creating a strong pull for advanced MSPP solutions.
- National Broadband Plans:Government mandates in countries like Australia and Malaysia to expand fiber-optic access to underserved areas provide a direct stimulus for telecommunication operators to invest in new optical transport hardware.
Market Restraints
- High Capital Outlay:The substantial upfront investment required for deploying next-generation optical transport networks and associated virtualization software acts as a significant barrier for smaller or budget-constrained telecommunication operators.
- Multi-Vendor Interoperability:Persistent challenges in ensuring seamless operation and orchestration across equipment from different vendors complicate network upgrades and limit operator flexibility, increasing integration costs and deployment times.
- Disaggregated Hardware Threat:The emergence of open-source and "white box" networking solutions provides a low-cost substitute, putting price pressure on traditional, integrated MSPP systems and eroding incumbent vendor margins.
Strategic Opportunities
- Edge Computing Infrastructure:The deployment of computing resources at the network edge for applications like industrial IoT and autonomous systems creates a need for compact, low-latency MSPPs in new, decentralized locations.
- AI-Powered Service Assurance:Integrating artificial intelligence into network management tools offers a path to predictive analytics, enabling proactive fault detection and automated network optimization for service providers managing complex topologies.
- Network Modernization in Africa:Telecommunication operators across countries like Nigeria and Kenya are upgrading their core networks, presenting an opportunity for vendors to supply next-generation platforms that bypass legacy technology cycles.
Industry Challenges
- Specialized Talent Scarcity:A shortage of network engineers possessing hybrid skills in optical physics, IP routing, and software orchestration creates a significant operational bottleneck for operators managing network transformation projects.
- Legacy System Migration Risk:The process of migrating critical services from deeply embedded SONET/SDH and TDM infrastructure to new packet-based platforms is complex and carries a high risk of service disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiservice Provisioning Platform Market |
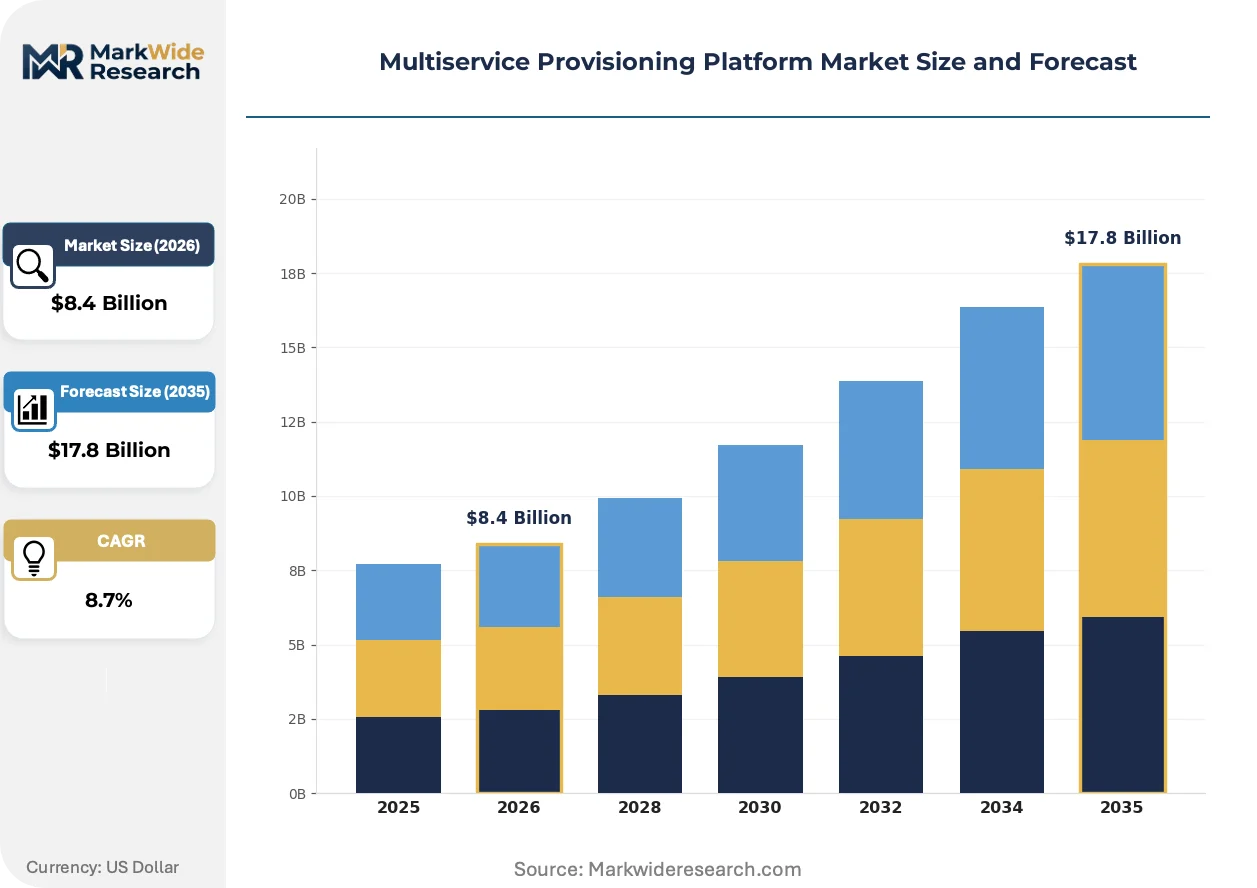
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $17.8 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid Cloud, Edge Computing Solution Type: Customer Management, Network Orchestration, Billing Integration, Service Assurance, Security Management Use Case: Voice & Data Convergence, IPTV Delivery, Virtualized Network Services, IoT Connectivity, Unified Communications End User Industry: Telecommunication Operators, Managed Service Providers, Internet Service Providers, Content Delivery Networks |
| Companies Covered | Siemens AG, Ciena Corp., Cisco Systems Inc., Nortel Networks Corp., ECI Telecom Ltd., Ericsson, Alcatel SA, Sycamore Networks Inc., Fujitsu Network Communications Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiservice Provisioning Platform Market Strategic Shifts & Innovations
A fundamental re-architecting of network functions is underway, driven by software-defined principles. This shift is dissolving traditional hardware boundaries and redefining how network services are provisioned, managed, and monetized by telecommunication operators across different geographies.
Packet-optical transport systems represent a key product evolution, combining DWDM optical transport and Layer 2/3 packet switching into a single platform. Telecommunication operators and large enterprises are adopting these systems to simplify network architecture and reduce power consumption. This integrated technology is converging with network orchestration software, creating a more agile and programmable infrastructure foundation for new services.
European Union cybersecurity directives, such as the NIS 2 Directive, impose stricter security requirements on critical infrastructure, including telecommunication networks. This regulation forces operators to enhance the security posture of their network management and provisioning platforms. The service assurance segment is most affected, now requiring advanced threat detection and security policy enforcement features built directly into the MSPP.
Operators are increasingly shifting from fixed-capacity hardware acquisitions to flexible, consumption-based software licensing models. This change disrupts the traditional one-time capital expenditure cycle for network equipment vendors. The trend is most visible in North America, where telecommunication firms prioritize operational agility and pay-as-you-grow capacity for services like 5G network slicing.
Multiservice Provisioning Platform Market Segmentation
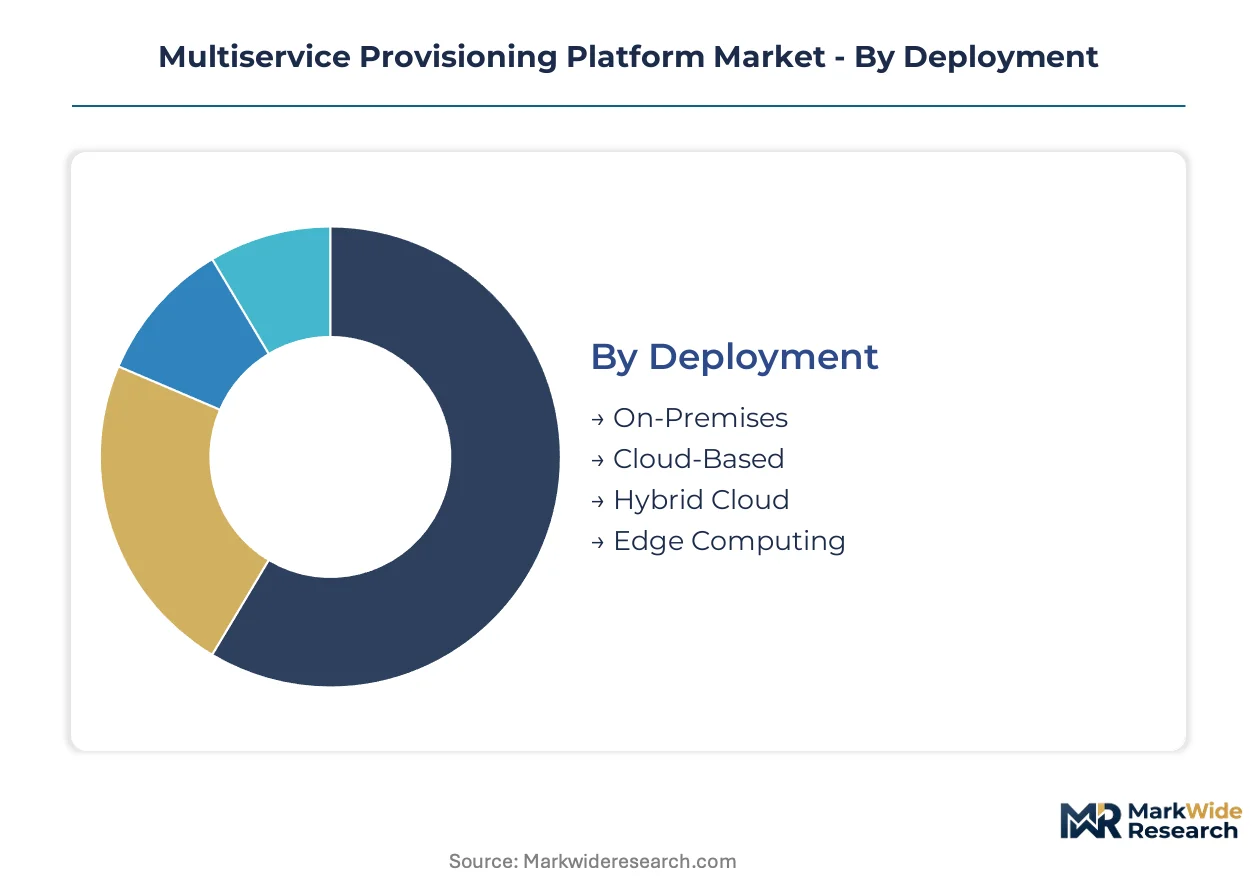
The Multiservice Provisioning Platform market is segmented across several critical dimensions, reflecting the diverse operational needs and technological priorities of network operators. Understanding these segments is vital for vendors to tailor solutions that address specific infrastructure challenges and service delivery requirements. This segmentation highlights distinct adoption patterns and investment areas within the evolving telecommunications landscape.
Deployment:
Telecommunication operators prioritize deployment models based on operational control, scalability requirements, and initial capital expenditure for their network infrastructure.
- Cloud-Based:These platforms leverage public or private cloud infrastructure, offering significant scalability and agility for managed service providers and telecommunication firms. Operators in North America increasingly adopt cloud-based models to support flexible consumption-based software licensing for 5G network slicing.
- Edge Computing:Deploying MSPPs at the network edge supports low-latency applications like industrial IoT and autonomous systems, creating new opportunities for decentralized network architectures. Countries like Germany are exploring edge deployments to enhance manufacturing automation and data processing closer to the source.
- On-Premises:Traditional deployments where hardware and software reside within the operator’s own data centers, offering maximum control and security for legacy systems. Many telecommunication operators in India maintain significant on-premises infrastructure for core network functions.
- Hybrid Cloud:A combination of on-premises and cloud resources, allowing operators to balance control over sensitive data with the flexibility of cloud services.
Volume sits with On-Premises; growth tilts toward Cloud-Based.
Solution Type:
The functional focus of a multiservice provisioning platform dictates its value proposition and strategic importance for network operators managing complex, multi-vendor environments.
- Network Orchestration:This solution automates the provisioning, configuration, and management of network services across diverse hardware and software components, driven by the shift to SDN and NFV. Telecommunication operators in China rely on advanced network orchestration to manage their extensive 5G infrastructure rollouts.
- Service Assurance:These platforms monitor network performance, detect faults, and ensure service level agreements are met, incorporating AI-powered analytics for proactive issue resolution. European Union cybersecurity directives, such as NIS 2, mandate enhanced security management features within service assurance platforms.
- Security Management:Integrates robust security features to protect network infrastructure and data from cyber threats, addressing regulatory mandates like those from the US FCC and China's MIIT.
- Customer Management:Tools that handle subscriber data, service subscriptions, and customer-facing interactions, streamlining service delivery processes.
- Billing Integration:Connects provisioning platforms with billing systems to accurately charge for services and manage revenue streams, a critical function for monetizing new offerings.
Network Orchestration solutions currently dominate deployments, while Security Management is expanding most quickly.
Use Case:
The specific service offerings and revenue streams dictate the primary use case for multiservice provisioning platforms across telecommunication networks.
- Virtualized Network Services:These platforms enable the dynamic creation and management of network functions as software instances, supporting agile service deployment and resource optimization. Telecommunication operators across Japan are increasingly adopting virtualized network services for rapid deployment of new enterprise solutions.
- IoT Connectivity:MSPPs facilitate the management and provisioning of diverse IoT devices and their data traffic, supporting applications from smart cities to industrial automation. Countries like the United Arab Emirates are investing in IoT connectivity for smart infrastructure projects, driving demand for these platforms.
- Voice & Data Convergence:Aggregates traditional voice and modern data traffic onto a single optical transport network, simplifying infrastructure and reducing operational costs.
- Unified Communications:Integrates various communication services like voice, video, and messaging onto a single platform for enterprises and service providers.
- IPTV Delivery:Manages the efficient and reliable distribution of Internet Protocol Television services, ensuring quality of experience for subscribers.
Voice & Data Convergence remains a foundational use case, but Virtualized Network Services exhibit the steepest expansion trajectory.
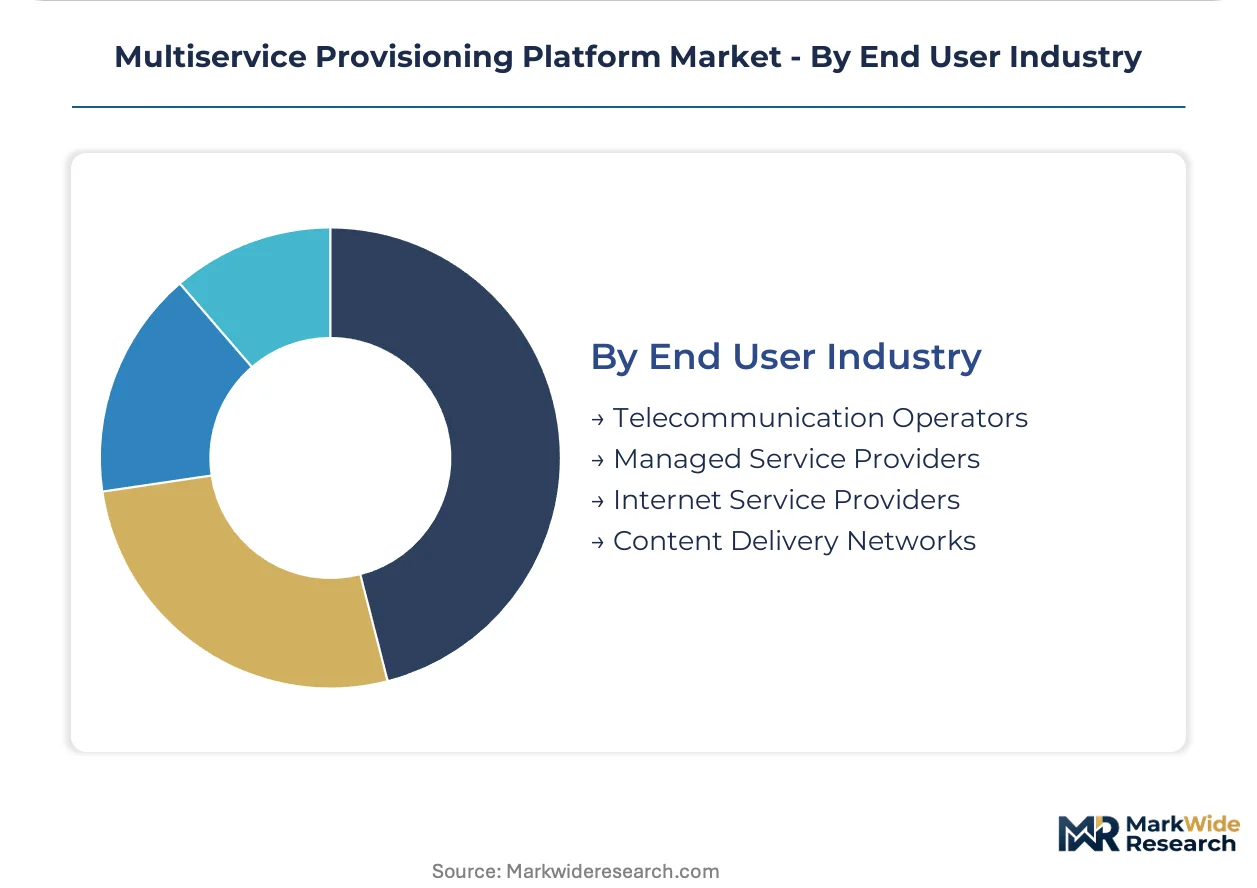
End User Industry:
Customer type influences the feature set and scale required from multiservice provisioning platforms, driving specialized product development and market focus.
- Telecommunication Operators:The primary adopters of MSPPs, utilizing them for core network upgrades, 5G rollouts, and the delivery of diverse services to residential and business customers. Ericsson sustains its market position by focusing on mobile backhaul solutions for its expansive 5G infrastructure customer base among these operators.
- Managed Service Providers:These entities leverage MSPPs to offer scalable and flexible network services to their enterprise clients, often preferring cloud-based deployment models for operational efficiency. Ciena Corp. differentiates through its specialization in optical networking, targeting high-capacity metro networks for these providers.
- Internet Service Providers:Utilize MSPPs to manage their network infrastructure, ensuring reliable internet access and supporting value-added services for their subscriber base.
- Content Delivery Networks:Employ MSPPs to optimize the distribution of digital content by ensuring high-capacity links and efficient traffic management, particularly for streaming video.
Telecommunication Operators represent the largest segment, with Managed Service Providers gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's advanced technological ecosystem drives significant Multiservice Provisioning Platform adoption, particularly for cloud-based models supporting 5G network slicing. This region's focus on software-defined networking and virtualization sets a global benchmark. Telecommunication operators here increasingly demand flexible, consumption-based software licensing.
United States
Telecommunication operators in the United States prioritize cloud-based MSPP deployments for agile 5G network slicing and operational flexibility. The US FCC mandates specific network performance and security standards, influencing platform development. Major data centers in Virginia and Texas fuel demand for high-capacity optical links between facilities.
China
Extensive 5G infrastructure rollouts in China necessitate advanced network orchestration solutions for managing complex, multi-vendor environments. China's MIIT actively promotes network densification and capacity expansion across its vast network. Shanghai's technology hubs require robust MSPPs for sophisticated enterprise solutions and data center interconnectivity.
India
India's rapid 5G deployment and data center interconnect expansion generate substantial demand for next-generation Multiservice Provisioning Platforms. The TRAI's initiatives for national broadband plans stimulate investment in optical transport hardware. Bengaluru's IT sector and new data center parks drive the need for scalable network infrastructure.
Germany
German industries are exploring edge computing deployments for applications like industrial IoT and manufacturing automation, creating demand for compact, low-latency MSPPs. European Union cybersecurity directives, such as NIS 2, influence security management features in these platforms. Munich's automotive and industrial clusters require robust, secure network foundations.
Japan
Telecommunication operators across Japan increasingly adopt virtualized network services for agile deployment of new enterprise solutions. METI's push for digital transformation encourages investment in advanced network infrastructure. Tokyo's dense urban environment and technology firms drive demand for efficient packet-optical transport systems.
Multiservice Provisioning Platform Market Key Industry Players
Premium-margin players sit above commodity-margin players across service assurance capabilities and network orchestration sophistication. The market structure exhibits a tiered consolidation, with established vendors offering comprehensive portfolios alongside specialized innovators focusing on niche segments. Three strategic archetypes emerge: integrated solution providers, optical networking specialists, and mobile backhaul experts. Dominant competitive moves include portfolio diversification and strategic partnerships to address complex integration challenges.
Within the integrated solution provider archetype, Cisco Systems Inc., a prominent US-based corporation, represents a significant entity, leveraging its broad networking portfolio to offer comprehensive security and orchestration capabilities across diverse network environments. Ciena Corp., another US-headquartered company, exemplifies specialization in optical networking, particularly differentiating through its focus on coherent optics for high-capacity metro and long-haul networks. Ericsson, a Swedish multinational corporation, sustains its market position by anchoring the mobile backhaul segment, catering to an expansive 5G infrastructure customer base across various geographies and supporting critical core network functions.
| Leading Market Players |
|---|
| Siemens AG |
| Ciena Corp. |
| Cisco Systems Inc. |
| Nortel Networks Corp. |
| ECI Telecom Ltd. |
| Ericsson |
| Alcatel SA |
| Sycamore Networks Inc. |
| Fujitsu Network Communications Inc. |
| Others |
Cost & Logistics Intelligence
Vertical integration into core network infrastructure by telecommunication operators anchors their supply position and dictates pricing power for specialized Multiservice Provisioning Platform solutions. This strategic choice influences the market's cost structure and vendor relationships.
Pricing Analysis
Outcome-based pricing for Multiservice Provisioning Platforms ties platform costs to network performance metrics like throughput and service uptime. The dominant pricing model is a hybrid of subscription-based software licensing and project-based hardware acquisition. Price differentiation stems from customization levels for specific network environments and the depth of integrated security features. Pricing softness reflects the increasing availability of disaggregated hardware alternatives, particularly impacting commodity-tier offerings. Managed Service Providers exhibit higher price sensitivity compared to large telecommunication operators.
Supply Chain Analysis
Optical component supply rests heavily on manufacturers in China and Japan, feeding the Multiservice Provisioning Platform ecosystem. Key component dependencies include specialized optical transceivers, high-performance processors, and custom ASICs. A structural risk involves single-source vulnerability for advanced coherent optics, particularly from US-based specialists. Distribution runs through direct sales channels from large equipment vendors to telecommunication operators and Managed Service Providers. Regional logistics hubs in Europe and North America facilitate final assembly and deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Multiservice Provisioning Platform market presents a supply-constrained story, where specialized optical component manufacturing capacity bottlenecks often prop up pricing. This constraint affects the availability and cost of high-performance networking solutions.
For Market Incumbents: Deepen software-defined networking capabilities to counter the threat of disaggregated hardware alternatives. Invest in vertical integration for critical optical components to secure supply chains and mitigate price volatility. Enhance AI-powered service assurance features to differentiate from commodity offerings and retain high-value telecommunication operator contracts. Prioritize R&D in next-generation coherent optics to maintain technological leadership.
For New Entrants and Emerging Players: Enter via cloud-based MSPP solutions targeting Managed Service Providers in North America, leveraging flexible licensing models. Focus on edge computing infrastructure in countries like Germany for industrial IoT applications, a penetrable segment due to decentralized demand. Offer specialized security management platforms with enhanced threat detection, using a partnership-driven go-to-market angle with existing network integrators.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized software firms providing network orchestration and AI-powered service assurance. The market retains strong long-term viability over a five-to-ten year window, driven by ongoing 5G and data center expansion. Target acquisition profiles include innovators in NFV/SDN software and compact edge computing hardware. A crucial signal to watch is the acceleration of telecommunication operators' shift from on-premises to cloud-native network functions.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Software-Defined Networking Portfolio | This initiative enhances agility for telecommunication operators managing complex multi-vendor environments. |
| Invest in Coherent Optics R&D | Advanced coherent optics enable Ciena Corp. to support higher capacity metro and long-haul networks. |
| Form Strategic Partnerships for Edge Deployments | These partnerships allow vendors to target new decentralized opportunities in industrial IoT for countries like Germany. |
| Acquire AI-Powered Service Assurance Firms | Integrating AI into platforms offers predictive analytics and automated network optimization for service providers. |
| Develop Consumption-Based Licensing Models | This shift helps telecommunication firms in North America achieve operational agility and flexible 5G network slicing capacity. |
Research Approach
Multi-period observation of network traffic growth and infrastructure investment anchored the trend analysis, supplemented by interviews with industry stakeholders. Primary research involved discussions with telecommunication operator CTOs, Managed Service Provider executives, and network engineers. Secondary validation drew from telecommunication industry reports, US FCC regulatory filings, and corporate financial disclosures. This approach ensured robust bottom-up and top-down triangulation for market sizing.
An input-output matrix framework modeled market dynamics across the analysis window, integrating various data points. Segmentation dimensions included deployment model, solution type, use case, and network capacity requirements. Compound Annual Growth Rates were derived from historical trends and projected technological shifts, including 5G rollout trajectories. Key forecast inputs included projected 5G subscriber growth and data center expansion rates.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rapid technological disruption or unforeseen regulatory shifts. Forecasts reflect assumptions regarding telecommunication operator investment cycles and global economic stability. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Ethernet Backhaul Equipment Market
Network Technology
Global Ethernet Switch and Routers Market
Network Technology
Software-Defined Wide Area Network (SD-WAN) Market
Network Technology
DHCP and IP Address Management Market
Network Technology
Global Carrier Wi-Fi Equipment Market
Network Technology
Wi-Fi Router Market
Network Technology
GCC Set-Top Box Market
Network Technology
Passive Optical LAN (POL) Market
Network Technology
North America Structured Cabling Market
Network Technology
Structured Cabling Market
Network Technology
Carrier Routing Equipment Market
Network Technology
Protocol Analyzer Market
Network Technology
Session Border Controller (SBC) Market
Network Technology
Virtual Router Market
Network Technology
Passive Optical Network Market
Network Technology
Asia Pacific Structured Cabling Market