
 Global Managed Wi-Fi Solutions Market | 2026-2036
Global Managed Wi-Fi Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Managed Wi-Fi Solutions Market Foresight
Buyer concentration across large corporations and managed service providers is rebalancing as mid-market enterprises fragment into discrete procurement pools. Cisco Systems leverages its channel depth to sustain dominance in cloud-based controller architectures, while Aruba Networks anchors its position through campus switching integration. Ruckus Wireless specializes in high-density venue coverage, competing on RF engineering rather than software stack breadth.
Managed Wi-Fi solutions encompass centrally orchestrated wireless local area network infrastructure combining access points, cloud controllers, and policy engines operating across 2.4 GHz, 5 GHz, and 6 GHz spectrum bands with WPA3-Enterprise encryption. These systems deliver measurable quality-of-service guarantees for latency-sensitive traffic across distributed commercial environments. Cloud-based deployment captures the majority of new margin pools as operational expenditure models displace capital-intensive controller hardware, while security management functions extract premium pricing through zero-trust network access integration. Network monitoring analytics segments show fastest expansion as IT departments demand predictive fault detection across multi-vendor environments.
FCC spectrum allocation decisions in the United States, ETSI EN 303 687 standards in Europe, and MIIT radio type approval requirements in China collectively shape product certification timelines and hardware interoperability obligations. GDPR and HIPAA frameworks further compel encryption-at-rest and audit-log capabilities within managed platform software. Stakeholders must weigh regulatory divergence against platform standardization when architecting multi-territory deployments.
Market Dynamics
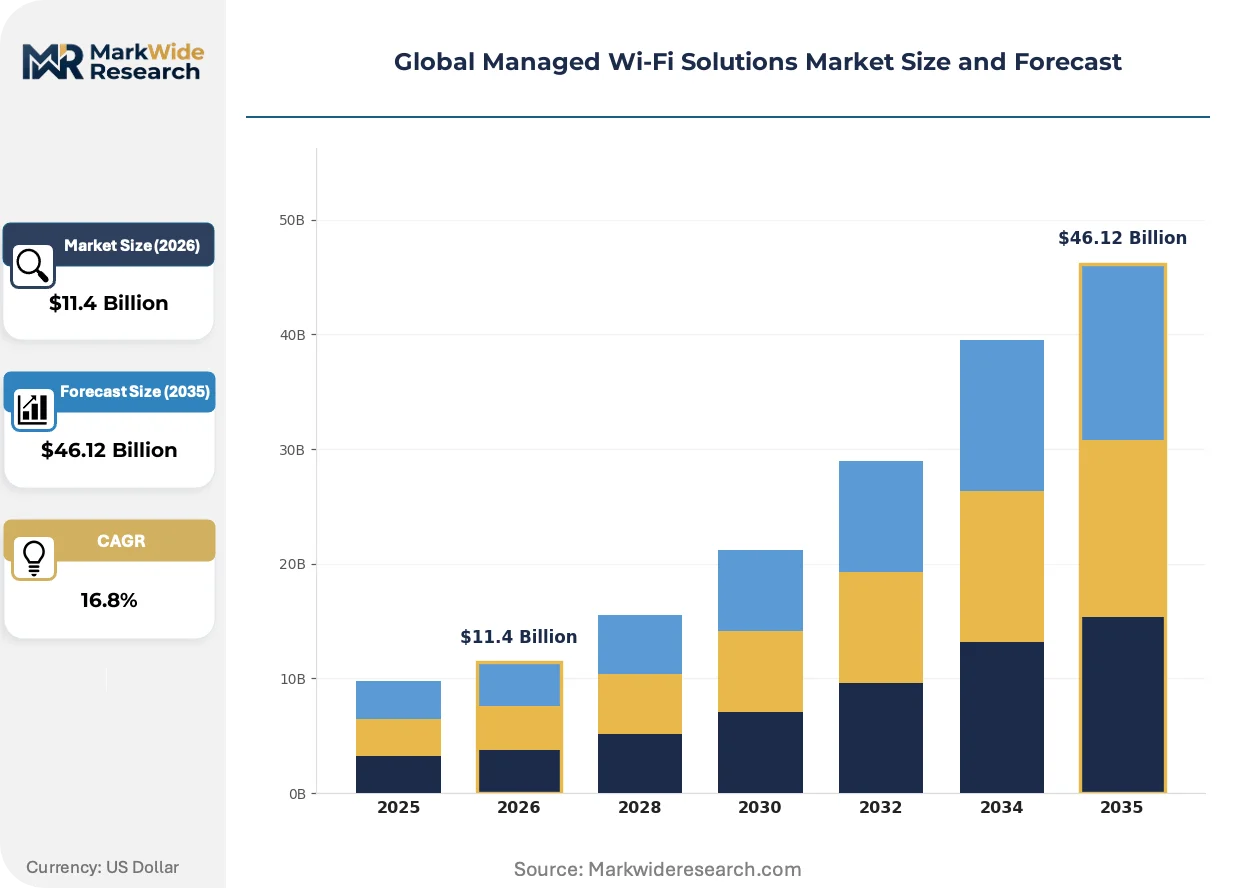
Cloud-native controller architectures are compressing hardware refresh cycles as enterprise buyers abandon capital-intensive on-premises deployments for subscription-based operational expenditure models. This structural shift redistributes margin pools toward software vendors and managed service providers while eroding traditional equipment resale economics.
Growth Catalysts
- HIPAA encryption mandates:Healthcare facilities across the United States face intensifying audit requirements for wireless patient data transmission. Centrally managed WPA3-Enterprise infrastructure satisfies these compliance obligations while reducing IT staffing overhead.
- 6 GHz spectrum commercialization:FCC unlicensed allocations in the United States and ETSI EN 303 687 harmonization in Europe expand channel capacity for high-density venue deployments. Hardware refresh cycles accelerate as enterprises capture interference-free bandwidth.
- Zero-trust network access convergence:Policy engines are integrating identity-based segmentation directly into wireless controllers. Financial services and government buyers demand this architecture to replace perimeter-based security models.
Market Restraints
- Semiconductor supply concentration:Wi-Fi 6E and Wi-Fi 7 chipsets depend on TSMC and Samsung foundry capacity concentrated in Taiwan and South Korea. Geopolitical friction threatens hardware delivery timelines for access point manufacturers.
- Radio certification fragmentation:MIIT type approval in China, FCC equipment authorization in the United States, and TELEC certification in Japan impose divergent testing protocols. Multi-territory product launches face sequential regulatory delays.
- Legacy controller stranded assets:Enterprises with depreciated on-premises hardware resist full cloud migration due to sunk cost rationalization. Hybrid management complexity persists as a drag on pure subscription conversion rates.
Strategic Opportunities
- India smart city infrastructure:Municipal Wi-Fi deployments under the Smart Cities Mission create procurement pools for managed service operators. TRAI spectrum recommendations favor neutral host models for public venue coverage.
- Predictive analytics unbundling:AI-driven fault detection modules are separating from core controller subscriptions. IT departments purchase these capabilities standalone for multi-vendor environment visibility.
- EU CSRD sustainability reporting:Corporate sustainability disclosure requirements mandate energy consumption tracking for network infrastructure. Power-over-Ethernet monitoring and green access point certifications extract premium positioning.
Industry Challenges
- RF engineering talent scarcity:Dense venue deployments require specialized site survey and interference mitigation expertise. System integrators compete for certified wireless professionals capable of heatmap modeling and spectrum analysis.
- Multi-vendor integration complexity:Enterprises operate heterogeneous access point estates accumulated through acquisition and decentralized procurement. Centralized management platforms must normalize disparate command interfaces and firmware versions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Managed Wi-Fi Solutions Market |
| Market Size in 2026 | $11.4 Billion |
| Market Size in 2035 | $46.12 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Solution Type: Network Monitoring, Security Management, Access Control, Bandwidth Optimization, Analytics Application: Hospitality, Education Institutions, Healthcare Facilities, Retail Stores, Government Offices Customer Type: Small Enterprises, Medium Businesses, Large Corporations, Managed Service Providers |
| Companies Covered | Cisco Systems, Aruba Networks, Ruckus Wireless, Ubiquiti Networks, Extreme Networks, Netgear, TP-Link, D-Link, Juniper Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Managed Wi-Fi Solutions Market Shifts & Advancements
Artificial intelligence inference at the network edge is compressing mean-time-to-resolution for wireless performance degradation. Vendors are embedding telemetry analysis directly into access point firmware to preempt client connectivity failures.
Wi-Fi 7 is integrating 320 MHz channel bonding and multi-link operation to deliver deterministic latency for augmented reality and industrial automation workloads. Manufacturing facilities in Germany and Japan are piloting these deployments for time-sensitive networking applications. The technology is integrating deterministic wireless into operational technology environments previously served by proprietary protocols.
FCC spectrum enforcement actions against unauthorized 6 GHz device operation are tightening equipment compliance verification. Manufacturers face expanded testing documentation requirements for automated frequency coordination certification. United States enterprise buyers are prioritizing authorized equipment databases to avoid interference liability exposure.
Subscription-based network-as-a-service contracts are displacing perpetual license purchases among mid-market enterprises. Value-added distributors are building managed Wi-Fi practices to capture recurring revenue streams. This pattern is most visible in United States commercial real estate and retail verticals where capital constraints favor operational expenditure treatment.
Global Managed Wi-Fi Solutions Market Segmentation
Managed Wi-Fi procurement decisions split across four distinct dimensions: how infrastructure is hosted, what functional modules are prioritized, where connectivity is deployed, and who holds the purchasing authority. Each axis carries different margin structures and vendor competitive dynamics.
Deployment:
Capital allocation preferences between operational and capital expenditure models drive deployment architecture selection.
- Cloud-Based:Subscription controller platforms eliminate on-site hardware refresh cycles. United States healthcare facilities favor this model to satisfy HIPAA audit-log requirements without dedicated security infrastructure.
- On-Premises:Perpetual-license controller hardware remains entrenched in government and financial services with stringent data sovereignty mandates. Germany's BSI compliance framework reinforces this preference for critical infrastructure operators.
- Hybrid:Split architectures preserve legacy controller investments while enabling cloud analytics overlay. Japan's manufacturing sector pilots this approach for gradual operational technology integration.
- Edge:Distributed intelligence processing reduces backhaul dependency for latency-sensitive applications. Smart city deployments in India leverage edge controllers for municipal Wi-Fi resilience.
Volume sits with Cloud-Based deployments; growth tilts toward Edge architectures.
Solution Type:
Module unbundling allows buyers to purchase capabilities separately from core controller subscriptions.
- Network Monitoring:Telemetry aggregation across multi-vendor access point estates. Large corporations with acquisition-driven infrastructure fragmentation purchase standalone modules for unified visibility.
- Security Management:Zero-trust policy enforcement with WPA3-Enterprise and certificate-based authentication. Healthcare facilities mandate this module for HIPAA wireless compliance.
- Access Control:Identity-based segmentation integrating with directory services. Government offices require this for classified network isolation.
- Bandwidth Optimization:Traffic shaping for latency-sensitive voice and video streams. Hospitality venues deploy this to guarantee guest experience SLAs.
- Analytics:AI-driven predictive fault detection and client behavior insights. Retail stores extract footfall patterns for merchandising optimization.
Security Management commands the largest module attach rate; Analytics expands most quickly as IT departments demand predictive capabilities.
Application:
Vertical-specific compliance and density requirements shape solution configuration.
- Hospitality:High-density guest access with captive portal branding and tiered service levels. United States hotel chains prioritize seamless roaming across multi-property portfolios.
- Education Institutions:Massive concurrent device density with content filtering and classroom management integration. K-12 districts in Germany require GDPR-compliant student data handling.
- Healthcare Facilities:Medical-grade reliability with interference mitigation for sensitive equipment. FCC Part 15 compliance for 6 GHz operation is mandatory for United States hospital deployments.
- Retail Stores:Location analytics integration with point-of-sale systems for personalized engagement. Japan's convenience store chains deploy this for inventory-aware promotions.
- Government Offices:Classified network segmentation with audit-trail documentation. India's Smart Cities Mission creates procurement pools for municipal administrative buildings.
Healthcare Facilities represent the highest per-site spending; Education Institutions are climbing the fastest as one-to-one device programs proliferate.
Customer Type:
Organizational scale determines procurement channel and pricing structure.
- Small Enterprises:Simplified cloud packages with minimal IT staffing requirements. Value-added distributors in the United States target this segment with bundled managed services.
- Medium Businesses:Hybrid deployment flexibility with phased cloud migration paths. Germany's Mittelstand manufacturing sector favors this category for operational technology integration.
- Large Corporations:Global template standardization with multi-territory support obligations. Direct vendor relationships predominate with dedicated technical account management.
- Managed Service Providers:White-label platform access for resale to downstream clients. India's telecom operators leverage this model for Smart Cities Mission participation.
Large Corporations dominate absolute spending; Managed Service Providers gain share fastest as subscription economics reshape channel economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare and smart city infrastructure investments concentrate managed Wi-Fi demand across specific national markets, with regulatory frameworks and spectrum policy creating divergent deployment timelines.
United States
HIPAA audit requirements and FCC 6 GHz commercialization drive healthcare facility upgrades. The FCC enforces automated frequency coordination for unlicensed 6 GHz operation. Hospital networks in Texas Medical Center and Boston's Longwood Medical Area deploy medical-grade wireless for interference-sensitive equipment.
Germany
BSI compliance mandates and Industrie 4.0 integration sustain on-premises controller preference. The EU CSRD requires energy consumption disclosure for network infrastructure. Manufacturing clusters in Baden-Württemberg pilot Wi-Fi 7 for time-sensitive networking in automotive production lines.
India
Smart Cities Mission procurement and TRAI neutral-host recommendations expand municipal Wi-Fi coverage. The CEA mandates power consumption standards for telecom equipment. Bengaluru and Hyderabad deploy edge-based controllers for resilient public venue connectivity under municipal contracts.
Japan
Manufacturing automation and aging IT infrastructure create hybrid deployment demand. METI promotes wireless technology adoption for operational technology environments. Industrial corridors in Aichi Prefecture integrate Wi-Fi 7 for deterministic latency in precision assembly operations.
China
MIIT radio type approval requirements and dual carbon goals shape hardware certification and energy efficiency priorities. GB standards enforce encryption capabilities for enterprise wireless. Shenzhen's electronics manufacturing base supplies Wi-Fi 6E and Wi-Fi 7 chipsets for domestic and export markets.
Global Managed Wi-Fi Solutions Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-native specialization and vertical-specific analytics modules. The vendor ecosystem stratifies across three tiers: full-stack infrastructure providers, RF engineering specialists, and white-label platform operators. Competitive positioning depends on channel depth for enterprise accounts and API extensibility for service provider integration. M&A activity targets predictive analytics capabilities; strategic partnerships secure semiconductor supply for Wi-Fi 7 transitions.
Within the full-stack infrastructure tier, Cisco Systems and Aruba Networks exemplify integrated platform approaches spanning campus switching and wireless controllers. Ruckus Wireless occupies a specialist position emphasizing high-density RF engineering for venue deployments. These anchors demonstrate how vendor archetypes align with buyer procurement patterns across healthcare, education, and hospitality verticals.
| Leading Market Players |
|---|
| Cisco Systems |
| Aruba Networks |
| Ruckus Wireless |
| Ubiquiti Networks |
| Extreme Networks |
| Netgear |
| TP-Link |
| D-Link |
| Juniper Networks |
| Others |
Supply & Pricing Matrix
EU CSRD sustainability disclosure mandates for network infrastructure energy consumption create dual gates: qualified supply chains must demonstrate green access point certifications and power-over-Ethernet monitoring capabilities, while premium-tier pricing access requires documented carbon footprint reduction. This regulatory architecture concentrates margin capture among vendors with embedded environmental compliance.
Pricing Analysis
Volume concentrates in cloud-based subscription tiers while margin pools shift toward security management and analytics modules. Price differentiation hinges on zero-trust certification grade and after-sales service bundling for multi-territory deployments. Cost compression in standard hardware tiers intensifies as TSMC and Samsung foundry capacity constraints ease. Small enterprises exhibit highest price sensitivity; large corporations with global template standardization show lowest sensitivity due to compliance-driven procurement.
Supply Chain Analysis
India's phased manufacturing program and China's MIIT radio type approval requirements reshape sourcing toward domestic assembly partners for government and smart city contracts. Wi-Fi 6E and Wi-Fi 7 chipsets draw from Taiwan, South Korea, and China. Radio frequency components, power amplifiers, and antenna arrays feed from concentrated Asian manufacturing bases. Single-source vulnerability in semiconductor foundry capacity threatens hardware delivery timelines. Distribution runs through value-added distributors building managed Wi-Fi practices for recurring revenue capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Semiconductor foundry capacity bottlenecks at TSMC and Samsung prop pricing power for qualified hardware vendors, sustaining premium tiers despite subscription model diffusion.
For Market Incumbents: Acquire predictive analytics capabilities to preempt cloud-native entrants unbundling AI-driven fault detection modules. Deepen channel control through dedicated technical account management for large corporation global templates. Counter emerging white-label platform operators by embedding zero-trust policy engines directly into controller firmware. For New Entrants and Emerging Players: Begin with India smart city infrastructure procurement pools under TRAI neutral-host recommendations, where municipal contracts favor new service operators over entrenched equipment vendors. Target mid-market enterprises in United States commercial real estate with network-as-a-service contracts displacing perpetual licenses. Lead with edge-based deployment architectures for latency-sensitive manufacturing automation in Germany and Japan. For Investors and Strategic Acquirers: FCC enforcement actions against unauthorized 6 GHz device operation are the leading indicator that authorized equipment database compliance will separate viable acquisition targets from liability-exposed hardware vendors. Position for five-to-ten year viability around vendors with automated frequency coordination certification and multi-territory regulatory approval depth. Watch for MIIT type approval acceleration in China as signal of supply chain normalization enabling margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Predictive analytics unbundling creates standalone module vendors for multi-vendor environment visibility. |
| Strategic Partnership | Semiconductor supply agreements with TSMC and Samsung secure Wi-Fi 7 transition capacity for access point manufacturers. |
| Platform Integration | Zero-trust network access convergence embeds identity-based segmentation directly into wireless controllers for financial services. |
| Geographic Expansion | India smart city deployments under Smart Cities Mission create procurement pools for managed service operators. |
| Product Launch | Wi-Fi 7 with 320 MHz channel bonding delivers deterministic latency for German automotive production lines. |
Research Methodology
Document review covered SEC filings, FCC equipment authorization databases, ETSI EN standards documentation, and MIIT radio type approval records, complemented by interviews with CTOs at healthcare systems, IT procurement officers at manufacturing enterprises, platform engineers at cloud controller vendors, and channel partners at value-added distributors. Secondary validation drew from customs trade data for access point hardware flows, hyperscaler capex disclosures for cloud infrastructure investment, and regulatory filing databases for spectrum policy shifts. Bottom-up deployment modeling triangulated against top-down market sizing across subscription and perpetual license revenue pools.
Historical shipment data cross-referenced against panel input from infrastructure vendors and managed service providers anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include deployment architecture, solution module type, vertical application, and customer organizational scale. CAGRs derived from curve-fitting historical cloud migration patterns against semiconductor supply cycle normalization. Industry-specific forecast inputs incorporated FCC spectrum enforcement timelines and EU CSRD sustainability reporting phase-in schedules.
Underlying measurement precision varies by segment; cloud-based deployment and security management module attach rates carry tighter precision than emerging edge architecture adoption. Forecasts reflect assumptions regarding regulatory approval velocity and foundry capacity allocation that could revise with geopolitical friction or spectrum policy divergence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Network Technology
Fiber to the Premises Market
Network Technology
Global Network Monitoring Market
Network Technology
CPE Router Market
Network Technology
5G CPE Device Market
Network Technology
Session Border Controller (SBC) Market
Network Technology
Global Home Networking Device Market
Network Technology
Network Fault Monitoring Tools Market
Network Technology
BYOD Market
Network Technology
Wi-Fi Router Market
Network Technology
Global 5G Smart Antenna Market
Network Technology
Global Wi-Fi Range Extender Market
Network Technology
DHCP and IP Address Management Market
Network Technology
Network Devices Market
Network Technology
Carrier Routing Equipment Market
Network Technology
Europe Video Conferencing Hardware Market
Network Technology
Global Carrier Wi-Fi Equipment Market