
 Global Dissolved Oxygen Meters and Controllers Market | 2026-2036
Global Dissolved Oxygen Meters and Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dissolved Oxygen Meters and Controllers Market Foresight
Multi-sourced component procurement is expanding across dissolved oxygen instrument manufacturing as vendors diversify sensor supply chains. Thermo Fisher Scientific leverages in-house optical sensor fabrication to reduce electrochemical probe dependency. Hach Instruments anchors North American municipal water utility relationships through localized calibration service networks. Endress+Hauser competes in European process industries with integrated transmitter-controller architectures.
Dissolved oxygen meters and controllers are electrochemical or optical instruments that quantify molecular oxygen concentration in aqueous media, typically reporting values in milligrams per liter or percent saturation for process control and regulatory compliance. Optical luminescent technology now dominates new installations due to reduced membrane maintenance and drift stability compared to polarographic methods. Online controllers command premium positioning in continuous process applications, while portable meters sustain replacement demand across environmental fieldwork. Pharmaceutical manufacturing applications require validated optical systems that satisfy pharmacopeial traceability standards.
EPA Clean Water Act enforcement and EU Urban Wastewater Treatment Directive revisions compel utilities to upgrade from manual sampling to continuous dissolved oxygen monitoring. China's MEE surface water quality standards and India's CPCB effluent norms extend comparable requirements across Asia-Pacific industrial zones. Stakeholders must evaluate sensor interoperability protocols and cloud-platform integration roadmaps before committing to next-generation controller architectures.
Market Dynamics
Optical luminescent sensor technology is compressing replacement cycles and redrawing competitive boundaries across dissolved oxygen instrumentation, as membrane-free designs eliminate the consumable revenue streams that sustained legacy electrochemical vendors for decades.
Growth Catalysts
- EPA Clean Water Act enforcement:US municipal utilities face escalating penalties for dissolved oxygen excursions in effluent discharge, forcing continuous monitoring retrofits at thousands of aging treatment plants.
- Pharmaceutical water-for-injection standards:Pharmacopeial validation requirements for dissolved oxygen measurement in biologics manufacturing drive validated optical system procurement across sterile processing suites.
- China MEE surface water mandates:Provincial environmental bureaus now require real-time dissolved oxygen telemetry at industrial outfalls, creating concentrated demand clusters in Jiangsu and Zhejiang manufacturing corridors.
Market Restraints
- Luminescent dye supply concentration:Ruthenium complex and platinum porphyrin chemistries depend on limited specialty chemical production in Germany and Japan, exposing sensor manufacturers to input volatility.
- Electrochemical legacy lock-in:Polarographic probe installed bases at US municipal utilities create switching friction due to trained technician familiarity and established calibration protocols.
- Capital intensity of validation documentation:Pharmaceutical-grade optical systems require extensive IQ/OQ/PQ documentation that extends sales cycles and elevates customer acquisition costs.
Strategic Opportunities
- India CPCB effluent norm expansion:Central Pollution Control Board mandates for dissolved oxygen monitoring at textile and tannery clusters create first-mover positioning in underpenetrated industrial zones.
- Cloud-platform integration:Edge-to-cloud dissolved oxygen data architectures enable predictive maintenance subscriptions that transform hardware vendors into recurring-revenue service providers.
- Modular transmitter designs:Swappable sensor head architectures allow end-users to upgrade from electrochemical to optical measurement without replacing full controller infrastructure.
Industry Challenges
- Optical calibration expertise scarcity:Field service organizations struggle to recruit technicians proficient in luminescent sensor drift compensation algorithms and factory calibration traceability.
- Legacy system integration complexity:SCADA and DCS interoperability protocols vary across process industries, forcing customized middleware development for each major installation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dissolved Oxygen Meters and Controllers Market |
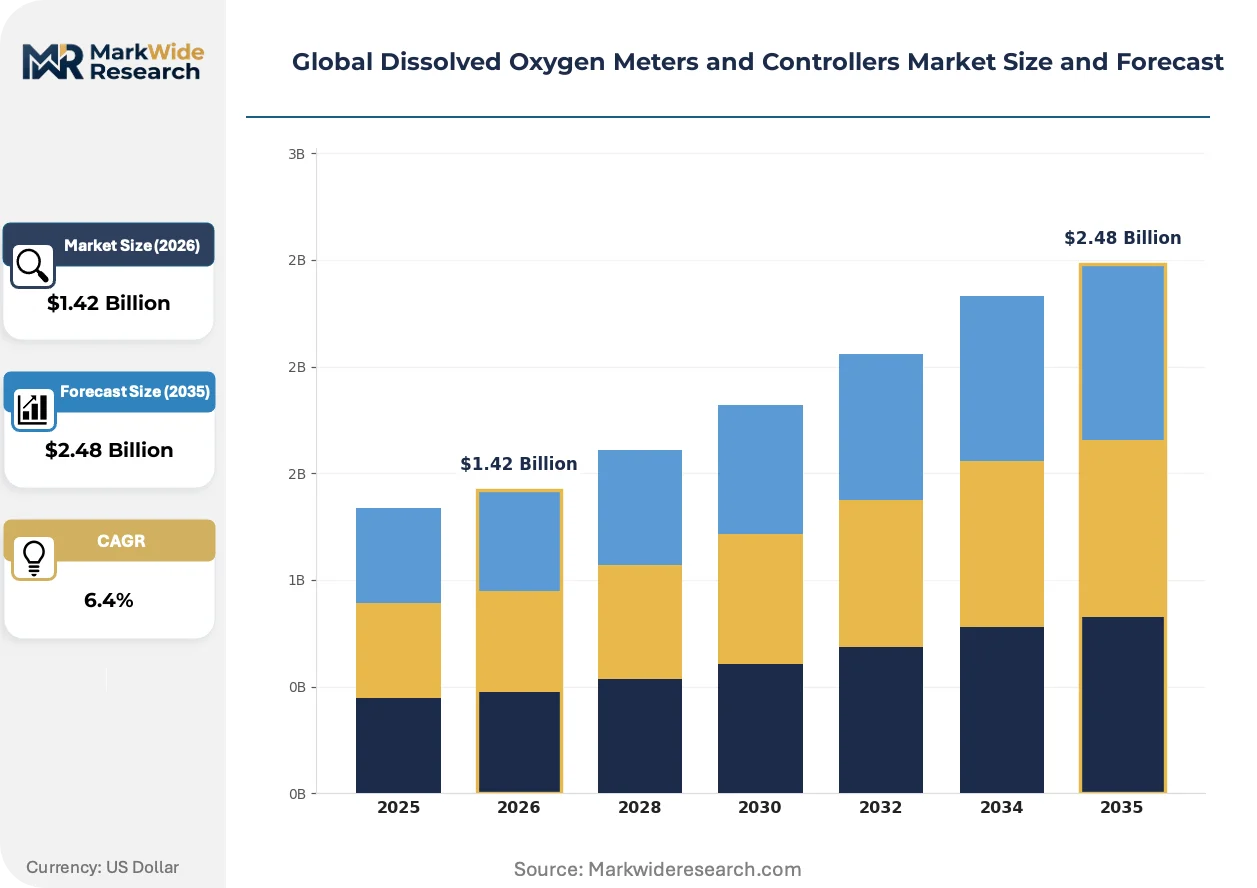
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Meters, Benchtop Meters, Online Controllers, Handheld Sensors, Compact Probes Measurement Technology: Electrochemical, Optical, Galvanic, Polarographic, Luminescent Application: Aquaculture, Wastewater Treatment, Environmental Monitoring, Food Processing, Pharmaceutical Manufacturing End User: Water Treatment Facilities, Research Laboratories, Food & Beverage Plants, Pharmaceutical Companies, Government Agencies |
| Companies Covered | Thermo Fisher Scientific, Hach Instruments, Mettler Toledo, HORIBA, Xylem, YSI, Endress+Hauser, Hamilton Company, Oakton, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dissolved Oxygen Meters and Controllers Market Shifts & Advancements
Digital sensing architectures and predictive analytics are redefining how dissolved oxygen data generates value, shifting competitive advantage from measurement accuracy alone toward actionable process intelligence.
Self-cleaning optical sensor heads with integrated wiper mechanisms and anti-fouling coatings are electrifying adoption in high-solids wastewater applications. Food and beverage processors deploy these systems at fermentation tanks where biological film accumulation previously demanded weekly manual maintenance. The technology is electrifying service contract restructuring, as vendors shift from spare parts revenue to guaranteed uptime performance guarantees.
EU Urban Wastewater Treatment Directive revisions mandate nutrient removal optimization that depends on precise dissolved oxygen cascade control. German and Dutch utilities must retrofit aeration basins with multi-point optical sensor arrays to meet total nitrogen discharge limits. Continuous monitoring infrastructure is displacing grab-sample compliance approaches across municipal procurement specifications.
Environmental field crews increasingly reject single-parameter portable meters in favor of multiprobe platforms that consolidate dissolved oxygen with pH, conductivity, and turbidity. Rental and lease-to-own arrangements are displacing capital purchase models among US watershed monitoring consortiums and academic research stations. California water quality districts exhibit the most pronounced shift toward subscription-based instrument access.
Global Dissolved Oxygen Meters and Controllers Market Segmentation
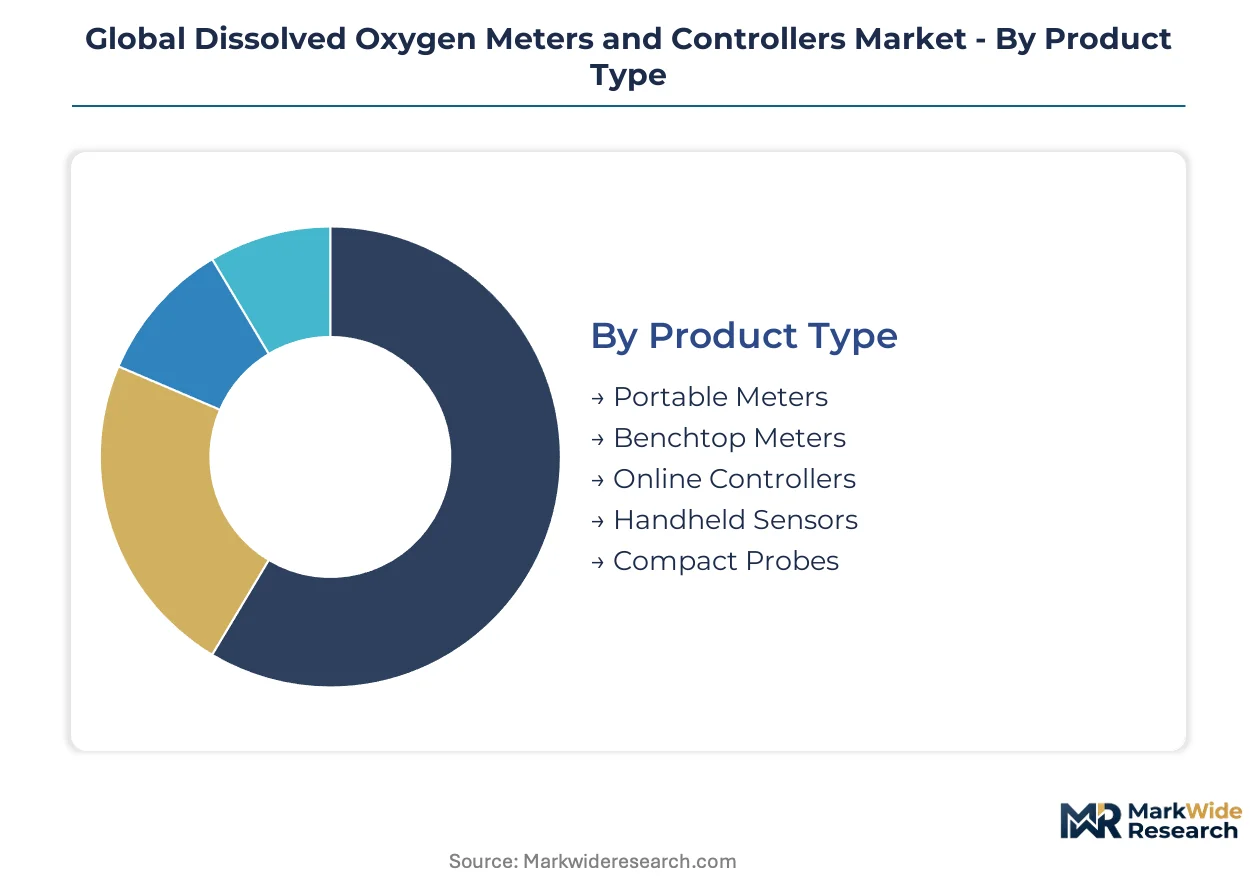
Dissolved oxygen instrumentation fragments across deployment modes from field-portable units to permanent process controllers, with each configuration demanding distinct sensor architectures and service models. Procurement patterns diverge sharply between capital-intensive municipal infrastructure and research laboratory replacement cycles.
Product Type:
Standalone portable instruments dominate field environmental work, while embedded online controllers anchor continuous process automation in treatment facilities and manufacturing plants.
- Portable Meters:Battery-operated handheld units with electrochemical or optical probe interfaces serve watershed monitoring crews and regulatory inspectors. Demand clusters at US EPA-funded water quality districts and European river basin authorities where grab-sample protocols still prevail.
- Online Controllers:Panel-mounted transmitter units with 4-20mA output and Modbus integration enable closed-loop aeration control in activated sludge basins. Municipal utilities in Germany and China specify these for nutrient removal optimization under tightening discharge permits.
- Benchtop Meters:Laboratory-grade instruments with temperature compensation and salinity correction algorithms support R&D and quality control workflows.
- Handheld Sensors:Smartphone-integrated probe heads with Bluetooth telemetry appeal to citizen science programs and small-scale aquaculture operators.
- Compact Probes:Miniaturized optical sensor heads designed for multi-parameter sonde integration in oceanographic and limnological deployments.
Volume placements concentrate in Online Controllers; the faster expansion belongs to Portable Meters.
Measurement Technology:
Cost tiering separates legacy electrochemical methods from premium optical platforms, with intermediate galvanic systems occupying budget-conscious niches.
- Optical:Luminescent quenching sensors with ruthenium complex dyes eliminate membrane replacement and electrolyte maintenance. Pharmaceutical manufacturers in Switzerland and the United States mandate these for water-for-injection validation under pharmacopeial traceability requirements.
- Electrochemical:Polarographic and galvanic probe designs with replaceable membranes and electrolyte reservoirs retain installed base dominance at US municipal utilities where technician familiarity reduces switching friction.
- Luminescent:Solid-state optical variants with platinum porphyrin indicators optimized for high-pressure steam sterilization cycles in bioreactor applications.
- Polarographic:Clark cell architectures requiring periodic membrane and electrolyte service, still specified in legacy procurement contracts.
- Galvanic:Self-polarizing probe designs with zinc anode consumption, favored in aquaculture for low-cost dissolved oxygen alarms.
Revenue margins peak in Optical; the steepest volume trajectory is climbing in Luminescent.
Application:
Customer maturity varies dramatically, with wastewater treatment representing established specification-driven procurement and pharmaceutical manufacturing demanding validated system integration.
- Wastewater Treatment:Activated sludge aeration control and effluent compliance monitoring at municipal and industrial facilities. China's MEE provincial bureaus drive concentrated retrofit demand in Jiangsu and Zhejiang manufacturing corridors.
- Pharmaceutical Manufacturing:Water-for-injection and pure steam systems requiring 21 CFR Part 11 compliant data integrity. FDA inspection enforcement elevates procurement scrutiny for optical systems with IQ/OQ/PQ documentation packages.
- Aquaculture:Dissolved oxygen management in intensive recirculating systems and pond aeration, with sensor fouling resistance as critical specification.
- Environmental Monitoring:Surface water quality networks and watershed assessment programs, increasingly shifting to multiprobe telemetry stations.
- Food Processing:Fermentation tank monitoring in breweries and dairy operations, where CIP/SIP compatibility determines sensor selection.
Installed base dominance sits with Wastewater Treatment; the fastest share gain is occurring in Pharmaceutical Manufacturing.
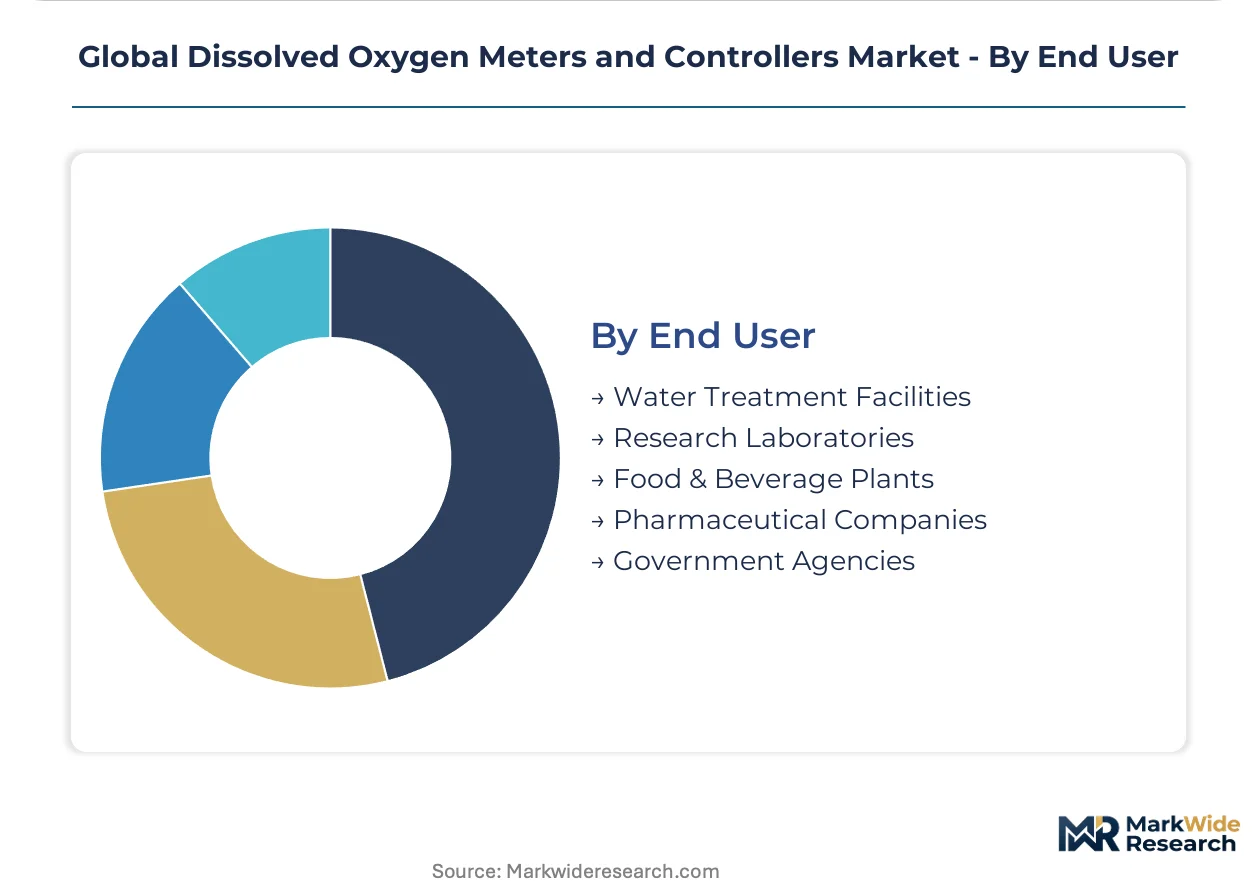
End User:
Procurement authority structures differentiate between public-sector utilities with extended tender cycles and private manufacturing with validated supplier relationships.
- Water Treatment Facilities:Municipal and industrial utilities with SCADA integration requirements and multi-year service contracts. German and Dutch operators lead EU procurement for nutrient removal sensor arrays.
- Pharmaceutical Companies:Sterile manufacturing suites with GMP compliance and audit trail documentation requirements. Endress+Hauser and Hamilton compete on validation package completeness.
- Research Laboratories:Academic and government research stations with grant-funded capital cycles and multiprobe platform preferences.
- Food & Beverage Plants:Process optimization teams seeking reduced maintenance overhead through optical sensor retrofits.
- Government Agencies:Environmental regulators and watershed management authorities standardizing on portable meter fleets for field inspection protocols.
Budget authority concentrates in Water Treatment Facilities; the most rapid specification evolution is emerging from Pharmaceutical Companies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ruthenium complex and platinum porphyrin dye production concentrates in German and Japanese specialty chemical facilities, anchoring sensor supply chains for dissolved oxygen instrumentation worldwide. This feedstock geography shapes procurement strategies across instrument manufacturers in North America, Europe, and Asia-Pacific.
United States
EPA Clean Water Act enforcement drives continuous monitoring retrofits at aging municipal treatment plants. The agency's escalating penalties for dissolved oxygen excursions compel utilities across the Midwest and Southeast to replace manual sampling protocols. Chicago and Atlanta metropolitan utilities lead procurement clusters for multi-point optical sensor arrays.
Germany
EU Urban Wastewater Treatment Directive revisions mandate nutrient removal optimization through precise aeration control. German utilities in North Rhine-Westphalia and Bavaria retrofit activated sludge basins with dense optical sensor networks. The Ruhr industrial corridor exhibits concentrated demand for validated pharmaceutical-grade systems.
China
MEE surface water quality standards require real-time dissolved oxygen telemetry at industrial outfalls. Provincial environmental bureaus in Jiangsu and Zhejiang manufacturing corridors enforce compliance across textile and chemical processing clusters. Shanghai and Suzhou municipal authorities drive specification upgrades for integrated transmitter-controller architectures.
India
CPCB effluent norm expansion targets dissolved oxygen monitoring at textile and tannery clusters. Central Pollution Control Board mandates create first-mover positioning opportunities in underpenetrated industrial zones. Tiruppur and Surat textile hubs exhibit emerging procurement activity for portable meter fleets and online controllers.
Switzerland
Pharmacopeial validation requirements for water-for-injection systems concentrate demand among Basel-area pharmaceutical manufacturers. Swissmedic inspection enforcement elevates procurement scrutiny for optical systems with complete IQ/OQ/PQ documentation. The country's sterile processing suites mandate 21 CFR Part 11 compliant data integrity architectures.
Global Dissolved Oxygen Meters and Controllers Market Competitive Landscape
Technology licensing dominates the current landscape as optical sensor patents reshape competitive boundaries. The vendor base stratifies across three tiers: integrated multinational instrument houses, specialized sensor technology licensors, and regional calibration service providers. Two strategic archetypes define positioning: those captaining in-house optical dye synthesis capabilities and those assembling modular transmitter platforms from licensed componentry. M&A activity and backward integration into sensor materials represent the dominant competitive vectors.
Among integrated multinational instrument houses, Thermo Fisher Scientific and Endress+Hauser occupy positions exemplifying divergent supply chain strategies. Thermo Fisher Scientific represents the archetype of captive optical sensor fabrication, reducing external feedstock dependency through in-house ruthenium complex production. Endress+Hauser anchors European process industry positioning through integrated transmitter-controller architectures. Hach Instruments sits within the North American municipal utility tier, sustaining competitive position through localized calibration service networks rather than component manufacturing depth.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Hach Instruments |
| Mettler Toledo |
| HORIBA |
| Xylem |
| YSI |
| Endress+Hauser |
| Hamilton Company |
| Oakton |
| Others |
Supply & Pricing Matrix
Optical sensor calibration specialists in Germany and Switzerland command wage premiums that propagate through instrument pricing, widening spreads between validated pharmaceutical-grade systems and standard municipal utility configurations. Labor-cost differentials between these precision-manufacturing regions and assembly operations in China and Mexico directly shape three-tier pricing architectures across the dissolved oxygen instrumentation sector.
Pricing Analysis
Warranty and service-bundling arrangements separate premium-tier offerings from unbundled economy alternatives, with pharmaceutical manufacturers demanding comprehensive validation documentation and field calibration support while municipal utilities prioritize lowest first-cost procurement. Pricing stratifies across premium, standard, and economy tiers according to certification grade and after-sales service intensity. Cost compression in the economy tier is intensifying because Chinese manufacturers are expanding optical probe assembly capacity. Municipal water treatment facilities exhibit the highest price sensitivity, whereas sterile pharmaceutical processors accept substantial premiums for pharmacopeial traceability packages.
Supply Chain Analysis
Freight costs for temperature-sensitive luminescent dye shipments from Germany and Japan to North American and Asian assembly plants add measurable landed-cost premiums to optical sensor production. Ruthenium complex and platinum porphyrin chemistries draw from concentrated specialty chemical production in Germany and Japan. Single-source vulnerability in luminescent dye feedstocks exposes instrument manufacturers to input volatility. Distribution runs through authorized instrumentation distributors with localized calibration service capabilities rather than direct OEM-to-end-user channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around vendors with captive optical sensor fabrication capabilities, as luminescent dye supply concentration and validation expertise requirements force smaller assemblers toward exit or acquisition.
For Market Incumbents: Extend backward integration into ruthenium complex synthesis or secure exclusive supply agreements with German and Japanese specialty chemical producers to defend against feedstock disruption. Deepen field service organization capabilities in luminescent sensor drift compensation to differentiate from emerging Chinese competitors with weaker calibration infrastructure.
For New Entrants and Emerging Players: Enter via modular transmitter architectures that allow electrochemical-to-optical sensor head upgrades without full controller replacement, targeting US municipal utilities with legacy polarographic probe installed bases. Focus initial penetration on India's textile and tannery clusters where CPCB effluent mandates are creating first-mover windows with limited incumbent service presence.
For Investors and Strategic Acquirers: Re-rating potential sits with mid-scale optical sensor technology licensors given pharmaceutical validation requirements and cloud-platform integration roadmaps that favor recurring-revenue service models. Long-term viability hinges on demonstrated IQ/OQ/PQ documentation completeness and established relationships with FDA-inspected sterile manufacturing suites. Watch for inflection when major German utilities begin specifying predictive maintenance subscriptions in tender specifications.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Luminescent Dye Synthesis | Captive ruthenium complex production reduces dependency on German and Japanese specialty chemical suppliers. |
| Cloud-Platform Integration Partnership | Edge-to-cloud dissolved oxygen telemetry enables predictive maintenance subscriptions for municipal utility customers. |
| Modular Transmitter Architecture Launch | Swappable sensor heads allow electrochemical-to-optical upgrades without full controller infrastructure replacement. |
| Validation Documentation Package Expansion | Complete IQ/OQ/PQ documentation satisfies FDA inspection enforcement for pharmaceutical water-for-injection systems. |
| Localized Calibration Service Network Buildout | Regional service capabilities anchor municipal utility relationships against low-cost Chinese instrument competitors. |
Research Methodology
Independent corroboration across instrument manufacturer product managers, municipal utility operations directors, and pharmaceutical validation engineers underwrites the qualitative findings presented in this study. Primary interviews with field service technicians, SCADA integration specialists, and environmental compliance officers combined with secondary validation from EPA enforcement records, EU Urban Wastewater Treatment Directive implementation reports, and China MEE surface water quality standard filings. Bottom-up shipment data from optical sensor assemblers and top-down procurement budget analysis from water treatment facility capital plans were triangulated to establish market sizing.
Comparable-period anchoring to historical installation base data and retrofit cycle patterns shaped the projection methodology across the forecast period. Segmentation dimensions modeled include product type, measurement technology, application vertical, and end-user procurement authority structure. CAGRs were derived from weighted average of technology displacement curves and regulatory mandate implementation timelines. Forecast inputs incorporated luminescent dye supply capacity expansion plans and cloud-platform adoption rates among German and Dutch utilities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated electrochemical probe replacement or extended luminescent dye supply disruptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Measuring Instruments
TDS Meter Market
Measuring Instruments
Ultraviolet Data Logger Market
Measuring Instruments
Global Container Weighing Systems Market
Measuring Instruments
3D Metrology Market
Measuring Instruments
Digital Refrigeration Gauge Market
Measuring Instruments
Laser Distance Meter Market
Measuring Instruments
Handheld Wind Anemometer Market
Measuring Instruments
Multifunction Calibrators Market
Measuring Instruments
Temperature Loggers Market
Measuring Instruments
Borescope Inspection Camera Market
Measuring Instruments
Americas 3D Metrology Market
Measuring Instruments
3D Laser Scanner Market
Measuring Instruments
Data Acquisition Market
Measuring Instruments
India Hydrological and Meteorological Equipment Market
Measuring Instruments
North America Scientific Instruments Market
Measuring Instruments
Air Velocity Meter Market