
 Canning Machine Market | 2026-2036
Canning Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Canning Machine Market Analysis
CE marking under the EU Machinery Directive is unwinding the competitive field for canning equipment sold into European food and beverage operations. GEA Group AG leverages its integrated processing and packaging platform to anchor large-scale brewery contracts across Germany and Scandinavia. Krones AG competes through end-to-end line engineering that extends from depalletizing through palletizing. Ball Corporation dominates aluminum container supply and positions its filling technology partnerships to control access to lightweight can formats.
A canning machine is an industrial packaging system designed to fill, seam, and hermetically seal metal, composite, or polymer containers at speeds ranging from 30 to 2,000 units per minute, employing rotary or inline mechanical architectures to preserve product integrity and shelf stability. Its primary purpose is to enable ambient-stable distribution of perishable goods by excluding oxygen and microorganisms through double-seam closure or aseptic isolation. Automatic canning machines command the largest installed base in high-volume beverage operations, while aseptic canning technology captures the fastest expansion as dairy and nutraceutical processors seek extended shelf life without refrigeration. Vacuum canning systems occupy a specialized niche in premium food preservation where oxygen exclusion determines product quality.
The FDA governs food-contact surfaces and sanitation standards for canning equipment deployed in United States facilities, while the EU Machinery Directive and CE marking framework dictate safety and electromagnetic compliance for European installations. In China, the national standardization administration enforces GB standards for food machinery hygiene that condition market access for imported systems. Stakeholders must monitor evolving PFAS restrictions in food-contact materials and the trajectory of deposit-return schemes across multiple jurisdictions, as these regulatory vectors will determine which sealing technologies and container formats qualify for future production lines.
Market Dynamics
Aluminum packaging preferences are restructuring beverage manufacturing footprints as craft producers scale micro-canning capacity and legacy bottlers retrofit glass-dominant lines. FDA food-contact substance regulations and evolving aseptic processing standards are compressing equipment qualification timelines while reshaping vendor qualification criteria across North American and European installations.
Growth Catalysts
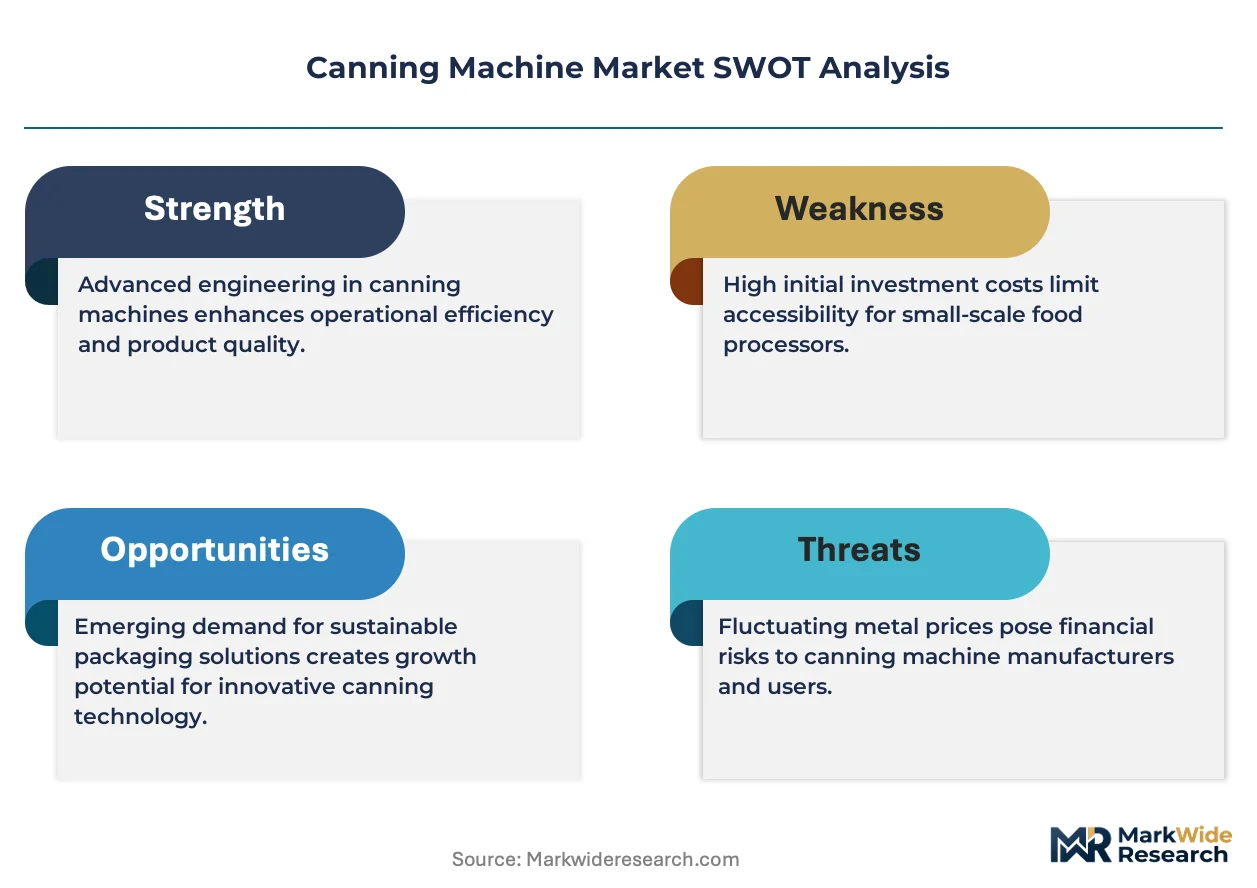
- Deposit-return scheme expansion:Germany's DPG and similar programs across Nordic markets are mandating aluminum-compatible filling infrastructure, forcing bottler capex into canning retrofits.
- Aseptic canning technology maturation:Dairy and nutraceutical processors are adopting hydrogen peroxide vapor sterilization systems to achieve ambient-stable distribution without cold chain dependency.
- Baden-Württemberg precision engineering clusters:German mechanical engineering concentration supplies high-speed rotary filling systems with sub-millimeter seaming tolerance to European beverage bottlers.
Market Restraints
- Aluminum ingot price volatility:LME aluminum contract fluctuations compress container cost predictability and deter long-term filling line commitments from mid-scale producers.
- CE marking compliance burden:EU Machinery Directive conformity assessment timelines extend 8-14 months for non-European OEMs, constraining competitive entry.
- Retort pouch substitution:Flexible aseptic packaging formats are capturing shelf-stable food applications previously served by metal cans, narrowing addressable volume for traditional seaming equipment.
Strategic Opportunities
- India beverage packaging greenfield:FSSAI hygiene mandates and rising sparkling water consumption are creating first-mover advantage for aseptic canning system deployments in Maharashtra and Karnataka.
- PFAS-free sealing compound transition:EPA and state-level restrictions on perfluoroalkyl substances are opening specification windows for epoxy-phenolic and oleoresin-based lining technologies.
- Blockchain-container integration:Serialization and provenance tracking requirements are converging with filling line automation, enabling premium pricing for traceability-enabled equipment packages.
Industry Challenges
- Mechatronics technician scarcity:Servo-driven rotary filler maintenance requires blended mechanical-electrical competencies that vocational pipelines in Bavaria and Michigan have not scaled to match demand.
- Legacy line integration complexity:Brownfield brewery retrofit projects face mechanical interface mismatches between 1990s-era depalletizers and modern seaming heads, extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canning Machine Market |
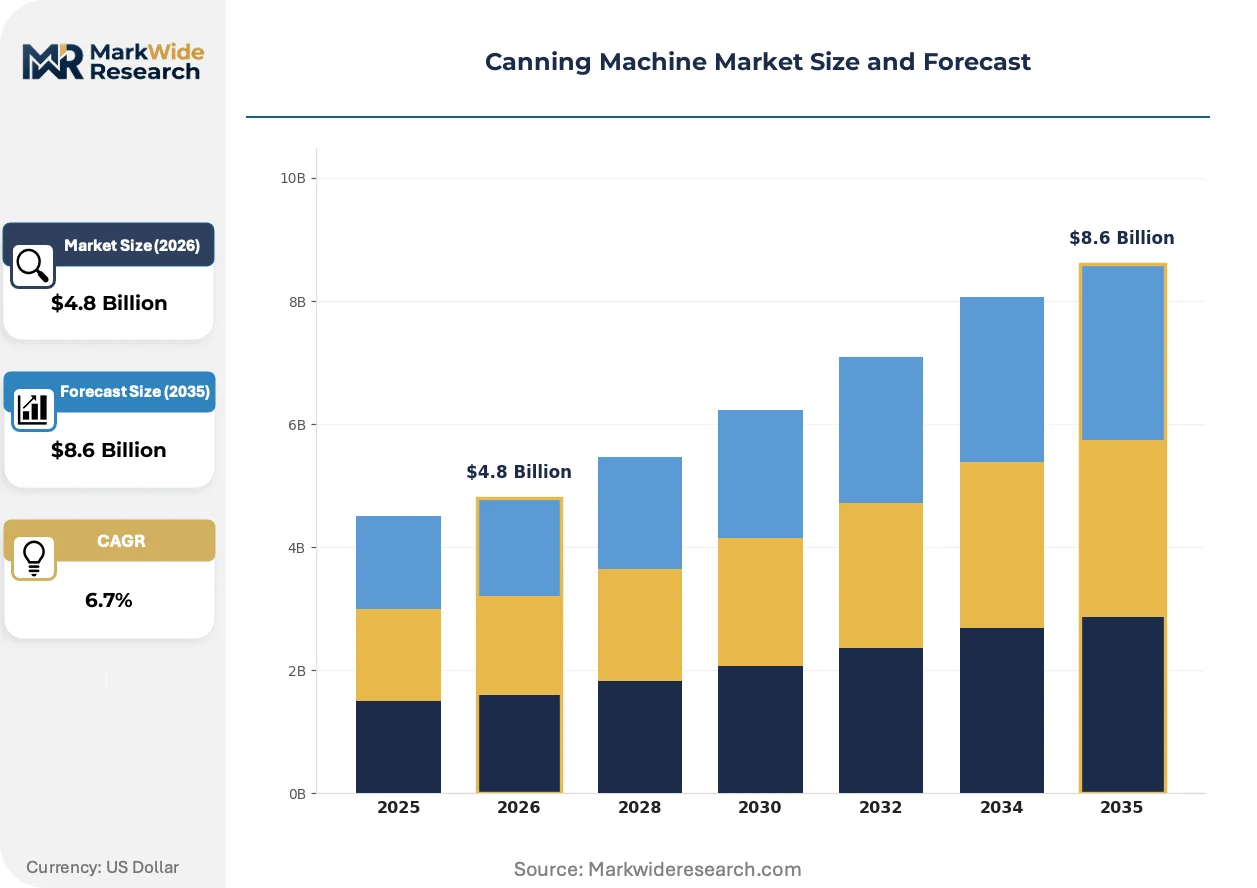
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Canning Machines, Semi-Automatic Canning Machines, Manual Canning Machines, Vacuum Canning Machines End User: Food Processing, Beverage Industry, Pharmaceuticals, Chemicals Technology: Pressure Canning, Water Bath Canning, Steam Canning, Aseptic Canning Capacity: Low Capacity, Medium Capacity, High Capacity, Custom Capacity |
| Companies Covered | Cask Global Canning Solutions, HOR YANG Machinery, American Canning Machines, GEA Group AG, Tetra Pak International SAGL, Ball Corporation, Dixie Canner, Comac Group, Krones AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canning Machine Market Emerging Trajectories
Digital twin simulation and modular line architecture are compressing commissioning risk and enabling faster format changeovers. Equipment vendors are repositioning around total cost of ownership metrics rather than throughput specifications alone.
Electromagnetic seaming technology is decomposing traditional mechanical roller systems in high-speed beverage applications. Premium craft breweries in Oregon and Colorado are piloting servo-controlled seaming heads that eliminate mechanical wear components. This shift is decomposing the aftermarket spare parts revenue model that legacy OEMs depend upon.
EU F-Gas Regulation phase-down schedules are accelerating adoption of natural refrigerant-based product cooling systems in aseptic canning lines. Compressor OEMs are engineering CO2 and ammonia-compatible chilling modules to replace HFC-dependent equipment. German dairy processors face the most acute retrofit pressure as their installed base ages into replacement windows.
Direct equipment financing through captive lessors is displacing traditional capex purchase models among mid-scale beverage entrants. Third-party ownership structures bundle maintenance and format tooling into per-unit charges. This pattern is most pronounced in Texas and Florida craft brewing clusters where capital constraints meet rapid volume scaling needs.
Canning Machine Market Segmentation
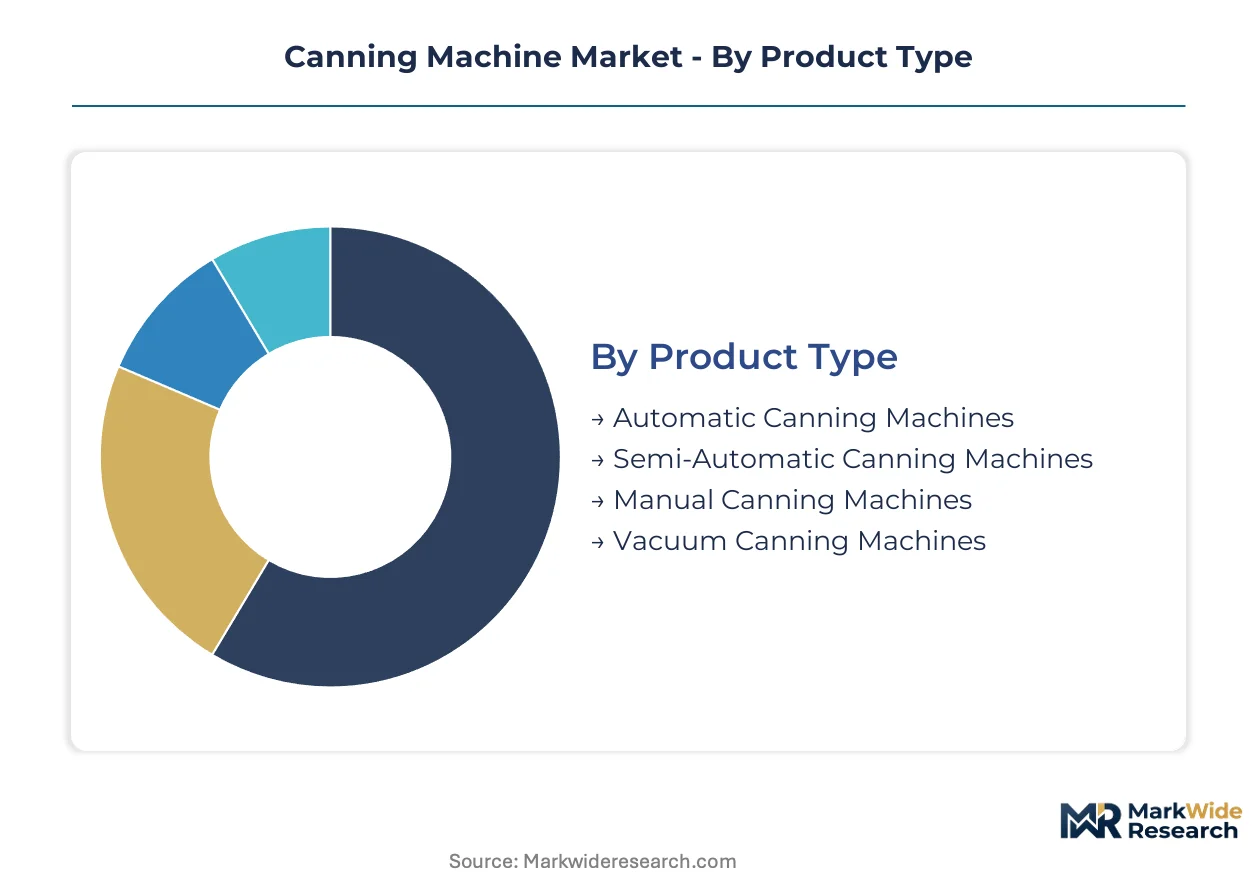
Canning equipment specification varies sharply across regulatory regimes, with FDA 21 CFR compliance requirements for food-contact surfaces diverging from EU Machinery Directive safety protocols. End-use application and throughput requirements further stratify procurement patterns as beverage bottlers prioritize speed while pharmaceutical processors emphasize isolator integrity.
Product Type:
CE marking timelines under the EU Machinery Directive compress 8-14 months for non-European OEMs, favoring established automatic system suppliers with notified body relationships already in place.
- Automatic Canning Machines:Rotary filler architectures achieve 2,000 units per minute through servo-driven seaming heads with electromagnetic closure systems. Demand concentrates in Bavaria and Baden-Württemberg brewing clusters where GEA Group AG and Krones AG anchor high-volume contracts. FDA food-contact substance regulations mandate 316L stainless steel contact surfaces and clean-in-place validation protocols that extend qualification timelines.
- Semi-Automatic Canning Machines:Inline mechanical configurations bridge manual loading with automated seaming for 30-300 units per minute. Craft beverage producers in Oregon and Colorado scale micro-canning capacity through these systems as aluminum packaging preferences strengthen. Capital constraints in Texas and Florida brewing clusters drive third-party financing structures that bundle maintenance into per-unit charges.
- Manual Canning Machines:Benchtop lever-operated systems serve laboratory and pilot-scale validation with minimal utility requirements.
- Vacuum Canning Machines:Oxygen exclusion systems preserve premium food quality through chamber-based evacuation preceding double-seam closure.
Established volume favors Automatic Canning Machines; emerging adoption favors Semi-Automatic Canning Machines.
End User:
Application-specific hygiene mandates reshape equipment architecture as aseptic isolation requirements diverge from ambient filling protocols.
- Beverage Industry:High-speed rotary fillers with hydrogen peroxide vapor sterilization enable ambient-stable distribution without cold chain dependency. Deposit-return schemes in Germany's DPG system and Nordic markets mandate aluminum-compatible infrastructure that forces bottler capex into canning retrofits. EU F-Gas Regulation phase-down schedules accelerate CO2 and ammonia-based cooling module adoption.
- Food Processing:Retort-compatible seaming systems achieve commercial sterility through post-fill thermal processing. Retort pouch substitution narrows addressable volume as flexible aseptic formats capture shelf-stable applications previously served by metal cans. PFAS-free sealing compound transitions open specification windows for epoxy-phenolic lining technologies.
- Pharmaceuticals:Isolator-integrated fillers meet FDA aseptic processing guidance with vaporized hydrogen peroxide bio-decontamination.
- Chemicals:Corrosion-resistant contact surfaces handle aggressive formulations through specialty alloy specifications.
Installed base concentration sits with Beverage Industry; steepest expansion trajectory runs through Pharmaceuticals.
Technology:
Processing temperature and microbial kill step configuration determine equipment qualification burden and line integration complexity.
- Aseptic Canning:Hydrogen peroxide vapor sterilization systems achieve extended shelf life without refrigeration for dairy and nutraceutical processors. German dairy operations face acute retrofit pressure as aging installed base enters replacement windows concurrent with EU F-Gas compliance deadlines. FDA evolving aseptic processing standards compress equipment qualification timelines.
- Pressure Canning:Steam-pressure retort systems achieve 240°F processing temperatures for low-acid food commercial sterility.
- Water Bath Canning:Open-kettle atmospheric processing serves high-acid foods with simpler regulatory validation requirements.
- Steam Canning:Direct steam injection reduces processing time for acidified products through rapid heat transfer.
Legacy dominance belongs to Pressure Canning; technology maturation favors Aseptic Canning.
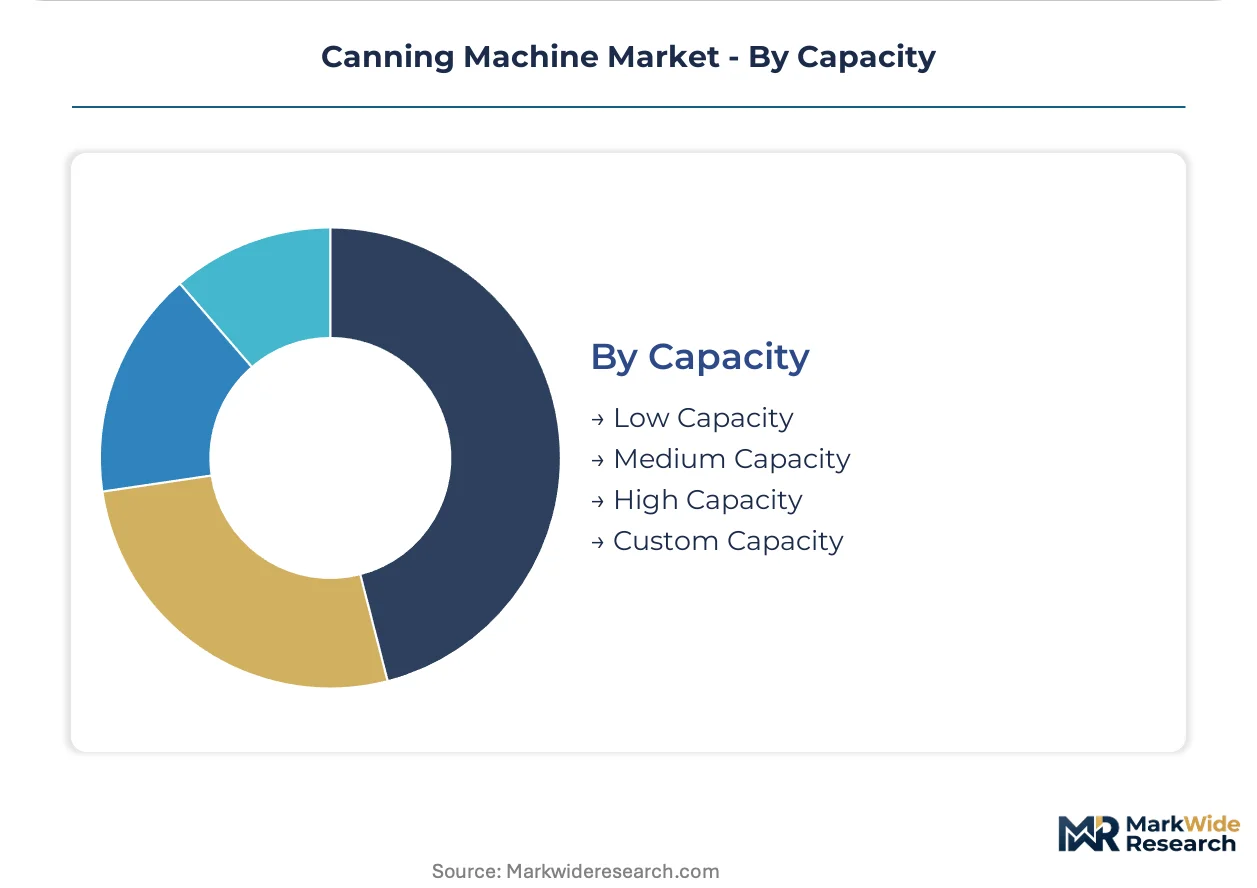
Capacity:
Throughput specification correlates with financing structure as mid-scale entrants favor operational expenditure models over capital deployment.
- High Capacity:Rotary architectures exceeding 1,000 units per minute require precision engineering clusters with sub-millimeter seaming tolerance. Baden-Württemberg mechanical engineering concentration supplies European bottlers through integrated processing and packaging platforms. Mechatronics technician scarcity in Bavaria and Michigan constrains maintenance scaling.
- Medium Capacity:100-500 units per minute inline systems balance footprint efficiency with format flexibility.
- Low Capacity:Laboratory and pilot-scale systems serve validation and specialty production with minimal infrastructure requirements.
- Custom Capacity:Modular line architecture enables brownfield retrofit integration where legacy depalletizer interfaces constrain standard specification.
Revenue concentration aligns with High Capacity; format flexibility demand elevates Custom Capacity specification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deposit-return schemes and evolving food-contact regulations are restructuring canning equipment procurement across major manufacturing jurisdictions. Aluminum packaging mandates and aseptic processing standards are compressing vendor qualification timelines while redirecting capital flows toward compliant filling infrastructure.
United States
Craft beverage producers in Oregon, Colorado, Texas, and Florida are scaling micro-canning capacity as aluminum preferences displace glass-dominant lines. FDA 21 CFR food-contact substance regulations mandate 316L stainless steel surfaces and clean-in-place validation that extends equipment qualification. Servo-controlled seaming head pilots in Pacific Northwest brewing clusters are decomposing traditional mechanical roller aftermarket revenue models.
Germany
The DPG deposit-return system mandates aluminum-compatible infrastructure that forces bottler capital expenditure into canning retrofits. EU F-Gas Regulation phase-down schedules accelerate CO2 and ammonia-based cooling module adoption in aseptic dairy lines. Precision engineering clusters in Bavaria and Baden-Württemberg supply high-speed rotary fillers with sub-millimeter seaming tolerance to European beverage operations.
China
GB standards for food machinery hygiene condition market access for imported canning systems. National standardization administration enforcement creates compliance barriers for non-domestic OEMs seeking dairy and beverage sector placement. Yangtze River Delta manufacturing bases are absorbing technology transfer partnerships for aseptic filling line localization.
India
FSSAI hygiene mandates and rising sparkling water consumption are creating first-mover deployment opportunities in Maharashtra and Karnataka. Central food safety authority regulations reshape equipment architecture requirements for ambient-stable dairy distribution. Western and Southern state beverage packaging greenfields attract aseptic canning system investments as cold chain limitations persist.
Japan
METI industrial policy supports precision manufacturing retention in canning equipment component supply. Pharmaceutical-grade isolator integration requirements from PMDA aseptic processing guidance compress domestic vendor qualification timelines. Kanto and Kansai machinery clusters maintain specialized competence in high-tolerance seaming head fabrication for regional bottlers.
Canning Machine Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with integrated processing-packaging platforms alongside specialized precision engineering houses. The competitive field organizes around three archetypes: beverage-line integrators commanding rotary filler scale, aseptic technology specialists isolating dairy-pharma applications, and regional fabricators serving craft-scale micro-canning demand. Dominant competitive moves include strategic partnerships with aluminum container suppliers and technology licensing arrangements for electromagnetic seaming systems.
Among Germany-based engineering conglomerates, GEA Group AG and Krones AG exemplify the integrated platform archetype, anchoring large-scale brewery contracts through end-to-end line engineering that extends from depalletizing through palletizing. Cask Global Canning Solutions occupies a position within the craft-specialist tier, representing the micro-canning equipment segment where capital constraints and rapid volume scaling needs converge. These three entities illustrate the market's tripartite structure: conglomerate integrators, regional precision houses, and craft-scale specialists each commanding distinct procurement decision criteria.
| Leading Market Players |
|---|
| Cask Global Canning Solutions |
| HOR YANG Machinery |
| American Canning Machines |
| GEA Group AG |
| Tetra Pak International SAGL |
| Ball Corporation |
| Dixie Canner |
| Comac Group |
| Krones AG |
| Others |
Supply Flow & Price Mechanics
Rotary filler scale economies in Bavaria and Baden-Württemberg concentrate precision engineering capacity, compressing unit costs for high-speed systems while elevating price floors for mid-capacity entrants lacking equivalent manufacturing density. This supply-side clustering shapes procurement negotiations as European bottlers leverage geographic proximity against Asian competitors facing extended CE marking timelines.
Pricing Analysis
Certification level (FDA-grade, CE-marked, ISO-compliant) creates the primary spread across equipment tiers, with aseptic-validated systems commanding substantial premiums over ambient-fill alternatives. Three-tier pricing structure separates premium electromagnetic seaming platforms from standard mechanical roller systems and economy inline configurations. Cost compression in the semi-automatic tier is intensifying because craft-scale financing models bundle maintenance into per-unit charges, eroding upfront margin capture. Craft beverage producers in Texas and Florida exhibit highest price sensitivity, while pharmaceutical isolator integrations show least elasticity due to regulatory compliance mandates.
Supply Chain Analysis
Germany and China anchor precision machining and control system fabrication respectively, with Baden-Württemberg mechanical engineering clusters supplying seaming head components and Yangtze River Delta bases producing servo drives and HMI panels. Aluminum ingot sourcing draws from Australian bauxite refining and Chinese smelter output, while 316L stainless steel contact surfaces rest on German and Japanese mill production. Single-source vulnerability concentrates in high-tolerance seaming head bearings sourced from specialized Bavarian fabricators. Distribution runs through captive OEM service networks and third-party lessor partnerships that displace traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The canning equipment market is recovering from cyclical aluminum price volatility and capex deferrals, with deposit-return scheme expansion across Nordic and German markets providing sustained demand visibility.
For Market Incumbents: Shield installed base revenue through captive aftermarket service contracts and predictive maintenance telemetry that locks out independent service providers. Deepen backward integration into electromagnetic seaming head production to capture technology transition margins and neutralize component supplier leverage. Retort pouch substitution in shelf-stable food applications represents the primary demand threat requiring aseptic dairy line diversification. For New Entrants and Emerging Players: Lead with modular line architecture targeting brownfield brewery retrofits where legacy depalletizer interface constraints frustrate established OEM specification. Maharashtra and Karnataka beverage packaging greenfields offer the most penetrable geography given FSSAI hygiene mandate timing and limited incumbent service infrastructure. Direct equipment financing partnerships with regional banks bypass capital constraint barriers that dominate craft-scale procurement decisions. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors aseptic technology specialists with hydrogen peroxide vapor sterilization competencies over commodity rotary filler fabricators. Long-term viability centers on isolator-integrated pharmaceutical applications where regulatory qualification timelines create durable competitive moats. The signal to monitor is PFAS-free sealing compound transition velocity, as EPA and state-level restriction timing will determine which lining technology vendors capture specification windows.| Strategic Initiative | Industry Significance |
|---|---|
| Electromagnetic Seaming Technology Licensing | Decomposes mechanical roller aftermarket revenue models while enabling premium positioning in high-speed beverage lines. |
| Aseptic Dairy Line Retrofit Partnerships | Captures EU F-Gas Regulation-driven replacement demand as German processors face simultaneous compliance deadlines. |
| Blockchain-Enabled Traceability Integration | Meets serialization requirements from deposit-return schemes while justifying equipment premium through provenance verification. |
| PFAS-Free Lining Technology Transition | Opens specification windows for epoxy-phenolic compounds as EPA restrictions eliminate incumbent fluoropolymer alternatives. |
| Captive Equipment Financing Launch | Addresses capital constraints in Texas and Florida craft brewing clusters through bundled per-unit charge structures. |
Methodological Framework
Cross-validation between primary interviews with plant engineers, OEM procurement teams, aftermarket service heads, and craft brewery operations directors anchors the qualitative findings against secondary validation from customs records, SEC equipment supplier filings, and EU Machinery Directive notified body disclosure databases. Bottom-up triangulation aggregates individual line deployment data while top-down verification cross-checks against aluminum container shipment volumes and regional beverage production statistics.
Sensitivity analysis around aluminum ingot price volatility, CE marking timeline variability, and aseptic processing standard evolution informs the analytical framework across the projection horizon. Segmentation dimensions modeled include automation level, end-use application, processing technology, and capacity tier alongside regional regulatory cluster differentiation. CAGRs derive from installed base replacement cycles, greenfield capacity announcements, and technology substitution elasticities calibrated against historical equipment procurement patterns.
Forecasts assume regulatory continuity in FDA food-contact substance enforcement, EU Machinery Directive CE marking protocols, and FSSAI hygiene mandates; material policy shifts in PFAS restrictions or deposit-return scheme expansion would require re-modeling. Specific risks that could revise projections include aluminum LME contract sustained elevation, mechatronics technician scarcity acceleration, and retort pouch technology cost breakthroughs in shelf-stable food applications. Recalibration cycles align with material shifts in aseptic processing guidance, F-Gas Regulation phase-down schedules, and blockchain-container integration mandate timing.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Global Industrial Food Blanchers Market
Food Processing Equipment
Tea Processing Machine Market
Food Processing Equipment
Walk-In Refrigerator Market
Food Processing Equipment
Decanter Centrifuge Market
Food Processing Equipment
Global Food Deaerators Market
Food Processing Equipment
Europe Commercial Sous Vide Machine Market
Food Processing Equipment
Ice Cream Processing Equipment Market
Food Processing Equipment
Global Commercial Refrigeration Market
Food Processing Equipment
Global Powder Processing Equipment Market
Food Processing Equipment
Commercial Food Processors Market
Food Processing Equipment
Kebab Machine Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Insect Protein Processing Equipment Market
Food Processing Equipment
Micro Winery Equipment Market
Food Processing Equipment
Spiral Cooler Market
Food Processing Equipment
Philippines Cold Storage Warehouse Market