
 Global Non Thermal Processing Market | 2026-2036
Global Non Thermal Processing Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non Thermal Processing Market Intelligence
The beverage industry's share of non-thermal processing applications is consolidating as demand for cold-pressed juices and functional drinks outpaces other segments. Hiperbaric leads the market with its specialization in High Pressure Processing (HPP) equipment for this sector. JBT Corporation competes through a broader portfolio of both thermal and non-thermal solutions, offering integrated processing lines. Elea Technology differentiates itself with a focus on Pulsed Electric Field (PEF) systems, particularly for potato and fruit processing applications.
Non-thermal processing encompasses methods that inactivate microorganisms and enzymes in food products without applying significant heat. Technologies like High Pressure Processing utilize pressures up to 600 MPa to achieve pasteurization, preserving nutritional and sensory qualities. The primary purpose is to extend shelf life and ensure food safety while maintaining a 'fresh' product profile. High Pressure Processing technology dominates the market, while the food preservation application, particularly for premium juices and ready-to-eat meals, represents the fastest-growing segment.
Regulatory frameworks from the US Food and Drug Administration (FDA) and the European Food Safety Authority (EFSA) create pathways for novel food processing technologies. These bodies set the standards for safety validation, which directly influences market access and consumer trust. For food and beverage manufacturers, the key decision centers on balancing the high initial capital investment for equipment against the long-term benefits of improved product quality and extended shelf life.
Market Dynamics
The central dynamic in the non-thermal processing market is the tension between the high capital investment required for advanced equipment and the intensifying consumer and regulatory demand for minimally processed foods with extended shelf life and preserved nutritional value.
Growth Catalysts
- Clean-Label Demand:Consumer preference for foods and beverages with simple ingredient lists and 'fresh' attributes is a primary catalyst, particularly within the premium juice, dairy alternatives, and ready-to-eat meal segments.
- Regulatory Frameworks:Food safety mandates from bodies like the FDA and EFSA, which require validated pathogen reduction steps, encourage the adoption of non-thermal methods as effective alternatives to traditional heat pasteurization.
- Technology Maturation:The proven efficacy and expanding application scope of High Pressure Processing beyond beverages into solid foods like meats and seafood are broadening the technology's addressable market for manufacturers.
Market Restraints
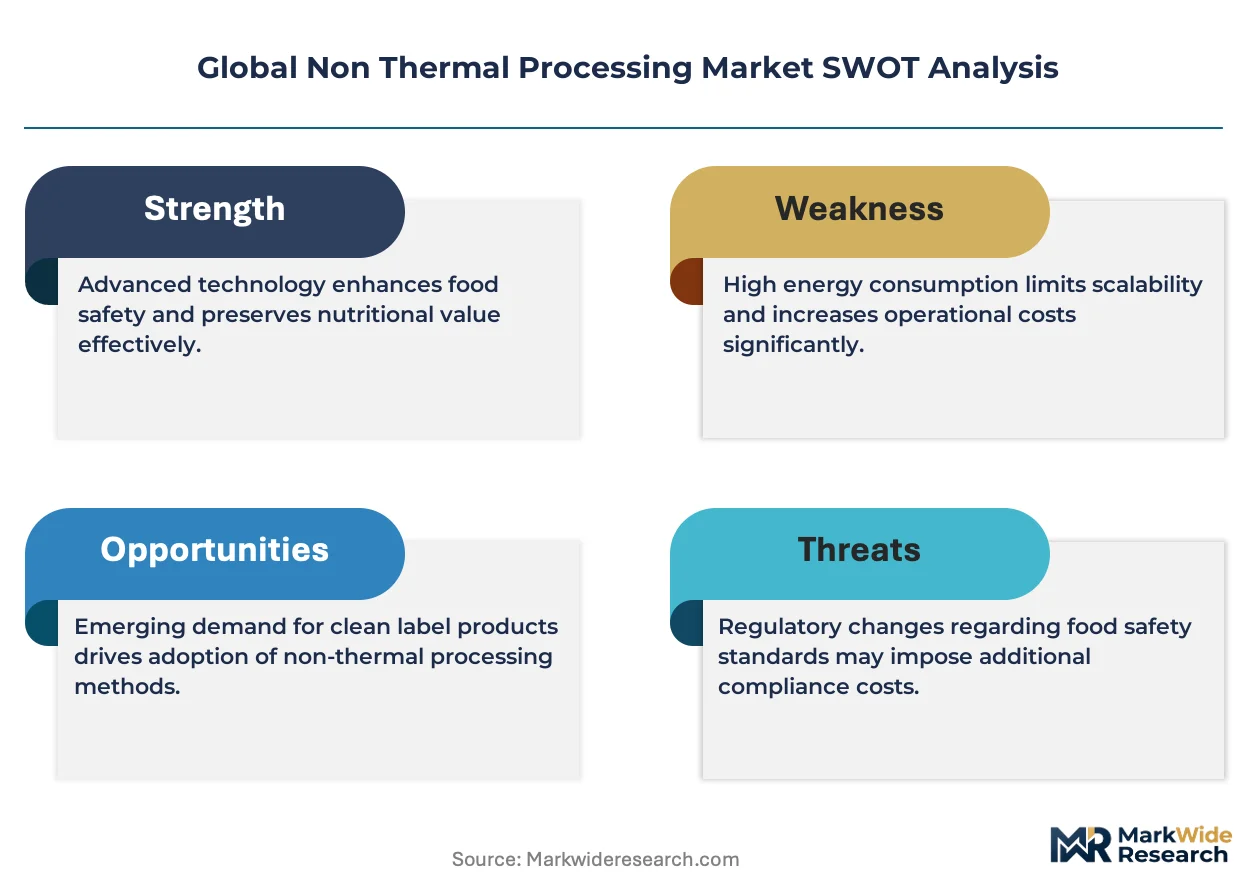
- High Capital Outlay:The significant upfront cost of acquiring, installing, and validating industrial-scale HPP or PEF systems remains a substantial barrier to entry for small and medium-sized food processors.
- Processing Limitations:Non-thermal technologies are not universally applicable; their effectiveness can be limited by food composition, such as low water activity or the presence of internal air pockets, restricting use in certain product categories.
- Energy Consumption:The high energy requirements for generating extreme pressures in HPP systems or creating powerful electric fields in PEF contribute to high operational costs, impacting manufacturer margins.
Strategic Opportunities
- Geographic Expansion:There is significant opportunity in Asia-Pacific food manufacturing hubs where rising food safety standards and growing middle-class demand for premium packaged foods create a new market for non-thermal solutions.
- Pharmaceutical and Cosmetic Applications:The technology's ability to sterilize heat-sensitive materials presents an opportunity to expand into niche, high-value applications like processing biologics, vaccines, or active cosmetic ingredients.
- Hybrid Processing Systems:Combining PEF as a pre-treatment to increase cell permeability with subsequent HPP or gentle heating offers a path to enhanced microbial inactivation and improved processing efficiency.
Industry Challenges
- Specialized Skill Gaps:A shortage of food engineers and technicians with the expertise to operate, maintain, and validate complex non-thermal processing equipment constrains efficient deployment and scaling by food manufacturers.
- System Integration Complexity:Integrating large-footprint non-thermal equipment into existing, often continuous, production lines designed around thermal processing creates significant logistical and workflow challenges for operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non Thermal Processing Market |
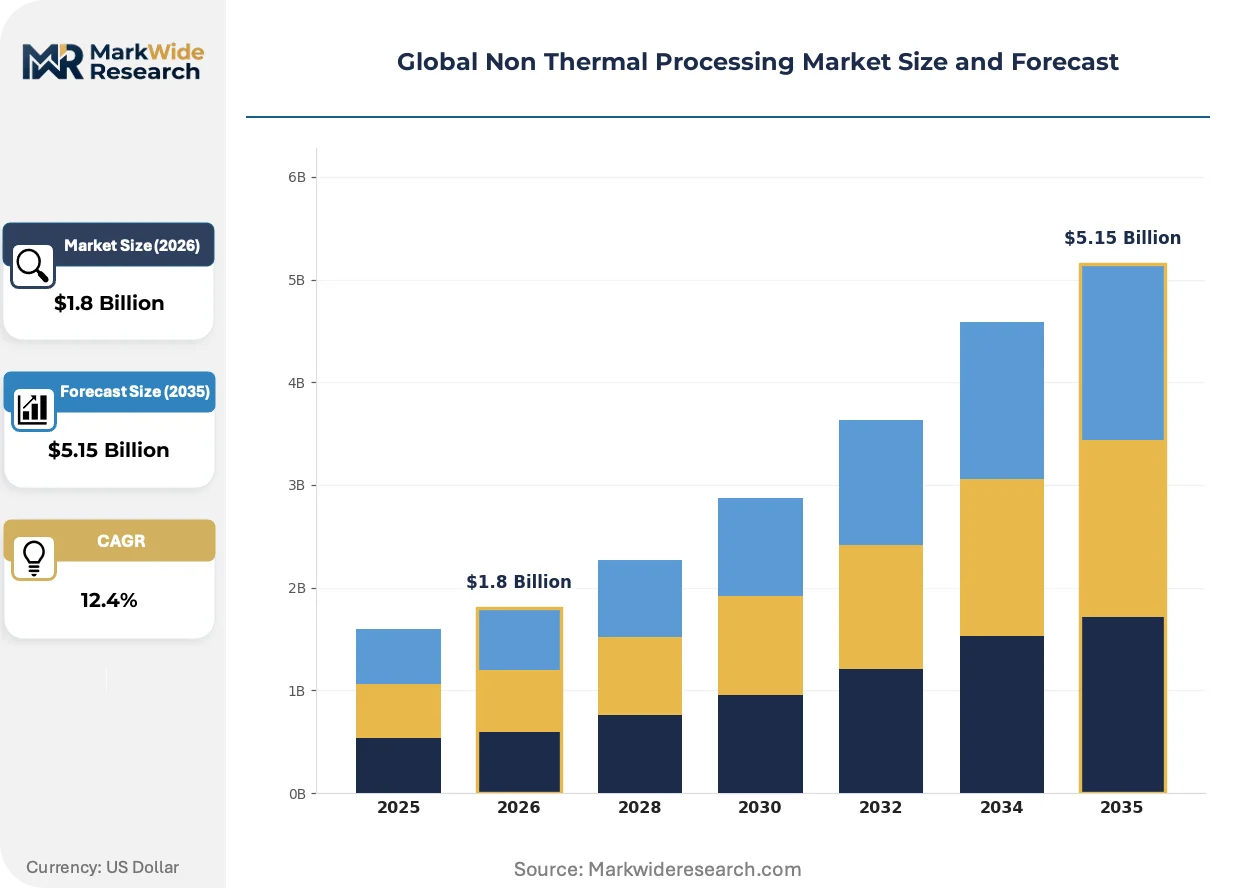
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.15 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: High Pressure Processing, Pulsed Electric Fields, Ultrasound, Cold Plasma Application: Food Preservation, Juice Processing, Meat Processing, Dairy Products End User: Food Industry, Beverage Industry, Pharmaceuticals, Cosmetics Distribution Channel: Online Retail, Supermarkets, Wholesale Distributors, Direct Sales |
| Companies Covered | Hiperbaric, JBT Corporation, Dukane, Symbios Technologies, Elea Technology, Thyssenkrupp Uhde GmbH, Nordion, Bosch, Pulsemaster, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non Thermal Processing Market Strategic Shifts & Innovations
The market is being reshaped by a move toward more flexible and accessible technology configurations, enabling a wider range of producers to adopt non-thermal methods. This shift is democratizing access beyond large-scale, centralized industrial operations.
Pulsed Electric Field technology is evolving toward smaller, modular systems designed for lower-throughput applications. Small and mid-sized producers of artisanal beverages, sauces, and liquid foods are the primary adopters of these more accessible units. This trend toward smaller-footprint equipment is decentralizing processing capabilities, allowing for localized production and reducing reliance on large, centralized tolling facilities.
Regulatory bodies are creating clearer validation pathways for non-thermal technologies. The US FDA's Food Safety Modernization Act (FSMA) explicitly supports using validated processes like HPP to control foodborne pathogens. This provides manufacturers with a defined framework for demonstrating safety and compliance. The cold-pressed juice and deli meat segments are most affected, now using HPP validation data to satisfy FSMA's preventive controls rule.
A notable shift in capital strategy involves manufacturers opting for third-party toll processing services instead of direct equipment acquisition. This model allows food brands to leverage HPP without the prohibitive upfront investment, disrupting the traditional in-house equipment purchasing cycle. This trend is most prominent in the United States and Germany, especially among startups in the functional beverage and plant-based food sectors.
Global Non Thermal Processing Market Segmentation
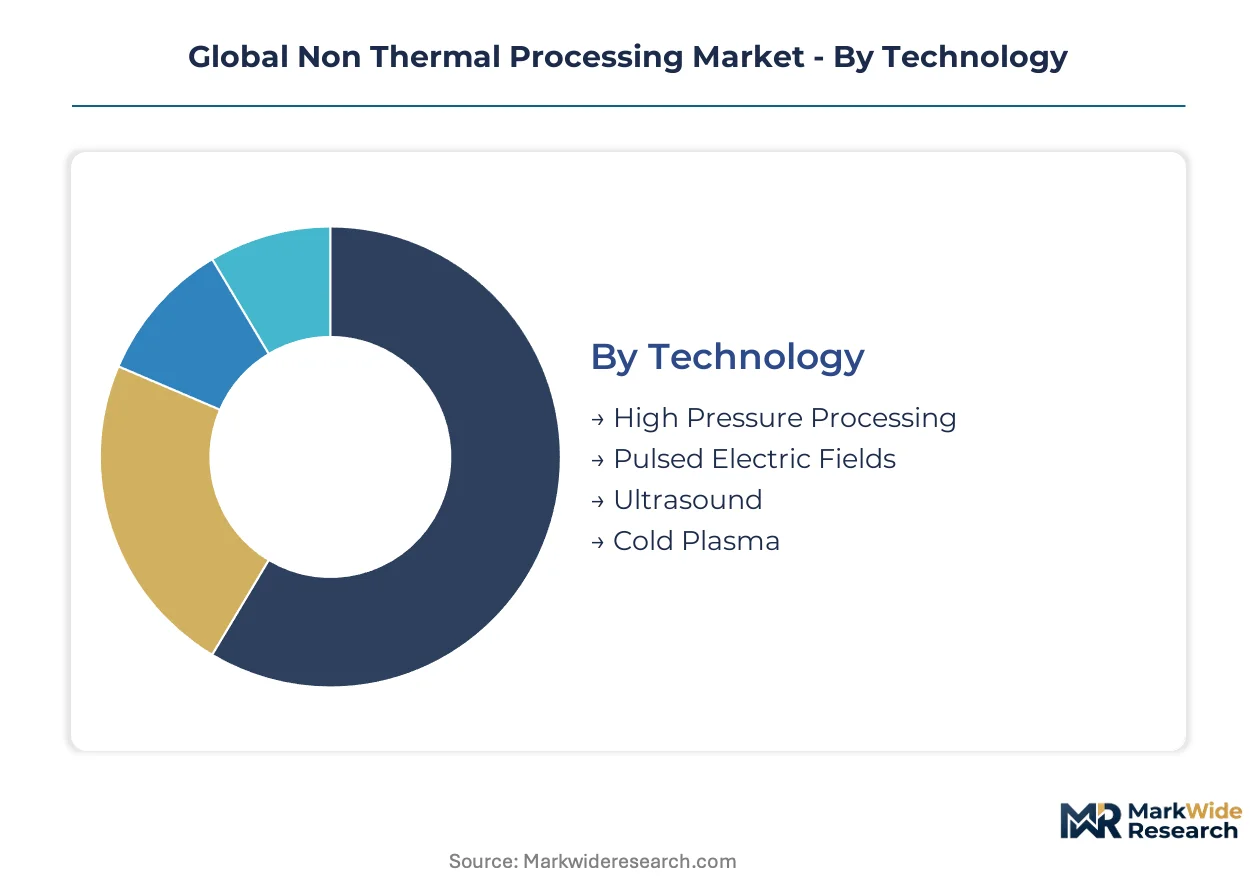
Understanding the Global Non Thermal Processing Market through segmentation reveals how diverse technologies meet specific application needs across various industries. This granular view helps identify key growth areas and informs strategic investment decisions for manufacturers and technology providers. Distinct end-user requirements drive the adoption of specialized non-thermal solutions.
Technology:
Buyers in this category differentiate based on the specific processing requirements for their products, balancing efficacy, cost, and product integrity.
- High Pressure Processing:This technology utilizes hydrostatic pressure up to 600 MPa to inactivate microorganisms and enzymes, preserving product freshness. It dominates food preservation applications, particularly for premium juices and ready-to-eat meals in the United States.
- Pulsed Electric Fields:This method applies short, high-voltage pulses to create temporary pores in cell membranes, enhancing extraction or microbial inactivation. It gains significant traction in potato and fruit processing within European markets like Germany.
- Ultrasound:Employs high-frequency sound waves for emulsification, extraction, and mild microbial reduction in liquid foods.
- Cold Plasma:Generates reactive species for surface decontamination and sterilization of food products and packaging materials.
High Pressure Processing leads volumes today; Pulsed Electric Fields is gaining share fastest.
Application:
The primary use case for non-thermal processing shapes technology selection and market penetration for food and beverage manufacturers.
- Food Preservation:This application extends the shelf life and ensures the microbiological safety of various food products, including meats, seafood, and prepared dishes. It represents a primary driver for non-thermal methods across ready-to-eat meals and deli meats globally.
- Juice Processing:This category focuses on maintaining the nutritional content and sensory qualities of fruit and vegetable juices without thermal degradation. It is fueled by consumer demand for cold-pressed and functional beverages in North America.
- Meat Processing:Improves the safety, texture, and color stability of processed meat products such as ham and poultry.
- Dairy Products:Enhances the shelf life and safety of milk, yogurt, and other dairy alternatives while preserving heat-sensitive nutrients.
Food Preservation applications hold the largest market share; Juice Processing shows significant expansion.
End User:
Different industries adopt non-thermal processing to address unique product characteristics and regulatory compliance needs.
- Food Industry:This segment comprises manufacturers of a wide array of processed foods, including snacks, produce, and prepared meals. Demand is driven by the need for clean-label products and extended shelf life across global markets.
- Beverage Industry:Producers of juices, functional drinks, and dairy alternatives form this significant end-user segment. It is propelled by consumer preference for fresh-like beverages, especially in the US and Germany.
- Pharmaceuticals:Utilizes non-thermal methods for sterilizing heat-sensitive biologics, vaccines, and active pharmaceutical ingredients.
- Cosmetics:Applies processing techniques to preserve active ingredients and extend the shelf life of personal care formulations.
The food industry accounts for the majority of installations; pharmaceuticals present a high-value niche.
Distribution Channel:
The method by which non-thermal processed products reach consumers impacts market accessibility and brand visibility.
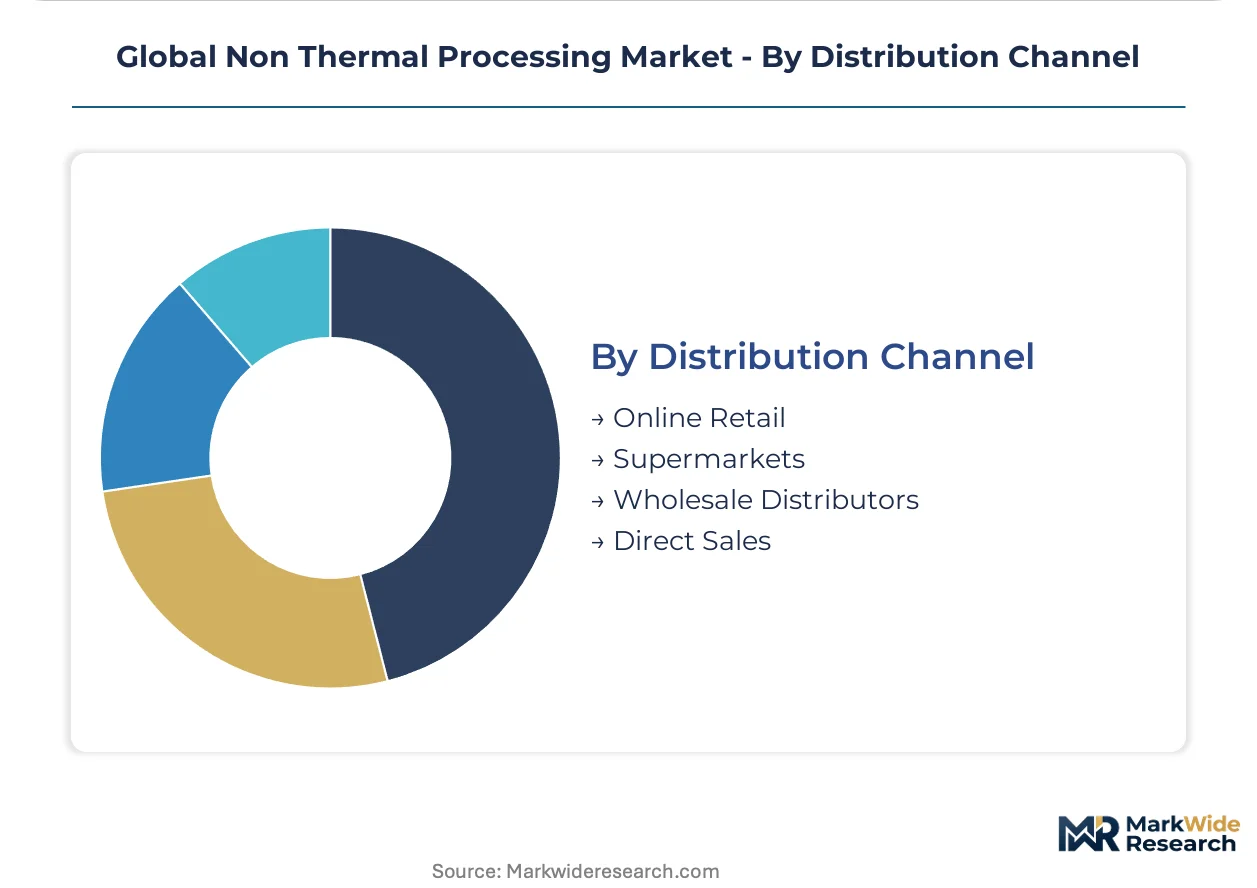
- Online Retail:This channel encompasses direct-to-consumer sales platforms and e-commerce marketplaces for food and beverage products. It facilitates market access for niche brands and specialized non-thermal products, particularly in developed digital economies.
- Supermarkets:Large-scale grocery chains and hypermarkets form the traditional and dominant distribution channel for consumer packaged goods. This serves as the primary channel for mass-market non-thermal processed foods and beverages.
- Wholesale Distributors:Supplies bulk non-thermal processed products to restaurants, catering services, and institutional buyers.
- Direct Sales:Manufacturers sell directly to industrial clients or through proprietary retail outlets, offering specialized solutions.
Traditional supermarkets remain central; online retail expands reach for specialized offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The non-thermal processing market sees production shifts influenced by varying regulatory landscapes and operational costs across regions. Manufacturers often evaluate geographies based on the stringency of food safety mandates and the availability of specialized infrastructure. This creates opportunities for market expansion in regions balancing robust regulatory frameworks with favorable investment climates.
United States
Consumer preference for clean-label foods and functional beverages drives demand for non-thermal processing in the United States. The US Food and Drug Administration (FDA) FSMA provides clear validation pathways for technologies like HPP. Major food manufacturing hubs in California and the Midwest are expanding HPP toll processing facilities.
Germany
Demand for premium dairy alternatives and minimally processed fruit products fuels non-thermal technology adoption in Germany. The European Food Safety Authority (EFSA) sets stringent standards for novel food processing, encouraging investment in validated non-thermal methods. Industrial clusters in Bavaria and North Rhine-Westphalia are key centers for PEF system development.
China
Rising food safety concerns and a growing middle class seeking high-quality packaged foods stimulate non-thermal processing growth in China. The State Administration for Market Regulation (SAMR) incorporates advanced processing techniques into its food safety guidelines. Coastal manufacturing zones, particularly in the Yangtze River Delta, invest in HPP equipment for seafood and ready-to-eat meals.
India
The expanding organized retail sector and consumer demand for hygienic, longer-shelf-life products boost non-thermal processing in India. The Food Safety and Standards Authority of India (FSSAI) develops regulations to integrate novel food processing technologies. Food processing parks in Maharashtra and Gujarat are emerging as centers for HPP adoption.
Brazil
Strong domestic consumption of fresh-like juices and processed meats supports the non-thermal processing market in Brazil. The Brazilian Health Regulatory Agency (ANVISA) oversees food safety, recognizing non-thermal methods for pathogen reduction. Agricultural processing regions in São Paulo and Minas Gerais are adopting HPP for fruit pulp and meat preservation.
Global Non Thermal Processing Market Key Industry Players
Technology maturation dominates the current landscape, with companies focusing on refining non-thermal processing systems for broader applications and improved efficiency. The market exhibits a tiered structure, from specialized equipment manufacturers to diversified industrial conglomerates offering integrated solutions. Strategic archetypes include pure-play HPP specialists, PEF innovators, and broad-spectrum food processing equipment providers. Portfolio diversification and geographic expansion are primary competitive moves, alongside strategic partnerships for market reach.
Companies like Hiperbaric, a Spanish manufacturer, exemplify pure-play specialization in High Pressure Processing equipment, primarily serving the food and beverage industry. JBT Corporation, a US-based entity, represents the diversified industrial conglomerate archetype, offering both thermal and non-thermal solutions across various food processing lines and integrated systems. Elea Technology GmbH, a German company, sits within the innovative PEF specialist segment, focusing on pulsed electric field systems for specific applications like potato and fruit processing, differentiating through its technology.
| Leading Market Players |
|---|
| Hiperbaric |
| JBT Corporation |
| Dukane |
| Symbios Technologies |
| Elea Technology |
| Thyssenkrupp Uhde GmbH |
| Nordion |
| Bosch |
| Pulsemaster |
| Others |
Cost & Logistics Intelligence
Specialized food engineers in advanced manufacturing hubs, like those in Germany and the United States, command higher salaries, which directly impacts the premium pricing of non-thermal processing equipment and services. This labor cost differential influences the economic viability of in-house versus toll processing models.
Pricing Analysis
Distributor margins for non-thermal processing equipment often reflect the complexity of installation and after-sales support. The dominant pricing structure for HPP and PEF systems is project-based, tailored to specific production line integration requirements. Price differentiation stems from equipment capacity and the level of customization for unique product applications; after-sales service contracts also significantly influence the total cost of ownership. Pricing softness for entry-level PEF systems is emerging due to technology maturation and the availability of modular units. Small and medium-sized food processors exhibit the highest price sensitivity, often opting for toll processing services over direct equipment acquisition.
Supply Chain Analysis
Logistics costs for delivering large-scale non-thermal processing equipment are substantial, particularly for international shipments. Equipment manufacturing concentrates in countries like Germany and Spain, where specialized engineering expertise resides. The supply chain relies on high-precision components, including ultra-high-pressure pumps and advanced electrical systems. Single-source vulnerability for critical components poses a structural risk to equipment manufacturers. Distribution runs through a direct sales model to industrial clients, often involving installation and commissioning teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The non-thermal processing market presents a margin-expansion opportunity, driven by consumer willingness to pay a premium for clean-label, minimally processed foods. Technology maturation also enables cost-down efficiencies in equipment operation.
For Market Incumbents: Lock in long-term contracts with large food and beverage manufacturers to secure stable revenue streams against emerging modular PEF systems. Invest in advanced material science R&D to improve equipment durability and reduce maintenance downtime, mitigating operational cost pressures. Geographic expansion into Asia-Pacific manufacturing hubs offers new capacity deployment.
For New Entrants and Emerging Players: Third-party toll processing facilities offer an accessible entry point for new equipment manufacturers to showcase technology without requiring large capital outlays from food brands. Target the artisanal beverage and plant-based food segments with smaller, modular PEF systems. Leverage direct-to-consumer online retail channels for specialized non-thermal processed products, emphasizing freshness and nutritional integrity.
For Investors and Strategic Acquirers: Diversified industrial conglomerates are the most active acquirers in this space, seeking to integrate non-thermal capabilities into broader food processing portfolios. The market demonstrates long-term viability due to persistent consumer demand for clean-label products and evolving food safety regulations. Target PEF innovators with proven efficacy in specific food matrices. The signal to watch is the increasing patent activity in hybrid processing systems.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia-Pacific | Expands market reach and capitalizes on rising food safety standards in China and India. |
| Hybrid System R&D | Combines PEF and HPP to enhance microbial inactivation and improve processing efficiency. |
| Modular PEF System Development | Lowers entry barriers for small and medium-sized producers of artisanal beverages and sauces. |
| Partnerships with Toll Processors | Enables wider adoption of non-thermal technologies without prohibitive upfront capital investment. |
| Certification for Pharmaceutical Use | Unlocks high-value niche applications for sterilizing heat-sensitive biologics and vaccines. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary insights with secondary validation. Interviews with food processing engineers, regulatory affairs specialists, and R&D directors informed market dynamics. Secondary data sources included FDA and EFSA publications, industry association reports, and company annual filings. This approach ensured robust bottom-up and top-down triangulation of market data.
Segment weighting across technology, application, end-user, and distribution channel formed the basis of the analytical framework over the projection horizon. CAGRs were derived from historical growth patterns and anticipated market shifts. Key forecast inputs included consumer preference for clean-label products and the stringency of food safety regulations in advanced economies.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving food safety standards and technology breakthroughs. Forecasts reflect assumptions regarding capital investment trends and consumer adoption rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Edible Collagen Casing Market
Food Processing Equipment
Decanter Centrifuge Market
Food Processing Equipment
Bread Slicer Market
Food Processing Equipment
Mobile Bottling Line Market
Food Processing Equipment
Sandwich Preparation Refrigerators Market
Food Processing Equipment
Food Slicer and Dicer Market
Food Processing Equipment
Cook Processor Market
Food Processing Equipment
Smart Bread Maker Market
Food Processing Equipment
Convection Ovens Market
Food Processing Equipment
Brining Systems Market
Food Processing Equipment
Vacuum Cooling Equipment Market
Food Processing Equipment
Global Conveyor Oven Market
Food Processing Equipment
Yogurt Makers Market
Food Processing Equipment
Wine Processing Equipment Market
Food Processing Equipment
Magnetic Grill Market
Food Processing Equipment
Batter Mixer Machines Market