
 Food Extruder Market | 2026-2036
Food Extruder Market Size, Share, and Industry Trends Forecast 2026-2036
Food Extruder Market Foresight
A shortage of trained extrusion process engineers is unwinding capacity expansion timelines across the industry. Bühler Group leverages its Swiss engineering heritage to sustain premium positioning in extrusion cooking technology for breakfast cereals. Coperion anchors its competitive stance through deep specialization in co-rotating twin screw systems for high-moisture meat analogues. Wenger Manufacturing dominates the pet food extrusion segment with extensive installed bases across North American protein processing facilities.
Food extruders are continuous processing machines that force raw materials through a shaped die under controlled temperature, pressure, and shear conditions, typically operating at barrel temperatures between 80°C and 200°C with screw speeds ranging from 100 to 800 rpm to achieve specific product expansion and texture profiles. Twin screw extrusion technology leads capital expenditure flows due to its superior mixing efficiency and flexibility across starch-protein formulations, while cold extrusion segments serving pasta and specialty dough applications retain steadier margin pools despite slower volume growth. Extrusion cooking commands the largest application share as snack food manufacturers prioritize high-throughput thermal processing for expanded products.
The FDA's Good Manufacturing Practice regulations and the USDA's FSIS oversight shape equipment sanitation standards and material specifications for food-contact surfaces in US installations. REACH compliance in Europe restricts certain lubricant and coating chemistries used in extruder barrels, redirecting R&D investment toward food-safe ceramic and nickel-based alloy alternatives. Stakeholders must monitor evolving EFSA guidance on acrylamide formation during high-temperature extrusion to anticipate retrofit requirements and process redesign obligations.
Market Dynamics
Twin screw extrusion systems are capturing capital allocation flows as EU Green Deal mandates force plant-based meat analogue producers toward energy-efficient thermal processing platforms with measurable carbon footprint reductions.
Growth Catalysts
- EU Green Deal efficiency mandates:Sustainability disclosure requirements under CSRD are compelling food manufacturers across Germany, France, and Italy to replace legacy single-screw systems with high-throughput twin screw extruders that deliver superior energy recovery.
- Plant-based protein expansion:Meat analogue producers in the Netherlands and Denmark are scaling wet extrusion capacity to meet retailer commitments for alternative protein shelf space, driving equipment replacement cycles.
- High-moisture extrusion technology:Advanced co-rotating systems capable of processing 40-70% moisture content are unlocking texture profiles that satisfy European consumer taste benchmarks for whole-muscle simulation.
Market Restraints
- Specialized alloy input costs:Nickel-based barrel linings and food-grade ceramic coatings face price volatility linked to mining supply concentration in Indonesia and Russia, compressing equipment margin structures.
- REACH compliance friction:ECHA restrictions on perfluorinated lubricants and certain anti-corrosion chemistries are extending R&D timelines and forcing reformulation of critical barrel surface treatments.
- Process engineering talent scarcity:The shortage of trained extrusion technologists with starch-protein rheology expertise is elongating commissioning timelines and inflating specialist labor rates.
Strategic Opportunities
- EFSA acrylamide guidance anticipation:Proactive equipment retrofitting to mitigate Maillard reaction byproducts during high-temperature extrusion positions vendors ahead of anticipated mandatory process redesign obligations.
- Cold extrusion diversification:Pasta and specialty dough applications in Italy and Spain offer steadier margin pools with lower capital intensity and reduced thermal energy requirements.
- Digital twin integration:Convergence of extrusion process modeling with real-time sensor analytics enables predictive maintenance contracts and outcome-based service pricing for snack manufacturers.
Industry Challenges
- Extrusion process engineer recruitment:The shallow talent pool for specialists capable of optimizing screw configurations across variable moisture-protein matrices is constraining capacity expansion timelines.
- Legacy system integration complexity:Retrofitting Industry 4.0 connectivity into installed single-screw bases requires bespoke mechanical and software engineering that extends project delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Extruder Market |
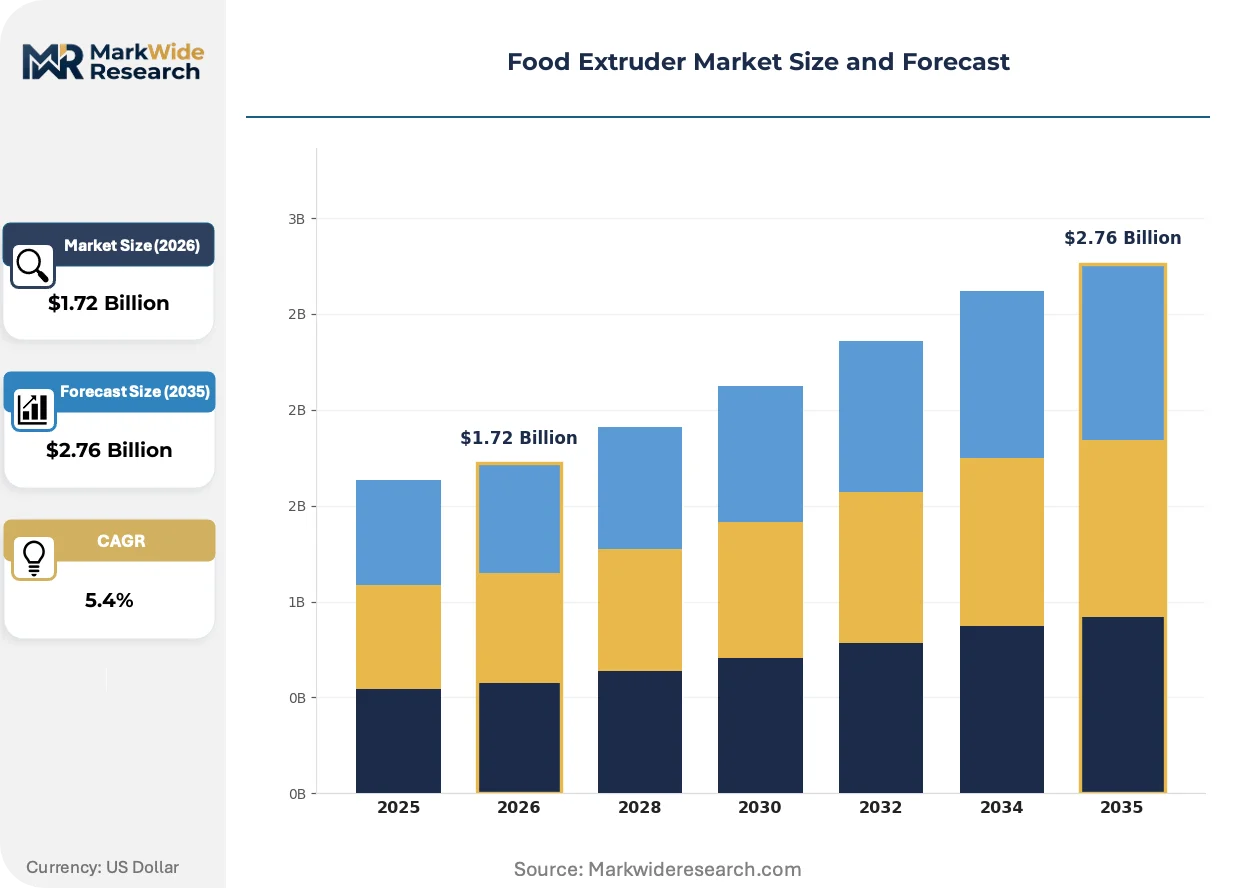
| Market Size in 2026 | $1.72 Billion |
| Market Size in 2035 | $2.76 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Screw, Twin Screw, Conical Twin Screw, Ram Extruders Application: Snack Foods, Breakfast Cereals, Pet Food, Pasta Products, Meat Analogues End User: Food Processing Companies, Contract Manufacturers, Ingredient Suppliers, Specialty Food Producers Technology: Cold Extrusion, Hot Extrusion, Twin Screw Extrusion, Extrusion Cooking |
| Companies Covered | Baker Perkins, Pavan Group, Bühler Group, Coperion, CPM Extrusion Group, Clextral, Reading Bakery Systems, American Extrusion International, Wenger Manufacturing, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Extruder Market Shifts & Advancements
Extrusion technology is pivoting toward precision thermal control and predictive automation as sustainability mandates and labor scarcity reshape equipment specifications across European food manufacturing.
Co-rotating twin screw systems with segmented barrel designs and independent temperature zones are displacing conventional single-screw platforms in high-throughput snack production. Large-scale cereal manufacturers in Germany and Switzerland are adopting these configurations to achieve real-time viscosity modulation across starch-protein blends. This displacement is compressing the residual value of legacy equipment and accelerating replacement cycles.
REACH restrictions on perfluorinated compounds and specific lubricant chemistries are forcing barrel coating reformulations toward nickel-based alloys and ceramic alternatives. Equipment manufacturers face extended certification timelines as ECHA evaluates novel surface treatments for food-contact compliance. Wet extrusion segments serving meat analogue production are absorbing the bulk of compliance costs through dedicated process validation protocols.
Outcome-based equipment performance contracts are replacing traditional capital purchase models among mid-scale plant-based protein processors. Dutch and Belgian manufacturers now contract for guaranteed throughput and texture consistency metrics rather than owning extrusion assets outright. This shift concentrates vendor risk but locks in multi-year service revenue streams for technology providers with strong process engineering capabilities.
Food Extruder Market Segmentation
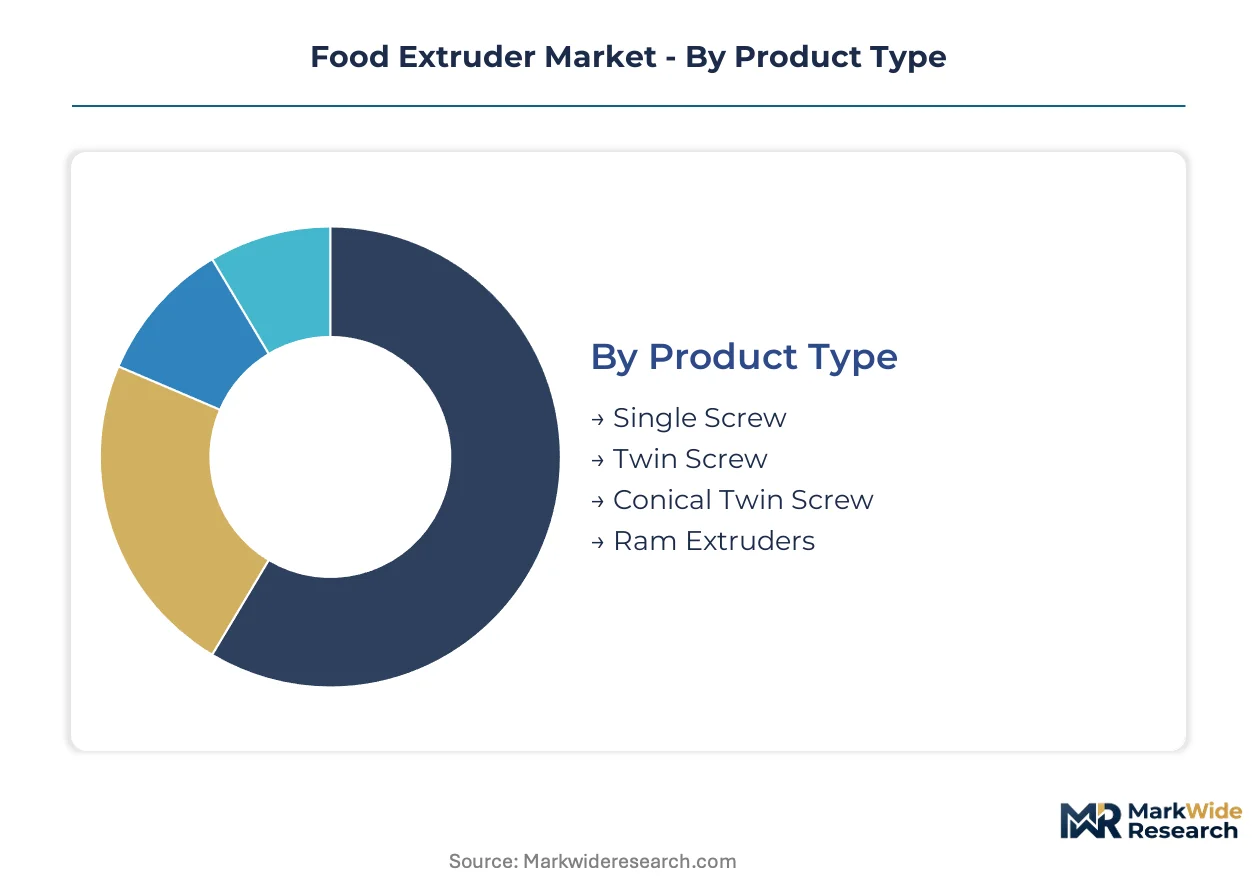
Equipment specification varies sharply across extrusion applications, with thermal processing requirements and moisture tolerance dictating screw geometry, barrel alloy selection, and die configuration. Manufacturers configure product portfolios around distinct operational envelopes rather than pursuing universal platform designs.
Product Type:
German and Swiss cereal manufacturers favor twin screw systems for export-oriented production, while domestic-focused pasta processors in Italy retain single screw installations for lower throughput requirements.
- Single Screw:Simple helical geometry forces material through a heated barrel using one rotating shaft. Italian pasta manufacturers and specialty dough processors favor these systems for their lower capital intensity and reduced maintenance complexity in medium-batch operations.
- Twin Screw:Co-rotating intermeshing screws deliver superior mixing intensity and thermal uniformity across variable moisture-protein matrices. Dutch meat analogue producers and German snack manufacturers are concentrating procurement here to satisfy EU Green Deal efficiency benchmarks and retailer sustainability audits.
- Conical Twin Screw:Tapered screw geometry enables high compression ratios in compact footprints. Specialized pet food processors in France deploy these configurations for dense feed formulations requiring precise density control.
- Ram Extruders:Piston-driven batch systems process highly viscous or fibrous materials unsuitable for continuous screw feeding. Artisanal meat analogue startups in Denmark utilize ram extrusion for small-scale texture development before scaling to continuous platforms.
Twin screw holds installed capacity. Conical twin screw is rotating up the share rankings.
Application:
Margin structures diverge between high-volume thermal expansion applications and precision-forming segments with steadier equipment utilization rates.
- Snack Foods:High-temperature extrusion cooking expands starch matrices into porous, crispy structures through rapid moisture flash-off. German and Polish manufacturers dominate European capacity, driven by private-label contract manufacturing growth for discount retail chains.
- Breakfast Cereals:Controlled expansion and coating compatibility requirements demand precise screw speed modulation and die temperature profiling. Swiss and UK cereal producers are retrofitting aging lines with segmented barrel designs to reduce energy intensity per kilogram output.
- Pet Food:High-moisture extrusion of animal protein and grain blends requires corrosion-resistant barrel linings and specialized die face cutters. French and Spanish processors are expanding wet extrusion capacity for premium functional pet nutrition products.
- Pasta Products:Cold extrusion at controlled temperatures preserves protein structure and surface texture integrity. Italian manufacturers retain dominant equipment bases, with Emilia-Romagna and Campania clusters specializing in bronze-die traditional formats.
- Meat Analogues:High-moisture extrusion at 40-70% water content creates fibrous textures simulating whole-muscle meat. Dutch and Belgian plant-based protein specialists are absorbing the steepest expansion trajectory as retailer shelf-space commitments accelerate.
Snack foods concentrate legacy installed base. Meat analogues are climbing the fastest.
End User:
Procurement authority is fragmenting as contract manufacturers gain technical capabilities previously captive to integrated food processors.
- Food Processing Companies:Integrated manufacturers with in-house R&D capabilities specify customized extrusion lines for proprietary product formulations. German and Swiss cereal and snack conglomerates dominate capital expenditure flows, prioritizing throughput maximization and energy recovery systems.
- Contract Manufacturers:Third-party processors serving multiple brand owners demand equipment flexibility across rapid product changeovers. Dutch and Polish contract extrusion specialists are expanding twin screw capacity to capture plant-based protein toll manufacturing contracts.
- Ingredient Suppliers:Pre-gelatinized starch and textured vegetable protein producers require dedicated extrusion assets for intermediate ingredient production. Belgian and German ingredient technology firms are retrofitting lines for clean-label expansion and reduced acrylamide formation.
- Specialty Food Producers:Artisanal and regional manufacturers prioritize small-batch flexibility over throughput optimization. Italian specialty pasta and Danish craft meat analogue producers favor compact twin screw systems with rapid configuration change capability.
Food processing companies anchor equipment ownership. Contract manufacturers are expanding fastest.
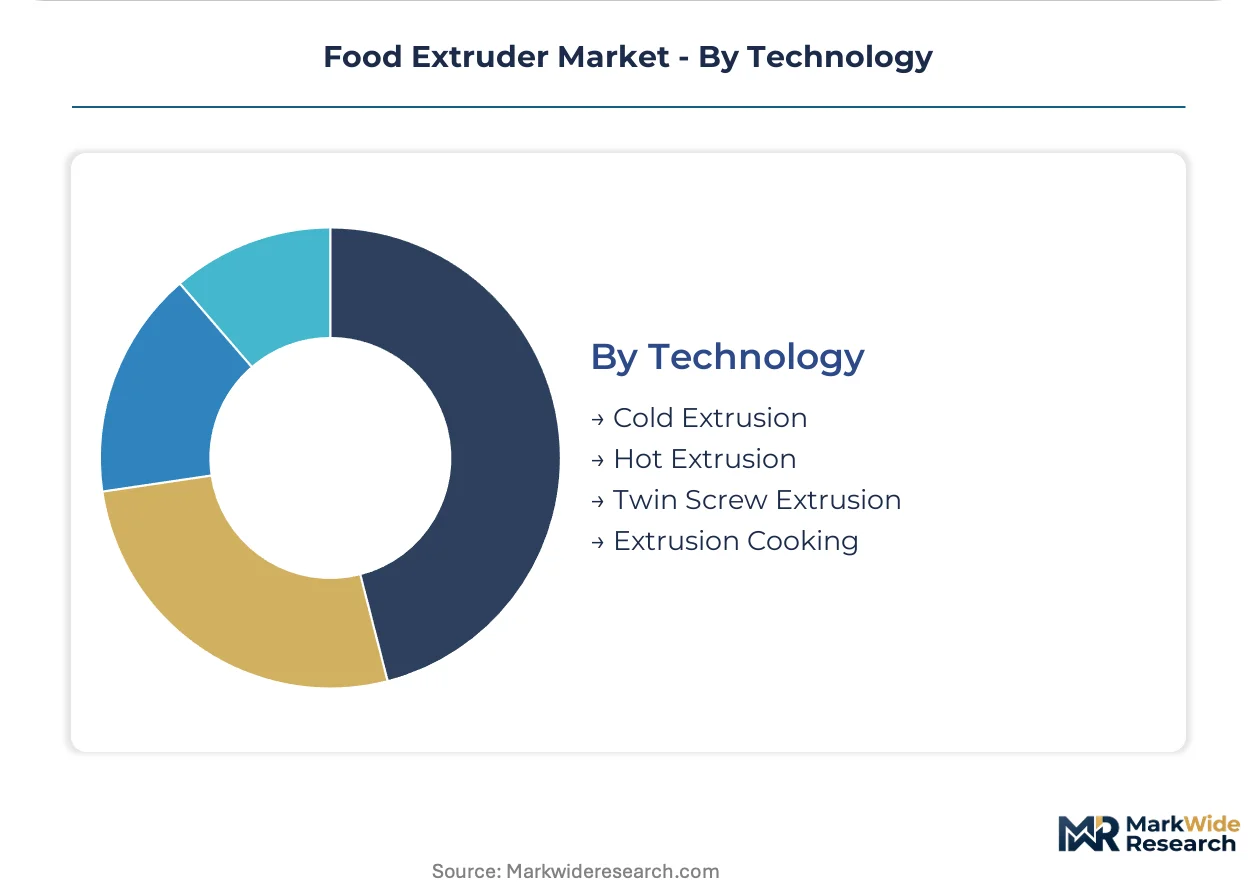
Technology:
Energy intensity and thermal recovery specifications are hardening selection criteria as CSRD disclosure requirements extend to Scope 2 emissions accounting.
- Cold Extrusion:Processing below gelatinization temperatures preserves native starch and protein structures for pasta and specialty dough applications. Italian manufacturers retain dominant process expertise, with lower thermal energy requirements insulating margins from electricity price volatility.
- Hot Extrusion:Elevated barrel temperatures enable starch gelatinization and protein denaturation for expanded snacks and cereals. German snack producers are retrofitting heat recovery systems to satisfy EU Green Deal efficiency mandates and reduce carbon intensity metrics.
- Twin Screw Extrusion:Intermeshing screw geometry delivers distributive and dispersive mixing across viscous, multi-component formulations. Dutch meat analogue specialists and German cereal manufacturers are concentrating procurement here for superior process control and reduced specific energy consumption.
- Extrusion Cooking:Integrated thermal and mechanical energy input achieves complete starch conversion and microbial reduction in single-pass processing. High-throughput snack manufacturers in Germany and Poland favor these systems for continuous production economics.
Extrusion cooking holds installed capacity. Twin screw extrusion is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German snack manufacturers deploy twin screw systems for energy-intensive thermal expansion, while Italian pasta producers favor cold extrusion with minimal heat input, revealing a stark consumption-mix split between northern and southern European processing philosophies.
Germany
Large-scale cereal and snack conglomerates in North Rhine-Westphalia and Bavaria drive replacement cycles for high-throughput twin screw systems. The EU Green Deal mandates under CSRD disclosure requirements compel manufacturers to retrofit heat recovery systems and document Scope 2 emissions reductions. Cologne and Munich industrial clusters concentrate wet extrusion capacity expansion for plant-based meat analogue toll manufacturing contracts.
Netherlands
Dutch meat analogue specialists absorb the steepest equipment procurement trajectory as retailer shelf-space commitments for alternative proteins accelerate. EFSA guidance on acrylamide formation during high-temperature extrusion shapes process redesign obligations for manufacturers in Gelderland and Noord-Brabant. Eindhoven-based contract extruders are adopting outcome-based performance contracts rather than capital purchase models.
Italy
Domestic-focused pasta processors retain single screw installations for lower throughput requirements in traditional bronze-die formats. REACH restrictions on perfluorinated lubricants redirect barrel coating R&D toward food-safe ceramic alternatives among equipment fabricators in Emilia-Romagna. Parma and Campania clusters specialize in cold extrusion for protein structure preservation and surface texture integrity.
France
Pet food processors expand wet extrusion capacity for premium functional nutrition products requiring corrosion-resistant barrel linings. ECHA evaluation timelines for novel surface treatments extend certification protocols for equipment manufacturers serving the Grand Est and Occitanie regions. Toulouse industrial zones deploy conical twin screw configurations for dense feed formulations with precise density control.
Belgium
Ingredient technology firms retrofit lines for clean-label expansion and reduced acrylamide formation in pre-gelatinized starch production. CSRD sustainability disclosure requirements pressure Antwerp and Flemish Brabant facilities to replace legacy single-screw systems with energy-efficient platforms. Belgian plant-based protein specialists concentrate procurement of advanced co-rotating systems for 40-70% moisture content processing.
Food Extruder Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in food extrusion equipment supply. Swiss and German engineering conglomerates anchor premium positioning through thermal processing heritage and co-rotating twin screw specialization. The mid-tier fragments across regional fabricators serving pasta, pet food, and snack segments with standardized single-screw platforms. Strategic moves concentrate on geographic expansion through distribution partnerships and technology licensing agreements for high-moisture meat analogue applications.
Within the integrated engineering tier, Bühler Group and Coperion occupy positions shaped by Swiss and German manufacturing heritage respectively. Wenger Manufacturing exemplifies the specialist archetype through its concentration in pet food extrusion segments. These three entities represent distinct competitive vectors: thermal processing technology leadership, co-rotating twin screw system specialization, and segment-dominant installed base leverage.
| Leading Market Players |
|---|
| Baker Perkins |
| Pavan Group |
| Bühler Group |
| Coperion |
| CPM Extrusion Group |
| Clextral |
| Reading Bakery Systems |
| American Extrusion International |
| Wenger Manufacturing |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation contracts dominate procurement between Dutch meat analogue specialists and German equipment fabricators, locking in twin screw extruder allocation and insulating buyers from nickel-alloy barrel lining price volatility. These arrangements concentrate pricing power with Swiss and German engineering conglomerates while extending delivery visibility across CSRD-mandated retrofit cycles.
Pricing Analysis
Project-based equipment procurement with outcome-based performance guarantees is displacing traditional capital purchase models among mid-scale plant-based processors. Three-tier pricing structure across premium, standard, and economy levels separates Swiss-engineered systems with full digital twin integration from Polish-fabricated single-screw platforms and refurbished legacy installations. Cost compression in standard-tier equipment is intensifying because Indonesian nickel supply concentration feeds input volatility into barrel alloy specifications. Contract manufacturers serving multiple brand owners exhibit highest price sensitivity, while integrated German cereal conglomerates prioritize throughput guarantees over unit economics.
Supply Chain Analysis
Inventory cycles for food-grade ceramic barrel coatings now stretch fourteen to twenty months as ECHA certification protocols extend validation timelines for novel surface treatments. Manufacturing concentrates in Germany, Switzerland, and Italy, with Emilia-Romagna fabricators specializing in cold extrusion components for traditional pasta formats. Nickel-based alloys and perfluorinated lubricant alternatives draw from mining operations in Indonesia and Russia, creating single-source vulnerability for REACH-compliant barrel linings. Distribution runs through direct OEM sales teams for large-scale installations and regional distributor networks for aftermarket parts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Food extrusion equipment is transitioning toward platform economics as digital twin integration and predictive maintenance contracts restructure vendor-customer relationships around guaranteed throughput outcomes rather than asset ownership.
For Market Incumbents: Compound defensive positioning through captive supply of nickel-based barrel alloys and in-house ceramic coating capabilities to offset REACH-driven input cost volatility. Deepen process engineering talent pools via apprenticeship partnerships with Dutch and German technical universities to constrain commissioning timeline elongation. Prioritize retrofit service contracts for installed single-screw bases threatened by EU Green Deal replacement mandates. For New Entrants and Emerging Players: Anchor in Italian cold extrusion segments serving bronze-die pasta specialists, where lower capital intensity and steadier margin pools reduce competitive exposure to Swiss-German engineering conglomerates. Target artisanal meat analogue startups in Denmark with compact twin screw systems offering rapid configuration change capability. Pursue toll manufacturing partnerships with Belgian ingredient suppliers seeking clean-label extrusion capacity. For Investors and Strategic Acquirers: Specialized process engineering firms with starch-protein rheology expertise represent compelling acquisition targets as talent scarcity constrains industry capacity expansion. Evaluate long-term viability through lens of CSRD disclosure adoption rates across European food manufacturing. Watch EFSA acrylamide guidance finalization as inflection indicator for mandatory retrofit demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Alloy Supply | Captive sourcing of barrel linings insulates margins from Indonesian supply volatility and REACH certification delays. |
| Digital Twin Platform Integration | Real-time sensor analytics enable predictive maintenance contracts with German snack manufacturers seeking CSRD compliance. |
| Process Engineering Talent Acquisition | Specialist recruitment compresses commissioning timelines for Dutch meat analogue capacity expansions. |
| Cold Extrusion Segment Diversification | Italian pasta equipment demand offers steadier margins with reduced thermal energy exposure. |
| Outcome-Based Performance Contracting | Guaranteed throughput metrics lock in multi-year revenue streams with Belgian plant-based protein processors. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of ECHA regulatory filings, EU trade statistics, and equipment manufacturer technical documentation. Primary interviews engaged extrusion process engineers, plant managers at German snack facilities, procurement leads at Dutch meat analogue specialists, and aftermarket service heads at Swiss engineering conglomerates. Secondary sources included customs data on nickel alloy imports, EFSA guidance documents, and SEC filings from publicly traded food processing equipment vendors. Bottom-up installation base estimates triangulated against top-down capital expenditure flows across European food manufacturing.
Segmentation dimensions modeled include screw geometry configuration, moisture content tolerance, thermal processing intensity, end-use application, and geographic regulatory cluster. CAGRs derived from equipment replacement cycle analysis, EU Green Deal mandate adoption curves, and plant-based protein capacity expansion announcements. Forecast inputs incorporated REACH compliance timeline projections and EFSA acrylamide guidance anticipation effects across the analysis window.
Decision-makers should treat outputs as directional under assumptions of sustained EU Green Deal enforcement and stable nickel supply from Indonesian mining operations; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Dry Ice Market
Food Processing Equipment
Global Automatic Mask Production Equipment Market
Food Processing Equipment
Milk Sterilizer Machine Market
Food Processing Equipment
Pasta Machine Market
Food Processing Equipment
Food Ingredients Sterilization Market
Food Processing Equipment
Deep Fryer Machine Market
Food Processing Equipment
Potato Processing Market
Food Processing Equipment
Fish Filleting Machine Market
Food Processing Equipment
Food Slicer and Dicer Market
Food Processing Equipment
Global Powder Processing Equipment Market
Food Processing Equipment
Homogenizers Market
Food Processing Equipment
Residential Food Waste Disposer Market
Food Processing Equipment
Softgel Encapsulation Machine Market
Food Processing Equipment
Walk-In Refrigerator Market
Food Processing Equipment
Global Food and Beverage Coding and Marking Equipment Market
Food Processing Equipment
Non-Thermal Food Processing Market