
 Pet Food Extrusion Market | 2026-2036
Pet Food Extrusion Market Size, Share, and Industry Trends Forecast 2026-2036
Pet Food Extrusion Market Outlook
Market Context
The dog food application vertical is rebalancing toward premium kibble and functional nutrition formats as pet owners prioritize protein density and digestibility claims. Bühler AG leverages its Swiss engineering heritage to dominate high-capacity twin-screw extrusion installations across North American facilities. Coperion GmbH sustains technology leadership in integrated process control systems that link raw material intake to finished product cooling. WENGER MANUFACTURING anchors its competitive position through deep specialization in aquatic and high-fat pet food extrusion recipes that demand precise thermal management.
Technical Definition and Segment Structure
Pet food extrusion subjects compounded feed mixtures to mechanical shear, thermal energy, and pressure within a rotating screw barrel, forcing the plasticized mass through a shaped die where rapid pressure drop induces expansion and texturization into shelf-stable kibble or treats. The process typically operates at barrel temperatures between 80°C and 180°C with residence times under 60 seconds to preserve amino acid bioavailability while achieving target starch gelatinization above 75 percent. Kibble production occupies the largest value pool given its ubiquity across dog and cat feeding routines, though freeze-dried formats command disproportionate margin concentration due to limited equipment supply and premium positioning. Plant-based ingredient sourcing is accelerating fastest among European processors responding to consumer pressure for reduced livestock dependency in companion animal diets.
Regulatory Framework and Outlook
FDA Center for Veterinary Medicine oversight and AAFCO model feed regulations govern ingredient safety, nutritional adequacy statements, and manufacturing sanitation standards across United States pet food extrusion operations. The European Food Safety Authority enforces feed hygiene regulation EC 183/2005 alongside national implementations of the EU Green Deal, pressuring manufacturers to document carbon intensity and packaging recyclability across extruded product lines. Stakeholders must monitor evolving state-level extended producer responsibility mandates and the trajectory of precision fermentation-derived proteins that could reshape conventional extrusion ingredient specifications and equipment design requirements.
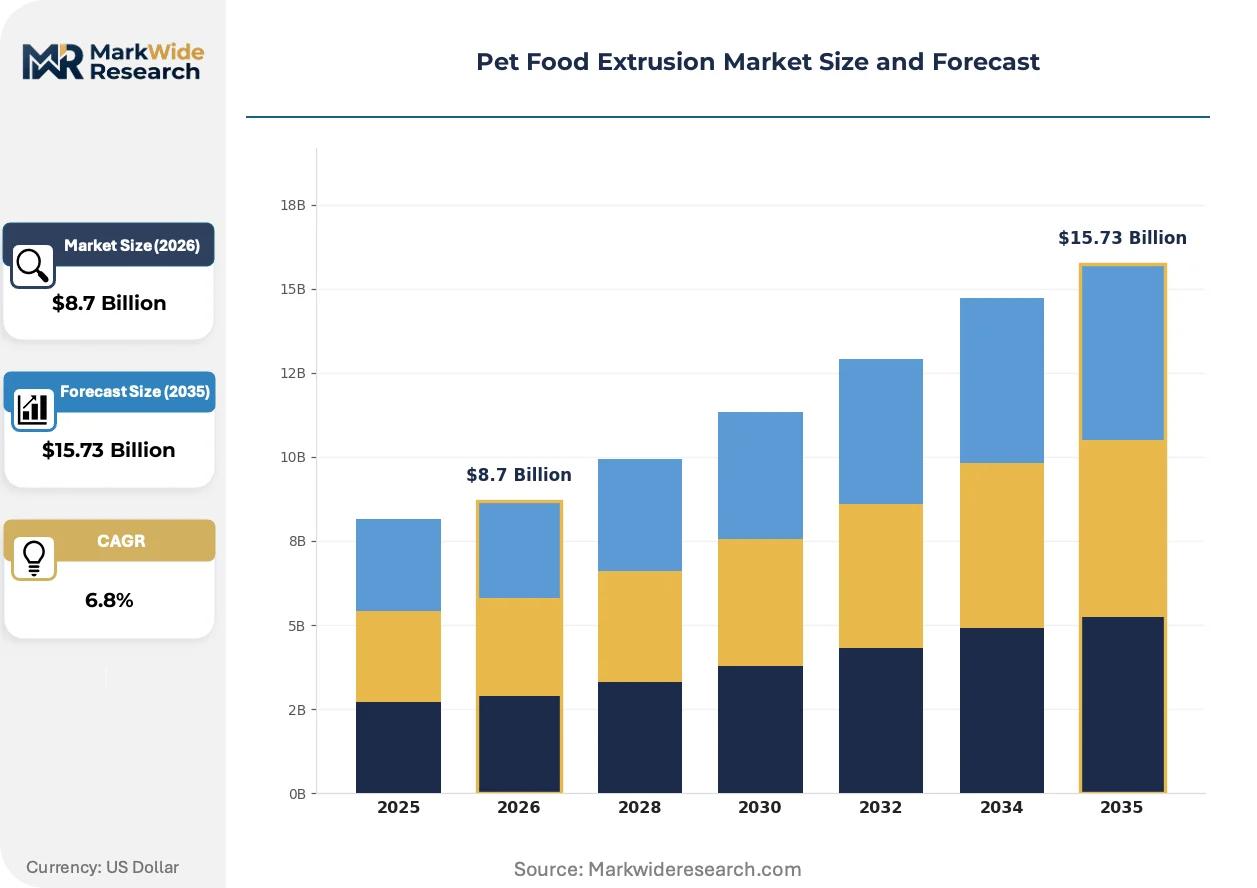
Market Dynamics
High-moisture extrusion technology is rebalancing capital allocation across pet food manufacturing, as processors retool lines to capture premium kibble margins while maintaining throughput economics on legacy dry extrusion assets.
Growth Catalysts
- AAFCO Nutritional Guidelines:Tightened label claim requirements in the United States are forcing manufacturers to upgrade extrusion traceability systems, creating replacement demand for integrated process control infrastructure.
- Brazilian Export Scaling:Regional manufacturers in São Paulo state are deploying automated extrusion capacity to serve Latin American distribution networks, concentrating procurement orders for high-capacity twin-screw systems.
- Protein Density Formulations:Consumer preference for digestibility claims is pulling formulation R&D toward high-moisture extrusion recipes that preserve amino acid bioavailability through precise thermal management.
Market Restraints
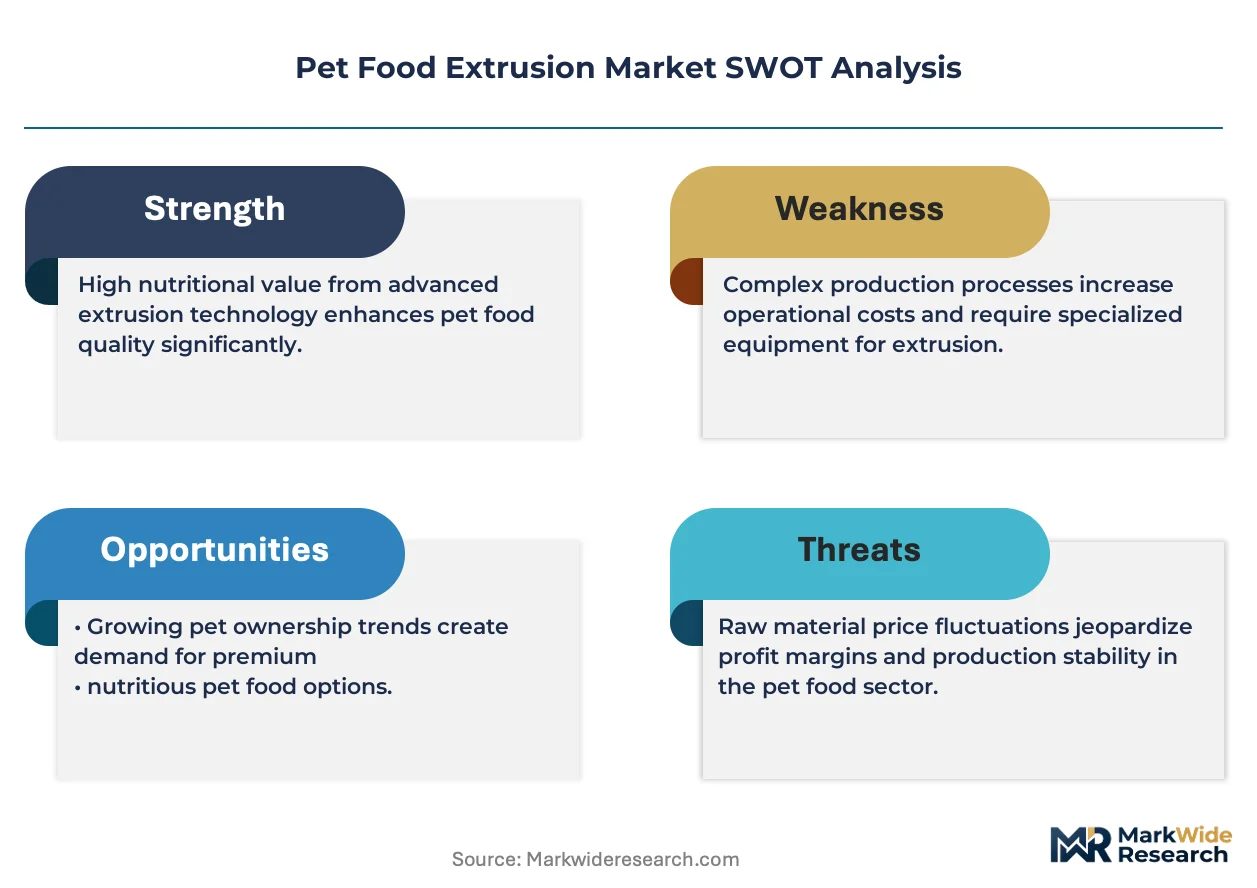
- Starch Input Volatility:Corn and pea starch prices fluctuate with agricultural commodity cycles, compressing margin predictability for extrusion processors dependent on gelatinization targets above 75 percent.
- Equipment Supplier Concentration:Swiss and German engineering firms dominate high-capacity twin-screw extrusion technology, creating single-source risk for North American facility expansions.
- Freeze-Dried Substitution:Limited equipment supply for freeze-dried formats creates capacity bottlenecks, but premium positioning in treats and toppers draws capital away from conventional extrusion expansion.
Strategic Opportunities
- Precision Fermentation Proteins:Novel protein streams from microbial biomass are expanding into extrusion trials, offering formulation pathways to reduce livestock dependency in companion animal diets.
- EU Green Deal Alignment:Carbon intensity documentation requirements and packaging recyclability mandates are creating first-mover advantages for European processors with integrated sustainability reporting.
- Veterinary Channel Penetration:Prescription therapeutic diets represent an underdeveloped application vertical, with clinics and specialty retailers seeking extruded products with clinical validation protocols.
Industry Challenges
- Thermal Process Engineering Talent:The intersection of food science and mechanical engineering required for high-fat aquatic recipe extrusion exceeds available specialized labor pools in emerging manufacturing regions.
- Legacy Control System Integration:Brownfield facilities face friction linking modern raw material intake sensors to existing cooling line automation, delaying throughput optimization projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pet Food Extrusion Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kibble, Canned, Freeze-Dried, Treats Ingredient Source: Meat, Plant-Based, Grain, Others Application: Dogs, Cats, Small Animals, Specialty Pets Packaging Type: Bags, Cans, Pouches, Tubs |
| Companies Covered | Baker Perkins, Coperion GmbH, Bühler AG, GEA Group Aktiengesellschaft, Amandus Kahl GmbH & Co. KG, Clextral, WENGER MANUFACTURING, Extru-Tech Inc., ANDRITZ, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pet Food Extrusion Market Strategic Shifts
Extrusion technology is bifurcating between premium high-moisture systems and efficiency-optimized dry lines, with regulatory pressure and consumer protein claims driving divergent capital deployment strategies across manufacturing footprints.
Twin-screw extrusion configurations with segmented barrel heating are expanding into high-fat aquatic and novel protein recipes previously considered incompatible with continuous thermal processing. Specialty pet food manufacturers in the United States and Western Europe are adopting these systems at accelerated replacement cycles, compressing equipment depreciation timelines while enabling formulation differentiation that commands shelf-space premiums in specialty retail channels.
EFSA enforcement of feed hygiene regulation EC 183/2005 is tightening manufacturing sanitation documentation across European extrusion facilities. Processors must now validate cleaning-in-place protocols and allergen segregation procedures with third-party certification, increasing compliance overhead but creating competitive moats for operators with integrated quality management systems already deployed across multi-site production networks.
Direct-to-consumer subscription models are disrupting traditional distributor relationships for premium kibble brands, with pet owners prioritizing customization and auto-replenishment over retail aisle discovery. This channel shift concentrates demand forecasting risk with extrusion manufacturers serving contract manufacturing relationships, particularly visible in United States metropolitan markets where digitally native pet food brands have captured disproportionate share of premium segment growth.
Pet Food Extrusion Market Segmentation
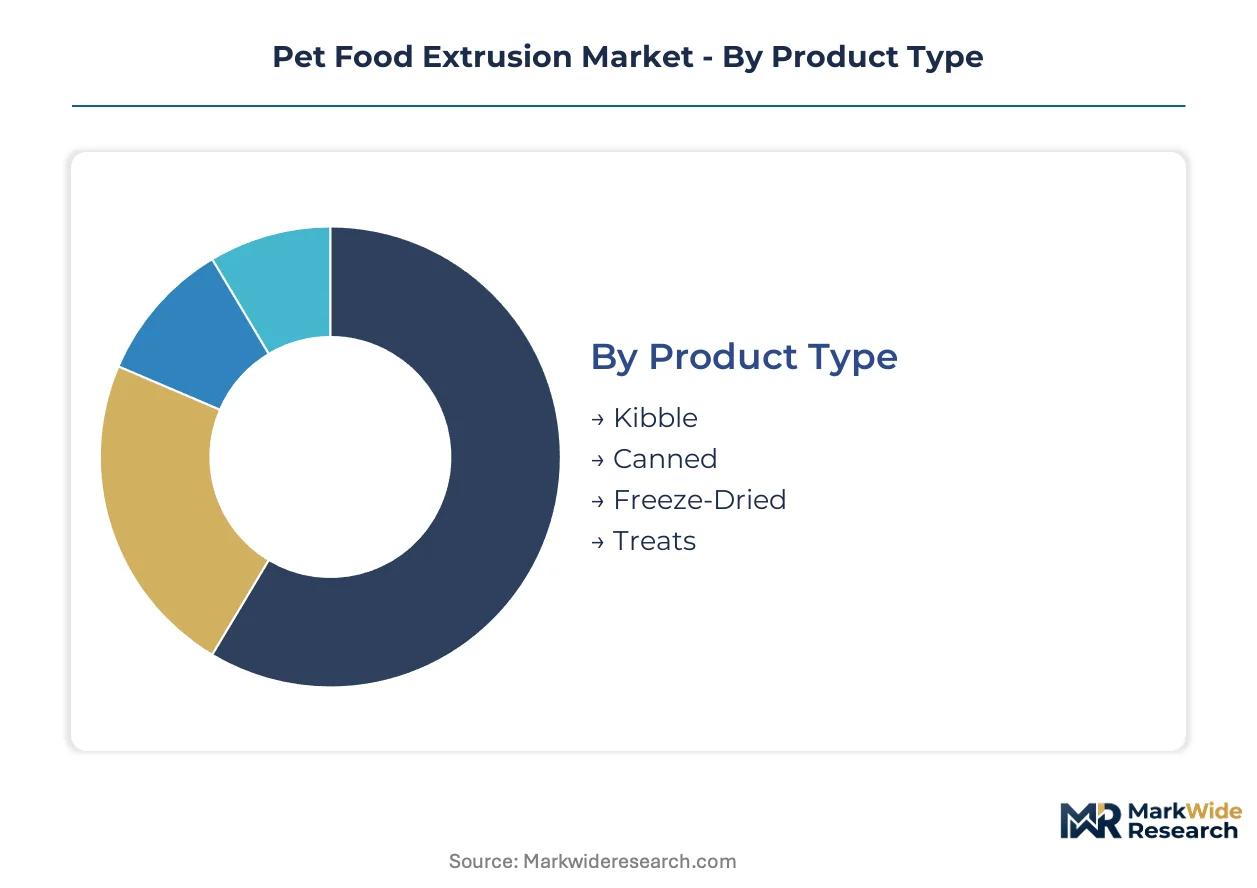
Pet food extrusion equipment and process configurations diverge sharply across product formats and target species, with thermal parameters and die geometries calibrated to specific moisture targets and expansion ratios. Procurement patterns concentrate where premiumization pressures intersect with regulatory compliance burdens, creating distinct investment profiles across manufacturing footprints.
Product Type:
Thermal processing intensity and die pressure differentials separate extrusion line configurations across shelf-stable formats.
- Kibble:Continuous extrusion at 80°C to 180°C barrel temperatures gelatinizes starch above 75 percent while preserving amino acid bioavailability through sub-60-second residence times. Brazilian manufacturers in São Paulo state scale automated twin-screw capacity to serve Latin American export networks, concentrating procurement for high-throughput systems.
- Freeze-Dried:Limited equipment supply creates capacity bottlenecks for this premium format, with thermal management preceding sublimation drying rather than expansion through die pressure drop. European processors document carbon intensity under EU Green Deal mandates, gaining first-mover positioning in sustainability-verified premium segments.
- Canned:Retort sterilization replaces extrusion as the primary thermal process, though extruded pre-forms enter wet filling lines for texture differentiation.
- Treats:Smaller die apertures and lower throughput economics characterize specialty extrusion for training and dental formats.
Kibble leads on scale; freeze-dried leads on momentum.
Ingredient Source:
Protein functionality and starch gelatinization requirements drive screw configuration and barrel heating segmentation across raw material inputs.
- Meat:High-fat animal protein recipes demand precise thermal management to prevent lipid oxidation while achieving target expansion ratios, with WENGER MANUFACTURING specializing in aquatic and high-fat extrusion systems. FDA and AAFCO nutritional guidelines tighten traceability requirements for meat-based label claims in United States facilities.
- Plant-Based:Pea and pulse protein concentrates require modified screw geometries to handle lower fat binding capacity, with European processors accelerating sourcing to reduce livestock dependency in companion animal diets.
- Grain:Corn and wheat starch volatility compresses margin predictability for processors dependent on consistent gelatinization targets.
- Others:Precision fermentation-derived proteins from microbial biomass enter extrusion trials, offering novel formulation pathways with unproven equipment compatibility.
Meat-based formulations dominate current throughput; plant-based sourcing is climbing the fastest.
Application:
Species-specific nutritional adequacy standards and feeding behavior shape die geometry and product density specifications.
- Dogs:Premiumization rebalances procurement toward high-moisture extrusion lines capable of protein density formulations with digestibility claims, with Bühler AG dominating North American high-capacity installations.
- Cats:Obligate carnivore metabolism drives higher meat inclusion rates, requiring specialized thermal profiles to preserve taurine and arachidonic acid stability through extrusion shear.
- Small Animals:Lower volume throughput and specialized pellet geometries characterize rabbit and rodent extrusion, with limited equipment standardization.
- Specialty Pets:Reptile and avian formulations occupy niche equipment footprints with irregular demand patterns.
Dogs anchor equipment scale; cats command premium thermal engineering intensity.
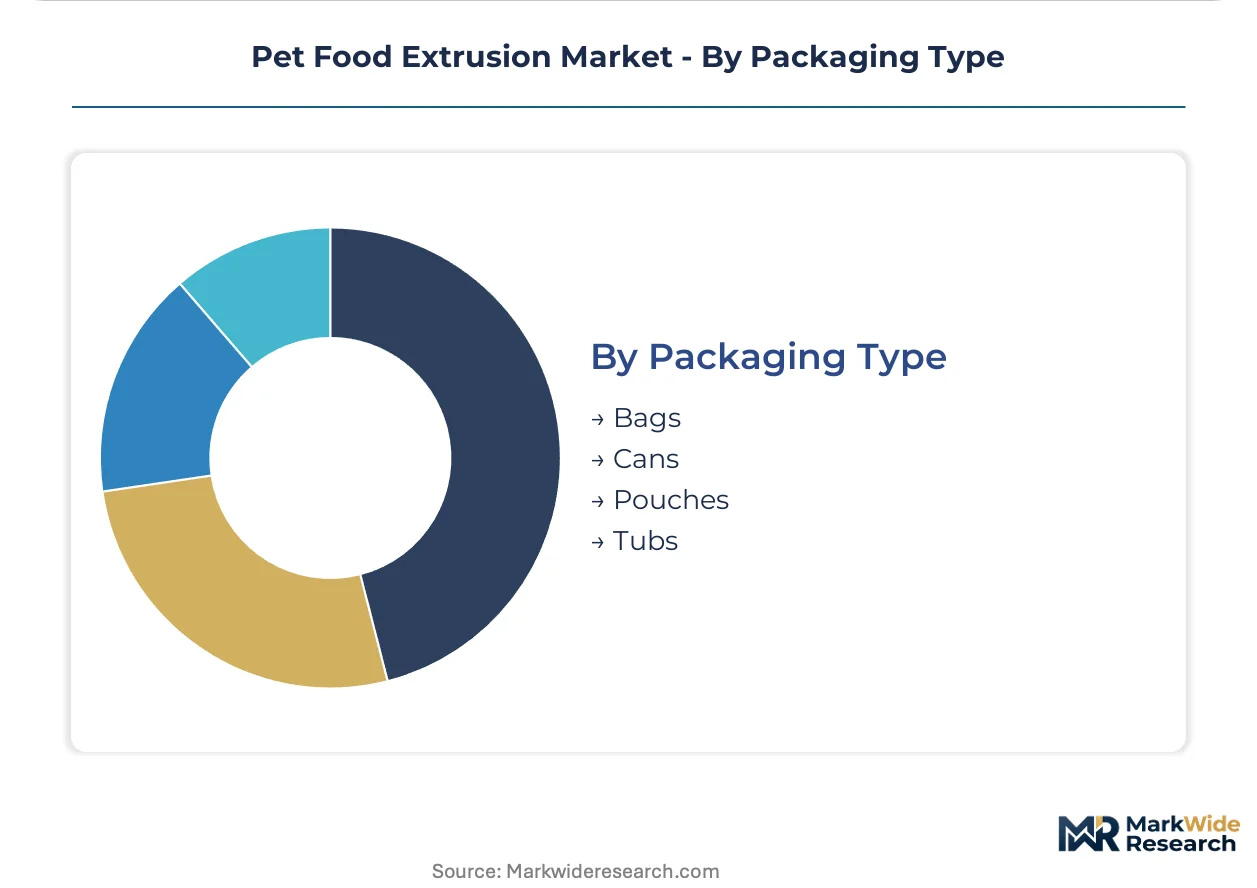
Packaging Type:
Moisture barrier requirements and shelf-life targets downstream of extrusion cooling determine material specifications and line integration architecture.
- Bags:Multi-layer flexible films with oxygen scavengers dominate kibble containment, with extended producer responsibility mandates in multiple United States states pressuring recyclability redesign.
- Pouches:Retort-compatible structures for wet extruded products require metallized barrier layers with higher unit economics.
- Cans:Metal containment for high-moisture retorted products sits outside extrusion line integration.
- Tubs:Refrigerated fresh formats with minimal thermal processing demand cold-chain logistics rather than shelf-stable packaging engineering.
Bags lead on volume throughput; pouches face steepest sustainability compliance cost escalation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo state's manufacturing corridor anchors extrusion capacity deployment for Latin American export markets, with regional processors scaling automated twin-screw systems to serve distribution networks across Mercosur trade zones. FDA and AAFCO nutritional guidelines in the United States are tightening traceability requirements, while EFSA enforcement of feed hygiene regulation EC 183/2005 reshapes European manufacturing documentation protocols.
United States
Premiumization in dog food formulations is pulling procurement toward high-moisture extrusion lines capable of protein density claims. FDA Center for Veterinary Medicine oversight governs ingredient safety and nutritional adequacy statements. Midwest manufacturing clusters in Kansas and Iowa concentrate extrusion capacity for domestic distribution and Canadian export.
Brazil
Regional pet food manufacturers in São Paulo state are deploying automated extrusion capacity to serve Latin American distribution networks. ANVISA regulatory alignment with Mercosur trade standards facilitates cross-border ingredient sourcing. Campinas and Sorocaba industrial zones concentrate high-throughput twin-screw system installations for regional export.
Germany
EU Green Deal carbon intensity documentation requirements are pressuring manufacturers to validate sustainability metrics across extruded product lines. EFSA feed hygiene regulation EC 183/2005 mandates third-party certification of cleaning-in-place protocols. Baden-Württemberg engineering clusters specialize in integrated process control systems linking raw material intake to finished product cooling.
China
Domestic pet ownership growth is stimulating demand for shelf-stable kibble formats with localized protein sourcing. SAMR feed safety standards govern manufacturing sanitation and ingredient traceability. Yangtze River Delta manufacturing zones concentrate mid-capacity extrusion lines serving domestic brands and Southeast Asian export markets.
Switzerland
Swiss engineering heritage dominates high-capacity twin-screw extrusion technology for North American facility expansions. Swissmedic alignment with EU veterinary feed regulations facilitates cross-border equipment certification. Zurich and Basel industrial corridors anchor precision thermal management system development for aquatic and high-fat recipe applications.
Pet Food Extrusion Market Competitive Environment
Capacity expansion dominates the current landscape as processors retool lines to capture premium kibble margins while maintaining throughput economics on legacy dry extrusion assets. The vendor base concentrates around Swiss and German engineering firms with deep specialization in thermal process control, creating tiered supply dynamics between integrated system providers and component specialists. Two strategic archetypes prevail: full-line integrators offering end-to-end process control, and niche specialists focused on high-fat aquatic recipes or novel protein thermal management. Geographic expansion into Brazilian and Southeast Asian markets and technology licensing for precision fermentation protein compatibility represent the dominant competitive moves.
Within the full-line integrator tier, Bühler AG and Coperion GmbH exemplify the engineering-intensive positioning required for high-capacity twin-screw installations. WENGER MANUFACTURING occupies a specialist position anchored in aquatic and high-fat recipe thermal management. These three firms collectively represent the concentration of extrusion technology leadership serving North American and European premium pet food manufacturing footprints.
| Leading Market Players |
|---|
| Baker Perkins |
| Coperion GmbH |
| Bühler AG |
| GEA Group Aktiengesellschaft |
| Amandus Kahl GmbH & Co. KG |
| Clextral |
| WENGER MANUFACTURING |
| Extru-Tech Inc. |
| ANDRITZ |
| Others |
Value Chain & Pricing Dynamics
High-moisture extrusion technology adoption is compressing cost economics for premium kibble while concentrating procurement power among Swiss and German engineering suppliers capable of precision thermal management systems. This production-method transition simultaneously elevates capital requirements for new entrants and tightens margin predictability for processors caught between legacy dry-line assets and replacement cycles for protein-density-capable equipment.
Pricing Analysis
Input-cost pass-through from corn and pea starch volatility runs through standard-tier kibble formulations, while premium-mid-economy pricing differentiation separates high-moisture systems with digestibility claims from commodity dry extrusion output. Price differentiation hinges on thermal precision certification and protein density validation. Pricing pressure stems from Brazilian manufacturers scaling automated capacity for Latin American export markets. Contract manufacturing buyers exhibit highest price sensitivity; direct-to-consumer premium brands show lowest.
Supply Chain Analysis
Regional distribution centers in São Paulo state, Kansas-Iowa clusters, and Yangtze River Delta zones anchor hub-and-spoke patterns for extrusion equipment and finished kibble movement. Geographic supply concentration centers on Switzerland, Germany, and Brazil for high-capacity twin-screw systems. Raw material flows draw from corn belt agriculture, pea protein processing, and precision fermentation biomass trials. Single-source vulnerability from Swiss-German engineering dominance creates procurement risk. Distribution runs through veterinary clinics, specialty retailers, and direct-to-consumer subscription platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pet food extrusion operates as a late-cycle quality story where premiumization toward protein-density formulations with AAFCO-validated label claims now determines competitive survival. This demand-shift rewards processors with integrated process control infrastructure and penalizes legacy asset dependence.
For Market Incumbents: Deepen backward integration into precision fermentation protein supply to preempt ingredient specification disruption from novel biomass streams. Expand high-moisture extrusion capacity in São Paulo state to capture Latin American export procurement concentration. Defend against freeze-dried format substitution by accelerating thermal management R&D for aquatic and high-fat recipes. For New Entrants and Emerging Players: Veterinary clinic networks represent the most penetrable channel partner type for prescription therapeutic diet white-space, bypassing saturated retail shelf competition. Target underdeveloped small animal and specialty pet extrusion segments where equipment standardization gaps limit incumbent scale advantages. Pursue equipment-as-a-service financing to overcome capital barriers from Swiss-German supplier concentration. For Investors and Strategic Acquirers: Valuations sit cheapest among European processors with EU Green Deal carbon documentation systems already deployed, trading at discounts to North American peers despite sustainability compliance moats. Five-to-ten year viability favors operators with multi-site quality management certification and backward integration into alternative protein R&D. Watch precision fermentation protein extrusion compatibility trials as the inflection signal for conventional livestock ingredient displacement.| Strategic Initiative | Industry Significance |
|---|---|
| High-Moisture Extrusion Capacity Expansion | Brazilian São Paulo manufacturers capture Latin American export procurement concentration. |
| Precision Fermentation Protein Integration | Novel microbial biomass streams reduce livestock dependency in companion animal formulations. |
| EU Green Deal Compliance Certification | Carbon intensity documentation creates competitive moats for European multi-site operators. |
| Veterinary Channel Partnership Development | Prescription therapeutic diets unlock underpenetrated clinic and specialty retail distribution. |
| Direct-to-Consumer Subscription Platform Launch | Auto-replenishment models concentrate demand forecasting risk with contract extrusion manufacturers. |
Study Parameters
Multiple input streams — extrusion equipment procurement databases, pet food manufacturer facility filings, and regulatory submission records — were reconciled against primary interviews with plant engineering directors, procurement leads at regional pet food processors, AAFCO regulatory affairs specialists, and veterinary channel sales heads. Secondary validation drew from FDA Center for Veterinary Medicine guidance documents, EFSA feed hygiene regulation implementations, ANVISA Mercosur alignment protocols, and customs trade data for extrusion equipment imports. Bottom-up capacity installations and top-down market value estimates underwent iterative triangulation.
Data-stream reconciliation across equipment shipments, ingredient sourcing patterns, and finished product distribution channels informed the analytical framework over the projection horizon. Segmentation dimensions modeled include product format, ingredient source, target species application, and regional manufacturing cluster. CAGRs were derived from capacity-weighted average growth assumptions. Industry-specific forecast inputs incorporated thermal process equipment replacement cycles and precision fermentation protein commercialization timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to regulatory shifts in FDA nutritional guideline enforcement, precision fermentation protein scale-up viability, and extended producer responsibility mandate expansion across United States states. Outputs reflect documented assumptions about equipment supplier concentration and premiumization demand elasticity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Ultrasonic Homogenizer Machines Market
Food Processing Equipment
North America Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Ribbon Blenders Market
Food Processing Equipment
Sous Vide Cooking Appliances Market
Food Processing Equipment
Plastic Processing Machinery Market
Food Processing Equipment
Cookie Dropper Machine Market
Food Processing Equipment
Global Non Thermal Processing Market
Food Processing Equipment
Commercial Food Processors Market
Food Processing Equipment
Smart Meat Thermometer Market
Food Processing Equipment
Freshwater Flake Ice Machine Market
Food Processing Equipment
Food and Beverages Air Filters Market
Food Processing Equipment
Global Wine Tanks Market
Food Processing Equipment
Global Electrodialysis Equipment Market
Food Processing Equipment
Walk-In Coolers and Freezers Market
Food Processing Equipment
Microbrewery Equipment Market
Food Processing Equipment
Individual Quick Freezing Market