
 Wine Processing Equipment Market | 2026-2036
Wine Processing Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Wine Processing Equipment Market Analytics
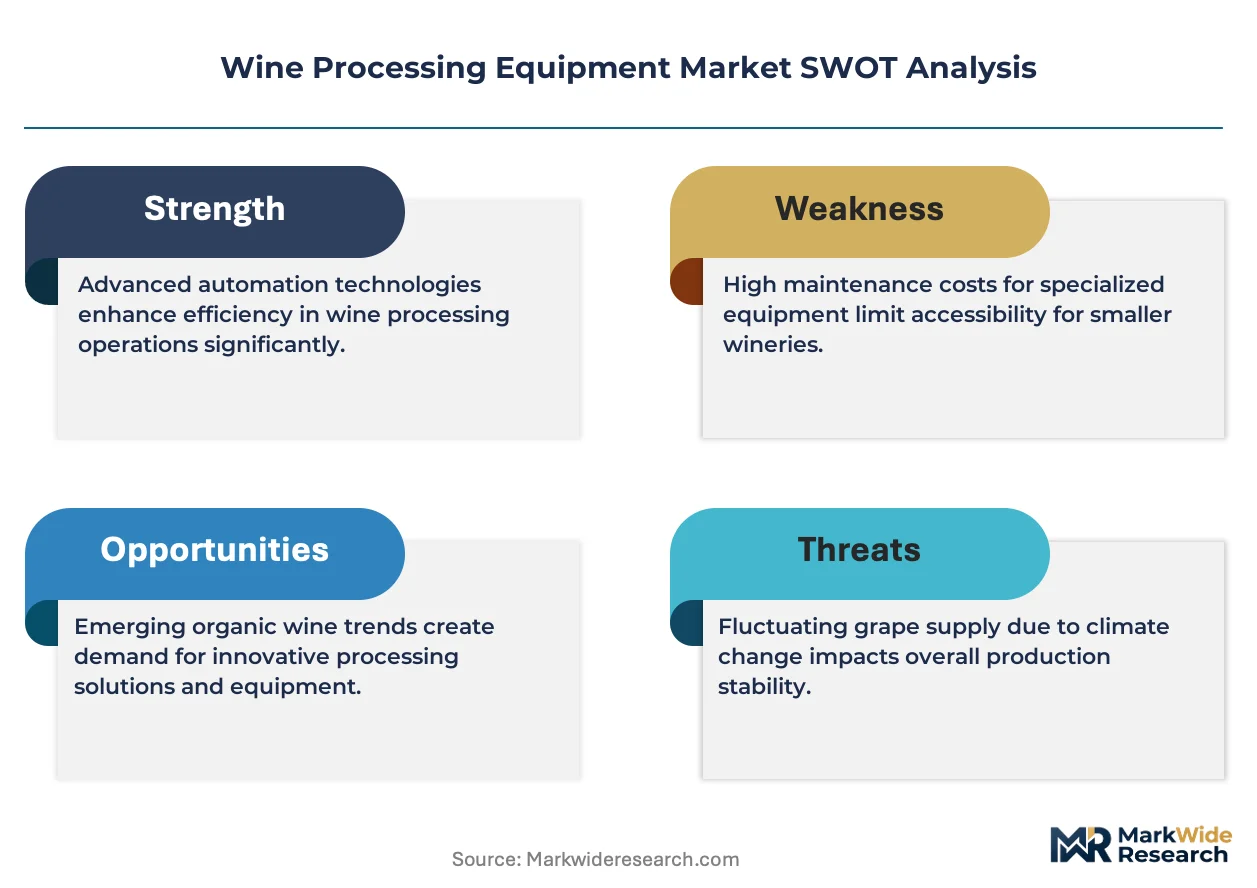
The EU Green Deal is decoupling wine processing equipment procurement from energy-intensive legacy designs across European Union member states. Criveller Group leverages its North American manufacturing footprint to sustain delivery advantages for stainless steel fermentation tanks. Pellenc Group differentiates through precision harvesting and sorting integration that anchors its equipment within premium winery workflows. Deutsche Beverage Technology competes on modular system architecture that allows boutique producers to scale capacity without full line replacement.
Wine processing equipment encompasses the mechanical and thermal systems used to transform harvested grapes into finished wine, including stainless steel fermenters with temperature control jackets operating between 10°C and 30°C, pneumatic presses exerting 0.5 to 2.0 bar pressure, cross-flow filters rated at 0.45 to 1.0 micron retention, and variable-speed must pumps handling viscosities up to 5,000 cP. Fermenters dominate capital expenditure allocation due to their central role in alcohol conversion and flavor development, while cold stabilization equipment records the fastest growth trajectory as wineries confront climate-driven vintage variability. Reverse osmosis technology occupies concentrated margin pools among high-volume producers seeking alcohol adjustment and water removal without thermal degradation.
Regulatory frameworks including the EU F-Gas Regulation, FDA Current Good Manufacturing Practice standards for alcoholic beverages, and Australia's Food Standards Code govern refrigerant selection, sanitary design, and labeling compliance across equipment procurement decisions. REACH and RoHS constraints in Europe restrict certain stainless steel alloy compositions and electrical component chemistries, while CE marking mandates shape third-party testing expenditures for machinery exporters. Stakeholders must monitor evolving national energy efficiency standards and carbon border adjustment mechanisms to align capital deployment with compliance trajectories that will determine market access eligibility.
Market Dynamics
Automated fermentation systems are displacing open-tank traditional setups as estate wineries confront labor scarcity and vintage compression from climate volatility. Equipment procurement decisions now hinge on energy efficiency certification and carbon footprint disclosure rather than throughput metrics alone.
Growth Catalysts
- EU F-Gas Regulation:Mandatory refrigerant phase-downs are accelerating replacement cycles for cold stabilization equipment across Italian and Spanish wineries, creating pull-through demand for compliant heat pump systems.
- Premium vineyard modernization:Estate producers in California's Napa Valley and Sonoma County are retrofitting temperature-controlled stainless steel fermenters to achieve block-level fermentation precision for single-vineyard bottlings.
- Cross-flow filtration:Membrane filtration rated at 0.45 micron retention is displacing diatomaceous earth and sheet filtration in high-volume Australian export facilities seeking water recovery and waste reduction.
Market Restraints
- Stainless steel alloy volatility:REACH and RoHS constraints on specific chromium and nickel compositions are restricting supply availability and extending lead times for European tank fabricators.
- Specialized technician scarcity:Cross-flow membrane maintenance and automated control system calibration require skills concentrated among a limited cohort of service providers in South Australia and Northern California.
- Legacy infrastructure lock-in:Existing concrete and wooden fermentation vessels in traditional Tuscan estates create sunk-cost barriers to full-line replacement despite efficiency gains from steel alternatives.
Strategic Opportunities
- Small-lot contract processing:Mobile bottling and custom crush facilities in emerging wine regions of Texas Hill Country and Virginia are creating demand for modular, trailer-mounted filtration and stabilization units.
- Carbon border adjustment alignment:EU Green Deal compliance documentation is becoming a procurement gate for export-oriented wineries in Chile and Argentina seeking European market access.
- Reverse osmosis and spinning cone convergence:Integrated alcohol adjustment and volatile acidity correction systems are opening margin pools among high-volume producers managing climate-driven sugar accumulation.
Industry Challenges
- CE marking certification timelines:Third-party machinery testing for European market entry is extending product launch windows by 8-14 months for North American and Australian equipment manufacturers.
- Automation integration complexity:Retrofitting legacy pneumatic presses with IoT-enabled pressure monitoring requires custom engineering that strains boutique winery technical staff and capital budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wine Processing Equipment Market |
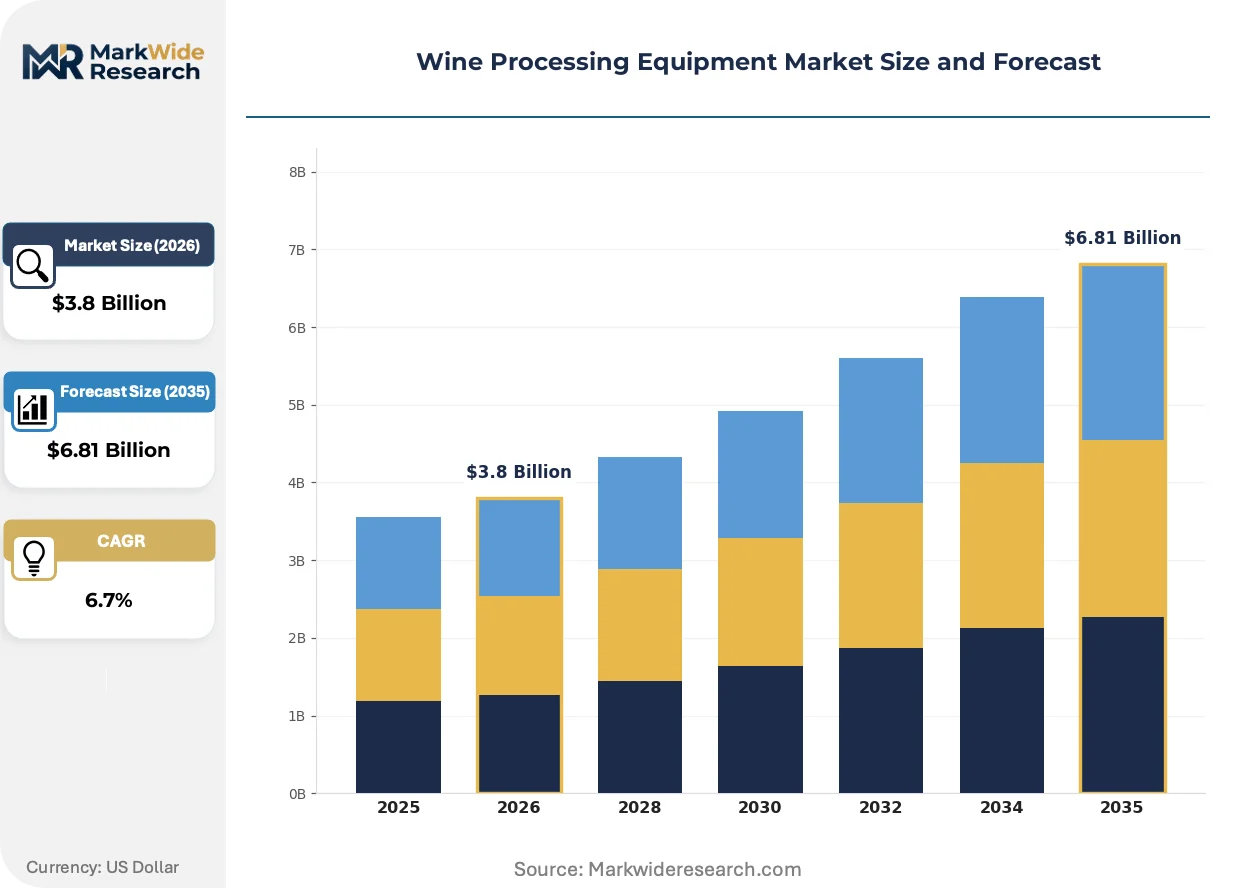
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fermenters, Presses, Filters, Pumps Technology: Malolactic Fermentation, Cold Stabilization, Reverse Osmosis, Flash Pasteurization End User: Commercial Wineries, Boutique Wineries, Vineyards, Research Institutions Installation: On-site, Off-site, Mobile, Permanent |
| Companies Covered | Criveller Group, Agrovin, Della Toffola Pacific, DT Pacific Pty Ltd, GW Kent Inc, Paul Mueller Company, Deutsche Beverage Technology, Boema S.p.A., Pellenc Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wine Processing Equipment Market Evolving Landscape
Digital fermentation monitoring and energy recovery systems are compressing the capability gap between estate-scale and industrial-scale wine production. Equipment vendors are repositioning around data-enabled service models rather than standalone hardware sales.
Temperature-controlled stainless steel fermenters with integrated cooling jackets are consolidating market share across premium and super-premium winery segments. Estate producers in California and Oregon are specifying glycol-cooled tanks with automated cap management to reduce labor exposure during harvest compression. This consolidation is compressing demand for traditional open-top wooden fermenters in new facility construction.
EU F-Gas Regulation phase-down schedules are mandating refrigerant transitions in cold stabilization and refrigeration equipment. Wineries across Germany, France, and Italy are retrofitting propane-based heat pump systems to replace legacy HFC installations ahead of 2030 prohibition deadlines. Cold stabilization equipment procurement in these markets is now contingent on refrigerant compliance certification from equipment suppliers.
Equipment-as-a-service contracting is displacing traditional capital purchase models among mid-scale wineries. California and Australian producers are subscribing to fermentation monitoring and predictive maintenance packages bundled with tank leases. This shift concentrates vendor relationships with regional service networks capable of guaranteed uptime performance rather than equipment financiers.
Wine Processing Equipment Market Segmentation
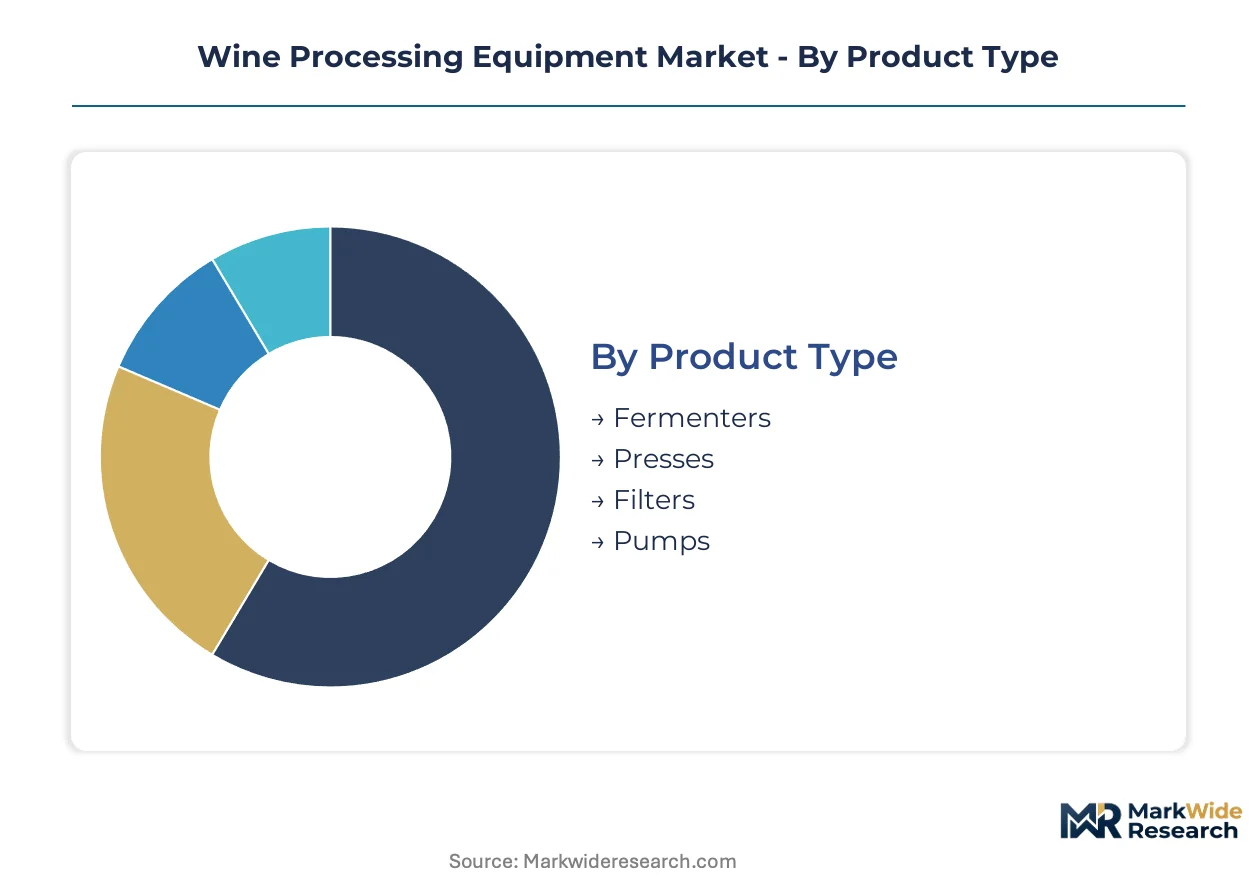
Wine processing equipment segmentation reveals distinct technology-performance tiers that shape capital deployment patterns across estate and industrial producers. Equipment specification directly determines energy compliance eligibility, labor substitution potential, and integration complexity within existing cellar infrastructure.
Product Type:
Temperature control precision and pressure specification differentiate equipment performance across fermentation and finishing stages.
- Fermenters:Stainless steel vessels with glycol-jacketed cooling systems operating between 10°C and 30°C anchor capital expenditure allocation due to their central role in alcohol conversion. Demand concentrates in California's Napa Valley and Sonoma County where estate producers retrofit for block-level fermentation precision.
- Presses:Pneumatic membrane systems exerting 0.5 to 2.0 bar pressure extract must with controlled phenolic extraction. Italian and Spanish wineries face replacement cycles driven by EU F-Gas Regulation phase-downs for integrated cooling systems.
- Filters:Cross-flow membrane units rated at 0.45 to 1.0 micron retention displace diatomaceous earth in Australian export facilities seeking water recovery compliance.
- Pumps:Variable-speed must pumps handle viscosities up to 5,000 cP across transfer and bottling operations.
Fermenters lead on scale; cold-stabilization-integrated filters lead on momentum.
Technology:
Process intensification technologies separate premium estate workflows from high-volume commodity production on energy efficiency and precision parameters.
- Malolactic Fermentation:Controlled bacterial conversion systems modulate acidity profiles in red wine production. French and Italian producers deploy temperature-controlled inoculation systems to manage vintage compression from climate volatility.
- Cold Stabilization:Propane-based heat pump systems replace legacy HFC installations ahead of EU prohibition deadlines. German and French retrofit demand accelerates as wineries confront carbon border adjustment documentation requirements for export eligibility.
- Reverse Osmosis:Membrane-based alcohol adjustment and water removal systems occupy concentrated margin pools among high-volume producers managing climate-driven sugar accumulation.
- Flash Pasteurization:High-temperature short-time thermal systems ensure microbial stability in bulk wine transport and private-label bottling.
Cold stabilization leads on regulatory pull-through; reverse osmosis leads on margin capture.
End User:
Scale and certification requirements fragment procurement patterns across estate ownership structures and production volumes.
- Commercial Wineries:Large-scale facilities across Australia's Riverina and California's Central Valley specify automated fermentation and cross-flow filtration for export volume compliance with EU Green Deal carbon documentation.
- Boutique Wineries:Estate producers in Oregon's Willamette Valley and Virginia's Monticello AVA prioritize modular system architecture enabling capacity scaling without full line replacement.
- Vineyards:Integrated grower-producers in South Australia specify mobile bottling and custom crush equipment for harvest flexibility.
- Research Institutions:University enology programs and cooperative extension facilities pilot precision fermentation monitoring for technology transfer to commercial adopters.
Commercial wineries lead on volume concentration; boutique wineries lead on equipment-as-a-service adoption velocity.
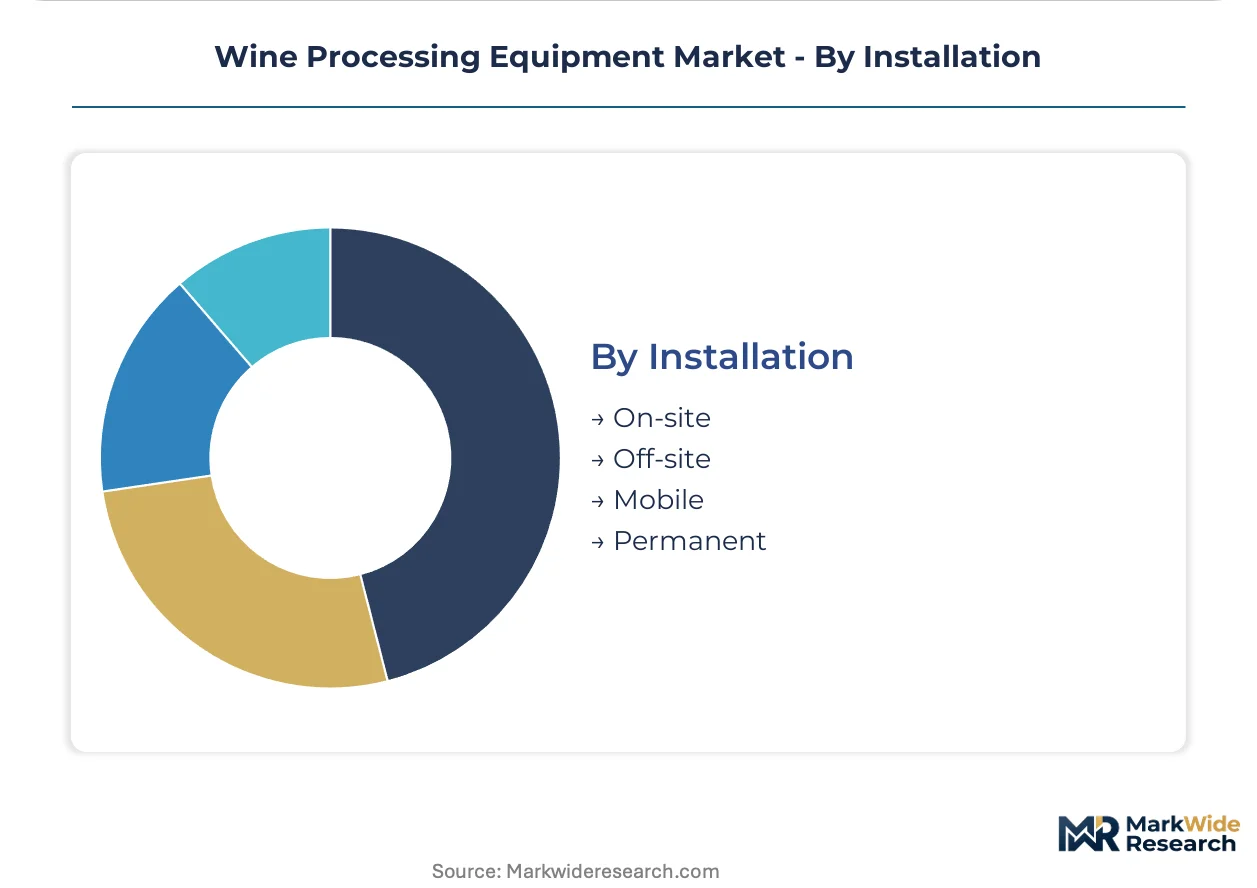
Installation:
Mobility and permanence trade-offs reflect capital efficiency priorities and regulatory permanence requirements.
- On-site:Fixed cellar installations dominate premium estate construction in Tuscany and Napa Valley where temperature-controlled concrete foundations support stainless steel tank farms.
- Off-site:Contract processing facilities in Texas Hill Country and Virginia aggregate small-lot production for shared filtration and stabilization.
- Mobile:Trailer-mounted bottling lines and filtration units serve emerging regions without permanent infrastructure investment.
- Permanent:Integrated architectural systems with embedded glycol distribution and wastewater recovery predominate in new European facility construction subject to REACH and RoHS constraints.
Permanent installations lead on capital deployment; mobile configurations lead on geographic expansion flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy pioneered modern wine processing equipment during the post-war mechanization of Tuscan and Piedmont estates. France and Germany subsequently developed precision fermentation controls and thermal systems that shaped contemporary standards. Today equipment procurement concentrates in established winegrowing nations confronting regulatory transitions and climate adaptation pressures.
Italy
Tuscan estates drive replacement demand for pneumatic presses with integrated cooling as EU F-Gas Regulation phase-downs accelerate. ANSM certification requirements govern refrigerant transitions in cold stabilization equipment. Producers around Florence and Siena retrofit temperature-controlled fermenters to maintain Brunello and Chianti Classico export eligibility under tightening carbon documentation rules.
United States
Napa Valley and Sonoma County estate wineries specify glycol-jacketed stainless steel tanks with automated cap management systems. FDA Current Good Manufacturing Practice standards shape sanitary design specifications for export-bound facilities. Central Valley bulk producers deploy cross-flow filtration rated at 0.45 micron retention to meet water recovery mandates under California agricultural efficiency programs.
Germany
Pfalz and Mosel producers confront compressed harvest windows from vintage variability, driving demand for rapid cold stabilization systems. ECHA REACH constraints on stainless steel alloy compositions extend lead times for tank fabricators serving the domestic market. Rheinhessen cooperatives retrofit propane-based heat pumps ahead of 2030 HFC prohibition deadlines under EU F-Gas Regulation schedules.
Australia
Riverina and Riverland export facilities scale automated fermentation capacity to meet Asian market volume commitments. TGA-aligned Food Standards Code provisions govern labeling and sanitary compliance for equipment procurement decisions. South Australian estates in Barossa and McLaren Vale specify mobile bottling units for harvest flexibility amid labor scarcity.
France
Bordeaux châteaux and Burgundy domaines prioritize block-level fermentation precision for single-vineyard bottlings. ANSM and CNIL oversight extends to data-enabled fermentation monitoring systems under GDPR-aligned privacy frameworks. Champagne houses in Reims and Épernay retrofit energy recovery systems to satisfy CSRD carbon disclosure requirements for luxury goods exporters.
Wine Processing Equipment Market Competitive Landscape
Capital-heavy stainless steel fabricators compete with asset-light system integrators across distinct value chain positions. The vendor base organizes around three strategic archetypes: integrated fermentation tank manufacturers with captive foundry capacity, precision harvesting technology specialists, and modular system architects serving boutique scale-ups. Consolidation pressure concentrates among mid-scale European fabricators confronting REACH alloy constraints and extended CE marking timelines. Geographic expansion into emerging wine regions and backward integration into control system development represent dominant competitive vectors.
Within the integrated manufacturing tier, Criveller Group and Paul Mueller Company anchor positions through North American and European fabrication footprints respectively. Pellenc Group exemplifies the precision agriculture-to-cellar convergence archetype. Deutsche Beverage Technology occupies the modular architecture position serving capacity-constrained boutique producers. Agrovin and Boema S.p.A. represent Mediterranean-origin specialists with established service networks across Italian and Spanish winegrowing regions.
| Leading Market Players |
|---|
| Criveller Group |
| Agrovin |
| Della Toffola Pacific |
| DT Pacific Pty Ltd |
| GW Kent Inc |
| Paul Mueller Company |
| Deutsche Beverage Technology |
| Boema S.p.A. |
| Pellenc Group |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap fabricators across Italy and Germany anchor supply-side discipline through multi-generational customer relationships and captive foundry investments. Their ownership structure resists quarterly margin pressure, sustaining premium pricing for CE-certified stainless steel tanks while passing REACH alloy cost volatility through to estate winery buyers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the equipment landscape. Premium tiers capture certification grade differentiation through EU F-Gas Regulation compliance and ANSM refrigerant documentation, while standard tiers compete on volume scale for Riverina export facilities. Cost compression in economy-tier pneumatic presses is intensifying because Chinese stainless steel imports erode European fabricator margins. Boutique wineries in Oregon and Virginia exhibit highest price sensitivity, deferring automation investments; Champagne houses show least sensitivity, prioritizing energy recovery documentation for CSRD disclosure.
Supply Chain Analysis
CE marking and REACH alloy qualification gating extends lead times for European market entry, compressing procurement flexibility. Stainless steel supply concentrates in Italy, Germany, and China, with nickel and chromium sourcing drawing from Indonesian and South African concentrate markets. Single-source vulnerability runs through specialized membrane suppliers for cross-flow filtration units. Distribution runs through regional service networks capable of guaranteed uptime performance rather than equipment financiers, concentrating vendor relationships with captive maintenance providers in Napa Valley and Barossa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU F-Gas Regulation phase-downs and carbon border adjustment documentation create replacement demand independent of vintage economics.
For Market Incumbents: Deploy service network densification as the primary defensive lever. Criveller Group and Paul Mueller Company should expand captive maintenance capabilities in South Australia and Northern California to counter emerging modular system architects threatening boutique winery relationships. Capacity addition in Texas Hill Country and Virginia AVA clusters captures contract processing growth before regional fabricators establish local presence. For New Entrants and Emerging Players: Enter via mobile equipment-as-a-service contracting for emerging wine regions lacking permanent infrastructure. Trailer-mounted filtration and stabilization units address white-space demand in Texas Hill Country and Virginia where capital-constrained producers seek harvest flexibility without full line investment. Partner with regional custom crush facilities to establish service credibility before scaling to permanent installations. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale European fabricators confronting extended CE marking timelines and REACH alloy constraints. Long-term viability over a five-to-ten year window favors specialists with backward integration into control system development and established regional service networks. Watch EU carbon border adjustment implementation timing as the inflection signal determining export eligibility premium capture for compliant equipment suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Refrigerant Compliance Retrofit Program | EU F-Gas Regulation phase-downs mandate propane-based heat pump adoption across German and Italian wineries. |
| Mobile Equipment-as-a-Service Launch | Trailer-mounted bottling lines address contract processing demand in Texas Hill Country and Virginia AVA clusters. |
| Control System Backward Integration | In-house IoT-enabled fermentation monitoring development reduces boutique winery automation integration complexity. |
| Regional Service Network Expansion | Captive maintenance capabilities in Napa Valley and Barossa defend incumbent positions against modular competitors. |
| Carbon Documentation Certification Investment | EU Green Deal compliance documentation capabilities become procurement gate for Chilean and Argentine export facilities. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged equipment procurement managers at commercial wineries, technical directors at boutique estates, aftermarket service heads at regional fabricators, and regulatory compliance officers navigating EU F-Gas and REACH constraints. Secondary validation drew from ECHA substance restriction databases, CE marking notification records, Australian TGA Food Standards Code provisions, and customs trade data for stainless steel alloy shipments. Bottom-up equipment shipment tallies and top-down winery capital expenditure surveys were cross-referenced for triangulation.
Segment-weighting approaches modeled fermentation equipment, pressing systems, filtration units, and stabilization technology across the projection horizon. Technology tiers differentiated precision-controlled estate workflows from high-volume commodity production. End-user segmentation captured commercial winery export compliance requirements, boutique estate modularity preferences, and vineyard mobile equipment demand. CAGRs were derived from vintage volume projections, regulatory replacement cycle acceleration, and climate-driven sugar accumulation patterns affecting alcohol adjustment system demand.
Inputs from primary stakeholder interviews and secondary regulatory databases were available through the study window; gaps in real-time winery capital expenditure disclosure introduce uncertainty bands around quarterly equipment shipment estimates. Forecasts reflect assumptions regarding EU F-Gas phase-down adherence schedules and carbon border adjustment implementation scope. A model refresh is warranted upon material change in EU Green Deal documentation requirements or REACH alloy restriction amendments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Ice Cream Processing Equipment Market
Food Processing Equipment
Steam Blanching Equipment Market
Food Processing Equipment
Fish Filleting Machine Market
Food Processing Equipment
Food Processor Market
Food Processing Equipment
Global Food Sterilization Machines Market
Food Processing Equipment
Freeze-Drying Equipment Market
Food Processing Equipment
Global Fermenters Market
Food Processing Equipment
Craft Brewery Equipment Market
Food Processing Equipment
US Cold Storage Market
Food Processing Equipment
Beer Brewing Equipment Market
Food Processing Equipment
North America Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Griddle Market
Food Processing Equipment
Asia-Pacific Walk-In Refrigerators and Freezers Market
Food Processing Equipment
Global Food and Beverage Coding and Marking Equipment Market
Food Processing Equipment
UHT Systems Market
Food Processing Equipment
Sheet Metal Processing Equipment Market