
 Fish Filleting Machine Market | 2026-2036
Fish Filleting Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Fish Filleting Machine Market Foresight
CE-marked stainless-steel construction with IP69K washdown ratings is unwinding older mild-steel equipment across European and North American processing floors. BAADER Global leverages captive engineering centers in Germany and Denmark to sustain high-throughput salmon and whitefish configurations. Marel differentiates through software-integrated yield optimization that positions its lines in premium whitefish operations. PERUZA anchors mid-scale installations across the Iberian Peninsula with compact footprint designs.
A fish filleting machine automates the separation of flesh from frame using reciprocating blade arrays, vacuum hold-down conveyors, and computer-vision guidance, typically processing 20 to 120 fish per minute depending on species and machine class. Automatic filleting machines capture the dominant share of capital expenditure as labor-scarce regions force mechanization, while robotic arm integration represents the fastest-expanding technology tier as vision-guided end-effectors reduce yield loss on variable-sized catch. Laser-guided systems and ultrasonic filleting carve out niche positions in high-value species processing where precision commands price premiums.
EFSA hygiene mandates and the EU Green Deal's water-efficiency benchmarks compel equipment redesigns toward closed-loop cleaning and energy recovery, while FDA HACCP compliance in the United States shapes blade-sanitization protocols and traceability interfaces. ISO 14155 machinery safety standards and CE marking requirements under the EU Machinery Directive govern market access across European Economic Area states. Buyers must weigh total cost of ownership against yield recovery gains as automation depth diverges between commodity and premium processing tiers.
Market Dynamics
Labor scarcity across seafood processing corridors is forcing capital substitution faster than depreciation cycles, compressing payback thresholds from seven years toward four as wage inflation outpaces equipment financing costs.
Growth Catalysts
- EU Green Deal water-efficiency mandates:Closed-loop recirculation systems earn preferential financing terms through green transition funds, accelerating replacement of once-through cooling designs in North Sea processing plants.
- Pangasius export consolidation in Vietnam:Mekong Delta processors are standardizing on automatic filleting lines to meet EU import traceability requirements and reduce per-kilogram labor exposure.
- Computer-vision yield optimization:Real-time blade-path adjustment based on fish morphology is recovering two to four percentage points of sellable meat, justifying premium machine classes in whitefish operations.
Market Restraints
- Stainless steel alloy volatility:Grade 316L price swings distort total cost of ownership calculations and delay procurement approvals at mid-scale processors.
- CE marking complexity:Machinery Directive conformity assessment timelines stretch twelve to eighteen months, freezing smaller vendors out of European Economic Area tenders.
- Manual filleting persistence:Artisanal processors serving domestic fresh markets in Southern Europe and coastal Latin America resist mechanization where hand-cut presentation commands price premiums.
Strategic Opportunities
- Indonesian archipelago expansion:Cold chain infrastructure investments in Sulawesi and Papua are creating first-mover openings for compact, containerized filleting units on remote landing sites.
- FDA HACCP digital integration:Blade-sanitization logging and lot-traceability modules that auto-populate compliance dashboards are commanding attach-rate premiums in US catfish and tilapia plants.
- Robotic arm convergence with ultrasonic sensing:Hybrid systems combining vision-guided end-effectors with bone-detection feedback are penetrating high-value tuna and swordfish processing where precision justifies capital intensity.
Industry Challenges
- Mechatronics technician scarcity:Maintenance of servo-driven blade arrays and vacuum conveyor systems requires skills absent in traditional fish-plant workforces, extending downtime during failures.
- Legacy line integration friction:Brownfield installations face control-protocol mismatches between new filleting heads and existing grading and packing equipment, inflating commissioning costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fish Filleting Machine Market |
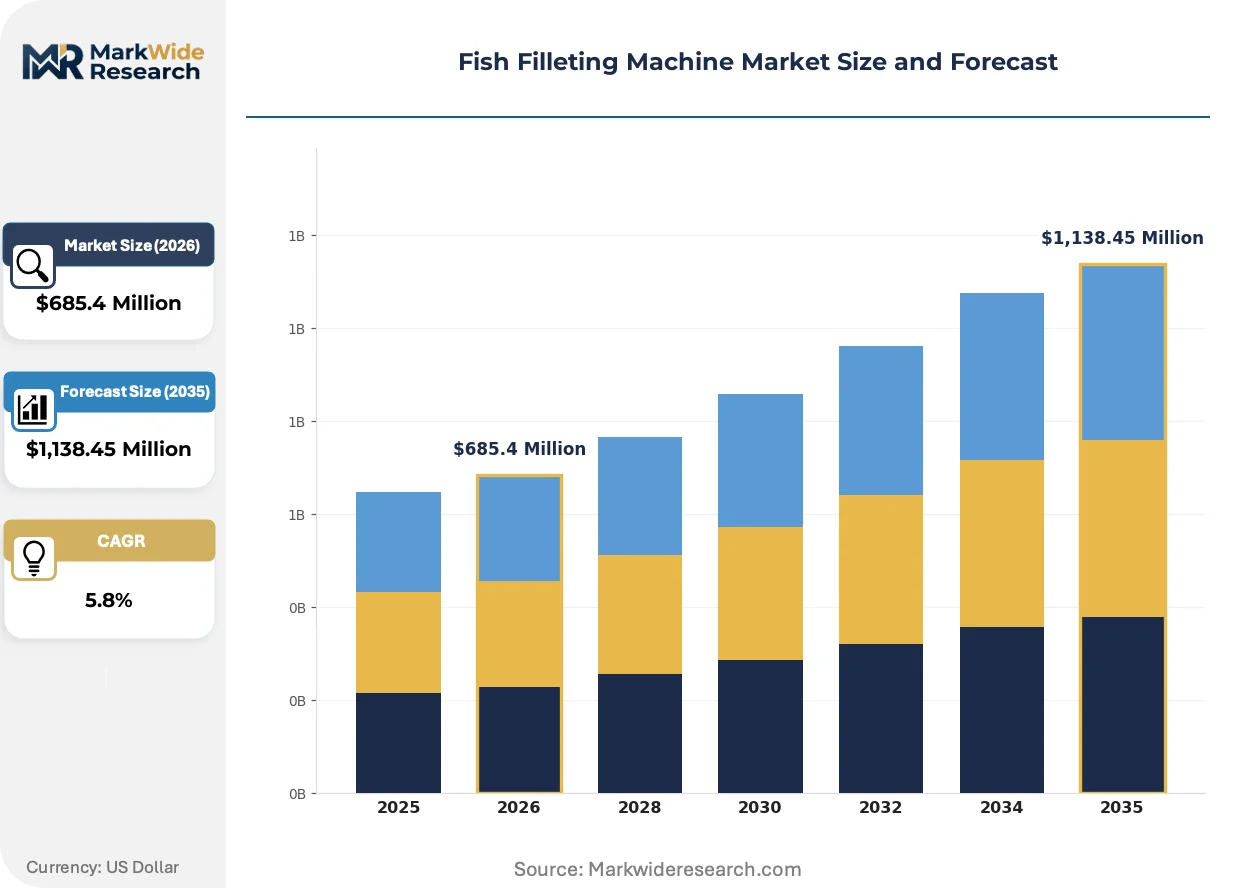
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,138.45 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automatic Filleting Machines, Semi-automatic Filleting Machines, Manual Filleting Tools, Skinning Machines, Deboning Machines Technology: Laser-guided Systems, Ultrasonic Filleting, Hydraulic Automation, Pneumatic Filleting, Robotic Arm Integration Application: Seafood Processing Plants, Fish Markets, Food Service Operations, Aquaculture Facilities, Frozen Food Manufacturers End User: Fish Processors, Seafood Wholesalers, Catering Companies, Marine Product Exporters, Retail Fishmongers |
| Companies Covered | Zhang Jiang Hongwu Machinery Co, Carnitec, Ingeniería de Proyectos Marinos, S.L., BAADER Global, Marel, PERUZA, Shining Fish Technology Ltd., Norbech A/S, Kroma, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fish Filleting Machine Market Shifts & Advancements
Equipment architecture is bifurcating between throughput-maximized lines for commodity species and precision-configured systems for high-value catch, with software-defined yield management becoming the primary differentiation axis.
Ultrasonic bone-detection arrays are displacing mechanical probe systems in premium whitefish processing, with North Atlantic cod and haddock operators adopting the technology to reduce pin-bone remnants below detection thresholds. The shift is compressing demand for secondary hand-trimming labor and repositioning quality premiums toward automation depth rather than manual skill.
EFSA hygiene mandates under the EU Food Information for Consumers Regulation are forcing redesigns of blade-housing geometries and clean-in-place nozzle placement to eliminate biofilm accumulation zones. Salmon processors in Scotland and Norway are absorbing the compliance costs fastest, while Mediterranean sea-bass and sea-bream plants lag in retrofit scheduling.
Service unbundling is separating hardware procurement from software subscriptions and predictive maintenance contracts, with buyers in the Pacific Northwest and British Columbia negotiating multi-year uptime guarantees rather than capital purchases. The shift concentrates vendor risk in operational performance rather than equipment durability, favoring suppliers with captive service networks over pure manufacturers.
Fish Filleting Machine Market Segmentation
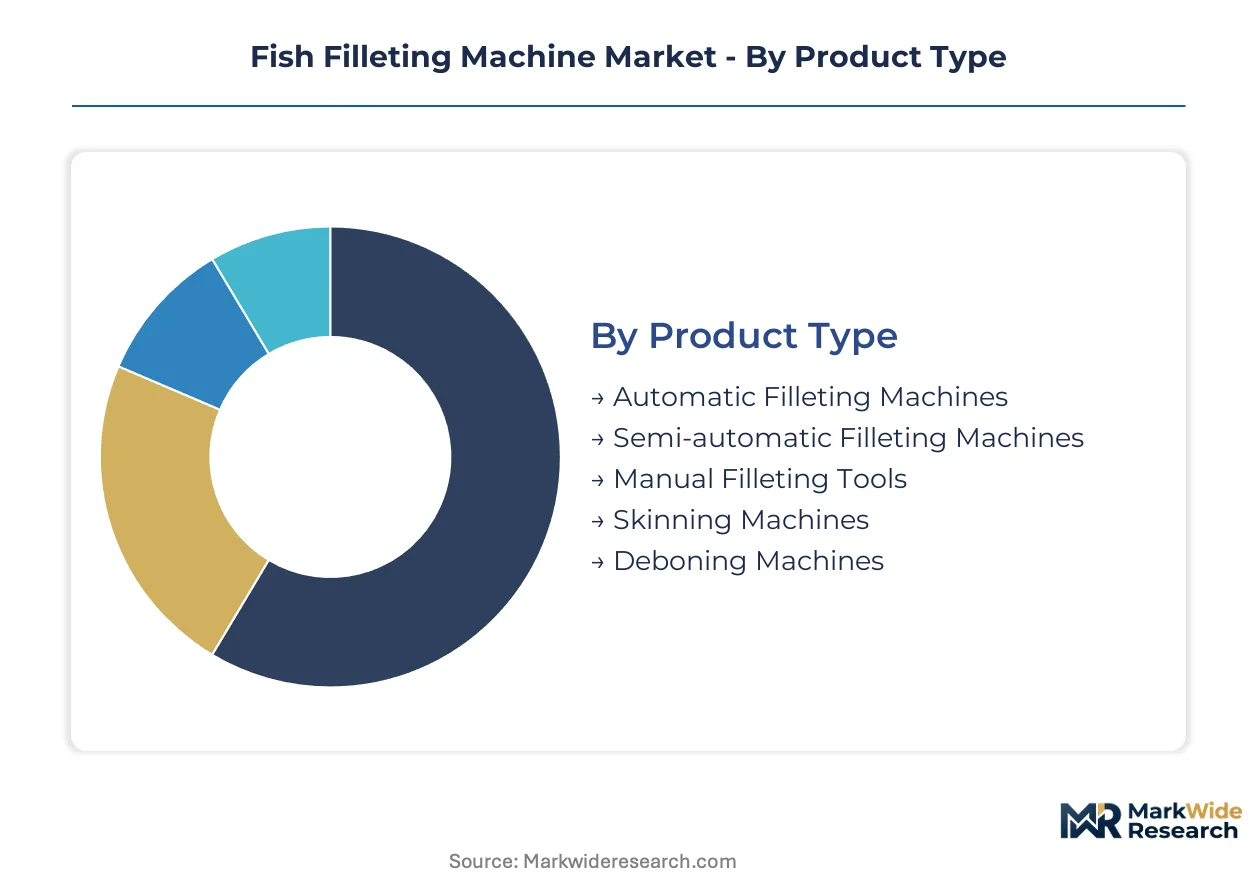
Segmentation in fish filleting equipment reveals how automation depth, precision technology, and end-use economics allocate capital across processing tiers. Buyers face divergent payback calculations depending on species value, labor availability, and regulatory exposure in their operating geographies.
Product Type:
Substitution pressure from manual filleting persists strongest in segments where hand-cut presentation commands price premiums, forcing equipment vendors to demonstrate yield recovery and labor cost arbitrage more aggressively.
- Automatic Filleting Machines:Reciprocating blade arrays with vacuum hold-down conveyors process 20 to 120 fish per minute, with computer-vision guidance adjusting cut paths to morphology. Demand concentrates in Vietnam's Mekong Delta pangasius cluster as exporters standardize lines to meet EU traceability mandates and compress per-kilogram labor exposure.
- Semi-automatic Filleting Machines:Hybrid stations combine powered blade drives with manual fish positioning, occupying the mid-scale tier where capital constraints delay full automation. Iberian Peninsula processors favor compact footprint designs from PERUZA for sea-bass and sea-bream operations where throughput requirements fall below salmon-scale lines.
- Manual Filleting Tools:Hand-held knives and cutting boards persist in artisanal Southern European and coastal Latin American markets where fresh domestic presentation sustains price premiums over mechanized cuts.
- Skinning Machines:Rotary blade or drum-based systems separate skin from fillet post-primary processing, with adoption concentrated in whitefish operations seeking to eliminate secondary hand labor.
- Deboning Machines:Pin-bone removal systems using water-jet or mechanical probe arrays target premium species where bone remnant thresholds determine quality grades and export eligibility.
Automatic Filleting Machines retain volume leadership; Robotic Arm Integration holds the steepest expansion curve as vision-guided end-effectors reduce yield loss on variable-sized catch.
Technology:
Cost tier stratification separates commodity processors deploying proven hydraulic and pneumatic systems from premium operators absorbing precision technology premiums for yield recovery gains.
- Laser-guided Systems:Optical triangulation maps fish contours in real-time, enabling sub-millimeter blade positioning for high-value species where precision commands price premiums. North Atlantic cod and haddock operators adopt these configurations to reduce pin-bone remnants below detection thresholds and eliminate secondary hand-trimming labor.
- Ultrasonic Filleting:High-frequency acoustic arrays detect bone density variations, guiding blade paths around skeletal structures invisible to optical systems. Scottish and Norwegian salmon processors absorb compliance costs fastest under EFSA hygiene mandates that favor closed-loop cleaning designs compatible with ultrasonic transducer housings.
- Hydraulic Automation:Fluid-power actuation drives blade reciprocation in high-throughput lines for commodity species, with mature supply chains and technician familiarity sustaining installed base longevity.
- Pneumatic Filleting:Compressed-air systems occupy the economy tier where lower capital outlays offset reduced precision, prevalent in emerging market installations with constrained financing access.
- Robotic Arm Integration:Six-axis manipulators with vision-guided end-effectors adapt to irregular catch dimensions, representing the convergence point of automation depth and flexibility for mixed-species operations.
Hydraulic Automation maintains the largest installed base; Ultrasonic Filleting is climbing the fastest as bone-detection precision repositions quality premiums toward automation depth rather than manual skill.
Application:
Customer type divergence allocates equipment sophistication across integrated processing plants versus distributed retail and foodservice endpoints with divergent throughput and precision requirements.
- Seafood Processing Plants:Large-scale facilities with dedicated species lines drive capital intensity, with Vietnam's pangasius exporters and North Sea whitefish operators standardizing on automatic configurations to meet EFSA and FDA HACCP compliance burdens.
- Fish Markets:Distributed retail environments favor compact semi-automatic or manual stations where fresh presentation and species variety preclude dedicated high-speed lines.
- Food Service Operations:Central kitchens and restaurant chains with consistent species procurement adopt mid-scale automatic units to reduce labor dependency and portion variability.
- Aquaculture Facilities:Integrated grow-out and processing operations in Norway, Scotland, and British Columbia specify equipment with software-integrated yield optimization and predictive maintenance contracts.
- Frozen Food Manufacturers:Block-frozen and individually quick-frozen processors prioritize throughput-maximized lines with minimal changeover capability for commodity whitefish and tilapia.
Seafood Processing Plants dominate capital deployment; Aquaculture Facilities are gaining share fastest as integrated operations consolidate filleting capacity at grow-out sites.
End User:
Margin structure across the value chain determines equipment sophistication, with exporters and integrated processors capturing yield recovery premiums unavailable to fragmented retail operators.
- Fish Processors:Primary filleting operations with direct species contracts invest deepest in automation, with BAADER Global and Marel positioning yield-optimization software in premium whitefish and salmon configurations.
- Seafood Wholesalers:Intermediate handlers with mixed species intake favor flexible semi-automatic systems accommodating batch variability without dedicated line changeovers.
- Catering Companies:Contract foodservice providers with predictable volume requirements adopt compact automatic units for labor cost reduction in institutional meal preparation.
- Marine Product Exporters:EU-bound Vietnamese pangasius and Indonesian tuna operators specify CE-marked stainless-steel construction with IP69K washdown ratings and digital traceability interfaces to satisfy import compliance.
- Retail Fishmongers:Independent counter operators persist with manual filleting where customer-visible skill sustains price premiums and species variety exceeds automated line flexibility.
Fish Processors anchor equipment demand; Marine Product Exporters are expanding fastest as traceability mandates and green transition financing accelerate replacement cycles in export-oriented installations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import imbalances reshape equipment procurement geography. Net seafood exporters invest in automation to maintain price competitiveness, while import-dependent markets prioritize yield recovery to offset raw material costs. Processing clusters concentrate where cold chain infrastructure intersects with species-specific landing volumes.
Vietnam
Mekong Delta pangasius exporters drive replacement cycles as EU traceability mandates tighten. The Ministry of Agriculture and Rural Development's seafood export promotion programs subsidize automation upgrades. Processing corridors around Cần Thơ and An Giang standardize on automatic filleting lines to reduce per-kilogram labor exposure.
Norway
Integrated salmon producers consolidate filleting capacity at grow-out sites to capture vertical margin. EFSA hygiene mandates under the EU Green Deal accelerate closed-loop equipment adoption. Facilities from Bergen to Tromsø absorb compliance costs fastest, absorbing redesigns for water-recirculating systems.
United States
Catfish and tilapia processors in the Mississippi Delta and Texas face FDA HACCP compliance burdens for blade-sanitization logging. USDA aquaculture programs channel financing toward traceability-integrated equipment. Arkansas and Alabama processing plants negotiate digital compliance modules as attach-rate premiums.
Germany
CE marking complexity under the EU Machinery Directive stretches conformity timelines, freezing smaller vendors out of tenders. The country's national food safety regulator enforces strict hygiene protocols for North Sea whitefish operations. Processing centers in Bremerhaven and Cuxhaven upgrade stainless-steel infrastructure to IP69K washdown ratings.
Indonesia
Cold chain investments in Sulawesi and Papua create first-mover openings for containerized filleting units. The national maritime fisheries ministry's infrastructure programs target remote landing sites. Bitung and Sorong processing zones adopt compact equipment configurations where technician scarcity constrains maintenance capabilities.
Fish Filleting Machine Market Competitive Landscape
Listed leaders compete with private specialists across automation depth and service bundling. Market structure bifurcates between scale-driven throughput maximizers and precision-configured yield optimizers. Three archetypes dominate: captive-engineering multinationals with integrated software platforms, regional footprint specialists serving mid-scale processors, and emerging-market fabricators competing on capital outlay. Competitive moves concentrate on predictive maintenance contracting and geographic service network expansion.
Within the captive-engineering tier, BAADER Global and Marel exemplify integrated platform providers. PERUZA occupies a position among compact-footprint specialists serving Iberian and Mediterranean processors. Zhang Jiang Hongwu Machinery Co represents emerging-market fabricators competing on equipment accessibility for cost-constrained installations. Shining Fish Technology Ltd. and Norbech A/S sit within the precision-technology segment where ultrasonic and vision-guided systems command premium positioning. Kroma and Carnitec anchor regional service networks across Northern European processing corridors.
| Leading Market Players |
|---|
| Zhang Jiang Hongwu Machinery Co |
| Carnitec |
| Ingeniería de Proyectos Marinos, S.L. |
| BAADER Global |
| Marel |
| PERUZA |
| Shining Fish Technology Ltd. |
| Norbech A/S |
| Kroma |
| Others |
Supply & Pricing Matrix
CE marking requirements under the EU Machinery Directive gate both supplier qualification timelines and price differentiation across equipment tiers, compressing margins for uncertified fabricators while embedding compliance premiums into stainless-steel configurations destined for European Economic Area tenders.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with CE-certified stainless-steel systems commanding attach-rate premiums for IP69K washdown ratings and FDA HACCP digital interfaces. Price differentiation hinges on certification grade and software-integrated yield optimization depth, with BAADER Global and Marel extracting brand premiums for predictive maintenance contracts. Cost compression in the economy tier intensifies as Indonesian and Vietnamese fabricators compete on capital outlay, while aquaculture facilities in Norway and British Columbia demonstrate lowest price sensitivity due to uptime guarantee negotiations.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for servo drives and precision blade arrays sourced from German and Danish engineering centers. Manufacturing concentrates in Germany, Denmark, and China, with Grade 316L stainless steel and computer-vision sensors anchoring raw material dependencies. Single-source vulnerability in ultrasonic transducer supply creates exposure for premium whitefish configurations. Distribution runs through captive service networks for predictive maintenance bundling, favoring vendors with regional technician presence over pure equipment manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where CE marking complexity and multi-year service contracts create switching costs that freeze smaller vendors out of European tenders and concentrate buyer relationships with integrated platform providers.
For Market Incumbents: Fortify captive service networks across Southeast Asian processing corridors before emerging-market fabricators close the technician-scarcity gap. Deepen backward integration into ultrasonic sensor supply to offset single-source vulnerability in bone-detection arrays. Absorb EFSA hygiene mandate redesign costs fastest to reposition mild-steel competitors as compliance laggards. For New Entrants and Emerging Players: Anchor in Indonesian archipelago cold chain investments where containerized compact units address technician scarcity at remote Sulawesi and Papua landing sites. Target mid-scale Iberian sea-bass and sea-bream processors with footprint-optimized semi-automatic stations below PERUZA's configuration floor. Lead with FDA HACCP digital compliance modules as attach-rate differentiators in US catfish and tilapia tenders. For Investors and Strategic Acquirers: EU Green Deal water-efficiency mandate implementation reshapes the acquisition landscape toward closed-loop recirculation specialists with green transition fund eligibility. Long-term viability favors precision-technology vendors where ultrasonic and vision-guided systems reposition quality premiums toward automation depth. Monitor stainless-steel alloy price volatility as the inflection signal for distressed mid-scale processor procurement delays.| Strategic Initiative | Industry Significance |
|---|---|
| Predictive Maintenance Contracting | Concentrates vendor risk in operational performance rather than equipment durability for British Columbia salmon operators. |
| Backward Integration into Ultrasonic Sensors | Reduces single-source vulnerability for bone-detection arrays in North Atlantic cod and haddock configurations. |
| CE Marking Fast-Track Investment | Compresses twelve-to-eighteen-month conformity timelines to capture frozen-out smaller vendor share in German tenders. |
| Containerized Compact Unit Development | Addresses technician scarcity constraints at remote Indonesian landing sites in Sulawesi and Papua. |
| Software Subscription Unbundling | Separates hardware procurement from yield-optimization algorithms for Pacific Northwest aquaculture facilities. |
Research Methodology
Initial hypotheses were tested against primary input from seafood processing plant managers, OEM procurement teams, aftermarket service heads, and regulatory compliance officers across Vietnam, Norway, and the United States, and refined through secondary validation against EU Machinery Directive filings, EFSA hygiene guidance documents, FDA HACCP enforcement records, and customs trade data for stainless-steel equipment imports. Bottom-up installation counts across Mekong Delta pangasius corridors and North Sea whitefish clusters were triangulated with top-down capital expenditure flows from aquaculture integration announcements.
Variance decomposition across the projection horizon isolates equipment replacement cycles, regulatory compliance deadlines, and labor cost inflation as distinct growth drivers. Segmentation dimensions span automation depth, precision technology tier, species-specific application, and end-user margin structure. CAGRs were derived from installed base growth rates adjusted for yield recovery premiums and green transition financing availability. Industry-specific inputs include pangasius export consolidation timelines and EFSA hygiene mandate implementation schedules across Scottish and Norwegian salmon facilities.
Material uncertainties — stainless-steel alloy price volatility, CE marking timeline extensions, and mechatronics technician availability — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding labor scarcity persistence and regulatory enforcement intensity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Processing Equipment
Coconut Crushers Market
Food Processing Equipment
Food Extrusion Market
Food Processing Equipment
Freezers Market
Food Processing Equipment
Food Slicer and Dicer Market
Food Processing Equipment
Pizza Scissors Market
Food Processing Equipment
Food Waste Composting Machine Market
Food Processing Equipment
Hand Blender Market
Food Processing Equipment
Global Nutating Mixers Market
Food Processing Equipment
Global Shawarma Machines Market
Food Processing Equipment
Ice Maker Machines Market
Food Processing Equipment
Dehydrators Market
Food Processing Equipment
Edible Oil Extracting Machine Market
Food Processing Equipment
Global Conveyor Oven Market
Food Processing Equipment
Asia-Pacific Commercial Sous Vide Machine Market
Food Processing Equipment
North America Commercial Sous Vide Machine Market
Food Processing Equipment
Dual-Ovenable Cook Trays Market