
 Global Location-Based Virtual Reality Market | 2026-2036
Global Location-Based Virtual Reality Market Size, Share, and Industry Trends Forecast 2026-2036
Global Location-Based Virtual Reality Market Foresight
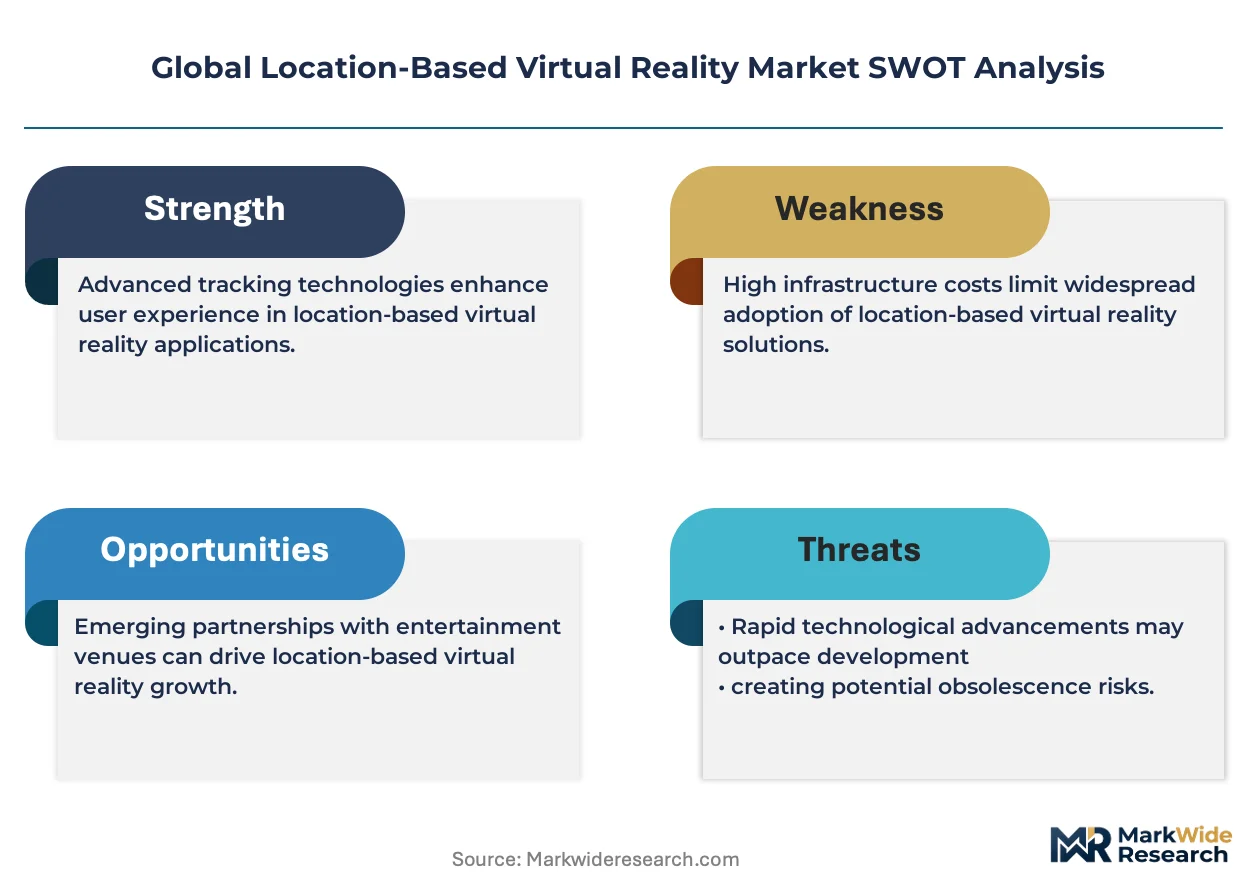
The capital-intensity divergence between warehouse-scale free-roam operators and compact kiosk deployers is redrawing competitive boundaries in location-based VR. Sandbox VR sustains premium positioning through proprietary motion-tracking arenas in high-rent urban districts. Hologate GmbH competes with modular turnkey systems that slash venue retrofit costs for mid-sized entertainment operators. Zero Latency Pty Ltd anchors the free-roam segment with multi-player wireless installations across Australia, the United States, and Europe.
Location-based virtual reality denotes commercial installations where untethered or station-based VR hardware enables group experiences outside residential settings, typically employing sub-20ms motion-to-photon latency thresholds and positional tracking across 100-500 square meter volumes to prevent simulator sickness. The technology serves entertainment venues, corporate training campuses, and museum exhibitors seeking differentiated foot traffic or risk-free simulation environments. Hardware Type segments show VR headsets and haptic devices capturing the bulk of equipment spend, while motion trackers represent the fastest-growing component as free-roam venues proliferate. Application demand tilts toward entertainment centers, though simulation training for aviation and healthcare is deepening margin pools through multi-year enterprise contracts.
FDA guidance on VR exposure limits for pediatric users, FCC rules on wireless spectrum allocation for untethered headsets, and China's GB standards for electromagnetic compatibility shape product design cycles and venue liability frameworks across major markets. The EU AI Act's risk-classification provisions for biometric tracking in immersive environments will influence European operator compliance costs. Stakeholders must weigh hardware standardization bets against platform-fragmentation risks as console-connected and cloud-based architectures diverge in latency performance.
Market Dynamics
The capital-intensity divergence between warehouse-scale free-roam operators and compact kiosk deployers is redrawing competitive boundaries in location-based VR, compressing mid-tier venue economics while premium and budget tiers expand.
Growth Catalysts
- MIIT Hardware Standards:China's interoperability mandates accelerate domestic equipment certification cycles, reducing time-to-market for headset manufacturers targeting commercial venues.
- Experiential Leisure Spending:North American entertainment centers convert vacant retail space into VR arenas as landlords prioritize foot-traffic generators over traditional tenants.
- Wireless Tracking Arrays:Sub-20ms motion-to-photon latency thresholds enable untethered multiplayer arenas, eliminating cable management costs and expanding playable volumes.
Market Restraints
- High-Rent Urban Real Estate:Premium positioning in city centers requires sustained throughput above 200 sessions weekly to cover occupancy costs, filtering out smaller operators.
- Motion Sickness Susceptibility:Latency spikes above 20 milliseconds trigger simulator sickness in 15-30% of users, capping session lengths and repeat visitation rates.
- Console Platform Fragmentation:Divergent architectures between tethered PC-VR and cloud-streaming headsets force venue operators to place incompatible standardization bets.
Strategic Opportunities
- Aviation Simulation Contracts:Enterprise training campuses seek multi-year agreements for risk-free pilot certification environments, deepening margin pools beyond entertainment.
- Healthcare Rehabilitation Protocols:FDA-cleared VR exposure therapies for pediatric anxiety and physical therapy create reimbursable service lines for hospital outpatient departments.
- Modular Turnkey Systems:Mid-sized entertainment operators adopt plug-and-play kiosk formats that slash retrofit timelines from months to weeks.
Industry Challenges
- Positional Tracking Calibration:Free-roam venues require daily recalibration of lighthouse and inside-out tracking arrays, consuming technical staff hours and disrupting operating schedules.
- Biometric Data Compliance:EU AI Act risk-classification provisions for eye-tracking and physiological monitoring impose documentation burdens on European operators deploying analytics.
- Content Licensing Fragmentation:Exclusive IP agreements between studios and hardware platforms restrict venue access to marquee franchises, forcing costly multi-platform subscriptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Location-Based Virtual Reality Market |
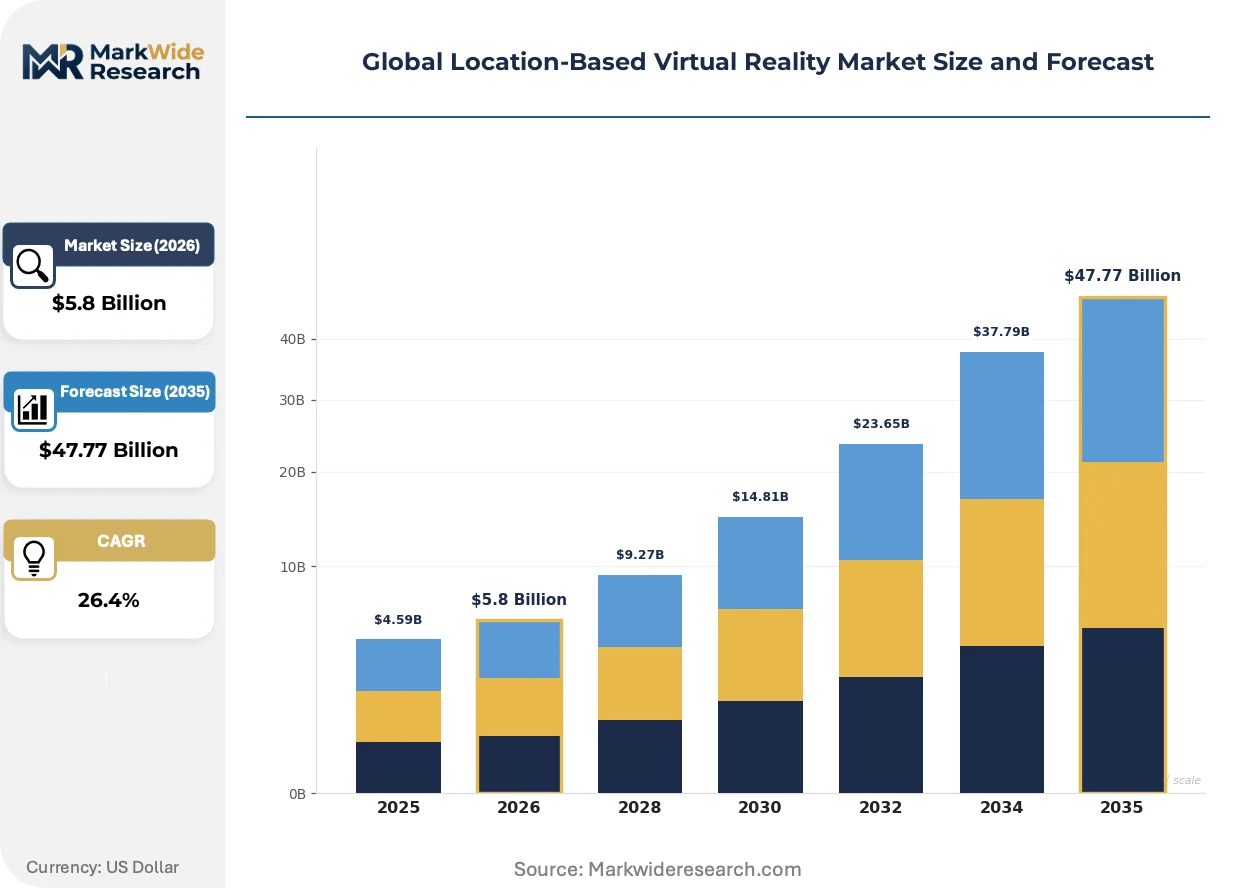
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $47.77 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Hardware Type: VR Headsets, Motion Trackers, Haptic Devices, Sensory Suits, Control Gloves Application: Entertainment Centers, Educational Institutions, Real Estate Visualization, Simulation Training, Tourism Experiences Platform Integration: Standalone Systems, PC-Connected, Console-Connected, Cloud-Based, Mobile-Tethered End User: Theme Parks, Training Facilities, Corporate Enterprises, Museums, Event Venues |
| Companies Covered | Zero Latency Pty Ltd, Sandbox VR, Hologate GmbH, Dreamscape Immersive Inc., The VOID LLC, EXIT VR GmbH, Survios Inc., VRstudios Inc., IMAX Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Location-Based Virtual Reality Market Shifts & Advancements
Immersive hardware architectures are splitting into two incompatible performance tiers, forcing venue operators to choose between premium fidelity and operational flexibility while regulatory frameworks crystallize around biometric data collection.
Inside-out tracking systems with embedded depth sensors are displacing external lighthouse installations in compact venues. Family entertainment centers in Japan and South Korea adopt these self-contained units to minimize technical staffing. The technology is bifurcating the install base: premium free-roam arenas retain sub-millimeter precision for competitive esports, while mid-market operators sacrifice accuracy for deployment speed.
EU AI Act provisions classifying biometric inference in immersive environments as high-risk systems impose conformity assessment obligations on headset manufacturers. European venue operators must maintain audit trails for eye-tracking data and physiological responses. Germany's KBA and France's CNIL have issued supplementary guidance on local data residency, compressing vendor compliance timelines.
Corporate training procurement now favors annual subscription models over perpetual hardware purchases. Aviation and healthcare campuses in the United States bundle content libraries with hardware refresh cycles, shifting vendor revenue from upfront equipment sales to recurring service fees. This restructuring concentrates buying power among enterprise procurement teams at the expense of independent venue operators.
Global Location-Based Virtual Reality Market Segmentation
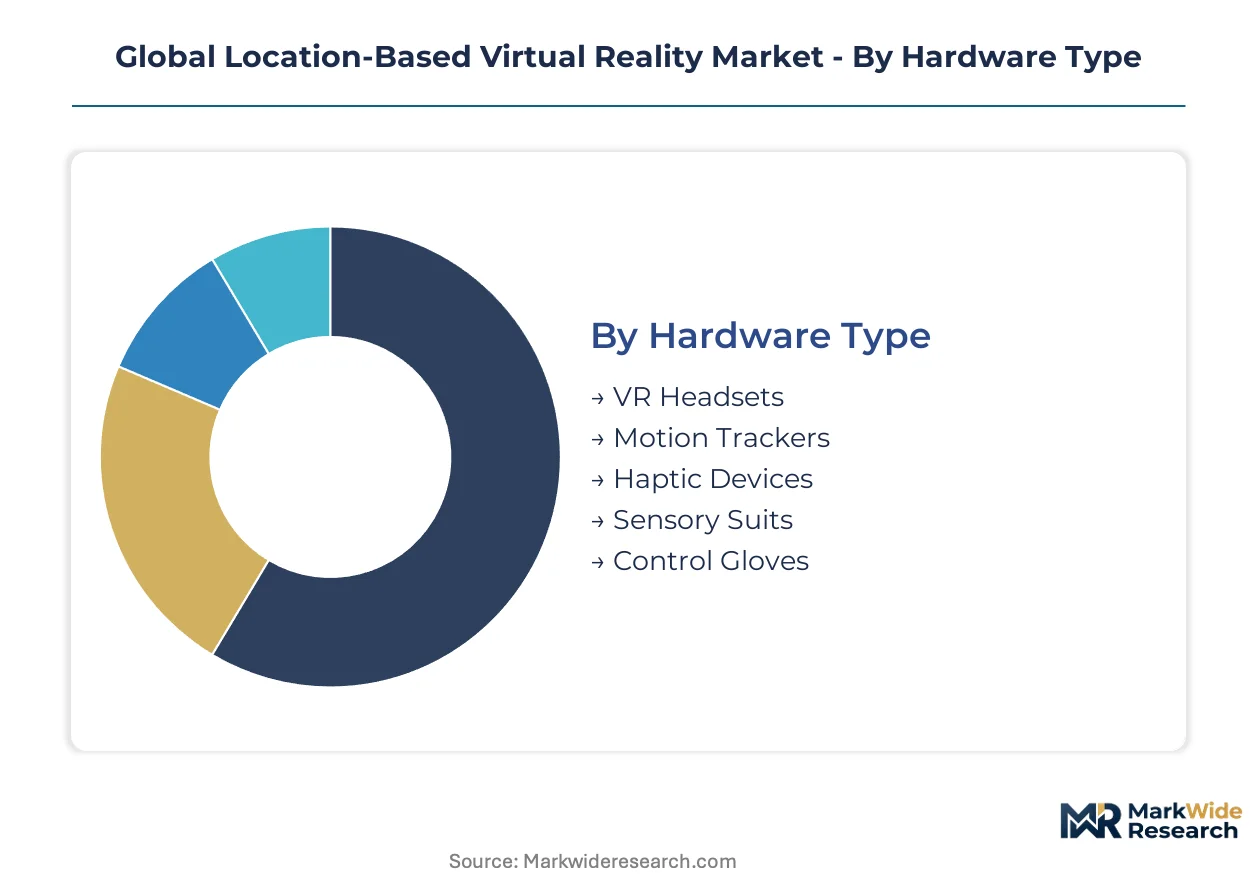
Segmentation in location-based VR reveals how venue economics fragment across hardware intensity, application risk profiles, and integration complexity. Operators must match capital deployment to specific throughput models and liability frameworks.
Hardware Type:
Substitution pressure from smartphone-based AR and mixed-reality headsets threatens low-immersion peripherals, while precision tracking arrays defend premium free-roam installations.
- VR Headsets:Display and optics modules delivering sub-20ms motion-to-photon latency through OLED or microLED panels. Demand concentrates in United States urban entertainment centers where Sandbox VR and Zero Latency anchor throughput-dependent business models requiring wireless fidelity.
- Motion Trackers:Lighthouse and inside-out camera arrays enabling positional accuracy across 100-500 square meter volumes. China's MIIT certification cycles accelerate domestic deployment in Shenzhen and Shanghai venues seeking rapid equipment turnover.
- Haptic Devices:Vibration and force-feedback peripherals enhancing tactile immersion without full-body coverage.
- Sensory Suits:Full-body haptic garments with thermal and pressure actuators for maximum immersion density.
- Control Gloves:Finger-tracking wearables enabling fine manipulation in simulation training environments.
VR Headsets retains volume leadership; Motion Trackers holds the steepest expansion curve.
Application:
Margin concentration diverges sharply between high-frequency entertainment traffic and long-cycle enterprise contracts with divergent payback periods.
- Entertainment Centers:Freestanding VR arenas and arcade installations prioritizing session throughput and repeat visitation. North American landlords in Chicago, Los Angeles, and Toronto retrofit vacant retail into these foot-traffic generators.
- Simulation Training:Risk-free environments for aviation, healthcare, and hazardous materials handling. Australia's Civil Aviation Safety Authority and Germany's KBA certify pilot training modules, deepening contract durations.
- Educational Institutions:Campus-based STEM and history immersion labs with grant-dependent procurement cycles.
- Real Estate Visualization:Pre-construction property walkthroughs for developers and brokers.
- Tourism Experiences:Heritage site reconstructions and destination preview installations at airports and visitor centers.
Entertainment Centers captures the highest transaction velocity; Simulation Training commands the longest contract tenures.
Platform Integration:
Architecture choices lock operators into incompatible content ecosystems with divergent latency guarantees and refresh cadences.
- Standalone Systems:Self-contained headsets with embedded processing eliminating external hardware dependencies. Japan's family entertainment centers in Osaka and Tokyo adopt these for minimal technical staffing.
- PC-Connected:Tethered configurations leveraging desktop GPU performance for premium fidelity. United States esports venues retain this architecture for competitive precision requirements.
- Console-Connected:PlayStation and Xbox-integrated systems with standardized content libraries.
- Cloud-Based:Streaming architectures reducing local hardware costs while demanding robust connectivity.
- Mobile-Tethered:Smartphone-dependent headsets offering lowest entry cost and portability.
PC-Connected defends the premium tier; Standalone Systems expands most quickly through Asia-Pacific deployment.
End User:
Procurement authority separates centralized enterprise buying from fragmented independent venue decision-making.
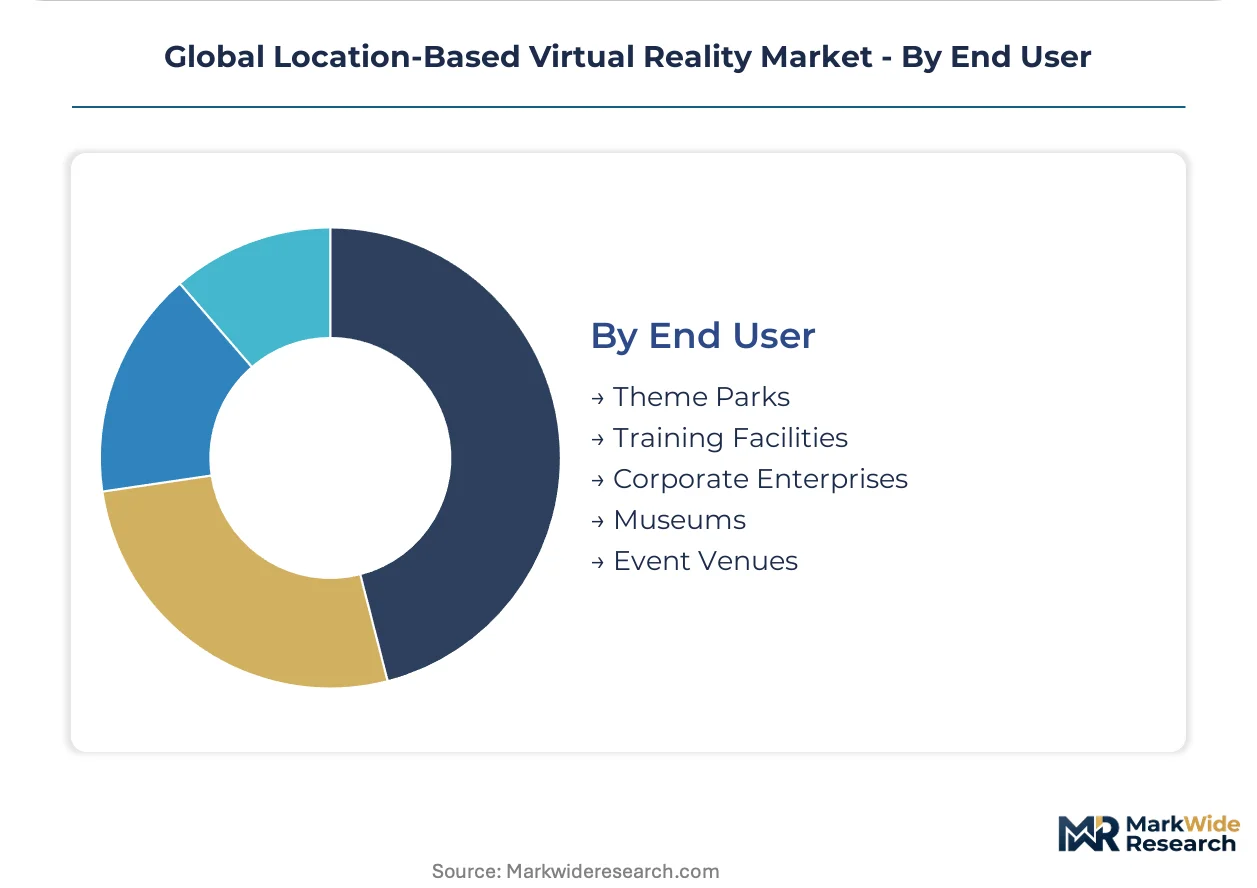
- Theme Parks:Large-scale operators integrating VR into queue entertainment and standalone attractions. United States and Japanese park chains in Florida, California, and Chiba prefecture drive volume procurement.
- Corporate Enterprises:Internal training campuses and employee engagement installations with annual subscription preferences.
- Training Facilities:Dedicated aviation, medical, and military simulation centers with certification requirements.
- Museums:Cultural institutions deploying immersive exhibits for differentiated programming.
- Event Venues:Temporary and pop-up installations for corporate activations and private functions.
Theme Parks maintains equipment volume dominance; Corporate Enterprises shifts fastest toward recurring service models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and the United States show low price elasticity for premium free-roam installations, while operators in India and Southeast Asia prioritize modular kiosk economics. European venues occupy a mid-position where regulatory compliance costs constrain budget-tier expansion.
United States
Theme park operators in Florida and California drive demand for warehouse-scale VR arenas with sub-20ms latency specifications. FCC wireless spectrum rules for untethered headsets shape hardware certification timelines. Chicago and Los Angeles landlords retrofit vacant retail into VR foot-traffic generators.
China
Shenzhen and Shanghai venue operators seek rapid equipment turnover cycles for family entertainment centers. MIIT interoperability standards compress domestic headset certification timelines. Pearl River Delta manufacturers accelerate motion tracker production for export markets.
Japan
Osaka and Tokyo family entertainment centers adopt standalone inside-out tracking systems to minimize technical staffing. METI guidelines on electromagnetic compatibility influence product design cycles. Chiba prefecture theme park chains integrate VR into queue entertainment installations.
Germany
Aviation training campuses in Bavaria and North Rhine-Westphalia procure multi-year simulation contracts with certification requirements. KBA pilot training module standards deepen contract durations. Berlin-Brandenburg venues face EU AI Act compliance burdens for biometric data collection.
Australia
Melbourne and Sydney free-roam operators deploy wireless multiplayer arenas across entertainment districts. Civil Aviation Safety Authority certification for pilot training modules attracts enterprise procurement. Technical staff hours consumed by daily tracking array calibration constrain operating schedules.
Global Location-Based Virtual Reality Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the former controlling proprietary motion-tracking architectures and the latter competing on deployment speed. The upper tier captures premium urban real estate through throughput-dependent economics, while mid-market operators struggle with compressed margins between rent burdens and kiosk pricing. Three archetypes dominate: warehouse-scale free-roam integrators, modular turnkey system providers, and enterprise training specialists. Competitive moves concentrate on exclusive IP licensing for content differentiation and geographic expansion into Asia-Pacific markets.
Within the free-roam integrator tier, Zero Latency Pty Ltd and Sandbox VR exemplify contrasting geographic strategies, with the former spanning Australia, the United States, and Europe while the latter concentrates in high-rent urban districts. Hologate GmbH occupies a position among modular turnkey specialists, serving mid-sized entertainment operators with reduced retrofit timelines. These three entities represent the capital-intensity divergence reshaping competitive boundaries between premium fidelity and operational flexibility.
| Leading Market Players |
|---|
| Zero Latency Pty Ltd |
| Sandbox VR |
| Hologate GmbH |
| Dreamscape Immersive Inc. |
| The VOID LLC |
| EXIT VR GmbH |
| Survios Inc. |
| VRstudios Inc. |
| IMAX Corporation |
| Others |
Supply & Pricing Matrix
Inside-out tracking systems displacing external lighthouse arrays in compact venues simultaneously concentrates component sourcing in Shenzhen and Osaka while compressing hardware margins for mid-tier operators unable to absorb premium sensor costs.
Pricing Analysis
Annual content licensing subscriptions now drive lifetime value beyond initial hardware deployment, with venue operators paying recurring fees for exclusive IP access. Three-tier pricing structure across premium free-roam, standard kiosk, and economy mobile-tethered levels separates Sandbox VR's urban positioning from Hologate's modular systems. Cost compression in mid-market equipment is intensifying because MIIT-certified Chinese manufacturers flood domestic channels with interoperable headsets. Independent venue operators in India and Southeast Asia exhibit highest price sensitivity, while theme park procurement teams in the United States and Japan show lowest elasticity for certified simulation hardware.
Supply Chain Analysis
Shenzhen port congestion and Pearl River Delta component shortages periodically choke headset and motion tracker deliveries to Australian and European venues. Manufacturing gravity centers on China for display panels and final assembly, South Korea for OLED microdisplays, and Japan for precision optical components. Raw material dependencies span rare-earth magnets for haptic actuators, gallium arsenide for wireless tracking arrays, and specialized polymers for lightweight headset housings. Tariff exposure on Chinese electronics imports into the United States creates margin vulnerability for domestic distributors. Distribution runs through direct OEM relationships with large venue chains and regional integrators serving mid-sized operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Location-based VR functions as a service-attach business where recurring content licensing and maintenance contracts expand faster than one-time hardware sales, rewarding vendors who bundle subscription tiers with equipment refresh cycles.
For Market Incumbents: Compound defensive moats through exclusive IP lockups with major entertainment studios and backward integration into proprietary motion-tracking hardware. Sandbox VR and Zero Latency should deepen certification relationships with Australia's Civil Aviation Safety Authority and Germany's KBA to extend contract durations in simulation training. Cloud-streaming headset architectures threaten PC-connected fidelity advantages, making wireless latency optimization the critical R&D priority. For New Entrants and Emerging Players: Differentiate on deployment velocity by offering turnkey kiosk systems with sub-four-week installation timelines for vacant retail conversions in secondary United States cities and Southeast Asian malls. Healthcare rehabilitation protocols in hospital outpatient departments represent the most penetrable white-space segment, with FDA-cleared VR exposure therapies creating reimbursable service lines absent dominant incumbents. Target corporate training procurement teams with annual subscription pitches that shift buyer preference from capital expenditure to operating expense. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated platform owners with captive content libraries and proprietary tracking hardware over pure-play venue operators. Long-term viability hinges on enterprise training contract diversification beyond entertainment's session-throughput volatility. Acquisition targets should demonstrate recurring revenue ratios above hardware sales and certification relationships with aviation or medical regulators. Watch for EU AI Act enforcement patterns as the signal indicating compliance cost inflection that could filter out undercapitalized European operators.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive IP Licensing Agreement | Secures marquee franchise access that differentiates premium venues from commodity kiosk operators. |
| Wireless Tracking Hardware Refresh | Sub-20ms motion-to-photon latency defends free-roam positioning against inside-out tracking commoditization. |
| Aviation Certification Pathway | KBA and Civil Aviation Safety Authority approvals deepen contract tenures and margin pools. |
| Modular Turnkey System Launch | Slashes venue retrofit timelines from months to weeks for mid-sized entertainment operators. |
| Healthcare Reimbursement Strategy | FDA-cleared VR exposure therapies create reimbursable service lines in hospital outpatient departments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with VR venue operators, theme park procurement directors, aviation training campus managers, healthcare rehabilitation specialists, and hardware OEM product planners. Secondary validation drew from FCC equipment authorization databases, MIIT certification registries, FDA 510(k) filings for VR medical devices, and EU AI Act implementation guidance. Customs records tracking headset and motion tracker shipments, SEC filings from disclosed entertainment technology vendors, and venue operator lease disclosure patterns supplemented quantitative sizing. Bottom-up venue count estimates triangulated against top-down hardware shipment data across the analysis window.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmentation across hardware type, application risk profile, platform architecture, and end-user procurement authority. CAGRs were derived from regression analysis of historical equipment deployment rates against experiential leisure spending indices and enterprise training budget allocations. Forecast inputs incorporated FCC wireless spectrum allocation timelines, MIIT interoperability standard adoption curves, and EU AI Act compliance cost assumptions for biometric data handling.
Decision-makers should treat outputs as directional under assumptions of sustained experiential leisure spending and stable regulatory frameworks for wireless spectrum and biometric data; material deviation in consumer discretionary patterns or accelerated EU enforcement would warrant model refresh. Practitioners should keep alternative scenarios live as hardware standardization bets between console-connected and cloud-streaming architectures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Immersive Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Virtual Reality (VR) Health Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Augmented and Mixed Reality (VR/AR) Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Firefighter Simulator Market
Virtual Reality (VR) and Augmented Reality (AR)
Internet of Senses Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Dressing Room Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Virtual Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Telepresence Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality (AR) in Healthcare Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
AR & VR Headset Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
India Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
3D Somatosensory Virtual Fitting Market
Virtual Reality (VR) and Augmented Reality (AR)
Location-Based VR Entertainment Market