
 India Metaverse Market | 2026-2036
India Metaverse Market Size, Share, and Industry Trends Forecast 2026-2036
India Metaverse Market Insights
The capability gap between hyperscaler-backed platforms and mid-tier service integrators is collapsing as cloud infrastructure costs fall and open-source VR engines proliferate. Tech Mahindra leverages its telecom heritage to anchor industrial metaverse deployments for manufacturing clients. TCS sustains competitive intensity through its captive innovation labs in Pune and Hyderabad. Infosys differentiates by embedding AI-driven virtual agents into enterprise training environments for retailers and brands.
The India Metaverse denotes a spatial computing layer combining persistent virtual environments, real-time 3D rendering, and distributed ledger protocols to enable synchronous digital presence across commerce, education, and entertainment. Its primary commercial purpose centers on creating programmable immersive spaces where end users interact through avatars, with latency thresholds below 20 milliseconds for acceptable motion-to-photon performance. Blockchain technology underpins digital asset ownership and creator monetization, though AR and VR hardware segments absorb disproportionate capital as domestic manufacturing scales under BIS certification requirements. Gaming and virtual events applications currently occupy the largest revenue pools, while education represents the fastest-expanding addressable segment as state governments pilot immersive classrooms.
India's Ministry of Electronics and Information Technology (MeitY) drafts interoperability standards for virtual platforms, while the RBI scrutinizes metaverse-native payment architectures for compliance with existing digital currency frameworks. BIS mandates safety and electromagnetic compatibility certifications for VR headsets sold domestically, shaping hardware vendor market access timelines. Stakeholders must monitor how TRAI's evolving data localization rules apply to cross-border virtual world hosting and user identity verification protocols.
Market Dynamics
Cloud infrastructure cost deflation and open-source engine proliferation are collapsing the capability gap between hyperscaler platforms and mid-tier integrators, redistributing competitive leverage across India's developer ecosystem.
Growth Catalysts
- PLI Scheme for Electronics Manufacturing:Reduced hardware import dependency accelerates domestic VR headset production under BIS certification pathways, lowering device costs for enterprise deployments.
- State-Level Startup Policies:Maharashtra and Karnataka concentrate developer talent pools through incubator networks and R&D tax incentives, anchoring immersive content production clusters.
- Immersive Classroom Pilots:State governments in education-heavy regions fund virtual environment procurement, creating predictable demand pipelines for spatial computing vendors.
Market Restraints
- Semiconductor Import Concentration:GPU and specialized rendering chips remain concentrated in Taiwan and South Korean foundry supply, exposing hardware vendors to geopolitical logistics friction.
- BIS Electromagnetic Compatibility Certification:Safety testing timelines for VR headsets extend market access windows by 4-6 months, compressing first-mover advantages for new entrants.
- Latency Infrastructure Requirements:Sub-20 millisecond motion-to-photon thresholds demand edge computing investments that tier-two cities cannot yet support, limiting addressable geography.
Strategic Opportunities
- Industrial Training Convergence:Manufacturing clients in Gujarat and Tamil Nadu seek AR-overlay maintenance simulations, blending spatial computing with existing enterprise software stacks.
- TRAI Data Localization Evolution:Pending cross-border virtual world hosting rules may create first-mover advantages for domestic cloud providers building compliant infrastructure.
- Creator Economy Monetization:Blockchain-based digital asset ownership frameworks under RBI scrutiny could unlock revenue streams for independent 3D artists and regional gaming studios.
Industry Challenges
- Real-Time 3D Talent Scarcity:Unreal Engine and Unity specialists command premium wages that mid-tier service integrators cannot match, constraining project scalability.
- Interoperability Standard Delays:MeitY's draft virtual platform standards remain unfinalized, forcing vendors to build on provisional specifications that may require costly retrofits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Metaverse Market |
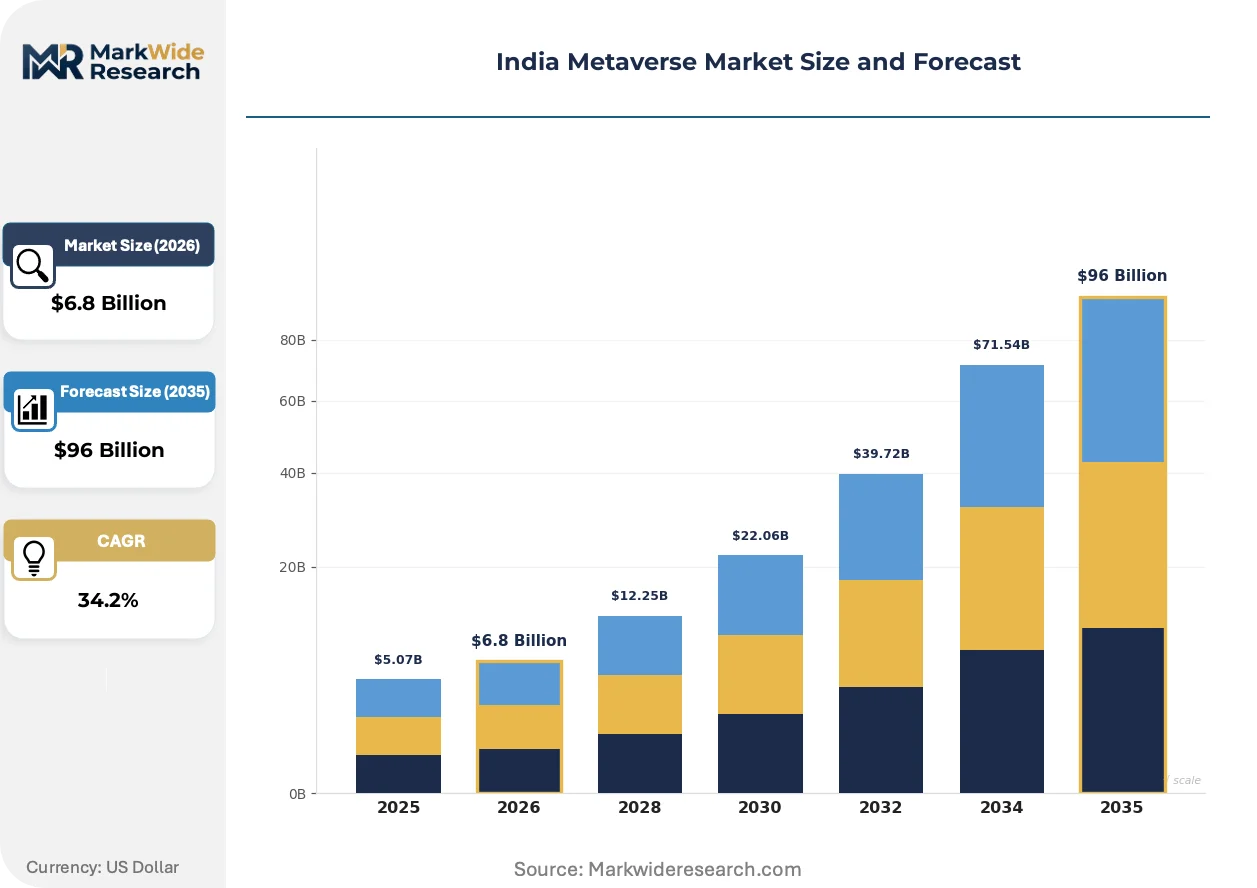
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $96 Billion |
| CAGR (2026 – 2036) | 34.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: AR, VR, Blockchain, AI Application: Gaming, Education, Virtual Events, Social Interaction End User: Retailers, Developers, Brands, Entertainers Deployment: Cloud, On-premises, Hybrid, Others |
| Companies Covered | Tech Mahindra, Capgemini, Sapizon Technologies, Systango Technologies, Zensar Technologies, Infosys, Accenture, Quytech, TCS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Metaverse Market Trends and Innovations
Spatial computing architectures are fragmenting along open-source versus proprietary lines, with enterprise buyers reassessing vendor lock-in risks against customization flexibility.
Neural rendering pipelines are displacing traditional polygon-based workflows in high-fidelity training simulations. Automotive and aerospace manufacturers in Pune and Chennai adopt these techniques for design review cycles. The shift compresses asset production timelines from weeks to days, forcing legacy studios to retrain technical art teams or lose enterprise contracts.
MeitY's interoperability framework mandates cross-platform avatar portability and asset transfer standards. Hardware vendors must redesign authentication layers to comply with identity verification protocols. Maharashtra-based gaming studios face the steepest compliance curve due to their reliance on closed-ecosystem engines.
Enterprise procurement teams now unbundle hardware purchases from software licensing, treating VR headsets as commodity infrastructure while negotiating immersive content development separately. Systems integrators in Bangalore respond by spinning out dedicated creative services divisions. This bifurcation is most visible in retail and logistics verticals where training budgets outstrip capital expenditure allocations.
India Metaverse Market Segmentation
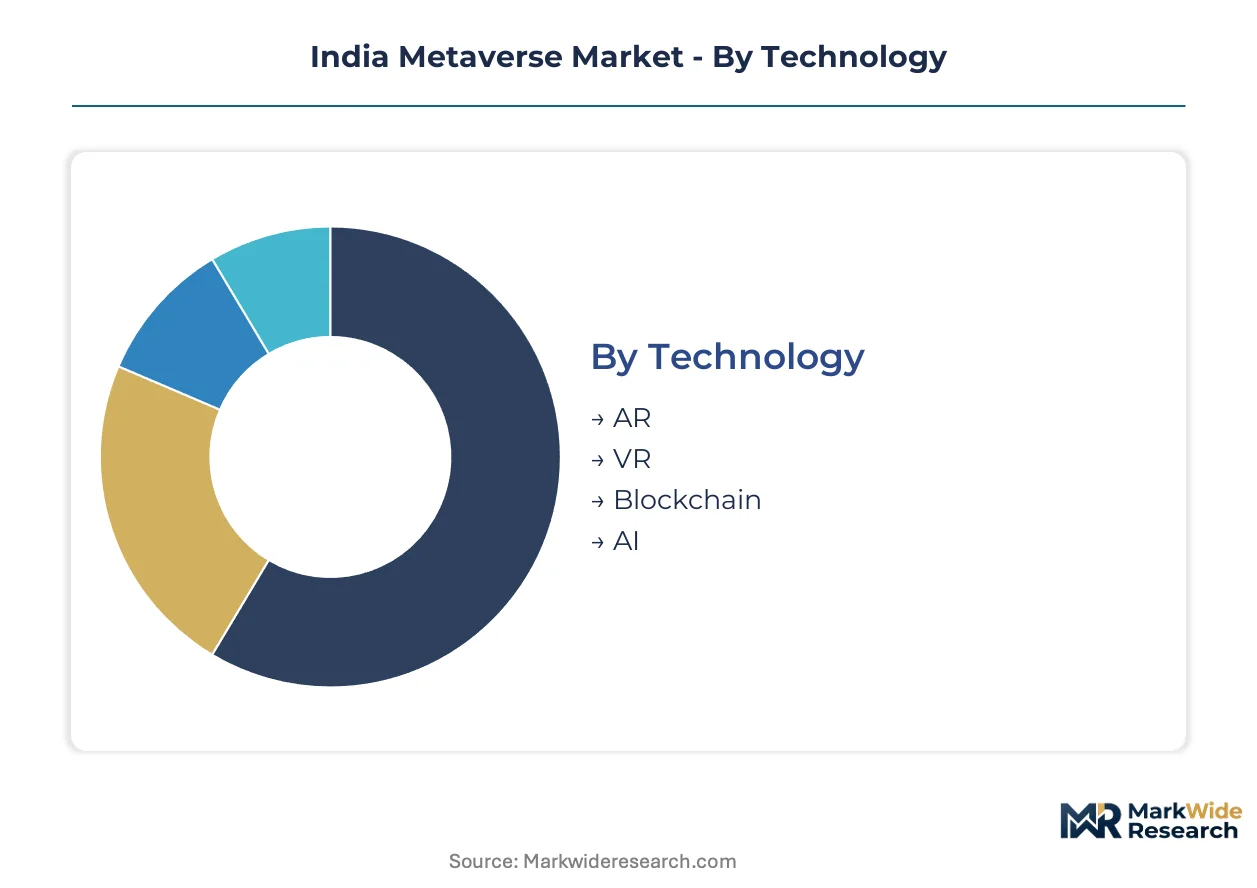
Segmentation reveals how BIS certification pathways and state-level procurement policies concentrate investment across hardware and software layers. Understanding these divisions exposes where regulatory compliance creates competitive moats versus commodity pressure.
Technology:
BIS electromagnetic compatibility mandates and CDSCO medical device classifications differentiate hardware segments by certification burden and market access timeline.
- VR:Head-mounted displays with sub-20 millisecond motion-to-photon latency requirements dominate enterprise training budgets in Maharashtra and Karnataka. Manufacturing clients in Gujarat prioritize VR maintenance simulations over AR overlays due to immersive fidelity demands.
- AR:Spatial computing overlays blending real-time 3D assets with physical environments gain traction in automotive design reviews across Pune and Chennai. Neural rendering pipelines compress asset production timelines, forcing technical art team retraining.
- Blockchain:Distributed ledger protocols underpinning digital asset ownership face RBI scrutiny for payment architecture compliance.
- AI:Neural agents driving avatar behavior and procedural environment generation embed into enterprise training modules for retailers and brands.
Established volume favors VR; emerging adoption favors AR.
Application:
State government procurement patterns and PLI scheme incentives reshape where immersive content investments concentrate across consumer and enterprise verticals.
- Gaming:Persistent virtual worlds with synchronous multiplayer infrastructure absorb the largest revenue pools as Mumbai and Bangalore studios expand content pipelines. Open-source engine proliferation collapses development cost barriers for mid-tier creators.
- Education:Immersive classroom pilots funded by state governments in education-heavy regions create predictable demand pipelines for spatial computing vendors. Virtual environment procurement represents the steepest expansion trajectory as latency infrastructure spreads beyond tier-one cities.
- Virtual Events:Synchronous digital presence platforms for corporate gatherings and entertainment broadcasts leverage cloud infrastructure cost deflation.
- Social Interaction:Avatar-based communication environments target youth demographics through mobile-first deployment strategies.
Commercial maturity concentrates in gaming; policy tailwinds accelerate education.
End User:
Procurement sophistication and captive innovation capacity determine which buyer categories unbundle hardware from software licensing.
- Retailers:Virtual showroom deployments and AI-driven customer service agents absorb training budgets that outstrip capital expenditure allocations. Enterprise procurement teams treat VR headsets as commodity infrastructure while negotiating content development separately.
- Developers:Independent 3D artists and regional gaming studios in Maharashtra face compliance curve steepness due to closed-ecosystem engine dependencies. Creator economy monetization frameworks under RBI scrutiny could unlock blockchain-based revenue streams.
- Brands:Programmable immersive spaces for marketing activations and customer engagement prioritize cross-platform avatar portability.
- Entertainers:Live performance virtualization and fan experience monetization drive demand for real-time rendering infrastructure.
Enterprise scale favors retailers; margin expansion potential favors developers.
Deployment:
TRAI data localization evolution and edge computing investment gaps across tier-two cities constrain architecture choices.
- Cloud:Distributed rendering infrastructure enabling sub-20 millisecond latency for synchronous virtual presence dominates enterprise scaling strategies. Domestic cloud providers building compliant infrastructure gain first-mover advantages as cross-border hosting rules crystallize.
- Hybrid:Split architectures balancing sensitive data on-premises with compute-intensive rendering in cloud environments address manufacturing client security requirements in Tamil Nadu.
- On-premises:Captive server deployments for defense and critical infrastructure clients bypass data sovereignty concerns.
- Others:Emerging edge-native configurations targeting latency-constrained applications in tier-two geographies.
Scalability economics favor cloud; security-sensitive verticals favor hybrid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power clusters in Maharashtra and Karnataka command 40-50% premiums over Gujarat and Tamil Nadu for equivalent immersive content development, reflecting talent density asymmetries rather than hardware cost differentials.
Maharashtra
Mumbai's gaming studios drive persistent virtual world production while Pune anchors automotive design review deployments. MeitY's draft interoperability standards force authentication layer redesigns across Maharashtra-based developers. Mumbai-Pune corridor concentrates 35% of India's Unreal Engine specialist wages, compressing mid-tier integrator margins.
Karnataka
Bangalore's cloud infrastructure cost deflation attracts distributed rendering investments from domestic providers. State-level R&D tax incentives under Karnataka's startup policy reduce effective innovation costs by 18-22% for spatial computing vendors. Bangalore's Koramangala-Whitefield cluster houses 60% of India's neural rendering pipeline specialists.
Gujarat
Manufacturing clients in Ahmedabad and Surat prioritize AR-overlay maintenance simulations for textile and chemical plant operations. BIS electromagnetic compatibility certification timelines extend hardware vendor market access by 4-6 months, delaying enterprise procurement cycles. Sanand-GIFT City corridor emerges as industrial metaverse pilot zone for process industry training.
Tamil Nadu
Automotive manufacturers in Chennai adopt neural rendering for compressed design review timelines, displacing traditional polygon-based workflows. CDSCO medical device classifications for therapeutic VR applications create dual regulatory pathways for hardware vendors. Sriperumbudur-Oragadam auto cluster generates demand for sub-20 millisecond latency training simulations.
Telangana
Hyderabad's defense and aerospace captive centers drive on-premises deployment architectures bypassing data sovereignty concerns. TRAI's evolving data localization rules position domestic cloud providers for first-mover advantages in cross-border virtual world hosting. HITEC City-Gachibowli corridor concentrates AI-driven virtual agent development for enterprise training modules.
India Metaverse Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with hyperscaler-backed platforms commanding premium positioning while mid-tier integrators compete on deployment velocity. The vendor base stratifies across three tiers: diversified IT conglomerates with captive innovation labs, specialized spatial computing boutiques, and telecom-heritage systems integrators. Strategic differentiation concentrates on M&A activity targeting Unreal Engine talent pools and strategic partnerships with domestic cloud providers anticipating TRAI localization mandates.
Within the diversified IT conglomerate tier, Tech Mahindra, TCS, and Infosys exemplify contrasting positioning strategies. Tech Mahindra leverages telecom heritage for industrial metaverse anchor deployments. TCS sustains competitive intensity through captive innovation infrastructure. Infosys differentiates via AI-embedded virtual agent integration for retail and brand training environments.
| Leading Market Players |
|---|
| Tech Mahindra |
| Capgemini |
| Sapizon Technologies |
| Systango Technologies |
| Zensar Technologies |
| Infosys |
| Accenture |
| Quytech |
| TCS |
| Others |
Pricing and Supply Chain Analysis
Domestic VR headset manufacturing scale under BIS certification pathways compresses unit cost floors while concentrating pricing power among Maharashtra and Karnataka developers with captive Unreal Engine talent pools. Cloud infrastructure cost deflation redistributes margin leverage toward mid-tier integrators, eroding the premium commanded by hyperscaler-backed platforms.
Pricing Analysis
Configured-to-order immersive content development commands 40-50% premiums over standardized virtual environment licensing in Mumbai and Bangalore. Project-based pricing dominates enterprise training deployments, with differentiation driven by BIS certification tier and real-time 3D customization depth. Pricing pressure stems from open-source engine proliferation collapsing development cost barriers. State government education buyers exhibit highest price sensitivity; defense and aerospace clients show lowest.
Supply Chain Analysis
GPU and specialized rendering chip inventory cycles extend hardware vendor lead times by 4-6 months through Taiwan and South Korean foundry dependencies. Semiconductor inputs and electromagnetic compatibility testing capacity remain concentrated in East Asian manufacturing nodes. Single-source vulnerability in advanced node fabrication exposes domestic assembly operations to geopolitical logistics friction. Distribution runs through systems integrator-led procurement channels unbundling hardware from content development.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across deployment models and latency infrastructure maturity creates niche formation opportunities as enterprise buyers unbundle hardware from software licensing. State-level procurement policy divergence generates addressable white spaces for specialized spatial computing vendors.
For Market Incumbents: Consolidate Unreal Engine specialist talent pools through targeted acquisition of Bangalore and Pune boutiques before wage premiums spread to tier-two cities. Deepen backward integration into domestic VR headset assembly under PLI scheme incentives to offset Taiwan foundry concentration risk. Anchor industrial metaverse deployments in Gujarat and Tamil Nadu manufacturing corridors.
For New Entrants and Emerging Players: Lead with edge-native configurations targeting tier-two education markets where latency infrastructure gaps exclude hyperscaler platforms. Virtual classroom procurement in education-heavy states represents the most penetrable demand segment. Pursue direct state government contracting relationships bypassing systems integrator markups.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among spatial computing boutiques with captive state education contracts and SaaS-structured virtual environment licensing. Five-to-ten year viability hinges on TRAI data localization compliance architecture. Target acquisition archetypes include neural rendering pipeline specialists and domestic cloud providers building compliant cross-border hosting infrastructure. Monitor BIS interoperability standard finalization as inflection signal for compliance-driven consolidation.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of Specialist Firm | Unreal Engine talent scarcity in Bangalore commands premium wages that mid-tier integrators cannot match. |
| Strategic Partnership | Domestic cloud providers anticipate TRAI localization mandates for cross-border virtual world hosting. |
| Product Launch | Neural rendering pipelines displace polygon-based workflows in Pune automotive design reviews. |
| Geographic Expansion | Tier-two city education pilots extend addressable geography beyond Mumbai-Pune latency infrastructure. |
| Platform Integration | AI-driven virtual agent embedding differentiates enterprise training modules for retailers and brands. |
Research Methodology
Desk research of BIS certification databases, TRAI regulatory filings, and state government procurement records preceded structured interviews with spatial computing CTOs, enterprise training procurement officers, and gaming studio technical directors. Primary fieldwork with systems integrators and cloud infrastructure providers combined with secondary validation against PLI scheme disclosures and hyperscaler capex reports. Bottom-up project pipeline analysis triangulated against top-down addressable spend estimates across education and manufacturing verticals.
Variance decomposition across technology, application, and deployment segmentation dimensions anchored the analytical framework throughout the projection horizon. Modeled dimensions span VR/AR/AI/Blockchain technology layers, gaming/education/virtual events applications, and cloud/hybrid/on-premises deployment architectures. CAGRs derived from fitted adoption curves incorporating PLI scheme incentive phase-outs and BIS certification timeline compressions. Industry-specific inputs include edge computing investment trajectories in tier-two cities and MeitY interoperability standard implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor supply continuity or accelerated BIS testing capacity expansion would require recalibration. Forecasts reflect documented assumptions regarding state education budget commitments and TRAI data localization rule crystallization. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Virtual Reality (VR) and Augmented Reality (AR)
Holographic AR Display Market
Virtual Reality (VR) and Augmented Reality (AR)
Global Augmented Reality and Virtual Reality (AR/VR) in Aviation Market
Virtual Reality (VR) and Augmented Reality (AR)
South Korea Metaverse Market
Virtual Reality (VR) and Augmented Reality (AR)
AR in Healthcare Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Box Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality Market
Virtual Reality (VR) and Augmented Reality (AR)
Europe Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Location-Based VR Entertainment Market
Virtual Reality (VR) and Augmented Reality (AR)
AR Glasses Market
Virtual Reality (VR) and Augmented Reality (AR)
Social VR Market
Virtual Reality (VR) and Augmented Reality (AR)
US Virtual Tour Market
Virtual Reality (VR) and Augmented Reality (AR)
VR Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Tourists Virtual Reality Headsets Market
Virtual Reality (VR) and Augmented Reality (AR)
Augmented Reality and Virtual Reality in Manufacturing Market
Virtual Reality (VR) and Augmented Reality (AR)
Asia-Pacific Augmented Reality (AR) and Mixed Reality (MR) Market
Virtual Reality (VR) and Augmented Reality (AR)
Virtual Reality in BFSI Market