
 Prader-Willi Syndrome (PWS) Market | 2026-2036
Prader-Willi Syndrome (PWS) Market Size, Share, and Industry Trends Forecast 2026-2036
Prader-Willi Syndrome (PWS) Market Analytics
A shift from single-source growth hormone supply toward multi-source biologics procurement is rebalancing how hospital systems secure PWS therapies. Soleno Therapeutics specializes in metabolic disorder pipelines with a dedicated focus on hyperphagia management. Novo Nordisk leverages its endocrinology manufacturing scale to sustain insulin and hormone product leadership. Pfizer anchors its rare disease portfolio through broad clinical infrastructure and global distribution networks.
Prader-Willi Syndrome constitutes a complex genetic disorder characterized by chromosome 15q11-q13 deletion or maternal uniparental disomy, resulting in hypothalamic dysfunction, hyperphagia-driven obesity, and growth hormone deficiency that demands multidisciplinary clinical intervention. Growth hormones represent the established therapeutic backbone with mature reimbursement pathways, while appetite suppressants command emerging margin pools as novel drug candidates advance through regulatory pipelines. Pediatric patients drive volume concentration through early diagnosis protocols, though adult patient segments are expanding as longitudinal survival improves and transition-of-care programs mature across specialized centers.
FDA orphan drug incentives and EMA rare disease designations shape PWS drug development economics by compressing trial timelines and extending market exclusivity periods for approved therapies. The country's national pharmaceutical regulator in Japan, PMDA, maintains distinct pediatric trial requirements that influence Asia-Pacific market entry sequencing for hormone replacement therapies. Stakeholders must monitor regulatory harmonization progress between FDA and EMA on biomarker qualification for hyperphagia endpoints, as this alignment will determine whether centralized trial designs can support simultaneous multi-region filings.
Market Dynamics
FDA orphan drug designations and priority review vouchers are compressing clinical trial timelines for rare disease therapeutics, accelerating the shift from single-source growth hormone supply toward multi-source biologics procurement across hospital systems.
Growth Catalysts
- EMA Rare Disease Designations:Extended market exclusivity periods incentivize pharmaceutical investment in hyperphagia-targeting drug candidates across European markets.
- Pediatric Endocrinology Clinic Expansion:Specialized treatment protocols in the United States concentrate diagnostic volume and drive early intervention adoption.
- Longitudinal Survival Improvements:Transition-of-care program maturation expands the addressable adult patient segment beyond traditional pediatric focus.
Market Restraints
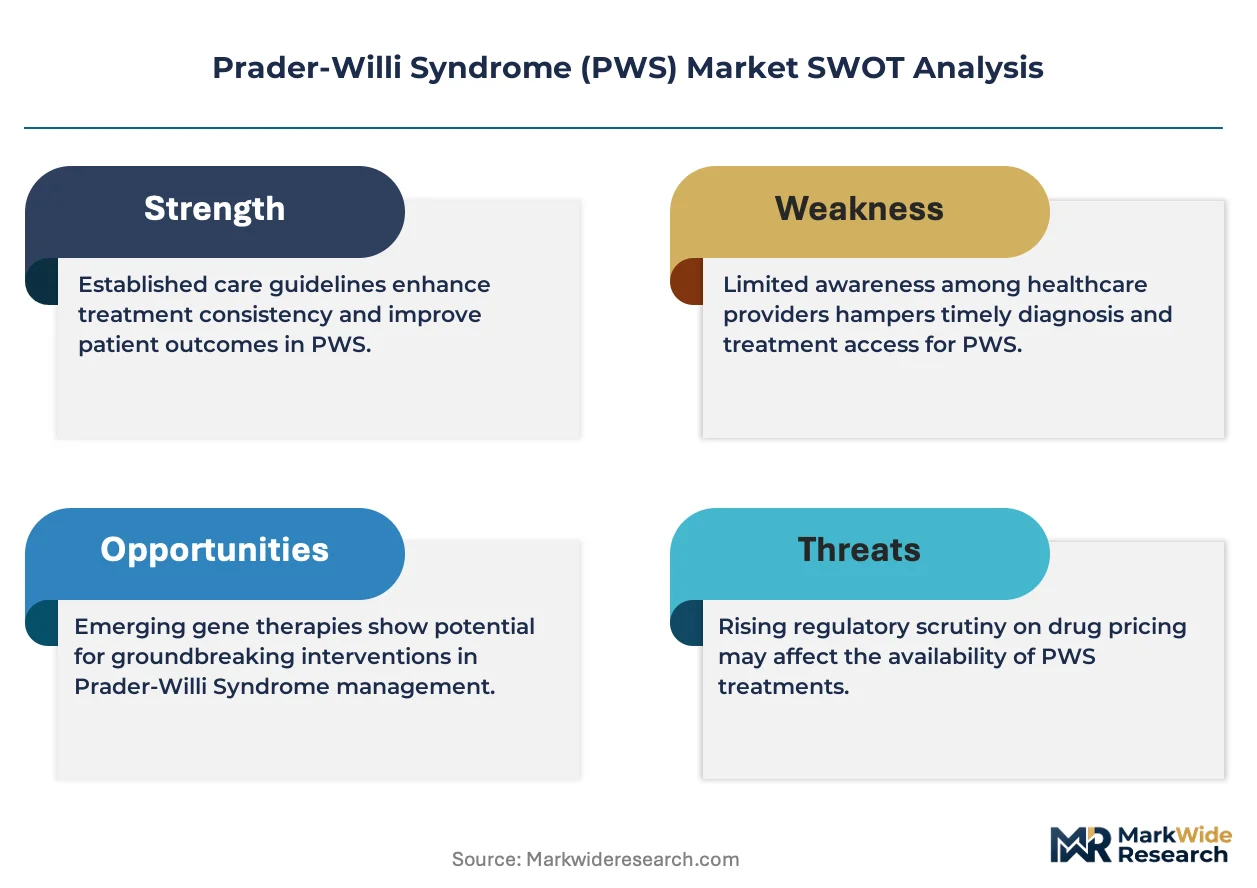
- Biologics Manufacturing Concentration:Limited FDA-approved growth hormone production facilities create supply vulnerability concentrated in North American contract manufacturing networks.
- PMDA Pediatric Trial Requirements:Japan's distinct regulatory pathway for hormone replacement therapies delays Asia-Pacific market entry sequencing.
- Hyperphagia Endpoint Validation:Absence of harmonized biomarker qualification between FDA and EMA forces redundant trial designs for appetite suppressant candidates.
Strategic Opportunities
- Adult Care Network Expansion:Underpenetrated transition clinics in Germany and France offer first-mover positioning for longitudinal patient management services.
- Telemedicine Integration:Remote endocrinology consultations are penetrating rural United States markets previously underserved by specialized PWS centers.
- Regulatory Harmonization:FDA-EMA alignment on hyperphagia endpoints would enable centralized trial designs supporting simultaneous multi-region filings.
Industry Challenges
- Multidisciplinary Care Coordination:Integration of endocrinology, nutrition, behavioral health, and genetics expertise strains hospital staffing models.
- Reimbursement Pathway Complexity:Divergent coding for growth hormone versus emerging appetite therapeutics creates prior authorization friction in United States commercial payers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Prader-Willi Syndrome (PWS) Market |
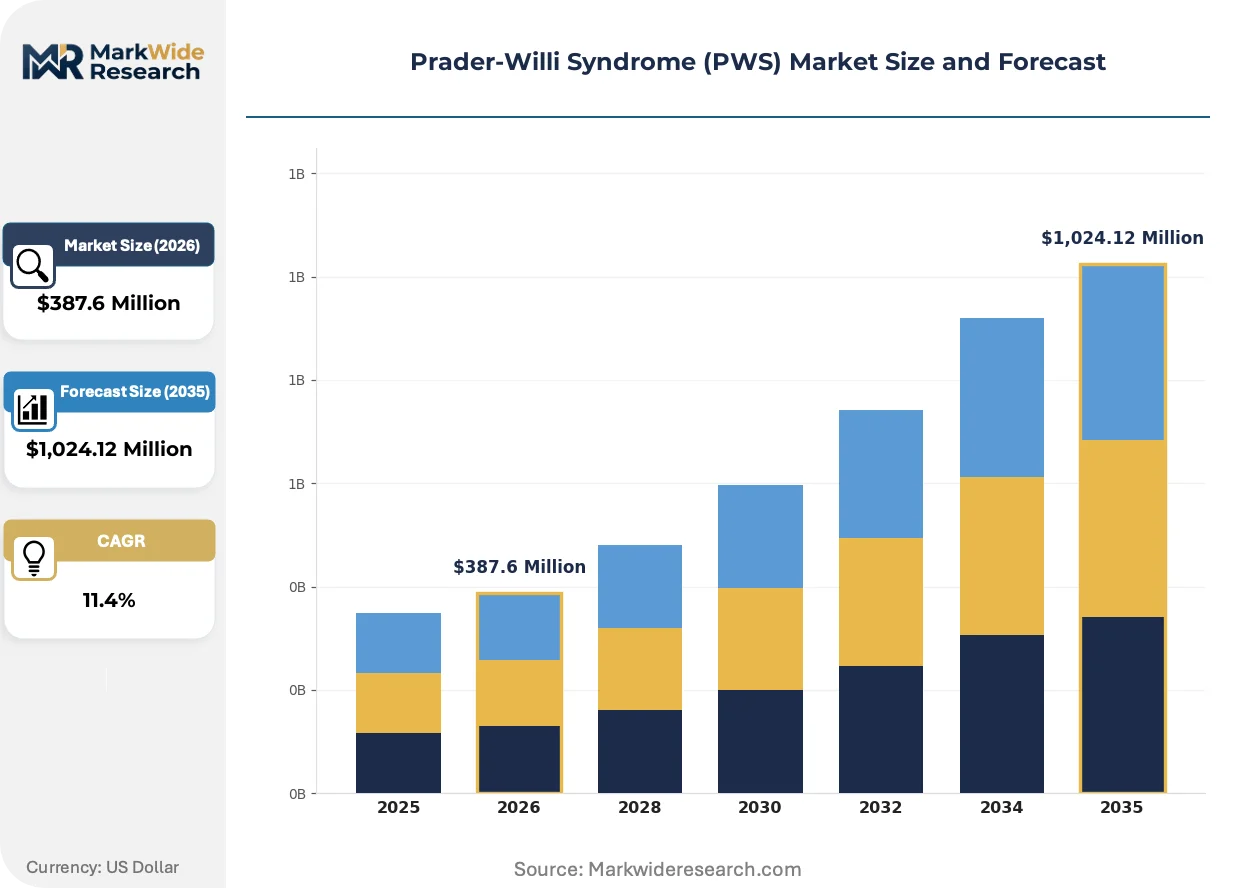
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,024.12 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Growth Hormones, Appetite Suppressants, Behavioral Therapy, Nutritional Supplements End User: Pediatric Patients, Adult Patients, Caregivers, Healthcare Providers Therapy Area: Endocrinology, Nutrition, Psychology, Rehabilitation Delivery Mode: Injections, Oral Medications, Nutritional Plans, Therapy Sessions |
| Companies Covered | Soleno Therapeutics, Pfizer, Novo Nordisk, Harmony Biosciences, Novartis, Aardvark Therapeutics, Sarepta Therapeutics, Gedeon Richter, Jazz Pharmaceuticals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Prader-Willi Syndrome (PWS) Market Evolving Landscape
Novel drug candidates targeting hypothalamic dysfunction are advancing through regulatory pipelines, reshaping competitive positioning between established hormone replacement and emerging appetite suppression modalities.
Continuous glucose monitoring integration with automated insulin delivery is overtaking traditional episodic metabolic assessment in PWS patient management. Pediatric endocrinology clinics in the United States are adopting these closed-loop systems at accelerating pace. This convergence is overtaking conventional growth hormone monotherapy by enabling real-time metabolic intervention that addresses the syndrome's dual hormonal and glycemic dysregulation.
EMA's Orphan Drug Regulation revision tightens post-market evidence requirements for rare disease therapeutics. Sponsors must now commit to extended pharmacovigilance protocols beyond initial approval. Growth hormone manufacturers with mature products face the highest compliance burden, while novel hyperphagia drug developers factor these costs into European market entry timing.
Hospital system consolidation is compressing supplier relationships from fragmented local purchasing to centralized biologics procurement. Integrated delivery networks in the United States are mandating sole-source or dual-source contracts for high-cost hormone therapies. This concentration is most visible in Midwestern states where Catholic health system mergers have reduced purchasing entities by half since 2020.
Prader-Willi Syndrome (PWS) Market Segmentation
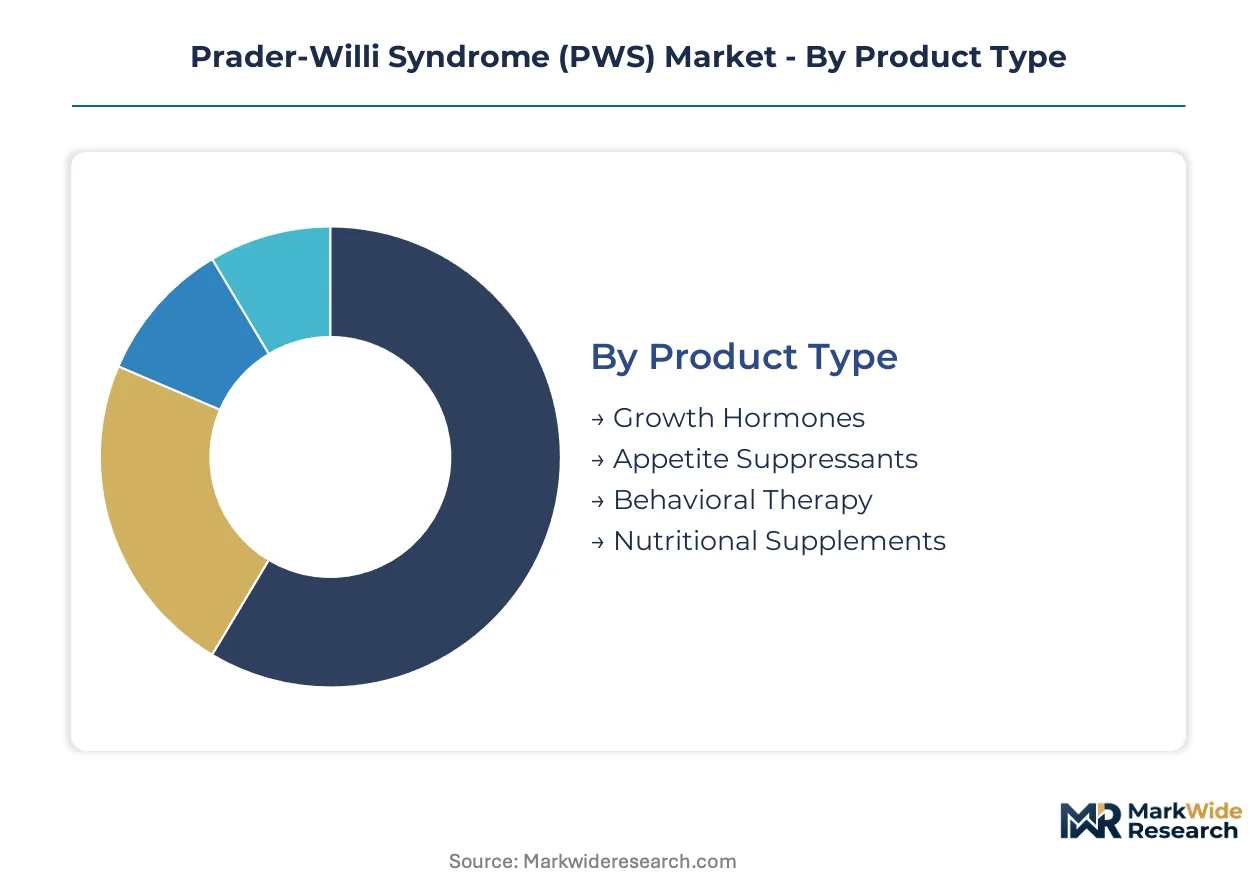
Prader-Willi Syndrome treatment selection hinges on disease stage, comorbidity profile, and reimbursement tier. Segmentation reveals how growth hormone dominance confronts emerging appetite suppression modalities across pediatric and adult care pathways.
Product Type:
Procurement decisions split between established biologics with mature reimbursement and novel therapeutics commanding premium pricing.
- Growth Hormones:Recombinant human growth hormone formulations constitute the pharmacological backbone, administered via daily subcutaneous injection. Pediatric endocrinology clinics in the United States drive procurement volume through early intervention protocols. FDA orphan drug exclusivity has compressed generic entry timelines for legacy products.
- Appetite Suppressants:Novel drug candidates targeting hypothalamic melanocortin pathways address hyperphagia, the syndrome's most debilitating behavioral manifestation. European EMA rare disease designations accelerate development timelines for these candidates. Reimbursement pathways remain unsettled as payers evaluate behavioral versus metabolic endpoints.
- Behavioral Therapy:Structured intervention protocols manage compulsive eating behaviors and social integration challenges.
- Nutritional Supplements:Specialized formulations address micronutrient deficiencies common in restricted-calorie management regimens.
Volume sits with Growth Hormones; growth tilts toward Appetite Suppressants.
End User:
Care delivery stratifies across developmental stages with distinct clinical infrastructure and funding mechanisms.
- Pediatric Patients:Early diagnosis through neonatal genetic screening enables hormone replacement initiation before growth velocity compromise. Academic medical centers concentrate diagnostic expertise and longitudinal follow-up capacity.
- Adult Patients:Expanded life expectancy has created an underserved population transitioning from pediatric care networks. Germany and France exhibit the most developed adult transition clinic infrastructure in Europe.
- Caregivers:Family members require training in environmental food security and behavioral crisis management.
- Healthcare Providers:Multidisciplinary teams spanning endocrinology, genetics, nutrition, and psychology coordinate complex care.
Clinical investment concentrates on Pediatric Patients; capacity expansion targets Adult Patients.
Therapy Area:
Reimbursement coding and specialist availability determine which disciplines capture patient flow.
- Endocrinology:Growth hormone deficiency management anchors therapeutic protocols with established CPT and HCPCS coding. Pediatric endocrinology fellowship programs in the United States have expanded PWS-specific curricula.
- Nutrition:Restricted-calorie diet design and metabolic monitoring prevent obesity-related complications. Registered dietitian integration into multidisciplinary teams varies by hospital system consolidation patterns.
- Psychology:Behavioral intervention addresses obsessive-compulsive features and intellectual disability accommodations.
- Rehabilitation:Physical and occupational therapy improves motor function and adaptive independence.
Reimbursement stability favors Endocrinology; service integration demands expand Nutrition.
Delivery Mode:
Patient adherence and caregiver burden shape modality selection across home and clinical settings.
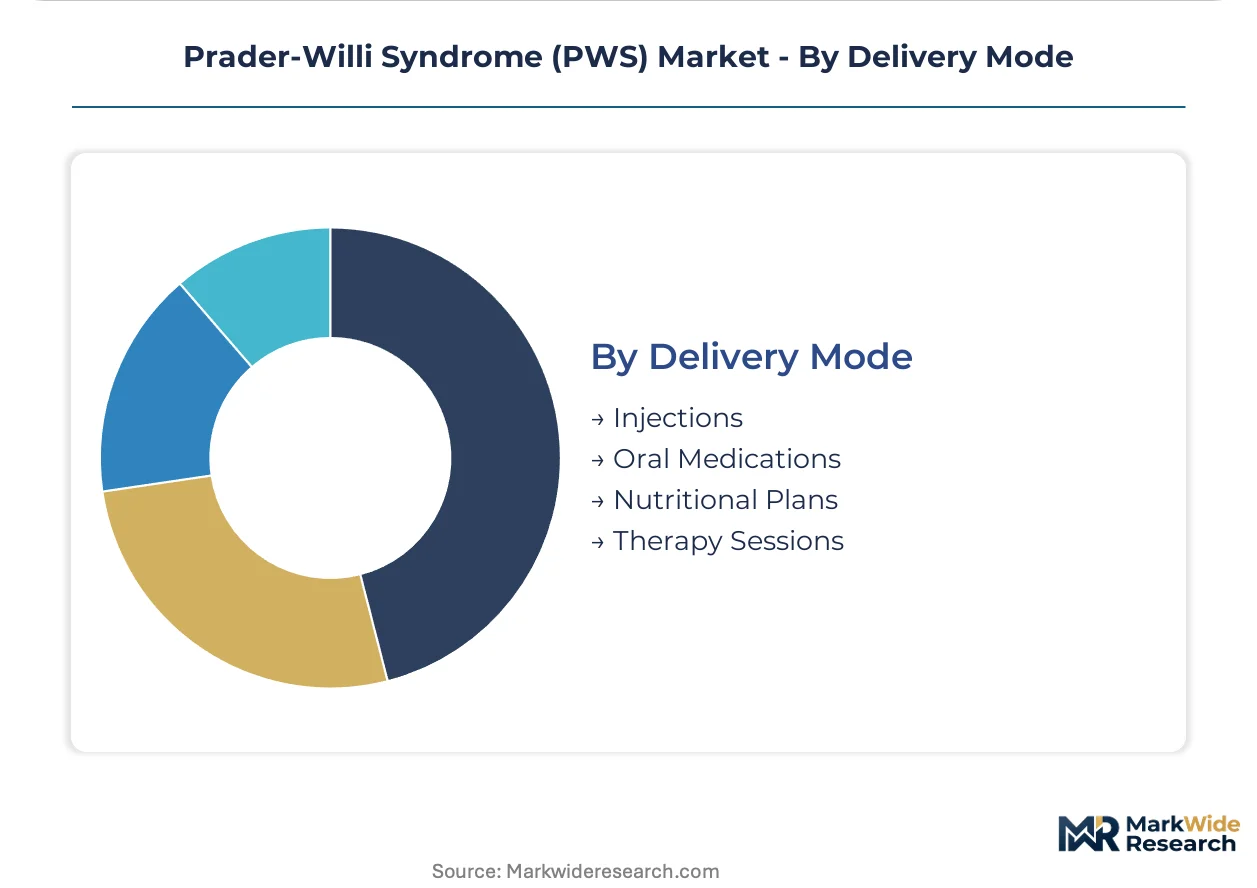
- Injections:Daily subcutaneous growth hormone administration requires caregiver training and cold chain maintenance. Home nursing support services concentrate in metropolitan United States markets with specialized PWS centers.
- Oral Medications:Emerging appetite suppressants promise reduced administration burden versus injectable biologics. Formulation stability and bioavailability challenges complicate development timelines for hypothalamic-targeting compounds.
- Nutritional Plans:Structured meal protocols with locked kitchen environments prevent unauthorized food access.
- Therapy Sessions:Behavioral and developmental interventions require consistent scheduling and specialized practitioner availability.
Clinical standardization centers on Injections; patient preference and adherence drivers elevate Oral Medications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chromosome 15q11-q13 deletion research clusters in the United States anchor clinical trial density for Prader-Willi Syndrome therapeutics. FDA orphan drug designations concentrate development incentives in markets with established rare disease infrastructure.
United States
Pediatric endocrinology clinics in Boston and Philadelphia drive diagnostic volume through early intervention protocols. FDA priority review vouchers compress development timelines for hyperphagia-targeting candidates. The Midwestern hospital system consolidation has halved purchasing entities since 2020, mandating sole-source contracts for growth hormone therapies.
Germany
Adult transition clinics in Munich and Hamburg exhibit Europe's most developed infrastructure for longitudinal PWS patient management. EMA rare disease designations extend market exclusivity periods for novel appetite suppressants. The country's national pharmaceutical regulator, BfArM, maintains accelerated assessment pathways for orphan indications.
Japan
PMDA pediatric trial requirements for hormone replacement therapies delay market entry sequencing relative to Western regulators. Tokyo academic medical centers concentrate diagnostic expertise for chromosome 15q11-q13 deletion screening. The Kanto region hosts the densest cluster of specialized endocrinology fellowship programs in Asia-Pacific.
United Kingdom
NHS specialized commissioning frameworks concentrate PWS treatment in London and Manchester tertiary centers. MHRA alignment with EMA orphan drug protocols enables parallel regulatory submissions for growth hormone formulations. The Oxford-Cambridge corridor anchors academic research into hypothalamic dysfunction mechanisms.
France
ANSM maintains distinct post-market surveillance requirements for biologics that shape European pharmacovigilance costs. Paris and Lyon house the continent's largest adult PWS patient registries outside Germany. The Île-de-France region concentrates multidisciplinary care coordination training programs for rare genetic disorders.
Prader-Willi Syndrome (PWS) Market Competitive Landscape
Portfolio diversification dominates the current landscape as established hormone manufacturers expand into hypothalamic-targeting modalities. The vendor base stratifies across three tiers: large-cap pharmaceutical conglomerates with rare disease divisions, mid-cap biotech specialists in metabolic disorders, and emerging clinical-stage developers focused on single indications. Two strategic archetypes predominate: endocrinology incumbents leveraging manufacturing scale, and precision medicine specialists advancing novel mechanisms. M&A activity and strategic partnerships represent the dominant competitive moves as players seek to bridge capability gaps between hormone replacement and appetite suppression expertise.
Within the large-cap tier, Pfizer anchors its positioning through broad clinical infrastructure and global distribution networks that span rare disease therapeutic categories. Novo Nordisk occupies a position reflecting deep endocrinology manufacturing scale and sustained leadership in insulin and hormone product categories. Soleno Therapeutics exemplifies the specialist archetype with dedicated metabolic disorder pipelines emphasizing hyperphagia management. These three entities collectively represent the competitive spectrum from diversified pharmaceutical scale to focused clinical-stage development.
| Leading Market Players |
|---|
| Soleno Therapeutics |
| Pfizer |
| Novo Nordisk |
| Harmony Biosciences |
| Novartis |
| Aardvark Therapeutics |
| Sarepta Therapeutics |
| Gedeon Richter |
| Jazz Pharmaceuticals |
| Others |
Value Network & Pricing Analysis
Recombinant protein production costs indexed to Chinese hamster ovary cell culture media and North American cold-chain logistics tariffs cascade through biologics procurement tiers, compressing margins on growth hormone formulations while elevating premium capture for novel appetite suppressants with differentiated hypothalamic-targeting mechanisms.
Pricing Analysis
Service bundling separates cold-chain logistics and home nursing support from base drug pricing in United States commercial contracts, while European tenders unbundle these elements. Three-tier pricing structure across premium patent-protected biologics, standard biosimilar growth hormones, and economy-tier compounded formulations prevails. Price differentiation hinges on FDA orphan exclusivity status and EMA rare disease designation tier. Cost compression in standard-tier products is intensifying as Midwestern integrated delivery networks consolidate to dual-source contracts. Pediatric endocrinology clinics demonstrate lowest price sensitivity due to established reimbursement pathways; adult transition clinics exhibit highest sensitivity.
Supply Chain Analysis
Active pharmaceutical ingredient supply for recombinant growth hormones rests on contract manufacturing organizations concentrated in the United States, Ireland, and South Korea. Key inputs span genetically engineered cell lines, bioreactor-grade nutrients, and single-use containment systems. Single-source vulnerability concentrates in FDA-approved fill-finish facilities for pediatric-dose formulations. Distribution runs through specialty pharmacy networks with cold-chain certification, bypassing traditional wholesale channels for temperature-sensitive biologics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into hypothalamic-targeting drug discovery platforms is reshaping competitive positioning, with upstream control over peptide formulation capabilities emerging as the decisive capability gap between hormone incumbents and appetite suppression specialists.
For Market Incumbents: Deploy manufacturing scale leverage to secure sole-source contracts with consolidating United States hospital systems before adult transition clinic networks mature. Accelerate backward integration into peptide synthesis capabilities to offset biosimilar pressure on legacy growth hormone portfolios. Counter emerging hyperphagia drug developers by anchoring endocrinology clinic relationships through bundled metabolic monitoring services. For New Entrants and Emerging Players: Melanocortin pathway modulation intellectual property offers entry positioning against established hormone manufacturers with limited CNS-targeting expertise. White-space concentration sits with adult patient segments in Germany and France where transition clinic infrastructure exceeds therapeutic supply. Telemedicine-enabled remote endocrinology consultations present the most penetrable distribution channel for rural United States markets previously excluded from specialized PWS center access. For Investors and Strategic Acquirers: The window for entry favors clinical-stage developers with Phase II hyperphagia endpoints and existing FDA orphan designations. Long-term viability hinges on regulatory harmonization between FDA and EMA biomarker qualification timelines that would enable centralized trial economics. Watch FDA-EMA alignment negotiations on hypothalamic dysfunction endpoints as the inflection signal for multi-region filing feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Phase II hyperphagia endpoints with FDA orphan designation compress regulatory timelines for novel melanocortin modulators. |
| Manufacturing Scale-Up | Bioreactor capacity expansion in Ireland and South Korea secures supply continuity for multi-source growth hormone procurement. |
| Regulatory Approval Pathway | EMA rare disease designation extends market exclusivity periods and accelerates European assessment for appetite suppressant candidates. |
| Pipeline Diversification | Hypothalamic-targeting drug candidates hedge against biosimilar erosion in mature growth hormone franchises. |
| Hospital System Partnership | Sole-source contracts with Midwestern integrated delivery networks lock in procurement volume through transition-of-care program integration. |
Research Methodology
Document review covered FDA orphan drug designations, EMA rare disease submissions, ClinicalTrials.gov protocols, and hospital procurement databases, complemented by interviews with pediatric endocrinologists, formulary directors at United States payers, regulatory affairs leads at biologics manufacturers, and procurement managers at integrated delivery networks. Secondary validation drew from CMS Medicare claims data, GPO contract repositories, and European hospital pharmacy association reports. Bottom-up patient volume estimates triangulated against top-down pharmaceutical revenue disclosures.
Market size outputs reflect segment-level modeling across product type, patient age cohort, therapy area, and delivery mode dimensions throughout the forecast period. CAGRs were derived from longitudinal survival trend projections and regulatory approval probability-weighted revenue forecasts. Key inputs incorporated PMDA pediatric trial requirement timelines, EMA post-market surveillance cost assumptions, and telemedicine penetration rates in rural United States markets.
Several conditions sit outside the modeled scope, including unannounced biosimilar litigation outcomes, sudden FDA manufacturing facility inspection actions, and national health technology assessment reclassifications in European markets. Forecasts reflect assumptions on regulatory harmonization progress and reimbursement pathway stability. A small set of named triggers warrants ongoing watch: FDA-EMA biomarker alignment negotiations, PMDA pediatric trial requirement revisions, and Catholic health system merger completion timelines in the United States Midwest.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Fabry Disease Market
Rare Diseases
Chaple Syndrome Market
Rare Diseases
Zellweger Spectrum Disorders Market
Rare Diseases
Rett Syndrome Market
Rare Diseases
Donohue Syndrome Treatment Market
Rare Diseases
Sarcoidosis Therapeutics Market
Rare Diseases
Muckle-Wells Syndrome Market
Rare Diseases
Krabbe Disease Treatment Market
Rare Diseases
Rare Diseases Treatment Market
Rare Diseases
Phelan-Mcdermid Syndrome Market
Rare Diseases
Arthrogryposis Management Market
Rare Diseases
Behcets Disease Market
Rare Diseases
Canavan Disease Treatment Market
Rare Diseases
Chronic Granulomatous Disease Market
Rare Diseases
Alzheimer Disease Market