
 Hemophagocytic Lymphohistiocytosis Market | 2026-2036
Hemophagocytic Lymphohistiocytosis Market Size, Share, and Industry Trends Forecast 2026-2036
Hemophagocytic Lymphohistiocytosis Market Outlook
The specialized immunologist workforce is bifurcating between academic medical centers and community hospitals, constraining diagnostic capacity outside major metropolitan hubs. Incyte Corporation leverages its JAK inhibitor pipeline to sustain leadership in targeted HLH therapeutics. Swedish Orphan Biovitrum AB (Sobi) anchors European distribution through its rare disease commercial infrastructure. Quest Diagnostics Incorporated competes on esoteric testing volume, operating one of the largest reference laboratory networks for hemophagocytic syndrome biomarker panels.
Hemophagocytic lymphohistiocytosis constitutes a life-threatening hyperinflammatory syndrome driven by unchecked T-cell and macrophage activation, typically characterized by ferritin levels exceeding 10,000 micrograms per liter and soluble IL-2 receptor elevation. The condition demands immediate immunosuppressive intervention to prevent multi-organ failure. Biologics command the deepest margin pools among product types, with anti-IFN-gamma monoclonal antibodies reshaping first-line protocols for primary HLH. Pediatric care applications outpace adult segments in clinical trial enrollment, though chronic management represents an underserved structural opportunity for home healthcare expansion.
The FDA Orphan Drug program and EMA's PRIME designation framework both accelerate HLH therapy development by granting protocol assistance and fee waivers to sponsors. ISO 15189 accreditation requirements shape diagnostic laboratory market access, particularly for soluble CD25 and ferritin quantification assays. Stakeholders must monitor emerging biomarker-guided trial designs that could redefine which patient subsets receive biologic versus chemotherapy-first protocols.
Market Dynamics
The transition from chemotherapy-first protocols to biologic-targeted induction is restructuring treatment algorithms and redistributing value capture across manufacturers, diagnostic laboratories, and specialized infusion centers.
Growth Catalysts
- FDA Orphan Drug Designation:Fee waivers and protocol assistance compress development timelines for rare immune disorder therapeutics, accelerating sponsor entry into HLH indication expansion.
- Pediatric hematology-oncology unit expansion:Tertiary hospitals in the United States are building dedicated HLH treatment protocols, concentrating referral volume and standardizing care pathways.
- Histiocyte Society treatment center density:Dense referral networks in metropolitan hubs improve patient identification and accelerate time-to-diagnosis for hyperinflammatory syndromes.
Market Restraints
- Specialized immunologist workforce bifurcation:Academic medical centers capture diagnostic expertise while community hospitals face capacity constraints, creating geographic access disparities.
- Biologics manufacturing complexity:Anti-IFN-gamma monoclonal antibody production requires single-use bioreactor infrastructure with limited contract manufacturing availability.
- ESLD biomarker assay standardization gaps:Soluble CD25 quantification lacks harmonized reference ranges across ISO 15189-accredited laboratories, complicating multi-site trial enrollment.
Strategic Opportunities
- Home healthcare chronic management:Adult HLH survivor populations require long-term immunosuppression monitoring, creating white space for ambulatory infusion and remote ferritin tracking services.
- EMA PRIME designation leverage:European sponsors accessing accelerated assessment pathways can compress market access negotiations with national health technology assessment bodies.
- Biomarker-guided protocol stratification:Integration of soluble IL-2 receptor kinetics with next-generation sequencing enables precision assignment to biologic versus chemotherapy-first induction.
Industry Challenges
- Pediatric clinical trial enrollment bottlenecks:Limited eligible patient pools across dispersed treatment centers complicate Phase II/III study powering and site activation timelines.
- Multi-organ failure diagnostic latency:Non-specialist emergency departments miss hyperinflammatory syndrome recognition, delaying critical immunosuppressive intervention and compromising outcomes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hemophagocytic Lymphohistiocytosis Market |
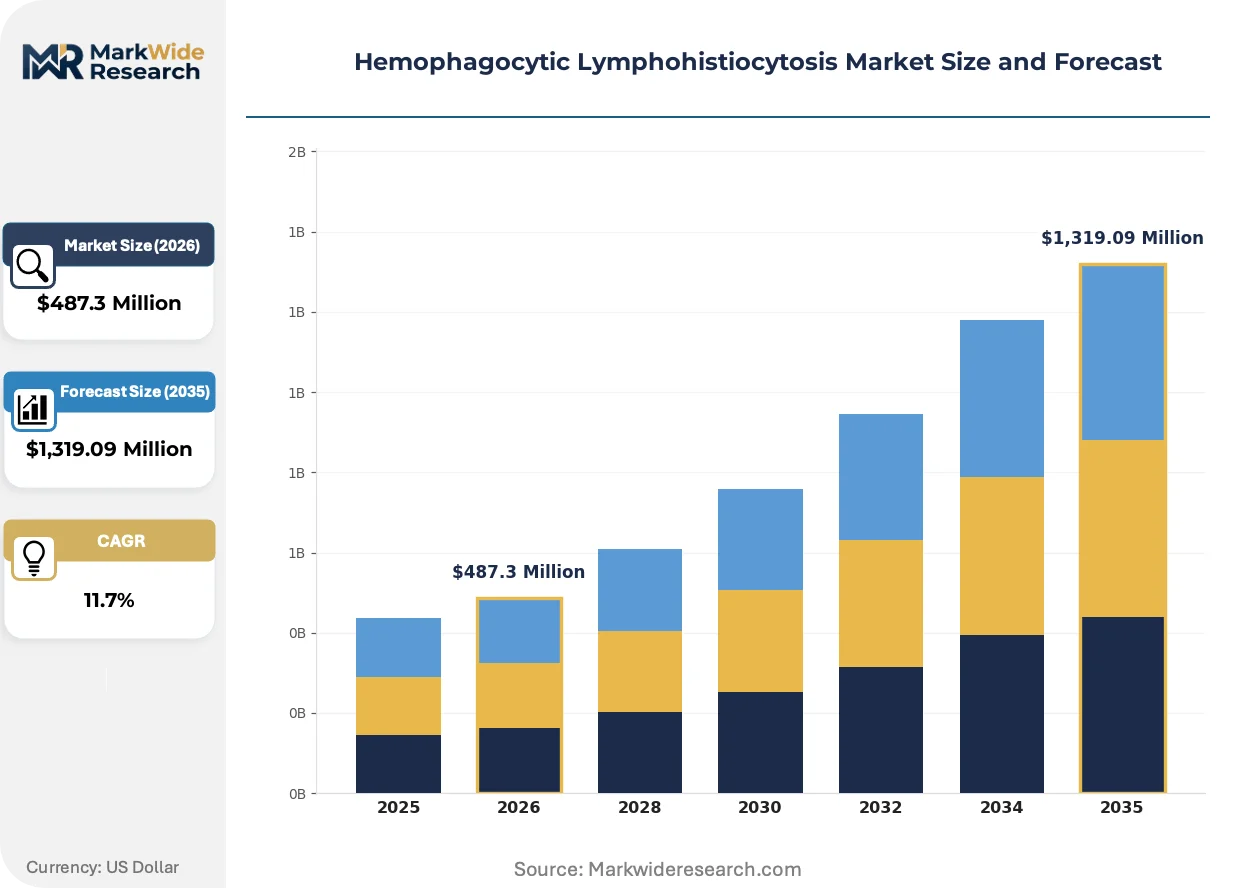
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,319.09 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biologics, Corticosteroids, Chemotherapy Agents, Supportive Care Therapy Area: Oncology, Immunology, Infectious Diseases, Autoimmune Disorders Application: Pediatric Care, Adult Care, Emergency Treatment, Chronic Management End User: Hospitals, Specialty Clinics, Research Institutions, Home Healthcare |
| Companies Covered | TJ Biopharma, Labcorp, Swedish Orphan Biovitrum AB (Sobi), ARUP Laboratories, Quest Diagnostics Incorporated, Electra Therapeutics Inc., AB2 Bio Ltd., Incyte Corporation, Novartis AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hemophagocytic Lymphohistiocytosis Market Strategic Shifts
Precision immunology is compressing the diagnostic-to-treatment interval while regulatory incentives reshape competitive entry patterns across rare disease development.
Anti-IFN-gamma monoclonal antibodies are supplanting etoposide-based induction in primary HLH first-line protocols. Pediatric hematology-oncology units at academic medical centers are adopting these biologics within eighteen months of label expansion. This transition is compressing chemotherapy manufacturing volumes while expanding cold-chain logistics requirements for biologic distribution.
EMA's PRIME designation framework is accelerating HLH therapy assessment through enhanced protocol assistance and accelerated evaluation pathways. Sponsors receiving this designation gain priority access to scientific advice and potential conditional marketing authorization routes. European rare disease commercial infrastructure is responding by building early access programs ahead of formal reimbursement decisions.
Consolidated procurement through integrated delivery networks is displacing hospital-level purchasing autonomy for biologic therapeutics. Large United States health systems are centralizing formulary decisions for high-cost immunomodulators, compressing vendor fragmentation. This concentration is most visible in the Northeast and Midwest, where referral network density enables volume-based contracting leverage.
Hemophagocytic Lymphohistiocytosis Market Segmentation
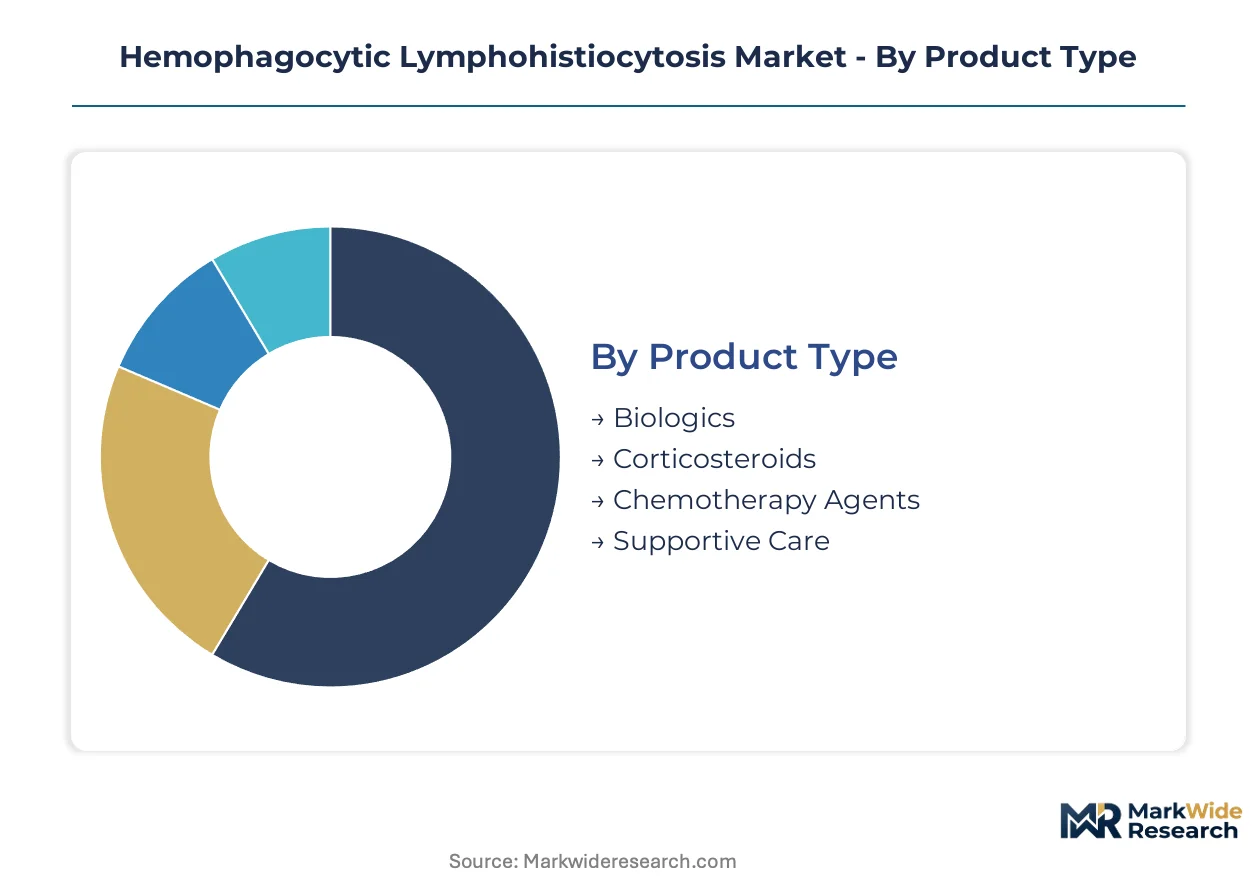
HLH market segmentation reveals how therapeutic modality, patient population, and care setting interact to determine access patterns and commercial viability. Channel configurations vary sharply across segments, with biologics flowing through restricted distribution networks while supportive care penetrates outpatient retail.
Product Type:
Channel-mix patterns diverge sharply: biologics move through specialty pharmacy and hospital infusion centers under REMS protocols, while corticosteroids and supportive care flow through broader wholesale and retail channels.
- Biologics:Anti-IFN-gamma monoclonal antibodies and JAK inhibitors require cold-chain logistics and specialty pharmacy distribution. Demand concentrates in pediatric hematology-oncology units at academic medical centers with Histiocyte Society accreditation, driven by FDA Orphan Drug Designation accelerating sponsor market entry.
- Corticosteroids:Dexamethasone and methylprednisolone serve as bridging immunosuppression in induction protocols. These agents reach community hospitals through standard wholesale distribution, though tertiary centers capture the highest-margin protocol-driven volumes.
- Chemotherapy Agents:Etoposide-based regimens still anchor salvage therapy and secondary HLH protocols.
- Supportive Care:IVIG, albumin, and antimicrobial prophylaxis complete therapeutic bundles.
By volume, corticosteroids lead. By growth pace, biologics are climbing the fastest.
Therapy Area:
Cost tier stratification shapes reimbursement negotiations, with oncology commanding premium pricing and immunology accessing distinct funding pools through rare disease pathways.
- Oncology:Malignancy-associated HLH drives the deepest clinical trial investment and protocol standardization. Pediatric leukemia-lymphoma programs at tertiary hospitals generate concentrated demand for combined chemo-immunotherapy approaches.
- Immunology:Primary HLH and autoinflammatory disorders attract biologic-first treatment algorithms. Academic medical centers with dedicated histiocytosis programs capture this high-margin segment through specialized diagnostic workflows.
- Infectious Diseases:EBV-triggered and other infection-driven HLH cases require rapid diagnostic differentiation.
- Autoimmune Disorders:Macrophage activation syndrome overlaps drive rheumatology-oncology collaboration.
Oncology captures the largest revenue pool. Immunology shows the steepest expansion trajectory.
Application:
Patient age and acuity determine site-of-care economics, with emergency treatment generating the highest per-episode costs and chronic management offering subscription-like revenue stability.
- Pediatric Care:Primary HLH predominates in infants and children under two years, demanding immediate hematopoietic stem cell transplant evaluation. Children's hospitals with dedicated HLH protocols capture this segment through rapid diagnostic ferritin and soluble CD25 testing.
- Adult Care:Secondary HLH from malignancy or infection presents diagnostic complexity in emergency departments. Academic medical centers with adult HLH treatment protocols concentrate this historically underserved population.
- Emergency Treatment:Multi-organ failure recognition in non-specialist settings remains a critical bottleneck.
- Chronic Management:Post-induction immunosuppression and transplant surveillance create ambulatory service opportunities.
Emergency treatment dominates episode value. Chronic management is gaining share fastest.
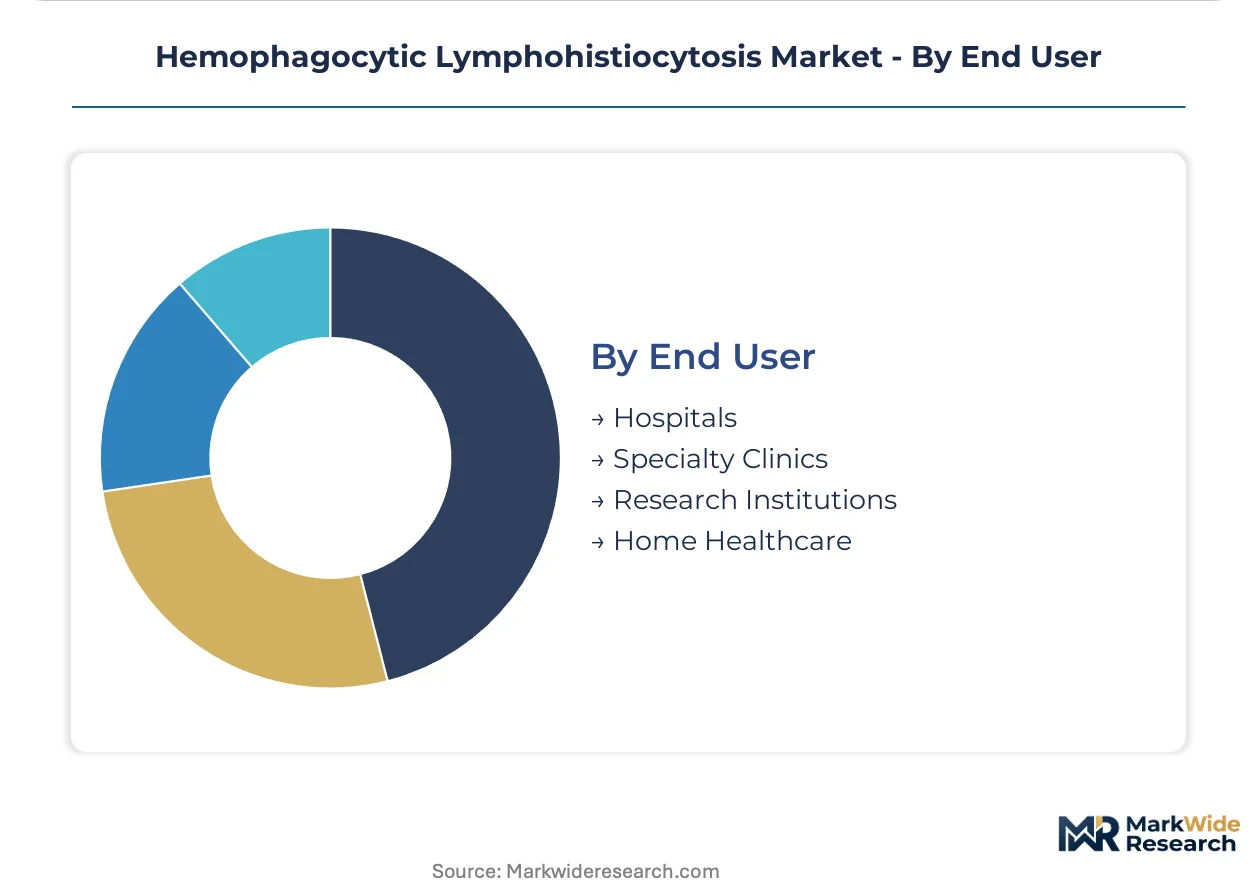
End User:
Customer type determines procurement leverage and protocol influence, with integrated delivery networks centralizing high-cost biologic purchasing while research institutions shape future standard-of-care.
- Hospitals:Tertiary academic medical centers with pediatric hematology-oncology units anchor HLH care volume. These institutions command formulary decisions for anti-IFN-gamma biologics through consolidated procurement within large health systems.
- Specialty Clinics:Histiocytosis-focused outpatient centers manage chronic immunosuppression and transplant surveillance. These sites generate recurring revenue through scheduled ferritin monitoring and infusion services.
- Research Institutions:Clinical trial sites drive protocol innovation and biomarker validation.
- Home Healthcare:Ambulatory infusion and remote monitoring services target adult survivor populations.
Hospitals lead by patient volume. Home healthcare is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States treatment protocols emphasize biologic-first induction for primary HLH, while European centers maintain more heterogeneous chemotherapy-biologic sequencing. Asian markets concentrate diagnostic capacity in national referral hospitals with distinct regulatory acceleration pathways.
United States
Pediatric hematology-oncology units at tertiary hospitals drive concentrated demand for anti-IFN-gamma monoclonal antibodies. FDA Orphan Drug Designation compresses development timelines through protocol assistance and fee waivers. Boston and New York metropolitan clusters anchor Histiocyte Society-accredited treatment centers with dense referral networks.
Germany
Academic medical centers in Baden-Württemberg and Bavaria standardize HLH diagnostic workflows with soluble CD25 quantification. EMA PRIME designation accelerates assessment pathways for rare disease therapeutics. Heidelberg and Munich university hospitals concentrate clinical trial enrollment for biologic induction protocols.
United Kingdom
London and Birmingham pediatric hematology networks coordinate national HLH treatment guidelines. NICE technology appraisals shape reimbursement access for high-cost immunomodulators. Oxford and Cambridge research institutions anchor biomarker validation studies for protocol stratification.
Japan
PMDA Sakigake designation accelerates HLH therapy review for severe unmet medical needs. Tokyo and Osaka university hospitals concentrate diagnostic expertise for hyperinflammatory syndrome differentiation. Kansai region medical centers lead adult HLH protocol development historically underrepresented in pediatric-dominated research.
Switzerland
Swissmedic expedited pathways support rare disease therapeutic development with enhanced scientific advice. Basel and Zurich pharmaceutical clusters anchor European commercial infrastructure for biologic distribution. Geneva university hospitals coordinate cross-border referral networks for complex HLH cases.
Hemophagocytic Lymphohistiocytosis Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with biologics manufacturers commanding premium positioning through orphan drug exclusivity. Diagnostic laboratories compete on esoteric testing volume and ISO 15189 accreditation breadth. Strategic moves concentrate on portfolio diversification into complementary immunomodulators and geographic expansion through rare disease commercial partnerships.
Within the biologics development tier, Incyte Corporation and Swedish Orphan Biovitrum AB (Sobi) exemplify integrated rare disease players with established JAK inhibitor and monoclonal antibody pipelines. Among diagnostic service providers, Quest Diagnostics Incorporated anchors reference laboratory scale for hemophagocytic syndrome biomarker panels. TJ Biopharma represents emerging biotechnology entrants targeting cytokine modulation pathways.
| Leading Market Players |
|---|
| TJ Biopharma |
| Labcorp |
| Swedish Orphan Biovitrum AB (Sobi) |
| ARUP Laboratories |
| Quest Diagnostics Incorporated |
| Electra Therapeutics Inc. |
| AB2 Bio Ltd. |
| Incyte Corporation |
| Novartis AG |
| Others |
Value Chain & Pricing Dynamics
Single-use bioreactor capacity utilization at contract manufacturing organizations shapes both supply availability and price floors for anti-IFN-gamma monoclonal antibodies. Scale economies in cold-chain logistics concentrate negotiating leverage among integrated health systems while fragmenting access for smaller pediatric treatment centers.
Pricing Analysis
Long-term offtake agreements between integrated delivery networks and biologics manufacturers dominate procurement for anti-IFN-gamma therapies, compressing spot-market availability. Price differentiation rests on Histiocyte Society accreditation tier and volume commitment scale, with tertiary academic centers commanding standard-plus rebates unavailable to community hospitals. Cost compression in corticosteroid bridging therapy intensifies as biosimilar dexamethasone entrants multiply. Pediatric hematology-oncology units show lowest price sensitivity due to protocol-driven formulary lock-in, while adult emergency departments exhibit highest sensitivity where diagnostic uncertainty delays committed purchasing.
Supply Chain Analysis
The United States and Switzerland anchor biologics manufacturing through FDA-inspected facilities and Swissmedic-authorized production sites. Raw material dependencies center on Chinese-sourced recombinant cell lines, German-engineered single-use bioreactor systems, and Singapore-based cold-chain packaging. Single-source vulnerability in anti-IFN-gamma fill-finish capacity creates bottleneck risk during pediatric protocol expansion waves. Distribution runs through restricted specialty pharmacy networks with REMS-mandated patient tracking, bypassing standard wholesale channels entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment through FDA Orphan Drug exclusivity periods constructs formidable defensive moats for established HLH therapeutics developers. Switching costs between induction protocols lock treatment centers into sustained vendor relationships.
For Market Incumbents: Secure backward integration into diagnostic biomarker assay development to capture protocol-standardization influence. Expand manufacturing capacity in Basel-region biologics clusters ahead of EMA PRIME designation acceleration waves. Emerging JAK inhibitor entrants threaten margin compression in secondary HLH salvage therapy. For New Entrants and Emerging Players: Adult chronic management service gaps expose under-served ambulatory infusion demand post-transplant surveillance. Home healthcare ferritin monitoring represents the most penetrable segment, accessible through remote patient platform partnerships with existing specialty pharmacy networks. Target rheumatology-oncology collaboration protocols for macrophage activation syndrome overlap indications. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors platform biologics developers with cytokine modulation pipelines spanning multiple rare immune indications. Five-to-ten year viability hinges on biomarker-guided protocol stratification capabilities rather than single-product dominance. Acquisition target archetype: integrated diagnostic-therapeutic developers with ISO 15189-accredited laboratory networks. The signal to watch is soluble IL-2 receptor kinetic assay adoption rates across Histiocyte Society treatment centers.| Strategic Initiative | Industry Significance |
|---|---|
| Biomarker-Guided Protocol Stratification | Precision assignment to biologic versus chemotherapy-first induction reshapes competitive positioning at academic medical centers. |
| EMA PRIME Designation Acceleration | Enhanced protocol assistance compresses market access timelines for European rare disease commercial infrastructure expansion. |
| Integrated Delivery Network Consolidation | Centralized formulary decisions for high-cost immunomodulators displace hospital-level purchasing autonomy in Northeast and Midwest clusters. |
| Home Healthcare Chronic Management Buildout | Ambulatory infusion and remote ferritin tracking services capture adult HLH survivor populations previously lost to follow-up. |
| Diagnostic Laboratory Accreditation Expansion | ISO 15189 certification for soluble CD25 quantification secures multi-site clinical trial enrollment access and protocol influence. |
Study Parameters
Cross-validation between primary interviews with pediatric hematology-oncology directors, regulatory affairs specialists at rare disease sponsors, formulary directors at integrated delivery networks, and reference laboratory operations managers anchors the qualitative findings. Secondary validation draws from FDA Orphan Drug Designation filings, EMA PRIME designation decisions, ClinicalTrials.gov protocol registrations, and hospital procurement database extracts. Bottom-up demand modeling for biologic induction protocols triangulates against top-down market sizing from manufacturer reported volumes and distributor channel data.
Sensitivity analysis around pediatric clinical trial enrollment assumptions and adult diagnostic latency parameters tests forecast robustness across the projection horizon. Segmentation dimensions modeled include therapeutic modality, patient age category, care setting acuity, and regional regulatory cluster. CAGRs derive from logarithmic interpolation of validated baseline and terminal year estimates, incorporating biomarker assay standardization timelines and health system consolidation trajectories as HLH-specific forecast inputs.
Forecasts assume regulatory continuity in FDA Orphan Drug and EMA PRIME frameworks; material policy shifts would require re-modeling. Diagnostic protocol adoption rates and biologics manufacturing capacity expansion schedules represent specific revision triggers. Recalibration cycles align with material shifts in Histiocyte Society treatment center accreditation density and soluble CD25 assay harmonization progress.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rare Diseases
Dystrophic Epidermolysis Bullosa Management Market
Rare Diseases
Chronic Granulomatous Disease Market
Rare Diseases
Arthrogryposis Management Market
Rare Diseases
Churg Strauss Syndrome Market
Rare Diseases
Cri-Du-Chat Syndrome Treatment Market
Rare Diseases
Aarskog Scott Syndrome Treatment Market
Rare Diseases
Global Rare Hemophilia Factors Market
Rare Diseases
Fragile X Syndrome Market
Rare Diseases
Gastrointestinal Rare Diseases Treatment Market
Rare Diseases
Global Neuromyelitis Optica Spectrum Disorder Market
Rare Diseases
North America Rett Syndrome Market
Rare Diseases
Prader-Willi Syndrome (PWS) Market
Rare Diseases
Middle East and Africa Rett Syndrome Market
Rare Diseases
Chronic Granulomatous Disease (CGD) Management Market
Rare Diseases
Alpha-1 Antitrypsin Deficiency Market
Rare Diseases
Dravet Syndrome Market