
 Global in Circuit Tester Market | 2026-2036
Global in Circuit Tester Market Size, Share, and Industry Trends Forecast 2026-2036
Global in Circuit Tester Market Intelligence
EU RoHS and REACH compliance is restructuring capital allocation for test equipment vendors serving European electronics manufacturers. Keysight Technologies leverages its RF testing heritage to anchor premium positioning in aerospace and defense verification workflows. Teradyne Inc. sustains manufacturing scale advantages through vertically controlled supply chains for automated handler integration. SPEA S.p.A. specializes in high-throughput modular architectures that dominate European automotive PCB test floors.
An in-circuit tester electrically verifies populated printed circuit boards by measuring component values and detecting solder defects without powering the assembly. These systems typically operate at test speeds exceeding thousands of nodes per second using bed-of-nails fixtures with spring-loaded probes contacting pre-designed test pads. Automated testers capture the dominant share of factory-floor deployments where throughput economics favor capital-intensive inline configurations over handheld alternatives. Boundary scan technology leads technology segmentation due to its compatibility with miniaturized surface-mount packages that resist physical probe access, while RF testing commands premium margins from 5G baseband and radar module validation.
FDA quality system regulations for medical devices, FAA DO-160 environmental qualification standards, and EU CE marking under the EMC Directive collectively elevate test coverage requirements for mission-critical electronics. China's GB standards and MIIT equipment certification add parallel compliance layers for vendors accessing domestic production networks. Stakeholders must monitor how IEC 61508 functional safety derivatives propagate beyond automotive into industrial automation and medical device test protocols.
Market Dynamics
Automotive functional safety mandates under ISO 26262 are compressing test cycle timelines and forcing capital redeployment toward inline verification systems with higher node-per-second throughput.
Growth Catalysts
- ISO 26262 functional safety:Automotive OEMs in Germany and Japan mandate in-circuit verification for power electronics and ADAS modules, expanding factory-floor tester procurement.
- 5G infrastructure buildout:China's MIIT equipment certification drives domestic PCB production scaling for baseband and antenna modules, concentrating equipment demand.
- Bed-of-nails fixture advancement:Spring-loaded probe arrays now exceed thousands of nodes per second, enabling parallel test execution that reduces per-unit verification cost.
Market Restraints
- Fixture fabrication cost volatility:Precision-machined aluminum and spring-loaded contact probes face raw material price pressure from aerospace and medical device competing demand.
- Probe access limitation:Miniaturized surface-mount packages below 0.4mm pitch resist physical bed-of-nails contact, forcing expensive boundary scan augmentation.
- EU RoHS and REACH compliance:European electronics manufacturers restructure capital allocation toward lead-free solder verification workflows, elevating equipment qualification burden.
Strategic Opportunities
- Industrial automation convergence:IEC 61508 functional safety derivatives propagate beyond automotive into factory automation controllers, opening new verification verticals.
- RF module validation:5G baseband and radar modules command premium margins for aerospace and defense verification workflows with specialized signal integrity testing.
- Medical device certification:FDA quality system regulations elevate test coverage requirements for mission-critical electronics in diagnostic and therapeutic equipment.
Industry Challenges
- Boundary scan integration complexity:Legacy test floors require firmware and fixture retrofitting to accommodate JTAG-based verification protocols alongside traditional in-circuit methods.
- Handler synchronization:Automated inline configurations demand precise timing alignment between bed-of-nails actuation and robotic board handling, compressing maintenance windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global in Circuit Tester Market |
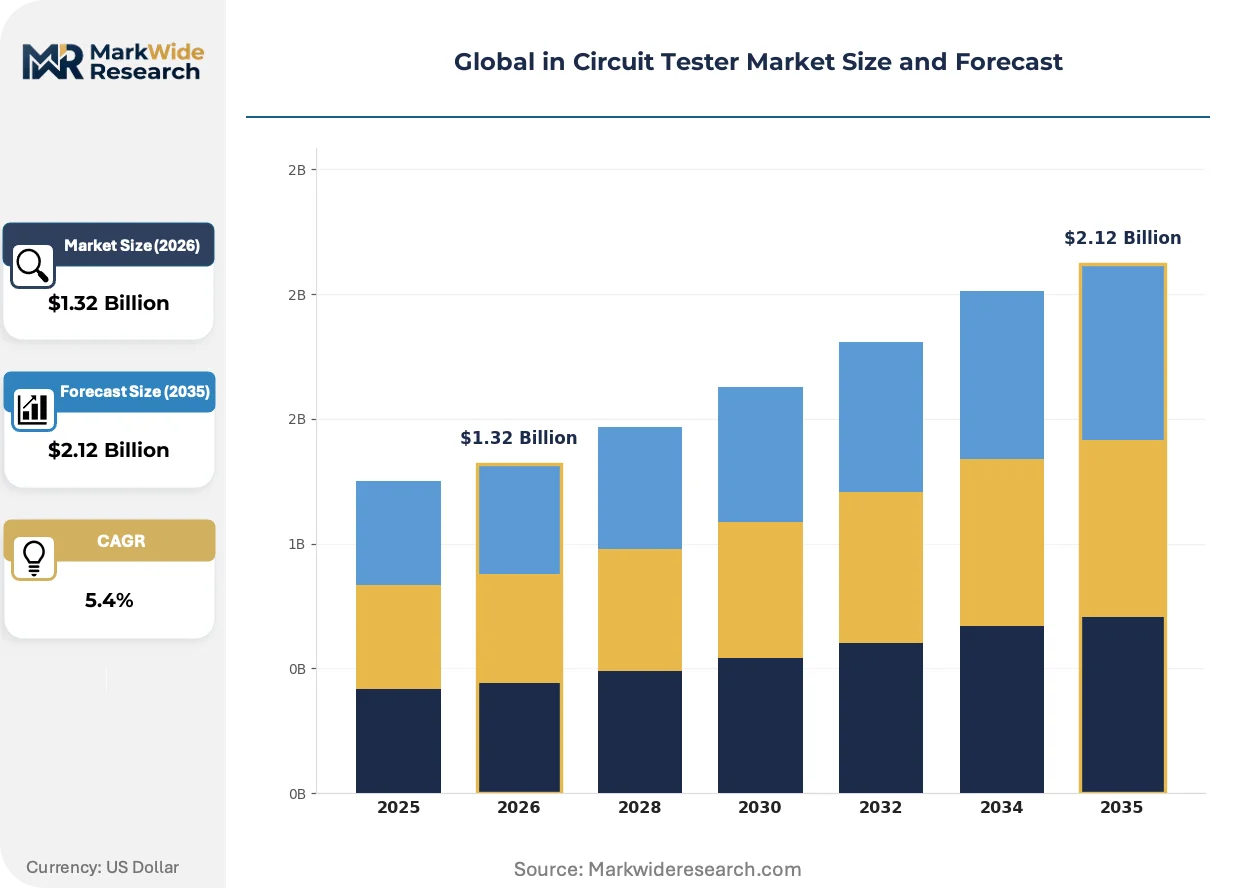
| Market Size in 2026 | $1.32 Billion |
| Market Size in 2035 | $2.12 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Testers, Modular Testers, Automated Testers, Handheld Testers Technology: Boundary Scan, Functional Testing, RF Testing, Digital Testing End User: Consumer Electronics, Automotive, Aerospace, Medical Devices Deployment: On-Premises, Cloud-Based, Hybrid, Integrated Systems |
| Companies Covered | Teradyne Inc., Keysight Technologies, SPEA S.p.A., Test Research, Inc., Digitaltest GmbH, Hioki E.E. Corporation, Acculogic Inc., Kyoritsu Test System Corporation, Seica S.p.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global in Circuit Tester Market Strategic Shifts & Innovations
Test system architectures are fragmenting from monolithic platforms toward configurable subsystems that accommodate rapid product changeovers in high-mix manufacturing environments.
Modular test head designs with swappable probe cards and software-defined measurement channels are modularizing capital deployment across automotive and telecommunications contract manufacturers. Tier-one EMS providers in South Korea and Taiwan adopt these architectures to avoid dedicated fixture obsolescence when PCB designs iterate quarterly. The shift compresses equipment amortization periods while preserving test coverage consistency across product generations.
EU CE marking under the EMC Directive now requires radiated emission pre-compliance screening during in-circuit verification, not merely post-assembly functional test. Electronics manufacturers serving European industrial and medical markets integrate spectrum analyzers and shielded enclosures into bed-of-nails stations. Automotive PCB test floors in Germany and France respond fastest, driven by OEM supplier qualification mandates that bundle electromagnetic compatibility with solder joint integrity.
Capital equipment purchasing has migrated from outright ownership toward performance-guaranteed service agreements where verification throughput, not hardware depreciation, determines vendor compensation. Tier-two automotive suppliers in Mexico and Eastern Europe favor this model to align test capacity with volatile production schedules. The arrangement transfers fixture maintenance and calibration liability to equipment vendors, concentrating service capability with vertically integrated manufacturers.
Global in Circuit Tester Market Segmentation
In-circuit tester procurement decisions hinge on throughput requirements, probe access constraints, and integration complexity with existing factory automation. Segmentation reveals where capital concentrates versus where technology is displacing legacy methods.
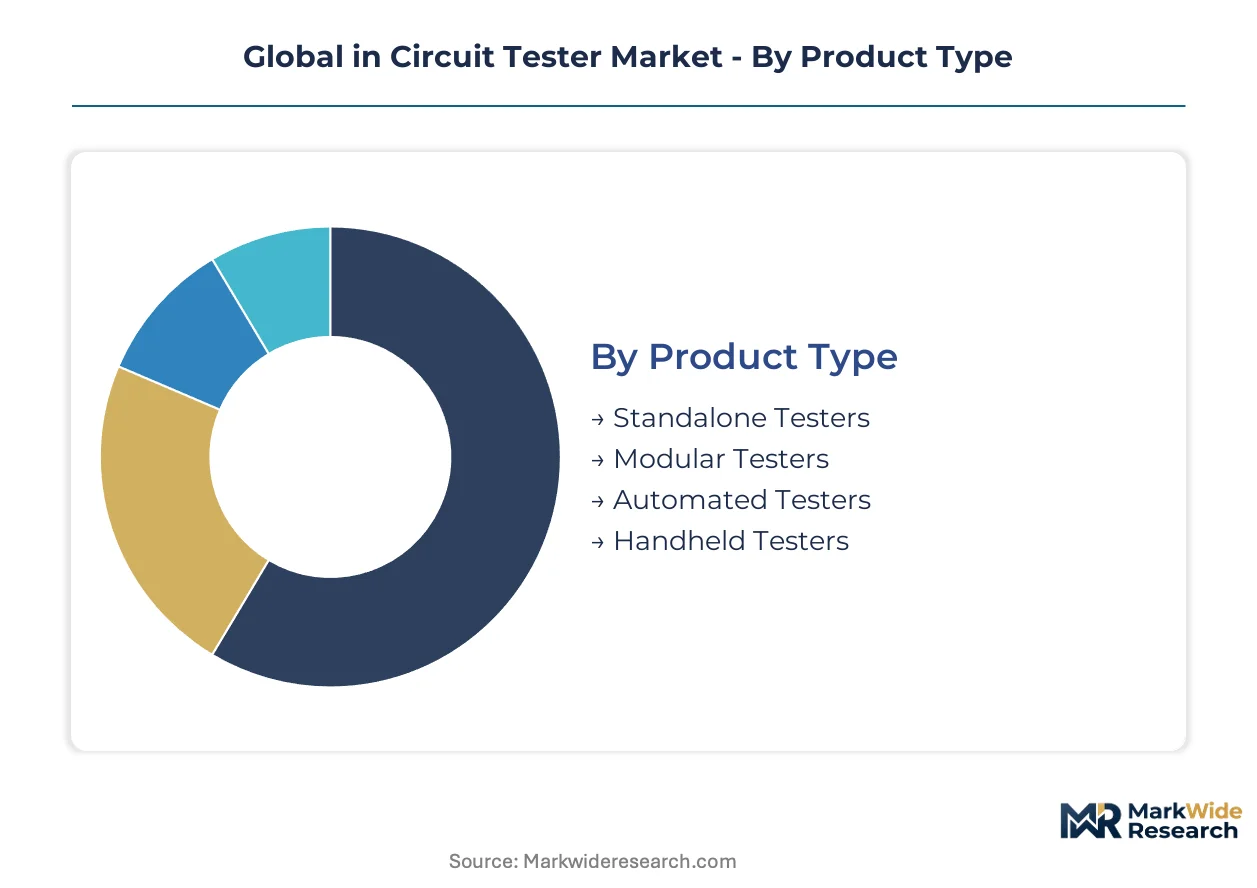
Product Type:
Capital intensity varies sharply across configurations, with inline automated systems demanding fixture fabrication, handler integration, and facility retrofitting that handheld units avoid entirely.
- Automated Testers:Inline configurations with bed-of-nails fixtures and robotic board handling dominate automotive PCB test floors in Germany and Japan. ISO 26262 functional safety mandates compress cycle times and force capital redeployment toward these high-throughput systems.
- Modular Testers:Swappable probe cards and software-defined measurement channels enable rapid product changeovers for high-mix contract manufacturers in South Korea and Taiwan. Tier-one EMS providers adopt these architectures to avoid dedicated fixture obsolescence when PCB designs iterate quarterly.
- Standalone Testers:Self-contained units serve mid-volume electronics manufacturers requiring dedicated test stations without handler synchronization complexity.
- Handheld Testers:Portable diagnostic units address field repair and prototype verification where factory-floor throughput economics do not justify inline capital deployment.
Most installed capacity flows through Automated Testers. Expansion is steepest in Modular Testers.
Technology:
Technical differentiation centers on physical probe access versus non-contact verification methods, with miniaturization trends favoring certain protocols.
- Boundary Scan:JTAG-based verification protocols accommodate surface-mount packages below 0.4mm pitch that resist physical bed-of-nails contact. Legacy test floors in European automotive and industrial automation require firmware retrofitting to integrate this method alongside traditional in-circuit approaches.
- RF Testing:Signal integrity validation for 5G baseband and radar modules commands premium margins in aerospace and defense workflows. China's MIIT equipment certification drives domestic demand for these specialized capabilities.
- Functional Testing:Power-on verification of assembled PCBs detects integration failures that structural tests miss, serving medical device manufacturers under FDA quality system regulations.
- Digital Testing:Logic-level verification of digital ICs and bus architectures supports consumer electronics production scaling for 5G infrastructure.
Boundary Scan captures the dominant share of new technology adoption. RF Testing is gaining share fastest among premium-margin segments.
End User:
Regulatory stringency and production scale create divergent equipment specifications across vertical applications.
- Automotive:Power electronics and ADAS module verification under ISO 26262 functional safety mandates drives factory-floor tester procurement by OEMs and Tier-one suppliers in Germany and Japan.
- Consumer Electronics:High-volume PCB production for smartphones and telecommunications equipment concentrates demand in China and Taiwan, where MIIT certification and rapid design iteration shape equipment specifications.
- Aerospace:FAA DO-160 environmental qualification and mission-critical reliability requirements elevate test coverage standards for avionics and satellite electronics.
- Medical Devices:FDA quality system regulations and EU MDR compliance impose traceability and documentation burdens on diagnostic and therapeutic equipment manufacturers.
Automotive accounts for the largest installed base. Medical Devices shows the steepest expansion trajectory as IEC 61508 derivatives propagate beyond automotive.
Deployment:
Data architecture choices determine integration complexity with manufacturing execution systems and remote diagnostics capabilities.
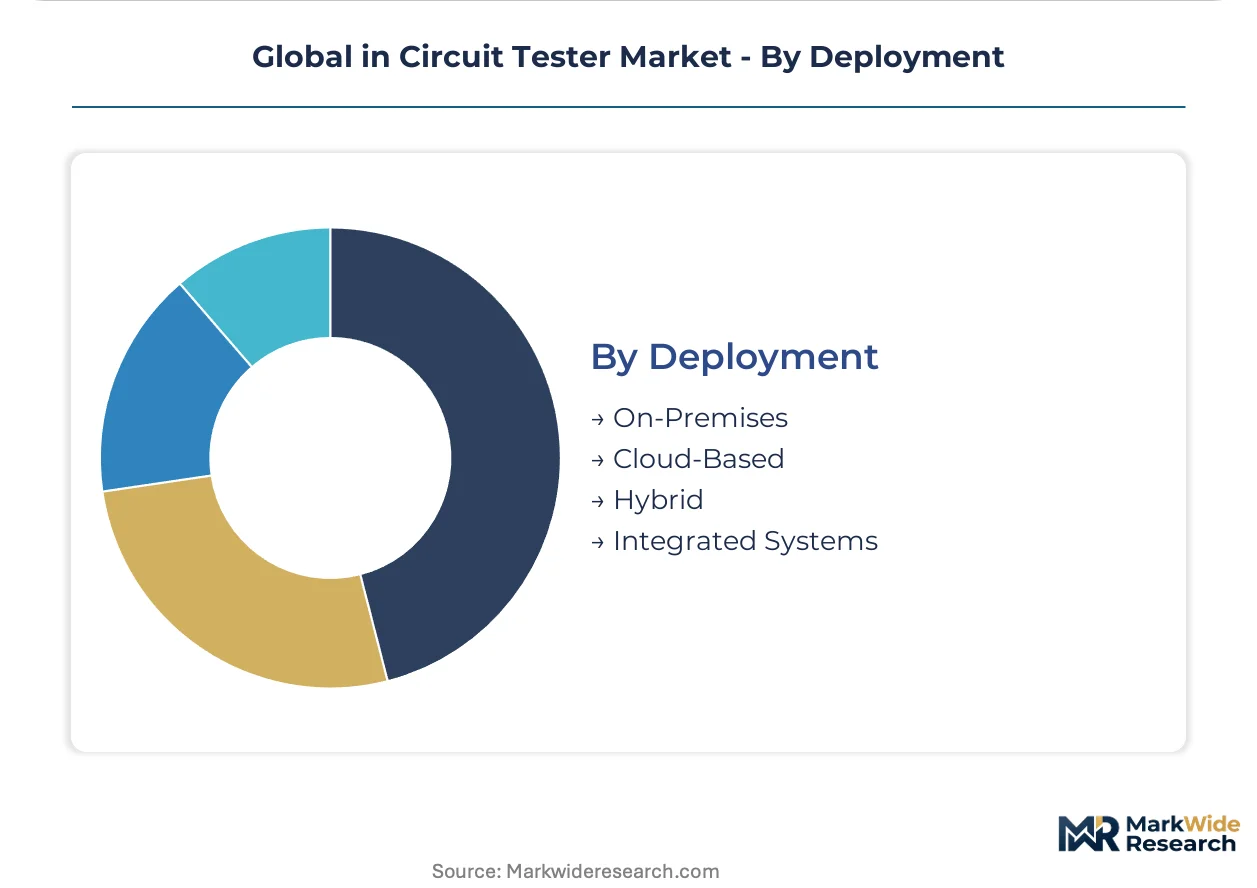
- On-Premises:Local test data storage and processing remains standard for aerospace and medical device manufacturers with stringent data sovereignty and security requirements.
- Integrated Systems:Tight coupling with factory automation controllers and ERP platforms serves high-volume automotive and consumer electronics producers seeking real-time quality feedback loops.
- Hybrid:Split architectures process sensitive test data locally while pushing analytics to cloud infrastructure, accommodating European GDPR constraints and Chinese data localization requirements.
- Cloud-Based:Remote test program management and predictive maintenance analytics attract Tier-two automotive suppliers in Mexico and Eastern Europe seeking to align test capacity with volatile production schedules.
On-Premises retains the dominant installed footprint. Hybrid deployment is climbing the fastest as manufacturers navigate cross-border data governance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled electronics manufacturing engineers concentrate in Germany's automotive corridor, Japan's precision equipment belt, and China's Pearl River Delta, anchoring regional tester demand patterns.
China
Domestic PCB production for 5G base stations and EV power modules drives equipment procurement at unprecedented scale. MIIT equipment certification mandates rigorous pre-market testing that domestic manufacturers must satisfy. Shenzhen and Dongguan clusters host contract manufacturers scaling automated inline verification systems for telecommunications exports.
Germany
Automotive OEM supplier networks in Bavaria and Baden-Württemberg mandate ISO 26262-compliant verification for ADAS and power electronics modules. KBA oversight of functional safety certification elevates test coverage requirements throughout the supply chain. Stuttgart and Ingolstadt production hubs concentrate bed-of-nails installations for Tier-one powertrain suppliers.
Japan
Precision equipment manufacturers in Nagoya and Tokyo metropolitan areas sustain demand for high-throughput modular architectures. METI industrial policy supports domestic production of advanced semiconductor test equipment. Toyota City and Hamamatsu industrial zones anchor automotive electronics verification capacity for hybrid and electric vehicle programs.
United States
Aerospace and defense contractors in Southern California and Texas command premium RF testing capabilities for radar and satellite electronics. FAA DO-160 environmental qualification standards impose stringent verification protocols on avionics suppliers. Dallas-Fort Worth and Greater Boston clusters concentrate mission-critical electronics manufacturing requiring traceable test documentation.
South Korea
Memory semiconductor and display panel manufacturers in Gyeonggi Province and Busan-Ulsan region adopt rapid product changeover architectures. MFDS medical device regulations for diagnostic equipment create parallel demand for FDA-aligned verification systems. Suwon and Pyeongtaek industrial complexes host EMS providers serving global consumer electronics brands with quarterly design iterations.
Global in Circuit Tester Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across distinct technology tiers, creating a stratified vendor ecosystem. Market structure consolidates around equipment vendors with captive fixture fabrication capabilities and vertically controlled supply chains. Three archetypes dominate: full-system integrators with automated handler capabilities, modular architecture specialists serving high-mix contract manufacturers, and regional champions with strong domestic service networks. Competitive moves center on strategic partnerships for software-defined measurement channels and selective capacity expansion in Mexico and Eastern Europe to serve nearshored automotive production.
Within the premium-system tier, Teradyne Inc. and Keysight Technologies occupy positions defined by scale and RF testing heritage respectively. SPEA S.p.A. exemplifies the European modular specialist archetype with concentrated presence in automotive PCB test floors. These three anchors represent distinct strategic postures: North American conglomerate diversification, precision instrumentation legacy, and regional manufacturing proximity.
| Leading Market Players |
|---|
| Teradyne Inc. |
| Keysight Technologies |
| SPEA S.p.A. |
| Test Research, Inc. |
| Digitaltest GmbH |
| Hioki E.E. Corporation |
| Acculogic Inc. |
| Kyoritsu Test System Corporation |
| Seica S.p.A. |
| Others |
Cost & Logistics Intelligence
Skilled test fixture engineers in Germany's automotive corridor command wage premiums that compress margin spreads between premium automated systems and mid-tier modular configurations. Labor-cost differentials between Bavarian production hubs and Eastern European service centers widen pricing-tier spreads for European buyers seeking ISO 26262-compliant verification workflows.
Pricing Analysis
Equipment procurement splits sharply between capital-sale ownership and performance-guaranteed service agreements where throughput metrics determine vendor compensation. Three-tier pricing structure across premium, standard, and economy levels separates aerospace RF validation systems from automotive inline configurations and handheld diagnostic units. Price differentiation hinges on certification grade for functional safety compliance and after-sales service bundling that transfers fixture maintenance liability to vendors. Pricing pressure stems from raw material volatility in precision-machined aluminum and spring-loaded contact probes. Tier-two automotive suppliers in Mexico exhibit highest price sensitivity; aerospace contractors in Southern California show least.
Supply Chain Analysis
Dual-sourcing requirements from automotive OEMs in Germany and Japan mandate multi-supplier qualification for bed-of-nails fixtures and automated handler subsystems. Manufacturing concentrates in Germany, Japan, and China. Component sourcing draws from Taiwan for precision probes, Switzerland for high-density interconnect substrates, and South Korea for robotic handling modules. Single-source vulnerability persists in specialty spring alloys for contact probes. Distribution runs through vertically integrated equipment vendors with captive fixture fabrication capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where functional safety certification costs in Germany run substantially higher than equivalent MIIT compliance pathways in China, creating divergent capital deployment strategies.
For Market Incumbents: Lock in fixture fabrication scale advantages through backward integration into precision-machining capacity. Secure long-term probe alloy supply agreements to neutralize commodity volatility. Defend against modular architecture specialists by embedding software-defined measurement channels that accelerate product changeover velocity for high-mix contract manufacturers.
For New Entrants and Emerging Players: Boundary scan firmware retrofitting for legacy European automotive test floors offers immediate white-space access. Target medical device verification verticals where FDA quality system regulations elevate test coverage requirements and incumbent presence remains thin. Pursue cloud-based predictive maintenance analytics as the primary go-to-market angle for Tier-two suppliers seeking capacity flexibility.
For Investors and Strategic Acquirers: Semiconductor test equipment conglomerates are the most active acquirers in this space, consolidating modular architecture specialists to fill portfolio gaps. Five-to-ten year viability hinges on RF testing capabilities for 5G and radar module validation. Monitor IEC 61508 propagation into industrial automation as the inflection signal for medical device verification demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Test Head Development | Swappable probe cards enable quarterly PCB design iterations for Taiwanese EMS providers. |
| RF Testing Capability Expansion | Signal integrity validation captures premium margins from China's MIIT-certified 5G baseband production. |
| Cloud-Based Service Agreement Launch | Throughput-based pricing aligns test capacity with volatile Mexican automotive supplier schedules. |
| Fixture Fabrication Backward Integration | In-house aluminum machining neutralizes aerospace competing demand for precision components. |
| Boundary Scan Firmware Retrofit | JTAG integration opens legacy European automotive test floors to non-contact verification protocols. |
Research Approach
Direct dialogue with test floor managers at Tier-one automotive suppliers, EMS procurement directors, semiconductor equipment engineers, and regulatory compliance officers grounded qualitative findings. Secondary validation drew from SEC 10-K filings of diversified test equipment vendors, MIIT equipment certification databases, ISO 26262 auditor disclosures, and customs records for precision-machined fixture components. Bottom-up and top-down triangulation cross-checked equipment shipment data against PCB production scaling metrics.
Bottom-up modeling aggregated segment-level demand across product type, technology protocol, end-user vertical, and deployment architecture dimensions. Top-down constraints calibrated aggregate market expansion against capital expenditure patterns in automotive electronics and telecommunications infrastructure. CAGRs derived from regression analysis of historical equipment procurement cycles mapped to regulatory mandate implementation timelines. Forecast inputs incorporated ISO 26262 adoption curves and 5G base station deployment trajectories across the analysis window.
The model holds under stable functional safety regulatory enforcement and continuous PCB miniaturization trends; deviation in automotive platform electrification pace or probe access technology breakthroughs would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Creep and Stress Rupture Testers Market
Test and Measurement
Field Inspection Tester Market
Test and Measurement
Automated Ultrasonic Testing Market
Test and Measurement
Ceramic Tester Market
Test and Measurement
Fuel Capacitance Test Equipment Market
Test and Measurement
Optical Wafer Inspection Systems Market
Test and Measurement
State Transition Testing Market
Test and Measurement
Resonant Testing Machines Market
Test and Measurement
Electromagnetic Compatibility Test Equipment and Testing Services Market
Test and Measurement
Bursting Strength Tester Market
Test and Measurement
Automated Optical Inspection (AOI) Equipment Market
Test and Measurement
Global Arbitrary Waveform Generator Market
Test and Measurement
Edge Computing Enclosure Environmental Stress Test Equipment Market
Test and Measurement
Tensile Testers Market
Test and Measurement
Bit Error Rate Tester Market
Test and Measurement
Radio Frequency Test Equipment Market