
 Calibrator Market | 2026-2036
Calibrator Market Size, Share, and Industry Trends Forecast 2026-2036
Calibrator Market Outlook
Wireless connectivity and cloud-native firmware architectures is tilting development priorities across the calibrator industry toward remote diagnostics and predictive maintenance integration. Keysight Technologies leverages its instrumentation heritage to anchor premium segments in RF and microwave calibration. Fluke Corporation dominates handheld and portable portfolios through channel density and field-service brand equity. Yokogawa Electric Corporation positions its automated calibration systems for continuous process environments in energy and chemical installations.
A calibrator is a precision instrument that generates or measures known physical quantities—electrical signals, pressure, temperature, or flow—to verify and adjust the accuracy of other measurement devices, typically achieving traceability to national standards through uncertainties expressed in parts per million. Manufacturing processes involve precision voltage references, thermocouple simulation circuits, and pneumatic pressure controllers assembled under controlled environmental conditions. Portable calibrators capture the largest volume share due to distributed maintenance operations across oil refineries and power generation sites, while automated calibrators represent the fastest-expanding margin pool as pharmaceutical batch records demand electronic documentation of every instrument verification. Digital sensor technology now leads technology segmentation as legacy analog architectures face obsolescence in industries requiring digital communication protocols.
FDA 21 CFR Part 11 and EU MDR impose electronic records and design-control requirements that directly expand calibration documentation burdens in healthcare and medical device manufacturing. EPA emissions monitoring rules and OSHA process safety management standards mandate periodic instrument verification, creating recurring revenue streams for calibration service providers. NIST-traceable standards and ISO 17025 accreditation function as market-access gatekeepers, with laboratories refusing vendor equipment lacking documented metrological chains. Stakeholders must weigh captive calibration laboratory investments against third-party service partnerships as regulatory audit frequency intensifies.
Market Dynamics
The semiconductor fabrication sector's migration toward sub-7nm process nodes is compressing calibration tolerances across metrology chains, forcing fabs to rebuild their instrument verification infrastructure from voltage references through final test.
Growth Catalysts
- ISO 17025 traceability mandates:South Korean semiconductor fabs are expanding metrology budgets to secure accreditation for export-qualified measurement chains.
- Electric vehicle battery testing protocols:German automotive OEMs now mandate tighter calibration intervals for thermal cycling and impedance measurement equipment.
- Digital sensor architectures:The transition from analog to digital communication protocols is accelerating replacement cycles across process industries.
Market Restraints
- Precision voltage reference supply concentration:Production of ultra-stable zener references concentrates among a handful of specialized foundries, creating single-source vulnerability.
- NIST-traceable standard lead times:Primary standard artifacts face 18-24 month delivery windows, constraining laboratory expansion timelines.
- Skilled metrologist scarcity:The specialized knowledge required for uncertainty budget analysis and chain-of-traceability documentation outpaces vocational training output.
Strategic Opportunities
- Cloud-native firmware architectures:Remote diagnostics and predictive maintenance integration open recurring revenue models for instrument vendors.
- Pharmaceutical electronic batch records:FDA 21 CFR Part 11 compliance requirements are expanding demand for automated calibrators with embedded documentation capabilities.
- India's industrial automation corridor:Process industries under BIS standards adoption are building greenfield calibration capabilities without legacy analog infrastructure.
Industry Challenges
- Multi-protocol integration complexity:Field instruments now demand simultaneous support for HART, Foundation Fieldbus, and PROFIBUS, complicating universal calibrator design.
- ISO 17025 audit preparation burden:Documentation requirements for inter-laboratory comparisons and measurement uncertainty validation consume increasing technical staff hours.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calibrator Market |
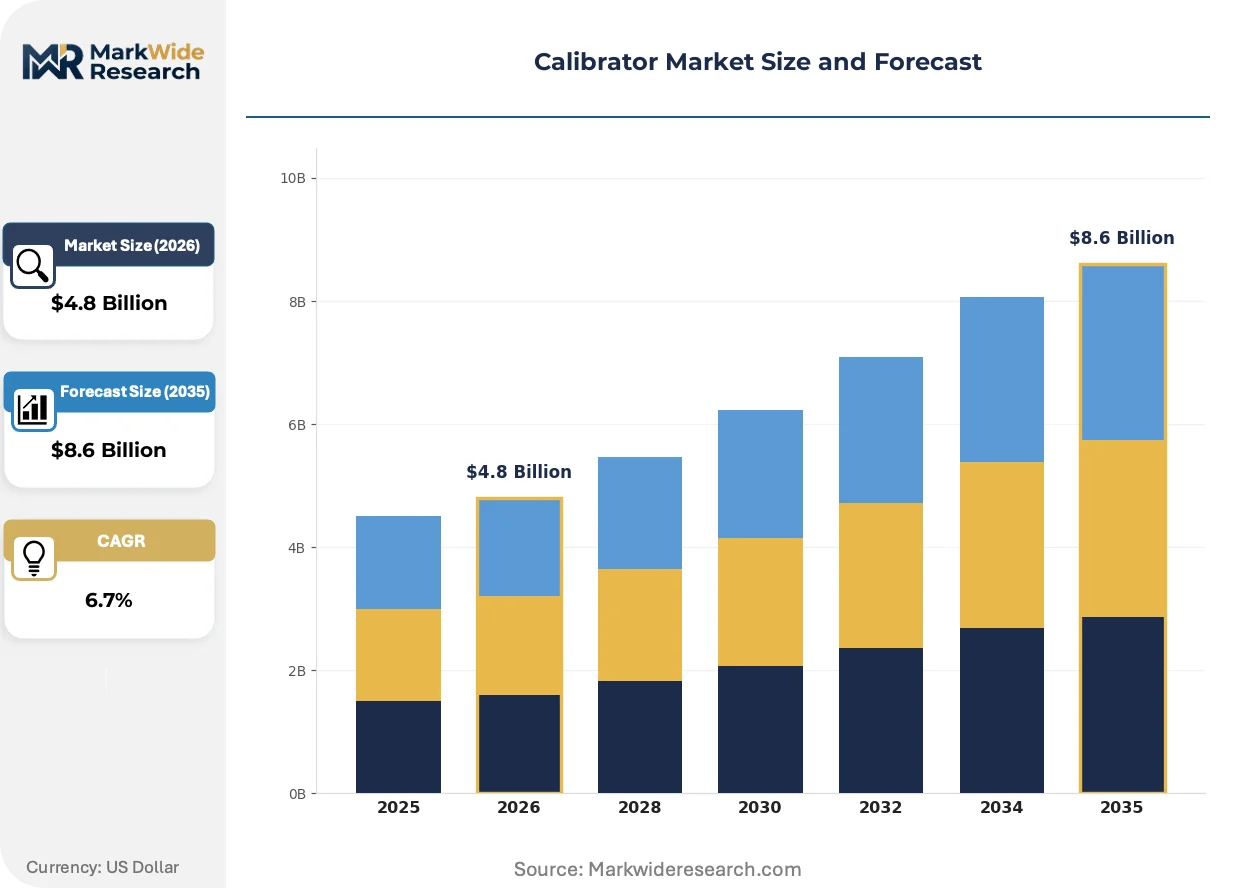
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Calibrators, Stationary Calibrators, Handheld Calibrators, Automated Calibrators Technology: Digital Sensors, Analog Sensors, Multimeters, Thermometers End User: Manufacturing, Aerospace, Automotive, Healthcare Application: Process Control, Quality Assurance, Research Laboratories, Calibration Services |
| Companies Covered | Fluke Corporation, Keysight Technologies, Yokogawa Electric Corporation, AMETEK, Tektronix, WIKA Alexander Wiegand SE & Co. KG, Beamex Oy Ab, Omega Engineering, Time Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calibrator Market Strategic Shifts
Wireless connectivity standards and edge computing architectures are redistributing calibration intelligence from central laboratories to distributed field devices, collapsing the traditional separation between portable and laboratory-grade verification.
Multi-channel automated pressure controllers with embedded silicon resonant sensors are rendering obsolete pneumatic piston gauges in pharmaceutical sterile processing environments. Aseptic manufacturers are adopting these systems to eliminate contamination risks from oil-lubricated mechanical standards. The technology is rendering obsolete decades-old primary calibration workflows that required instrument removal from cleanroom suites.
EU MDR design-control requirements now mandate documented calibration traceability for every measurement device influencing medical device conformity assessments. notified bodies are rejecting submissions lacking ISO 17025-accredited verification records for dimensional and electrical safety testing equipment. German and Irish medical device manufacturers are consolidating supplier lists to pre-qualified calibration service providers with dual US-EU accreditation.
Asset-light calibration service contracts are displacing capital-intensive captive laboratory investments among mid-sized chemical processors. Third-party providers now bundle instrument verification with cloud-based certificate management and audit-ready documentation packages. This model is gaining traction most visibly in Texas and Louisiana petrochemical corridors where OSHA process safety management audits have intensified verification frequency requirements.
Calibrator Market Segmentation
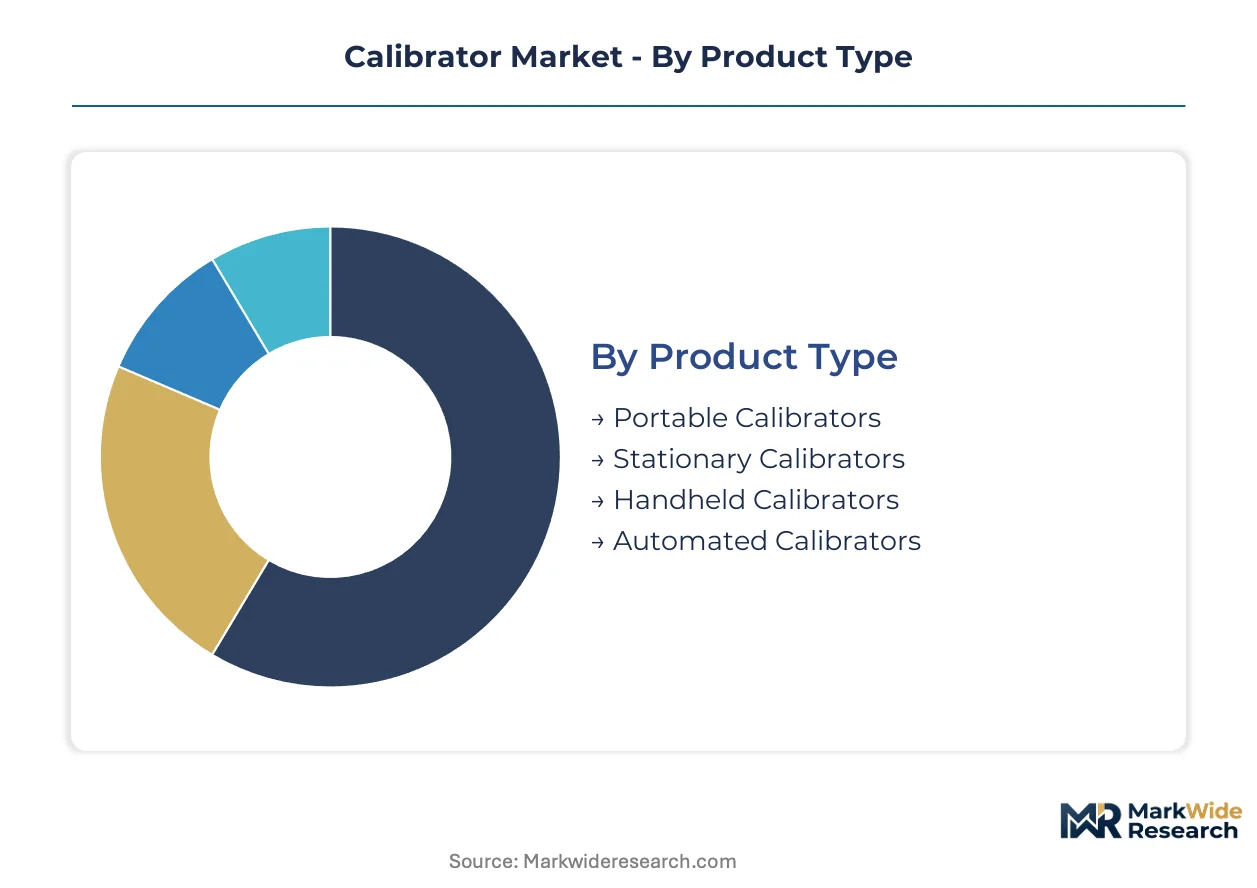
Calibration equipment procurement patterns diverge sharply across deployment contexts. Service intensity, documentation requirements, and traceability mandates reshape how vendors configure product portfolios and support infrastructure for each segment cluster.
Product Type:
After-sales service intensity varies dramatically by portability tier, with field-deployable units demanding rapid turnaround logistics and laboratory systems requiring specialized metrologist support contracts.
- Portable Calibrators:Self-contained units with internal pressure pumps and electrical source/measure capabilities designed for distributed maintenance rounds. Oil refineries in Texas and Louisiana deploy these across sprawling process units where instrument removal disrupts continuous operations. Keysight Technologies and Fluke Corporation compete through channel density and 24-hour replacement programs.
- Automated Calibrators:Rack-mounted systems executing unattended calibration sequences with embedded documentation for electronic batch records. Pharmaceutical manufacturers under FDA 21 CFR Part 11 mandate these for sterile processing environments where human intervention risks contamination. The fastest margin expansion sits here as certificate management migrates to cloud-native architectures.
- Stationary Calibrators:Laboratory-grade systems anchored to primary standard artifacts for highest-precision work.
- Handheld Calibrators:Single-function or limited-range devices prioritized for quick field verification.
By volume, Portable Calibrators leads. By growth pace, Automated Calibrators is ahead.
Technology:
Cost tier stratification separates premium digital architectures from legacy analog maintenance, with migration timelines dicting replacement revenue windows across installed bases.
- Digital Sensors:Microprocessor-based measurement engines communicating via HART, Foundation Fieldbus, or PROFIBUS protocols. South Korean semiconductor fabs specify these exclusively for sub-7nm process metrology chains requiring ISO 17025 traceability. The transition from analog architectures accelerates replacement cycles as digital communication becomes mandatory.
- Analog Sensors:Continuous voltage or current signal outputs dominating legacy process control infrastructure. Chemical processors in Germany's industrial automation corridor maintain these for compatibility with decades-old distributed control systems, though procurement is shifting toward digital replacements.
- Multimeters:Combined voltage, current, and resistance measurement functions in bench or handheld formats.
- Thermometers:Temperature simulation and measurement devices spanning thermocouple, RTD, and infrared technologies.
By installed base, Analog Sensors still dominates. By expansion trajectory, Digital Sensors is climbing the fastest.
End User:
Application context drives specification severity, with regulated industries imposing documentation burdens that reshape vendor service models and pricing structures.
- Manufacturing:Broad demand spanning discrete automation, process industries, and fabrication facilities. German automotive OEMs mandate tightened calibration intervals for electric vehicle battery testing equipment, compressing metrology cycle times across supplier networks.
- Healthcare:Medical device manufacturers and hospital clinical engineering departments under EU MDR design-control requirements. Irish and German notified bodies reject conformity submissions lacking ISO 17025-accredited verification records, consolidating procurement to pre-qualified service providers.
- Aerospace:Flight-critical instrumentation and ground support equipment requiring FAA traceability documentation.
- Automotive:Dedicated vehicle testing and production line metrology, increasingly converging with battery and powertrain electrification programs.
By contract value, Manufacturing leads. By compliance-driven pricing power, Healthcare is gaining share fastest.
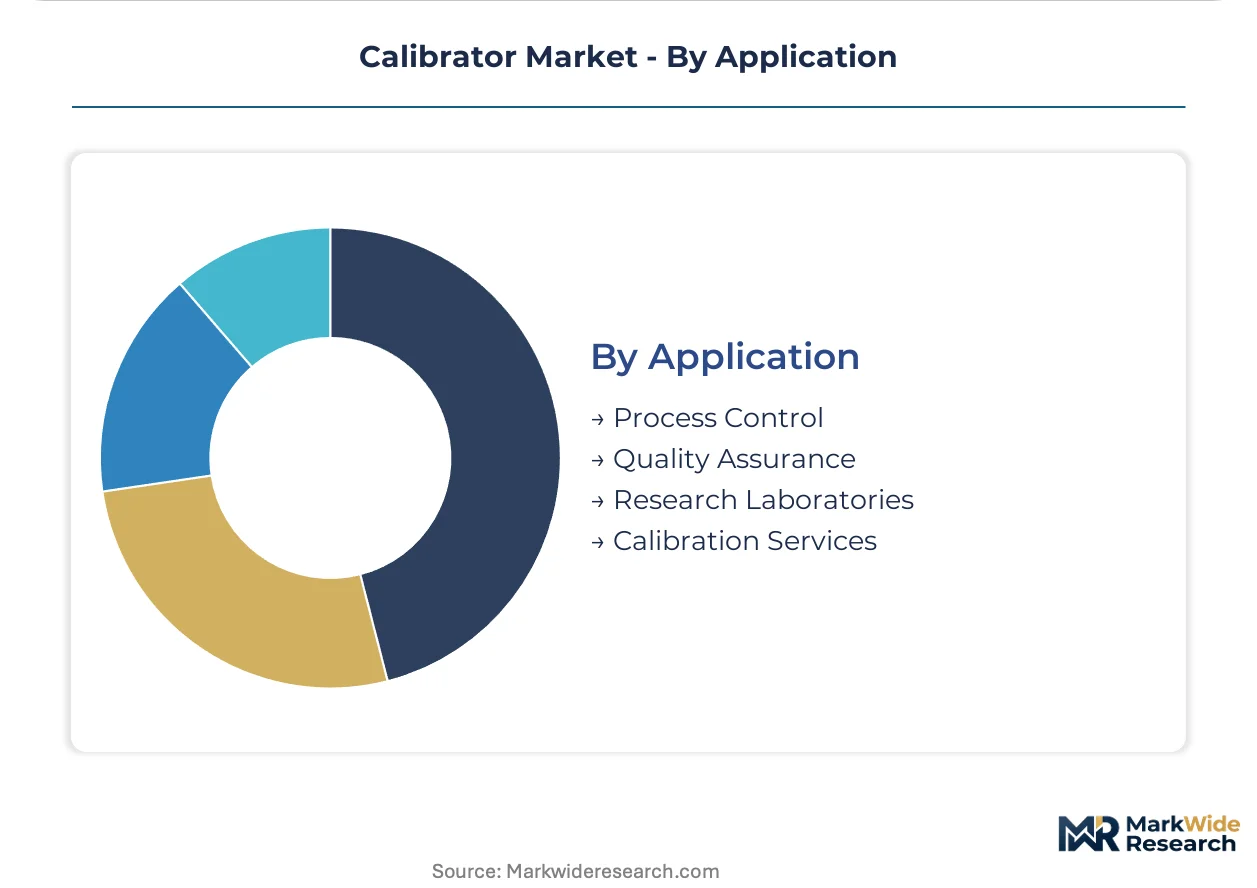
Application:
Customer type differentiation separates internal captive laboratories from external service providers, with asset-light outsourcing reshaping competitive dynamics in mid-market segments.
- Calibration Services:Third-party providers bundling instrument verification with cloud-based certificate management and audit-ready documentation. Texas and Louisiana petrochemical corridors show fastest adoption as OSHA process safety management audits intensify verification frequency requirements.
- Process Control:In-line instrument verification within continuous manufacturing environments. Energy and chemical installations specify automated systems from Yokogawa Electric Corporation for uninterrupted production.
- Quality Assurance:Incoming inspection and final test verification in discrete manufacturing.
- Research Laboratories:National metrology institutes and corporate R&D facilities maintaining primary standards.
By revenue concentration, Process Control leads. By business model disruption, Calibration Services shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German automotive OEMs export electric vehicle battery testing equipment to South Korean semiconductor fabrication facilities, creating a trans-Eurasian calibration services corridor anchored by ISO 17025 traceability requirements.
Germany
Automotive OEMs mandate tightened calibration intervals for thermal cycling and impedance measurement equipment used in battery testing. EU MDR design-control requirements impose electronic records documentation on medical device manufacturers in Baden-Württemberg. The industrial automation corridor spanning Bavaria and North Rhine-Westphalia concentrates metrology procurement for electric vehicle powertrain programs.
South Korea
Semiconductor fabrication facilities expanding sub-7nm process nodes demand compressed calibration tolerances across metrology chains. MFDS traceability mandates for export-qualified measurement chains expand laboratory accreditation budgets. The Gyeonggi-do cluster surrounding Seoul anchors the nation's precision instrument verification infrastructure rebuild.
United States
Texas and Louisiana petrochemical corridors intensify calibration verification frequency under OSHA process safety management audits. FDA 21 CFR Part 11 drives pharmaceutical manufacturers toward automated calibrators with embedded documentation. Houston's energy sector concentration shifts procurement toward asset-light third-party service contracts bundling cloud-based certificate management.
India
Process industries under BIS standards adoption build greenfield calibration capabilities without legacy analog infrastructure. The country's national standards body accelerates accreditation timelines for industrial automation corridors. Maharashtra and Gujarat manufacturing clusters specify digital sensor architectures exclusively for new capacity installations.
Japan
Precision instrument manufacturers face METI pressure to maintain JIS standard leadership amid regional competitor expansion. Medical device exporters navigate dual US-EU accreditation requirements for calibration traceability. The Chubu region around Nagoya concentrates automotive and aerospace metrology demand from Toyota and Mitsubishi supply chains.
Calibrator Market Competitive Environment
On the supply side, the industry is consolidating around instrumentation heritage players with embedded channel density and metrology accreditation credentials. Three strategic archetypes dominate: diversified electronics conglomerates with RF and microwave specialization, field-service brands with portable portfolio dominance, and process automation specialists with continuous environment expertise. Competitive moves center on cloud-native firmware development partnerships and ISO 17025-accredited service network expansion.
Among diversified instrumentation conglomerates, Keysight Technologies and Fluke Corporation exemplify contrasting positioning vectors—one anchoring premium laboratory segments through RF heritage, the other dominating distributed maintenance operations through handheld portfolio breadth. Yokogawa Electric Corporation occupies the process automation specialist archetype, with its automated calibration systems serving energy and chemical installations requiring uninterrupted production verification. These three entities represent the dominant competitive anchors against which mid-tier specialists and regional fabricants define differentiation strategies.
| Leading Market Players |
|---|
| Fluke Corporation |
| Keysight Technologies |
| Yokogawa Electric Corporation |
| AMETEK |
| Tektronix |
| WIKA Alexander Wiegand SE & Co. KG |
| Beamex Oy Ab |
| Omega Engineering |
| Time Electronics |
| Others |
Value Chain & Pricing Dynamics
Ultra-stable zener reference production concentrates among specialized foundries in Japan and the United States, anchoring margin pools in laboratory-grade systems downstream while portable calibrator vendors compete on channel density and service turnaround velocity.
Pricing Analysis
Current-generation digital sensor calibrators command substantial premiums over prior-generation analog architectures, while next-generation cloud-native firmware systems are capturing the fastest margin expansion. Three-tier pricing structure across premium laboratory, standard industrial, and economy handheld levels separates ISO 17025-accredited systems from field-service units. Cost compression in economy handheld tiers is intensifying because channel partners demand 24-hour replacement guarantees. Process industries with captive laboratories show the least price sensitivity; mid-sized chemical processors outsourcing to third-party providers exhibit the highest.
Supply Chain Analysis
Export control regimes restricting precision voltage reference and silicon resonant sensor technologies limit flows from Japanese and US suppliers to Chinese end-users, reshaping procurement patterns. Manufacturing concentrates in Japan, the United States, and Germany for primary standard artifacts; South Korea and Taiwan dominate semiconductor-grade metrology components. Supply chains draw from specialized zener diode substrates, thermocouple alloy wires, and pneumatic precision valves. Single-source vulnerability in ultra-stable reference production creates systemic risk. Distribution runs through authorized metrology service networks with ISO 17025 accreditation credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cloud-native firmware architectures and embedded documentation capabilities are transforming calibrator markets into platform ecosystems where interoperability with enterprise asset management systems determines vendor viability.
For Market Incumbents: Harden ISO 17025-accredited service network density against emerging cloud-native entrants offering predictive maintenance subscriptions. Deepen backward integration into precision voltage reference supply through partnerships with Japanese specialized foundries. Channel control remains the critical defensive lever as asset-light third-party providers displace captive laboratory investments. For New Entrants and Emerging Players: India's industrial automation corridor under BIS standards adoption offers the most penetrable geography for digital-native calibrator portfolios unencumbered by legacy analog compatibility requirements. Target pharmaceutical manufacturers facing FDA 21 CFR Part 11 documentation mandates with automated calibration systems bundling cloud-based certificate management. A direct-to-plant sales model bypassing established distribution networks accelerates initial traction. For Investors and Strategic Acquirers: Capital is best deployed toward automated calibration system specialists with embedded software documentation capabilities and dual US-EU accreditation credentials. The five-to-ten year viability window favors vendors positioned for pharmaceutical and medical device regulatory compliance expansion. Watch for inflection signals in South Korean semiconductor fab metrology budget disclosures as sub-7nm node migration accelerates.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Firmware Development | Enables predictive maintenance subscriptions for Yokogawa process automation customers. |
| ISO 17025 Service Network Expansion | Secures accreditation credentials required by German automotive OEM battery testing protocols. |
| Automated Calibrator Platform Launch | Addresses FDA 21 CFR Part 11 electronic batch record requirements in pharmaceutical sterile processing. |
| Precision Reference Supply Partnership | Mitigates single-source vulnerability in Japanese zener diode substrate production. |
| Geographic Expansion into India | Captures greenfield digital sensor demand in Maharashtra and Gujarat manufacturing clusters. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with metrology laboratory directors, calibration service operations managers, pharmaceutical quality assurance leads, and semiconductor fab equipment engineers; and secondary validation against NIST technical publications, ISO 17025 accreditation registries, SEC filings from diversified instrumentation conglomerates, and MFDS regulatory guidance documents. Bottom-up instrument shipment analysis triangulated against top-down end-user budget surveys.
Forecast inputs span product type segmentation across portable, automated, stationary, and handheld tiers; technology architecture across digital sensor, analog sensor, multimeter, and thermometer categories; and end-use industry across manufacturing, healthcare, aerospace, and automotive verticals. CAGRs were derived from regression analysis of historical replacement cycle compression and regulatory mandate expansion across the projection horizon. Semiconductor node migration timelines and electric vehicle battery testing protocol adoption curves served as industry-specific demand drivers.
The forecast holds incumbent behavior within observed patterns; aggressive cloud-native platform investments by RF instrumentation specialists or automated calibration entrants would shift outcomes from base-case projections. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Magnetometer Sensor Market
Sensors and Controls
Global Nanosensors Market
Sensors and Controls
Two Wheeler Sensors Market
Sensors and Controls
Voltage Sensor Market
Sensors and Controls
High Purity Flow Meter Market
Sensors and Controls
APAC Proximity Sensors Market
Sensors and Controls
Automotive MEMS Market
Sensors and Controls
Differential Pressure Sensor Market
Sensors and Controls
United States Smart Sensors Market
Sensors and Controls
Asia Pacific Touch Screen Controllers Market
Sensors and Controls
Global Acceleration and Yaw Rate Sensors Market
Sensors and Controls
Mexico Digital Thermometer Market
Sensors and Controls
Sensor Bearing Market
Sensors and Controls
Anemometer Market
Sensors and Controls
North America Bulk Acoustic Wave Sensors Market
Sensors and Controls
Wireless Flow Sensors Market