
 Distortion Meter Market | 2026-2036
Distortion Meter Market Size, Share, and Industry Trends Forecast 2026-2036
Distortion Meter Market Outlook
Buyer concentration among telecommunications service providers is broadening as 5G network rollouts fragment procurement across regional carriers and specialized test laboratories. Keysight Technologies leverages its RF signal analysis heritage to dominate high-frequency distortion measurement for base station validation. Rohde & Schwarz anchors European demand through its broadcast and spectrum testing installed base. Tektronix competes in the oscilloscope-integrated segment, where engineers expect seamless harmonic analysis within mixed-signal debug workflows.
A distortion meter quantifies harmonic and intermodulation distortion in electronic signals, typically resolving total harmonic distortion (THD) below 0.001 percent at frequencies spanning 20 Hz to 100 kHz for audio-grade instruments. Engineers deploy these instruments to certify amplifier linearity, converter fidelity, and transmission path integrity across product development and production lines. Digital meters command the largest revenue share due to their software-defined measurement flexibility and automated compliance reporting, while portable meters represent the fastest-expanding category as field technicians replace bench-bound workflows with battery-operated analyzers. Hybrid technology instruments capture premium positioning by combining analog front-end sensitivity with DSP-based post-processing for multi-tone and burst-signal analysis.
FCC equipment authorization rules in the United States mandate spurious emission testing that indirectly drives distortion meter deployment for transmitter chain validation, while CE marking under the EU Radio Equipment Directive requires comparable harmonic suppression documentation for market access. Japan's METI enforces JIS standards on audio equipment efficiency that OEMs verify through certified THD+N measurement protocols. Stakeholders must monitor whether emerging wideband modulation formats for 6G research force instrument makers to extend effective measurement bandwidth without sacrificing dynamic range.
Market Dynamics
Software-defined measurement architectures are compressing hardware refresh cycles as instrument makers compete on DSP algorithm performance rather than analog front-end specifications alone.
Growth Catalysts
- 5G base station deployment:Telecommunications carriers in South Korea and Germany require harmonic distortion validation for massive MIMO transmitters, expanding procurement of RF-capable analyzers.
- METI electromagnetic compatibility enforcement:Japan's revised technical standards for consumer audio equipment mandate certified THD+N documentation, forcing OEMs to upgrade test floor instrumentation.
- Battery-powered field analyzers:Technicians servicing broadcast transmission towers and live event sound systems are replacing bench instruments with portable units supporting 8-hour continuous operation.
Market Restraints
- Precision resistor and capacitor volatility:Discrete component supply from Taiwanese foundries experiences 6-9 month lead time fluctuations, constraining analog front-end production schedules.
- Calibration laboratory concentration:Third-party certification services cluster in German and Japanese metropolitan areas, creating geographic friction for instrument users in emerging manufacturing zones.
- Subscription licensing friction:Software-defined instruments require recurring firmware access fees that conflict with capital equipment depreciation practices at mid-sized contract manufacturers.
Strategic Opportunities
- 6G research instrumentation:University laboratories in Finland and Singapore are piloting wideband distortion analyzers operating above 100 GHz for sub-terahertz communication prototyping.
- Medical ultrasound transducer testing:FDA 510(k) pathways for diagnostic imaging equipment now explicitly reference harmonic distortion specifications, opening adjacent demand from acoustic probe manufacturers.
- Cloud-native measurement workflows:Distributed engineering teams access shared instrument pools through browser-based interfaces, reducing per-site hardware duplication.
Industry Challenges
- RF calibration technician scarcity:Microwave measurement expertise concentrates among engineers with 15+ years experience, constraining service network expansion.
- Legacy GPIB integration complexity:Automated test systems in automotive amplifier factories rely on 1980s-era bus architectures that resist seamless incorporation of modern Ethernet-controlled instruments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Distortion Meter Market |
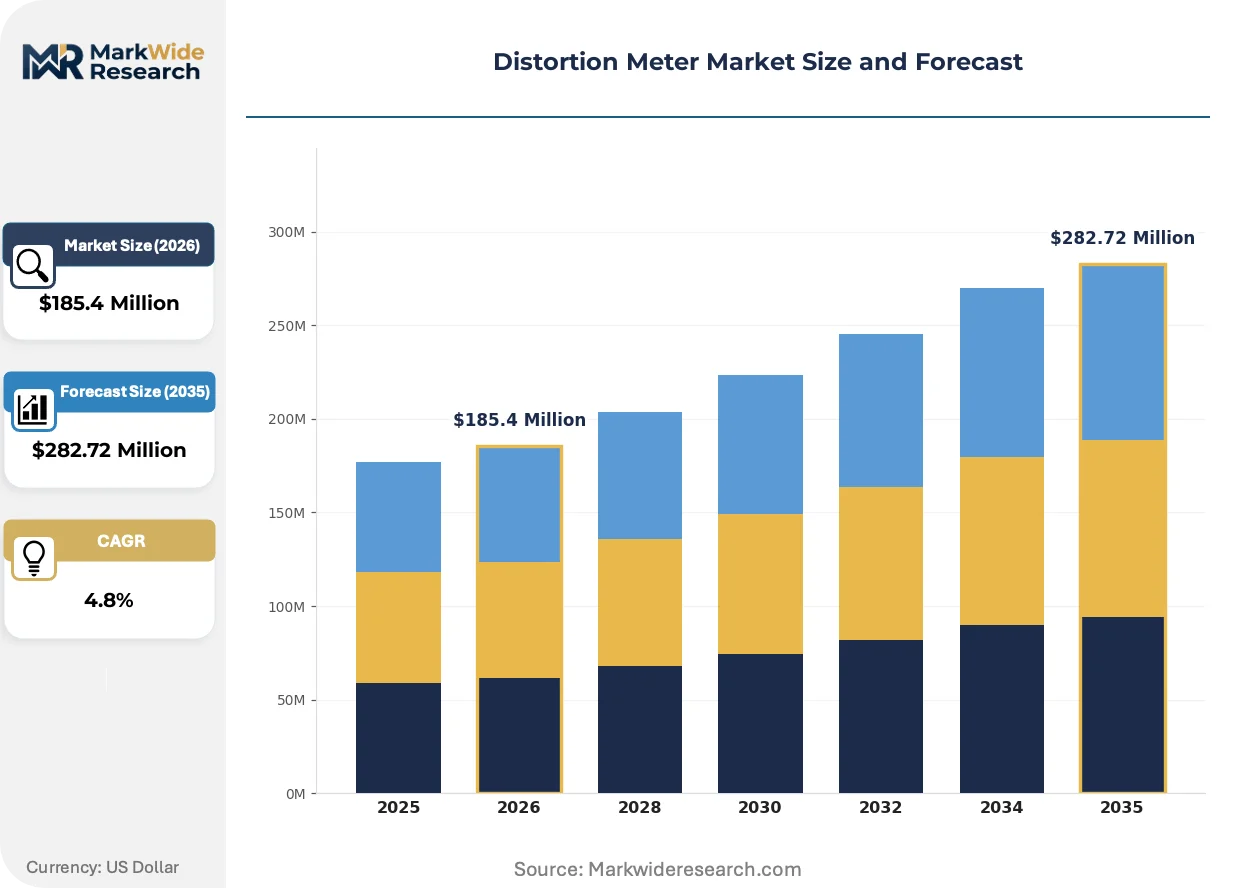
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $282.72 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Meters, Digital Meters, Portable Meters, Bench Meters End User: Manufacturers, Test Laboratories, Educational Institutions, Service Providers Technology: RF Technology, Digital Signal Processing, Optical Technology, Hybrid Technology Application: Audio Equipment Testing, Telecommunication, Research & Development, Quality Control |
| Companies Covered | Keysight Technologies, Rohde & Schwarz, Tektronix, Yokogawa, Anritsu, Fluke Corporation, National Instruments, PCE Instruments, Teledyne FLIR, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Distortion Meter Market Strategic Shifts
Artificial intelligence inference at the measurement edge is compressing analysis latency from seconds to milliseconds, enabling real-time production line feedback loops that were previously impractical.
Multi-tone DSP analysis is unifying formerly separate instrument categories. Single hardware platforms now execute harmonic distortion, intermodulation, and noise figure measurements through firmware reconfiguration. Semiconductor wafer probe stations in Taiwan and Arizona have adopted these unified architectures to consolidate test head footprints. The convergence is unifying procurement decisions around software ecosystem maturity rather than discrete instrument specifications.
EU Radio Equipment Directive harmonized standards now explicitly reference spurious emission limits for professional audio equipment. Manufacturers seeking CE marking must document harmonic suppression across 9 kHz to 30 MHz bands. Italian and Polish contract electronics assemblers have responded by embedding distortion verification into incoming component inspection protocols rather than final assembly testing.
Field service departments now purchase analyzers through equipment-as-a-service contracts rather than capital appropriations. Telecom infrastructure maintenance divisions in Australia and Canada lease portable units with bundled calibration and firmware update entitlements. The model concentrates working capital risk with distributors while accelerating technology refresh rates among end-users.
Distortion Meter Market Segmentation
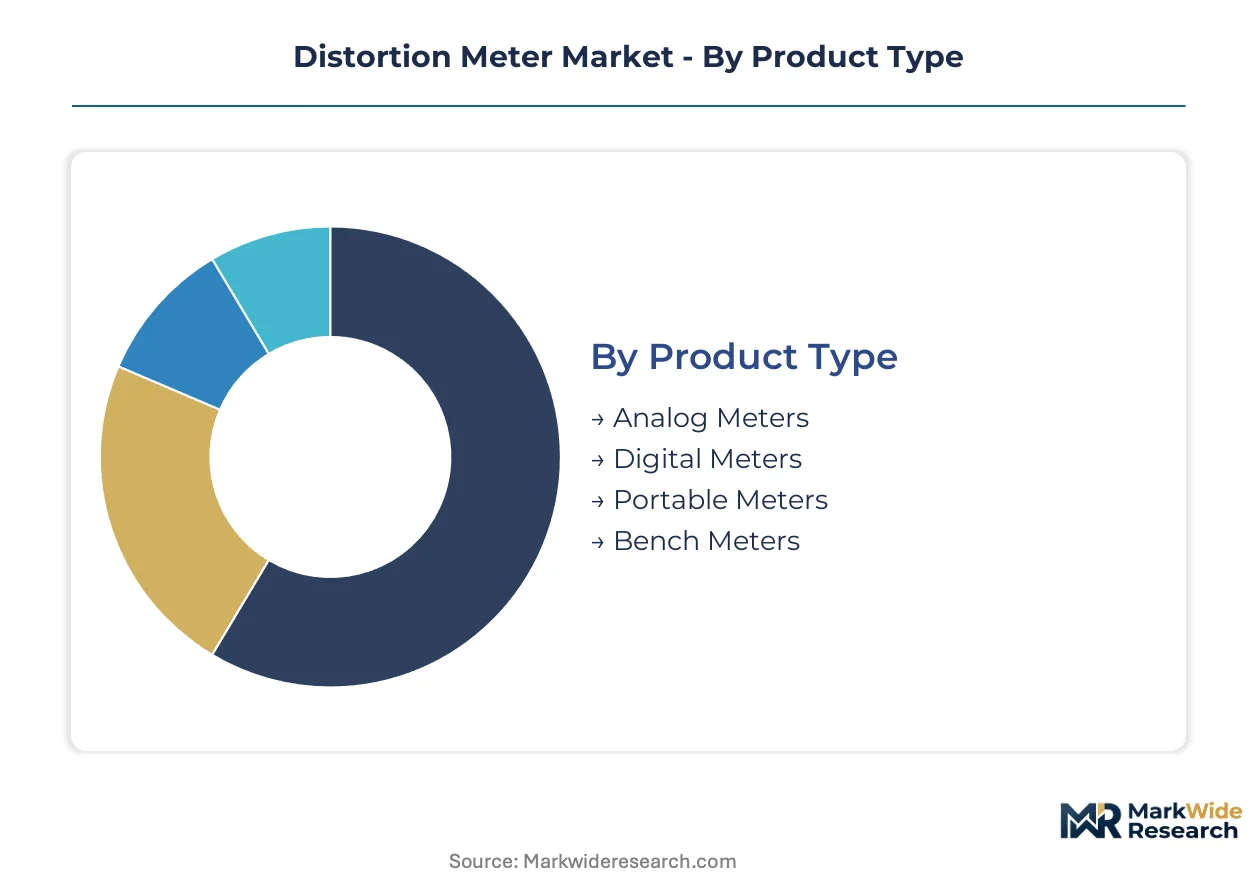
Engineers select distortion meters based on measurement bandwidth, portability requirements, and integration depth with existing test systems. Procurement patterns diverge sharply between R&D laboratories seeking maximum precision and field service teams prioritizing battery life and ruggedized enclosures.
Product Type:
Capital depreciation schedules and floor space constraints drive the trade-off between bench-bound precision and field-deployable flexibility.
- Digital Meters:Software-defined architectures execute THD+N, intermodulation, and noise figure measurements through firmware reconfiguration rather than dedicated hardware modules. Semiconductor wafer probe stations in Taiwan and Arizona embed these units for consolidated test head footprints, while Japanese audio OEMs deploy them for automated METI compliance documentation.
- Portable Meters:Battery-operated analyzers with 8-hour continuous operation replace legacy bench instruments for broadcast tower technicians and live event sound engineers. Australian telecom infrastructure maintenance divisions now lease these through equipment-as-a-service contracts with bundled calibration entitlements, accelerating refresh cycles beyond traditional capital appropriation timelines.
- Analog Meters:Discrete component front-ends deliver unmatched sensitivity for sub-0.001% THD resolution in metrology-grade applications.
- Bench Meters:Rack-mounted configurations dominate amplifier factory production lines with GPIB and Ethernet control interfaces.
Volume sits with Digital Meters; growth tilts toward Portable Meters.
End User:
Certification authority and measurement traceability requirements fragment procurement specifications across institutional buyer types.
- Test Laboratories:Third-party certification services cluster in German and Japanese metropolitan areas, creating geographic friction for instrument users in emerging manufacturing zones. These facilities demand NIST-traceable calibration chains and automated compliance reporting for FCC equipment authorization and CE marking documentation.
- Manufacturers:Automotive amplifier factories in Poland and Italy embed distortion verification into incoming component inspection protocols rather than final assembly testing, responding to EU Radio Equipment Directive harmonized standards. Production line integration requires seamless incorporation of modern Ethernet-controlled instruments alongside legacy GPIB architectures.
- Educational Institutions:University laboratories in Finland and Singapore pilot wideband analyzers above 100 GHz for sub-terahertz communication prototyping.
- Service Providers:Field service departments prioritize lease-based acquisition models with firmware update entitlements over capital purchases.
Procurement concentrates among Test Laboratories; Manufacturers are expanding most quickly.
Technology:
Signal frequency and modulation complexity determine the frontier between analog front-end sensitivity and DSP-based post-processing.
- Hybrid Technology:Combines analog front-end sensitivity with DSP-based post-processing for multi-tone and burst-signal analysis. These instruments capture premium positioning in RF base station validation where massive MIMO transmitters require harmonic distortion measurement across non-continuous transmission patterns.
- Digital Signal Processing:Algorithm performance competition compresses hardware refresh cycles as instrument makers differentiate on measurement speed rather than analog specifications alone. AI inference at the measurement edge compresses analysis latency from seconds to milliseconds, enabling real-time production line feedback loops.
- RF Technology:Microwave measurement expertise concentrates among engineers with 15+ years experience, constraining service network expansion for high-frequency instruments.
- Optical Technology:Emerging architectures address fiber optic communication link linearity verification for coherent modulation formats.
Revenue concentrates in Hybrid Technology; DSP-based platforms are gaining share fastest.
Application:
Regulatory enforcement intensity and product liability exposure shape investment priority across measurement use cases.
- Audio Equipment Testing:Japan's METI enforces JIS standards on audio equipment efficiency that OEMs verify through certified THD+N measurement protocols. Consumer electronics manufacturers face electromagnetic compatibility documentation requirements that force test floor instrumentation upgrades.
- Telecommunication:5G base station deployment in South Korea and Germany requires harmonic distortion validation for massive MIMO transmitters, expanding procurement of RF-capable analyzers. Spurious emission testing mandates under FCC equipment authorization rules indirectly drive distortion meter deployment for transmitter chain validation.
- Research & Development:University laboratories pilot wideband distortion analyzers for 6G research and sub-terahertz communication prototyping.
- Quality Control:FDA 510(k) pathways for diagnostic imaging equipment now explicitly reference harmonic distortion specifications, opening adjacent demand from acoustic probe manufacturers.
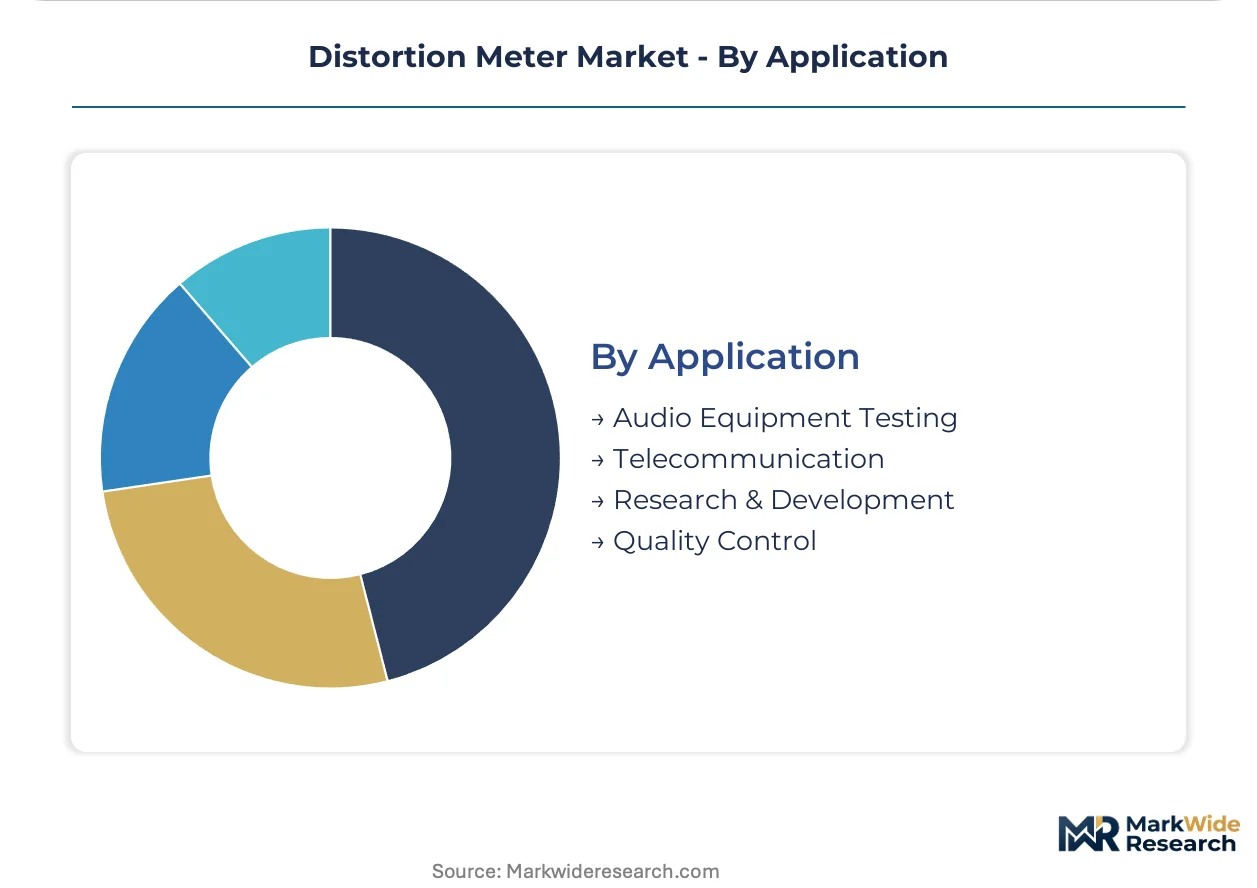
Deployment concentrates in Audio Equipment Testing; Telecommunication shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for distortion meters concentrates in precision manufacturing clusters where electromagnetic compatibility certification and telecommunications infrastructure deployment intersect. Procurement patterns diverge sharply between established test laboratory hubs and emerging production zones seeking localized calibration capabilities.
United States
FCC equipment authorization rules mandate spurious emission testing for transmitter chain validation, driving procurement among RF component manufacturers. The IRA's domestic manufacturing incentives accelerate test floor instrumentation upgrades in semiconductor packaging facilities. Greater Boston hosts concentrated metrology services serving defense and aerospace contractors requiring NIST-traceable calibration chains.
Germany
CE marking under the EU Radio Equipment Directive requires harmonic suppression documentation across professional audio equipment, expanding demand from contract electronics assemblers. The country's national automotive regulator enforces electromagnetic compatibility standards that force amplifier suppliers to embed distortion verification into production lines. Bavaria anchors European test laboratory capacity with third-party certification services clustering around Munich metropolitan infrastructure.
Japan
METI enforces revised JIS standards on audio equipment efficiency that OEMs verify through certified THD+N measurement protocols. Consumer electronics manufacturers in the Kanto region face electromagnetic compatibility documentation requirements forcing instrumentation upgrades. Tokyo-Osaka industrial corridors concentrate procurement of digital distortion meters as manufacturers automate compliance reporting workflows.
South Korea
Telecommunications carriers require harmonic distortion validation for massive MIMO transmitters during 5G network expansion. The country's national broadcasting regulator mandates transmission path integrity testing for broadcast infrastructure maintenance. Seoul Capital Area hosts specialized test laboratories serving regional carriers fragmenting procurement across domestic supply chains.
Singapore
University laboratories pilot wideband distortion analyzers operating above 100 GHz for sub-terahertz communication prototyping in 6G research programs. The country's national standards body coordinates regional calibration traceability for Southeast Asian manufacturing zones. Research institutions anchor demand for hybrid technology instruments combining analog sensitivity with DSP-based post-processing.
Distortion Meter Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue software-defined architectures and cloud-native measurement workflows. The vendor base stratifies between precision instrument heritage manufacturers and modular test platform specialists. Three archetypes dominate: RF signal analysis heritage players, oscilloscope-integrated solution providers, and portable field service equipment vendors. Competitive moves concentrate on DSP algorithm licensing partnerships and equipment-as-a-service contract structures that transfer working capital risk to distribution channels.
Among heritage precision instrument manufacturers, Keysight Technologies, Rohde & Schwarz, and Tektronix represent distinct competitive positioning vectors. Keysight occupies a position anchored in RF signal analysis heritage for high-frequency measurement applications. Rohde & Schwarz exemplifies European broadcast and spectrum testing installed base concentration. Tektronix sits within the oscilloscope-integrated segment where engineers expect seamless harmonic analysis within mixed-signal debug workflows.
| Leading Market Players |
|---|
| Keysight Technologies |
| Rohde & Schwarz |
| Tektronix |
| Yokogawa |
| Anritsu |
| Fluke Corporation |
| National Instruments |
| PCE Instruments |
| Teledyne FLIR |
| Others |
Value Chain & Pricing Dynamics
Japan's METI electromagnetic compatibility mandates gate qualified supply access and premium-tier pricing power, forcing OEMs to source only from vendors with certified THD+N documentation capabilities while compressing margins on uncertified economy-tier instruments.
Pricing Analysis
Volume concentrates in standard-tier digital meters while margins concentrate in hybrid-technology premium instruments. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and firmware flexibility differentiation. Cost compression in economy-tier portable units is intensifying because Taiwanese component volatility feeds through to bill-of-materials pressure. Contract manufacturers exhibit highest price sensitivity; telecommunications carriers with equipment-as-a-service contracts show lowest sensitivity due to bundled calibration entitlements.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Japanese audio manufacturers and South Korean telecom carriers, while distributor networks serve mid-sized European contract electronics assemblers. Precision resistor and capacitor supply draws from Taiwanese, Japanese, and German foundries. Analog front-end production hinges on discrete component availability. Single-source vulnerability concentrates in 6-9 month lead time fluctuations for precision passives. Distribution runs through authorized test equipment distributors with calibration laboratory partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
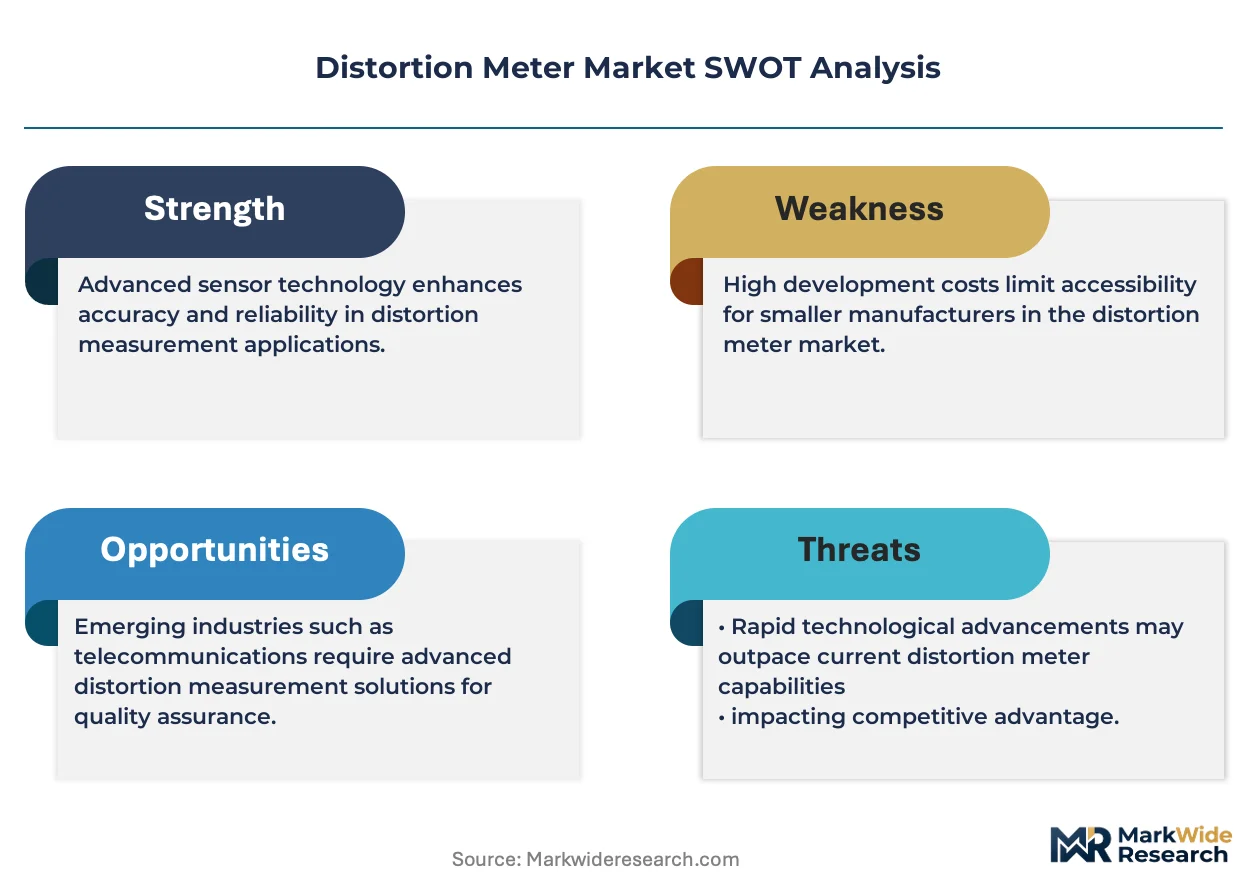
This market functions as a cost-of-compliance story where Japan's METI enforcement of JIS standards creates a barrier-to-entry moat for instrument makers with certified documentation capabilities.
For Market Incumbents: Lock in firmware ecosystem stickiness through DSP algorithm licensing partnerships that raise switching costs for semiconductor probe stations and audio OEMs. Deepen backward integration into precision analog component supply to buffer Taiwanese foundry volatility. Prioritize calibration laboratory accreditation expansion in emerging manufacturing zones to reduce geographic friction for buyers. For New Entrants and Emerging Players: Cloud-native measurement workflows offer the lowest-friction entry path for distributed engineering teams seeking shared instrument pool access. Target Australian and Canadian telecom infrastructure maintenance divisions with equipment-as-a-service contracts that transfer working capital risk to distribution channels. Pursue FDA 510(k) pathway alignment for medical ultrasound transducer testing as the most penetrable adjacent application. For Investors and Strategic Acquirers: University laboratory 6G research program initiations are the leading indicator that wideband analyzer demand above 100 GHz is approaching commercial inflection. Position for 5-10 year horizon viability by acquiring DSP algorithm specialists with AI inference-at-the-edge capabilities rather than legacy analog heritage assets. Monitor METI standard revision announcements as the signal for compliance-driven replacement cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Contract Structure | Transfers working capital risk to distributors while accelerating technology refresh rates among Australian and Canadian telecom maintenance divisions. |
| AI Inference-at-the-Edge Integration | Compresses analysis latency from seconds to milliseconds for real-time production line feedback loops in Taiwanese semiconductor probe stations. |
| Calibration Laboratory Network Expansion | Reduces geographic friction for instrument users in emerging manufacturing zones beyond German and Japanese metropolitan clusters. |
| Firmware Ecosystem Licensing Partnerships | Raises switching costs for semiconductor wafer probe stations that have consolidated test head footprints around software-defined architectures. |
| Medical Ultrasound Transducer Testing Alignment | Opens adjacent demand from acoustic probe manufacturers responding to FDA 510(k) harmonic distortion specification requirements. |
Study Parameters
Regulatory filing databases, trade customs records, and instrument maker technical documentation formed the secondary backbone, supplemented by primary interviews with test laboratory certification managers, RF calibration technicians, semiconductor probe station engineers, audio OEM quality directors, and telecom infrastructure maintenance procurement leads. Bottom-up unit demand estimates from end-user segments were triangulated against top-down manufacturer shipment data.
Historical trendline analysis across analog-to-digital instrument transition patterns informed projection modeling, with segmentation across product type, end user, technology, and application dimensions throughout the forecast period. CAGRs were derived from installed base replacement cycle analysis and compliance-driven upgrade intensity. 5G base station deployment timelines and METI enforcement phase-ins served as industry-specific forecast inputs.
The model holds under stable electromagnetic compatibility regulatory enforcement; deviation in standard revision timing or calibration laboratory capacity constraints would shift replacement cycle assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Battery Capacity Testers Market
Test and Measurement
Semiconductor Metrology and Inspection Market
Test and Measurement
Automated Calibration-as-a-Service Platforms for Test and Measurement Assets Market
Test and Measurement
Protective Earth Resistance Meter Market
Test and Measurement
Ultrasonic NDT Equipment Market
Test and Measurement
Electronic Test Instrument Market
Test and Measurement
Environmental Test Chambers Market
Test and Measurement
Wafer Testing Services Market
Test and Measurement
Brightness Meter Market
Test and Measurement
Universal Testing Machine Market
Test and Measurement
Non-Destructive Testing Market
Test and Measurement
Hearing Aid and True Wireless Earbud Acoustic Performance Test Systems Market
Test and Measurement
Gauss Meter Market
Test and Measurement
Voltage Calibrator Market
Test and Measurement
Europe NDT Equipment Market
Test and Measurement
DSL Tester Market