
 Battery Test Equipment Market | 2026-2036
Battery Test Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Battery Test Equipment Market Analytics
UN ECE R100 is unwinding competitive access for equipment vendors that lack certified abuse-test chamber portfolios. Chroma ATE leverages its Taiwan-based R&D footprint to dominate high-channel cell formation systems. Arbin Instruments sustains technology leadership through precision coulombic efficiency measurement at sub-ppm resolution. Maccor Inc. anchors North American laboratory demand with modular potentiostat architectures.
Battery test equipment comprises electrochemical instrumentation that subjects cells and packs to controlled charge-discharge cycles, thermal stress, and mechanical abuse while logging voltage, current, and temperature data at millisecond resolution. These systems verify compliance with safety thresholds and cycle-life guarantees before mass production release. Cell test systems represent the fastest-growing product category as cylindrical and prismatic formats multiply across automotive programs. Research laboratories command premium pricing tiers for multi-channel potentiostats with impedance spectroscopy capability, while production testing segments compete on throughput and capital efficiency per channel.
UN ECE R100 in Europe, GB 38031 in China, and UL 9540A in the United States each mandate distinct abuse-test protocols that force vendors to maintain region-specific certification portfolios. The EPA and OSHA in the United States add workplace and environmental compliance layers for thermal runaway containment infrastructure. Stakeholders must monitor how solid-state cell architectures alter calorimetry and pressure-vessel requirements before committing to next-generation platform investments.
Market Dynamics
Automotive solid-state battery programs are forcing test equipment vendors to recalibrate thermal runaway detection protocols and pressure-rated chamber specifications before 2025 platform commitments.
Growth Catalysts
- UN ECE R100 Revision 3:European cell-level abuse testing mandates now require nail penetration and overcharge validation at module scale, expanding chamber throughput requirements for export-bound suppliers.
- High-nickel cathode proliferation:NMC 811 and 9½½ formulations exhibit accelerated degradation signatures that demand sub-ppm coulombic efficiency resolution during formation cycling.
- Jiangsu-Guangdong corridor concentration:CATL and BYD gigafactory expansions in these provinces are absorbing multi-thousand-channel formation systems at unmatched capital deployment velocity.
Market Restraints
- Lithium hexafluorophosphate electrolyte price volatility:Input cost swings for reference cell production disrupt calibration standard pricing and test lab operating budgets.
- Single-source dependency on precision current sensor suppliers:German and Japanese component vendors concentrate 70% of high-accuracy shunt manufacturing, exposing equipment makers to allocation risk.
- UL 9540A thermal runaway propagation protocol:US fire safety certification requires 6-12 month validation cycles that delay new chamber model commercialization.
Strategic Opportunities
- Second-life battery grading:Automotive pack retirement streams are creating demand for rapid capacity-sorting test lines that bypass full formation protocols.
- Solid-state ceramic electrolyte characterization:Sulfide and oxide solid electrolytes require novel impedance spectroscopy methods and argon-atmosphere handling infrastructure.
- India PLI scheme localization:Battery manufacturing incentives are attracting test equipment vendors to establish calibration and service hubs near Reliance and Ola Electric facilities.
Industry Challenges
- Electrochemical engineering talent scarcity:Test system vendors compete with cell manufacturers for personnel skilled in equivalent circuit modeling and degradation mechanism identification.
- Legacy CAN bus integration friction:New high-speed data acquisition architectures must interface with automotive BMS validation benches running decade-old communication stacks.
- Multi-standard certification backlog:Simultaneous UN ECE R100, GB 38031, and UL 9540A qualification creates engineering bandwidth constraints for mid-tier equipment developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Battery Test Equipment Market |
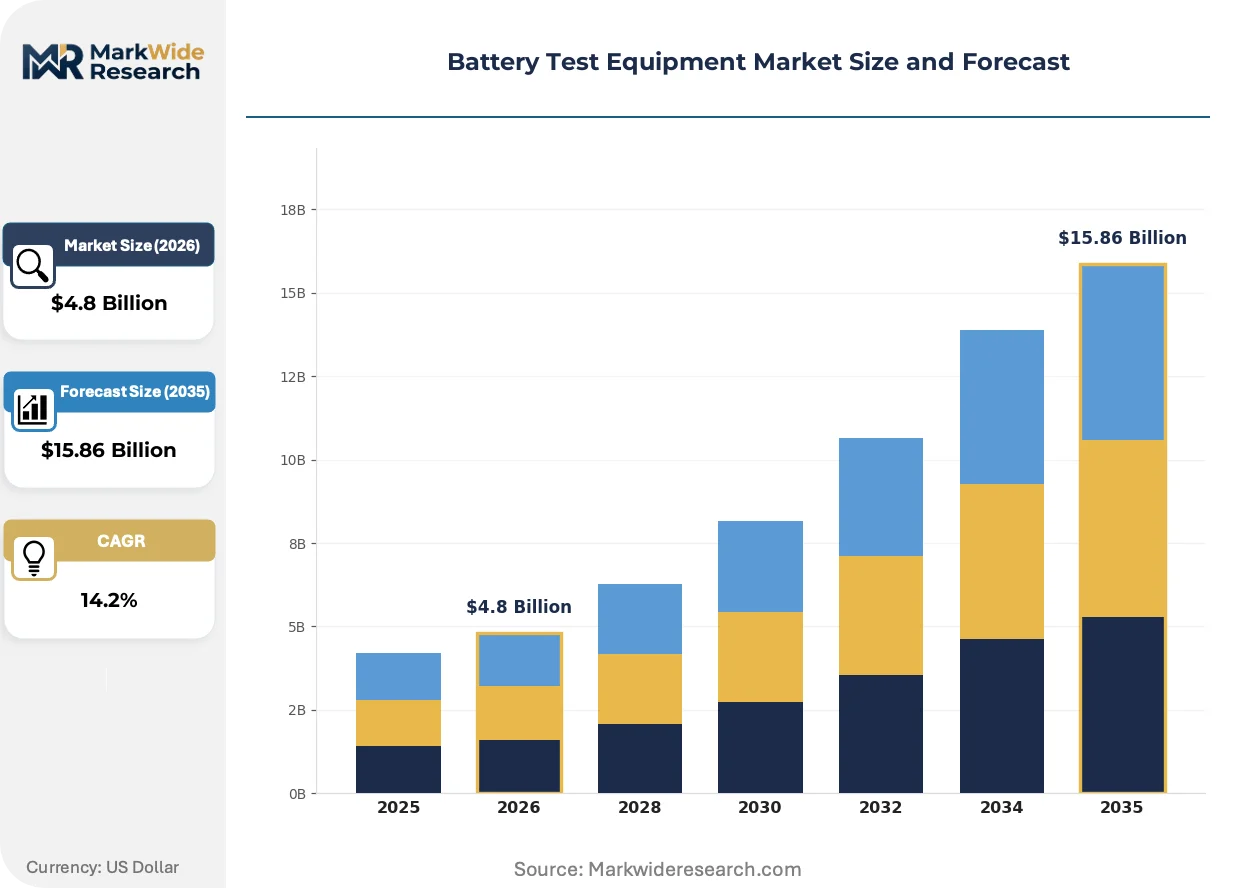
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $15.86 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Battery Analyzers, Cell Test Systems, Simulation Equipment, Load/Discharge Units End User: Aerospace, Automotive Manufacturers, Electronics Producers, Research Laboratories Technology: AC Measurement, DC Measurement, Thermal Imaging, Data Acquisition Application: Quality Control, Research & Development, Production Testing, Performance Evaluation |
| Companies Covered | Arbin Instruments, Chroma ATE, Bitrode Corporation, Maccor Inc., Ametek Scientific Instruments, DIGATRON, Midtronics, Neware Technology Limited, NH Research, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Battery Test Equipment Market Evolving Landscape
Test methodology is fragmenting across cell chemistries as solid-state, sodium-ion, and silicon-anode formats each demand specialized electrochemical characterization protocols that legacy platforms cannot accommodate.
High-channel cell formation systems are decomposing the traditional separation between laboratory precision and factory throughput. Equipment vendors now ship 512-channel cabinets with 0.02% current accuracy that match research-grade potentiostat resolution. Automotive cell manufacturers in Germany and South Korea are adopting these unified platforms to compress pilot-to-production transfer timelines from 18 months to 7 months.
GB 38031-2020 abuse testing amendments in China now mandate thermal runaway detection within 5 minutes of trigger initiation, compressing sensor response requirements. Equipment vendors must integrate multi-point fiber optic temperature monitoring and gas analysis modules to maintain access to CATL and BYD procurement lists. This regulatory tightening is accelerating replacement cycles for chambers installed before 2022.
Cell manufacturers are consolidating test service procurement under multi-year performance contracts that bundle equipment, maintenance, and data analytics. This model displaces discrete capital purchases in European automotive programs. The shift is most visible in Volkswagen Group and BMW supplier qualifications, where total-cost-per-test metrics now dominate channel selection.
Battery Test Equipment Market Segmentation
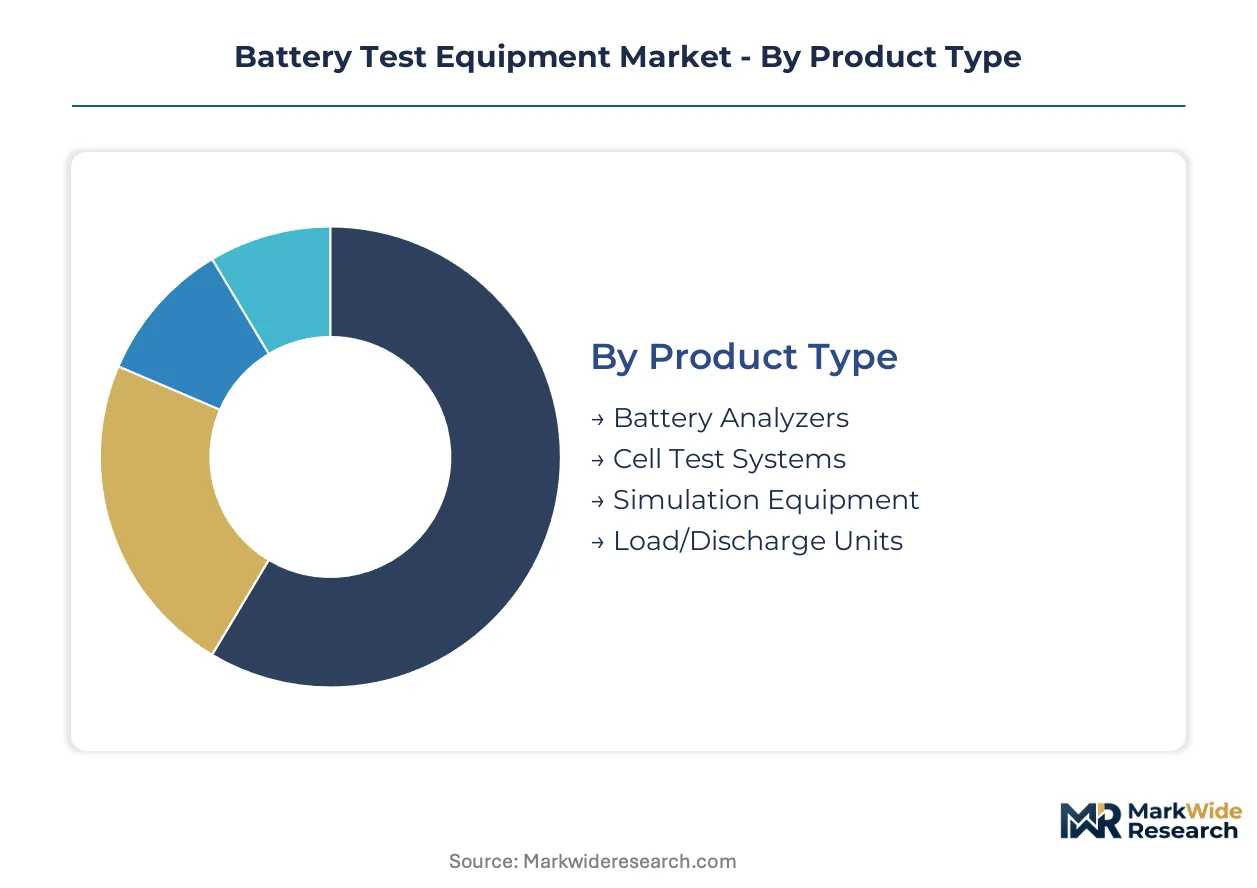
Segmentation in battery test equipment reflects divergent certification requirements across automotive, aerospace, and consumer electronics sectors. Each end-use imposes distinct precision, throughput, and safety containment specifications that reshape vendor product roadmaps.
Product Type:
UN ECE R100, GB 38031, and UL 9540A each mandate different chamber configurations, forcing vendors to maintain parallel hardware portfolios for export compliance.
- Cell Test Systems:Multi-channel potentiostat architectures deliver sub-ppm coulombic efficiency resolution during formation cycling. Demand concentrates in China's Jiangsu and Guangdong provinces where CATL and BYD operate gigascale battery plants, driven by high-nickel cathode validation requirements.
- Battery Analyzers:Portable and rack-mounted instruments verify pack-level state-of-health and state-of-charge parameters. Automotive manufacturers in Germany and South Korea deploy these for warranty validation and second-life grading decisions.
- Simulation Equipment:Hardware-in-the-loop platforms replicate drive cycles and grid storage profiles for BMS algorithm validation.
- Load/Discharge Units:High-power resistive and regenerative loads handle thermal runaway propagation testing under UL 9540A protocols.
Cell Test Systems handle the majority of throughput; Battery Analyzers are expanding most quickly on share.
End User:
Cost tier stratification separates capital-intensive automotive qualification from research laboratory premium procurement.
- Automotive Manufacturers:Solid-state and high-nickel cell programs demand 512-channel formation cabinets with 0.02% current accuracy. Volkswagen Group and BMW now bundle equipment, maintenance, and data analytics under multi-year performance contracts.
- Research Laboratories:Multi-channel potentiostats with impedance spectroscopy capability command premium pricing tiers. Academic and national lab procurement prioritizes measurement resolution over channel count.
- Electronics Producers:Consumer device and power tool manufacturers prioritize compact, high-throughput systems for cylindrical cell validation.
- Aerospace:Satellite and electric aviation programs require specialized thermal vacuum chambers and altitude simulation fixtures.
Automotive Manufacturers absorb the largest capital deployment; Research Laboratories extract the highest margin per channel.
Technology:
Application context determines whether AC or DC architectures dominate—laboratory precision favors AC impedance methods while production throughput demands DC coulometry.
- DC Measurement:Coulombic efficiency tracking at sub-ppm resolution enables degradation mechanism identification during formation cycling. Arbin Instruments sustains technology leadership through precision current sensing architectures.
- AC Measurement:Electrochemical impedance spectroscopy characterizes solid-state ceramic electrolyte interfaces. Sulfide and oxide solid electrolytes require novel frequency-domain methods and argon-atmosphere handling infrastructure.
- Thermal Imaging:Infrared arrays and fiber optic sensors detect thermal runaway initiation within GB 38031's five-minute mandate.
- Data Acquisition:Millisecond-resolution voltage, current, and temperature logging underpins abuse-test documentation for regulatory submission.
DC Measurement carries the heaviest channel volume; AC Measurement is climbing the fastest on share.
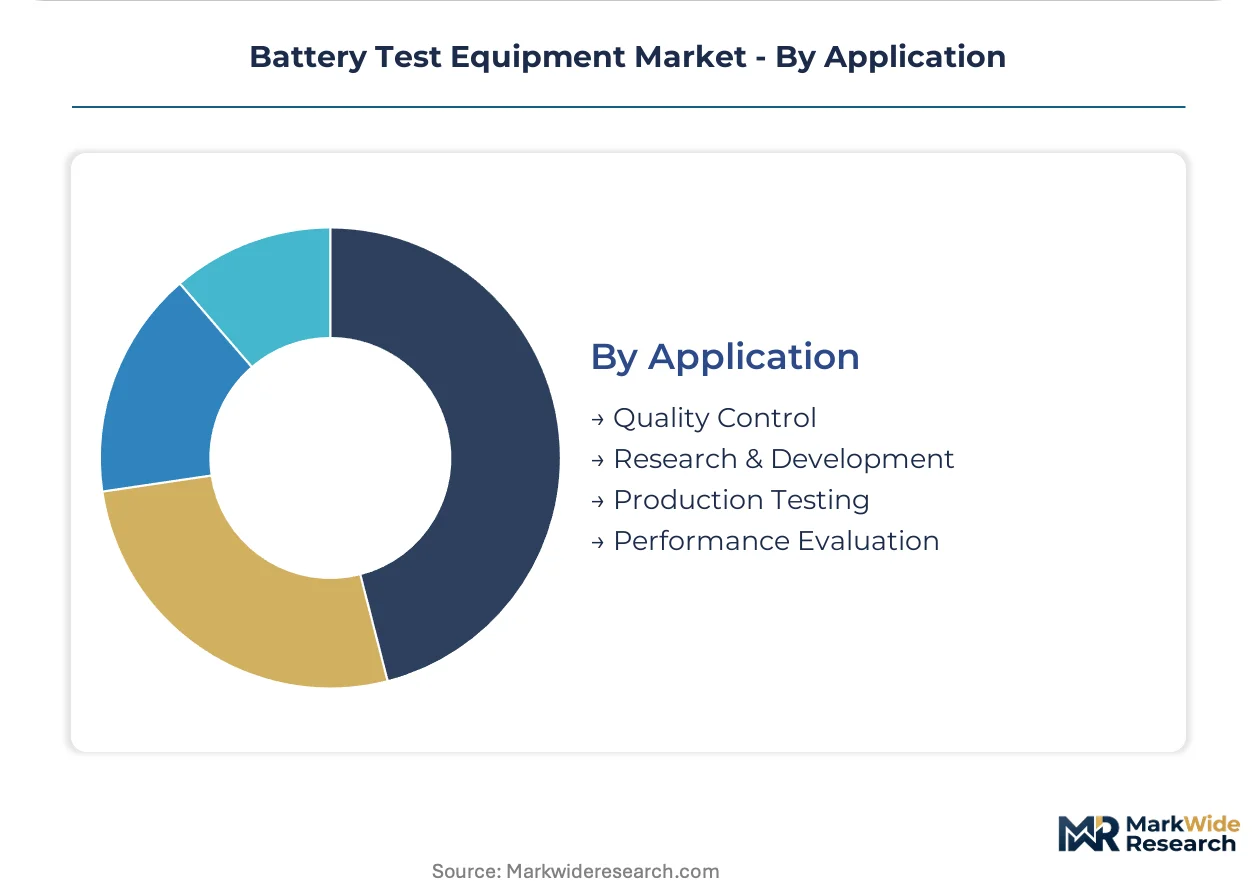
Application:
Customer type splits between discrete capital purchases and consolidated performance contracts, reshaping vendor business models.
- Production Testing:High-channel formation systems with unified laboratory-grade precision compress pilot-to-production transfer timelines. Equipment vendors now ship 512-channel cabinets that match research-grade potentiostat resolution.
- Research & Development:Modular potentiostat architectures enable rapid reconfiguration across cell chemistries. Maccor Inc. anchors North American laboratory demand with scalable hardware platforms.
- Quality Control:Incoming inspection and outgoing verification stations verify compliance with safety thresholds before mass production release.
- Performance Evaluation:Cycle-life guarantee validation and warranty reserve calculations depend on accelerated aging protocols.
Production Testing commands the greatest installed base; Research & Development shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
UN ECE R100 Revision 3 and GB 38031-2020 amendments are redirecting capital deployment toward certified abuse-test infrastructure. Equipment vendors with multi-standard certification portfolios capture procurement preference across export corridors.
China
GB 38031-2020 mandates thermal runaway detection within five minutes, compressing sensor response specifications for chamber vendors. CATL and BYD gigafactory expansions in Jiangsu and Guangdong provinces absorb multi-thousand-channel formation systems at unmatched velocity. The MIIT oversees battery safety standard alignment with automotive export requirements.
Germany
Volkswagen Group and BMW supplier qualifications now bundle equipment, maintenance, and data analytics under multi-year performance contracts. The KBA enforces UN ECE R100 Revision 3 compliance for cell-level abuse testing at module scale. Industrial clusters in Bavaria and Baden-Württemberg host solid-state battery pilot lines demanding recalibrated thermal runaway protocols.
United States
UL 9540A thermal runaway propagation certification requires six-to-twelve-month validation cycles that delay new chamber commercialization. The EPA and OSHA add workplace and environmental compliance layers for thermal runaway containment infrastructure. Michigan and California anchor automotive cell qualification demand.
South Korea
Automotive manufacturers adopt unified 512-channel formation platforms to compress pilot-to-production transfer timelines. MFDS alignment with international battery safety standards shapes export-bound equipment specifications. Seoul and Gyeonggi Province concentrate cell manufacturer procurement decisions.
India
PLI scheme localization incentives attract test equipment vendors to establish calibration and service hubs near Reliance and Ola Electric facilities. The CEA oversees grid-scale battery storage safety integration with renewable energy targets. Gujarat and Maharashtra host emerging cell manufacturing zones.
Battery Test Equipment Market Competitive Landscape
Player mix skews toward precision instrumentation specialists and high-volume formation system fabricators. The competitive structure concentrates around vendors with certified abuse-test chamber portfolios and sub-ppm coulombic efficiency resolution capabilities. Two strategic archetypes dominate: Taiwan-based R&D-intensive precision houses and North American modular architecture specialists. Competitive moves center on multi-standard certification acquisition and channel-count expansion in high-nickel formation systems.
Within the precision-tier segment, Arbin Instruments and Chroma ATE exemplify divergent geographic anchoring strategies. Arbin Instruments occupies a position among North American laboratory-grade specialists. Chroma ATE represents Taiwan-based R&D footprint advantages in high-channel cell formation. Maccor Inc. sits within the modular potentiostat architecture tier serving North American laboratory demand. These three companies illustrate how certification breadth and channel density separate procurement winners from compliance-locked challengers.
| Leading Market Players |
|---|
| Arbin Instruments |
| Chroma ATE |
| Bitrode Corporation |
| Maccor Inc. |
| Ametek Scientific Instruments |
| DIGATRON |
| Midtronics |
| Neware Technology Limited |
| NH Research |
| Others |
Value Network & Pricing Analysis
Multi-thousand-channel formation system deployments in Jiangsu and Guangdong provinces compress unit economics for high-volume cabinet architectures while elevating price floors for certified abuse-test chambers that lack scale leverage. This divergence between production-grade and laboratory-grade equipment reshapes how vendors allocate engineering bandwidth and manufacturing capacity.
Pricing Analysis
Certification level—UN ECE R100, GB 38031, UL 9540A—creates the primary spread between premium and standard tiers, with multi-standard qualified chambers commanding substantial premiums over single-protocol alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by channel count, measurement resolution, and after-sales bundling depth. Cost compression in standard-tier formation systems is intensifying because 512-channel cabinets with 0.02% accuracy now match research-grade resolution. Automotive manufacturers under multi-year performance contracts show least price sensitivity; mid-tier equipment developers facing certification backlog constraints absorb greatest margin pressure.
Supply Chain Analysis
Container availability fluctuations on Asia-Europe trade lanes disrupt inbound logistics for precision current sensor components sourced from German and Japanese vendors. Manufacturing concentration in Taiwan, China, and South Korea feeds from specialized electrochemical engineering talent pools and precision shunt fabrication capabilities. Single-source dependency on high-accuracy shunt suppliers exposes equipment makers to allocation risk during semiconductor cycle upturns. Distribution runs through direct OEM relationships for automotive qualification programs and regional service hubs for laboratory and aftermarket segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Data analytics and predictive maintenance layers now expand faster than hardware shipments, transforming capital equipment vendors into recurring-revenue service platforms. This service-attach dynamic favors vendors that bundle calibration, software upgrades, and performance guarantees under multi-year contracts.
For Market Incumbents: Fortify certification breadth across UN ECE R100, GB 38031, and UL 9540A to lock out mid-tier challengers facing engineering bandwidth constraints. Deepen backward integration into precision current sensor architectures to reduce exposure to German and Japanese supplier allocation risk. Anchor capacity expansion in Jiangsu-Guangdong corridor proximity to capture CATL and BYD procurement velocity.
For New Entrants and Emerging Players: Differentiate on solid-state ceramic electrolyte characterization capabilities—sulfide and oxide protocols remain underserved by legacy platform vendors. Target India PLI scheme localization requirements where calibration and service hub infrastructure gaps persist near Reliance and Ola Electric facilities. Pursue rapid capacity-sorting test lines for second-life battery grading as automotive pack retirement streams accelerate.
For Investors and Strategic Acquirers: Precision-tier specialists with sub-ppm coulombic efficiency resolution and modular potentiostat architectures represent the most defensible acquisition profile. Long-term viability hinges on R&D intensity sustaining chemistry-agnostic platform evolution across sodium-ion, silicon-anode, and solid-state formats. Watch solid-state pilot line commitments by automotive OEMs as inflection indicator for next-generation calorimetry and pressure-vessel demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Standard Certification Acquisition | UN ECE R100, GB 38031, and UL 9540A alignment secures procurement access across export corridors. |
| Channel Count Expansion | 512-channel cabinets with laboratory-grade resolution compress pilot-to-production transfer timelines for automotive clients. |
| Service Contract Bundling | Equipment-maintenance-analytics packages displace discrete capital purchases in Volkswagen Group and BMW supplier qualifications. |
| Solid-State Protocol Development | Argon-atmosphere handling and impedance spectroscopy methods address sulfide and oxide electrolyte characterization gaps. |
| India Localization Investment | Calibration and service hubs near Reliance and Ola Electric facilities capture PLI scheme procurement preference. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with test equipment procurement managers at CATL and BYD, calibration service directors, automotive cell qualification engineers, and laboratory instrumentation specialists at national research facilities. Secondary validation drew from MIIT battery safety standard filings, KBA type-approval documentation, UL 9540A certification registries, and customs data on precision current sensor trade flows. Bottom-up channel count estimates and top-down capital deployment trajectories were triangulated to anchor market sizing.
Across the analysis window, the forecasting framework modeled product type segmentation—cell test systems, battery analyzers, simulation equipment, load/discharge units—against end-user categories, technology architectures, and application contexts. CAGRs were derived from equipment shipment velocities correlated with gigafactory expansion pipelines and regulatory amendment implementation timelines. Solid-state battery pilot line commitments and high-nickel cathode formation cycling requirements served as chemistry-specific demand drivers.
The analysis sits within stated boundaries; outcomes outside continued automotive electrification capital deployment, stable lithium hexafluorophosphate electrolyte pricing, and sustained multi-standard regulatory convergence would require recalibration. Forecasts reflect assumptions on certification timeline predictability and electrochemical engineering talent availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Next-Generation Industrial Metrology and Inspection Market
Test and Measurement
Global Laser Tracker Market
Test and Measurement
Electromagnetic Compatibility Test Equipment and Testing Services Market
Test and Measurement
Test and Measurement Market
Test and Measurement
United States Borescope Market
Test and Measurement
Battery Testing Equipment Market
Test and Measurement
Smart Contact Lens Optical and Telemetry Test Equipment Market
Test and Measurement
Electric Vehicle Edrive Test System Market
Test and Measurement
MEMS and Sensor Performance and Reliability Test Equipment Market
Test and Measurement
Miniaturized Package Solder Joint Reliability Test Equipment Market
Test and Measurement
Semiconductor Bond Testing Market
Test and Measurement
5G Testing Devices Market
Test and Measurement
Portable Appliance Tester (PAT) Market
Test and Measurement
Semiconductor Metrology and Inspection Equipment Market
Test and Measurement
Battery CT Inspection Market
Test and Measurement
Millimeter-Wave and Sub-THz Semiconductor Device Characterization Platforms Market