
 Ultrasonic Flaw Detector Market | 2026-2036
Ultrasonic Flaw Detector Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Flaw Detector Market Outlook
Modular probe configurations is decoupling hardware from software purchasing decisions across industrial buyers. Olympus (Evident) leverages its phased array probe ecosystem to sustain recurring revenue from transducer upgrades. Baker Hughes (GE) anchors its position through integrated inspection workflows for pipeline integrity programs. Eddyfi Technologies differentiates via portable instrument specialization for rope-access inspection teams in offshore environments.
An ultrasonic flaw detector is an electromechanical instrument that transmits high-frequency sound waves, typically between 0.5 and 25 MHz, through a material to identify internal discontinuities such as cracks, voids, or inclusions. Its primary commercial purpose is to verify structural integrity without destroying the test specimen, thereby reducing warranty exposure and catastrophic failure risk in critical infrastructure. Portable detectors dominate field deployment scenarios where mobility outweighs laboratory precision, while automated systems capture margin pools in high-volume manufacturing lines requiring repeatable scan patterns. Phased array technology leads growth trajectories due to its ability to steer beam angles electronically, reducing inspection time for complex geometries in aerospace components.
FAA airworthiness directives and ASME boiler pressure vessel codes shape product certification requirements and create compliance-driven replacement cycles for inspection equipment. OSHA workplace safety standards and ISO 17640 weld testing protocols further standardize performance benchmarks that manufacturers must satisfy for market access. Stakeholders should monitor evolving regulatory harmonization between FAA and EASA certification pathways, as divergence in acceptable defect sizing thresholds could fragment product development roadmaps and testing service qualifications.
Market Dynamics
Phased array ultrasonic technology is compressing inspection cycle times for complex aerospace geometries, forcing equipment refresh decisions across maintenance, repair, and overhaul networks. This shift is redistributing margin from conventional probe manufacturers toward software-integrated platform vendors.
Growth Catalysts
- FAA Airworthiness Directives:Mandated structural inspection intervals for aging commercial fleets sustain replacement demand for portable flaw detection systems in US MRO facilities.
- ASME Boiler Pressure Vessel Code:Weld integrity verification requirements in energy infrastructure drive recurring instrumentation upgrades across North American power generation and petrochemical sites.
- Offshore Wind Foundation Inspection:Subsea weld monitoring protocols for monopile installations create specialized demand for immersion-capable phased array systems in European maritime construction.
Market Restraints
- Piezoelectric Ceramic Supply Concentration:Transducer manufacturing depends on specialized ceramic substrates sourced from limited East Asian suppliers, exposing lead times to geopolitical friction.
- Capital Intensity of Certification:TÜV and ISO 17025 accreditation for inspection service providers requires substantial instrumentation investment, freezing smaller testing firms out of aerospace contract pools.
- Radiographic Testing Substitution:Digital radiography systems with automated defect recognition are capturing share in pipeline girth weld applications where archive documentation requirements favor filmless methods.
Strategic Opportunities
- India Infrastructure Modernization:Bureau of Indian Standards adoption of ISO 17640 weld testing protocols for steel bridge construction opens replacement cycles for obsolete manual ultrasonic equipment.
- Drone-Mounted Inspection:Aerial deployment of lightweight phased array systems for storage tank roof surveys eliminates scaffolding costs and accelerates turnaround in refining operations.
- Battery Manufacturing Quality Control:Solid-state cell production lines require non-destructive verification of electrode-to-tab welds, extending ultrasonic applications beyond traditional metals inspection.
Industry Challenges
- Phased Array Operator Certification:ASNT Level II qualification requirements for beam steering interpretation create talent bottlenecks, constraining deployment velocity despite hardware availability.
- Legacy System Integration:Automated inspection cells in automotive body-in-white production require protocol bridges to connect modern phased array controllers with 1990s-era plant control networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Flaw Detector Market |
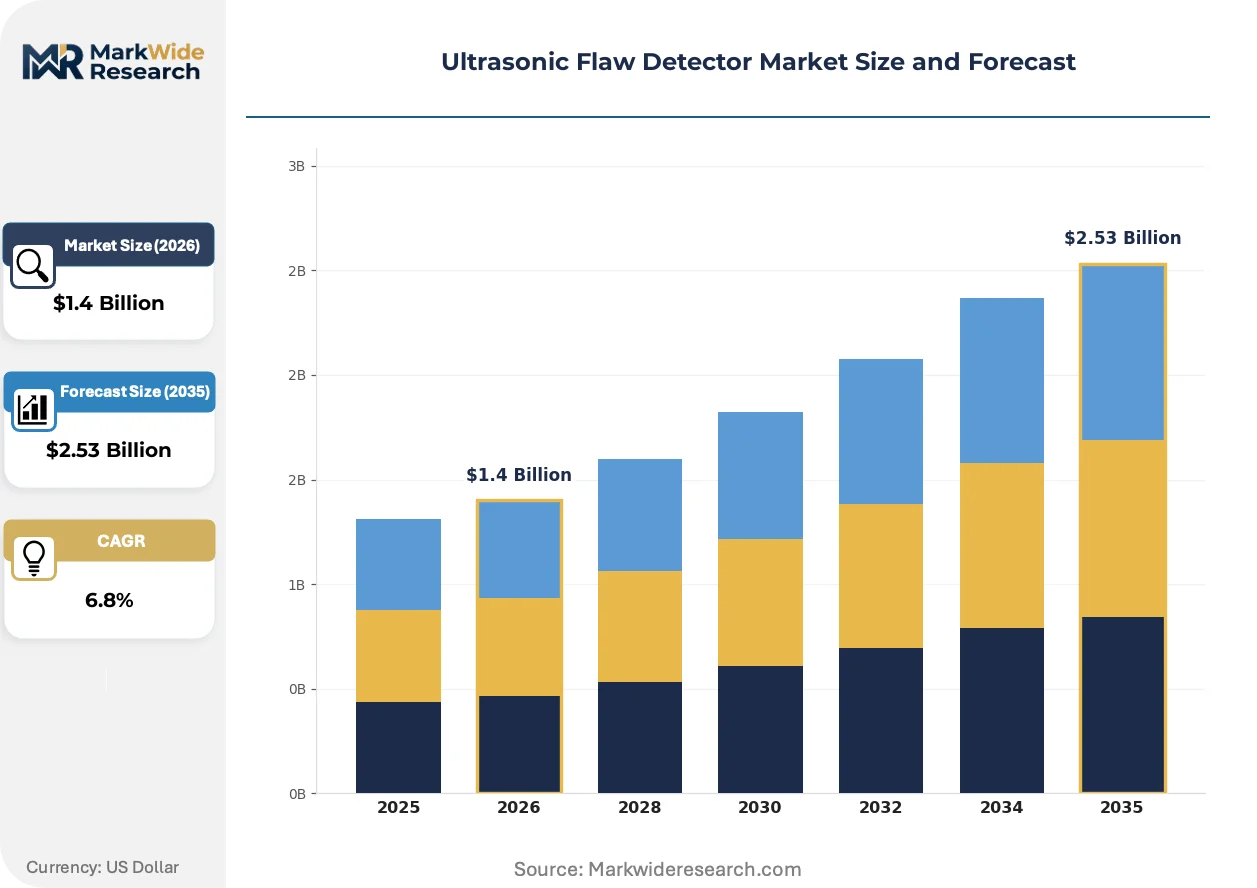
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Detectors, Fixed Detectors, Automated Systems, Specialty Devices End User: Aerospace, Manufacturing, Oil & Gas, Construction Technology: Pulsed Wave, Continuous Wave, Dual-Element, Phased Array Application: Weld Inspection, Material Testing, Bridge Inspection, Aerospace Components |
| Companies Covered | Eddyfi Technologies, Zetec, Baker Hughes (GE), Hitachi Power Solutions, Dakota Ultrasonics, Olympus (Evident), Krautkramer (Hexagon Company), HUATEC Group, Sonatest, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Flaw Detector Market Strategic Shifts
Inspection data monetization is restructuring competitive advantage around software analytics rather than hardware specifications. Vendors are repositioning around predictive maintenance integration and cloud-based defect archiving.
Total Focusing Method algorithms are overtaking conventional phased array reconstruction in aerospace turbine blade inspection. Rolls-Royce and Pratt & Whitney maintenance operations have standardized on TFM-enabled systems for single-crystal superalloy defect mapping. This compression of analysis time from hours to minutes is overtaking legacy A-scan interpretation workflows and forcing training curriculum overhauls at technical institutes.
The EU AI Act's risk classification framework for safety-critical inspection automation is reshaping product development roadmaps for European manufacturers. High-risk categorization of autonomous defect recognition triggers conformity assessment obligations that delay market entry. German TÜV and French ANSM coordination on AI validation protocols is creating a two-speed certification landscape that favors established vendors with regulatory affairs capacity.
Service unbundling is fragmenting the traditional instrument sale model. Offshore inspection contractors in the North Sea now lease phased array units with per-scan data pricing rather than capital purchase, transferring obsolescence risk to OEMs. This consumption shift concentrates in Norway and UK decommissioning projects where project-based budgeting dominates capital allocation.
Ultrasonic Flaw Detector Market Segmentation
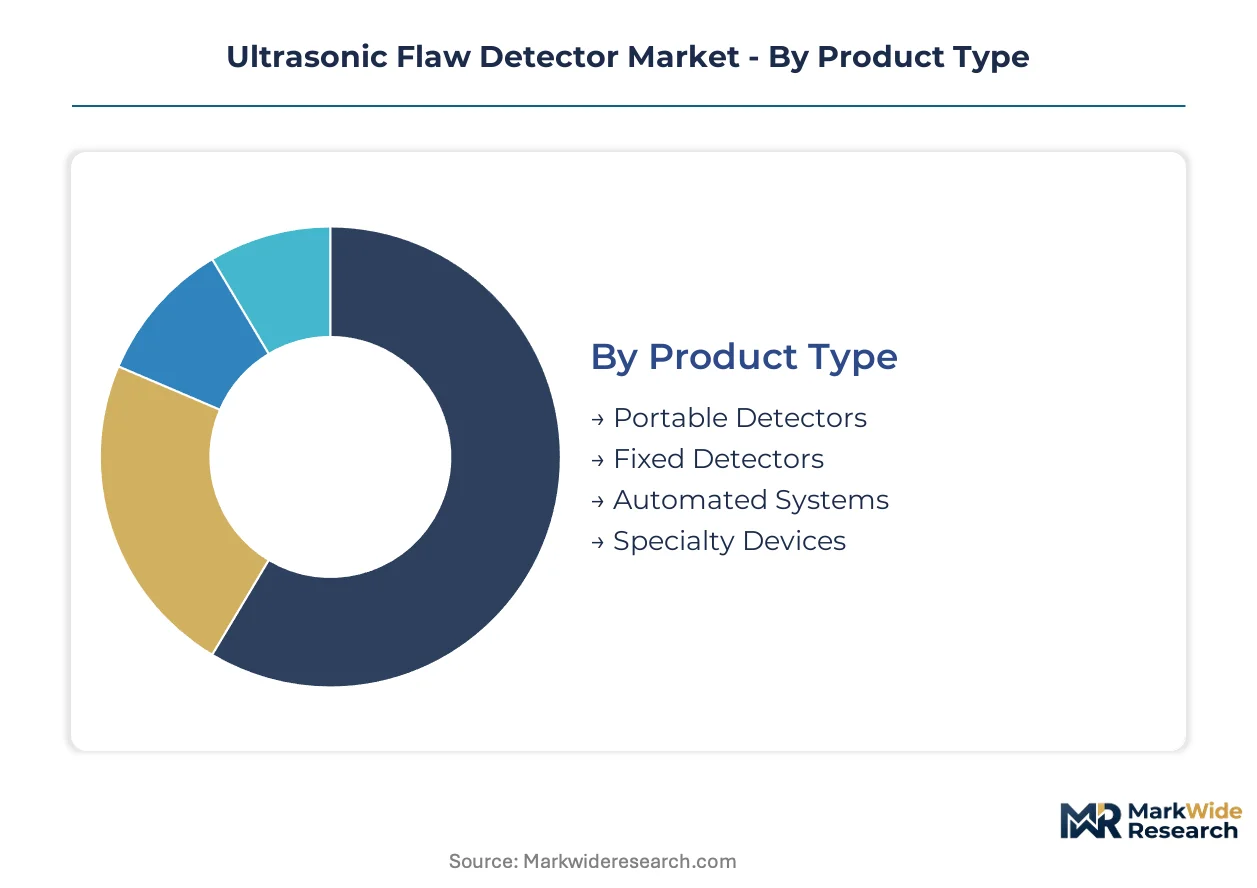
Segmentation in the ultrasonic flaw detector market reveals how inspection workflows, regulatory environments, and capital deployment patterns fragment demand across hardware configurations and service models. Buyers prioritize portability, automation depth, or analytical sophistication based on field conditions and compliance mandates.
Product Type:
Cost tier separates buyers in this category, with capital availability dictating hardware sophistication and software integration depth.
- Portable Detectors:Battery-powered units weighing under 5 kg dominate field deployment where rope-access technicians inspect offshore platforms and wind turbine towers. Demand concentrates in Norway and UK decommissioning projects where project-based budgeting favors lease arrangements over capital purchase.
- Automated Systems:Robotic scanning cells with encoded motion control capture high-volume manufacturing lines requiring repeatable scan patterns. German automotive OEMs deploy these for body-in-white weld verification, integrating phased array controllers with legacy plant networks through protocol bridges.
- Fixed Detectors:Permanent installation units monitor pipeline compressor stations and power generation assets for continuous integrity assessment.
- Specialty Devices:Immersion-capable systems serve subsea weld monitoring protocols for European monopile installations.
Volume sits with portable detectors; growth tilts toward automated systems.
End User:
Application maturity drives technology selection, with established sectors favoring proven methods while emerging use cases adopt phased array platforms.
- Aerospace:FAA airworthiness directives mandate structural inspection intervals for aging commercial fleets, sustaining replacement demand at US MRO facilities. Rolls-Royce and Pratt & Whitney maintenance operations have standardized on TFM-enabled systems for single-crystal superalloy defect mapping.
- Oil & Gas:Pipeline integrity programs require integrated inspection workflows covering girth welds, corrosion mapping, and crack detection. Offshore contractors in the North Sea now lease phased array units with per-scan data pricing rather than capital purchase.
- Manufacturing:Solid-state battery cell production lines require non-destructive verification of electrode-to-tab welds, extending ultrasonic applications beyond traditional metals.
- Construction:Bureau of Indian Standards adoption of ISO 17640 weld testing protocols for steel bridge construction opens replacement cycles for obsolete manual equipment.
Aerospace commands premium pricing; battery manufacturing represents the steepest expansion trajectory.
Technology:
Beam control sophistication separates performance tiers, with electronic steering capabilities compressing inspection cycle times for complex geometries.
- Phased Array:Electronic beam angle steering reduces inspection time for aerospace components with complex geometries. ASNT Level II qualification requirements for beam steering interpretation create talent bottlenecks, constraining deployment velocity despite hardware availability.
- Pulsed Wave:Conventional A-scan interpretation remains prevalent in legacy infrastructure and cost-sensitive applications where technician familiarity outweighs speed advantages.
- Continuous Wave:Resonance-based methods serve thickness gauging applications in corrosion monitoring.
- Dual-Element:Separate transmit-receive configurations optimize near-surface defect detection in rough casting inspections.
Pulsed wave retains installed base dominance; phased array gains share fastest.
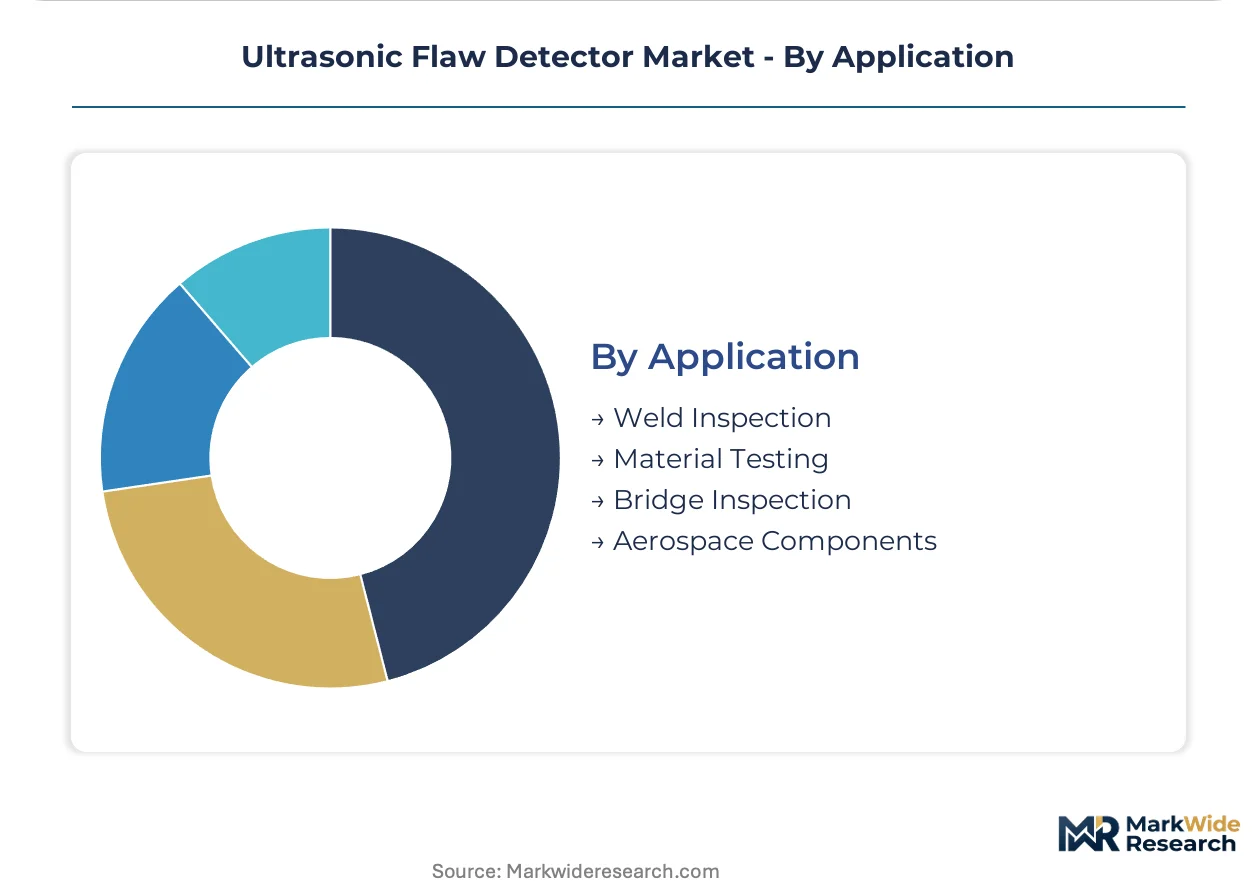
Application:
Documentation requirements and defect acceptance criteria shape instrumentation selection, with safety-critical applications demanding certified traceability.
- Weld Inspection:ASME Boiler Pressure Vessel Code requirements drive recurring instrumentation upgrades across North American power generation and petrochemical sites. Digital radiography systems compete for pipeline girth weld applications where archive documentation requirements favor filmless methods.
- Aerospace Components:Single-crystal superalloy turbine blades require Total Focusing Method algorithms for defect mapping. EU AI Act risk classification for autonomous defect recognition triggers conformity assessment obligations that delay market entry for automated interpretation systems.
- Material Testing:Foundry and forging operations verify internal integrity of cast components before machining operations.
- Bridge Inspection:Drone-mounted lightweight phased array systems for storage tank roof surveys eliminate scaffolding costs and accelerate turnaround in refining operations.
Weld inspection anchors revenue; aerospace components climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in Germany and the United States where precision instrument manufacturing meets aerospace certification requirements, while consumption spreads across maintenance networks in Norway, India, and China driven by infrastructure buildouts and fleet expansion programs.
Germany
TÜV-certified inspection services drive replacement cycles for precision testing equipment across automotive and aerospace supply chains. The EU AI Act's risk classification framework triggers conformity assessment obligations for autonomous defect recognition systems. Munich and Stuttgart industrial clusters host calibration laboratories serving European MRO facilities with phased array verification protocols.
United States
FAA airworthiness directives mandate structural inspection intervals for aging commercial fleets, sustaining replacement demand at MRO facilities in Oklahoma and Texas. OSHA workplace safety standards standardize performance benchmarks for portable flaw detection deployment. Houston's energy corridor integrates inspection workflows with pipeline integrity programs covering girth welds and corrosion mapping.
Norway
Offshore wind foundation inspection protocols for monopile installations create specialized demand for immersion-capable phased array systems. Project-based budgeting in North Sea decommissioning drives lease arrangements over capital purchase for rope-access inspection teams. Stavanger and Bergen serve as logistics hubs for subsea weld monitoring equipment deployment.
India
Bureau of Indian Standards adoption of ISO 17640 weld testing protocols for steel bridge construction opens replacement cycles for obsolete manual ultrasonic equipment. Central Electricity Authority regulations mandate non-destructive testing for power generation asset integrity. Mumbai-Pune and Delhi-Mumbai Industrial Corridor clusters absorb portable detectors for infrastructure modernization programs.
China
GB standards alignment with international weld testing protocols expands domestic manufacturing quality control requirements. MIIT industrial upgrading programs subsidize precision inspection equipment for high-speed rail and nuclear component suppliers. Yangtze River Delta manufacturing bases deploy automated scanning cells for export-oriented automotive production.
Ultrasonic Flaw Detector Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across hardware, software, and service layers. The market exhibits tiered concentration with premium-tier vendors capturing aerospace certification workflows and mid-tier suppliers serving cost-sensitive infrastructure applications. Three archetypes dominate: integrated industrial technology conglomerates with cross-sector inspection portfolios, specialized non-destructive testing equipment manufacturers with deep probe ecosystems, and regional fabricators targeting price-competitive emerging markets. Competitive moves center on phased array software licensing partnerships and backward integration into piezoelectric ceramic supply chains.
Among North American diversified industrial groups, Baker Hughes anchors integrated inspection workflows for energy infrastructure while Eddyfi Technologies exemplifies portable instrument specialization for offshore environments. Olympus represents the probe-ecosystem archetype through its phased array transducer upgrade programs. Zetec and Sonatest occupy positions within the mid-tier inspection equipment segment serving power generation and manufacturing quality control applications.
| Leading Market Players |
|---|
| Eddyfi Technologies |
| Zetec |
| Baker Hughes (GE) |
| Hitachi Power Solutions |
| Dakota Ultrasonics |
| Olympus (Evident) |
| Krautkramer (Hexagon Company) |
| HUATEC Group |
| Sonatest |
| Others |
Value Chain & Pricing Dynamics
Aerospace MRO procurement networks in Oklahoma and Texas concentrate purchasing power for TÜV-certified phased array systems, forcing three-tier pricing structure across premium, standard, and economy levels based on software integration depth and probe ecosystem breadth.
Pricing Analysis
Margin tightening in mid-tier portable detectors reflects ASNT Level II certification bottlenecks constraining deployment velocity despite hardware availability. Cost-down pressure on economy-grade pulsed wave units accelerates because Indian bridge construction contractors prioritize technician familiarity over speed advantages. Price differentiation separates FAA-compliant aerospace platforms from ISO 17640-weld-certified infrastructure equipment. Offshore wind contractors in Norway exhibit highest price sensitivity through per-scan lease arrangements, while Rolls-Royce maintenance operations show lowest sensitivity for TFM-enabled turbine blade systems.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Houston, and Singapore coordinate hub-and-spoke patterns for probe calibration and instrument verification. Manufacturing concentrates in Germany, Japan, and the United States where precision ceramic substrate processing meets aerospace certification requirements. Transducer production draws from specialized piezoelectric ceramic supply chains anchored in East Asian substrate foundries. Single-source vulnerability in lead zirconate titanate ceramic substrates exposes lead times to geopolitical friction. Distribution runs through TÜV-certified calibration laboratories serving European MRO facilities with phased array verification protocols.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FAA airworthiness directives create a cost-of-compliance moat that freezes smaller testing firms out of aerospace contract pools, privileging incumbents with regulatory affairs capacity and accredited calibration infrastructure.
For Market Incumbents: Extend phased array software licensing partnerships to capture recurring revenue from transducer upgrade cycles across aging commercial fleet inspection networks. Backward integration into piezoelectric ceramic supply chains defends against East Asian substrate concentration risks. Capacity addition in Stuttgart industrial clusters reinforces TÜV-certified service positioning against emerging pure-play specialists. For New Entrants and Emerging Players: Calibration laboratory partnerships in India offer the most penetrable entry vector for obsolete manual equipment replacement cycles under Bureau of Indian Standards ISO 17640 adoption. Drone-mounted inspection hardware for storage tank roof surveys represents underserved white space where scaffolding cost elimination justifies premium positioning. Go-to-market through rope-access contractor leasing programs in North Sea decommissioning projects bypasses capital purchase barriers. For Investors and Strategic Acquirers: The window for entry favors probe-ecosystem specialists with ASNT training curriculum integration and cloud-based defect archiving capabilities. Five-to-ten year viability hinges on predictive maintenance software monetization rather than hardware specifications. The signal to watch is EU AI Act conformity assessment completion rates for autonomous defect recognition systems, which will bifurcate vendor tiers across European aerospace supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Phased Array Software Licensing Partnership | Olympus leverages transducer ecosystem to sustain recurring revenue from aerospace MRO upgrade cycles. |
| Backward Integration into Ceramic Substrates | Captive supply of lead zirconate titanate substrates mitigates East Asian single-source vulnerability for transducer manufacturing. |
| Drone-Mounted Hardware Development | Eddyfi Technologies eliminates scaffolding costs for storage tank roof surveys in Houston refining operations. |
| ASNT Training Curriculum Integration | Technical institute partnerships address Level II qualification bottlenecks constraining phased array deployment velocity. |
| Cloud-Based Defect Archiving Platform | Inspection data monetization shifts competitive advantage from hardware specifications to predictive maintenance analytics. |
Study Parameters
Document review covered FAA airworthiness directive filings, ASME boiler pressure vessel code updates, and TÜV certification registries, complemented by interviews with maintenance directors at US MRO facilities, technical training institute curriculum designers, and procurement leads at Norwegian offshore wind contractors. Secondary validation drew from customs trade data for piezoelectric ceramic substrates, SEC filings from diversified industrial conglomerates, and ISO 17025 accreditation databases. Bottom-up and top-down triangulation reconciled instrument shipment volumes with service provider capacity expansion announcements.
Segmentation outputs reflect product type, end-use industry, beam control technology, and application workflow across the analysis window. CAGRs derived from regression analysis of replacement cycle timing against regulatory mandate implementation schedules. Forecast inputs incorporated Bureau of Indian Standards adoption timelines for ISO 17640 protocols and EU AI Act risk classification rollout for autonomous defect recognition systems.
Caveats apply where FAA-EASA divergence in acceptable defect sizing thresholds or piezoelectric ceramic supply disruptions could materially shift the outlook. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Digital Weighing Terminal Market
Test and Measurement
Advanced Probe Card and Wafer Probing Test Systems Market
Test and Measurement
Nanomechanical Testing Market
Test and Measurement
Automated Calibration-as-a-Service Platforms for Test and Measurement Assets Market
Test and Measurement
Leak Testing Machine Market
Test and Measurement
Photometer and Calorimeter Market
Test and Measurement
EMC Electromagnetic Compatibility Test Laboratory Market
Test and Measurement
Resonant Testing Machines Market
Test and Measurement
Europe NDT Equipment Market
Test and Measurement
NIR Moisture Analyzers Sales Market
Test and Measurement
Non-Destructive Testing (NDT) Service Market
Test and Measurement
Global in Circuit Tester Market
Test and Measurement
Fuel Capacitance Test Equipment Market
Test and Measurement
Durometer Calibration Service Market
Test and Measurement
Impact Testing Machine Market
Test and Measurement
Mud Test Equipment Market