
 Shock Data Logger Market | 2026-2036
Shock Data Logger Market Size, Share, and Industry Trends Forecast 2026-2036
Shock Data Logger Market Analytics
Buyer concentration in the automotive sector is pivoting toward tier-one suppliers and specialized test houses as OEMs outsource validation work. National Instruments leverages its PXI platform dominance to anchor high-channel-count shock measurement systems for crash laboratories. Yokogawa Electric Corporation competes through precision piezoelectric signal conditioning and established relationships with Japanese automotive regulators. Kistler Group specializes in piezoelectric force and acceleration sensors, sustaining its position in motorsport and defense test protocols.
A shock data logger is an instrumented device that records acceleration-time histories using piezoelectric or MEMS sensing elements, typically sampling at rates exceeding 10 kHz to capture transient mechanical events. These devices serve to document impact severity, validate protective packaging, and certify structural compliance across transportation and product safety regimes. Wireless data loggers are gaining share fastest where tethered installations prove impractical, while standalone units retain margin pools in budget-constrained electronics manufacturing. The accelerometer technology segment leads unit volume, though MEMS sensors are displacing legacy piezoelectric designs in cost-sensitive logistics monitoring applications.
The US NHTSA Federal Motor Vehicle Safety Standards and the EU's UNECE WP.29 framework mandate documented crash pulse data, directly shaping logger sampling requirements and calibration traceability. Japan's METI enforces similar documentation for domestic vehicle type approval, while ISO 6487 defines the mechanical filtering and channel classifications that manufacturers must satisfy for international market access. Stakeholders must monitor whether cloud-based deployment architectures satisfy emerging data sovereignty rules across multiple jurisdictions before committing to platform strategies.
Market Dynamics
Wireless telemetry adoption is compressing installation timelines for crash-test facilities while simultaneously exposing data sovereignty vulnerabilities across multi-jurisdictional deployments.
Growth Catalysts
- NHTSA FMVSS 208/214 mandates:Documented crash pulse requirements drive high-channel-count logger procurement for frontal and side-impact validation protocols in US test laboratories.
- Euro NCAP 2026 protocols:Expanded pedestrian protection and active safety testing expands sensor node density requirements for European validation centers.
- MEMS cost curves:Silicon micromachining advances reduce unit economics for logistics monitoring applications below piezoelectric thresholds.
Market Restraints
- Piezoelectric crystal supply:Lead zirconate titanate sourcing concentrates among Japanese and Chinese specialty ceramic producers, creating input volatility.
- Calibration infrastructure:ISO 16063-11 traceable shock calibration services cluster in Germany, Japan, and the United States, limiting facility expansion elsewhere.
- Optical fiber sensing substitution:Fiber Bragg grating systems capture extreme-g events without electromagnetic interference, threatening niche high-shock applications.
Strategic Opportunities
- India automotive testing:NCAP Bharat implementation and domestic OEM validation center buildouts create greenfield demand for channel-expandable systems.
- Battery pack abuse testing:Thermal runaway propagation studies for electric vehicle certification require multi-point shock-vibration-temperature synchronized logging.
- Cloud-edge hybrid architectures:Real-time anomaly detection at the edge with sovereign cloud storage addresses emerging data localization requirements in the EU and China.
Industry Challenges
- Multi-physics calibration expertise:Simultaneous shock, temperature, and humidity validation requires cross-functional metrology skills scarce outside established automotive clusters.
- Legacy system integration:Tethered logger installations from the 2010s resist wireless retrofit without full channel replacement, complicating facility upgrade cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Shock Data Logger Market |
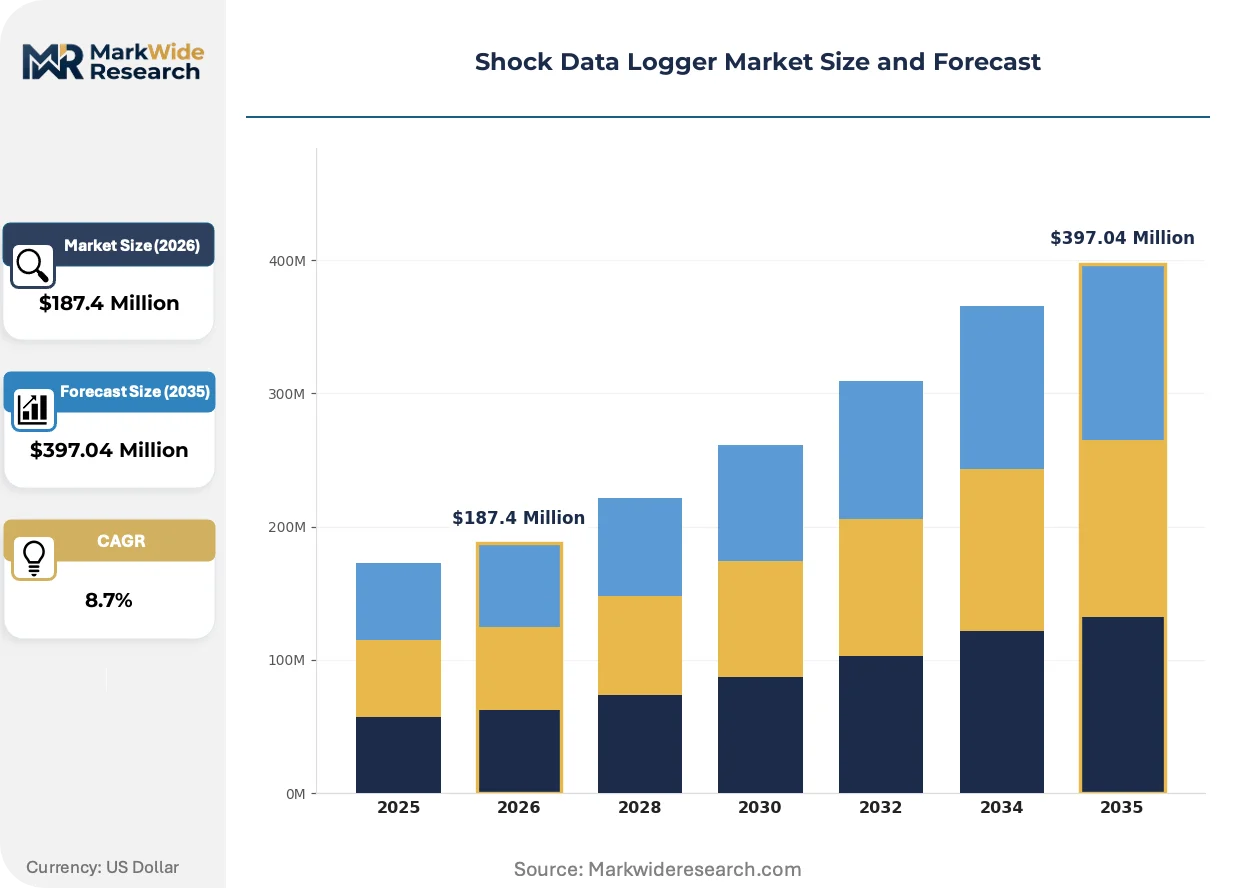
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standalone Data Loggers, Wireless Data Loggers, USB Data Loggers, Network Data Loggers End User: Aerospace, Automotive, Shipping, Electronics Deployment: On-Premise, Remote, Cloud-Based, Hybrid Technology: Accelerometer, MEMS Sensors, Piezoelectric Sensors, Digital Sensors |
| Companies Covered | National Instruments, Keysight Technologies, Yokogawa Electric Corporation, Omega Engineering, MadgeTech, Inc., Testo SE & Co. KGaA, Onset Computer Corporation, Kistler Group, Diversified Technical Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Shock Data Logger Market Evolving Landscape
Sensor fusion architectures and sovereign data handling requirements are redefining competitive differentiation beyond raw sampling specifications.
Tri-axial MEMS arrays with onboard digital signal processing are electrifying low-cost logistics monitoring by eliminating external charge amplifiers and enabling direct USB-C data retrieval. Third-party fulfillment providers in the United States and Germany are deploying these units at pallet-level granularity. The technology is compressing margin pools for standalone piezoelectric units below 500g full-scale range.
UNECE WP.29's cybersecurity management system requirements for vehicle type approval are mandating encrypted data transmission from onboard crash recorders. Test facilities must now demonstrate end-to-end chain-of-custody protocols that satisfy both the regulation and OEM audit requirements. European validation houses are responding by segregating logger networks from general IT infrastructure.
Equipment-as-a-service contracts are displacing capital purchase models for mid-size electronics manufacturers in Japan and South Korea. HIOKI and other regional suppliers offer per-test pricing with included calibration and firmware maintenance. This consumption pattern is most visible among contract manufacturers serving automotive tier-one suppliers with irregular validation volumes.
Shock Data Logger Market Segmentation
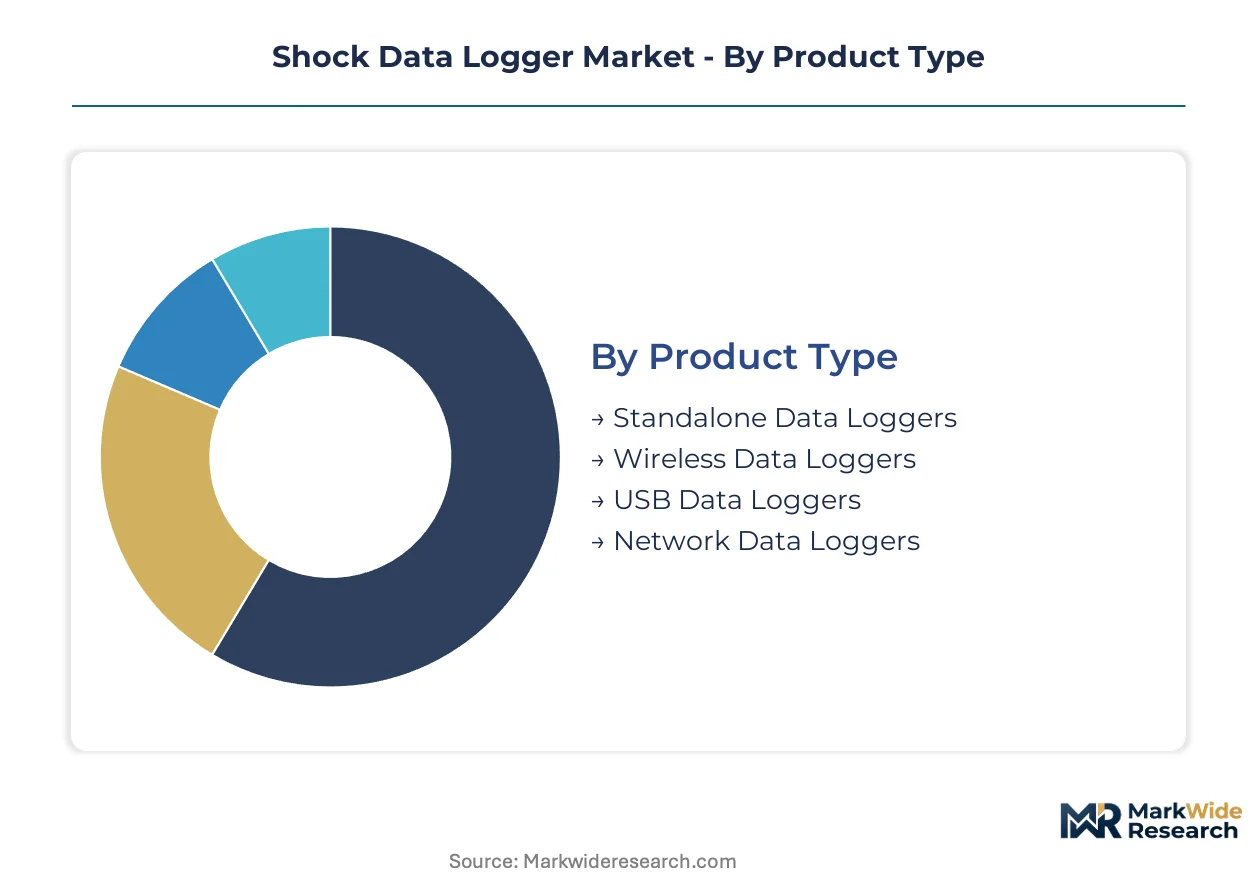
Shock data logger procurement splits sharply between high-channel-count crash-test installations and distributed logistics monitoring, with technology choices and deployment architectures diverging across these use cases. Understanding segment boundaries clarifies where margin pools concentrate versus where commoditization pressures dominate.
Product Type:
Cost tier and installation complexity separate buyers, with capital-intensive facilities favoring expandable architectures while logistics operators prioritize unit economics.
- Standalone Data Loggers:Self-contained units with onboard storage and battery power, sampling up to 50 kHz without external infrastructure. Electronics contract manufacturers in Japan and South Korea deploy these for irregular validation volumes where per-test pricing models dominate procurement.
- Wireless Data Loggers:Bluetooth or Wi-Fi-enabled devices eliminating tethered installations in crash-test facilities. Adoption accelerates in Germany and the United States where NHTSA and Euro NCAP compliance timelines compress installation windows; data sovereignty vulnerabilities across multi-jurisdictional deployments constrain cloud integration.
- USB Data Loggers:Direct-connect retrieval via USB-C, stripping out charge amplifiers and external signal conditioning. Third-party fulfillment providers deploy at pallet-level granularity for cost-sensitive logistics chains.
- Network Data Loggers:Ethernet-connected multi-channel systems for centralized laboratory data acquisition. High-channel-count PXI-based configurations serve automotive crash-test facilities requiring synchronized sampling across hundreds of sensor nodes.
Standalone units lead volumes today; wireless configurations are gaining share fastest.
End User:
Application severity and certification rigor determine specification thresholds, with aerospace and automotive demanding traceable calibration chains that shipping and electronics segments often bypass.
- Aerospace:Extreme-g event capture for structural qualification and payload safety validation. Fiber Bragg grating systems threaten niche applications where electromagnetic interference immunity matters; calibration infrastructure clusters in Germany and the United States limit facility expansion elsewhere.
- Automotive:NHTSA FMVSS 208/214 and Euro NCAP protocol compliance drives high-channel-count procurement. OEM validation center buildouts in India create greenfield demand for channel-expandable systems as NCAP Bharat implementation proceeds.
- Shipping:Pallet- and container-level impact documentation for supply chain liability assignment. MEMS cost curves enable silicon micromachining advances that reduce unit economics below piezoelectric thresholds for logistics monitoring.
- Electronics:Protective packaging validation for fragile component transport. Equipment-as-a-service contracts displace capital purchases among mid-size contract manufacturers with irregular validation volumes.
Automotive applications anchor revenue concentration; battery pack abuse testing for electric vehicle certification is expanding most quickly.
Deployment:
Data sovereignty requirements and real-time processing needs fragment architecture preferences across regulatory jurisdictions.
- On-Premise:Localized data storage and processing for facilities handling classified defense test protocols or proprietary OEM crash data. Japanese automotive regulators mandate domestic data residency for type approval documentation.
- Remote:Telemetry to off-site monitoring stations without cloud intermediary. Motorsport test houses leverage this architecture for trackside data acquisition where connectivity is intermittent.
- Cloud-Based:Centralized storage with analytics overlays, constrained by emerging data localization requirements in the EU and China. UNECE WP.29 cybersecurity mandates now require encrypted transmission and segregated networks.
- Hybrid:Edge anomaly detection with sovereign cloud storage addressing multi-jurisdictional compliance. European validation houses respond to OEM audit requirements by segregating logger networks from general IT infrastructure.
On-premise systems retain share in defense and regulated automotive testing; hybrid architectures show the steepest expansion trajectory.
Technology:
Performance-to-cost ratios and signal conditioning complexity differentiate sensing approaches, with MEMS displacement threatening legacy piezoelectric dominance in lower-g applications.
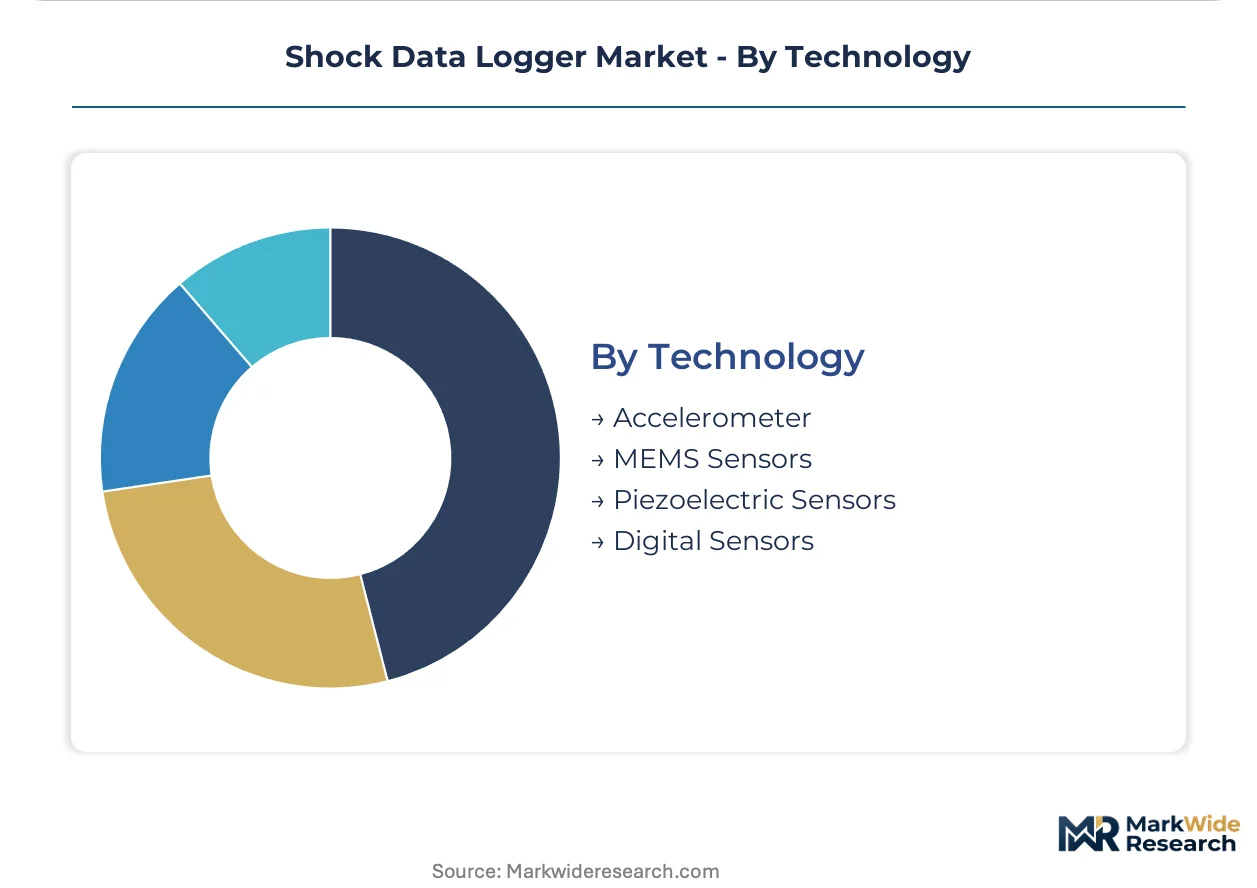
- Accelerometer:Macro-scale electromechanical devices dominating high-precision laboratory measurement. Established relationships with Japanese automotive regulators sustain incumbent positions in domestic type approval workflows.
- MEMS Sensors:Silicon micromachined tri-axial arrays with onboard digital signal processing. Direct USB-C data retrieval eliminates external charge amplifiers, compressing margin pools for piezoelectric units below 500g full-scale range.
- Piezoelectric Sensors:Lead zirconate titanate crystal-based elements for high-frequency transient capture. Supply concentrates among Japanese and Chinese specialty ceramic producers, creating input volatility and procurement risk.
- Digital Sensors:Integrated ADC and preprocessing reducing analog signal chain complexity. Emerging adoption in mid-tier electronics manufacturing where calibration traceability requirements are less stringent.
Piezoelectric sensors lead precision applications today; MEMS configurations are climbing the fastest across logistics and consumer electronics monitoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany and Japan maintain contrasting procurement patterns for shock data logger systems, with German facilities prioritizing channel-expandable architectures while Japanese regulators enforce stricter domestic data residency mandates for type approval workflows.
United States
NHTSA FMVSS 208/214 compliance drives high-channel-count logger procurement for frontal and side-impact validation at Detroit-area test laboratories. The Federal Motor Vehicle Safety Standards mandate documented crash pulse data with traceable calibration chains. Michigan's automotive validation corridor concentrates facility investment as OEMs expand NCAP Bharat-aligned testing capabilities for export markets.
Germany
Euro NCAP 2026 protocol expansion into pedestrian protection and active safety testing accelerates sensor node density requirements. UNECE WP.29 cybersecurity management systems now mandate encrypted data transmission from onboard crash recorders. Stuttgart and Munich validation centers are responding by segregating logger networks from general IT infrastructure to satisfy OEM audit requirements.
Japan
METI enforces domestic data residency requirements for vehicle type approval documentation, favoring on-premise deployment architectures. Piezoelectric signal conditioning expertise clusters around established relationships with domestic automotive regulators. Nagoya and Tokyo test houses are upgrading legacy tethered installations to hybrid edge-cloud configurations that preserve sovereign data handling.
India
NCAP Bharat implementation and domestic OEM validation center buildouts create greenfield demand for channel-expandable systems. The country's national automotive regulator mandates documented crash pulse data for domestic vehicle type approval. Pune and Chennai automotive clusters are attracting equipment-as-a-service contracts from regional suppliers offering per-test pricing with included calibration maintenance.
China
Battery pack abuse testing for electric vehicle certification requires multi-point shock-vibration-temperature synchronized logging. MIIT enforcement of GB standards for new energy vehicle safety creates compliance-driven procurement. Shanghai and Shenzhen testing facilities are deploying cloud-edge hybrid architectures to address emerging data localization requirements for international market access.
Shock Data Logger Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct tier positions in the shock data logger market. The vendor base organizes around three strategic archetypes: precision instrumentation conglomerates with broad test and measurement portfolios, specialized sensor manufacturers with deep piezoelectric expertise, and regional electronics suppliers serving cost-sensitive logistics monitoring. Consolidation pressures concentrate among mid-tier players as equipment-as-a-service contracts displace capital purchases. Strategic partnerships and technology licensing arrangements dominate competitive moves over vertical integration.
Within the precision instrumentation tier, National Instruments and Keysight Technologies exemplify platform-centric positioning through high-channel-count data acquisition architectures. Yokogawa Electric Corporation occupies a distinct position among Japan-based specialists with established regulatory relationships. Kistler Group represents the sensor-anchored archetype with concentrated expertise in piezoelectric force and acceleration measurement for motorsport and defense protocols.
| Leading Market Players |
|---|
| National Instruments |
| Keysight Technologies |
| Yokogawa Electric Corporation |
| Omega Engineering |
| MadgeTech, Inc. |
| Testo SE & Co. KGaA |
| Onset Computer Corporation |
| Kistler Group |
| Diversified Technical Systems |
| Others |
Value Network & Pricing Analysis
Equipment-as-a-service procurement among mid-size electronics contract manufacturers is forcing suppliers to absorb calibration and maintenance costs into recurring revenue models, compressing upfront price points while extending customer lifetime value calculations.
Pricing Analysis
Capacity additions in China and South Korea are reshaping price floors for MEMS-based logger configurations. Three-tier pricing structure across premium, standard, and economy levels separates PXI-based laboratory systems from USB-C logistics units and standalone budget devices. Price differentiation hinges on ISO 16063-11 calibration traceability and channel expandability. Cost compression in sub-500g MEMS segments is intensifying because silicon micromachining yields improve; electronics contract manufacturers show highest price sensitivity while aerospace qualification labs remain least sensitive.
Supply Chain Analysis
Lead zirconate titanate crystal supply rests on Japanese and Chinese specialty ceramic producers, with MEMS silicon wafers drawing from Taiwan and South Korea foundries. Raw material dependencies span piezoelectric ceramics, MEMS silicon substrates, and precision analog-to-digital converters. Single-source vulnerability concentrates in high-purity PZT sourcing for extreme-g applications. Distribution runs through tier-one test equipment distributors in Germany, Japan, and the United States, with direct OEM relationships dominating high-channel-count crash-test installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MEMS cost curves and equipment-as-a-service adoption are expanding addressable margins by shifting revenue from hardware transactions to bundled calibration and firmware maintenance streams.
For Market Incumbents: Lock in piezoelectric sensor relationships with Japanese automotive regulators before MEMS alternatives satisfy type approval precision thresholds. Secure captive supply of lead zirconate titanate through long-term offtake agreements with specialty ceramic producers in Japan. Fiber Bragg grating substitution threatens niche high-shock aerospace applications; counter with electromagnetic interference immunity certifications. For New Entrants and Emerging Players: Tier-one automotive test houses in India present the most penetrable channel partner type for channel-expandable system introductions. NCAP Bharat implementation creates greenfield validation center buildouts in Pune and Chennai lacking established supplier relationships. Target battery pack abuse testing for electric vehicle certification with multi-physics logging capabilities as entry wedge. For Investors and Strategic Acquirers: Asymmetric upside sits with pure-play MEMS logger specialists possessing USB-C direct-retrieval IP and logistics monitoring customer bases. Long-term viability favors vendors with sovereign data handling architectures addressing EU and China localization requirements. Watch for UNECE WP.29 cybersecurity mandate enforcement as inflection indicator for encrypted transmission capability premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Equipment-as-a-Service Transition | Per-test pricing with embedded calibration captures irregular-validation-volume customers in Japan and South Korea. |
| Hybrid Edge-Cloud Architecture Development | Real-time anomaly detection with sovereign storage addresses METI data residency and EU GDPR requirements simultaneously. |
| MEMS Sensor Platform Expansion | Tri-axial arrays with onboard DSP eliminate charge amplifiers and compress piezoelectric unit economics below 500g range. |
| Calibration Infrastructure Geographic Expansion | ISO 16063-11 traceable services beyond Germany, Japan, and the United States unlock India and China facility growth. |
| Cybersecurity Certification Investment | Encrypted transmission and segregated network capabilities satisfy UNECE WP.29 audit requirements for European validation houses. |
Research Methodology
Coverage spans the United States, Germany, Japan, India, and China, with primary inputs from each market. Primary interviews with crash-test laboratory directors, tier-one supplier procurement managers, automotive regulatory affairs leads, and calibration service technicians combined with secondary validation from NHTSA FMVSS filings, UNECE WP.29 documentation, METI type approval records, and ISO 6487 standards databases. Bottom-up unit shipment estimates and top-down market value triangulation cross-validated segment-level projections.
Rate-of-change decomposition across the analysis window isolates volume growth from price-mix effects and technology substitution patterns. Segmentation dimensions modeled include product type, end-user industry, deployment architecture, and sensing technology tier. CAGRs derive from logistic adoption curves for wireless configurations and linear penetration assumptions for established piezoelectric applications. Battery pack abuse testing requirements and NCAP Bharat implementation timelines served as industry-specific demand drivers.
Revisions become necessary when NHTSA or Euro NCAP protocol changes alter channel-count requirements, when lead zirconate titanate supply disruptions cascade through piezoelectric sensor availability, or when data sovereignty rules in additional jurisdictions mandate architectural redesigns. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Analog Multimeters Market
Test and Measurement
Non-Destructive Testing (NDT) Service Market
Test and Measurement
Battery Testing Equipment Market
Test and Measurement
Insulation Testing Instrument Market
Test and Measurement
Global 5G Test Equipment Market
Test and Measurement
Industrial X-Ray Inspection System Market
Test and Measurement
Continuous Level Measurement Market
Test and Measurement
Global Nondestructive Testing Equipment Market
Test and Measurement
Asia-Pacific Semiconductor Metrology and Inspection Market
Test and Measurement
Europe NDT Equipment Market
Test and Measurement
Test Rig Market
Test and Measurement
Digital Weighing Machine Market
Test and Measurement
Tribometer Market
Test and Measurement
Fiber Optic Tester Market
Test and Measurement
Online Weld Seam Quality Monitoring Test Systems for Steel Pipelines Market
Test and Measurement
Medical-Grade Flexible Electronics Bending and Fatigue Test Systems Market