
 Voice to Text on Mobile Devices Market | 2026-2036
Voice to Text on Mobile Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Voice to Text on Mobile Devices Market Analytics
The EU AI Act is recalibrating how voice data processors architect consent and transparency layers for European users. Google leverages its Tensor Processing Unit roadmap to sustain low-latency inference on Android devices. Apple anchors premium positioning through on-device neural engines that bypass cloud transmission. Nuance Communications specializes in clinical documentation workflows that dominate healthcare verticals.
Voice to text on mobile devices converts acoustic speech signals into machine-readable text through automatic speech recognition pipelines, typically employing mel-frequency cepstral coefficients for feature extraction and transformer-based acoustic models for sequence prediction. The technology serves industrial purposes from hands-free field data entry to real-time captioning for deaf and hard-of-hearing users. Natural Language Processing capabilities command the fastest expansion as multilingual intent parsing becomes standard across messaging and voice search applications. Smartphones occupy the core revenue pool, though wearables represent the steepest trajectory as hearables integrate always-on dictation.
The Federal Communications Commission shapes accessibility mandates through hearing aid compatibility rules that push OEMs toward embedded transcription. The FDA exercises oversight when voice interfaces control diagnostic or therapeutic software functions on mobile platforms. ISO 27001 certification has become a baseline procurement filter for enterprise buyers vetting cloud-based speech API providers. Stakeholders must weigh on-device processing trade-offs against cloud model accuracy gains as privacy regulations tighten across jurisdictions.
Market Dynamics
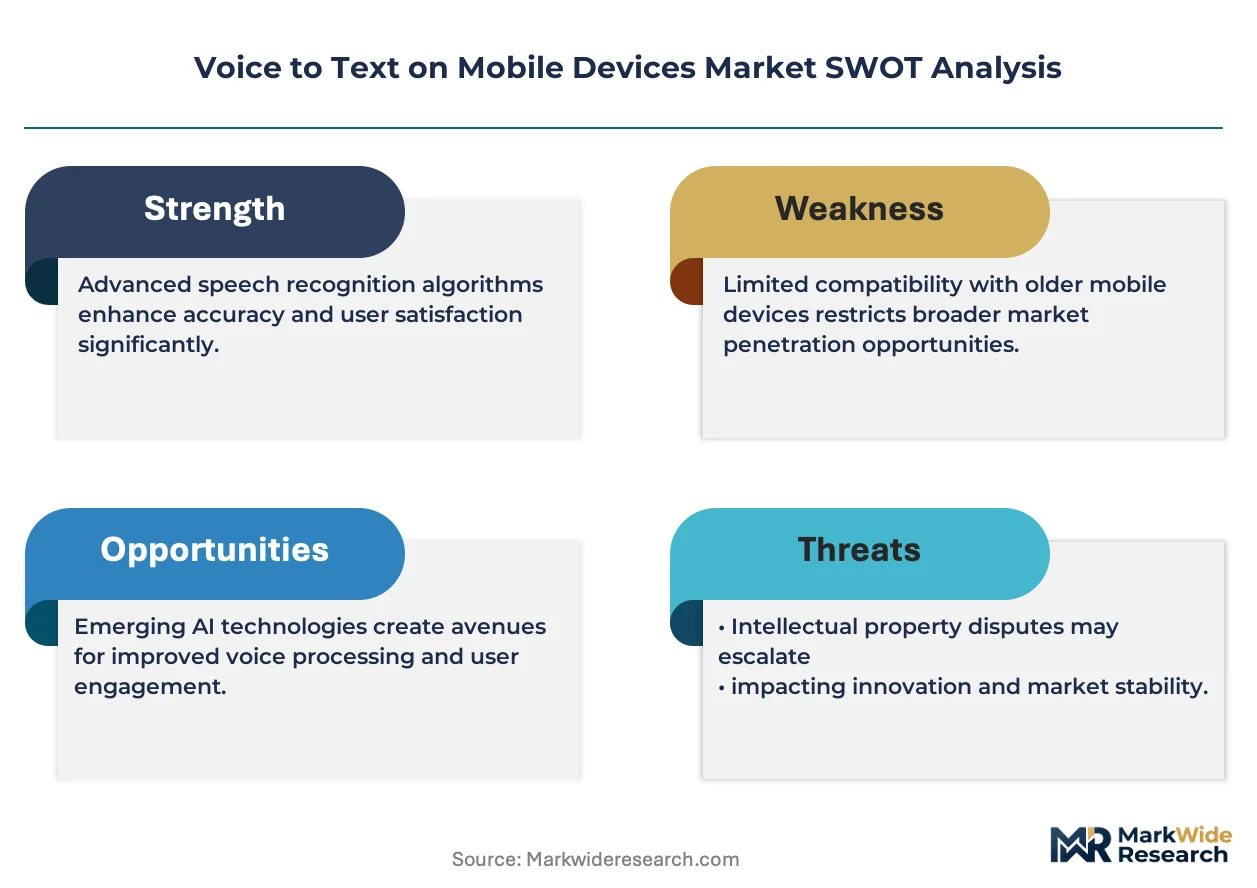
On-device neural processing is bifurcating the Voice to Text on Mobile Devices ecosystem between cloud-dependent accuracy and edge-bound privacy compliance. This architectural tension is forcing vendors to redesign inference pipelines around heterogeneous compute fabrics.
Growth Catalysts
- GDPR Article 25 (Data Protection by Design):European mandates for privacy-by-default are accelerating deployment of localized speech recognition that never transmits raw audio. Healthcare providers in Germany and France now specify on-device processing in procurement tenders.
- Clinical Documentation Workflows:Emergency medicine and primary care physicians are adopting mobile dictation to reduce EHR click burden. The American Medical Association's burnout reduction guidelines explicitly endorse speech-to-text for administrative relief.
- Mel-Frequency Cepstral Coefficients:Advances in acoustic feature extraction are compressing model sizes for microcontroller-class hardware. This is enabling always-on wake-word detection in true wireless earbuds with sub-10 milliwatt power budgets.
Market Restraints
- GPU/TPU Memory Constraints:On-device transformer inference requires HBM-class bandwidth that remains cost-prohibitive at mid-tier smartphone price points. Qualcomm and MediaTek SoCs face die-size trade-offs between NPU area and modem integration.
- Cloud API Concentration:Enterprise buyers exhibit vendor lock-in to hyperscale speech platforms due to custom vocabulary training investments. Migration costs deter switching even when privacy regulations tighten.
- Accent and Dialect Coverage Gaps:Low-resource language varieties lack training corpus depth. African, South Asian, and Indigenous American English variants exhibit word-error-rate degradation exceeding 15 percentage points versus General American.
Strategic Opportunities
- India's Bharat Bhasha Initiative:Government-backed corpus collection for 22 scheduled languages is creating training data infrastructure that commercial vendors can license. Mobile-first Indian language users represent an underpenetrated dictation demographic.
- FDA Software as Medical Device Pathway:Voice interfaces controlling diagnostic algorithms on smartphones qualify for streamlined 510(k) review. This regulatory clarity invites clinical workflow specialization.
- Convergence of Spatial Audio and Transcription:Head-tracking beamforming combined with speaker diarization enables multi-party meeting capture. Enterprise conferencing hardware vendors are integrating these capabilities into unified communication endpoints.
Industry Challenges
- Speech Science Talent Scarcity:The intersection of acoustic modeling, signal processing, and low-power system design commands premium compensation. Startups compete with Apple, Google, and Amazon for researchers with IEEE Signal Processing Society publication records.
- ISO 27001 Certification Timelines:Cloud API providers face 9-14 month audit cycles to satisfy enterprise procurement security requirements. This delays revenue recognition for new market entrants targeting Fortune 500 accounts.
- Legacy EHR Integration Complexity:Hospital IT environments run HL7 v2.x interfaces that predate modern REST architectures. Speech-to-text middleware requires custom adapter development per health system deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Voice to Text on Mobile Devices Market |
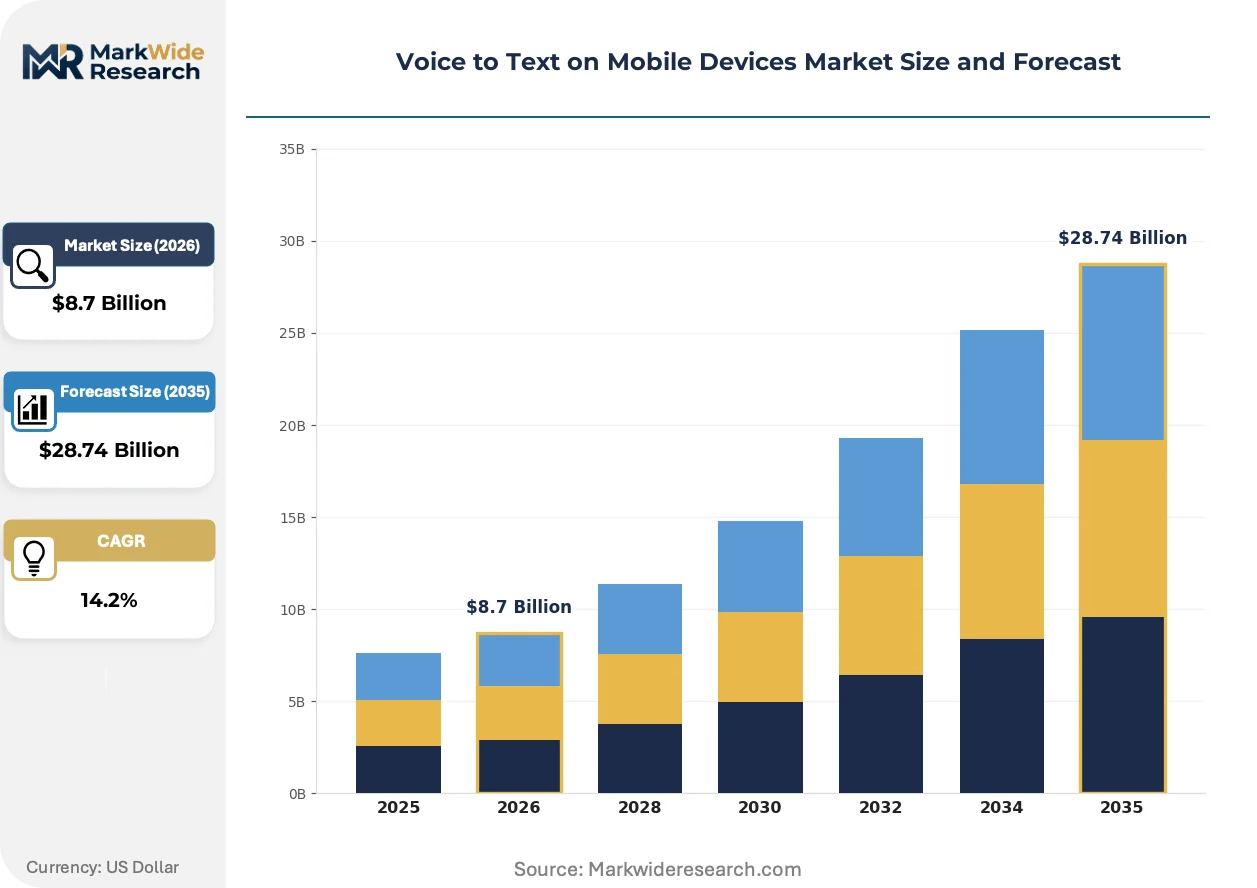
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Speech Recognition, Machine Learning, Natural Language Processing, Voice Command Application: Messaging, Note Taking, Voice Search, Transcription End User: Students, Professionals, Content Creators, Accessibility Applications Device Type: Smartphones, Tablets, Wearables, Laptops |
| Companies Covered | Deepgram, IBM, Google, Nuance Communications, Speechmatics, Apple, Amazon, AssemblyAI, Microsoft, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Voice to Text on Mobile Devices Market Evolving Landscape
Transformer compression techniques are redrawing the accuracy-latency frontier for mobile speech recognition. This is enabling new product architectures that were computationally infeasible three years prior.
Neural architecture search for automatic speech recognition is modularizing the traditional acoustic-model-pronunciation-lexicon pipeline into interchangeable sub-networks. Mobile OEMs can now license encoder blocks from specialist suppliers while retaining proprietary decoder layers for differentiation. Tier-1 smartphone vendors in South Korea and China are adopting this approach to reduce time-to-market for regional language support.
The EU AI Act's risk-classification framework for biometric identification systems is imposing documentation and human-oversight obligations on voiceprint analysis features. Speech-to-text vendors serving European enterprises must now maintain technical files demonstrating conformity with Annex III high-risk system requirements. This is diverting engineering resources from core accuracy improvements toward compliance tooling.
Healthcare procurement departments are unbundling transcription services from legacy EHR contracts and issuing standalone RFPs for mobile-compatible solutions. This is compressing vendor selection cycles from multi-year enterprise agreements to 12-18 month pilot-to-production timelines. The United States exhibits the most pronounced shift, with IDN consolidation creating centralized sourcing functions that aggregate demand across dozens of affiliated hospitals.
Voice to Text on Mobile Devices Market Segmentation
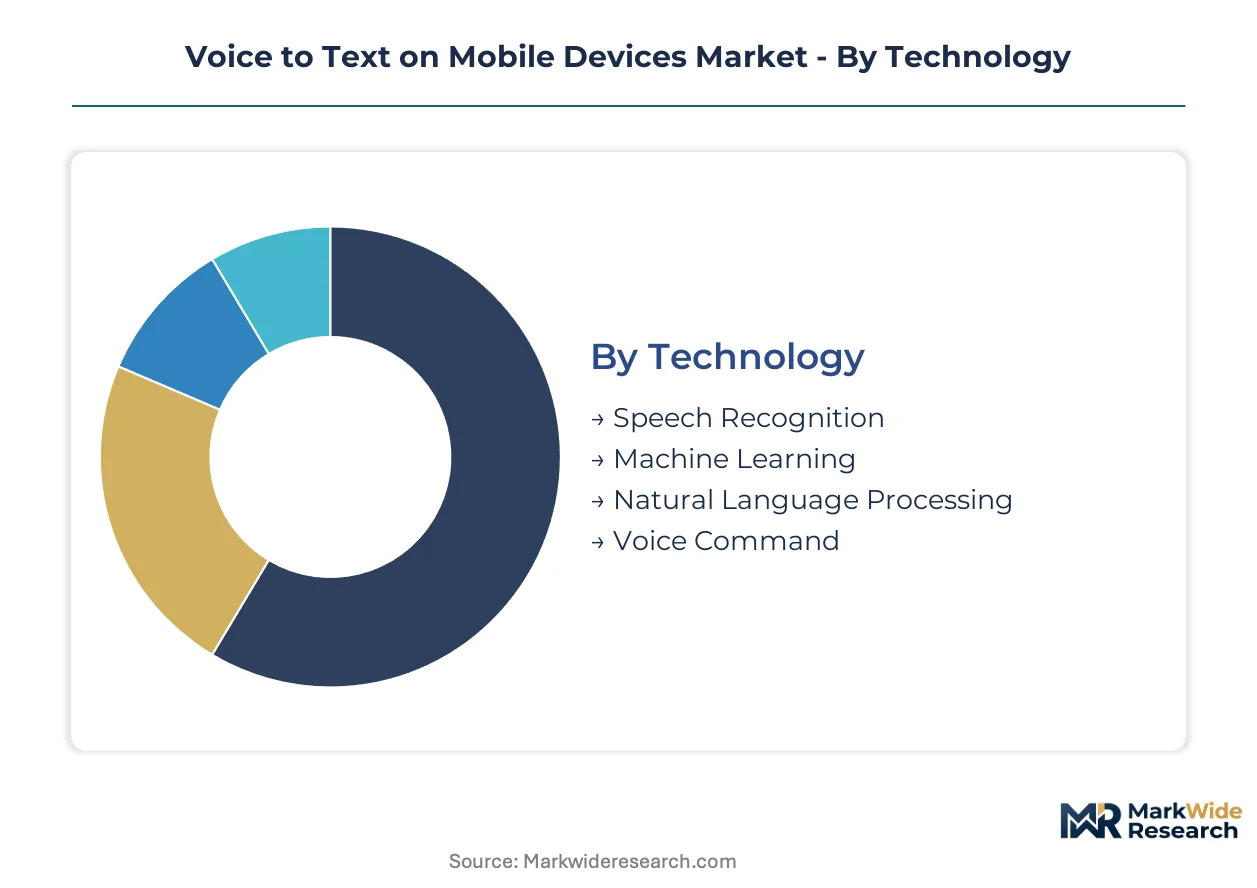
Segmentation reveals how capital allocation and engineering priorities diverge across the voice-to-text value chain. Hardware-dependent categories demand semiconductor R&D investment, while software layers concentrate on data infrastructure and model training spend.
Technology:
Capital intensity peaks in neural architecture design, where transformer optimization for edge deployment consumes the largest share of R&D budgets.
- Speech Recognition:Acoustic modeling pipelines convert mel-frequency cepstral coefficients into phoneme sequences through deep neural networks. Demand concentrates in smartphone OEMs integrating wake-word detection, driven by GDPR Article 25 mandates for on-device processing in Germany and France.
- Natural Language Processing:Intent parsing and entity extraction layers sit atop acoustic outputs, enabling contextual command understanding. Healthcare documentation workflows in the United States are driving procurement of clinical NLP modules that integrate with Epic and Cerner systems.
- Machine Learning:Federated learning frameworks train models across distributed device populations without centralizing raw audio. Apple and Google deploy this architecture to satisfy privacy-by-default requirements.
- Voice Command:Action-oriented interfaces trigger device functions through spoken directives. Automotive infotainment systems and smart home controllers represent primary integration targets.
Most installed capacity flows through Speech Recognition. Expansion is steepest in Natural Language Processing.
Application:
Revenue concentration varies sharply by session length and monetization model, with enterprise transcription commanding per-seat pricing far above consumer messaging.
- Transcription:Long-form audio conversion serves legal deposition capture, medical dictation, and media production. The American Medical Association's burnout guidelines explicitly endorse speech-to-text for EHR documentation relief.
- Voice Search:Query interfaces bypass typed input for hands-free information retrieval. Google's mobile search traffic shows pronounced voice query growth in Indian languages under the Bharat Bhasha Initiative.
- Messaging:Short-form dictation converts speech-to-text for SMS and chat applications. Asian markets with complex character input methods exhibit highest adoption intensity.
- Note Taking:Capture of unstructured thoughts and meeting minutes targets knowledge workers. Notion, Obsidian, and Roam Research have integrated voice capture modules.
Enterprise procurement concentrates spending on Transcription. Voice Search is gaining share fastest among application categories.
End User:
Customer lifetime value diverges dramatically between accessibility-mandated deployments and discretionary productivity tool adoption.
- Accessibility Applications:Real-time captioning and voice control serve deaf, hard-of-hearing, and motor-impaired users. The FCC's hearing aid compatibility rules push OEMs toward embedded transcription capabilities.
- Professionals:Enterprise knowledge workers deploy dictation for email, documentation, and calendar management. IDN consolidation in the United States is aggregating demand across hospital networks.
- Students:Lecture capture and study note automation target higher education demographics. Campus technology budgets increasingly specify mobile-compatible assistive tools.
- Content Creators:Podcasters, journalists, and video producers require accurate transcription for editing workflows. Descript and Otter.ai have captured this segment through collaborative editing features.
Accessibility Applications anchor regulatory-driven procurement. Professionals show the steepest expansion trajectory as enterprise pilots convert to production contracts.
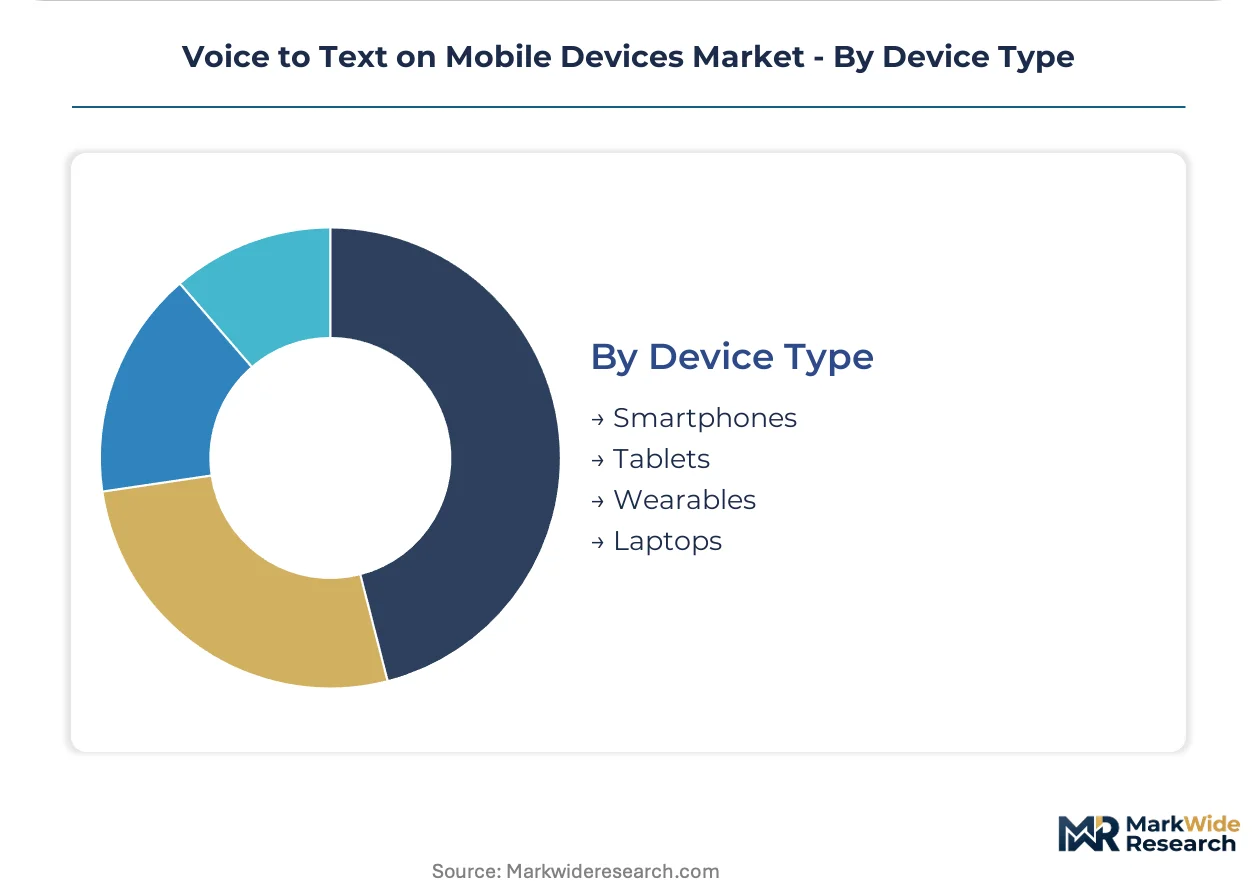
Device Type:
Compute constraints and power budgets fragment engineering requirements across form factors, with wearables demanding the most aggressive model compression.
- Smartphones:Flagship devices integrate dedicated neural processing units for on-device inference. Qualcomm's Snapdragon and Apple's A-series chips compete on TOPS-per-watt metrics for speech workloads.
- Wearables:True wireless earbuds and smartwatches operate under sub-10 milliwatt power envelopes. Always-on wake-word detection requires microcontroller-class acoustic models.
- Tablets:Larger thermal budgets enable more complex transformer architectures than phones. Stylus input hybrid workflows combine handwriting with voice annotation.
- Laptops:x86 and ARM-based systems leverage cloud-hybrid pipelines with local preprocessing. Microsoft and Google embed OS-level dictation across productivity suites.
Smartphones host the majority of installed base. Wearables are climbing the fastest as hearables integrate continuous transcription.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mobile speech recognition first achieved commercial scale in the United States through smartphone integration and cloud API deployment. From this origin, development patterns diverged across regulatory environments and hardware ecosystems.
United States
Enterprise professionals and healthcare providers drive procurement of clinical documentation tools. The FCC's hearing aid compatibility rules mandate embedded transcription capabilities in mobile devices. Greater Boston hosts specialist NLP firms serving pharmaceutical and biotech research workflows.
Germany
GDPR Article 25 enforcement has made privacy-by-default processing a procurement requirement for healthcare and automotive applications. The KBA maintains oversight standards for voice interfaces in connected vehicles. Stuttgart's automotive engineering cluster integrates speech recognition into production-line quality systems.
China
MIIT standards for intelligent voice interaction govern on-device processing requirements in domestic smartphone production. The Yangtze River Delta concentration of semiconductor foundries enables custom NPU designs for acoustic model inference. Shenzhen's hardware ecosystem produces true wireless earbuds with integrated wake-word detection at mass-market price points.
India
The Bharat Bhasha Initiative's corpus collection for 22 scheduled languages creates training infrastructure for multilingual speech recognition. TRAI guidelines on data localization influence cloud processing architectures for voice services. Bangalore's technology corridor hosts development centers optimizing models for Indic language phoneme recognition.
South Korea
MFDS regulatory clarity on Software as Medical Device classification enables clinical workflow applications for mobile voice interfaces. Seoul Capital Area conglomerates integrate proprietary neural engines across smartphone and home appliance product lines. Samsung and LG supply chains dominate MEMS microphone and edge-AI chip procurement for hearable devices.
Voice to Text on Mobile Devices Market Competitive Landscape
Capital-heavy cloud infrastructure providers compete with asset-light algorithm specialists for enterprise and developer segment share. The market structure concentrates around three hyperscale platforms while fragmenting across vertical specialists and regional language providers. Strategic archetypes include full-stack platform operators, clinical workflow specialists, and API-first transcription services. Competitive moves center on federated learning partnerships with device OEMs and custom vocabulary training investments that raise switching costs.
Among platform operators, Google, Apple, and Microsoft occupy positions spanning consumer and enterprise deployment vectors. Google exemplifies the cloud-hybrid archetype through Tensor Processing Unit integration with Android device ecosystems. Apple represents on-device processing specialization through neural engine architectures that bypass cloud transmission. Microsoft anchors enterprise productivity integration through Office suite and Azure speech service bundling.
| Leading Market Players |
|---|
| Deepgram |
| IBM |
| Nuance Communications |
| Speechmatics |
| Apple |
| Amazon |
| AssemblyAI |
| Microsoft |
| Others |
Value Network & Pricing Analysis
On-device versus cloud-hybrid processing bifurcation splits the Voice to Text on Mobile Devices market into premium privacy-compliant tiers and economy cloud-dependent offerings, with this divergence mapping directly onto semiconductor procurement strategies and API licensing cost structures. GDPR Article 25 enforcement in Germany and France has made localized neural processing a non-negotiable specification in healthcare tenders, forcing vendors to absorb higher silicon costs or sacrifice margin in regulated segments.
Pricing Analysis
Subscription-tiered SaaS licensing anchored to per-seat clinical documentation workflows dominates enterprise procurement, while API consumption models with volume-scaled unit economics capture developer segments. Price differentiation rests on ISO 27001 certification tier and custom vocabulary training depth, with healthcare buyers paying premiums for HIPAA-aligned data handling. Cost compression in mid-tier smartphone on-device inference is intensifying because Qualcomm and MediaTek NPU die-size trade-offs constrain performance-per-watt gains. Accessibility-mandated deployments through FCC hearing aid compatibility rules exhibit lowest price sensitivity, while freelance content creators drive economy-tier API commoditization.
Supply Chain Analysis
Neural processing unit supply rests on Taiwan Semiconductor Manufacturing Company foundry capacity, South Korea Samsung Electronics memory integration, and United States Qualcomm and Apple fabless design houses. Raw material dependencies span high-bandwidth memory stacks, advanced packaging substrates, and MEMS microphone sensors from Yangtze River Delta producers. Single-source vulnerability concentrates in 3nm-class EUV lithography equipment where ASML holds effective monopoly. Distribution runs through smartphone OEM direct integration, cloud API platform marketplaces, and clinical workflow middleware vendors serving hospital IT procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's biometric identification risk classification has compounded regulatory compliance into a demand amplifier, with Annex III documentation requirements now filtering vendor qualification before procurement cycles begin.
For Market Incumbents: Hedge against on-device accuracy gaps by federated learning partnerships with Tier-1 smartphone OEMs, securing training data pipelines that cloud-only entrants cannot replicate. Fortify position through backward integration into custom NPU IP blocks, reducing dependency on Qualcomm and MediaTek roadmap decisions. ISO 27001 certification renewal acceleration captures healthcare procurement windows before audit cycle delays disqualify competitors.
For New Entrants and Emerging Players: The mid-market price-point gap between Apple-Google premium on-device tiers and commodity cloud API offerings opens entry vectors through regional language specialization. India's Bharat Bhasha Initiative corpus infrastructure enables Indic phoneme model development at fraction of hyperscale training costs. Target clinical documentation workflow middleware as most penetrable segment, bypassing direct EHR integration complexity through standalone mobile app distribution.
For Investors and Strategic Acquirers: Consolidation pressure builds where ISO 27001 certification timelines and legacy HL7 adapter development capabilities create capability moats that scale economics favor acquiring over building. Long-term viability frames around federated learning infrastructure ownership and clinical NLP training data exclusivity. Watch FDA Software as Medical Device 510(k) clearance velocity as inflection indicator for clinical workflow segment maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Federated Learning Partnership | Apple and Google deploy this architecture to satisfy GDPR Article 25 privacy-by-default mandates. |
| ISO 27001 Certification Acceleration | Cloud API providers compress 9-14 month audit cycles to capture healthcare procurement windows. |
| Regional Language Model Development | India's Bharat Bhasha Initiative creates training infrastructure for 22 scheduled languages. |
| Clinical Workflow Middleware Integration | Standalone mobile solutions bypass legacy HL7 v2.x EHR adapter complexity per deployment. |
| Custom NPU IP Block Licensing | South Korean and Chinese OEMs adopt modular encoder licensing to accelerate regional language support. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with speech science researchers, healthcare IT procurement directors, mobile OEM platform engineers, and cloud API product managers with secondary validation against SEC filings from hyperscale providers, FDA 510(k) submission databases, EU AI Act technical documentation requirements, and TRAI data localization guidelines. Bottom-up smartphone shipment and API call volume estimates triangulated against top-down healthcare documentation workflow spend allocations.
Segment-weighting distributed value across technology layers, application use cases, end-user archetypes, and device form factors, with speech recognition, natural language processing, and machine learning subsegments modeled separately. CAGRs derived from installed base penetration curves and enterprise pilot-to-production conversion timelines across the projection horizon. Industry-specific inputs included mel-frequency cepstral coefficient compression ratios for microcontroller-class deployment and federated learning framework adoption rates.
Caveats apply where EU AI Act enforcement variance, FDA Software as Medical Device pathway interpretation shifts, or NPU foundry capacity constraints could materially shift the outlook. Forecasts reflect modeling assumptions around regulatory timeline adherence and semiconductor supply normalization. A small set of named triggers—GDPR Article 25 precedent expansion, Bharat Bhasha Initiative corpus licensing terms, and clinical burnout guideline revision—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Employee Engagement Software Market
Software & Services
Fiber Simulation Software Market
Software & Services
Global Call Center Software Market
Software & Services
Pure Play Software Testing Market
Software & Services
Global License Management Market
Software & Services
Global Data Governance Software Market
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
Backend-As-A-Service Market
Software & Services
B2B Price Optimization and Management Software Market
Software & Services
Global Integration Software Market
Software & Services
Software Licensing Market
Software & Services
Global Electronic Data Capture Software Market
Software & Services
HR Management Software (Personnel and Organization) Market
Software & Services
Global Handyman Software Market
Software & Services
Enterprise Intellectual Property (IP) Management Software Market
Software & Services
Global Demand Planning Software Market