
 Global License Management Market | 2026-2036
Global License Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global License Management Market Foresight
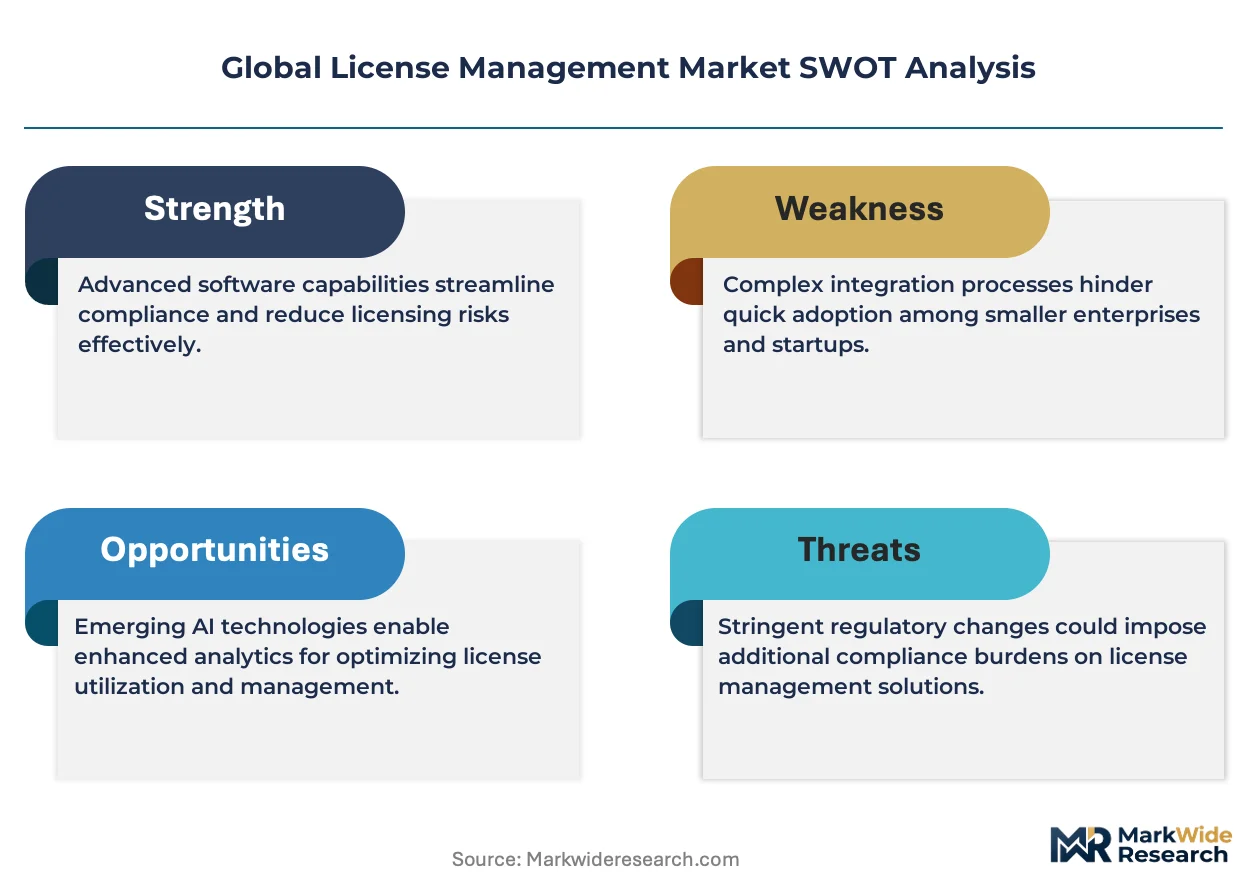
Enterprise-grade entitlement verification is unwinding legacy audit practices across the Global License Management Market. Flexera Software leverages deep discovery capabilities to anchor its position in hybrid IT environments. Snow Software sustains competitive pressure through agentless inventory methods that reduce deployment friction. IBM dominates mainframe-centric accounts where compliance complexity remains elevated.
License management governs the procurement, deployment, and optimization of software entitlements across on-premises, cloud-based, hybrid, and hosted environments, typically enforcing usage terms through token-based, node-locked, or concurrent-user models. Its primary commercial purpose is to eliminate shelfware, audit exposure, and true-up penalties while ensuring vendor contractual adherence. Cloud-based deployment is expanding fastest as containerized workloads and subscription billing models multiply tracking complexity. Software Asset Management solutions command the deepest margin pools because they integrate discovery, normalization, and reconciliation into unified workflows. Compliance Management functions are maturing in regulated industries where entitlement audits now occur quarterly rather than annually.
The EU AI Act, GDPR, and ISO/IEC 19770 standards collectively elevate software governance requirements across European enterprises, forcing procurement teams to document every license consumption event. The US FCC and SEC cybersecurity disclosure rules extend similar accountability to telecommunications and financial services firms operating domestically. Stakeholders must monitor how generative AI coding assistants alter seat-counting conventions before vendors recalibrate pricing architectures.
Market Dynamics
Containerized workload proliferation is fragmenting entitlement tracking across hybrid environments, forcing enterprises to abandon spreadsheet-based reconciliation in favor of automated discovery platforms that normalize consumption data across on-premises, SaaS, and edge deployments.
Growth Catalysts
- GDPR and EU AI Act enforcement:European financial services and healthcare enterprises must document every software consumption event, accelerating procurement of entitlement verification platforms that generate audit-ready evidence trails.
- Quarterly audit cycles in US financial services:SEC cybersecurity disclosure rules and heightened vendor true-up activity at major banks are compressing reconciliation timelines from annual to quarterly intervals.
- Agentless discovery methods:Cloud-native inventory technologies eliminate deployment friction across containerized environments, enabling faster time-to-value for mid-market SaaS operators.
Market Restraints
- Mainframe integration complexity:Legacy IBM z/OS environments resist API-based discovery, requiring specialized connectors that inflate implementation costs and extend deployment timelines.
- Oracle and Microsoft licensing opacity:Proprietary metric calculations and frequent contractual amendments create compliance blind spots that expose enterprises to unbudgeted true-up penalties.
- Skills scarcity in entitlement normalization:Shortage of practitioners who can reconcile publisher-specific metrics against actual consumption patterns limits platform utilization rates.
Strategic Opportunities
- Generative AI seat-counting disruption:GitHub Copilot and similar coding assistants are eroding traditional per-developer licensing conventions, creating openings for usage-based entitlement models.
- India's IT services expansion:Outsourcing providers in Bengaluru and Hyderabad require centralized license governance across thousands of client environments, driving demand for multi-tenant platforms.
- ISO/IEC 19770-1 certification tailwinds:Enterprises pursuing IT asset management standardization are mandating SAM tool deployment as a procurement prerequisite.
Industry Challenges
- Shadow SaaS proliferation:Business-unit software procurement outside IT oversight creates entitlement gaps that surface only during vendor audits.
- Publisher metric heterogeneity:Inconsistent definitions of "user," "processor," and "installation" across vendors complicate normalization algorithms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global License Management Market |
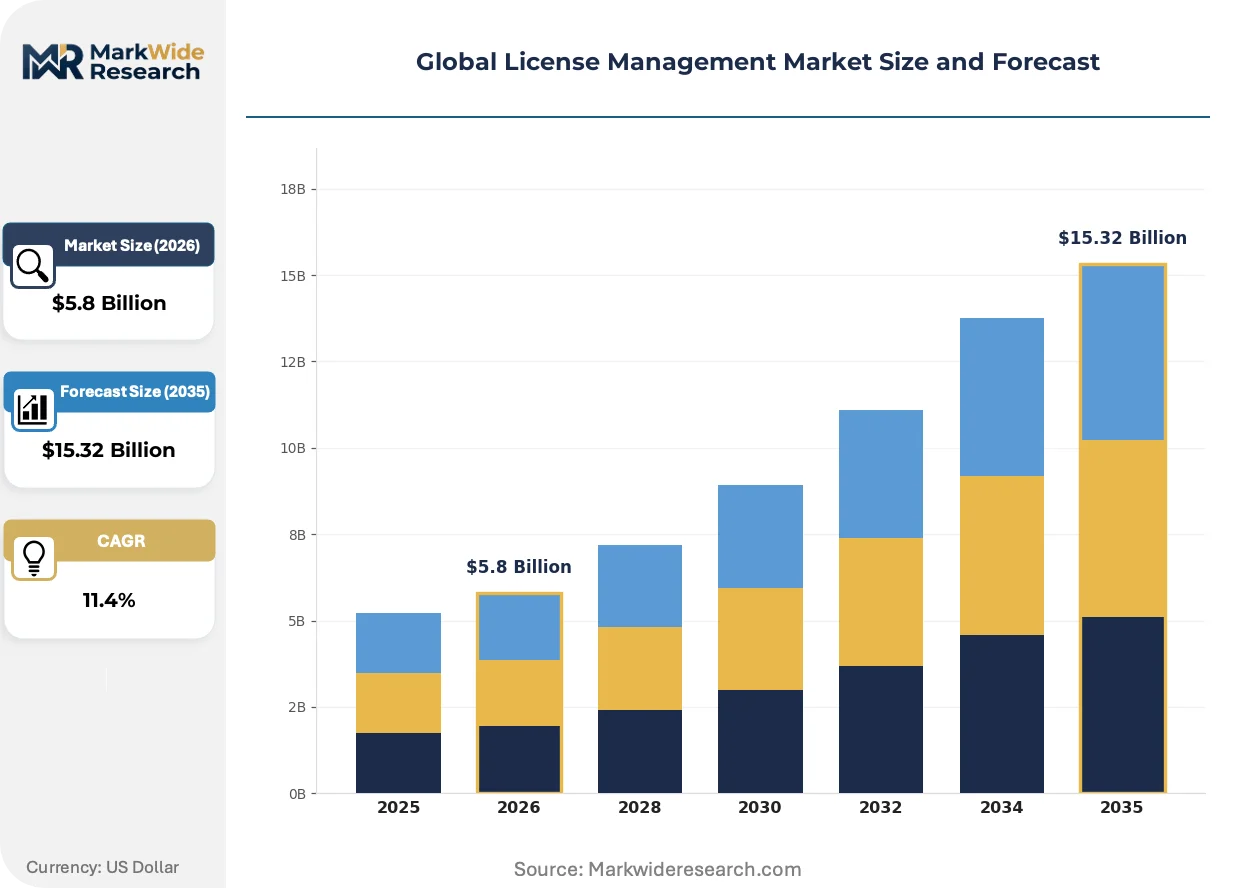
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $15.32 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, Hosted Solution Type: Software Asset Management, Compliance Management, Entitlement Management, Usage Analytics, Automation Tools Use Case: IT Asset Tracking, Cost Optimization, License Auditing, Software Compliance, Risk Mitigation End User Industry: Information Technology, Telecommunications, Financial Services, Manufacturing, Education |
| Companies Covered | Flexera Software, Snow Software, ServiceNow, IBM, Oracle Corporation, USU Software AG, DXC Technology Company, OpenLM Ltd, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global License Management Market Shifts & Advancements
Automated entitlement reconciliation is displacing manual audit preparation as the primary value proposition, with platforms embedding machine learning to predict consumption trajectories and flag optimization opportunities before contractual renewal windows.
API-first discovery architectures are fragmenting the traditional agent-based deployment model. These interfaces ingest consumption signals directly from cloud marketplaces, identity providers, and DevOps pipelines. Financial services firms in New York and London are adopting them fastest. The shift compresses implementation timelines from quarters to weeks.
The EU AI Act's software governance provisions are mandating algorithmic accountability documentation across high-risk AI deployments. Enterprises must now trace every licensed component within AI training pipelines. German automotive manufacturers and French healthcare AI developers face the steepest compliance ramps.
Subscription fatigue among enterprise procurement teams is shortening vendor evaluation cycles and elevating proof-of-concept requirements. Buyers now demand live entitlement reconciliation demonstrations against their actual environments before contract execution. This pattern is most pronounced among US mid-market SaaS companies with lean IT operations.
Global License Management Market Segmentation
License management platforms fragment across deployment architectures, solution depth, and governance intensity. Each segmentation axis reveals distinct margin pools and implementation friction points that shape vendor competitive positioning.
Deployment:
Geographic concentration varies sharply by deployment model, with cloud-based adoption led by SaaS-native enterprises in the United States and hybrid configurations dominating European regulated industries.
- On-Premises:Perpetual-license software running within enterprise data centers with direct hardware control. German automotive manufacturers and Japanese industrial conglomerates sustain demand here due to data residency requirements and air-gapped security protocols.
- Cloud-Based:Fully managed SaaS delivery eliminating infrastructure ownership. US financial services firms in New York and San Francisco are compressing procurement cycles for these solutions as SEC disclosure rules tighten.
- Hybrid:Split architectures spanning private infrastructure and public cloud orchestration. French healthcare providers and UK banking groups favor this model for GDPR-sensitive workloads requiring jurisdictional flexibility.
- Hosted:Single-tenant deployments managed by third-party operators. Indian IT services exporters in Bengaluru leverage hosted platforms to maintain client-specific isolation across multi-tenant delivery centers.
On-premises commands the established base. The steepest expansion runs through cloud-based configurations.
Solution Type:
Margin concentration tracks solution integration depth, with unified platforms capturing premium pricing against point-tool competitors.
- Software Asset Management:Integrated discovery, normalization, and reconciliation workflows spanning on-premises and cloud entitlements. US enterprise IT departments treat SAM as procurement infrastructure, mandating deployment before vendor contract renewals.
- Compliance Management:Audit preparation and regulatory evidence generation capabilities. EU AI Act enforcement is accelerating adoption among French AI developers and German medical device manufacturers facing algorithmic accountability mandates.
- Entitlement Management:License allocation and consumption tracking across user populations. Telecommunications operators in South Korea and Brazil utilize these tools to manage subscriber-based software provisioning.
- Usage Analytics:Consumption pattern visualization and optimization recommendations. Mid-market SaaS companies in the United Kingdom deploy these for subscription renewal negotiations.
- Automation Tools:Policy-driven license reclamation and reallocation engines. Indian outsourcing providers embed these across thousands of client environments to reduce manual reconciliation overhead.
Software Asset Management anchors vendor revenue. Automation Tools are gaining share fastest among cost-pressured procurement teams.
Use Case:
Application intensity correlates with audit frequency and penalty exposure, creating divergent customer lifetime value profiles.
- IT Asset Tracking:Hardware and software inventory maintenance across distributed environments. US healthcare systems deploy these for HIPAA-mandated device accounting.
- Cost Optimization:Shelfware identification and license reharvesting programs. UK public sector bodies facing budget compression prioritize this capability.
- License Auditing:Preemptive true-up assessment and vendor negotiation preparation. German engineering firms utilize these tools ahead of annual SAP and Oracle compliance reviews.
- Software Compliance:Contractual adherence verification against publisher metrics. Japanese automotive suppliers facing ISO certification requirements standardize on these solutions.
- Risk Mitigation:Shadow IT discovery and unlicensed usage remediation. Australian financial services firms deploy these following APRA cybersecurity guidance.
License Auditing drives established procurement spending. Risk Mitigation is expanding most quickly as shadow SaaS proliferation accelerates.
End User Industry:
Vertical specialization demands vary by regulatory density and software procurement complexity.
- Information Technology:Internal software governance and client-facing entitlement services. US cloud providers and Indian outsourcing firms represent concentrated demand.
- Telecommunications:Subscriber-scale license provisioning and network equipment entitlement tracking. South Korean and UAE operators face the steepest compliance ramps.
- Financial Services:Quarterly audit cycles and SEC disclosure rule adherence. New York and London banking clusters sustain premium platform spending.
- Manufacturing:Industrial software license management across global plant networks. German and Japanese automotive manufacturers lead deployment sophistication.
- Education:Volume-discounted academic licensing and research software governance. US research universities and Australian technical institutes drive procurement.
Financial Services commands premium platform investment. Information Technology is climbing fastest as SaaS-native vendors internalize governance tooling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in license management software, exporting entitlement verification platforms to European and Asian enterprises while importing specialized compliance modules from German and Israeli vendors. This export-import dynamic reflects concentrated SaaS development capabilities domestically against distributed regulatory expertise abroad.
United States
SEC cybersecurity disclosure rules and quarterly vendor audit cycles at New York financial institutions drive premium platform procurement. The FCC extends similar accountability mandates to telecommunications operators. San Francisco and New York banking clusters deploy cloud-native entitlement verification fastest.
Germany
Automotive manufacturers and medical device producers require algorithmic accountability documentation under EU AI Act enforcement. The KBA and BfArM coordinate software governance standards across industrial applications. Bavarian engineering firms and Baden-Württemberg automotive suppliers lead SAP and Oracle compliance sophistication.
United Kingdom
UK banking groups facing FCA operational resilience mandates compress reconciliation timelines from annual to quarterly intervals. The Information Commissioner's Office enforces GDPR-derived software consumption tracking requirements. London financial services clusters favor hybrid deployment models for jurisdictional flexibility.
India
Bengaluru and Hyderabad outsourcing providers require centralized license governance across thousands of client environments. RBI guidelines on IT outsourcing governance elevate procurement standards for financial services delivery. Indian IT services exporters leverage hosted platforms to maintain client-specific isolation.
Japan
Automotive suppliers and electronics manufacturers pursue ISO/IEC 19770-1 certification for supply chain standardization. METI promotes software asset management as industrial competitiveness infrastructure. Nagoya automotive clusters and Tokyo electronics manufacturers deploy entitlement verification for vendor negotiation preparation.
Global License Management Market Competitive Landscape
Listed leaders compete with private specialists across deployment architecture and discovery methodology dimensions. The vendor base organizes into three tiers: multinational technology conglomerates with integrated IT service portfolios, pure-play software asset management specialists, and regional compliance-focused providers. Strategic archetypes include API-first cloud-native platforms, mainframe-centric legacy integrators, and agentless inventory specialists. Competitive dynamics center on M&A activity consolidating point-tool capabilities and strategic partnerships embedding entitlement verification into broader IT service contracts.
Within the pure-play specialist tier, Flexera Software and Snow Software exemplify contrasting discovery philosophies. Flexera anchors hybrid IT positioning through deep infrastructure visibility capabilities. Snow Software occupies the agentless deployment vector reducing implementation friction for mid-market SaaS operators. IBM represents the conglomerate-integrated archetype, embedding license governance within broader mainframe service relationships. These three patterns illustrate how competitive positioning fragments across technical architecture choices rather than geographic or vertical segmentation.
| Leading Market Players |
|---|
| Flexera Software |
| Snow Software |
| ServiceNow |
| IBM |
| Oracle Corporation |
| USU Software AG |
| DXC Technology Company |
| OpenLM Ltd |
| Thales Group |
| Others |
Supply & Pricing Matrix
Ninety-day implementation timelines for enterprise license management platforms compress procurement cycles and concentrate pricing power with vendors possessing pre-built connectors for SAP and Oracle environments. This lead-time compression rewards suppliers maintaining certified integration libraries while penalizing point-tool competitors lacking normalized entitlement engines.
Pricing Analysis
Industrial OEM buyers anchor subscription-tiered pricing structures across the Global License Management Market. Pricing stratifies across premium, standard, and economy tiers differentiated by discovery depth and API integration count. Cost compression in the economy tier is intensifying because mid-market SaaS operators demand agentless deployment without implementation services. Procurement teams at Indian outsourcing providers exhibit highest price sensitivity, while New York financial institutions prioritize audit-ready compliance over cost minimization.
Supply Chain Analysis
Port congestion on transpacific routes from Shanghai to Los Angeles inflates inbound logistics costs for hardware-dependent discovery appliances deployed in air-gapped environments. Software supply concentrates in the United States, Germany, and India, with entitlement normalization algorithms drawing from open-source libraries and proprietary machine learning training sets. Single-source vulnerability rests on hyperscaler API dependencies for cloud-native inventory ingestion. Distribution runs through direct enterprise sales teams supplemented by systems integrators embedding license governance within broader IT transformation contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global License Management Market rewards vendors possessing scarce capabilities in mainframe entitlement reconciliation and ISO/IEC 19770-1 certification pathways. Procurement teams cannot source practitioners fluent in both Oracle metric calculations and containerized workload tracking from conventional talent pools.
For Market Incumbents: Compound defensive positioning through acquisition of agentless discovery specialists and certification investment in EU AI Act algorithmic accountability modules. Threat from API-first cloud-native entrants demands vertical integration into identity provider partnerships. Capacity addition in Bengaluru and Hyderabad captures Indian IT services expansion. For New Entrants and Emerging Players: Lead with generative AI seat-counting disruption targeting mid-market SaaS operators in the United Kingdom and United States. The most penetrable segment comprises procurement teams at SaaS-native vendors with lean IT operations lacking legacy mainframe complexity. Go-to-market angle emphasizes live entitlement reconciliation demonstrations against actual environments before contract execution. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment models as containerized architectures reduce infrastructure ownership requirements. Long-term viability favors platforms integrating discovery, normalization, and reconciliation into unified workflows over point-tool competitors. Acquisition target archetype includes agentless inventory specialists with pre-built hyperscaler connectors. Signal to watch is quarterly audit cycle adoption spreading from financial services into healthcare and telecommunications.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unified SAM workflows reduce reconciliation overhead for SEC-regulated financial institutions. |
| Acquisition of Specialist Firm | Agentless discovery capabilities eliminate deployment friction for mid-market SaaS operators. |
| Strategic Partnership | Identity provider alliances embed entitlement verification within zero-trust security architectures. |
| Geographic Expansion | Bengaluru and Hyderabad delivery centers capture Indian IT services governance demand. |
| Product Launch | EU AI Act compliance modules address algorithmic accountability mandates for German automotive manufacturers. |
Research Methodology
Operator-level perspectives from CIOs, IT procurement officers, software asset managers, and compliance auditors anchored the qualitative base for this study. Primary interviews across these stakeholder roles combined with secondary validation from SEC filings, ISO certification registries, vendor audit disclosure patterns, and hyperscaler partnership announcements. Bottom-up entitlement platform deployment counts triangulated against top-down enterprise software spend estimates across the analysis window.
Sensitivity analysis tested forecast outputs against alternative scenarios for SaaS proliferation velocity and regulatory enforcement intensity. Segmentation dimensions modeled span deployment architecture, solution integration depth, organization size tier, vertical regulatory density, and regional adoption pattern. CAGRs were derived from fitted growth curves calibrated to historical license management platform procurement trajectories. Industry-specific forecast inputs include quarterly audit cycle adoption rates and containerized workload penetration metrics.
Underlying assumptions cover sustained GDPR and EU AI Act enforcement momentum, with deviation risk concentrated in potential vendor pricing architecture recalibration for generative AI coding assistants. Forecasts reflect these documented conditions throughout the projection horizon. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Cloud Communication Platform Software Market
Software & Services
Global Professional Service Automation (PSA) Software Market
Software & Services
Global Lead Capture Software Market
Software & Services
Multivariate Testing Software Market
Software & Services
India HR Payroll Software Market
Software & Services
Patent Management Software Market
Software & Services
Global Online Form Builder Software Market
Software & Services
Performance Management Software Market
Software & Services
Global Content Management Software Market
Software & Services
Global Brand Management Software Market
Software & Services
Global Inside Sales Software Market
Software & Services
Mind Mapping Software Market
Software & Services
Server Operating System Market
Software & Services
Global Charity Accounting Software Market
Software & Services
Ecommerce Inventory Management Software Market
Software & Services
Clustering Software Market