
 Global Integration Software Market | 2026-2036
Global Integration Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Integration Software Market Foresight
Market Context
The divergence between premium and commodity tiers is hardening as enterprise buyers separate mission-critical real-time integration from batch-processed data movement. IBM Corporation leverages its mainframe heritage and hybrid cloud portfolio to dominate high-availability financial services deployments. Microsoft Corporation anchors the mid-market through native Azure connectivity and low-code tooling embedded across Office 365 and Dynamics ecosystems. SAP SE specializes in vertical integration within its S/4HANA customer base, competing on deep ERP-native connectivity rather than platform openness.
Technical Definition and Segment Structure
Integration software comprises middleware, connectors, and governance layers that enable disparate applications, databases, and services to exchange data through standardized protocols such as REST, SOAP, and event-driven architectures. Its primary commercial purpose is eliminating data silos while ensuring transactional integrity across heterogeneous IT estates. Cloud-based deployment now leads absolute spending as enterprises abandon capital-intensive on-premise infrastructure, though hybrid configurations capture the fastest growth trajectory where regulated workloads must remain on-site while analytics shift to public clouds. API Management commands the strongest margin pool because developer-centric pricing and consumption-based metering create recurring expansion revenue that batch-oriented data integration struggles to replicate.
Regulatory Frame and Outlook
The EU AI Act, GDPR, and HIPAA impose strict lineage and auditability requirements that reshape vendor feature roadmaps toward immutable logs and automated policy enforcement. The SEC's cybersecurity disclosure rules and Japan's METI data governance guidelines further fragment compliance architectures, forcing multi-tenant platforms to support jurisdiction-specific encryption and residency controls. Stakeholders must monitor whether emerging sovereign cloud mandates in Germany, India, and China fragment platform economics or create openings for regional specialists with native certification.
Market Dynamics
Enterprise buyers are forcing a bifurcation between mission-critical real-time integration and commodity batch processing, with cloud-native platforms capturing spending while legacy on-premise installations face accelerated replacement cycles.
Growth Catalysts
- HIPAA and GDPR lineage mandates:Healthcare providers in the United States and financial institutions across the European Union require immutable audit trails for every data touchpoint, driving replacement of legacy ETL tools with governed pipeline platforms.
- Event-driven architecture adoption:Retail and logistics operators are abandoning polling-based synchronization in favor of streaming event meshes that enable sub-second inventory visibility across distributed warehouses.
- India's digital public infrastructure:The country's Account Aggregator framework and Open Network for Digital Commerce are compelling domestic banks and insurers to modernize core banking integration layers.
Market Restraints
- Specialized engineering talent scarcity:Kubernetes-native integration engineering commands salary premiums exceeding forty percent above traditional middleware administration, constraining deployment velocity for mid-market enterprises.
- Concentrated hyperscaler dependency:Three cloud providers control the underlying compute and storage infrastructure for over seventy percent of new integration platform deployments, creating vendor lock-in exposure.
- Latency constraints of edge-to-core synchronization:Manufacturing IoT deployments in remote facilities face throughput bottlenecks when consolidating high-frequency sensor streams into centralized analytics warehouses.
Strategic Opportunities
- Brazil's open finance regulation:ANVISA-aligned data sharing mandates are creating greenfield demand for API management platforms among domestic payment processors and credit bureaus.
- Convergence of integration and observability:Unified platforms combining pipeline orchestration with real-time telemetry are displacing separate monitoring tool purchases in DevOps-heavy organizations.
- Sovereign cloud certification pathways:Germany's GAIA-X and India's MeitY empanelment programs are opening procurement channels for regional platform providers with native data residency controls.
Industry Challenges
- Mainframe connectivity expertise erosion:COBOL and CICS integration specialists are retiring faster than replacement pipelines complete, threatening modernization timelines for Fortune 500 core banking systems.
- Multi-jurisdiction encryption key management:Enterprises operating across EU, United States, and China must maintain separate HSM infrastructures to satisfy conflicting data sovereignty rulings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Integration Software Market |
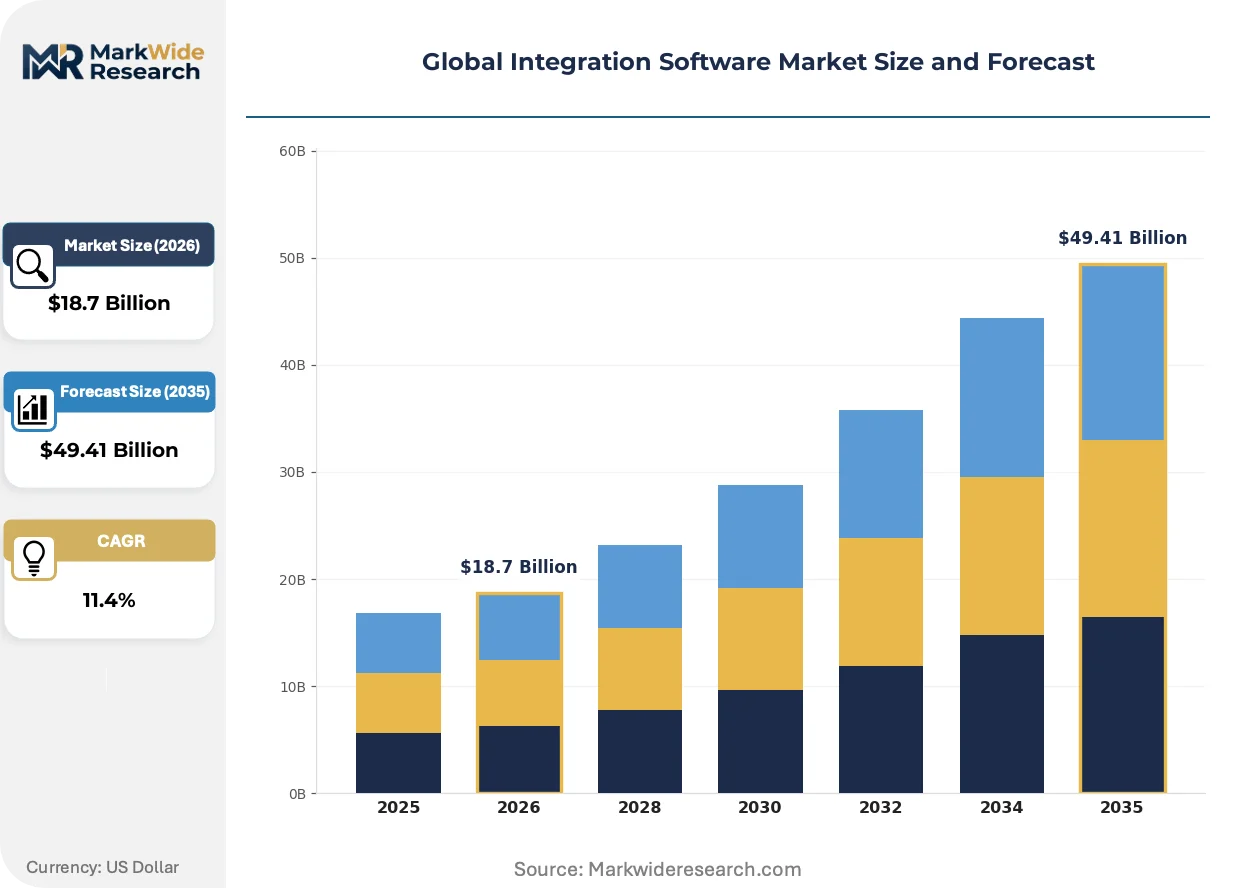
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, Managed Services Solution Type: Enterprise Application Integration, Data Integration, API Management, Messaging & Event Processing, Service-Oriented Architecture Use Case: Data Synchronization, Process Automation, Legacy Modernization, Cloud Migration, Real-Time Monitoring End User Industry: BFSI, Telecommunications, Government, Energy & Utilities, Transportation |
| Companies Covered | IBM Corporation, Microsoft Corporation, SAP SE, Oracle Corporation, Informatica, SAS Institute, Boomi, TIBCO Software, Talend, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Integration Software Market Shifts & Advancements
Artificial intelligence is embedding directly into integration runtimes, with automated schema mapping and anomaly detection compressing deployment timelines while reshaping vendor competitive differentiation away from connector breadth toward intelligent automation depth.
Event mesh architectures are unifying previously siloed application, data, and device integration layers into single control planes. Capital markets firms in London and Singapore are deploying these fabrics to collapse separate middleware estates that previously required distinct operational teams. This consolidation is unifying vendor selection criteria around platform-agnostic routing capabilities rather than point-to-point connector depth.
The EU AI Act's risk classification framework is forcing integration platforms to embed automated policy enforcement at pipeline design time. Financial services deployments in Frankfurt and Paris must now demonstrate that training data lineage meets auditability thresholds before production deployment. Healthcare AI workloads in Germany are responding by adopting immutable ledger integrations that satisfy both GDPR rectification requirements and AI Act documentation mandates.
Enterprise buyers are compressing vendor evaluation cycles from eighteen-month RFP processes to ninety-day proof-of-concept sprints. Manufacturing and retail procurement teams in the United States are prioritizing consumption-based pricing with transparent egress cost modeling over perpetual license negotiations. This behavioral shift is most visible among mid-market distributors replacing decade-old EDI VAN contracts with modern API gateway subscriptions.
Global Integration Software Market Segmentation
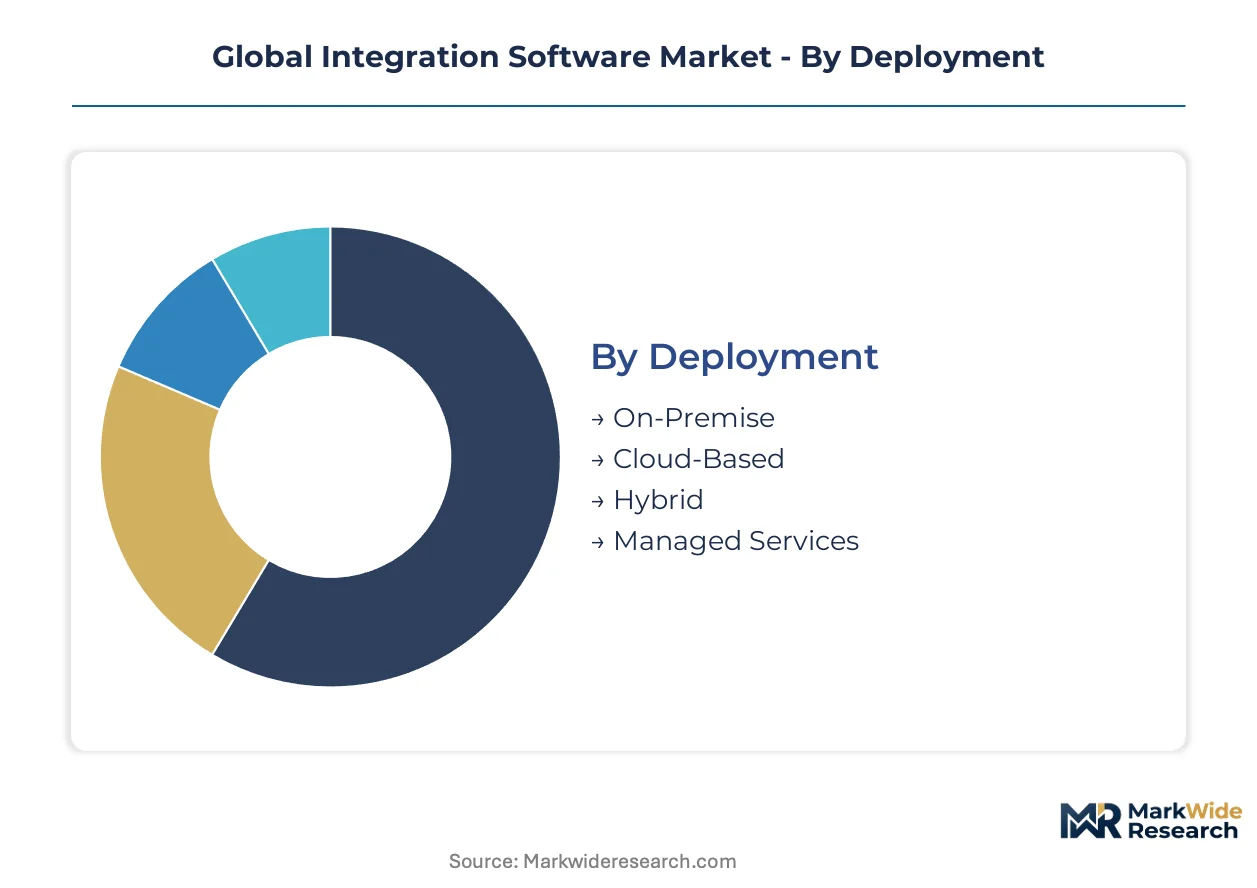
Integration software procurement patterns diverge sharply across deployment models and solution architectures, with enterprise buyers segmenting budgets between legacy system maintenance and cloud-native transformation initiatives. Understanding these splits reveals where vendor R&D investments concentrate and which integration paradigms capture replacement spending.
Deployment:
Upgrade cycles now favor consumption-based models over capital-intensive infrastructure commitments, reshaping how enterprises evaluate total cost of ownership across deployment options.
- Cloud-Based:Multi-tenant platforms with elastic scaling dominate new procurement among retail and logistics operators seeking to eliminate data center overhead. Financial services firms in Singapore and the United States are migrating core payment processing to these environments despite regulatory scrutiny over data residency.
- Hybrid:Configurations splitting transactional workloads on-premise from analytics in public clouds capture manufacturing and healthcare demand where HIPAA and GDPR mandate local data retention. German automotive suppliers deploy this architecture to keep proprietary design data on-site while feeding anonymized telemetry to cloud-based optimization engines.
- On-Premise:Legacy installations persist in defense and classified government environments where air-gapped networks remain mandatory.
- Managed Services:Outsourced integration operations appeal to mid-market enterprises lacking Kubernetes-native engineering talent.
Cloud-Based deployments sit at the top of the volume ranking, with Hybrid climbing the fastest as regulated industries navigate compliance complexity.
Solution Type:
Margin pools concentrate where developer-centric consumption metering enables recurring expansion revenue rather than perpetual license models.
- API Management:Gateway platforms with rate limiting, developer portals, and monetization layers command premium pricing in open banking and telecommunications. Brazilian payment processors under ANVISA-aligned mandates are replacing legacy EDI infrastructure with these tools to enable real-time data sharing.
- Enterprise Application Integration:Middleware connecting ERP, CRM, and SCM systems retains stronghold in Fortune 500 environments modernizing SAP and Oracle estates. Japanese manufacturers leverage METI-backed digital transformation subsidies to fund these deployments.
- Data Integration:ETL and ELT pipelines with automated schema mapping address cloud data warehouse consolidation needs.
- Messaging & Event Processing:Streaming platforms with sub-second latency support capital markets trading infrastructure in London and Singapore.
- Service-Oriented Architecture:Legacy SOAP-based integration persists in healthcare and government where change velocity remains constrained.
API Management leads margin capture, while Messaging & Event Processing shows the steepest expansion trajectory among capital markets and logistics operators.
Use Case:
Enterprise prioritization reflects pressure to demonstrate ROI within compressed evaluation cycles rather than multi-year transformation roadmaps.
- Legacy Modernization:COBOL and mainframe connectivity replacement dominates banking and insurance where retiring specialists threaten operational continuity. United States core banking systems face acute expertise erosion as CICS integration engineers exit the workforce faster than knowledge transfer completes.
- Cloud Migration:Lift-and-shift orchestration with replatforming assessment tools captures mid-market demand seeking to exit owned data centers. India's digital public infrastructure initiatives compel domestic insurers to modernize core banking integration layers through these projects.
- Data Synchronization:Batch and real-time replication between operational and analytical systems supports ERP consolidation.
- Process Automation:Workflow orchestration with human-in-the-loop capabilities addresses document-intensive industries.
- Real-Time Monitoring:Telemetry pipelines with automated alerting displace separate observability tool purchases in DevOps-heavy organizations.
Legacy Modernization commands the largest absolute spending pool, with Cloud Migration gaining share fastest among mid-market distributors and regional banks.
End User Industry:
Vertical-specific compliance mandates and data sovereignty requirements fragment procurement criteria across regulated sectors.
- BFSI:Banking, financial services, and insurance demand immutable audit trails and sub-millisecond latency for trading and settlement systems. EU AI Act and GDPR lineage requirements in Frankfurt and Paris force automated policy enforcement at pipeline design time.
- Government:Federal and state agencies prioritize FedRAMP and sovereign cloud certifications with encryption key escrow. Germany's GAIA-X and India's MeitY empanelment programs open procurement channels for regional providers with native data residency controls.
- Telecommunications:5G network slicing and edge orchestration drive API gateway deployment for service exposure.
- Energy & Utilities:SCADA integration with advanced metering infrastructure supports grid modernization.
- Transportation:Logistics visibility platforms consolidate warehouse management and fleet telematics.
BFSI dominates absolute vendor revenue, with Government expanding most quickly as sovereign cloud mandates proliferate across Germany, India, and China.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cloud-native engineering talent concentrates in the United States, Germany, India, and Singapore, anchoring integration platform development and enterprise deployment velocity across distinct regulatory environments.
United States
Fortune 500 enterprises in financial services and healthcare drive replacement of legacy ERP connectors. HIPAA and SEC cybersecurity disclosure rules mandate immutable audit trails for patient data and material incident reporting. New York and San Francisco clusters host the densest concentration of event-mesh deployments for real-time trading infrastructure.
Germany
Automotive suppliers and industrial manufacturers demand hybrid configurations splitting proprietary design data on-premise from cloud analytics. GAIA-X sovereign cloud certification and EU AI Act risk classification frameworks shape procurement criteria. Frankfurt's banking sector leads adoption of automated policy enforcement at pipeline design time.
India
Domestic banks and insurers modernize core banking layers under Account Aggregator and Open Network for Digital Commerce mandates. MeitY empanelment programs open procurement channels for platforms with native data residency controls. Bengaluru and Mumbai clusters concentrate Kubernetes-native integration engineering talent.
Singapore
Capital markets firms deploy sub-millisecond latency streaming platforms for trading and settlement systems. The Monetary Authority of Singapore's technology risk management guidelines enforce rigorous lineage documentation. The city-state's financial district anchors event-mesh consolidation across previously siloed middleware estates.
United Kingdom
London's fintech ecosystem drives API management adoption for open banking and embedded finance use cases. GDPR and emerging UK AI regulation impose cross-border data flow constraints. The capital's DevOps-heavy organizations prioritize unified platforms combining pipeline orchestration with real-time telemetry.
Global Integration Software Market Competitive Landscape
Top-tier vendors anchor high-availability financial services deployments, while mid-market specialists capture cloud-native transformation demand. The vendor base stratifies across three tiers: mainframe-heritage platforms, hyperscaler-native ecosystems, and vertical-specialist frameworks. Two strategic archetypes dominate competitive positioning: hybrid cloud portfolio providers competing on enterprise breadth, and API-centric platforms competing on developer experience. M&A activity concentrates on event-streaming capabilities, while strategic partnerships with sovereign cloud certifiers expand addressable markets in Germany and India.
Within the mainframe-heritage tier, IBM Corporation represents high-availability deployment patterns in regulated financial services. Microsoft Corporation and SAP SE occupy distinct positioning vectors: the former anchors mid-market adoption through native cloud connectivity, while the latter exemplifies ERP-native vertical integration competing on deep system connectivity rather than platform openness.
| Leading Market Players |
|---|
| IBM Corporation |
| Microsoft Corporation |
| SAP SE |
| Oracle Corporation |
| Informatica |
| SAS Institute |
| Boomi |
| TIBCO Software |
| Talend |
| Others |
Supply & Pricing Matrix
Horizontal integration into hyperscaler infrastructure anchors supply positioning for cloud-native platforms while compressing margin structures for independent software vendors competing against bundled Azure, AWS, and Google Cloud offerings. This integration choice concentrates pricing power with the three dominant cloud providers that control underlying compute and storage for over seventy percent of new deployments, forcing mid-market specialists to differentiate through vertical-specific compliance modules rather than infrastructure economics.
Pricing Analysis
Bundled infrastructure-and-platform offerings from hyperscalers now dominate enterprise procurement, while unbundled best-of-breed integration tools compete on specialized governance and lineage capabilities. Three-tier pricing structure across premium, standard, and economy levels separates Fortune 500 deployments with dedicated support from mid-market SaaS tiers and developer-centric consumption metering. Price differentiation hinges on certification depth—FedRAMP and GAIA-X compliance command thirty to fifty percent premiums—and geographic data residency controls. Cost compression in the mid-market tier is intensifying because hyperscalers embed basic integration tooling at marginal cost within existing cloud contracts. Healthcare providers and German automotive suppliers demonstrate lowest price sensitivity due to regulatory non-negotiability, while retail distributors and logistics operators prioritize transparent egress cost modeling over feature depth.
Supply Chain Analysis
Germany's GAIA-X sovereign cloud mandates and India's MeitY empanelment programs are reshaping sourcing patterns by requiring domestic data residency and local engineering presence for government and BFSI procurement. Engineering talent concentrates in the United States, Germany, India, and Singapore, with Kubernetes-native integration specialists commanding salary premiums that feed into platform delivery costs. Raw material dependencies in this intangible supply chain center on GPU compute allocations, proprietary connector libraries, and certified compliance documentation. Single-source vulnerability runs through hyperscaler infrastructure concentration, where three providers control the substrate for most enterprise deployments. Distribution runs through direct enterprise sales for Fortune 500 accounts, cloud marketplace listings for mid-market velocity, and systems integrator partnerships for complex hybrid implementations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where engineering talent cost differentials between Silicon Valley and Bengaluru enable competitive platform development, while regulatory fragmentation between EU AI Act jurisdictions and HIPAA environments creates premium pricing pockets for compliance-native vendors.
For Market Incumbents: Anchor high-availability financial services deployments through mainframe heritage and hybrid cloud portfolios while accelerating event-streaming capability acquisition to defend against cloud-native challengers. Invest in automated policy enforcement modules that embed EU AI Act risk classification at pipeline design time, as Frankfurt and Paris financial institutions now mandate this capability for production deployment. Vertical integration into sovereign cloud certification pathways—particularly Germany's GAIA-X and India's MeitY programs—locks out regional specialists from regulated procurement channels.
For New Entrants and Emerging Players: The price-point gap between premium mainframe-heritage platforms and economy-tier hyperscaler bundles creates white-space opportunity for API-centric specialists targeting mid-market manufacturers and regional banks. Brazil's open finance regulation under ANVISA-aligned mandates offers the most penetrable geography, with domestic payment processors replacing legacy EDI infrastructure under regulatory deadline pressure. A consumption-based pricing model with transparent egress cost modeling and ninety-day proof-of-concept sprints matches compressed procurement cycles observed among United States distributors and logistics operators.
For Investors and Strategic Acquirers: Roll-up economics work for event-streaming specialists because capital markets firms in London and Singapore are consolidating previously siloed middleware estates into single control planes, creating acquisition premiums for platform-agnostic routing capabilities. Target firms with deep Kubernetes-native engineering benches and existing GAIA-X or MeitY certifications, as sovereign cloud mandates proliferate across Germany, India, and China. Watch for inflection when ANVISA-aligned open finance deadlines in Brazil trigger replacement spending waves among domestic payment processors and credit bureaus.
| Strategic Initiative | Industry Significance |
|---|---|
| Event-Streaming Capability Acquisition | Capital markets firms in London consolidate siloed middleware estates into unified control planes. |
| Sovereign Cloud Certification Investment | GAIA-X and MeitY empanelment open procurement channels in Germany and India for compliant platforms. |
| Automated Policy Enforcement Development | Frankfurt banks must demonstrate AI Act lineage compliance before production deployment authorization. |
| API Management Platform Launch | Brazilian payment processors replace EDI infrastructure under ANVISA-aligned open finance mandates. |
| Hybrid Configuration Specialization | German automotive suppliers keep proprietary design data on-site while feeding anonymized telemetry to cloud engines. |
Research Methodology
Bottom-up enterprise deployment modeling reconciled against top-down hyperscaler infrastructure tracking forms the analytical core of this study. Primary interviews with CTOs, IT procurement officers, platform engineers, and integration specialists across financial services, healthcare, manufacturing, and logistics verticals inform adoption pattern assessment. Secondary validation draws from SEC filings documenting integration platform revenue disclosures, hyperscaler capex and R&D allocation reports, and regulatory filings with the SEC, EMA, and India's MeitY. Trade data and customs records trace hardware infrastructure flows underlying cloud deployment economics.
Historical trendline analysis of cloud migration velocity, event-driven architecture adoption, and compliance spending patterns establishes baseline growth assumptions across the projection horizon. Segmentation dimensions modeled include deployment model, organization size, vertical industry, integration complexity tier, and regional regulatory cluster. CAGRs derive from fitted trend extrapolation adjusted for technology substitution effects and regulatory inflection points. Forecast inputs incorporate Kubernetes-native engineering talent supply constraints and sovereign cloud certification pipeline timelines.
Caveats apply where hyperscaler pricing aggression, mainframe connectivity expertise erosion, or multi-jurisdiction encryption key management complexity could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and enterprise procurement cycle compression sustainability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Voice to Text on Mobile Devices Market
Software & Services
Lead Management Software Market
Software & Services
Sales Intelligence Software Market
Software & Services
Payroll and HR Software Market
Software & Services
Generative Design Software Market
Software & Services
Global Data Integration and Integrity Software Market
Software & Services
HPC Software Market
Software & Services
Middle East and Africa Automotive Software Market
Software & Services
Europe Integration Platform As a Service Market
Software & Services
Storyboarding Software Market
Software & Services
Sales Coaching Software Market
Software & Services
Screen and Video Capture Software Market
Software & Services
Data Center Backup and Recovery Software Market
Software & Services
Global Reporting Software Market
Software & Services
Global Document Management Software Market
Software & Services
Neurodiverse Workforce Productivity Tools Market