
 Enterprise Intellectual Property (IP) Management Software Market | 2026-2036
Enterprise Intellectual Property (IP) Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Enterprise Intellectual Property (IP) Management Software Market Foresight
Pharmaceutical and biotechnology end-use demand is pivoting toward integrated IP lifecycle platforms that unify patent prosecution with competitive intelligence. Anaqua sustains a dominant position in large-enterprise portfolio management through deep workflow customization for legal departments. Questel leverages its global patent data assets to anchor analytics modules that track prosecution outcomes across jurisdictions. Patsnap competes by extending AI-driven prior-art search capabilities that compress examination preparation timelines for research-intensive clients.
Enterprise Intellectual Property Management Software comprises modular platforms that orchestrate patent, trademark, and trade-secret workflows through structured databases, docketing engines, and analytics layers. These systems automate IDS preparation, deadline monitoring, and annuity payment verification while integrating with USPTO, EPO, and WIPO electronic filing portals. Cloud-based deployment leads segment adoption as corporations migrate away from on-premise maintenance burdens toward subscription models with embedded security compliance. Patent tracking functionality captures the fastest growth trajectory as prosecution teams demand real-time visibility into examiner behavior, continuation strategies, and competitive filing patterns. Law firm end users represent a mature segment where pricing pressure and client-mandated efficiency targets compress implementation margins.
The USPTO's evolving post-grant proceedings framework and the EPO's tightening opposition rules shape platform requirements for evidence management and deadline precision. FDA disclosure obligations for pharmaceutical patent linkages under Hatch-Waxman further tighten integration demands between regulatory and IP workflows. ISO 27001 certification and SOC 2 Type II attestation now function as baseline market-access requirements rather than differentiators for vendor selection. Stakeholders must monitor how generative AI tools for prior-art synthesis reshape examiner expectations and client willingness to pay for traditional search services.
Market Dynamics
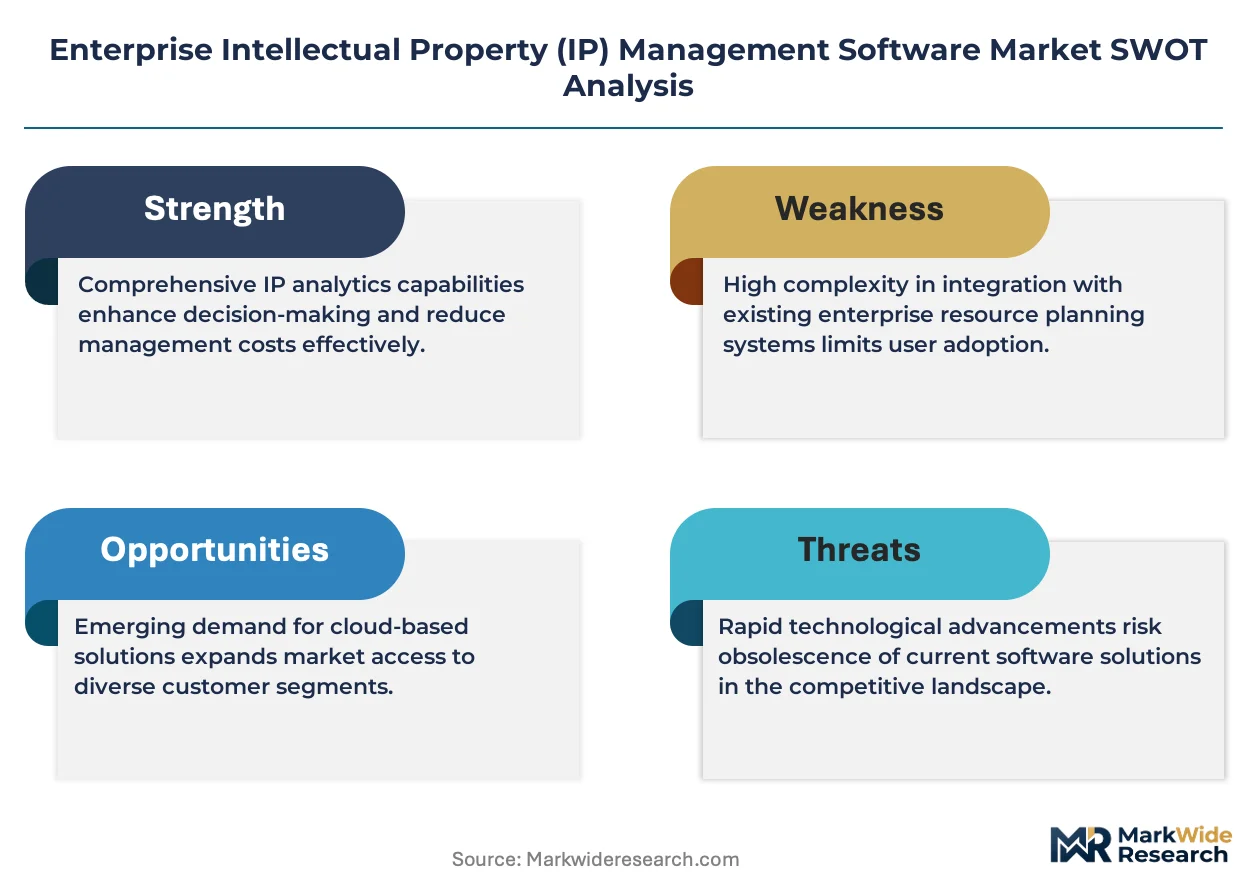
Generative AI tools for prior-art synthesis are compressing examiner expectations and client willingness to pay for traditional search services, forcing platform vendors to reconfigure value propositions around automated prosecution workflows.
Growth Catalysts
- US Leahy-Smith America Invents Act disclosure tightening:First-to-file requirements accelerate demand for deadline automation and IDS preparation modules across pharmaceutical patent portfolios.
- Biotechnology end-use digitization:Gene therapy developers deploy integrated IP lifecycle platforms to synchronize patent prosecution with FDA regulatory submissions under Hatch-Waxman linkage obligations.
- Cloud migration momentum:Corporate legal departments abandon on-premise maintenance burdens for SOC 2 Type II attested subscription models with embedded security compliance.
Market Restraints
- Specialized talent scarcity:Patent prosecution technologists with hybrid legal-engineering training command premium compensation, inflating implementation costs for enterprise deployments.
- Data sovereignty fragmentation:Divergent national cloud residency requirements across Germany, China, and Russia force redundant infrastructure investments.
- Legacy system entrenchment:Decades-old docketing databases resist API integration, trapping mid-market law firms in maintenance-heavy on-premise architectures.
Strategic Opportunities
- Indian pharmaceutical export compliance:CDSCO-mandated patent linkages for generic drug approvals create first-mover advantage for platforms localizing prosecution analytics.
- Trade secret module expansion:Know-how management tools for semiconductor process IP address gaps left by patent-centric legacy systems.
- ISO 56005 innovation management convergence:Certification-driven demand integrates IP analytics with R&D portfolio governance in research-intensive corporations.
Industry Challenges
- Generative AI hallucination risk:Prior-art synthesis tools generate false citations, exposing users to inequitable conduct penalties before USPTO examiners.
- Multi-jurisdiction deadline synchronization:EPO opposition timelines, USPTO continuation windows, and PCT national phase entries require real-time recalculation engines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Enterprise Intellectual Property (IP) Management Software Market |
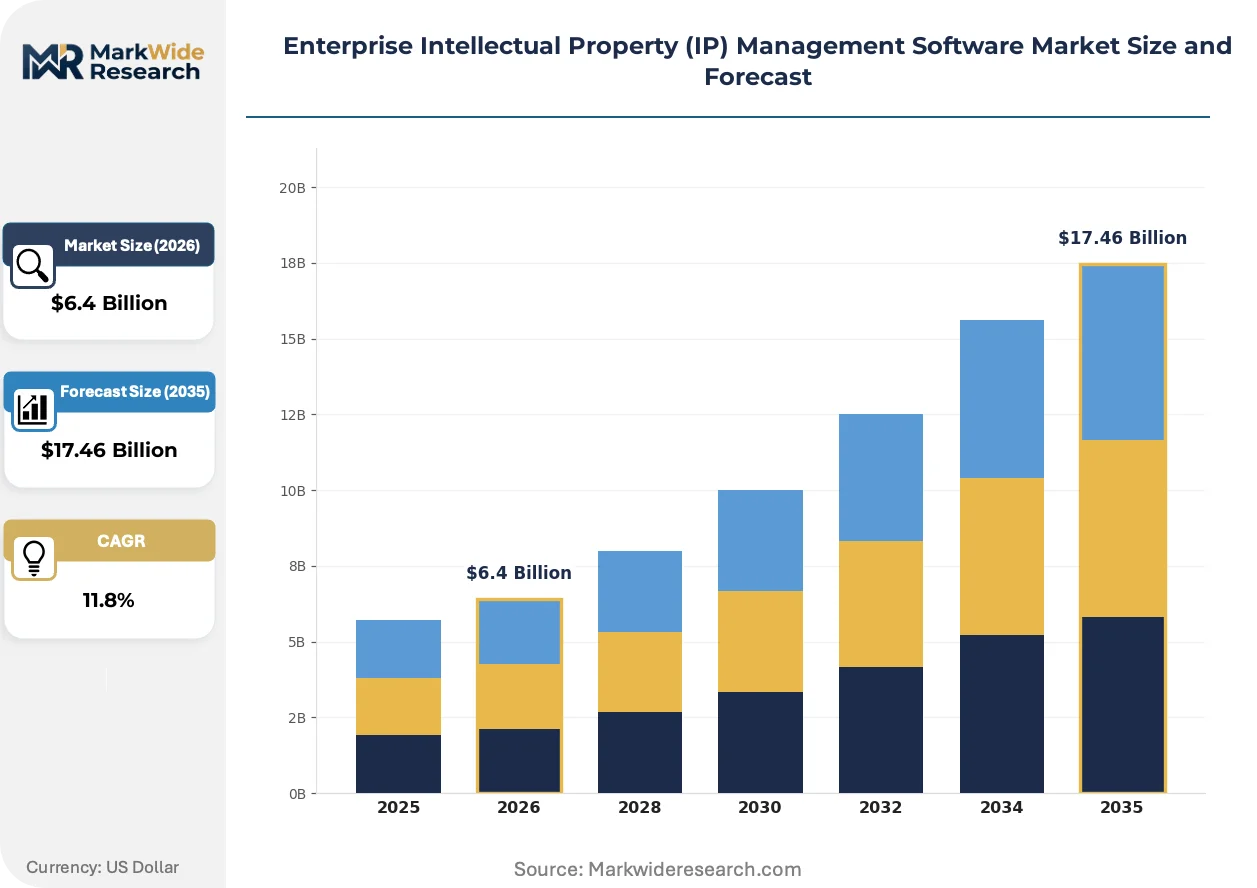
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $17.46 Billion |
| CAGR (2026 – 2036) | 11.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-based, On-premise, Hybrid, Desktop End User: Corporations, Law Firms, Research Institutions, Startups Feature: Document Management, Patent Tracking, Licensing, Analytics Service Type: Consulting, Implementation, Support, Training |
| Companies Covered | Questel, Anaqua, Inprotech, HeliosComplete, Alt Legal, Wellspring, Patsnap Analytics, Equinox, Clarivate IP Management, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Enterprise Intellectual Property (IP) Management Software Market Shifts & Advancements
Artificial intelligence is restructuring how prosecution teams prepare examination responses, with automation extending from prior-art retrieval into claim strategy optimization and competitive filing pattern analysis.
Natural language processing engines are unifying patent specification drafting with competitive intelligence monitoring. Pharmaceutical corporations deploy these tools to compress months of examiner behavior analysis into hours. The structural consequence is collapsing billable-hour models for traditional search services while elevating platform value toward strategic portfolio architecture.
EPO tightening of opposition evidence rules is mandating granular documentation standards for prior-art citations. Industrial consequence falls heaviest on biotechnology filers facing accelerated examination tracks. German pharmaceutical patent departments respond by embedding opposition analytics directly into prosecution workflow modules.
Enterprise legal departments now demand consumption-based licensing for IP management platforms rather than seat-based contracts. Channel disruption concentrates among mid-market law firms where client-mandated efficiency targets squeeze traditional implementation margins. This shift is most visible in United States corporate legal operations where procurement functions have centralized software vendor selection.
Enterprise Intellectual Property (IP) Management Software Market Segmentation
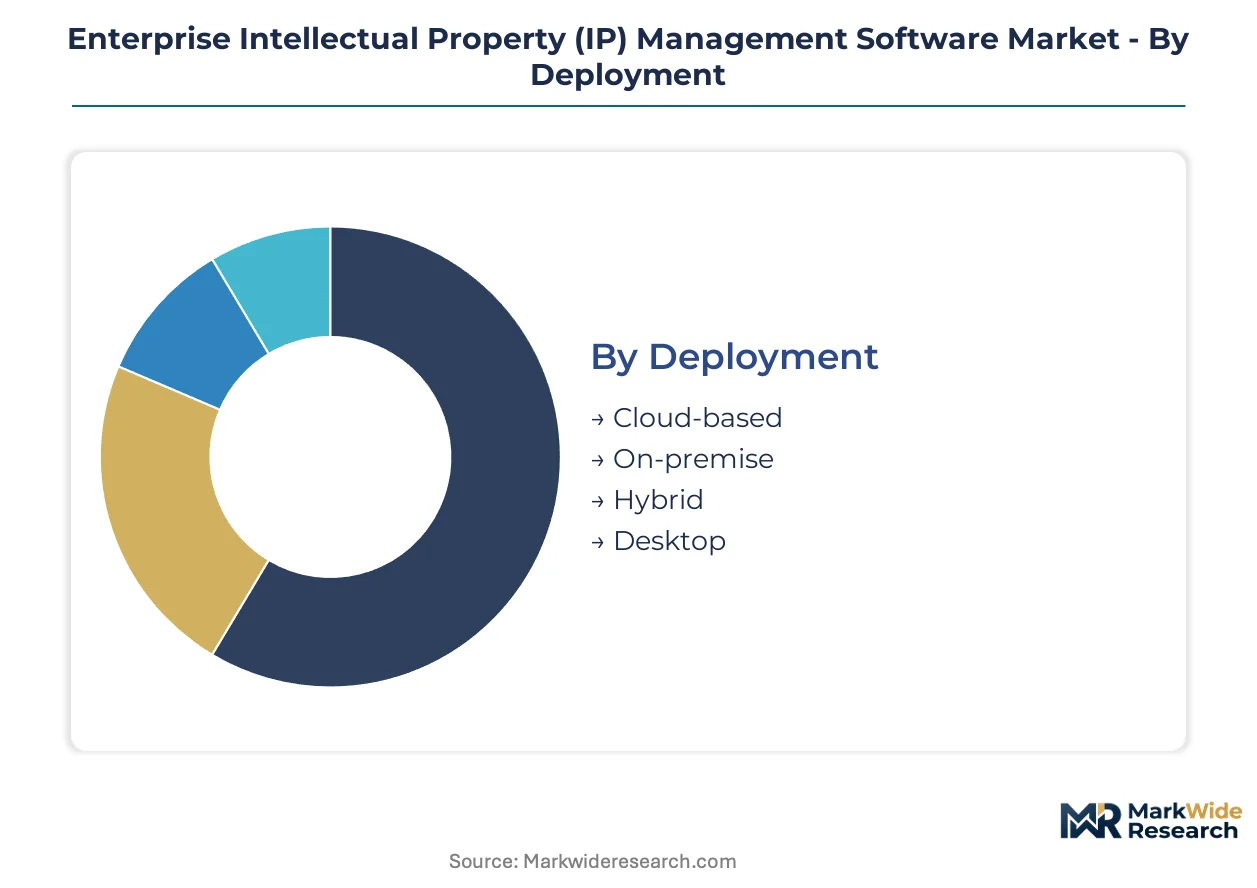
Segmentation in enterprise IP management software reveals how procurement criteria diverge across buyer sophistication levels. Deployment architecture, end-user complexity, and service requirements each impose distinct certification and integration burdens that reshape vendor competitive positioning.
Deployment:
ISO 27001 certification and SOC 2 Type II attestation function as baseline gating requirements for cloud-based procurement, while on-premise deployments face internal IT audit standards rather than external security frameworks.
- Cloud-based:Multi-tenant architectures with embedded encryption and automated compliance patching dominate pharmaceutical corporate adoption. US legal departments prioritize FedRAMP-authorized instances for federal contractor IP portfolios.
- On-premise:Legacy installations persist in defense contractors and classified research facilities where data sovereignty mandates air-gapped infrastructure. German automotive patent teams retain on-premise docketing systems to satisfy internal compliance protocols.
- Hybrid:Split configurations segregate active prosecution data in private clouds while archiving completed matters to public infrastructure. Biotechnology startups deploy hybrid models to balance cost control with examiner-facing document security.
- Desktop:Single-user installations survive in solo practitioner law offices and individual inventors with minimal portfolio complexity. These instances lack API connectivity to USPTO electronic filing systems.
Cloud-based sits at the top of the volume ranking, with hybrid climbing the fastest as procurement teams seek intermediate risk postures.
End User:
Cost tier stratification separates enterprise-grade workflow customization from standardized SaaS offerings aimed at budget-constrained buyers.
- Corporations:Fortune 500 legal departments demand white-glove implementation with dedicated customer success managers and custom docketing rule engines. US pharmaceutical giants negotiate enterprise-wide master service agreements spanning multiple jurisdictions.
- Law Firms:AmLaw 200 firms face acute pricing pressure from corporate clients mandating efficiency targets and alternative fee arrangements. These buyers prioritize matter-level profitability analytics over portfolio-wide strategic tools.
- Research Institutions:University technology transfer offices operate on constrained budgets with intermittent filing volumes. Federal grant compliance requirements drive demand for invention disclosure automation rather than full prosecution suites.
- Startups:Venture-backed biotechnology founders purchase seat-limited subscriptions with rapid scaling clauses tied to funding milestones. Y Combinator and similar accelerators negotiate portfolio-wide educational licenses for cohort companies.
Corporations command the highest average contract values, with startups expanding most quickly as venture funding flows into patent-intensive sectors.
Feature:
Application criticality determines which modules achieve procurement priority during budget compression cycles.
- Patent Tracking:Real-time docketing engines with automated deadline recalculation across USPTO, EPO, and PCT timelines represent the core value proposition for prosecution-heavy users. Biotechnology filers on accelerated examination tracks depend on granular examiner behavior analytics.
- Document Management:Centralized repositories with version control and IDS auto-generation streamline pre-filing workflows. These systems integrate directly with USPTO electronic filing systems and WIPO ePCT portals.
- Analytics:Competitive intelligence modules tracking rival filing patterns and continuation strategies command premium pricing. Pharmaceutical portfolio managers use these tools to identify white-space opportunities in crowded therapeutic areas.
- Licensing:Royalty tracking and contract lifecycle management features address revenue-generating IP operations. These modules see strongest adoption in semiconductor and software patent holders with established outbound licensing programs.
Patent tracking leads feature adoption by installed base, with analytics gaining share fastest as procurement shifts toward strategic intelligence over administrative automation.
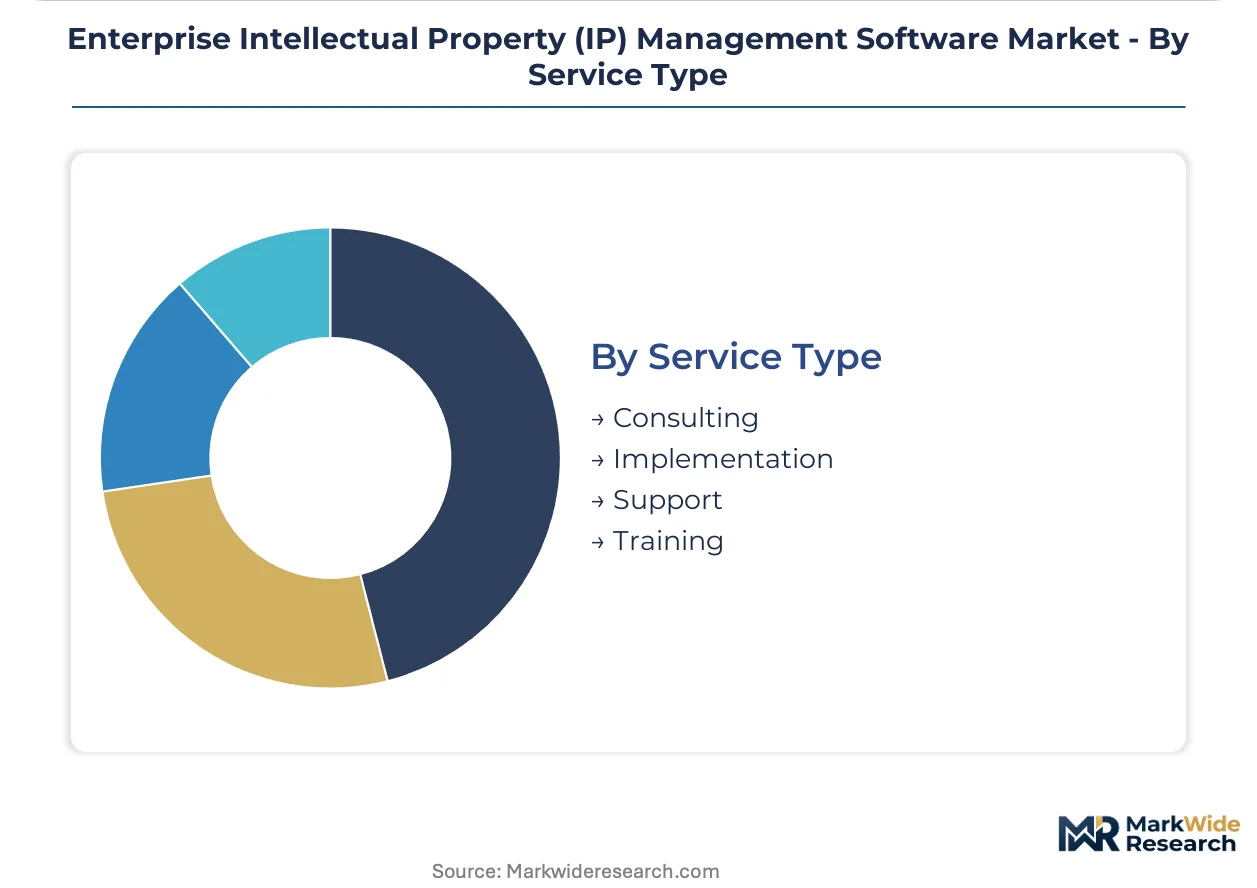
Service Type:
Customer maturity and internal technical capacity dictate whether buyers consume professional services or self-implement through vendor documentation.
- Implementation:Complex data migration from legacy docketing systems requires specialized project teams with hybrid legal-technical expertise. Mid-market law firms struggle to resource these conversions without vendor support.
- Consulting:Strategic advisory services cover portfolio optimization, competitive positioning analysis, and prosecution workflow redesign. These engagements typically precede or accompany platform upgrades.
- Support:Tiered response-time guarantees differentiate enterprise contracts from standard subscriptions. 24/7 coverage with dedicated technical account managers commands substantial premiums.
- Training:Certification programs for power users and administrator-level configuration skills reduce long-term dependency on vendor professional services. Corporate legal operations teams prioritize train-the-trainer models for cost containment.
Implementation generates the largest service revenue pool, with consulting expanding most quickly as buyers seek strategic guidance beyond technical deployment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is accelerating procurement decisions as pharmaceutical corporations migrate IP management workloads toward jurisdictions offering streamlined patent examination and favorable tax treatment for R&D documentation. Cost-of-compliance gaps between the United States and select European and Asian markets now exceed implementation differentials for cloud-based platforms.
United States
Dense patent litigation activity in Delaware and Eastern Texas federal districts sustains demand for prosecution workflow automation and competitive intelligence modules. The USPTO's post-grant proceedings framework under the Leahy-Smith America Invents Act mandates granular deadline tracking across inter partes review and reexamination timelines. Boston and San Francisco biotechnology clusters anchor enterprise deployment volumes for integrated IP lifecycle platforms.
Germany
Automotive and pharmaceutical patent departments in Munich and Stuttgart drive adoption of opposition analytics embedded directly into prosecution workflows. The EPO's tightening evidence standards for opposition proceedings force granular documentation investments. Baden-Württemberg industrial patent teams retain hybrid cloud configurations to satisfy internal compliance protocols while accessing real-time examiner behavior data.
China
Domestic pharmaceutical filers and semiconductor manufacturers accelerate platform procurement to manage dual filing strategies across SIPO and PCT channels. The country's national intellectual property regulator continues harmonizing examination guidelines with WIPO standards. Beijing and Shanghai corporate legal departments prioritize multi-tenant architectures with localized data residency for trade secret protection.
India
CDSCO-mandated patent linkages for generic drug approvals create first-mover opportunity for platforms localizing prosecution analytics to Indian pharmaceutical export compliance. The central government's production-linked incentive schemes for active pharmaceutical ingredients intensify documentation requirements. Hyderabad and Mumbai generic manufacturers deploy seat-limited subscriptions with rapid scaling clauses tied to ANDA filing milestones.
United Kingdom
Post-Brexit divergence from EU trademark systems sustains demand for modular platforms managing split UK-EU portfolios. The UK Intellectual Property Office's accelerated examination tracks for green technology patents attract cleantech venture investment. London financial services patent teams prioritize consumption-based licensing models over traditional seat-based contracts.
Enterprise Intellectual Property (IP) Management Software Market Competitive Landscape
Platform specialization dominates the current landscape as vendors retreat from horizontal suites toward defensible workflow niches. The vendor base clusters around three archetypes: legacy docketing incumbents with deep customization capabilities, data-centric analytics platforms anchored to global patent corpora, and AI-native entrants compressing prior-art search timelines. Competitive intensity concentrates on two vectors: strategic partnerships with national patent offices for direct filing integration, and vertical integration into regulatory submission workflows for pharmaceutical clients.
Within the enterprise customization tier, Anaqua and Questel occupy positions representing divergent strategic bets—one emphasizing legal department workflow depth, the other leveraging global patent data assets for prosecution outcome tracking. Patsnap exemplifies the AI-native archetype, anchoring competitive positioning around examiner-facing document preparation acceleration.
| Leading Market Players |
|---|
| Questel |
| Anaqua |
| Inprotech |
| HeliosComplete |
| Alt Legal |
| Wellspring |
| Patsnap Analytics |
| Equinox |
| Clarivate IP Management |
| Others |
Supply & Pricing Matrix
Corporate legal department procurement centralization is forcing platform vendors toward consumption-based licensing models that compress implementation margins while demanding SOC 2 Type II attestation as table stakes. This buyer consolidation shifts supply-side investment toward cloud infrastructure redundancy and specialized professional services capacity.
Pricing Analysis
Direct-to-enterprise discounts dominate cloud-based subscription negotiations, with Fortune 500 master service agreements commanding volume-based rate cards. Three-tier pricing structure across premium, standard, and economy levels separates white-glove implementation with dedicated customer success managers from self-service SaaS tiers. Cost compression in mid-market law firm segments is intensifying because client-mandated efficiency targets squeeze traditional billable-hour recovery. Research institutions and university technology transfer offices exhibit highest price sensitivity, while pharmaceutical corporations with federal R&D tax incentives show lowest sensitivity to per-seat costs.
Supply Chain Analysis
Regional distribution centers for cloud infrastructure concentrate in the United States, Germany, and Singapore to satisfy data residency mandates across pharmaceutical and defense contractor deployments. Platform development draws from specialized patent prosecution technologists with hybrid legal-engineering training, cloud security certification pipelines, and AI/ML research talent pools. Single-source vulnerability concentrates in legacy docketing database migration specialists, where decades-old system entrenchment traps mid-market buyers. Distribution runs through direct enterprise sales teams, channel partners serving law firm segments, and accelerator-network educational licenses for startup cohorts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Enterprise IP Management Software Market functions as a stable compounder, with regulatory disclosure tightening under the US Leahy-Smith America Invents Act and evolving EPO guidelines driving persistent platform refresh cycles.
For Market Incumbents: Anchor defensive positioning through ISO 56005 innovation management certification integration and backward integration into regulatory submission workflows for Hatch-Waxman compliance. Deepen workflow customization moats against AI-native entrants compressing prior-art search timelines. Prioritize strategic partnerships with national patent offices for direct USPTO and EPO filing portal integration. For New Entrants and Emerging Players: Begin with trade secret module expansion for semiconductor process IP, where patent-centric legacy systems leave persistent gaps. Indian pharmaceutical export compliance presents the most penetrable geography, with CDSCO-mandated patent linkages for generic drug approvals creating first-mover timing. Pursue seat-limited subscription models with rapid scaling clauses tied to ANDA filing milestones. For Investors and Strategic Acquirers: Asymmetric upside sits with AI-native platforms possessing examiner-facing document preparation acceleration capabilities and established training data moats. Long-term viability centers on vendors bridging IP analytics with R&D portfolio governance in research-intensive corporations. Monitor generative AI hallucination risk exposure as inflection indicator for inequitable conduct liability and client willingness-to-pay compression.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies patent prosecution with FDA regulatory submission workflows under Hatch-Waxman obligations. |
| Strategic Partnership | Secures direct filing integration with USPTO and EPO electronic portals for deadline automation. |
| Acquisition of Specialist Firm | Captures hybrid legal-engineering talent pools for complex legacy docketing system migrations. |
| Geographic Expansion | Localizes prosecution analytics for CDSCO-mandated patent linkages in Indian pharmaceutical exports. |
| Product Launch | Deploys AI-driven prior-art synthesis modules that compress examination preparation timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with IP operations directors, legal department procurement leads, patent prosecution attorneys, cloud security compliance officers, and biotechnology portfolio managers with secondary validation against USPTO filing statistics, EPO opposition records, FDA Orange Book listings, and corporate R&D tax credit disclosures. Bottom-up deployment volume estimates triangulated against top-down market sizing across cloud, on-premise, hybrid, and desktop architectures.
Historical reference periods anchored the projection horizon through patent filing volume trajectories, cloud migration adoption curves, and regulatory implementation timelines across the Leahy-Smith America Invents Act disclosure phases and EPO opposition rule evolutions. Segmentation dimensions modeled deployment architecture, end-user complexity tier, feature module criticality, and service consumption pattern. CAGRs derived from patent prosecution automation penetration rates, examiner behavior analytics adoption, and competitive intelligence module attach rates.
Caveats apply where generative AI tool maturation, examiner expectation shifts, or data sovereignty regulatory fragmentation could materially shift the outlook. Forecasts reflect documented assumptions regarding cloud security certification baseline requirements and pharmaceutical regulatory linkage integration demand. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Recipe Apps Market
Software & Services
Global Backup Restore Software Market
Software & Services
Global Franchise Management Software Market
Software & Services
Global Furniture Manufacturing Software Market
Software & Services
Global CMDB Software Market
Software & Services
Product Analytics Software Market
Software & Services
Global Meeting Room Booking System Software Market
Software & Services
Labor Management Software Market
Software & Services
Global Product Management Software Market
Software & Services
Employee Wellness Software Market
Software & Services
Tableau Services Market
Software & Services
Oracle Services Market
Software & Services
Simulation Software Market
Software & Services
Building Information Modeling (BIM) Extraction Software Market
Software & Services
Global Jewelry Store Management Software Market
Software & Services
BIM Objects Software Market