
 Global Employee Engagement Software Market | 2026-2036
Global Employee Engagement Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Employee Engagement Software Market Analysis
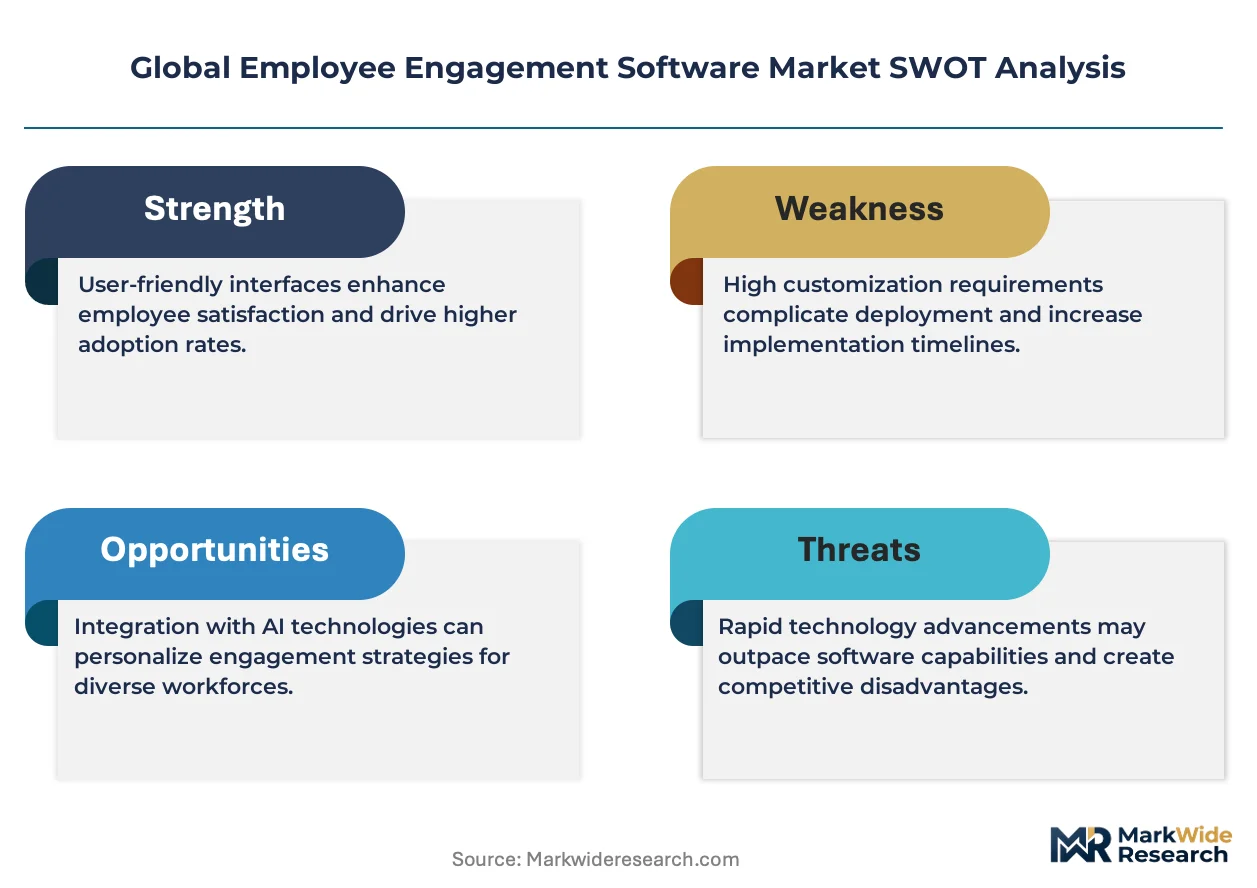
ISO 30414 human capital reporting standards is bifurcating the competitive landscape into disclosure-ready platform providers and legacy point-solution vendors. Workday leverages its native HRIS integration to anchor enterprise accounts with unified data models. Lattice competes through modular performance-management tooling that extends across mid-market buyers. Qualtrics differentiates by embedding experience-management analytics into engagement workflows for multinational employers.
Employee engagement software encompasses cloud-deployed applications that capture workforce sentiment, track performance metrics, and automate recognition programs through pulse surveys, 360-degree feedback engines, and AI-driven recommendation systems designed to reduce attrition and lift productivity. Cloud-based deployments now dominate new procurement as IT departments prioritize API-first architectures that integrate with existing HR stacks. Comprehensive platforms capture the widest margin pools by bundling feedback management, performance management, and recognition programs into single subscriptions, while freemium pricing models accelerate land-and-expand adoption among startups and small enterprises.
The U.S. Equal Employment Opportunity Commission and the EU's GDPR enforcement framework together shape product roadmaps by mandating audit trails for algorithmic HR decisions and restricting cross-border personnel data flows. OSHA whistleblower protections and the EU AI Act's risk-classification rules for employment applications are forcing vendors to build explainable AI modules and localized data residency options. Stakeholders must monitor how rapidly evolving algorithmic accountability legislation in multiple jurisdictions will redefine vendor liability and procurement criteria.
Market Dynamics
ISO 30414 human capital disclosure mandates are forcing procurement teams to abandon point-solution architectures in favor of unified data models that can generate audit-ready workforce metrics.
Growth Catalysts
- EU AI Act risk classification:Employment applications now face mandatory explainability requirements, pushing enterprises toward vendors with built-in algorithmic transparency modules.
- Healthcare workforce retention:Hospital systems facing nursing shortages are deploying pulse-survey platforms to identify burnout patterns before voluntary turnover accelerates.
- API-first integration:IT departments now require engagement tools that embed directly into existing HRIS stacks without custom middleware development.
Market Restraints
- GDPR data-residency costs:Cross-border personnel data flows require localized server infrastructure, inflating deployment expenses for multinational employers.
- Cloud concentration risk:Three hyperscale providers dominate hosting infrastructure, creating single-point-of-failure exposure for SaaS engagement platforms.
- Algorithmic audit complexity:OSHA whistleblower protections mandate documentation trails that many legacy sentiment-analysis engines cannot generate automatically.
Strategic Opportunities
- CSRD mandate expansion:European sustainability reporting rules now capture social metrics, creating compliance-driven demand for workforce analytics dashboards.
- Frontline worker digitization:Manufacturing and logistics employers are extending engagement tools to non-desk employees through mobile-native pulse applications.
- Recognition-API monetization:Vendors are exposing peer-to-peer reward engines as standalone microservices for integration into third-party collaboration platforms.
Industry Challenges
- Behavioral data science talent:Vendors struggle to hire industrial-organizational psychologists capable of designing valid predictive attrition models.
- Legacy system integration:Mainframe-based payroll and benefits platforms in established enterprises resist real-time API connectivity for sentiment data ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Employee Engagement Software Market |
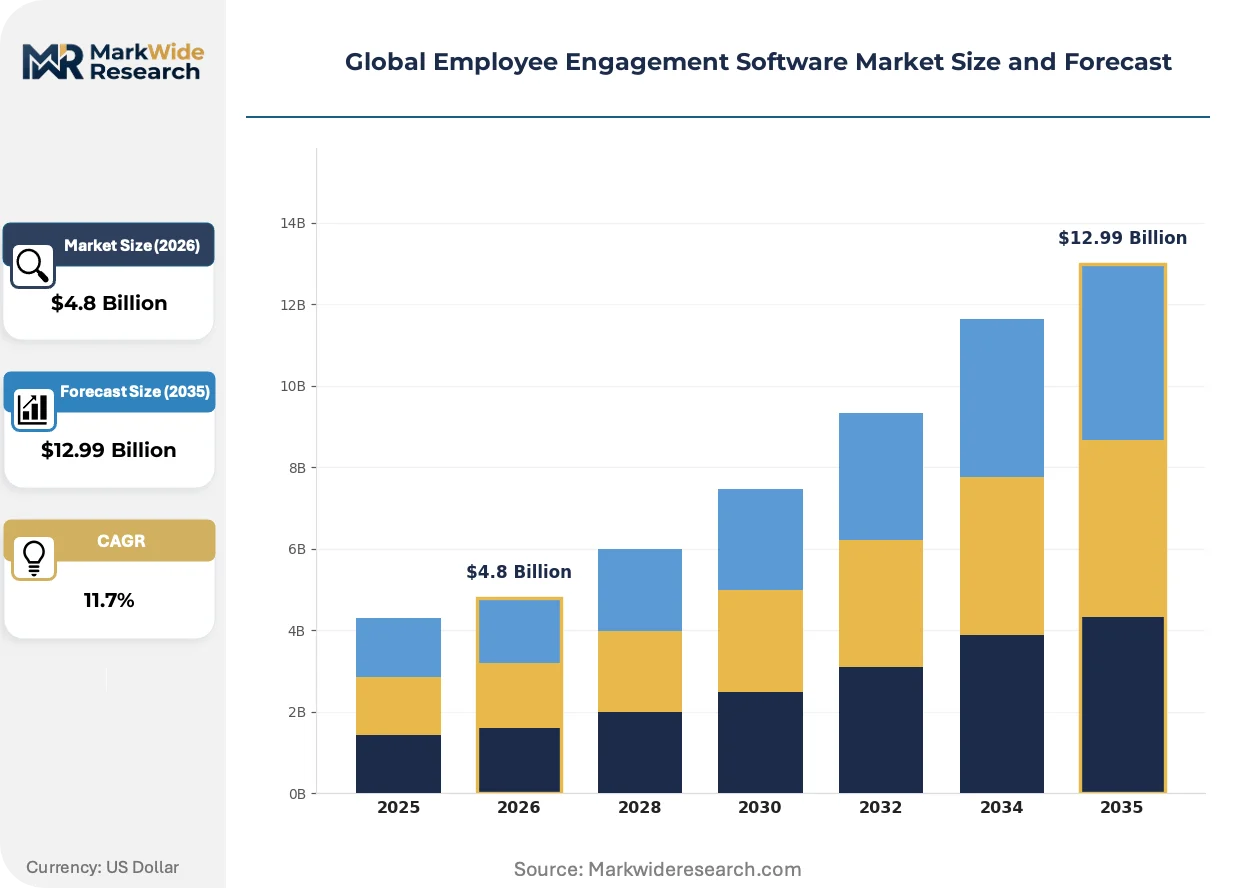
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Small Enterprises, Medium Enterprises, Large Corporations, Startups Solution: Feedback Management, Performance Management, Recognition Program, Comprehensive Platforms Pricing Model: Subscription-Based, One-Time License, Freemium, Tiered Pricing |
| Companies Covered | Lattice, Workday, Culture Amp, Achievers, SAP, 15Five, Leapsome, Workhuman, Qualtrics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Employee Engagement Software Market Emerging Trajectories
Generative AI is compressing the feedback-to-action cycle by auto-generating personalized manager coaching recommendations from unstructured survey responses. This capability is redrawing competitive boundaries between established platforms and specialized entrants.
Natural language processing engines trained on workforce sentiment corpora are bifurcating the vendor landscape. Healthcare systems and professional services firms are adopting these tools fastest, replacing annual engagement surveys with continuous listening architectures. The technology is bifurcating platform economics by concentrating margin in inference-layer providers while commoditizing survey-collection infrastructure.
The EU AI Act's high-risk system designation for employment decisions is mandating human-in-the-loop overrides for automated recommendations. Vendors must now build dual-path workflows where AI suggestions route through manager approval gates. European deployments are experiencing month-long implementation delays as legal teams validate compliance documentation.
Subscription unbundling is fragmenting buyer contracts. Mid-market employers are purchasing pulse-survey modules separately from performance-management suites, reversing prior consolidation toward all-in-one platforms. This pattern is most pronounced among technology startups with lean HR functions, where point solutions integrate more cleanly with existing Slack or Microsoft Teams environments.
Global Employee Engagement Software Market Segmentation
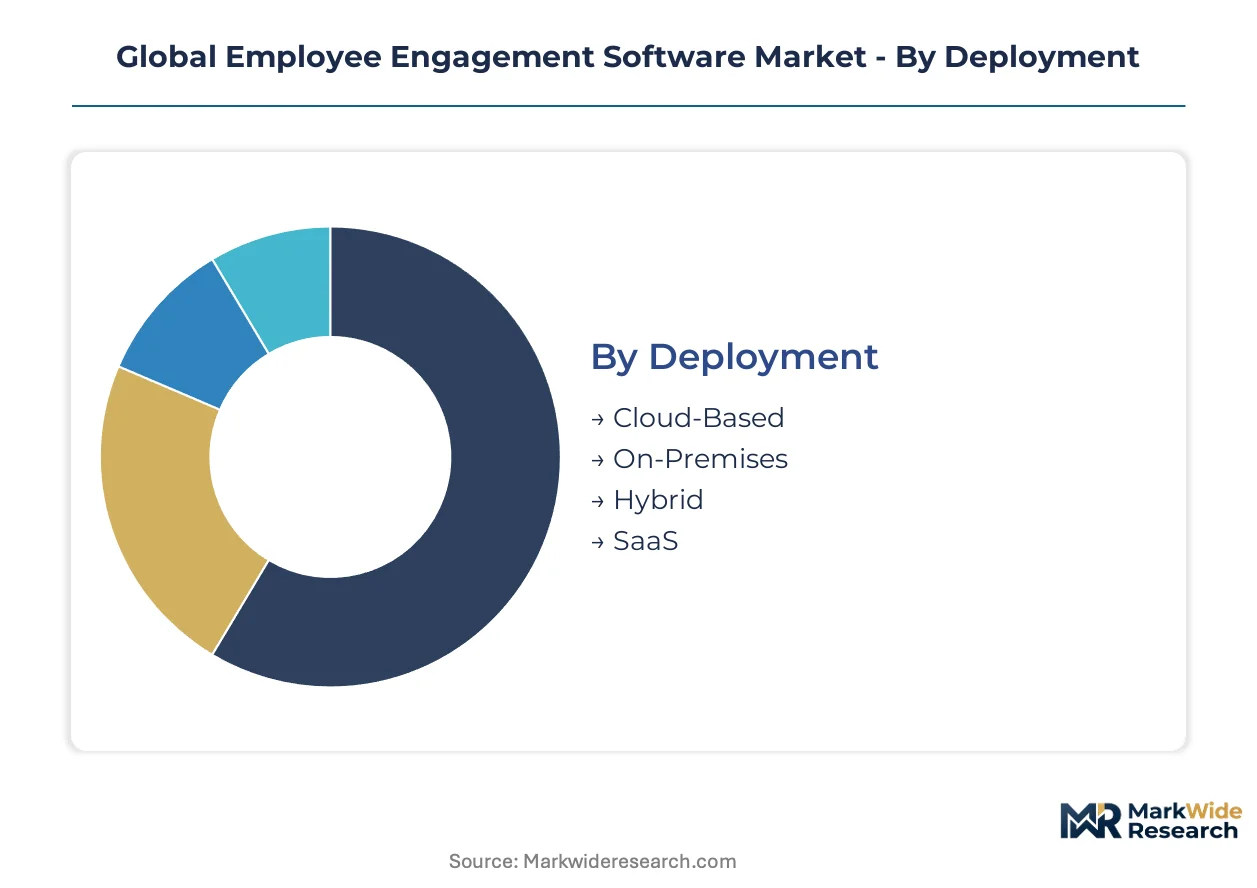
Segmentation in employee engagement software reveals how procurement priorities diverge across IT architectures, organizational scale, and commercial models. Buyers optimize for integration depth, compliance posture, and workforce analytics maturity rather than feature breadth alone.
Deployment:
Cloud-native architectures face intensifying substitution pressure from hybrid configurations as GDPR data-residency mandates force localized infrastructure investments.
- Cloud-Based:Multi-tenant SaaS architectures with API-first design patterns dominate new procurement among mid-market employers. United States enterprises prioritize these deployments for rapid HRIS integration without on-premise maintenance overhead.
- SaaS:Single-tenant managed services with dedicated instance isolation attract healthcare systems and financial services firms under strict audit requirements. Germany and France show concentrated demand as CNIL and BfDI enforcement hardens around cross-border data flows.
- Hybrid:Split architectures keeping sentiment data on-premise while analytics processing runs in cloud environments.
- On-Premises:Fully air-gapped deployments for defense contractors and critical infrastructure operators.
Cloud-Based deployments anchor the volume base while SaaS gains share at the steepest rate as compliance-sensitive sectors upgrade from legacy on-premise systems.
End User:
Cost tier segmentation separates buyers by procurement sophistication and integration complexity tolerance.
- Large Corporations:Global employers with 10,000+ headcount demand unified data models spanning multiple HRIS instances. ISO 30414 disclosure requirements drive these buyers toward comprehensive platforms with audit-ready workforce metrics.
- Medium Enterprises:Organizations between 500-5,000 employees represent the most contested segment. United Kingdom and Netherlands employers in this bracket favor modular solutions integrating with existing Microsoft 365 or Google Workspace environments.
- Small Enterprises:Lean HR functions purchasing point solutions through self-service channels.
- Startups:Venture-backed companies prioritizing freemium entry points with land-and-expand revenue models.
Large Corporations consume the highest absolute seat volumes while Medium Enterprises show the steepest expansion trajectory as ISO standards penetrate sub-enterprise procurement criteria.
Solution:
Application-based segmentation tracks how workforce analytics capabilities bundle or fragment across buyer journeys.
- Comprehensive Platforms:Integrated suites combining pulse surveys, 360-degree feedback, goal management, and recognition engines. Healthcare systems facing nursing shortages deploy these most aggressively to identify burnout patterns before voluntary turnover accelerates.
- Performance Management:Specialized modules for continuous feedback and career pathing. Professional services firms in Australia and Singapore adopt these fastest to replace annual review cycles with project-based coaching workflows.
- Feedback Management:Survey collection and sentiment analysis point solutions.
- Recognition Program:Peer-to-peer reward and milestone celebration tooling.
Comprehensive Platforms capture the widest margin pools while Performance Management climbs fastest as annual review cycles face systematic replacement.
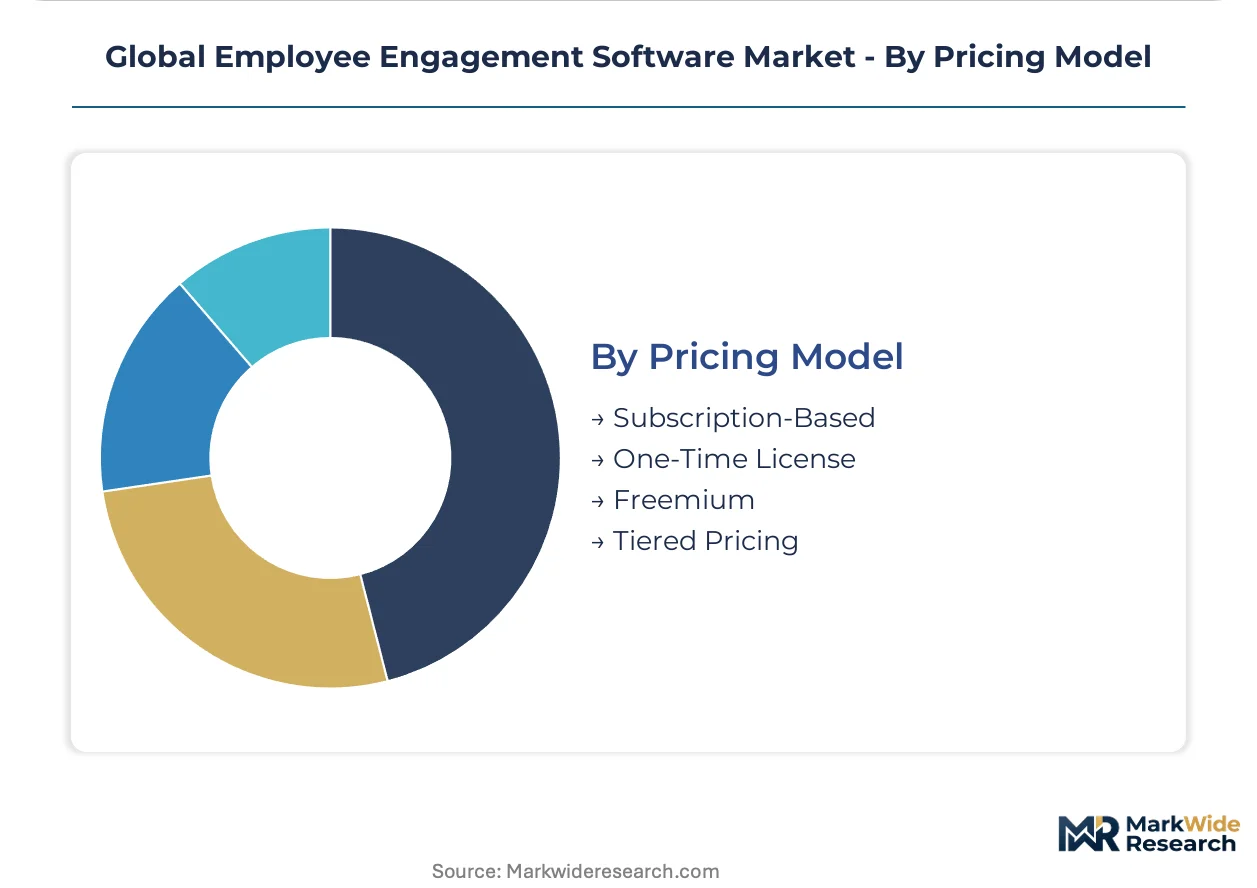
Pricing Model:
Customer type and contract structure segmentation reveals monetization strategy divergence across buyer maturity levels.
- Subscription-Based:Annual or multi-year recurring contracts with per-employee-per-month pricing. Enterprise procurement teams in the United States negotiate these most aggressively, demanding API rate guarantees and uptime SLAs above 99.9%.
- Freemium:Self-service entry tiers with feature-gated conversion paths. Technology startups in Israel and Sweden convert through these models at the highest rates, expanding to paid tiers once headcount exceeds 50 employees.
- Tiered Pricing:Three-band structures separating essential, professional, and enterprise capability levels.
- One-Time License:Perpetual deployment rights with annual maintenance fees.
Subscription-Based contracts anchor vendor revenue predictability while Freemium expands addressable market reach most quickly among pre-revenue and seed-stage employers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
GDPR enforcement and ISO 30414 disclosure mandates are redirecting procurement budgets toward compliant vendors with localized data architecture. Healthcare workforce retention pressures and API-first integration requirements are accelerating adoption curves across distinct national markets.
United States
Enterprise software procurement budgets remain the world's deepest, with hospital systems deploying pulse-survey platforms to combat nursing shortages. OSHA whistleblower protections mandate documentation trails that vendors must embed into sentiment-analysis engines. The Boston-Seattle corridor concentrates healthcare technology buyers seeking burnout prediction tools.
Germany
Industrial employers in automotive and machinery sectors demand hybrid deployments keeping personnel data on-premise while analytics processing runs cloud-based. BfDI enforcement hardens around cross-border data flows, forcing dedicated instance isolation. Munich and Stuttgart anchor the steepest SaaS conversion rates as compliance-sensitive manufacturers upgrade legacy systems.
United Kingdom
Mid-market employers between 500-5,000 employees favor modular solutions integrating with Microsoft 365 environments. The Information Commissioner's Office audits algorithmic HR decisions with increasing frequency. London and Manchester concentrate professional services firms replacing annual review cycles with continuous feedback architectures.
India
Technology startups in Bengaluru and Hyderabad convert through freemium entry points at the highest rates, expanding to paid tiers once headcount exceeds 50 employees. The Digital Personal Data Protection Act shapes vendor data residency requirements for multinational back-office operations. Mumbai's financial services cluster drives demand for audit-ready workforce metrics.
Israel
Venture-backed employers prioritize API-first architectures that embed directly into existing collaboration stacks without middleware development. The Privacy Protection Authority enforces strict cross-border transfer limitations for personnel sentiment data. Tel Aviv's dense startup ecosystem generates concentrated demand for recognition-API microservices.
Global Employee Engagement Software Market Vendor Landscape
Listed leaders compete with private specialists across platform breadth versus modular depth. The vendor landscape organizes into three tiers: comprehensive suite providers anchoring enterprise accounts, performance-management specialists capturing mid-market expansion, and point-solution vendors serving lean HR functions. Strategic moves concentrate on M&A for data science talent and geographic expansion through localized hosting partnerships.
Within the comprehensive platform tier, Workday exemplifies native HRIS integration anchoring unified data models, while Qualtrics occupies a position embedding experience-management analytics into engagement workflows. Lattice represents the modular specialist archetype, extending performance-management tooling across mid-market buyers seeking clean integration with existing collaboration environments.
| Leading Market Players |
|---|
| Lattice |
| Workday |
| Culture Amp |
| Achievers |
| SAP |
| 15Five |
| Leapsome |
| Workhuman |
| Qualtrics |
| Others |
Supply Flow & Price Mechanics
API-first architecture substitution for legacy middleware stacks is redrawing supply geography toward cloud-native development clusters while compressing pricing economics for integration-heavy deployments. This shift concentrates vendor engineering resources in United States and Israeli technology corridors where specialized talent pools command premium compensation, feeding back into per-employee-per-month pricing structures that separate API-native platforms from configuration-dependent alternatives.
Pricing Analysis
ISO 30414 certification readiness creates the primary spread between audit-ready platform tiers and basic survey-collection utilities. Three-tier pricing structure across premium, standard, and economy levels anchors enterprise procurement at the top band with guaranteed API rate limits and 99.9% uptime SLAs, while mid-market buyers negotiate standard tiers bundling core feedback and performance modules. Cost compression in the economy tier intensifies because freemium conversion engines subsidize user acquisition, making technology startups with sub-50 headcount the most price-sensitive segment and ISO-compliant healthcare systems the least.
Supply Chain Analysis
Inventory cycles for sentiment-analysis inference compute run 6-8 weeks at Nvidia and AMD distribution hubs, creating lead-time vulnerability during demand spikes. Engineering talent concentrates in United States, Israel, and India, where industrial-organizational psychologists and machine-learning engineers anchor platform development. The supply chain draws from hyperscale cloud infrastructure in United States, European Union, and Singapore, creating single-source vulnerability when GDPR data-residency mandates fragment hosting requirements. Distribution runs through direct enterprise sales teams for large accounts and self-service web portals for sub-500 employee buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial-organizational psychology expertise scarcity constrains predictive attrition model quality, creating competitive moats for vendors with captive behavioral data science teams and exposing point-solution vendors to talent poaching. This capability gap justifies aggressive compensation and acquisition strategies for specialized human capital.
For Market Incumbents: Secure exclusive partnerships with university industrial-organizational psychology departments to pipeline talent before emerging AI-native entrants can recruit. Lock in dedicated cloud instance capacity in Frankfurt and Singapore before GDPR enforcement hardens data-residency requirements and inflates hosting costs. Vertical integration into native HRIS data models anchors enterprise accounts against modular disaggregation threats. For New Entrants and Emerging Players: Differentiate on frontline-worker mobile-native architectures where manufacturing and logistics employers show minimal incumbent penetration. Target Indian technology startups and Israeli venture-backed employers with freemium entry points that convert at headcount thresholds above 50 employees. Pursue recognition-API microservices as a standalone wedge, embedding peer-to-peer reward engines into Slack and Microsoft Teams environments without requiring full platform displacement. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors comprehensive platform providers with ISO 30414 disclosure engines over point-solution vendors facing procurement abandonment. Long-term viability across the next decade hinges on algorithmic explainability modules that satisfy EU AI Act employment-risk classifications. Acquisition target archetype: mid-market performance-management specialists with clean Microsoft 365 integration and existing healthcare system logos. Watch for CSRD mandate expansion signals as workforce social metrics enter European sustainability reporting requirements, indicating inflection toward compliance-driven analytics demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Native HRIS data models reduce middleware costs for United States enterprise buyers. |
| Acquisition of Specialist Firm | Industrial-organizational psychology teams accelerate predictive attrition model deployment. |
| Geographic Expansion | Localized Frankfurt hosting satisfies BfDI cross-border enforcement for German manufacturers. |
| Product Launch | Explainable AI modules address EU AI Act high-risk system mandates for employment decisions. |
| Strategic Partnership | Microsoft Teams embedding extends reach into United Kingdom mid-market professional services. |
Methodological Framework
Initial hypotheses were tested against primary input from chief technology officers, HR information systems directors, procurement officers at hospital systems, and integration specialists at Microsoft and Slack, then refined through secondary validation. Primary fieldwork drew from SEC filings of publicly traded software vendors, hyperscaler capex disclosures from AWS and Azure, GDPR enforcement actions by CNIL and BfDI, and ISO 30414 implementation guidance documents. Bottom-up sizing of seat volumes and top-down cross-check against enterprise software procurement budgets anchored triangulation.
Variance decomposition across deployment models, organization size tiers, vertical industry adoption patterns, and regional regulatory clusters shaped analytical framework construction throughout the forecast period. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Model inputs included healthcare workforce turnover statistics from United States Bureau of Labor Statistics, EU AI Act implementation timelines, and cloud infrastructure availability zone expansion announcements.
The analysis sits within stated boundaries; outcomes outside sustained GDPR enforcement intensity or accelerated ISO 30414 adoption timelines would require recalibration. Forecasts reflect documented assumptions about regulatory implementation pace and enterprise procurement cycle normalization. Algorithmic accountability legislation evolution and hyperscale cloud concentration events represent specific risk factors that could revise projections. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Worldwide Persuasive Content Management Software Market
Software & Services
Push Notifications Software Market
Software & Services
Supplier Quality Management Applications Market
Software & Services
Sports Facility Scheduling and Management Software Market
Software & Services
Global Quantum Computing Software Market
Software & Services
Enterprise Resource Planning (ERP) Software Market
Software & Services
Design Collaboration Software Market
Software & Services
Creative Software Market
Software & Services
Global Remote Work Software Market
Software & Services
Global Integration Software Market
Software & Services
Indoor Cycling Software Market
Software & Services
Global PPC Software Market
Software & Services
Load Balancing Software Market
Software & Services
Video Management Software (VMS) Market
Software & Services
Tenant Billing Software Market
Software & Services
Home Design Software Market