
 Global Electronic Data Capture Software Market | 2026-2036
Global Electronic Data Capture Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Electronic Data Capture Software Market Foresight
EU MDR compliance pressure is hardening requirements for audit trails and source-data verification across medical device trials. Medidata Solutions leverages its cloud-native architecture to dominate large-scale oncology studies across North America and Europe. Oracle sustains competitive positioning through deep integration with its broader clinical applications ecosystem. IQVIA anchors its offering with real-world data linkages that differentiate trial execution from standalone EDC tools.
Electronic Data Capture Software comprises validated systems for collecting, managing, and reporting clinical trial data through electronic case report forms with built-in edit checks, audit trails, and role-based access controls. These platforms serve the primary purpose of replacing paper-based data collection to reduce transcription errors, accelerate database lock timelines, and enable real-time monitoring of patient safety signals. Cloud-Based deployment leads the market as sponsors prioritize scalability and reduced IT overhead for global trials spanning dozens of countries. Patient Data Management solutions represent the fastest-growing solution type as decentralized trial models require direct-to-patient data flows and wearable device integration. Contract Research Organizations constitute a concentrated demand segment as these firms standardize on multi-tenant platforms to serve diverse sponsor portfolios.
FDA 21 CFR Part 11, EU GDPR, and EMA's ICH E6(R2) Good Clinical Practice guidelines collectively shape validation requirements, data residency constraints, and risk-based monitoring protocols that determine platform architecture decisions. Health Canada's ICH E6(R3) alignment and Japan's PMDA data integrity expectations further fragment compliance obligations for global trial sponsors. Stakeholders must monitor evolving regulatory guidance on artificial intelligence in clinical data review and determine whether to build, buy, or partner for predictive analytics capabilities.
Market Dynamics
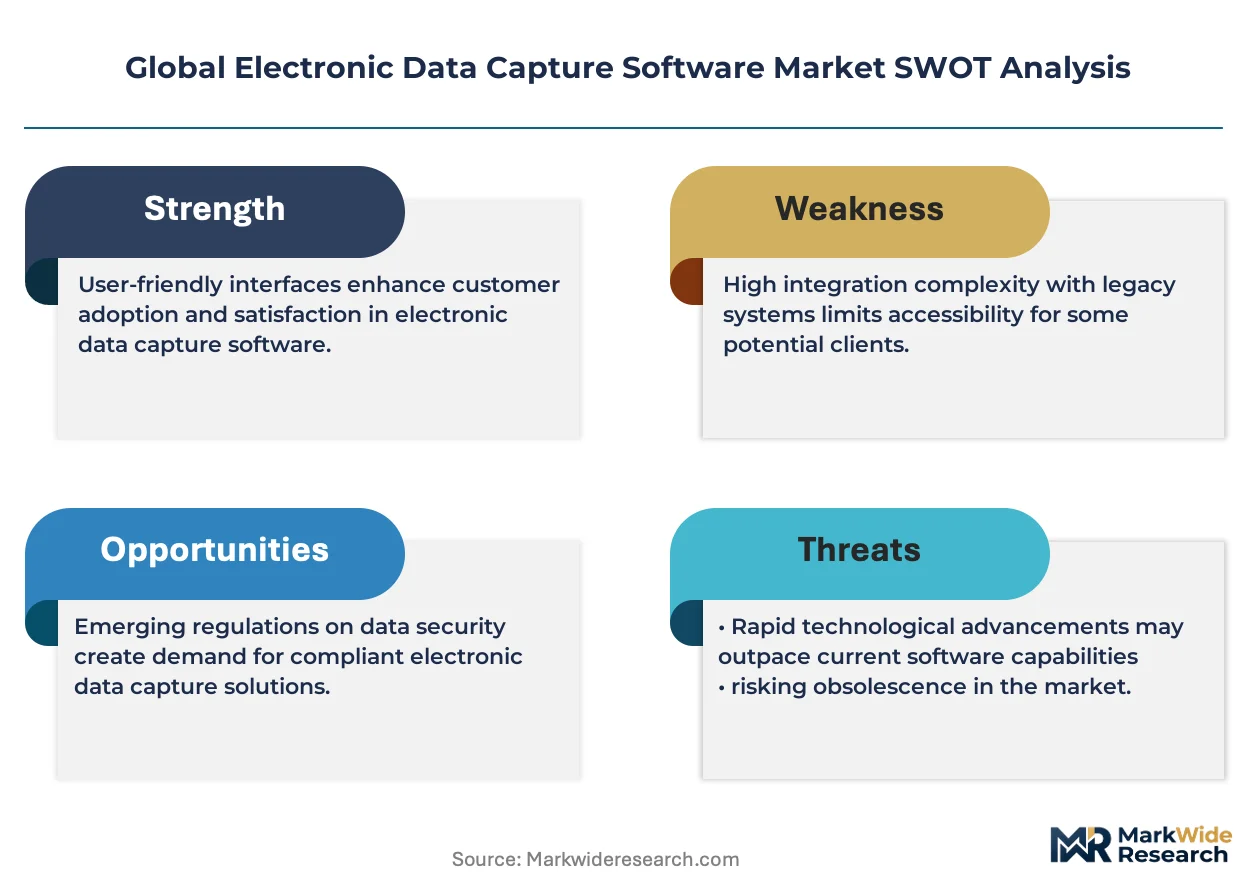
Cloud migration pressure from pharmaceutical sponsors is compressing replacement cycles for legacy on-premise EDC installations, forcing vendors to rearchitect around multi-tenant SaaS delivery and real-time data streaming capabilities.
Growth Catalysts
- FDA 21 CFR Part 11:Validation requirements for electronic records and signatures mandate audit trail capabilities that accelerate platform upgrades among US-based trial sponsors.
- Decentralized trial models:Direct-to-patient data collection through wearables and telemedicine endpoints expands addressable use cases beyond traditional site-based studies.
- Germany:Dense concentration of Phase III oncology trials drives demand for multi-site coordination tools with real-time safety monitoring.
Market Restraints
- Data residency mandates:EU GDPR and Japan's PMDA data localization requirements fragment cloud architecture decisions and inflate infrastructure costs.
- Validation timeline compression:FDA computer system validation protocols extend deployment cycles by months, delaying revenue recognition for vendors.
- Legacy system entrenchment:Large pharmaceutical sponsors maintain decade-old EDC investments with sunk-cost psychology that slows cloud migration.
Strategic Opportunities
- India:Underpenetrated clinical trial infrastructure and CDSCO regulatory modernization create first-mover advantages for cloud-native entrants.
- AI-assisted data review:Machine learning algorithms for anomaly detection and query management converge with core EDC workflows to differentiate platform offerings.
- Real-world evidence integration:Linkage between trial data and patient registries opens new revenue streams beyond traditional licensing models.
Industry Challenges
- Clinical data science talent scarcity:Shortage of professionals trained in both GCP compliance and cloud architecture limits implementation velocity.
- Interoperability friction:HL7 FHIR and CDISC standards gaps between EDC platforms and electronic health record systems require expensive custom integration work.
- Cybersecurity certification burden:SOC 2 Type II and ISO 27001 audits demand dedicated resources that strain mid-tier vendor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Electronic Data Capture Software Market |
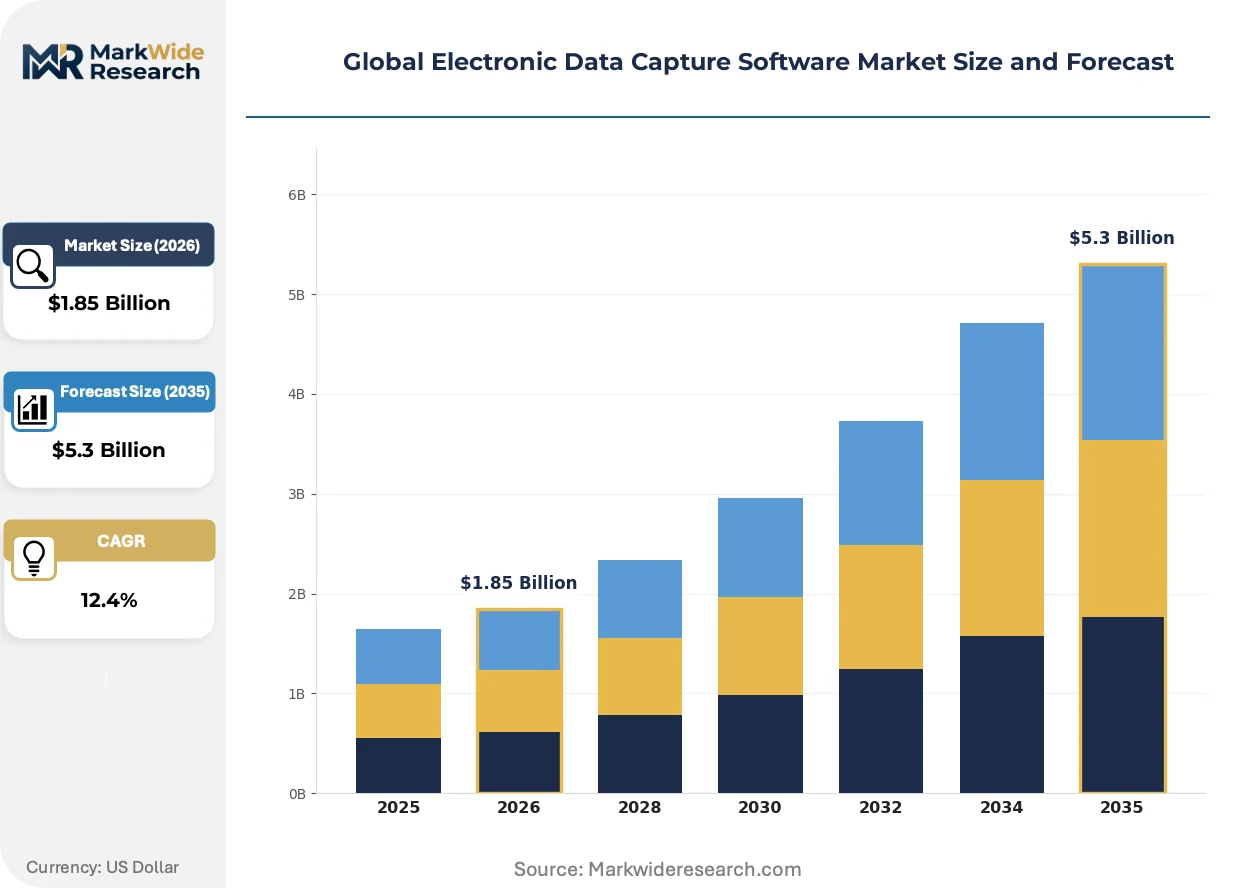
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $5.3 Billion |
| CAGR (2026 – 2036) | 12.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Web-Based, Mobile-Based Solution Type: Clinical Trial Management, Patient Data Management, Data Validation, Reporting & Analytics, Workflow Automation Application: Pharmaceutical Research, Biotechnology Studies, Medical Device Testing, Academic Research, Contract Research Organizations End User: Research Institutions, Academic Medical Centers, Clinical Laboratories, Regulatory Authorities, Data Management Companies |
| Companies Covered | Medidata Solutions, Oracle, Veeva Systems, IQVIA, IBM, Castor, OpenClinica, Medrio, DATATRAK, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Electronic Data Capture Software Market Shifts & Advancements
Artificial intelligence capabilities are absorbing into core platform architectures, reshaping how clinical data gets cleaned, monitored, and locked. Three interconnected developments are compressing traditional workflows.
Natural language processing engines are absorbing verbatim medical coding tasks previously handled by human clinical research associates. Large pharmaceutical sponsors in the United States and Switzerland are deploying these tools for adverse event narrative review, cutting query generation time by half. The technology is absorbing routine data management labor and forcing vendors to reposition around exception-handling and medical oversight services.
EMA's ICH E6(R2) and impending ICH E6(R3) alignment across EU member states mandate risk-based monitoring frameworks that privilege centralized statistical oversight over 100 percent source data verification. Contract research organizations operating across Germany, France, and Spain are reconfiguring monitoring plans to satisfy these guidelines. Oncology and rare disease trials with dispersed patient populations face the steepest compliance recalibration.
Site payment unbundling from full-service contracts is fragmenting procurement relationships between sponsors and investigative sites. Large academic medical centers in Japan and the United States are negotiating direct EDC licensing arrangements separate from CRO platform selections. This pattern concentrates negotiating leverage with high-enrolling institutions while compressing margins for multi-tenant platform providers serving mid-tier site networks.
Global Electronic Data Capture Software Market Segmentation
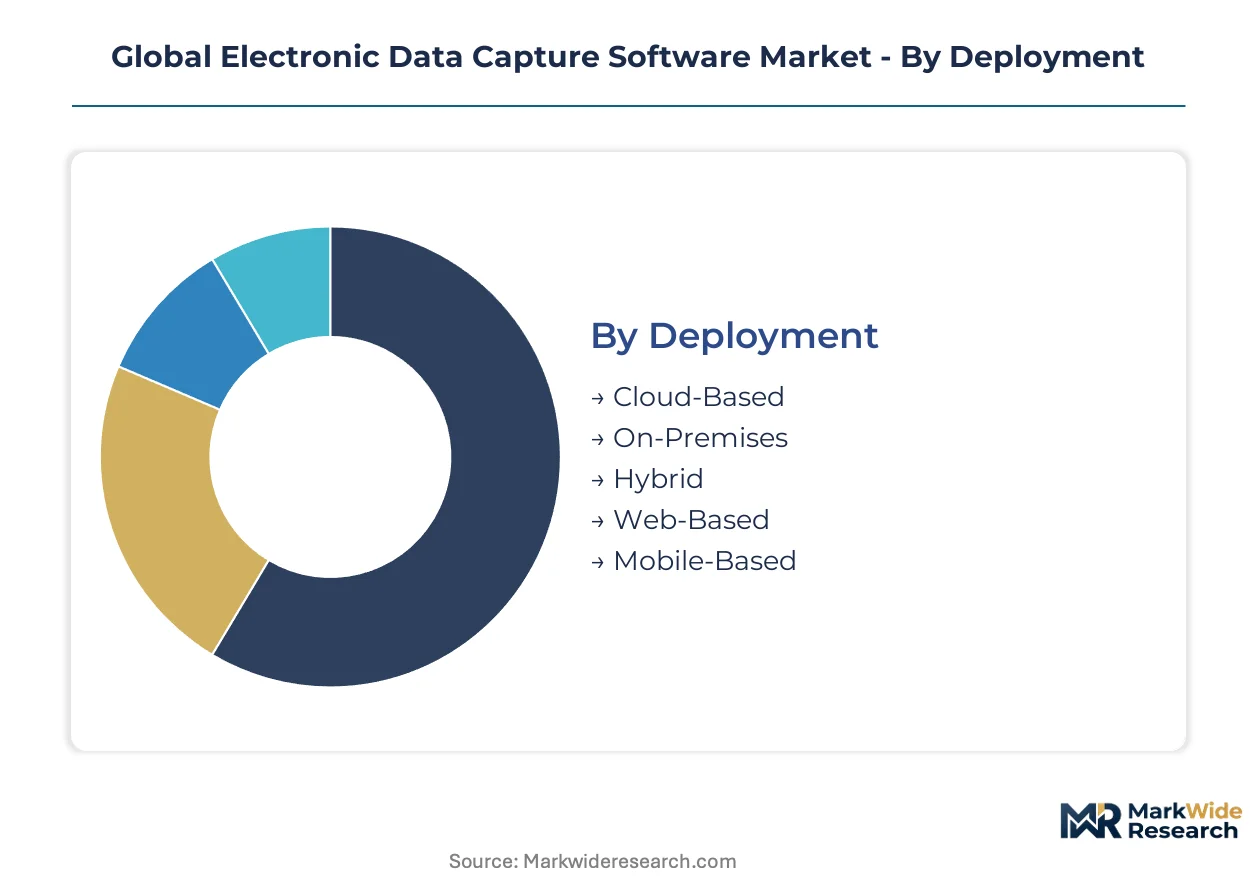
Electronic Data Capture Software segmentation reveals how deployment architectures, solution types, and end-user requirements fragment procurement decisions across the clinical trial ecosystem. Vendors must align platform configurations with specific compliance burdens, data residency constraints, and integration complexity thresholds that vary by sponsor type and study phase.
Deployment:
Customization versus standardization tension runs deepest in deployment architecture, where regulatory data residency requirements clash with multi-tenant efficiency imperatives.
- Cloud-Based:Multi-tenant SaaS architectures deliver elastic compute for global trials spanning dozens of countries. FDA 21 CFR Part 11 validation packages accelerate procurement by US-based pharmaceutical sponsors seeking reduced IT overhead.
- On-Premises:Dedicated hardware installations within sponsor data centers satisfy stringent data localization mandates from Japan's PMDA and EU GDPR jurisdiction requirements. Large pharmaceutical sponsors with decade-old investments exhibit sunk-cost psychology that slows migration timelines.
- Hybrid:Split architectures isolate protected health information on-premise while pushing anonymized analytics to cloud environments.
- Web-Based:Browser-accessible platforms with minimal client-side installation reduce site training burdens for investigator-initiated studies.
- Mobile-Based:Native applications support direct-to-patient data capture through smartphones and tablets in decentralized trial models.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Mobile-Based configurations.
Solution Type:
Cost tier stratification separates enterprise-grade integrated suites from modular point solutions targeting mid-tier sponsors.
- Clinical Trial Management:Comprehensive platforms unifying EDC, randomization, and supply chain forecasting. Contract Research Organizations operating across Germany, France, and Spain standardize on these systems to serve diverse sponsor portfolios with consistent SOP compliance.
- Patient Data Management:Direct-to-patient data flows with wearable device integration and electronic patient-reported outcomes capture. Decentralized oncology trials in the United States and Switzerland drive demand for real-time safety signal monitoring outside traditional site infrastructure.
- Data Validation:Automated edit checks and query management modules reduce manual data cleaning labor.
- Reporting & Analytics:Regulatory submission-ready outputs aligned with CDISC standards for FDA and EMA filings.
- Workflow Automation:Rules-based task routing and milestone tracking for study startup and monitoring workflows.
Clinical Trial Management absorbs the largest share of enterprise licensing spend. Patient Data Management is climbing the fastest as decentralized protocols proliferate.
Application:
Application segmentation tracks volume concentration in Phase III-heavy therapeutic areas against emerging demand from device and academic sponsors.
- Pharmaceutical Research:Large-scale interventional studies requiring multi-site coordination and real-time safety databases. Dense Phase III oncology trial concentrations in Germany and the United States drive platform requirements for complex adjudication workflows.
- Biotechnology Studies:Gene therapy and rare disease protocols with dispersed patient populations and specialized biomarker collection needs.
- Medical Device Testing:EU MDR compliance pressure hardens audit trail and source-data verification requirements across post-market surveillance studies.
- Academic Research:Investigator-initiated trials with constrained budgets and limited data management staffing.
- Contract Research Organizations:Multi-tenant platform standardization to serve diverse sponsor portfolios with configurable study templates.
Pharmaceutical Research commands the dominant share of platform revenue. Medical Device Testing is gaining share fastest under EU MDR compliance pressure.
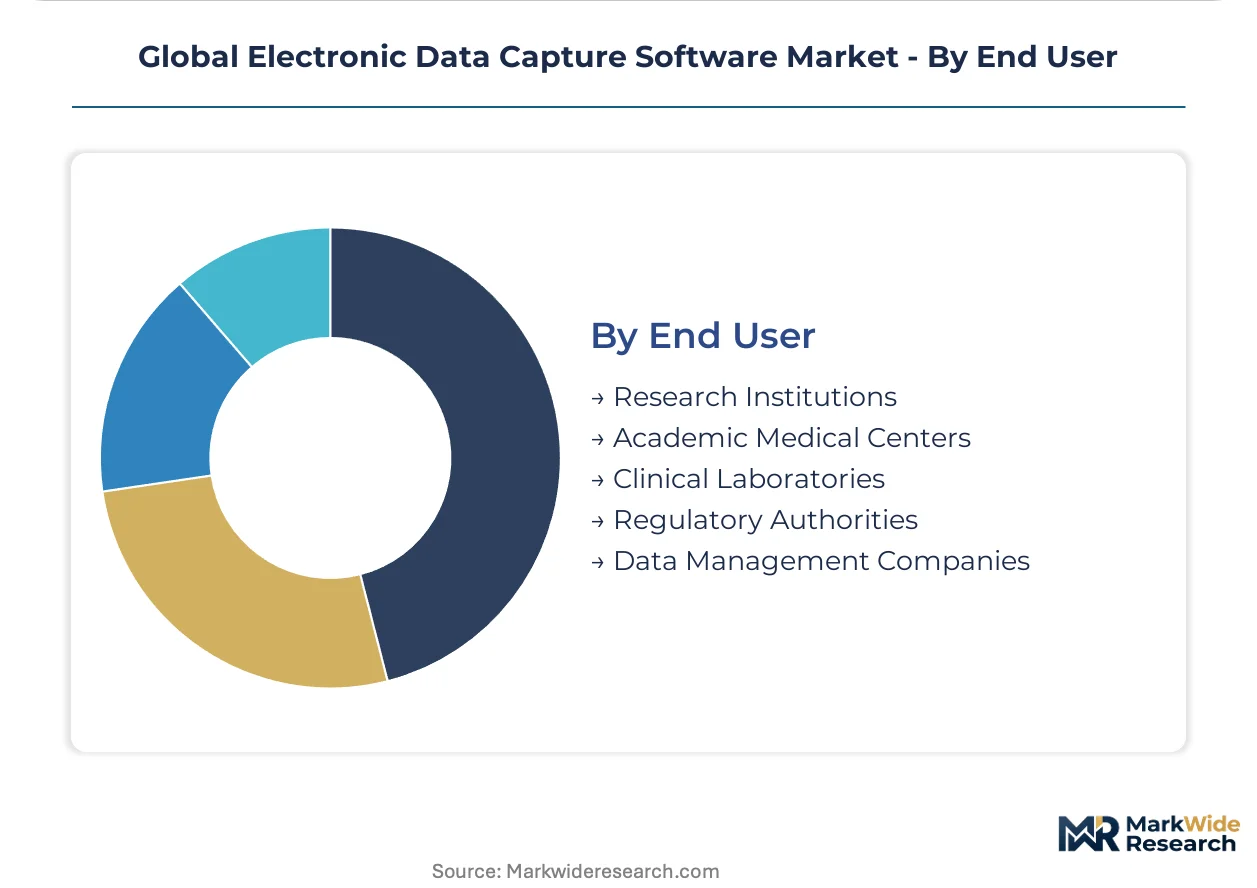
End User:
Customer type segmentation distinguishes between sponsors with direct platform control and intermediaries managing outsourced trial execution.
- Research Institutions:Independent academic and government research centers conducting investigator-initiated studies. Site payment unbundling trends concentrate negotiating leverage with high-enrolling academic medical centers in Japan and the United States.
- Academic Medical Centers:University-affiliated hospitals with dual roles as trial sites and occasional sponsors. These institutions increasingly negotiate direct EDC licensing arrangements separate from CRO platform selections.
- Clinical Laboratories:Central labs processing biomarker and pharmacokinetic samples requiring direct data integration with EDC platforms.
- Regulatory Authorities:Government agencies leveraging EDC systems for post-market surveillance and inspector training programs.
- Data Management Companies:Specialized service providers offering outsourced clinical data operations and biostatistics support.
Research Institutions represent the largest installed base. Academic Medical Centers are expanding most quickly as site unbundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States pioneered electronic data capture systems during the 1990s FDA digitalization push, establishing the regulatory and technical foundations that now define global platform standards.
United States
FDA 21 CFR Part 11 validation requirements and dense Phase III oncology trial concentrations drive enterprise platform procurement. Boston and San Francisco biotech clusters anchor demand for cloud-native architectures with real-time safety monitoring capabilities.
Germany
EU MDR compliance pressure and concentrated medical device trial activity harden audit trail requirements across sponsor organizations. Munich and Heidelberg pharmaceutical research hubs standardize on multi-tenant platforms for cross-border study coordination.
Japan
PMDA data integrity expectations and localization mandates sustain hybrid deployment preferences among domestic sponsors. Tokyo academic medical centers negotiate direct EDC licensing arrangements separate from CRO platform selections.
India
CDSCO regulatory modernization and underpenetrated clinical trial infrastructure create first-mover opportunities for cloud-native entrants. Hyderabad and Bangalore CRO clusters expand multi-tenant standardization to serve global sponsor portfolios.
Switzerland
Swissmedic alignment with ICH E6(R3) guidelines and concentrated gene therapy trial activity demand specialized biomarker data workflows. Basel pharmaceutical research sponsors deploy NLP-enabled coding engines for adverse event narrative review.
Global Electronic Data Capture Software Market Competitive Landscape
Premium-margin players sit above commodity-margin players across validation depth and integration breadth. The vendor base stratifies into three tiers: cloud-native specialists commanding enterprise oncology contracts, legacy platform vendors defending installed bases through ecosystem bundling, and open-source alternatives capturing academic and mid-tier sponsor segments. Consolidation pressure intensifies as FDA validation timelines compress and multi-tenant architecture becomes table stakes.
Within the cloud-native tier, Medidata Solutions and Veeva Systems exemplify architecture-first positioning that displaces legacy installations. Oracle occupies a position bridging enterprise software ecosystems with clinical applications. IQVIA anchors the real-world data convergence archetype, linking trial execution with patient registries.
| Leading Market Players |
|---|
| Medidata Solutions |
| Oracle |
| Veeva Systems |
| IQVIA |
| IBM |
| Castor |
| OpenClinica |
| Medrio |
| DATATRAK |
| Others |
Supply & Pricing Matrix
Multi-tenant SaaS architecture migration compresses infrastructure cost curves while concentrating platform development among vendors with FDA 21 CFR Part 11 validation capabilities. This shift simultaneously elevates switching costs for enterprise sponsors and fragments pricing power across deployment tiers.
Pricing Analysis
Subscription-based tiering across enterprise, mid-market, and investigator-initiated levels dominates procurement structures. Price differentiation hinges on validation depth against FDA 21 CFR Part 11 and EU GDPR compliance tiers, plus integration breadth with clinical trial management systems. Cost compression in mid-market tiers intensifies as open-source alternatives capture academic sponsors. Contract research organizations exhibit highest price sensitivity due to multi-tenant standardization pressures, while large pharmaceutical sponsors prioritize validation assurance over unit economics.
Supply Chain Analysis
Cloud infrastructure supply rests on hyperscale data center operators concentrated in the United States, Ireland, and Singapore. Software development draws from specialized clinical data science talent pools in India and Eastern Europe, while validation consulting services cluster in the United States and Germany. Single-source vulnerability runs through AWS and Azure dominance in healthcare-compliant regions. Distribution runs through direct enterprise sales teams for large sponsors and channel partnerships with contract research organizations for mid-tier penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electronic data capture software represents a late-cycle quality story as FDA validation requirements harden and sponsor procurement shifts toward integrated platforms with real-world evidence linkages.
For Market Incumbents: Extend platform stickiness through deeper integration with randomization and supply chain forecasting modules. Invest in AI-assisted data review capabilities to differentiate against emerging cloud-native entrants. Prioritize certification investment for EMA ICH E6(R3) alignment ahead of guideline finalization. Channel control through exclusive CRO partnerships defends against site payment unbundling trends concentrating leverage with academic medical centers. For New Entrants and Emerging Players: Investigator-initiated trial sponsors at academic medical centers in Japan and the United States present underserved demand with constrained procurement sophistication. India's CDSCO regulatory modernization creates whitespace for cloud-native platforms without legacy validation debt. Direct-to-patient data management modules offer the most penetrable entry vector as decentralized trial models proliferate. Go-to-market through specialized CRO partnerships serving mid-tier biotechnology sponsors bypasses direct competition with entrenched enterprise platforms. For Investors and Strategic Acquirers: Roll-up economics work for regional validation specialists because FDA timeline compression favors acquirers with established quality management systems over de novo platform builds. Long-term viability centers on convergence with real-world data assets and AI-enabled monitoring workflows. Acquisition targets should demonstrate installed base concentration in Phase III oncology or rare disease protocols with complex adjudication requirements. Watch CDSCO enforcement consistency and ICH E6(R3) adoption velocity as inflection indicators for emerging market expansion viability.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unification of EDC with randomization and supply forecasting tightens sponsor switching costs. |
| AI-Assisted Data Review | Machine learning for anomaly detection differentiates offerings as NLP engines absorb routine coding tasks. |
| Regulatory Certification Investment | Early EMA ICH E6(R3) alignment captures European sponsor procurement ahead of guideline enforcement. |
| Real-World Evidence Linkage | Integration with patient registries opens revenue streams beyond traditional per-study licensing. |
| Geographic Expansion | India's CDSCO modernization creates first-mover advantages for cloud-native validation packages. |
Research Methodology
Direct dialogue with clinical data management executives, regulatory affairs leads at pharmaceutical sponsors, contract research organization procurement officers, and FDA compliance consultants grounded qualitative findings. Secondary validation drew from FDA 21 CFR Part 11 guidance documents, EMA ICH E6(R2) and draft ICH E6(R3) texts, ClinicalTrials.gov protocol registries, and CDSCO regulatory circulars. Bottom-up and top-down triangulation cross-checked segment-level demand against aggregate market sizing.
Bottom-up modeling built from sponsor-reported trial volumes, CRO platform standardization trends, and deployment architecture shifts across cloud, on-premise, and hybrid configurations. Segmentation dimensions included deployment model, solution type, sponsor tier by trial phase concentration, and regional regulatory cluster. CAGRs were derived from regression against historical replacement cycle compression and cloud migration penetration curves. Forecast inputs incorporated decentralized trial adoption rates and AI capability absorption timelines.
Underlying measurement precision varies by segment; cloud-based deployment and pharmaceutical research applications carry tighter precision than emerging mobile-based configurations and academic research adoption. Forecasts reflect assumptions regarding regulatory timeline stability and sponsor IT modernization budgets. Specific risks that could revise projections include PMDA data localization mandate expansion, ICH E6(R3) delay or scope reduction, and cybersecurity certification burden escalation for mid-tier vendors. A small set of triggers—CDSCO enforcement actions, EMA guideline finalization timing, and large sponsor cloud migration acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Audience Response Software Market
Software & Services
Global Screen and Script Writing Software Market
Software & Services
Mobile Enterprise Application Development Platform Market
Software & Services
Global Personalisation Software Market
Software & Services
Global IVR Software Market
Software & Services
Middle East and Africa Digital Signage Software Market
Software & Services
Digital Onboarding Platform Market
Software & Services
Enterprise Mobility Software Market
Software & Services
Global Online Expense Management Software Market
Software & Services
Social Software As a Collaborative ERP Tool Market
Software & Services
Global Java Web Frameworks Software Market
Software & Services
Customer Revenue Optimization Software Market
Software & Services
Equipment Management Software Market
Software & Services
Human Resource Management Software Market
Software & Services
Cloud Testing and ASQ Software Market
Software & Services
Global Note Taking App Market