
 Global Data Governance Software Market | 2026-2036
Global Data Governance Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Data Governance Software Market Foresight
Cloud-native architectures are restructuring procurement economics for data governance platforms, displacing legacy on-premises licensing with consumption-based SaaS models. Collibra leverages embedded AI agents to automate metadata discovery across hybrid environments. Alation anchors its position through behavioral analysis engines that map actual data usage patterns. Informatica sustains R&D intensity in data quality pipelines, competing on integration depth with enterprise data lakes.
Data governance software encompasses policy-driven frameworks for data stewardship, quality assurance, and regulatory compliance, typically deployed through metadata repositories, business glossaries, and automated lineage tracking engines with API-first architectures. Its primary commercial purpose is to reduce regulatory exposure while accelerating trusted data access for analytics and AI workloads. Cloud deployment leads solution type adoption as enterprises abandon capital-intensive infrastructure, while data security management captures expanding margin pools from zero-trust mandates. Policy management segments are maturing fastest in BFSI end-user industries where Basel III and DORA obligations compound.
The US SEC, EU GDPR enforcement networks, and Japan's METI data governance guidelines are tightening cross-border data handling standards, forcing vendors to embed jurisdictional policy engines directly into platform cores. HIPAA and the EU AI Act further fragment certification requirements, raising barriers for single-tenant architectures. Stakeholders must monitor how sovereign cloud mandates in Germany, France, and India reshape deployment topology decisions before committing to regional expansion.
Market Dynamics
Automated policy enforcement engines are restructuring vendor economics as financial institutions replace manual compliance workflows with embedded AI governance agents. This shift compresses implementation timelines while elevating platform switching costs.
Growth Catalysts
- EU AI Act compliance mandates:Multinational enterprises must embed data lineage tracking into AI development pipelines, forcing procurement of automated governance platforms.
- Healthcare cloud migration:HIPAA-covered entities in the United States are deploying SaaS-native governance tools to manage protected health information across hybrid architectures.
- Behavioral analytics engines:Banking sector adoption of usage-pattern mapping accelerates metadata discovery without manual cataloging overhead.
Market Restraints
- Specialized talent scarcity:Shortage of data stewards fluent in both regulatory frameworks and API-first platform architecture limits enterprise rollout velocity.
- Jurisdictional fragmentation:Conflicting sovereignty requirements between Germany's Gaia-X mandates and India's data localization rules complicate single-tenant deployment strategies.
- Legacy integration friction:Mainframe data repositories in established financial institutions resist seamless API connectivity, extending implementation cycles.
Strategic Opportunities
- India's digital public infrastructure:Unified Payments Interface data streams and Aadhaar-linked health records create demand for scalable governance frameworks in emerging fintech clusters.
- Zero-trust security convergence:Integration of data access governance with identity-centric security architectures opens cross-sell opportunities in regulated industries.
- Sovereign cloud mandates:France's SecNumCloud certification and Germany's C5 standards are creating certified-deployment service layers around core platform licenses.
Industry Challenges
- Cross-border certification complexity:Simultaneous HIPAA, GDPR, and EU AI Act audits require platform vendors to maintain parallel compliance documentation.
- Metadata quality at scale:Automated discovery tools generate false-positive classification errors that demand human verification, inflating operational overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Data Governance Software Market |
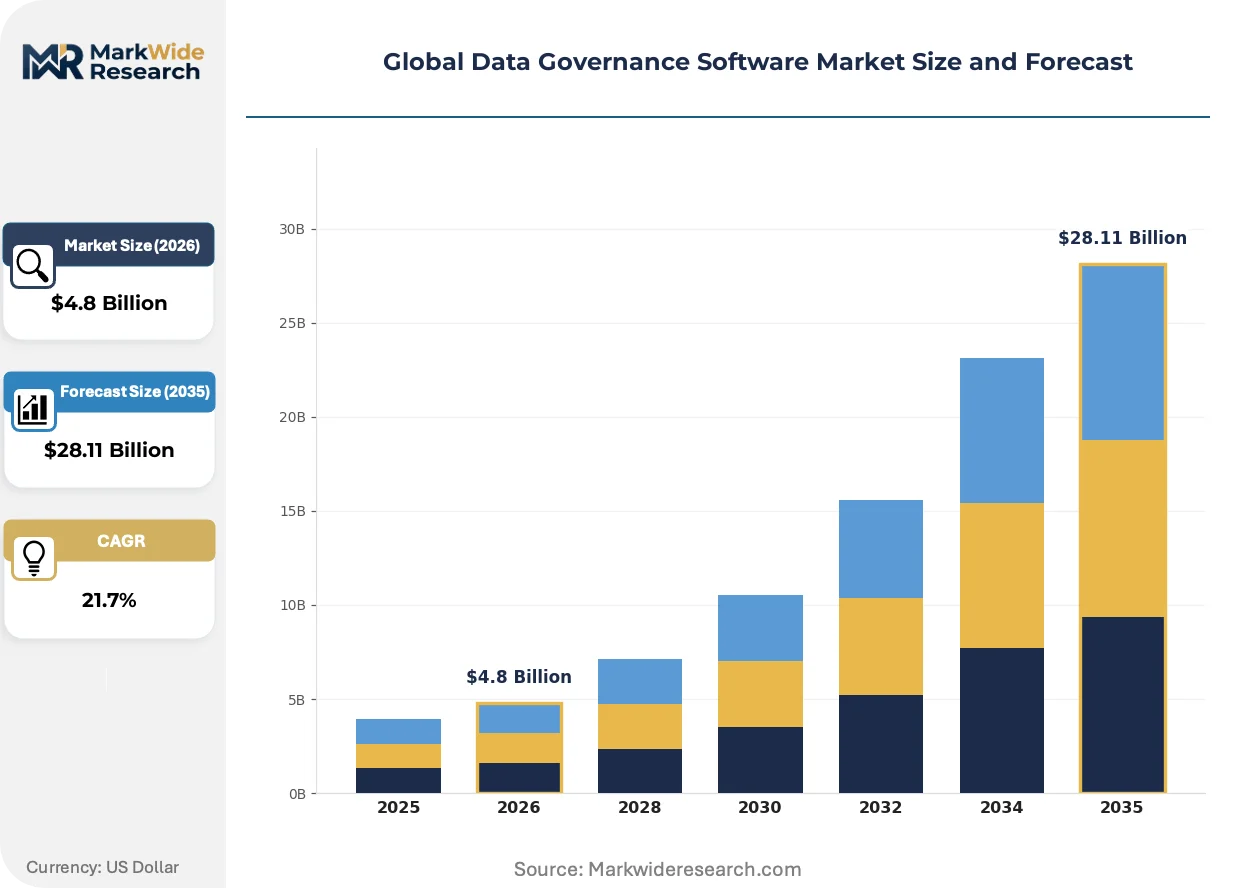
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $28.11 Billion |
| CAGR (2026 – 2036) | 21.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud, On-premises, Hybrid, Multi-cloud Solution Type: Data Quality Management, Metadata Management, Master Data Management, Data Security Management, Policy Management Application: Regulatory Compliance, Risk Management, Data Privacy, Operational Efficiency, Data Lifecycle Management End User Industry: BFSI, Telecommunications, Manufacturing, Government, Education |
| Companies Covered | Collibra, Alation, Informatica, IBM, SAP SE, Oracle Corporation, Microsoft Corporation, Ataccama, Databricks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Data Governance Software Market Shifts & Advancements
Embedded AI agents are redefining how metadata repositories populate themselves, shifting value capture from manual cataloging services toward autonomous discovery subscriptions.
Federated data governance architectures are decentralizing control plane functions across edge deployments. Manufacturing enterprises with distributed operational technology networks are piloting these frameworks to maintain local policy enforcement without centralized bottlenecks. This topology is compressing latency for real-time compliance decisions while fragmenting vendor revenue into modular component licenses.
Japan's METI data governance guidelines are mandating explainable AI documentation for cross-sector data sharing consortia. Industrial consequence includes mandatory provenance logging for training datasets used in collaborative machine learning projects. Automotive and electronics manufacturers are responding by embedding lineage capture at the data ingestion layer rather than retrofitting post-hoc.
Subscription consumption models are displacing perpetual licenses in enterprise procurement cycles. Healthcare systems in the United States now prioritize usage-based pricing that scales with active metadata assets rather than fixed user counts. This rotation pressures incumbent vendors to restructure revenue recognition while creating entry points for cloud-native competitors in mid-market hospital networks.
Global Data Governance Software Market Segmentation
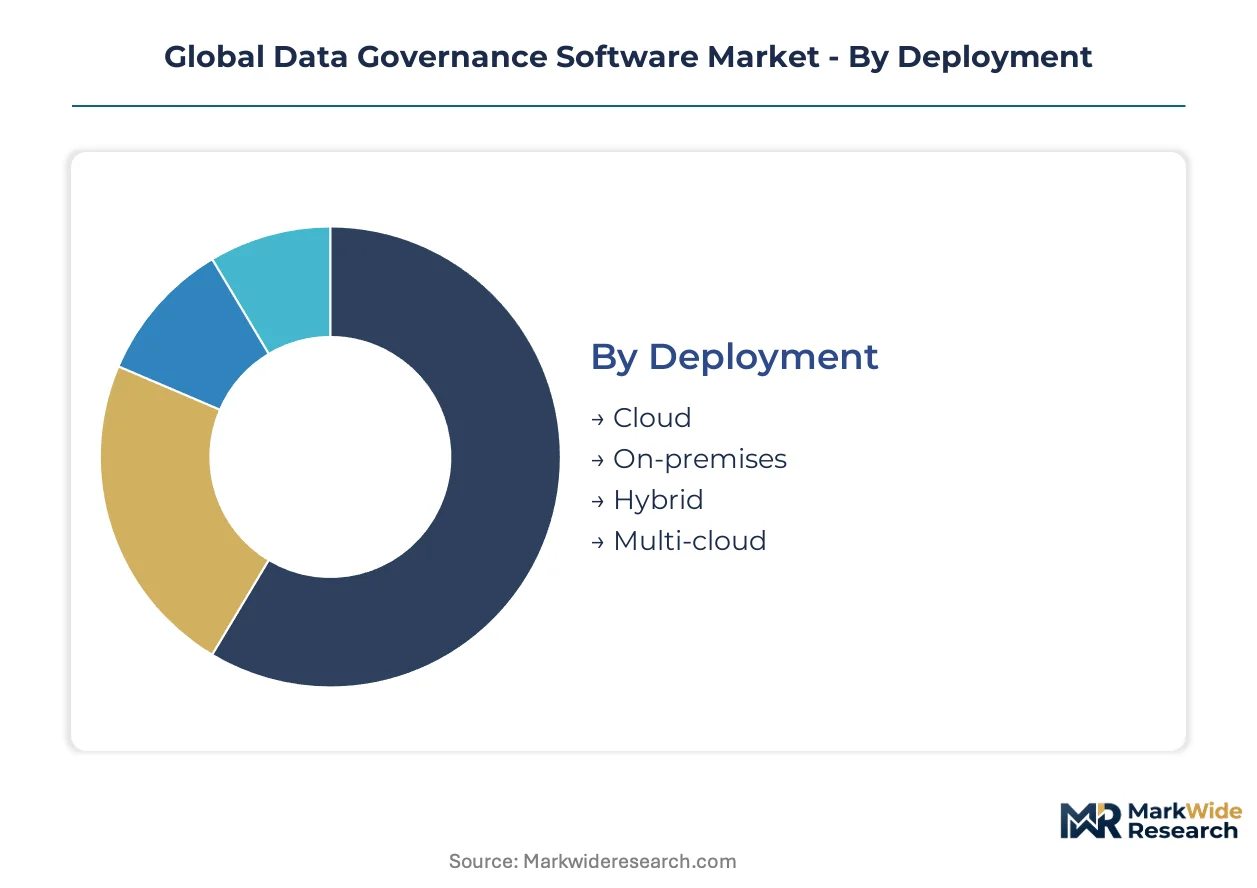
Segmentation in data governance software reveals how procurement economics, compliance architectures, and operational workloads fragment across deployment topologies and functional modules. Vendors must align licensing models with these structural divides to capture margin pools.
Deployment:
Capital intensity varies sharply across deployment modes, with multi-cloud configurations demanding the highest upfront integration investment while cloud-native SaaS minimizes infrastructure commitment.
- Cloud:SaaS-native platforms eliminate data center provisioning and shift governance infrastructure to consumption-based operational expenditure. Healthcare systems in the United States prioritize this model to accelerate HIPAA-compliant analytics deployment without capital approval cycles.
- On-premises:Self-managed deployments retain control over sensitive metadata repositories through dedicated hardware stacks. Established financial institutions in Germany maintain these configurations to satisfy Bundesbank operational resilience mandates and local audit requirements.
- Hybrid:Split architectures synchronize policy enforcement across cloud and legacy data centers through API bridges. Manufacturing enterprises with distributed operational technology networks deploy hybrid stacks to preserve local latency for real-time compliance decisions.
- Multi-cloud:Orchestration layers distribute governance workloads across AWS, Azure, and Google Cloud environments simultaneously. This topology demands specialized engineering talent and redundant policy synchronization engines.
Most installed capacity flows through Cloud deployments. Expansion is steepest in Multi-cloud configurations as enterprises resist vendor lock-in.
Solution Type:
Functional modules stratify by margin structure, with data security management commanding premium pricing from zero-trust mandates while policy management commoditizes through template standardization.
- Data Quality Management:Automated profiling engines detect schema drift and anomalous value distributions across pipeline stages. BFSI institutions in Japan deploy these tools under METI guidelines to ensure explainable AI training dataset integrity.
- Metadata Management:Business glossaries and technical catalogs create unified semantic layers across disparate data stores. Behavioral analytics engines from specialized vendors accelerate adoption by mapping actual query patterns rather than static documentation.
- Master Data Management:Golden record consolidation harmonizes customer, product, and supplier identifiers across ERP silos. Consumer goods manufacturers leverage MDM to synchronize pricing and inventory data across regional subsidiaries.
- Data Security Management:Access control matrices and encryption policy engines embed directly into data lakes and warehouses. Zero-trust architectures in United States federal agencies drive procurement of attribute-based access control modules.
- Policy Management:Workflow engines automate stewardship assignments and regulatory documentation. Template libraries from industry consortia are compressing differentiation in this segment.
Revenue concentrates in Data Security Management modules. Metadata Management is gaining share fastest as AI governance mandates proliferate.
Application:
Use case prioritization follows regulatory enforcement intensity, with risk management and data privacy absorbing discretionary budget while operational efficiency competes for shared services funding.
- Regulatory Compliance:Automated audit trails and lineage documentation satisfy GDPR, HIPAA, and EU AI Act evidence requirements. Multinational enterprises in France allocate dedicated budget to SecNumCloud-certified compliance modules.
- Risk Management:Data quality scoring and anomaly detection feed into enterprise risk frameworks. Basel III operational risk calculations in European banking drive integration with internal audit systems.
- Data Privacy:Consent management and right-to-erasure workflows automate subject access request fulfillment. India's emerging data protection authority mandates are stimulating demand among fintech clusters processing Aadhaar-linked records.
- Operational Efficiency:Self-service data discovery reduces time-to-insight for business analysts. Mid-market manufacturers deploy lightweight cataloging to bypass IT bottlenecks without full governance transformation.
- Data Lifecycle Management:Retention policy automation and archival tiering optimize storage economics. Healthcare providers in the United States apply these tools to manage imaging data explosion under HIPAA retention schedules.
Budget allocation peaks for Regulatory Compliance applications. Data Privacy workflows are expanding most quickly as enforcement mechanisms mature across jurisdictions.
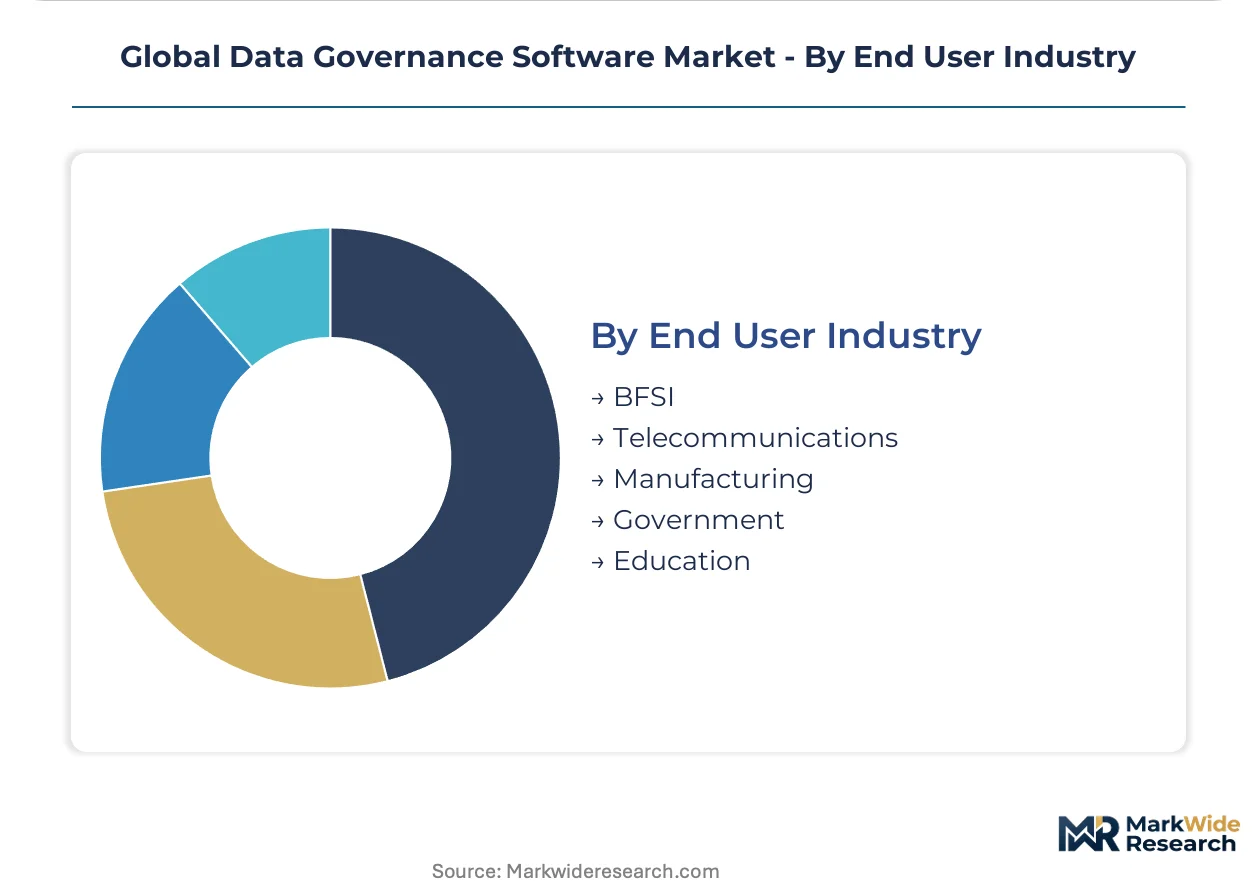
End User Industry:
Industry verticals diverge by procurement sophistication, with BFSI demanding enterprise-grade lineage capabilities while education segments prioritize cost-minimized cataloging.
- BFSI:Trading book data governance and anti-money laundering lineage requirements demand sub-second metadata propagation. DORA compliance deadlines in the European Union are accelerating replacement of legacy spreadsheet-based stewardship.
- Telecommunications:Subscriber data management and lawful intercept compliance require geofenced policy enforcement. Indian operators processing Unified Payments Interface transaction streams deploy governance layers to satisfy RBI data localization directives.
- Manufacturing:Industrial IoT sensor governance and supply chain provenance tracking embed at the edge. Automotive manufacturers in Japan implement METI-mandated explainable AI documentation for collaborative machine learning consortia.
- Government:Classified and unclassified data segregation demands certified deployment topologies. United States federal agencies prioritize FedRAMP-authorized SaaS platforms for open data initiatives.
- Education:Student information system governance and research data management operate under constrained central IT budgets. Regional university systems in the United States favor open-source metadata frameworks with commercial support overlays.
Revenue concentration sits with BFSI procurement. Manufacturing is climbing the fastest as operational technology convergence creates new governance surface area.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's cloud-native enterprises are driving procurement velocity for SaaS governance platforms as HIPAA-covered health systems and Basel III banks accelerate replacement of legacy stewardship tools.
United States
Healthcare cloud migration and zero-trust federal mandates dominate demand. HIPAA enforcement by the Office for Civil Rights pushes hospital networks toward automated data lineage. The Boston-Cambridge health tech cluster anchors deployment of AI governance agents for clinical trial documentation.
Germany
Established financial institutions maintain on-premises metadata repositories to satisfy Bundesbank operational resilience requirements. Gaia-X sovereignty mandates force vendors to embed jurisdictional policy engines. Frankfurt's banking district leads DORA compliance procurement for trading book lineage.
India
Unified Payments Interface data streams and Aadhaar-linked health records create governance demand in emerging fintech clusters. RBI data localization directives compel geofenced policy enforcement. Mumbai and Bangalore anchor deployment of scalable frameworks for digital public infrastructure.
Japan
Automotive and electronics manufacturers implement METI-mandated explainable AI documentation for collaborative machine learning consortia. Industrial IoT sensor governance embeds at the edge. Nagoya's automotive cluster leads provenance logging for training datasets in supplier networks.
France
SecNumCloud certification creates certified-deployment service layers around core platform licenses. Multinational enterprises allocate dedicated budget to compliance modules satisfying GDPR and EU AI Act evidence requirements. Paris anchors procurement of sovereign cloud governance for cross-border data handling.
Global Data Governance Software Market Competitive Landscape
Global majors compete with regional champions across deployment topology and compliance certification depth. Market structure tilts toward consolidated platform vendors with embedded AI agents, though specialized metadata discovery firms retain niche positions. Three archetypes dominate: cloud-native SaaS specialists, legacy enterprise software incumbents with governance modules, and AI-first metadata automation vendors. Competitive moves concentrate on strategic partnerships with hyperscale cloud providers and vertical integration into sovereign cloud certification services.
Within the cloud-native tier, Collibra and Alation exemplify divergent automation strategies, while Informatica occupies a position bridging legacy integration depth with modern API-first architectures. These three anchors represent how vendor economics restructure around autonomous discovery subscriptions versus manual cataloging services. Each sits within a distinct value-capture model: embedded AI agents, behavioral analytics engines, or data quality pipeline intensity.
| Leading Market Players |
|---|
| Collibra |
| Alation |
| Informatica |
| IBM |
| SAP SE |
| Oracle Corporation |
| Microsoft Corporation |
| Ataccama |
| Databricks |
| Others |
Supply & Pricing Matrix
EU AI Act documentation mandates gate both qualified supply and premium-tier pricing access for data governance platforms, forcing vendors to embed jurisdictional compliance engines before capturing enterprise contracts. SaaS-native architectures compress delivery costs while sovereign cloud certification layers inflate service premiums for regulated buyers.
Pricing Analysis
Input-cost pass-through from embedded AI development and compliance certification labor shapes subscription economics across deployment tiers. Three-tier pricing structure across premium, standard, and economy levels separates FedRAMP-authorized sovereign cloud deployments from multi-tenant SaaS and open-source core editions. Cost compression in standard tiers is intensifying because hyperscaler marketplace listings commoditize baseline metadata management. Mid-market healthcare systems exhibit highest price sensitivity; Basel III banks and DORA-mandated EU financial institutions show lowest.
Supply Chain Analysis
Dual-sourcing requirements from United States federal agencies and EU critical infrastructure operators mandate multi-supplier qualification for policy engine components. Software development concentrates in the United States, India, and Germany; cloud infrastructure draws from AWS, Azure, and Google Cloud regions simultaneously. Supply chain risk centers on single-source vulnerability for specialized AI governance agents trained on proprietary compliance corpora. Distribution runs through hyperscaler marketplaces and direct enterprise field sales with certified implementation partners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
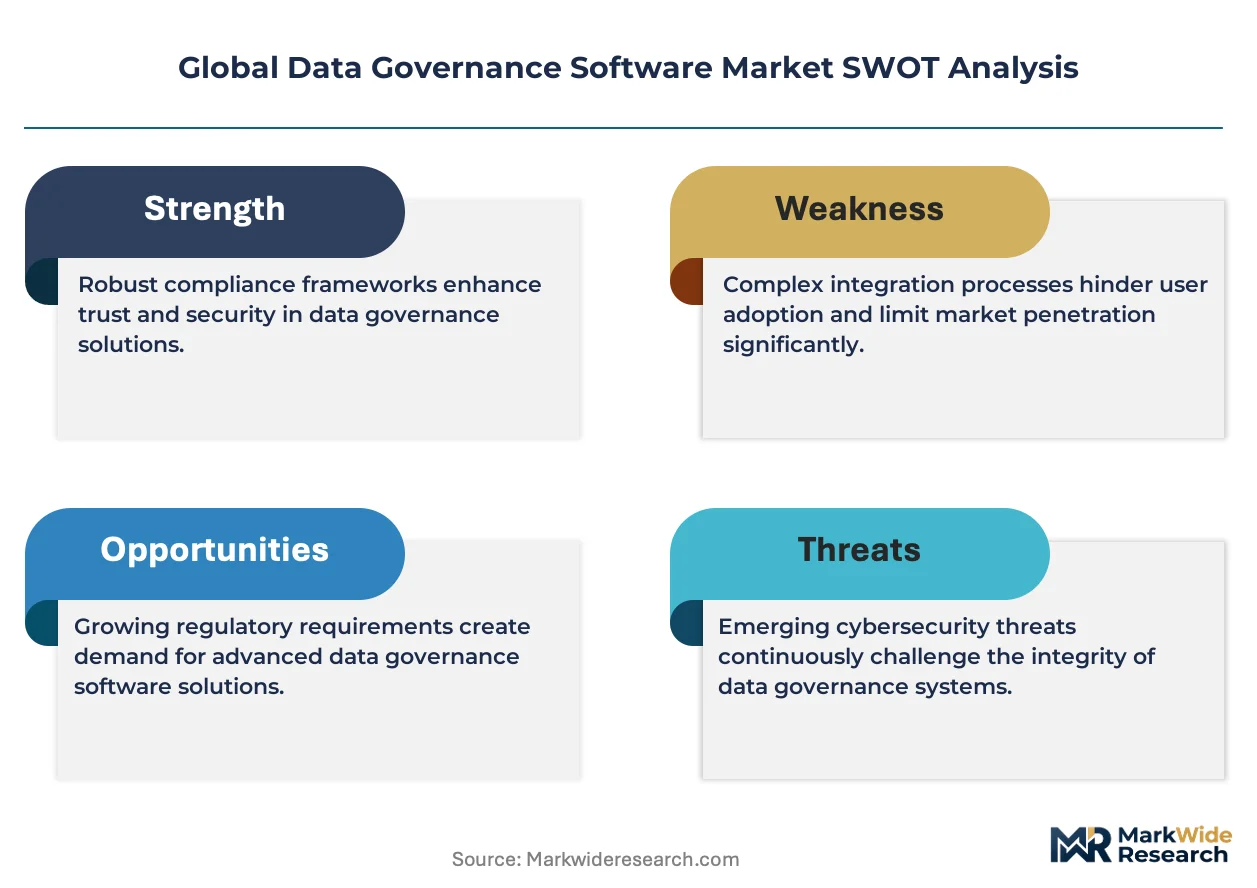
This market reads as a late-cycle quality story as procurement shifts toward EU AI Act-compliant lineage capabilities that command pricing premiums over basic cataloging tools.
For Market Incumbents: Acquire behavioral analytics engines to close gaps against Alation's usage-pattern mapping and defend against cloud-native entrants. Invest in SecNumCloud and FedRAMP certification pipelines to maintain access to sovereign cloud premiums. Consolidate channel control through exclusive partnerships with systems integrators specializing in DORA and HIPAA implementations.
For New Entrants and Emerging Players: Hyperscaler marketplace listings offer the fastest path to procurement visibility without dedicated field sales. Target India's emerging fintech clusters processing UPI and Aadhaar-linked records where incumbent presence remains thin. Position around API-first metadata discovery for manufacturing operational technology networks seeking edge-deployed governance.
For Investors and Strategic Acquirers: Roll-up economics work for specialized metadata automation vendors because platform consolidation accelerates AI agent training data accumulation and compliance corpus breadth. Five-to-ten year viability hinges on embedded policy engine differentiation rather than cataloging interface layers. Watch for hyperscaler native governance tool launches as the inflection signal compressing standalone vendor pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedded AI agents from Collibra automate metadata discovery across hybrid AWS-Azure-Google Cloud environments. |
| Strategic Partnership | Certified deployment partnerships with Atos and Capgemini unlock SecNumCloud sovereign cloud revenue layers in France. |
| Acquisition of Specialist Firm | Behavioral analytics engines map actual query patterns rather than static documentation, accelerating Alation's differentiation. |
| Geographic Expansion | Mumbai and Bangalore deployment centers capture UPI and Aadhaar-linked health record governance demand from Indian fintech clusters. |
| Product Launch | Federated governance architectures decentralize control planes across manufacturing edge networks for real-time compliance decisions. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with CTOs, IT procurement officers, platform engineers, and integration specialists alongside secondary validation from SEC filings, hyperscaler capex disclosures, App Annie enterprise software rankings, and EU regulatory implementation guidance. Bottom-up deployment counts by organization size and vertical triangulate against top-down vendor revenue segmentation.
Rate-of-change decomposition separates baseline SaaS subscription growth from AI governance premium attach rates and sovereign cloud certification service layers across the projection horizon. Segmentation dimensions modeled include deployment topology, solution type functional module, end-user industry vertical, and regional regulatory framework cluster. CAGRs derive from fitted adoption curves calibrated to DORA and EU AI Act enforcement timelines.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to hyperscaler native tool launches and sovereign cloud mandate fragmentation. Deviation in EU AI Act audit intensity or FedRAMP authorization timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Global Electrical Computer-Aided Design (ECAD) Market
Software & Services
Estate Management Software Market
Software & Services
Global Job Evaluation Software Market
Software & Services
Global Online Form Builder Software Market
Software & Services
Asia-Pacific ERP Software Market
Software & Services
Curriculum Mapping Software Market
Software & Services
France Digital Marketing Software Market
Software & Services
Data Integration Software/Tool Market
Software & Services
Global Recipe Apps Market
Software & Services
Product Analytics Software Market
Software & Services
Global Retail Management Systems Software Market
Software & Services
Labor Management Software Market
Software & Services
Library Management Software Market
Software & Services
Supplier Relationship Management Software Market
Software & Services
Compositing Software Market
Software & Services
Sales Platforms Software Market