
 Europe Public Safety Market | 2026-2036
Europe Public Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Public Safety Market Insights
Market Context
CE marking under the EU Radio Equipment Directive is bifurcating the vendor landscape into qualified integrators and peripheral equipment suppliers. Motorola Solutions Inc leverages its TETRA infrastructure installed base to sustain recurring service revenue across British emergency services networks. Thales Group anchors its position through cryptographic security modules that meet French ANSSI certification tiers for national defense-adjacent public safety contracts. Hexagon AB competes on real-time geospatial fusion platforms that dominate Nordic municipal dispatch centers.
Technical Definition and Segment Structure
Europe public safety encompasses integrated systems for threat detection, emergency coordination, and critical incident response, typically incorporating multi-sensor data fusion, encrypted narrowband and broadband communications, and interoperable command platforms designed to reduce emergency response latency below statutory thresholds. Surveillance Systems capture the largest installed base across urban police districts, though margin pools are migrating toward Cloud-Based deployment configurations as municipalities outsource infrastructure lifecycle management. Communication Equipment retains structural importance due to mandated interoperability standards, while Managed Services represent the fastest-expanding revenue line as agencies shift from capital procurement to subscription-based operational expenditure models.
Regulatory Framework
The EU AI Act, GDPR, and CE marking under the Radio Equipment Directive collectively shape product development roadmaps, with the EU AI Act specifically restricting biometric identification deployments in publicly accessible spaces without judicial authorization. ETSI standards for critical communications interoperability further constrain vendor selection to those maintaining certified protocol stacks. Stakeholders must monitor evolving national implementations of the EU AI Act across member states, as divergent enforcement timelines will fragment procurement eligibility and create first-mover advantages for compliant integrators in stricter jurisdictions.
Market Dynamics
The EU AI Act is decomposing legacy procurement patterns across European public safety agencies, forcing municipalities to requalify vendors against biometric surveillance restrictions and algorithmic transparency mandates before contract renewal cycles.
Growth Catalysts
- Biometric Surveillance Restrictions:The EU AI Act's prohibition on real-time biometric identification in public spaces without judicial authorization is accelerating demand for privacy-preserving video analytics that use behavioral pattern recognition instead of facial recognition.
- Interoperability Mandates:ETSI standards for critical communications are compelling cross-border emergency response coordination between Germany, France, and Benelux countries, expanding addressable market for unified command platforms.
- Cloud Migration:Municipal budget constraints across Nordic cities are shifting capital expenditure toward subscription-based operational models, creating recurring revenue pools for managed service providers.
Market Restraints
- Semiconductor Supply Concentration:Dependence on Asian foundries for cryptographic security modules creates procurement lead time volatility for ANSSI-certified French defense-adjacent contracts.
- Legacy TETRA Lock-in:British emergency services networks face high switching costs from Motorola's installed narrowband infrastructure, constraining broadband migration timelines.
- GDPR Compliance Burden:Data localization requirements for cross-border incident data sharing impose architectural constraints on cloud-based dispatch platforms serving multi-national metropolitan clusters.
Strategic Opportunities
- Eastern European Modernization:Polish and Romanian municipal police forces are replacing Soviet-era radio systems with EU-funded digital infrastructure, creating first-mover advantages for compliant integrators.
- Geospatial-AI Convergence:Fusion of real-time sensor feeds with predictive crime mapping is opening new procurement categories in Dutch and Belgian smart city programs.
- CSRD Reporting Alignment:Sustainability disclosure mandates are creating demand for energy-efficient edge computing nodes in surveillance networks, favoring vendors with circular design certification.
Industry Challenges
- Cybersecurity Skill Scarcity:Municipal IT departments lack personnel to manage zero-trust architectures for encrypted first-responder networks, forcing reliance on vendor-managed security operations.
- Interoperability Certification Delays:ETSI protocol stack validation timelines extend 18-24 months, compressing product refresh windows for technology roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Public Safety Market |
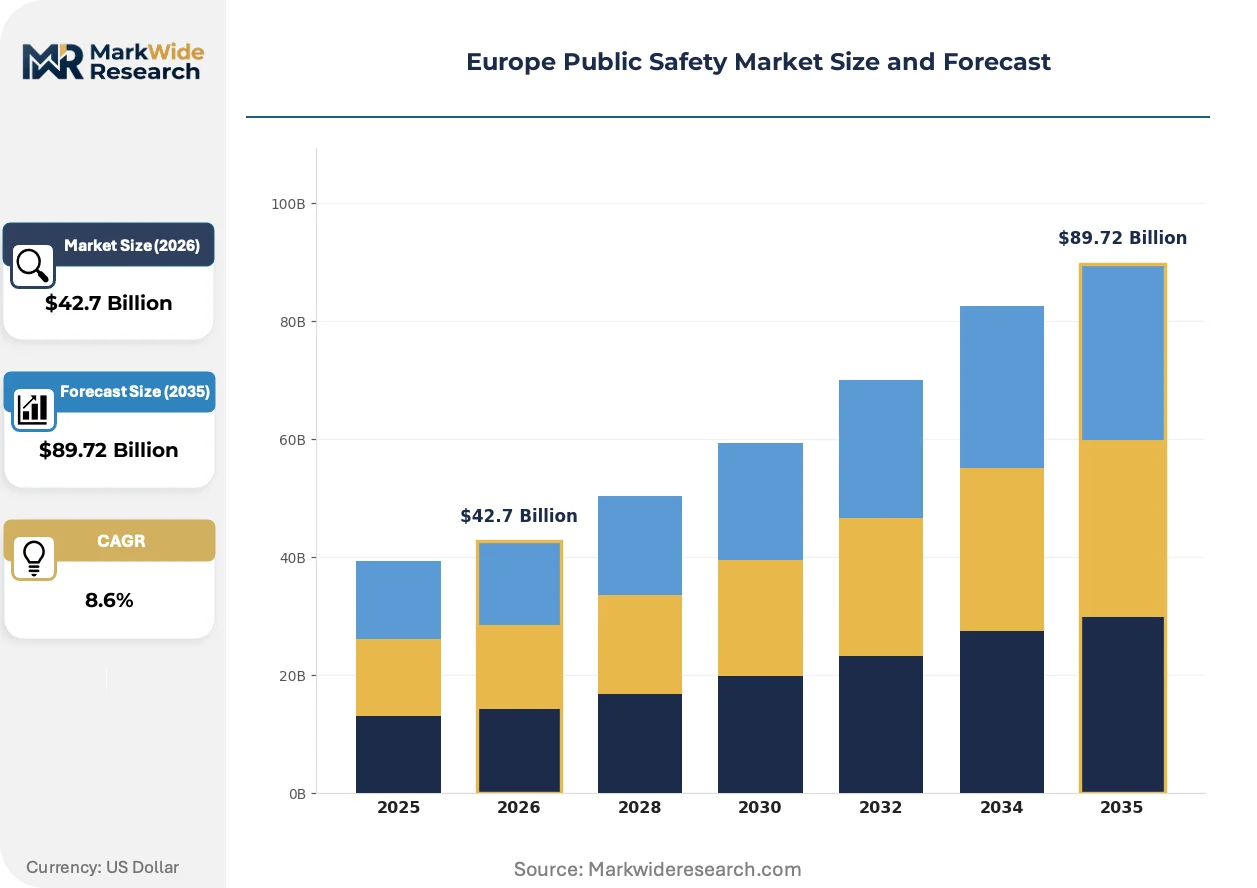
| Market Size in 2026 | $42.7 Billion |
| Market Size in 2035 | $89.72 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surveillance Systems, Emergency Response Systems, Communication Equipment, Fire Safety Equipment End User: Government Agencies, Public Safety Organizations, Hospitals, Educational Institutions Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing Service Type: Consulting Services, Managed Services, Training Services, Maintenance Services |
| Companies Covered | Hexagon AB, Atos SE, SAAB, ALE International, NEC Corporation, Motorola Solutions Inc, Thales Group, Siemens, Cisco Systems Inc, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Public Safety Market Trends and Innovations
Edge computing architectures are displacing centralized processing models across European urban surveillance networks, enabling real-time threat detection while satisfying GDPR data minimization principles through local inference.
Computer vision hardware is decomposing monolithic camera-server architectures into distributed sensor-edge-gateway hierarchies. German municipal police in Berlin and Munich are deploying battery-powered AI cameras with onboard inference chips that process footage locally, transmitting only anomaly alerts. This topology compresses bandwidth requirements and eliminates centralized storage of raw biometric data, directly addressing EU AI Act compliance burdens for public space monitoring.
REACH restrictions on per- and polyfluoroalkyl substances are forcing equipment redesigns for ruggedized outdoor surveillance housings. The regulation's industrial consequence extends to sealing gaskets and cable jacketing in emergency communications hardware. Nordic procurement agencies are now requiring PFAS-free material declarations in tender specifications, with Swedish transport authorities leading enforcement timelines.
Subscription contracting is replacing capital procurement across French departmental emergency services. The shift unbundles hardware ownership from operational capability, with Île-de-France region agencies piloting performance-based agreements where vendors guarantee response time thresholds. This model transfers lifecycle risk to integrators while converting municipal balance sheet obligations into predictable operational expenditures aligned with annual budget appropriations.
Europe Public Safety Market Segmentation
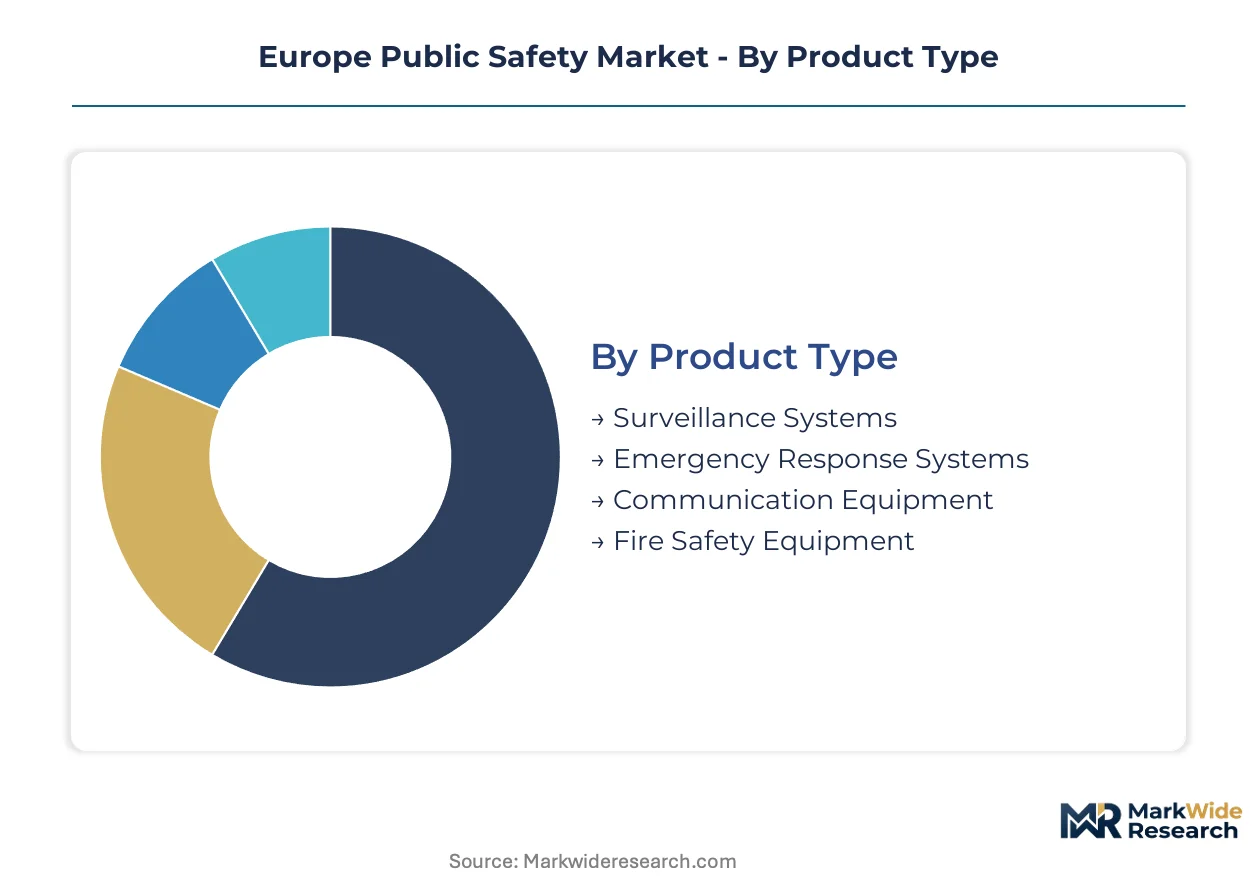
Segmentation in European public safety reveals how procurement priorities diverge across institutional buyers, with regulatory compliance and interoperability mandates reshaping product configuration requirements. Understanding these fault lines exposes where vendor margins concentrate and which deployment models are displacing legacy capital expenditure patterns.
Product Type:
Margin pools concentrate in integrated systems that bundle hardware with recurring software licenses, particularly where EU AI Act compliance creates qualification barriers for pure equipment vendors.
- Surveillance Systems:Multi-sensor platforms incorporating AI-enabled video analytics with edge inference capabilities. German municipal police in Berlin and Munich are expanding procurement of privacy-preserving behavioral recognition systems that avoid biometric identification restrictions under the EU AI Act.
- Communication Equipment:Encrypted narrowband and broadband infrastructure including TETRA, LTE, and mission-critical push-to-talk systems. British emergency services networks maintain structural dependence on Motorola's installed base, constraining migration timelines despite interoperability mandates.
- Emergency Response Systems:Integrated dispatch and incident management platforms with real-time geospatial fusion.
- Fire Safety Equipment:Detection, suppression, and evacuation systems with IoT connectivity for smart building integration.
The dominant share belongs to Surveillance Systems, while Communication Equipment is closing the gap fastest as broadband migration accelerates.
End User:
Volume concentrates in centralized procurement authorities that aggregate demand across multiple agencies, creating scale advantages for vendors with pan-European certification.
- Government Agencies:National and municipal police forces, border control, and defense-adjacent security services with ANSSI, BSI, or equivalent national certification requirements. French departmental emergency services are piloting subscription-based performance agreements where vendors guarantee response time thresholds.
- Public Safety Organizations:Fire departments, emergency medical services, and search-and-rescue operations with cross-border coordination mandates under ETSI standards. Benelux countries are driving unified command platform procurement for joint incident response.
- Hospitals:Healthcare emergency preparedness and mass casualty incident management systems.
- Educational Institutions:Campus security and threat detection for universities and research facilities.
Government Agencies command the largest procurement volumes, though Public Safety Organizations are expanding most quickly as cross-border interoperability mandates take effect.
Deployment:
Customer type stratification shows municipal IT departments favoring outsourced lifecycle management while defense-adjacent agencies retain on-premise control for sovereignty reasons.
- Cloud-Based:Subscription-hosted platforms with vendor-managed infrastructure and automatic compliance updates. Nordic cities including Stockholm and Copenhagen are shifting capital expenditure to operational models that align with annual budget appropriations.
- Edge Computing:Distributed processing architectures with local inference that satisfy GDPR data minimization principles. Battery-powered AI cameras with onboard chips are eliminating centralized biometric storage, directly addressing EU AI Act compliance burdens.
- On-Premise:Agency-owned infrastructure with full data sovereignty and air-gapped security.
- Hybrid:Segregated architectures combining sensitive on-premise core systems with cloud-based analytics tiers.
Cloud-Based configurations lead current procurement momentum, while Edge Computing is gaining share fastest as privacy regulations tighten.
Service Type:
Maturity differentiation separates established maintenance contracts from emerging outcome-based models that transfer operational risk to vendors.
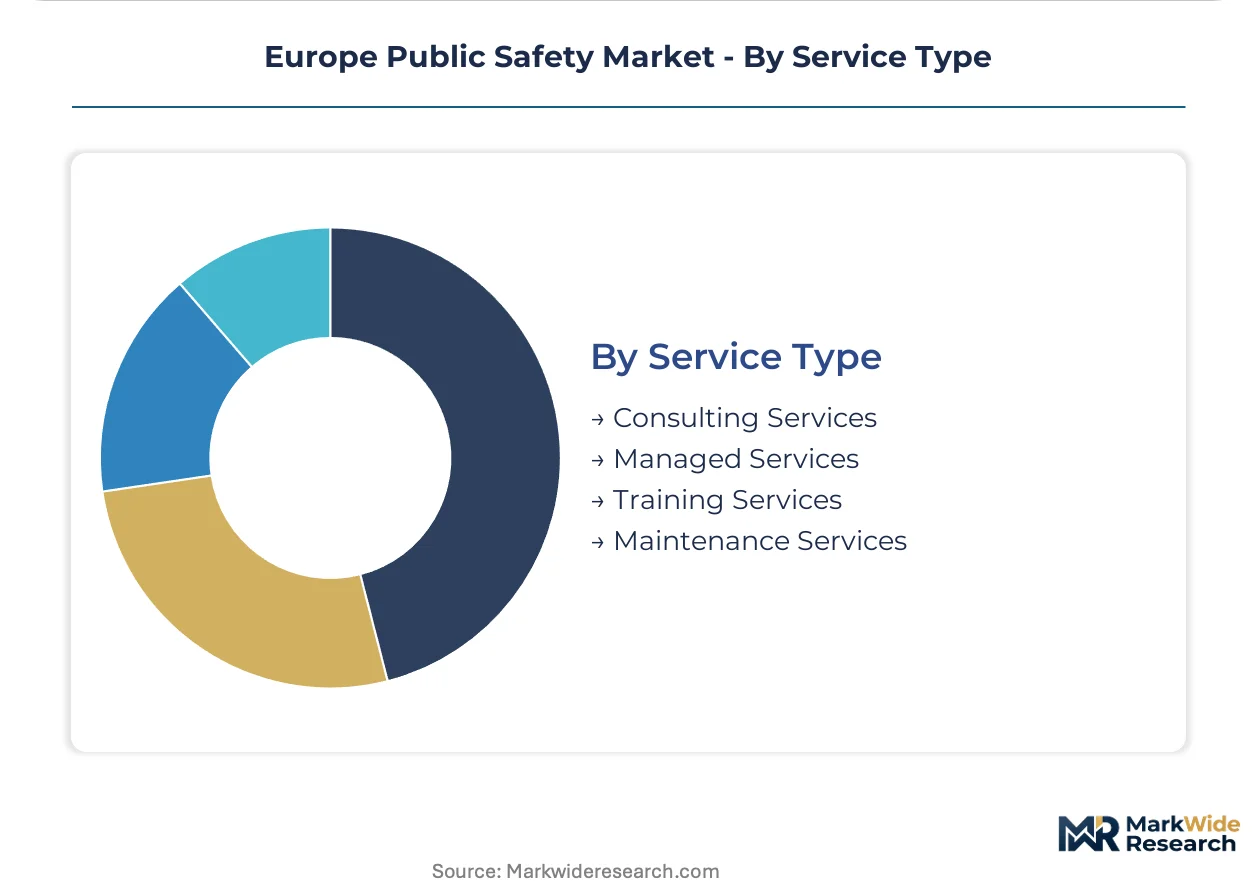
- Managed Services:End-to-end operational responsibility including cybersecurity, compliance monitoring, and performance guarantees. Municipal budget constraints across France and the Nordics are accelerating subscription contracting that unbundles hardware ownership from capability delivery.
- Consulting Services:System design, regulatory compliance roadmap development, and interoperability certification support. Vendors with ETSI protocol stack expertise command premium positioning as validation timelines extend 18-24 months.
- Training Services:Operator certification and scenario-based exercise programs for multi-agency coordination.
- Maintenance Services:Break-fix support and preventive maintenance for hardware lifecycle extension.
Managed Services holds the steepest expansion trajectory, while Consulting Services maintains margin leadership through scarce certification expertise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Alpine freight corridor anchors Germany's central role in cross-border emergency response coordination, with its dense logistics infrastructure demanding integrated public safety command systems across multiple jurisdictions.
Germany
Municipal police forces in Berlin and Munich are expanding procurement of AI-enabled video analytics with edge inference capabilities. BSI certification requirements for critical infrastructure protection are tightening vendor qualification criteria. The Rhine-Ruhr metropolitan cluster is driving demand for unified command platforms that coordinate emergency services across fragmented municipal boundaries.
France
Departmental emergency services in Île-de-France are piloting subscription-based performance agreements that transfer operational risk to integrators. ANSSI certification tiers for national defense-adjacent contracts are creating procurement barriers for non-compliant vendors. The Paris-Saclay research corridor is emerging as a testbed for geospatial-AI convergence in predictive policing applications.
United Kingdom
British emergency services networks maintain structural dependence on legacy narrowband infrastructure, constraining broadband migration timelines. The Home Office's interoperability mandates are compelling cross-agency coordination platforms for multi-jurisdictional incident response. Greater Manchester and West Midlands police forces are consolidating procurement through regional collaborative hubs.
Sweden
Nordic municipal dispatch centers are shifting capital expenditure toward cloud-based operational models that align with annual budget appropriations. Swedish transport authorities are enforcing REACH restrictions on PFAS in surveillance equipment through tender specifications. The Stockholm-Mälaren region is deploying battery-powered AI cameras with onboard inference chips for GDPR-compliant public space monitoring.
Poland
Municipal police forces are replacing Soviet-era radio systems with EU-funded digital infrastructure, creating first-mover advantages for compliant integrators. National cybersecurity frameworks are mandating encrypted communications for critical infrastructure protection. The Warsaw-Łódź corridor is consolidating regional procurement authorities to achieve scale in command-and-control system deployment.
Europe Public Safety Market Competitive Landscape
Listed leaders compete with private specialists across certification-intensive procurement channels, with the vendor landscape bifurcating between qualified integrators holding pan-European approvals and peripheral equipment suppliers serving sub-contractor roles. Market structure tilts toward consolidated service relationships where recurring revenue streams attach to installed infrastructure bases. Three archetypes dominate: defense-industrial conglomerates with cryptographic security modules, telecommunications incumbents leveraging TETRA infrastructure, and geospatial-software platforms specializing in real-time sensor fusion. Competitive positioning hardens through strategic partnerships for interoperability certification and portfolio diversification into managed services.
Within the defense-industrial tier, Thales Group and SAAB occupy positions anchored by national security-adjacent contracts requiring sovereign capability preservation. Motorola Solutions Inc exemplifies the telecommunications-incumbent archetype, sustaining recurring service relationships through legacy infrastructure installed bases. Hexagon AB sits within the geospatial-software specialization, competing on real-time data fusion platforms that dominate Nordic municipal dispatch centers. Atos SE and ALE International represent European-headquartered integrators pursuing scale through multi-country service contracts, while NEC Corporation and Cisco Systems Inc bring global technology portfolios to regional compliance-adapted configurations. Siemens maintains a diversified industrial position spanning both equipment supply and systems integration.
| Leading Market Players |
|---|
| Hexagon AB |
| Atos SE |
| SAAB |
| ALE International |
| NEC Corporation |
| Motorola Solutions Inc |
| Thales Group |
| Siemens |
| Cisco Systems Inc |
| Others |
Pricing and Supply Chain Analysis
Eighteen-to-twenty-four month ETSI protocol stack validation timelines compress procurement windows and amplify pricing power for certified integrators against peripheral equipment suppliers across European public safety procurement channels.
Pricing Analysis
Volume-discount tiering separates ANSSI-certified system integrators from uncertified sub-contractors across French defense-adjacent contracts. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling. Cost compression in standard tiers intensifies as municipal budget constraints favor subscription-based operational expenditure models. Government agencies exhibit lowest price sensitivity due to sovereign capability mandates, while municipal police forces demonstrate highest sensitivity to total cost of ownership.
Supply Chain Analysis
Inbound logistics costs through Rotterdam and Hamburg port corridors feed into lead-time volatility for cryptographic security modules sourced from Asian foundries. Semiconductor fabrication concentrates in Taiwan, South Korea, and China. Edge inference chips and encrypted narrowband radios draw from these concentrated sources. Single-source vulnerability in advanced node semiconductor production threatens ANSSI certification timelines. Distribution runs through pan-European systems integrators holding CE marking under the Radio Equipment Directive.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's public safety market represents early-cycle expansion as the EU AI Act forces vendor requalification and opens procurement windows for compliant alternatives to legacy infrastructure.
For Market Incumbents: Consolidate recurring revenue streams by deepening managed services penetration across British TETRA installed bases. Invest in EU AI Act compliance certification ahead of national implementation divergences to capture first-mover advantages in stricter jurisdictions. Counter broadband migration threats through performance-guarantee subscription models that transfer operational risk and lock in lifecycle relationships.
For New Entrants and Emerging Players: Lead with privacy-preserving behavioral analytics that bypass biometric identification restrictions under the EU AI Act. Target Polish and Romanian municipal police forces replacing Soviet-era radio systems with EU-funded digital infrastructure. Pursue interoperability certification partnerships with established ETSI protocol stack holders to compress 18-24 month validation timelines.
For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-compliance premium play because recurring revenue pools attach to certified infrastructure bases with high switching costs. Acquisition targets include geospatial-AI fusion specialists and edge computing hardware vendors with circular design certification. Watch for divergent EU AI Act enforcement timelines across member states as the signal for procurement fragmentation and compliance arbitrage opportunities.
| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Certification | Creates qualification barriers that fragment vendor eligibility across member state enforcement timelines. |
| Managed Services Transition | Converts municipal capital expenditure into recurring revenue aligned with annual budget appropriations. |
| Edge Computing Deployment | Satisfies GDPR data minimization through local inference while reducing bandwidth infrastructure costs. |
| ETSI Interoperability Partnership | Compresses 18-24 month protocol validation timelines for unified command platform market entry. |
| Eastern European Modernization Capture | Exploits EU-funded infrastructure replacement in Poland and Romania for first-mover positioning. |
Research Methodology
A spread of perspectives from municipal police procurement officers, emergency services IT directors, systems integration engineers, and regulatory compliance specialists converged on the working assumptions driving this analysis. Primary fieldwork combined structured interviews with secondary validation through ETSI technical specifications, CE marking databases, ANSSI certification registries, and municipal tender documentation across Berlin, Paris, Stockholm, and Warsaw. Bottom-up demand aggregation from national procurement authorities and top-down market sizing from installed base estimates were triangulated for convergence.
Segmentation dimensions modeled include product type, end user, deployment configuration, and service type across the analysis window. CAGRs were derived from trend extrapolation of procurement cycle timing, regulatory implementation schedules, and technology migration patterns. Forecast inputs incorporated EU AI Act enforcement divergence scenarios and TETRA-to-broadband infrastructure replacement curves.
The analysis sits within stated boundaries; outcomes outside EU AI Act implementation timelines, ETSI certification throughput, or semiconductor supply stability would require recalibration. Forecasts reflect documented assumptions about regulatory enforcement consistency and municipal budget continuity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market
Public Safety
Global Public Safety in Building Wireless Das System Market
Public Safety
Asia-Pacific Public Safety Market
Public Safety
Europe Public Infrastructure Safety Market
Public Safety
Outdoor Public Safety Market
Public Safety
Europe Wireless Broadband in Public Safety Market
Public Safety
Global Public Safety Solution Market
Public Safety
Global Public Safety Analytics Market
Public Safety
LAMEA Wireless Broadband in Public Safety Market
Public Safety
AI for Public Security and Safety Market
Public Safety
Public Safety Market
Public Safety
Global IoT for Public Safety Market
Public Safety
Europe Road Safety Market
Public Safety
Latin America Public Safety Market
Public Safety
Crowd Management System Market
Public Safety
Voice Evacuation Systems Market