
 Public Address and Voice Alarm Systems Market | 2026-2036
Public Address and Voice Alarm Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Public Address and Voice Alarm Systems Market Analytics
A shortage of certified fire safety systems engineers is reorganizing how manufacturers structure service networks and installer certification programs. Bosch Security Systems leverages its factory-trained technician ecosystem to sustain project execution capacity across European infrastructure contracts. Honeywell International Inc. anchors its competitive stance through backward integration into control panel manufacturing, while Siemens AG dominates large-scale transportation hub deployments with its rail-certified evacuation platforms.
Public address and voice alarm systems comprise distributed loudspeaker arrays, microphone stations, and central control equipment engineered to deliver intelligible speech transmission with a minimum sound pressure level of 75 dB at three meters during emergency conditions, primarily serving life safety evacuation and routine announcement functions in occupied buildings. IP systems are capturing the fastest expansion as Power-over-Ethernet switches reduce dedicated cabling infrastructure and enable centralized software management across multi-zone facilities. Conventional systems retain substantial replacement volume in aging institutional buildings where full infrastructure overhaul remains capital-constrained, while hybrid installations bridge these positions by preserving existing loudspeaker loops while upgrading control and routing intelligence.
The EU Construction Products Regulation and EN 54 family of standards mandate third-party certification for voice alarm components, creating a compliance barrier that filters non-certified suppliers from European public tenders. In the United States, NFPA 72 and OSHA workplace safety directives shape minimum audibility requirements and maintenance protocols for industrial occupancies. Stakeholders must monitor how evolving smart building codes integrate voice alarm networks with broader IoT security frameworks, as cybersecurity certification becomes inseparable from functional safety approval.
Market Dynamics
IP-based audio-over-Ethernet protocols are decomposing legacy analog infrastructure as Power-over-Ethernet switches eliminate dedicated cabling runs and enable centralized zone management across multi-facility deployments.
Growth Catalysts
- EN 54 Certification Mandates:The EU Construction Products Regulation requires third-party validation for voice alarm components, filtering non-certified suppliers from European public tenders and consolidating procurement toward compliant manufacturers.
- Smart City Infrastructure:China is accelerating unified emergency communication platform deployment through municipal digitization programs, concentrating demand for networked evacuation systems in transportation hubs and commercial complexes.
- Airport Modernization:Asia-Pacific aviation authorities are expanding procurement of networked evacuation systems to comply with stricter fire safety mandates, driving specification upgrades in terminal expansions and retrofit projects.
Market Restraints
- Copper and Semiconductor Input Volatility:Loudspeaker voice coils and amplifier chipsets face price instability from concentrated Asian foundry output and mining supply disruptions.
- Certified Engineer Scarcity:A shortage of fire safety systems engineers limits project execution capacity, forcing manufacturers to restructure service networks and installer certification programs.
- Legacy Infrastructure Lock-in:Aging institutional buildings retain substantial analog system bases where full infrastructure overhaul remains capital-constrained, compressing replacement velocity.
Strategic Opportunities
- Cybersecurity-Integrated Certification:Evolving smart building codes are merging voice alarm networks with IoT security frameworks, creating new compliance service revenue streams for systems integrators.
- Hybrid Retrofit Solutions:Installations bridging analog loudspeaker loops with upgraded IP control and routing intelligence address capital-constrained facilities without full infrastructure replacement.
- Rail-Certified Platform Expansion:Transportation hub deployments require evacuation systems meeting rail-specific safety standards, opening specialized verticals beyond conventional commercial construction.
Industry Challenges
- Multi-Protocol Integration Complexity:Facilities managers face operational friction merging IP-based audio-over-Ethernet systems with legacy analog cabling and proprietary control architectures.
- Extended Certification Timelines:Third-party validation under EN 54 and NFPA 72 protocols creates procurement delays, compressing project windows and straining contractor scheduling.
- Factory-Trained Technician Pipeline:Manufacturers must sustain project execution capacity through structured technician ecosystems as qualified installation labor pools tighten across European infrastructure contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public Address and Voice Alarm Systems Market |
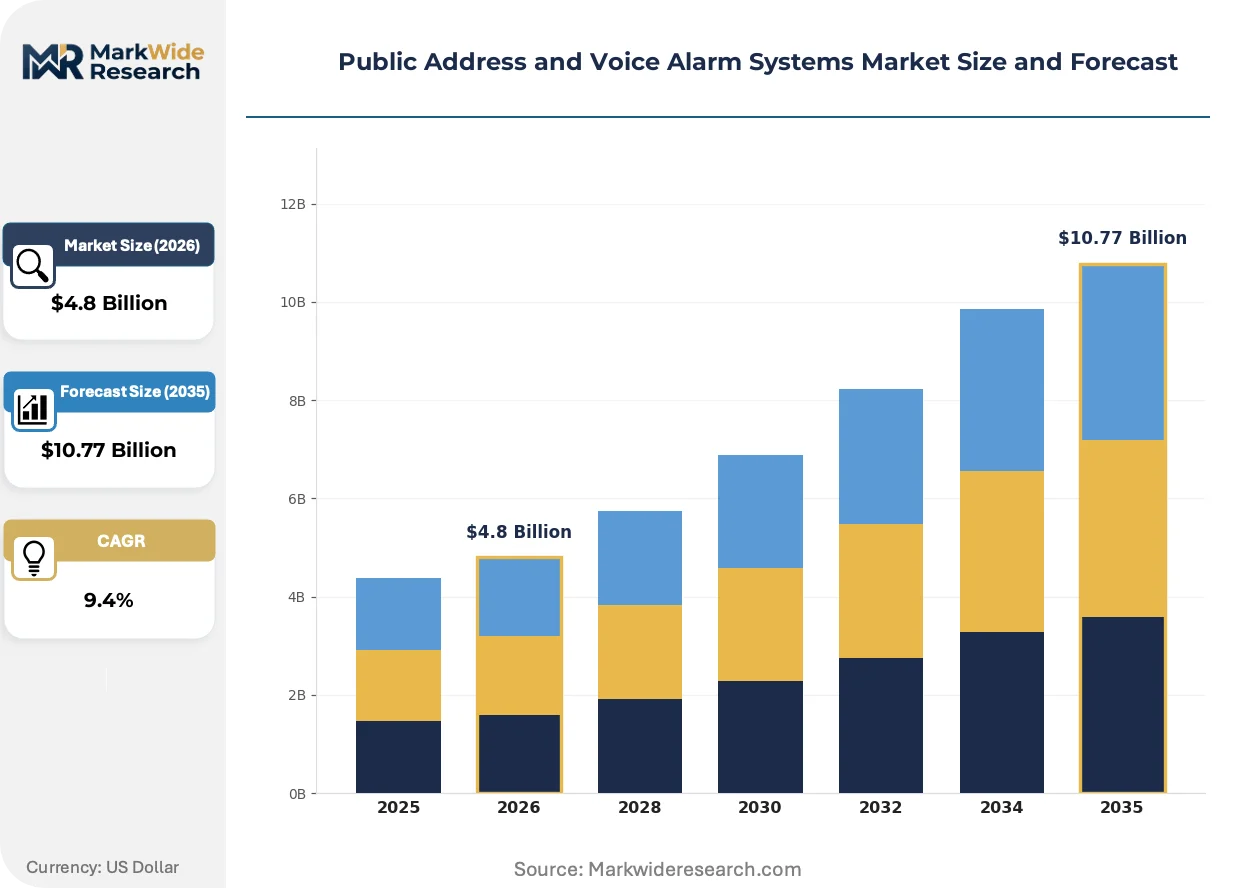
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.77 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional Systems, IP Systems, Digital Systems, Hybrid Systems Application: Industrial Facilities, Commercial Spaces, Transportation Hubs, Emergency Services End User: Educational Institutions, Government Buildings, Shopping Malls, Stadiums Installation Type: Fixed Installation, Portable Systems, Wireless Solutions, Integrated Systems |
| Companies Covered | Johnson Controls International Plc, ATEÏS, Bosch Security Systems, Heinrich Limited, Baldwin Boxall Communications Ltd, Honeywell International Inc., Zenitel, OPTIMUS S.A., Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public Address and Voice Alarm Systems Market Evolving Landscape
Audio distribution architecture is shifting from centralized amplifier banks to edge-computing endpoints, enabling software-defined zone management and reducing dedicated infrastructure overhead. This transformation touches hardware design, installation economics, and long-term service models.
Power-over-Ethernet switching is decomposing traditional analog cabling infrastructure by delivering both audio signal and amplifier power through standard Ethernet runs. Airport authorities and commercial developers are specifying PoE-based systems for greenfield construction to reduce dedicated conduit installation and enable centralized monitoring. The technology is compressing the installed cost gap between IP and conventional systems while enabling remote diagnostics that reduce on-site maintenance dispatch.
REACH and RoHS substance restrictions are reshaping loudspeaker component sourcing as European regulators tighten limits on hazardous materials in electronics. Manufacturers are reformulating cone materials, voice coil coatings, and circuit board substrates to maintain compliance without acoustic performance degradation. The regulations most acutely affect suppliers serving EU public tenders, where certification documentation requirements now extend through subcomponent supply chains.
Facility managers are unbundling after-sales service contracts from initial system procurement, selecting specialized maintenance providers based on response-time guarantees rather than manufacturer affiliation. This behavior is fragmenting the traditional single-source service model and creating openings for third-party technical service firms with multi-brand certification. The shift is most visible in German and French commercial real estate portfolios where asset managers prioritize operational expenditure flexibility over capital-package bundling.
Public Address and Voice Alarm Systems Market Segmentation
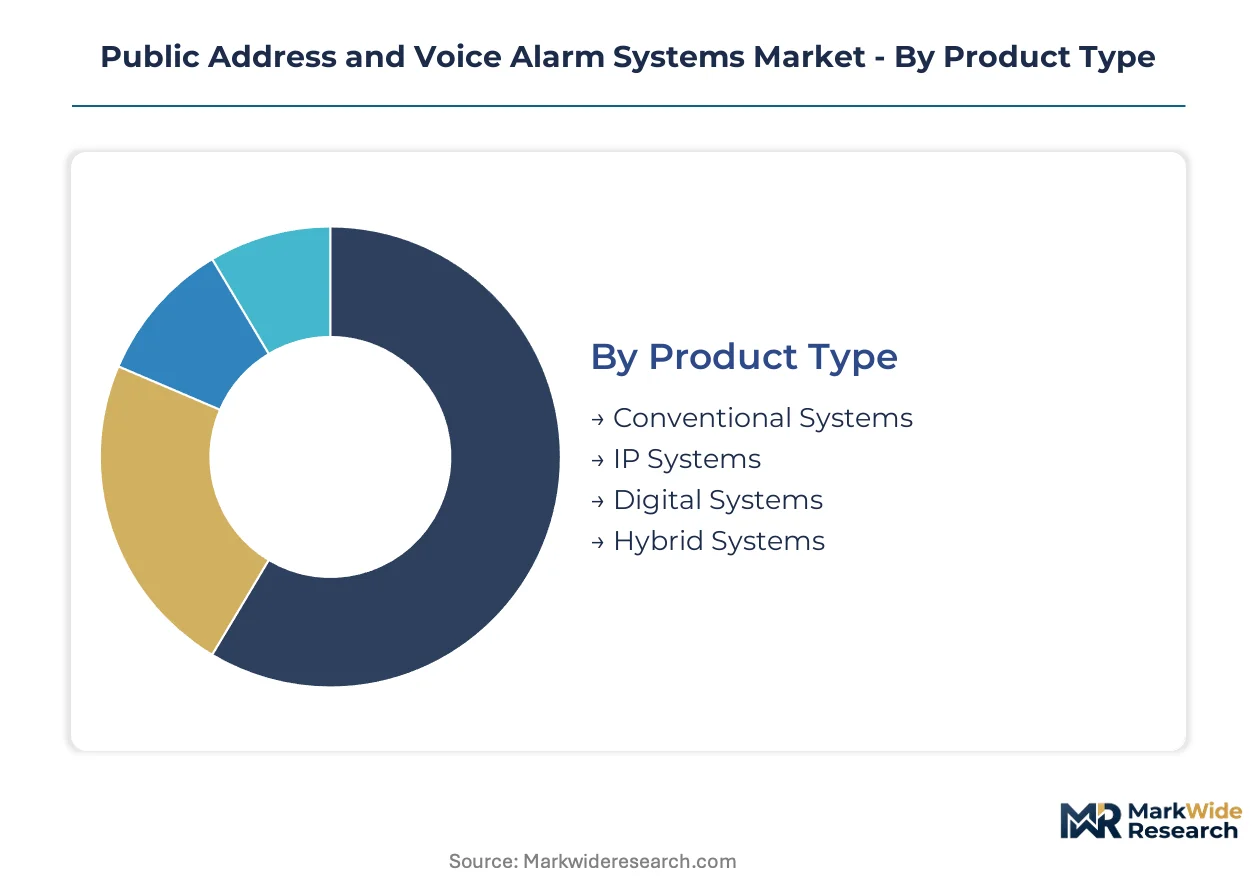
Segmentation reveals where procurement budgets concentrate across technology generations and facility types. Product architecture and installation constraints determine margin capture, while application verticals expose regulatory compliance intensity.
Product Type:
Margin pools concentrate in systems commanding software-defined management premiums and those bridging legacy infrastructure.
- IP Systems:Audio-over-Ethernet architectures deliver power and signal through unified cabling, eliminating dedicated amplifier racks. Demand clusters in Chinese smart city deployments and Asia-Pacific airport greenfield construction, driven by centralized zone management requirements and Power-over-Ethernet switch economics.
- Hybrid Systems:These configurations preserve existing loudspeaker loops while upgrading control and routing intelligence through IP gateways. European retrofit markets favor this approach where EN 54 certification mandates meet capital-constrained institutional budgets, particularly in aging German and French public buildings.
- Conventional Systems:Analog amplifier banks and dedicated copper cabling retain replacement volume in legacy facilities where full infrastructure overhaul remains uneconomical.
- Digital Systems:Proprietary digital audio networks offer intermediate functionality between analog and full IP architectures, serving mid-tier commercial installations seeking phased upgrade paths.
The dominant share belongs to Conventional Systems, while IP Systems is closing the gap fastest.
Application:
Volume concentrates in facilities with mandatory evacuation protocols and multi-zone occupancy complexity.
- Transportation Hubs:Rail-certified evacuation platforms must deliver 75 dB intelligibility at three meters across concourse zones with high ambient noise. China Railway and Asia-Pacific aviation authorities are expanding procurement to comply with stricter fire safety mandates in terminal expansions.
- Industrial Facilities:OSHA workplace safety directives in the United States shape minimum audibility requirements for manufacturing occupancies with high background machinery noise.
- Commercial Spaces:Office complexes and retail environments prioritize routine announcement functionality alongside emergency capability, with procurement decisions increasingly unbundling service contracts from initial system purchase.
- Emergency Services:Police, fire, and ambulance facilities require dedicated communication resilience with backup power integration and priority override protocols.
Transportation Hubs commands the largest procurement budgets, while Industrial Facilities shows the steepest expansion trajectory from regulatory enforcement tightening.
End User:
Purchasing authority varies sharply between public tender processes and private asset manager discretion.
- Government Buildings:EU public procurement rules and EN 54 certification requirements filter supplier pools, consolidating awards toward manufacturers with documented third-party validation and factory-trained technician networks.
- Stadiums:Large-venue deployments require distributed loudspeaker arrays capable of penetrating crowd noise during emergency conditions, with specifications often bundled into construction contractor packages.
- Educational Institutions:Campus-wide systems must serve daily paging functions alongside lockdown and evacuation protocols, with K-12 districts in the United States prioritizing NFPA 72 compliance.
- Shopping Malls:Multi-tenant commercial properties face operational friction merging IP-based audio with legacy analog infrastructure from phased development cycles.
Government Buildings maintains the deepest project pipeline, though Stadiums is gaining share fastest from post-pandemic venue modernization programs.
Installation Type:
Cost structures diverge between permanent infrastructure commitments and operational expenditure flexibility.
- Fixed Installation:Permanent conduit and cable infrastructure represents the conventional deployment model, with long amortization horizons favoring capital-package bundling in new construction.
- Wireless Solutions:Radio-frequency and mesh-network architectures reduce cabling requirements for heritage buildings and temporary facilities, though spectrum licensing and interference management add operational complexity.
- Portable Systems:Battery-powered units serve construction sites, outdoor events, and disaster response scenarios where permanent infrastructure is absent or compromised.
- Integrated Systems:Voice alarm networks merged with fire detection, access control, and building management platforms require cybersecurity certification alongside functional safety approval under evolving smart building codes.
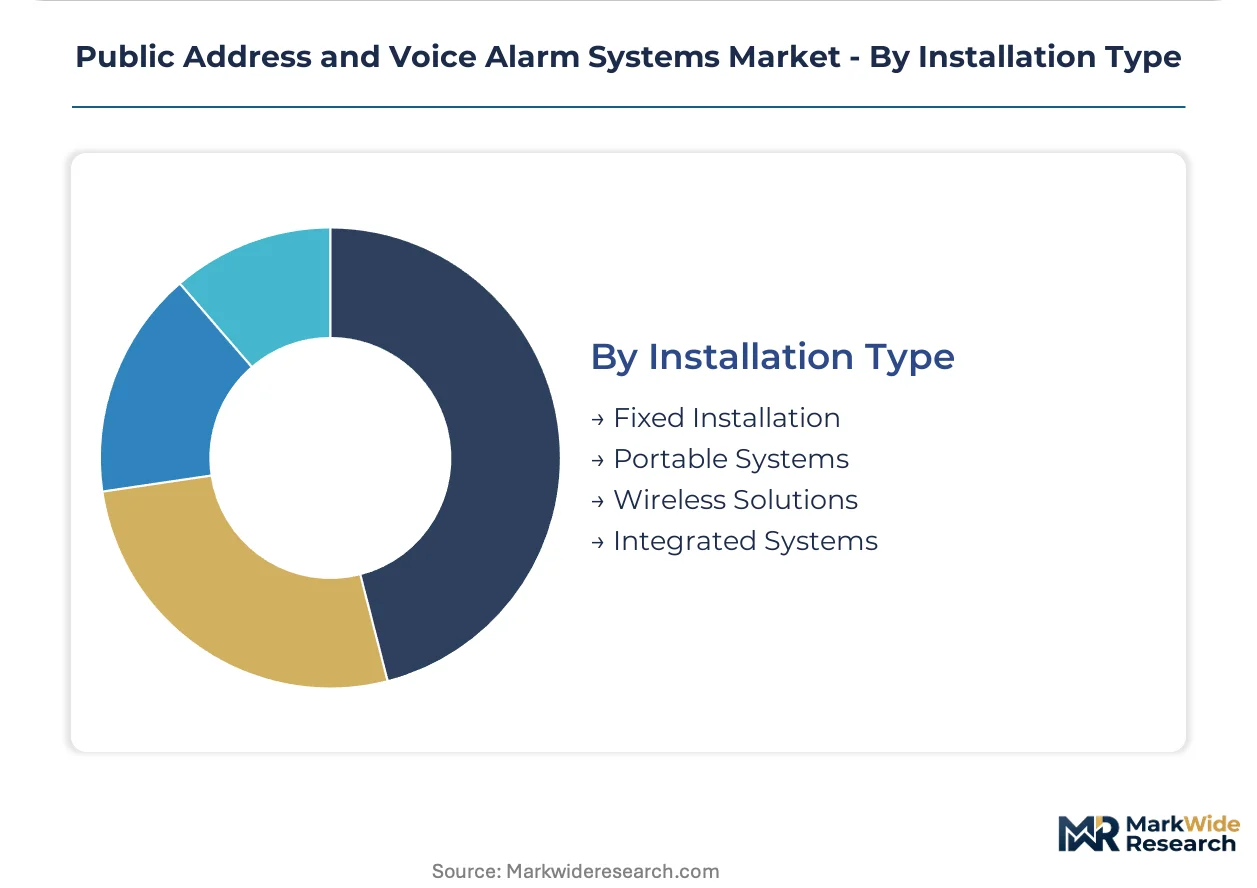
Fixed Installation retains the majority position, while Integrated Systems is climbing the fastest as IoT security frameworks merge with life safety mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EN 54 certification mandates under the EU Construction Products Regulation anchor procurement consolidation in European public tenders, while China's smart city investments and Asia-Pacific airport expansions concentrate demand growth in networked evacuation systems.
China
Municipal digitization programs are accelerating unified emergency communication platform deployment across transportation hubs and commercial complexes. The Ministry of Housing and Urban-Rural Development's smart city guidelines mandate integrated life safety networks in new construction. Shanghai and Beijing clusters dominate procurement volume as megacity infrastructure investments scale IP-based audio-over-Ethernet specifications.
Germany
Aging institutional buildings in the federal states are driving hybrid retrofit demand where EN 54 certification meets capital-constrained public budgets. The country's national construction regulator enforces third-party validation for voice alarm components in federal tenders. Bavaria and North Rhine-Westphalia concentrate project execution as factory-trained technician networks sustain installation capacity across European infrastructure contracts.
United States
OSHA workplace safety directives are tightening minimum audibility requirements for industrial manufacturing occupancies with high background machinery noise. NFPA 72 protocols shape procurement specifications for K-12 educational institutions and commercial real estate portfolios. Texas and California industrial corridors exhibit the steepest regulatory enforcement activity as regional building codes integrate smart building cybersecurity frameworks.
United Kingdom
Post-pandemic venue modernization programs are expanding stadium and transportation hub deployments requiring distributed loudspeaker arrays. The Health and Safety Executive enforces evacuation system compliance through workplace safety inspections. London and the Southeast concentrate specification activity as commercial developers unbundle service contracts from initial system procurement.
Japan
Rail-certified evacuation platforms are penetrating transportation infrastructure as METI standards harmonize with international safety protocols. JIS certification requirements filter supplier pools for public sector tenders. The Kanto and Kansai metropolitan areas anchor demand as high-speed rail terminal expansions specify intelligibility-compliant networked systems.
Public Address and Voice Alarm Systems Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with the upper tier commanding premium positioning through captive supply of control panel manufacturing and rail-certified platform portfolios. The middle tier fragments across regional certification specialists and hybrid retrofit solution providers. Three archetypes define competitive positioning: vertically integrated conglomerates with backward integration into core components, certification-heavy European specialists with factory-trained technician ecosystems, and IP-native technology providers leveraging Power-over-Ethernet switch economics. Dominant competitive moves include strategic partnerships for multi-protocol integration capabilities and geographic expansion through localized certification acquisition.
Within the integrated conglomerate tier, Siemens AG and Honeywell International Inc. exemplify scale-driven positioning through in-house production of control systems and rail-specific safety platforms. Bosch Security Systems anchors the European specialist archetype with its factory-trained technician network sustaining project execution capacity across infrastructure contracts. These three companies occupy positions that reflect the market's bifurcation between certification-intensive public tenders and technology-forward greenfield specifications.
| Leading Market Players |
|---|
| Johnson Controls International Plc |
| ATEÏS |
| Bosch Security Systems |
| Heinrich Limited |
| Baldwin Boxall Communications Ltd |
| Honeywell International Inc. |
| Zenitel |
| OPTIMUS S.A. |
| Siemens AG |
| Others |
Value Network & Pricing Analysis
Project-based procurement contracts with multi-year service bundling lock in supply access for certified manufacturers while anchoring price visibility against copper and semiconductor input volatility. EN 54 certification requirements in European public tenders create procurement friction that filters non-compliant suppliers, consolidating awards toward manufacturers with documented third-party validation and factory-trained technician networks.
Pricing Analysis
Geographic price spreads widen between EU-certified premium tiers and economy-grade Asian imports, with EN 54 validation adding substantial compliance premiums to European public tenders. Three-tier pricing structure across premium, standard, and economy levels separates rail-certified platforms from commercial-grade systems and basic analog replacements. Cost compression in economy tiers is intensifying because Power-over-Ethernet switch economics erode the installed cost gap with conventional systems. K-12 educational institutions in the United States exhibit the highest price sensitivity due to capital-constrained district budgets, while transportation hub authorities prioritize intelligibility compliance over unit cost.
Supply Chain Analysis
Taiwan Strait shipping lanes and South China Sea transit routes concentrate risk for amplifier chipset and Power-over-Ethernet switch deliveries to European and North American assembly facilities. Manufacturing concentrates in China, Germany, and the United States, with loudspeaker voice coils drawing from Malaysian copper processing and Taiwanese semiconductor foundries. Single-source vulnerability runs through concentrated Asian foundry output for DSP chips and Class-D amplifier modules. Distribution runs through manufacturer-direct channels for large infrastructure contracts and specialized systems integrators for retrofit installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory entrenchment story where EN 54 and NFPA 72 certification requirements create switching costs that lock facility managers into validated supplier relationships. The structural moat deepens as smart building codes merge voice alarm networks with IoT security frameworks, extending compliance documentation through subcomponent supply chains.
For Market Incumbents: Shield market position by deepening backward integration into control panel manufacturing and expanding factory-trained technician ecosystems across European infrastructure contracts. IP-native technology providers threaten premium positioning through Power-over-Ethernet switch economics that compress installed cost gaps. Certification investment in rail-specific safety platforms opens specialized verticals beyond conventional commercial construction. For New Entrants and Emerging Players: EN 54 fast-track certification partnerships with European notified bodies unlock filtered public tender access in German and French institutional retrofit markets. White-space concentrates in hybrid retrofit solutions bridging analog loudspeaker loops with IP control upgrades for capital-constrained aging buildings. Cybersecurity-integrated certification services for smart building code compliance offer recurring revenue entry points without full system manufacturing. For Investors and Strategic Acquirers: Regional certification specialists with documented third-party validation and localized technician networks present prime acquisition targets for geographic expansion. Long-term viability hinges on regulatory entrenchment deepening as IoT security frameworks merge with life safety mandates, extending compliance barriers. Monitor EN 54 certification timeline compression as the inflection signal indicating procurement velocity acceleration or contractor capacity constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity-Integrated Certification | Smart building code evolution in Texas and California creates compliance service revenue streams for systems integrators. |
| Hybrid Retrofit Solution Launch | Capital-constrained German public buildings drive specification demand for IP gateway upgrades preserving analog loudspeaker loops. |
| Rail-Certified Platform Expansion | China Railway and Asia-Pacific aviation authorities mandate evacuation systems meeting specialized transportation safety standards. |
| Factory-Trained Technician Network Buildout | Bavaria and North Rhine-Westphalia infrastructure contracts require sustained installation capacity across European markets. |
| Power-over-Ethernet Switch Partnership | Shanghai and Beijing smart city deployments specify unified cabling infrastructure reducing dedicated conduit installation costs. |
Research Methodology
Cross-validation between primary interviews with fire safety systems engineers, facility managers at transportation hubs, and procurement officers at institutional buyers anchors the qualitative findings against secondary validation from EN 54 certification databases, NFPA 72 compliance records, and municipal smart city procurement disclosures. Bottom-up triangulation aggregates project-level specification data across Chinese transportation hub expansions, German institutional retrofits, and United States K-12 deployments. Top-down reconciliation cross-checks against customs records for loudspeaker and amplifier trade flows, SEC filings from integrated conglomerates, and construction permit databases tracking new voice alarm installations.
Sensitivity analysis across the projection horizon tests demand elasticity to copper price volatility, certification timeline delays, and smart building code adoption rates. The analytical framework models technology generation splits between IP, hybrid, conventional, and digital architectures alongside application verticals spanning transportation hubs, industrial facilities, commercial spaces, and emergency services. CAGRs derive from segment-level growth rate blending weighted by procurement budget concentration. Industry-specific forecast inputs include Power-over-Ethernet switch penetration curves and EN 54 certification velocity by notified body.
Underlying assumptions cover sustained municipal digitization program funding in China, stable EN 54 enforcement intensity in European public tenders, and OSHA audibility requirement tightening in United States manufacturing corridors, with deviation risk concentrated in semiconductor supply disruptions and cybersecurity framework harmonization delays. Practitioners should keep alternative scenarios live as smart building code integration timelines and copper foundry capacity expansion evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Analyzers Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Eye Wash Stations Market
Safety Equipment and Personal Protective Equipment (PPE)
Respirator Fit Tester Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Anti-Fatigue Mats Market
Safety Equipment and Personal Protective Equipment (PPE)
Non-Powered Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
US Industrial Barrier Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
Protective Fluid Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia Pacific Gas Detector Market
Safety Equipment and Personal Protective Equipment (PPE)
North America Respiratory Protective Equipment (RPE) Market
Safety Equipment and Personal Protective Equipment (PPE)
Non Ionizing Radiation/EMF Detection, Measurement, and Safety Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Locker Market